
 Biocatalysis and Biocatalysts Market | 2026-2036
Biocatalysis and Biocatalysts Market Size, Share, and Industry Trends Forecast 2026-2036
Biocatalysis and Biocatalysts Market Analysis
European enzyme fermentation capacity is broadening as biotech infrastructure scales across the Netherlands and Denmark. Novozymes A/S leverages its Danish production base to dominate industrial enzyme supply chains. DSM-Firmenich anchors nutrition and pharma-grade biocatalyst output through integrated fermentation networks. BASF SE competes in specialty enzyme intermediates for agricultural and chemical markets.
Biocatalysis and biocatalysts comprise protein-based enzymes, whole-cell systems, and co-factors that accelerate chemical reactions under mild conditions, typically operating at 20-40°C and pH 5-8 to enable stereoselective transformations. These biological agents serve pharmaceutical, agricultural, and food processing industries by reducing energy input and toxic byproduct generation. Enzyme engineering and immobilization technologies command premium positioning due to reusability and process stability advantages. Pharmaceutical applications attract the deepest margin pools as chiral synthesis demands precision biocatalytic steps. Food and beverage applications sustain volume leadership through starch processing and dairy enzyme deployment.
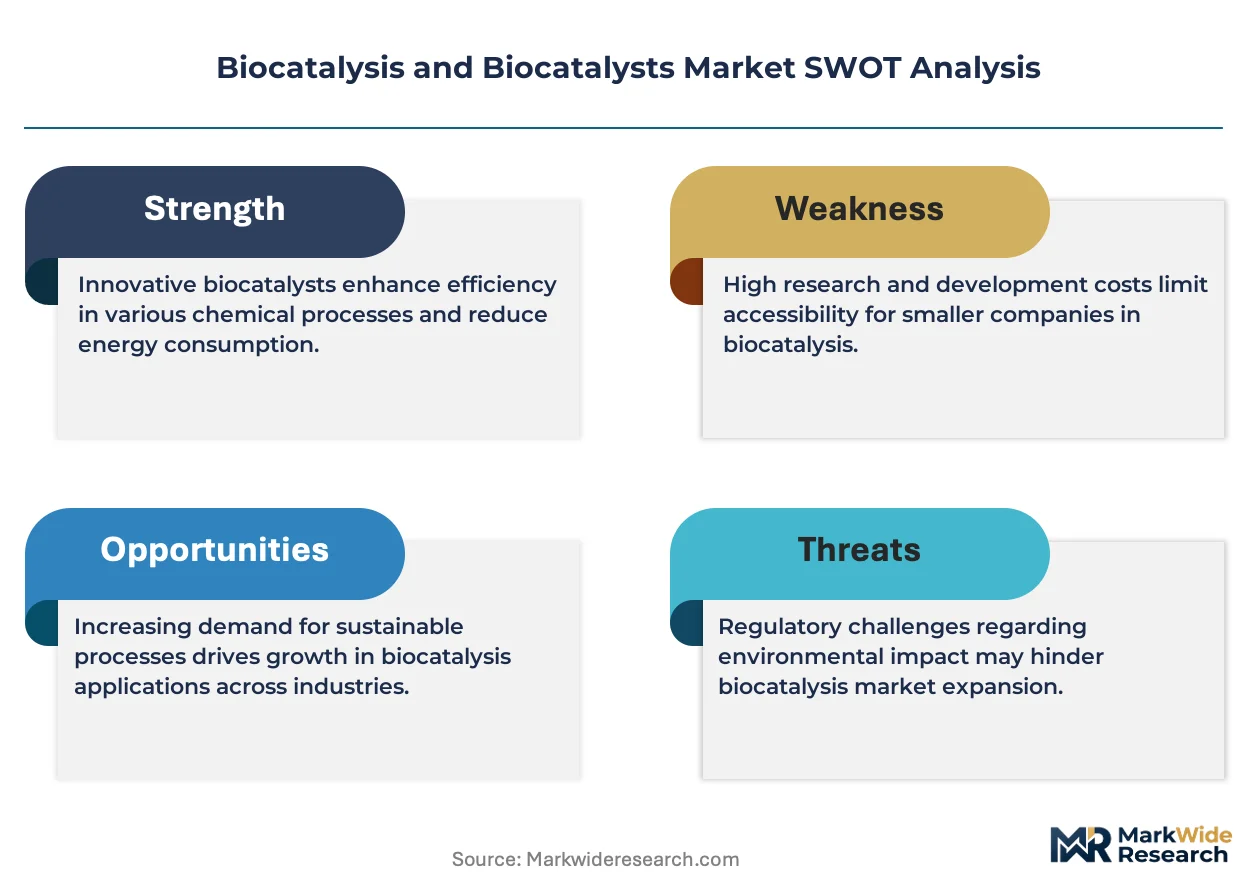
EPA industrial chemical guidelines and REACH substance authorization in Europe restrict conventional catalytic processes, directing capital toward enzymatic alternatives. FDA quality standards for biocatalytic pharmaceutical intermediates enforce purity thresholds that favor validated enzyme suppliers. Japan's METI biomanufacturing roadmap and China's dual carbon goals from MEE are tightening emissions criteria for chemical producers. Stakeholders must weigh regulatory trajectory against enzyme substitution economics when committing to process redesign.
Market Dynamics
Pharmaceutical manufacturers are systematically replacing high-temperature chemical synthesis with enzymatic pathways to meet tightening EPA and ECHA emission thresholds. This substitution mandate is restructuring capital allocation across fermentation capacity and enzyme engineering platforms.
Growth Catalysts
- REACH substance authorization:European chemical producers face phased restrictions on conventional catalytic processes, redirecting R&D budgets toward validated enzyme suppliers.
- Chiral synthesis demand:Small-molecule drug pipelines require stereoselective biocatalytic steps that chemical catalysts cannot replicate at ambient temperature.
- Denmark-Netherlands fermentation cluster:Concentrated biotech infrastructure expansion is compressing enzyme production lead times for industrial customers.
Market Restraints
- Protein engineering talent scarcity:Qualified enzyme designers command premium compensation, constraining mid-tier supplier scale-up.
- Denmark supply concentration:Industrial enzyme output clusters around Copenhagen-Aarhus corridor, creating single-point vulnerability.
- Thermal stability ceiling:Wild-type enzymes denature above 50°C, limiting application in high-temperature chemical processes.
Strategic Opportunities
- India food-grade penetration:Dairy and starch processing sectors remain under-supplied with tailored enzyme blends versus Western benchmarks.
- AI-directed evolution convergence:Machine learning algorithms paired with high-throughput screening are compressing enzyme optimization cycles from years to months.
- China MEE dual carbon compliance:Provincial emissions inspectors are granting expedited permitting to facilities demonstrating enzymatic process substitution.
Industry Challenges
- FDA biocatalytic intermediate validation:Pharmaceutical enzyme suppliers face 18-24 month purity certification timelines that delay revenue recognition.
- Legacy reactor incompatibility:Stainless-steel chemical plants require retrofitted temperature and pH control systems to host immobilized enzyme beds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biocatalysis and Biocatalysts Market |
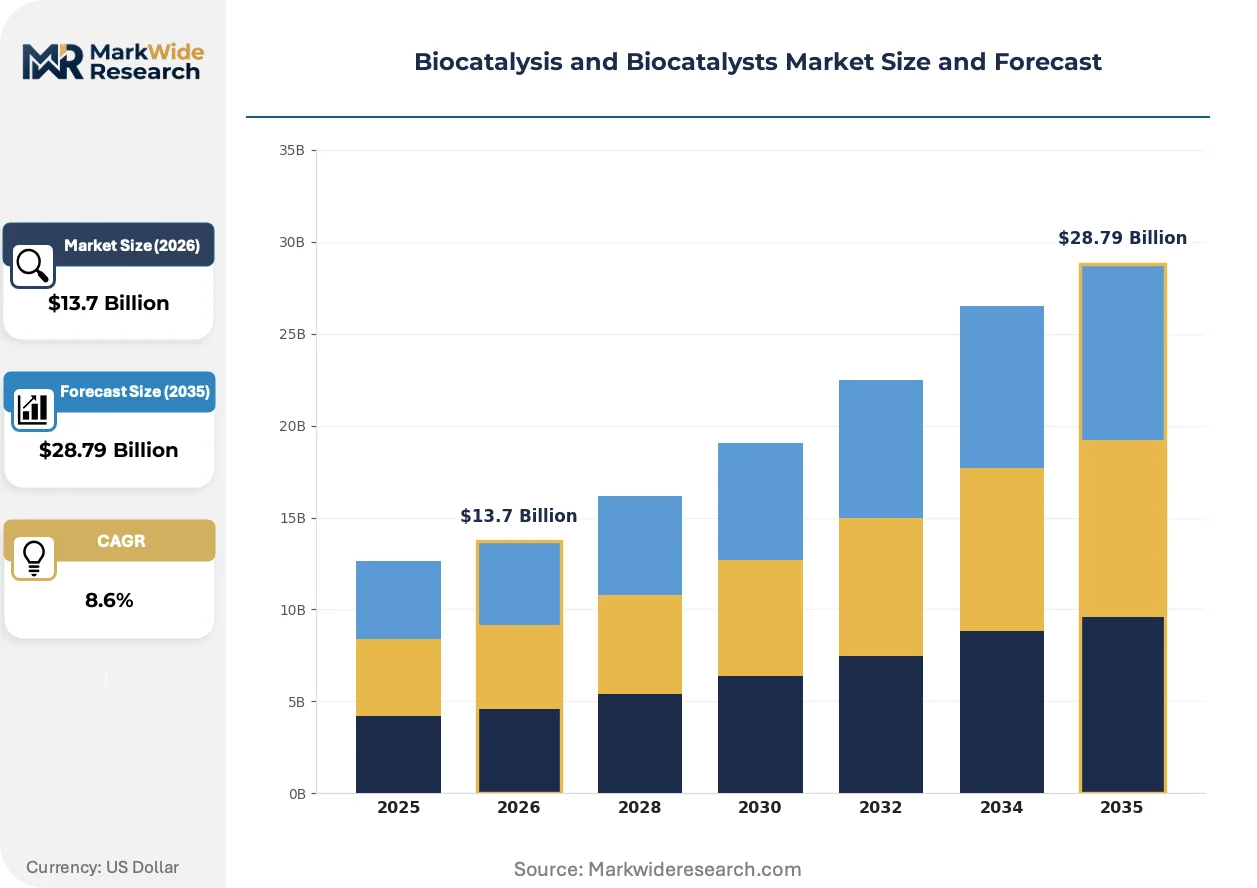
| Market Size in 2026 | $13.7 Billion |
| Market Size in 2035 | $28.79 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Whole Cells, Co-factors, Biocatalyst Systems Application: Pharmaceuticals, Agriculture, Food & Beverages, Biofuels End User: Biotech Companies, Research Institutions, Food Manufacturers, Chemical Producers Technology: Immobilization, Hybrid Biocatalysis, Enzyme Engineering, Fermentation |
| Companies Covered | DSM-Firmenich, Amano Enzyme Inc, Novozymes A/S, DuPont de Nemours, Chr. Hansen Holding, Codexis, Inc., AB Enzymes GmbH, Biocatalysts Ltd., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biocatalysis and Biocatalysts Market Emerging Trajectories
Computational protein design and continuous flow biocatalysis are converging to redefine manufacturing economics. These advances are compressing development timelines while expanding the reaction scope addressable by biological catalysts.
Directed evolution platforms incorporating machine learning prediction models are electrifying enzyme property optimization. Pharmaceutical process chemists at scale manufacturers are adopting these tools within 12-month procurement cycles. The technology is compressing competitive moats around historically dominant enzyme suppliers by democratizing access to high-performance variants.
EPA industrial chemical guidelines and REACH authorization timelines are synchronizing to favor enzymatic substitution. Chemical producers in Texas and Rotterdam port zones face coordinated enforcement pressure on solvent-intensive processes. Agricultural intermediate manufacturers are responding fastest, retrofitting amide bond formation steps with lipase biocatalysis to preempt regulatory penalties.
Contract development and manufacturing organizations are unbundling enzyme supply from process licensing. Small and mid-cap pharmaceutical developers now source validated biocatalysts through specialized distributors rather than captive fermentation. This pattern concentrates in Boston-San Diego corridor and Basel-Zurich cluster where virtual biotech models dominate pipeline origination.
Biocatalysis and Biocatalysts Market Segmentation
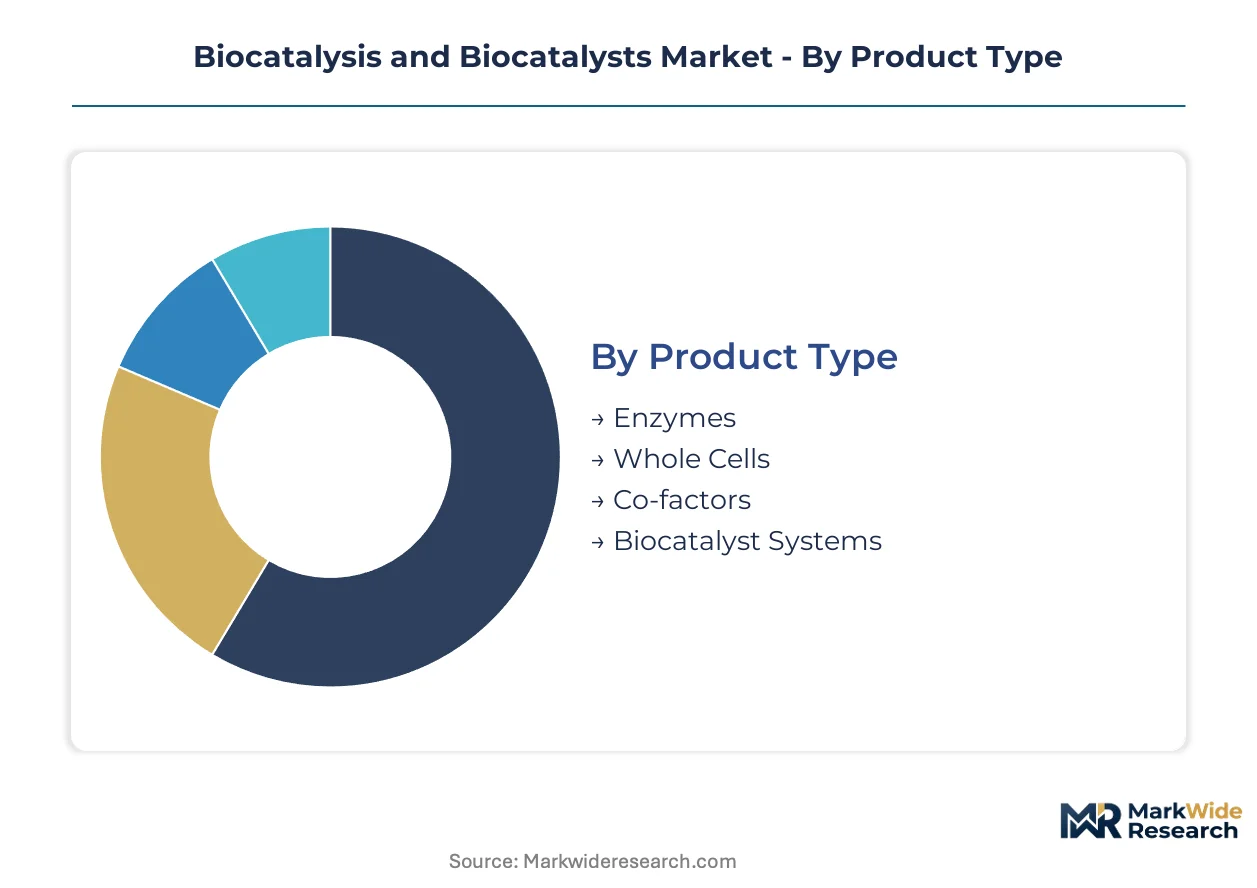
Process redesign cycles across pharmaceutical and chemical manufacturing are forcing granular segmentation of biocatalytic inputs. Suppliers now engineer distinct product-service bundles for chiral synthesis versus commodity food processing, with technology choices locking in decade-long customer relationships.
Product Type:
Replacement economics favor enzyme formats that reduce unit operation counts versus legacy whole-cell fermentation.
- Enzymes:Isolated protein catalysts deliver stereoselectivity at ambient temperature and pressure. Demand clusters in FDA-regulated pharmaceutical intermediates where ECHA REACH restrictions on heavy-metal catalysts accelerate substitution timelines.
- Whole Cells:Intact microbial systems execute multi-step metabolic pathways without enzyme purification overhead. Chemical producers in Rotterdam-Antwerp port zones deploy these for bulk agricultural intermediate manufacturing where cofactor regeneration complexity would otherwise escalate costs.
- Co-factors:NAD(P)H and ATP regenerating compounds enable redox biocatalysis in fine chemical synthesis.
- Biocatalyst Systems:Pre-integrated enzyme-immobilization-reactor packages reduce process development burden for mid-tier manufacturers.
Volume placements concentrate in Enzymes; the faster expansion belongs to Biocatalyst Systems.
Application:
Margin tiering separates blockbuster drug chiral steps from commodity starch hydrolysis.
- Pharmaceuticals:Chiral synthesis of small-molecule APIs commands premium pricing due to FDA validation requirements and EMA purity thresholds. Boston-Cambridge and Basel-Zurich biotech clusters source customized lipases and transaminases for late-stage clinical candidates.
- Agriculture:Biocatalytic routes to pesticide intermediates preempt EPA enforcement on solvent-intensive chemical processes. Iowa-Illinois agricultural chemical corridors retrofit amide bond formation with immobilized hydrolases.
- Food & Beverages:Starch processing and dairy enzyme applications sustain high-volume, lower-margin supply relationships.
- Biofuels:Cellulase cocktails for lignocellulosic ethanol face cost pressure from petroleum price volatility.
Revenue concentration sits with Pharmaceuticals; Food & Beverages maintains shipment leadership.
End User:
Procurement sophistication divides validated pharmaceutical suppliers from price-sensitive commodity buyers.
- Biotech Companies:Virtual drug developers outsource biocatalytic step development to specialized CDMOs, purchasing validated enzymes through distributor networks rather than captive fermentation.
- Research Institutions:Academic laboratories source catalog enzymes for proof-of-concept studies with minimal customization requirements.
- Food Manufacturers:Dairy and starch processors procure enzyme blends through annual tenders with specification-driven supplier qualification.
- Chemical Producers:Agrochemical and specialty chemical manufacturers face the steepest regulatory substitution pressure from EPA and ECHA enforcement.
Contract value peaks with Biotech Companies; order frequency dominates among Food Manufacturers.
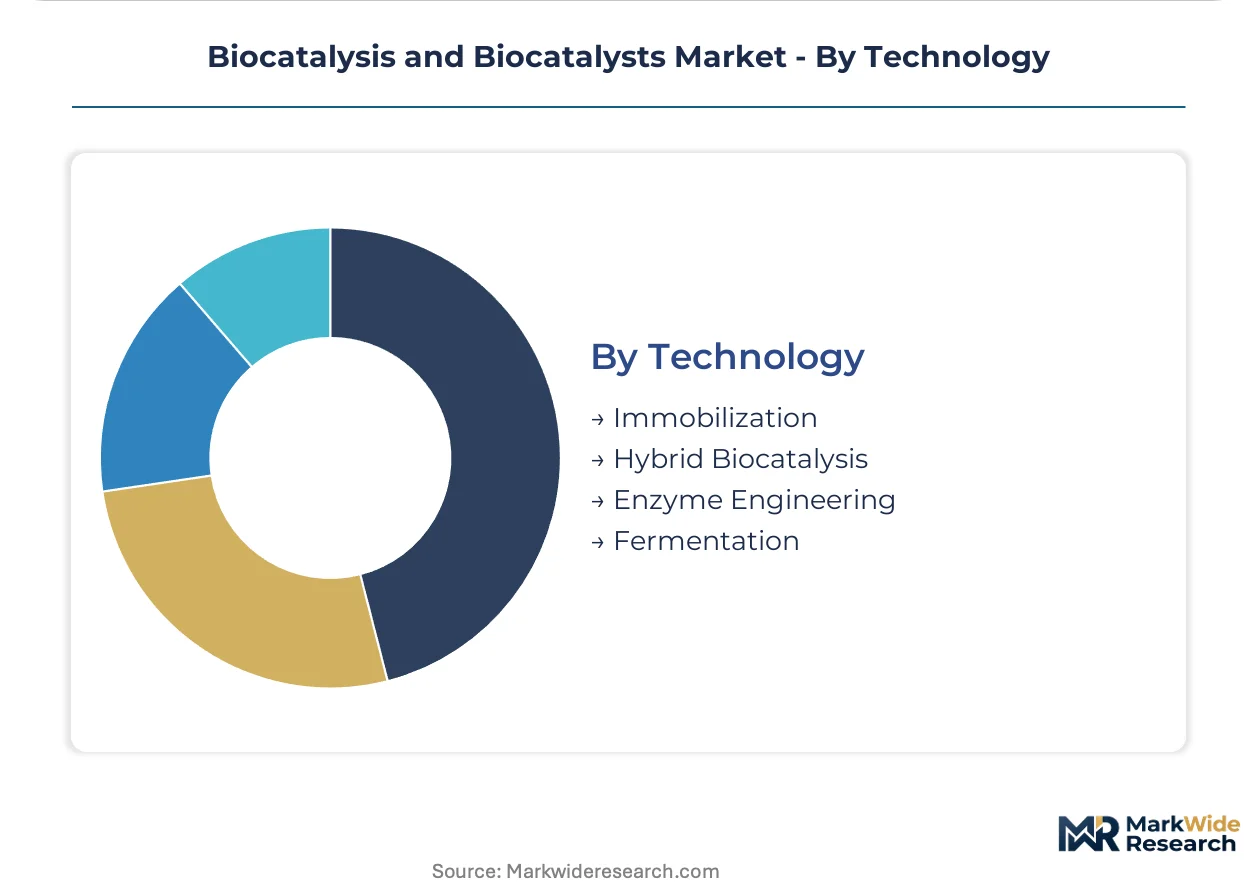
Technology:
Platform maturity determines whether customers license process technology or purchase commoditized enzyme units.
- Immobilization:Enzyme attachment to solid supports enables reactor reuse and continuous flow operation. Pharmaceutical manufacturers in North Rhine-Westphalia adopt these systems for GMP-compliant multi-ton campaigns.
- Hybrid Biocatalysis:Chemoenzymatic cascades combine biological and chemical steps for non-natural substrate scope. This approach gains traction where single-enzyme limitations would otherwise exclude biocatalytic routes.
- Enzyme Engineering:Directed evolution and computational design platforms compress variant optimization timelines. Machine learning-guided protein design is democratizing access to thermostable and solvent-tolerant variants.
- Fermentation:Upstream cell culture and downstream recovery operations supply bulk enzyme quantities for food and detergent applications.
Deployment scale favors Fermentation; capability premiums attach to Enzyme Engineering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Danish fermentation infrastructure anchors European enzyme supply chains, while Chinese and Indian manufacturing bases scale to serve domestic chemical and food processing demand. Regulatory pressure from EPA and REACH directives is synchronizing substitution timelines across industrial corridors.
United States
Pharmaceutical manufacturers in the Boston-Cambridge and San Diego clusters drive demand for chiral synthesis enzymes as they replace solvent-heavy chemical steps. EPA industrial chemical guidelines enforce emission thresholds that favor enzymatic process retrofits. Texas and Louisiana chemical corridors host the fastest capacity expansions for biocatalytic intermediate production.
Germany
Specialty chemical producers in North Rhine-Westphalia deploy immobilized enzyme systems for GMP-compliant multi-ton campaigns. ECHA REACH substance authorization restricts heavy-metal catalysts, redirecting R&D budgets toward validated enzyme suppliers. The Cologne-Düsseldorf industrial belt concentrates fermentation capacity expansion for pharmaceutical-grade outputs.
China
Provincial emissions inspectors under MEE dual carbon goals grant expedited permitting to facilities demonstrating enzymatic substitution. Yangtze River Delta chemical parks retrofit amide bond formation steps with lipase biocatalysis. Shanghai and Jiangsu province anchor the fastest-growing domestic enzyme engineering talent pools.
India
Dairy and starch processing sectors in Gujarat and Maharashtra remain under-supplied with tailored enzyme blends versus Western benchmarks. FSSAI food-grade certification requirements are tightening, favoring suppliers with validated quality systems. The Mumbai-Pune industrial corridor attracts contract manufacturing investments for export-oriented biocatalyst production.
Netherlands
Rotterdam-Antwerp port zone chemical producers face coordinated EPA-ECHA enforcement pressure on solvent-intensive processes. The country leverages integrated fermentation networks to supply nutrition and pharma-grade biocatalyst outputs. Eindhoven and the Randstad region concentrate biotech infrastructure scaling that compresses enzyme production lead times.
Biocatalysis and Biocatalysts Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-directed enzyme engineering and continuous flow biocatalysis. The market structures around three tiers: integrated fermentation giants, specialized enzyme engineering boutiques, and contract development distributors. Competitive moves concentrate on capacity expansion in Denmark-Netherlands corridor and strategic partnerships for pharmaceutical validation services. Technology licensing agreements are proliferating as machine learning platforms democratize access to high-performance variants.
Within the integrated fermentation tier, Novozymes A/S and DSM-Firmenich exemplify scale-driven supply chain dominance. Novozymes A/S leverages its Danish production base to anchor industrial enzyme distribution networks. DSM-Firmenich represents the nutrition-pharma convergence through captive fermentation capacity. BASF SE occupies a position among diversified chemical conglomerates pursuing specialty enzyme intermediates. Codexis, Inc. sits within the enzyme engineering specialist archetype, reflecting the premium attached to directed evolution capabilities.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Amano Enzyme Inc |
| Novozymes A/S |
| DuPont de Nemours |
| Chr. Hansen Holding |
| Codexis, Inc. |
| AB Enzymes GmbH |
| Biocatalysts Ltd. |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical process chemists in Boston-Cambridge and Basel-Zurich clusters anchor demand for validated biocatalysts, driving a contract-based pricing model where FDA certification tiers separate premium enzyme engineering services from commodity fermentation outputs. This buyer concentration enables suppliers to bundle process licensing with per-campaign enzyme supply, while food-grade purchasers in India and China negotiate on spot-market terms.
Pricing Analysis
Service bundling separates enzyme supply from process validation, with pharmaceutical CDMOs purchasing unbundled catalysts through distributor networks while retaining in-house regulatory filing responsibility. Three-tier pricing structure across premium, standard, and economy levels reflects FDA validation status, fermentation scale, and geographic delivery cost. Cost compression in food-grade lipases is intensifying because Indian dairy processors are consolidating annual tenders around fewer qualified suppliers. Chemical producers in Rotterdam-Antwerp zones show least price sensitivity due to ECHA enforcement-driven substitution mandates.
Supply Chain Analysis
Fermentation feedstock supply rests on Danish, Dutch, and German agricultural input networks, with glucose and nitrogen sources drawing from EU bioethanol byproduct streams. Protein engineering talent pools concentrate in Copenhagen-Aarhus, Shanghai-Jiangsu, and Boston-San Diego corridors. Single-source vulnerability clusters around the Denmark-Netherlands enzyme production belt, where Novozymes and DSM-Firmenich anchor capacity. Distribution runs through specialized biochemical distributors serving pharmaceutical CDMOs, with direct sales relationships dominating food and agriculture sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biocatalysis market sits in a technology-transition phase, with AI-directed enzyme engineering displacing traditional directed evolution timelines and compressing competitive moats around established suppliers.
For Market Incumbents: To counter democratized access to high-performance variants through machine learning platforms, Novozymes and DSM-Firmenich should deepen backward integration into computational protein design capabilities and expand GMP-certified fermentation capacity in North Rhine-Westphalia to anchor pharmaceutical validation services. For New Entrants and Emerging Players: REACH substance authorization in Europe opens a window for specialized enzyme engineering boutiques to capture share in chiral synthesis services, with under-supplied Indian dairy and starch processing sectors offering the most penetrable white-space for food-grade penetration through FSSAI-certified quality systems. For Investors and Strategic Acquirers: The window for entry favors AI-enabled enzyme engineering specialists with demonstrated thermostable variant libraries, with long-term viability hinging on pharmaceutical CDMO relationships and regulatory validation track records. Watch FDA biocatalytic intermediate certification timelines as the inflection signal for revenue recognition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Directed Enzyme Engineering Investment | Machine learning platforms compress optimization cycles from years to months for pharmaceutical process chemists. |
| GMP Fermentation Capacity Expansion | North Rhine-Westphalia facilities anchor multi-ton campaigns for FDA-regulated pharmaceutical intermediates. |
| Regulatory Validation Partnership | CDMO alliances in Boston-San Diego corridor secure 18-24 month FDA certification pathways. |
| India Food-Grade Distribution Buildout | Gujarat and Maharashtra dairy processors seek FSSAI-qualified enzyme blend suppliers. |
| Continuous Flow Biocatalysis Licensing | Immobilized enzyme-reactor packages reduce retrofit burden for legacy chemical plants. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted across fermentation plant managers, pharmaceutical process chemists, CDMO procurement leads, and regulatory affairs directors at ECHA and FDA. EMA submission databases, EPA enforcement records, and Cefic chemical production statistics provided validation benchmarks. Bottom-up enzyme shipment tracking and top-down pharmaceutical manufacturing value analysis enabled triangulation.
Data-stream reconciliation across product type, application, end user, and technology dimensions shaped the analytical framework across the analysis window. CAGRs derived from segment-level shipment velocity and value-per-unit trends, with pharmaceutical chiral synthesis premiums and food-grade volume baselines as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for machine learning-guided protein design would alter the outlook if algorithmic prediction accuracy stalls or regulatory validation timelines extend. Forecasts reflect assumptions on EPA-ECHA enforcement synchronization and enzyme substitution economics. A small set of named triggers—FDA certification backlog, Denmark supply disruption, and China MEE permitting acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Biocatalyst Market
Industrial Biotechnology
GCC Biocatalyst Market
Industrial Biotechnology
Global Enzymes Market
Industrial Biotechnology
Haematococcus Pluvialis Market
Industrial Biotechnology
Global Carbohydrase Market
Industrial Biotechnology
Pyruvate Synthase Market
Industrial Biotechnology
Protease Market
Industrial Biotechnology
China Specialty Enzymes Market
Industrial Biotechnology
Xylanase Market
Industrial Biotechnology
Hydrolase Enzymes Market
Industrial Biotechnology
Tannase Market
Industrial Biotechnology
Industrial Enzymes Market
Industrial Biotechnology
Esterase Market
Industrial Biotechnology
Inulinase Market
Industrial Biotechnology
Global Protein Hydrolysis Enzymes Market
Industrial Biotechnology
Marine Enzymes Market