
 White Biotech Market | 2026-2036
White Biotech Market Size, Share, and Industry Trends Forecast 2026-2036
White Biotech Market Analytics
Pharmaceutical-grade enzyme specifications is collapsing the gap between commodity bioprocessing and high-value therapeutic manufacturing. Lonza Group Ltd leverages its Swiss manufacturing network to sustain cGMP-compliant fermentation capacity for active pharmaceutical ingredients. Novozymes dominates industrial enzyme supply for detergents and textiles, while DSM-Firmenich AG anchors nutrition and fragrance biotechnology through integrated strain development platforms.
White biotechnology applies living cells or enzymes to manufacture chemicals, materials, and energy carriers, typically operating at 30-60°C and atmospheric pressure with aqueous solvents to reduce energy intensity versus petrochemical routes. Fermentation technology leads commercial deployment due to mature reactor engineering and strain optimization protocols, while genetic engineering commands premium margins through CRISPR-edited microbial cell factories producing rare organic acids. Enzyme applications in food processing and pharmaceuticals concentrate value capture, whereas biofuels compete primarily on carbon policy arbitrage rather than standalone cost parity.
EMA's Good Manufacturing Practice guidelines for biologically active substances shape facility investment thresholds across European pharmaceutical applications, while EPA's Renewable Fuel Standard and REACH registration requirements steer product development priorities in the United States and European Union respectively. China's NMPA biologics oversight and GB standards for industrial biotechnology create parallel compliance architectures for multinational firms operating dual supply chains. Stakeholders must monitor how divergent carbon border adjustment mechanisms reshape the cost competitiveness of imported versus domestically produced bioplastics and biofuels.
Market Dynamics
EU Green Deal industrial emissions rules are forcing pharmaceutical manufacturers to abandon petrochemical synthesis routes in favor of enzyme-based drug manufacturing, collapsing the traditional separation between commodity bioprocessing and high-value therapeutic production.
Growth Catalysts
- REACH registration pathways:European chemical safety frameworks now favor bio-based feedstock documentation over petrochemical hazard assessments, accelerating regulatory approval timelines for fermentation-derived intermediates.
- Fermentation scale-up:Mature reactor engineering and strain optimization protocols enable cost-competitive production of rare organic acids previously sourced from petroleum cracking.
- China:NMPA biologics oversight and GB standards for industrial biotechnology create dedicated compliance fast-tracks for multinational firms establishing dual supply chains.
Market Restraints
- Sugar feedstock volatility:Corn and sugarcane price swings in Brazil and the United States compress margins for first-generation fermentation processes lacking long-term agricultural contracts.
- Strain IP concentration:CRISPR-edited microbial cell factories remain controlled by a narrow patent pool, limiting independent development of novel production organisms.
- Steam sterilization energy:cGMP-compliant fermentation facilities face elevated natural gas costs for continuous autoclave operations, disadvantaging European producers against jurisdictions with cheaper thermal energy.
Strategic Opportunities
- India:PLI scheme incentives for bulk drug manufacturing create openings for enzyme-based API production serving domestic formulation and export markets.
- Carbon border adjustments:EU CBAM implementation rewards bioplastics with verified lifecycle emissions advantages over imported petrochemical polymers.
- Continuous processing convergence:Integration of real-time analytics with perfusion fermentation is displacing batch operations in high-value therapeutic protein manufacturing.
Industry Challenges
- Metabolic engineering talent scarcity:Strain development pipelines stall due to insufficient computational biologists capable of integrating multi-omics datasets with predictive metabolic models.
- cGMP facility retrofit timelines:Converting commodity fermentation plants to pharmaceutical-grade specifications requires 18-24 month validation cycles under EMA guidelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Biotech Market |
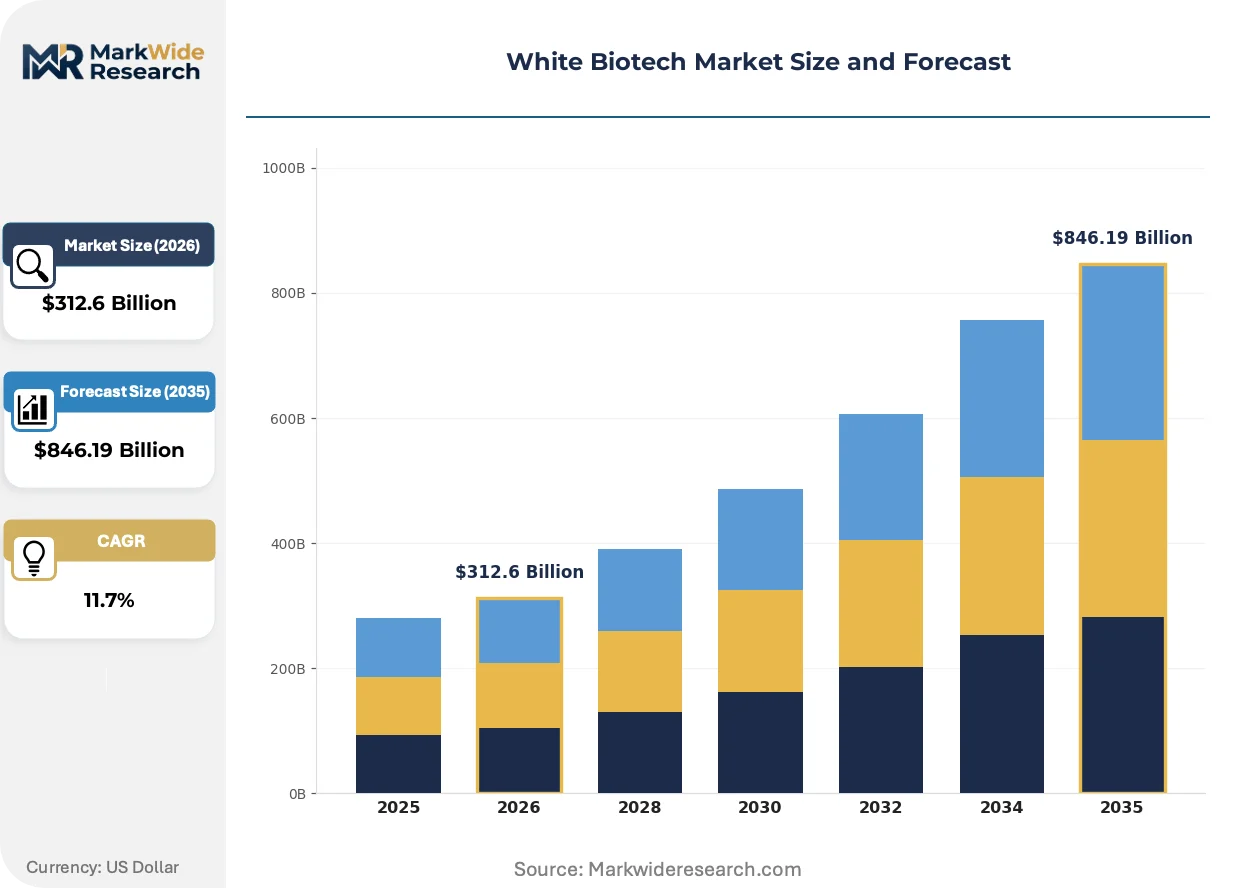
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $846.19 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biofuels, Bioplastics, Enzymes, Organic Acids Technology: Fermentation, Biotechnology Processes, Genetic Engineering, Bioprocessing End User: Agriculture, Chemicals, Food & Beverage, Pharmaceuticals Application: Biosurfactants, Bio-Detergents, Bioremediation, Waste Management |
| Companies Covered | Lonza Group Ltd, International Flavors & Fragrances Inc., Corbion NV, DSM-Firmenich AG, BASF SE, Novozymes, DuPont de Nemours Inc., Evonik Industries AG, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Biotech Market Evolving Landscape
White biotechnology is undergoing a platform shift from batch fermentation toward continuous biomanufacturing, driven by advances in process analytical technology and intensifying pressure to demonstrate lifecycle carbon advantages over petrochemical routes.
CRISPR-Cas9 multiplexed genome editing is displacing random mutagenesis and metabolic evolution as the dominant strain development methodology. Pharmaceutical enzyme producers in Switzerland and Germany now deploy edited microbial chassis to manufacture complex chiral intermediates with 40-60% yield improvements. This precision is compressing development timelines for novel biocatalysts from 36 months to under 18 months.
EPA's Renewable Fuel Standard and California LCFS credit mechanisms are redirecting capital toward cellulosic ethanol and advanced biofuel pathways. Industrial biotechnology firms respond by engineering cellulase cocktails and consolidated bioprocessing organisms capable of operating on agricultural residue feedstocks. The regulatory arbitrage between federal RIN values and state-level carbon intensity scores determines facility siting decisions across the Midwest and Southeast United States.
Long-term offtake agreements are replacing spot purchasing for industrial enzymes and fermentation-derived chemicals. Detergent and textile manufacturers in Germany and the Netherlands now contract directly with enzyme suppliers for five-year supply commitments with price escalation clauses tied to agricultural input indices. This contract manufacturing model is concentrating procurement power among the largest end-users while squeezing mid-tier bioprocessing houses dependent on merchant sales.
White Biotech Market Segmentation
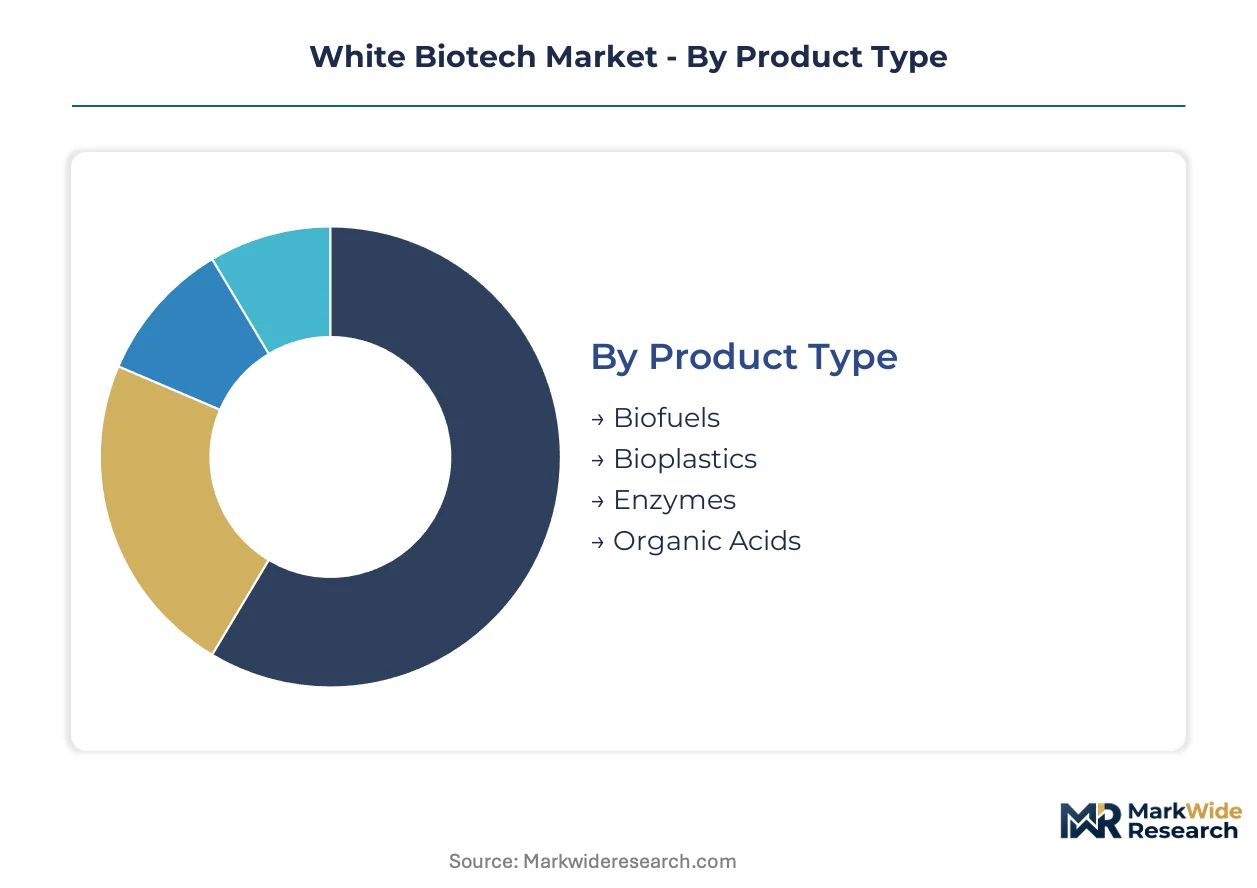
White biotechnology spans divergent value chains where pharmaceutical-grade enzymes command premium pricing while commodity biofuels compete on carbon policy arbitrage. Segmentation reveals how technology maturity and regulatory pressure concentrate investment across product categories.
Product Type:
Enzymes and organic acids flow through cGMP-certified pharmaceutical channels, while biofuels and bioplastics distribute via bulk chemical terminals and polymer converters.
- Enzymes:Protein biocatalysts operating at 30-60°C with aqueous solvents reduce energy intensity versus petrochemical routes. Pharmaceutical manufacturers in Germany and Switzerland concentrate demand for cGMP-compliant therapeutic enzymes as EMA guidelines tighten. FDA and EMA quality standards create dual validation requirements for cross-border supply.
- Organic Acids:Fermentation-derived citric, lactic, and succinic acids serve as platform chemicals for biodegradable polymers. China's NMPA biologics oversight and GB standards create dedicated compliance fast-tracks for multinational firms establishing dual supply chains.
- Biofuels:Cellulosic ethanol and advanced biofuel pathways compete on EPA Renewable Fuel Standard RIN values and California LCFS carbon intensity scores.
- Bioplastics:Fermentation-derived polyhydroxyalkanoates and polylactic acid face EU CBAM lifecycle emissions verification for import competitiveness.
Enzymes dominate installed base. Bioplastics is where expansion concentrates.
Technology:
Cost tier separates mature fermentation infrastructure from capital-intensive genetic engineering platforms requiring specialized talent.
- Fermentation:Mature reactor engineering and strain optimization protocols enable cost-competitive production at atmospheric pressure. Brazil and United States agricultural feedstock proximity supports first-generation ethanol scale.
- Genetic Engineering:CRISPR-edited microbial cell factories produce rare organic acids with 40-60% yield improvements over random mutagenesis. Strain IP concentration in narrow patent pools limits independent organism development.
- Biotechnology Processes:Integrated downstream purification and continuous processing convergence displace batch operations in high-value therapeutic manufacturing.
- Bioprocessing:Real-time analytics integration with perfusion fermentation reduces facility footprint for active pharmaceutical ingredient production.
Fermentation anchors volume scale. Genetic engineering captures margin expansion.
End User:
Application maturity varies sharply: food processing enzymes deploy at commodity scale while pharmaceutical biocatalysts require extended validation cycles.
- Pharmaceuticals:Enzyme-based drug synthesis replaces petrochemical routes under EU Green Deal industrial emissions rules. EMA Good Manufacturing Practice guidelines shape 18-24 month facility retrofit timelines.
- Food & Beverage:Processing enzymes for dairy, baking, and beverage applications operate under FSSAI standards in India and FDA GRAS determinations in the United States.
- Chemicals:Bio-based intermediates compete on REACH registration pathway advantages over petrochemical hazard assessments.
- Agriculture:Biofertilizers and biocontrol agents face divergent national registration requirements across Brazil ANVISA and India Central Insecticides Board frameworks.
Food & Beverage holds largest installed capacity. Pharmaceuticals is climbing the fastest.
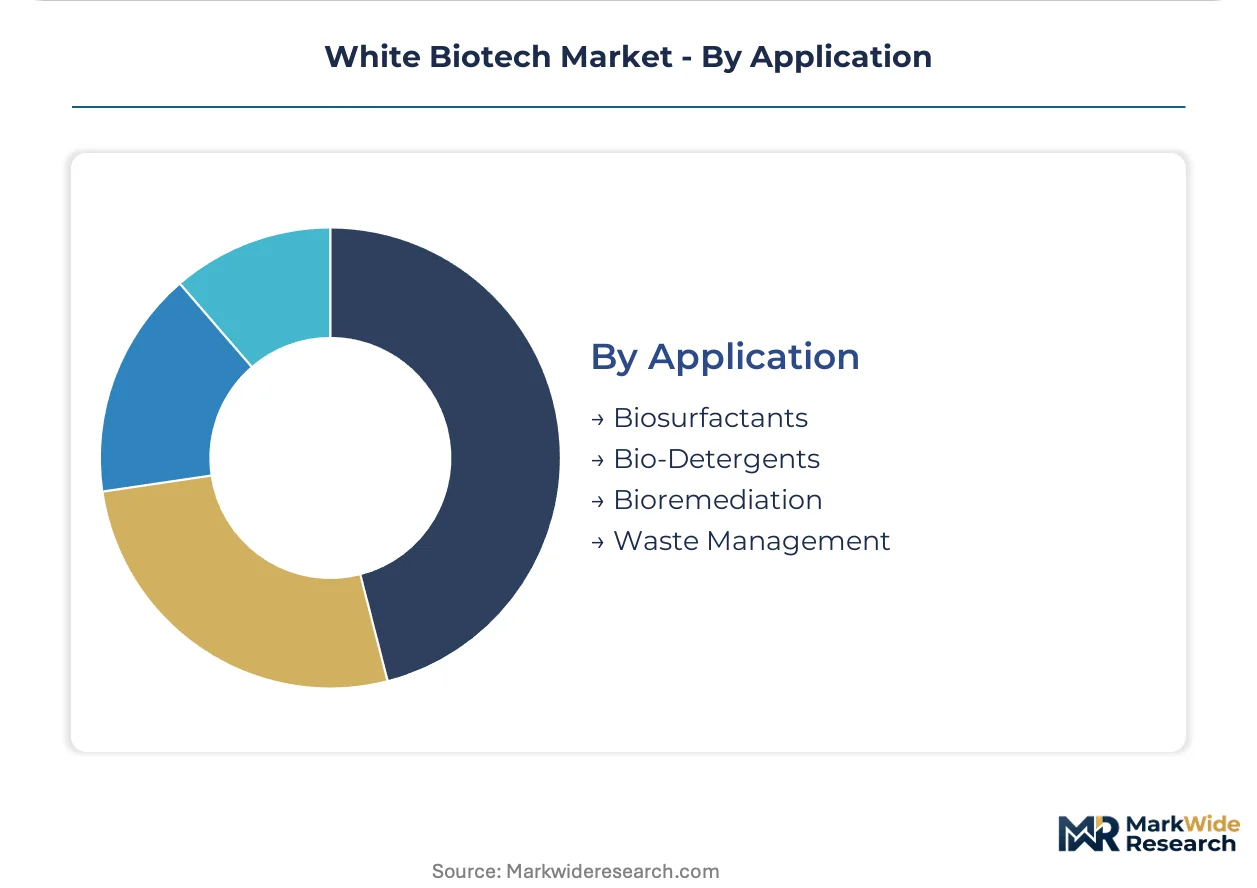
Application:
Customer procurement patterns differentiate: biosurfactants and bio-detergents move through five-year offtake contracts, while bioremediation and waste management rely on project-based municipal tendering.
- Bio-Detergents:Protease, lipase, and cellulase formulations for household and industrial cleaning. Germany and Netherlands manufacturers contract directly with enzyme suppliers for agricultural input-indexed price escalation.
- Bioremediation:Engineered microbial consortia for soil and groundwater decontamination. EPA remediation standards and state-level brownfield programs drive site-specific deployment.
- Biosurfactants:Rhamnolipid and sophorolipid production from agricultural residue feedstocks competes on petroleum surfactant substitution economics.
- Waste Management:Anaerobic digestion and composting accelerators face municipal procurement budget constraints and seasonal demand variation.
Bio-Detergents commands contract manufacturing concentration. Bioremediation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances diverge sharply across major white biotechnology hubs, with fermentation-derived intermediates flowing from feedstock-rich jurisdictions toward regulatory-premium markets in Europe and North America.
United States
EPA Renewable Fuel Standard RIN values and California LCFS carbon intensity scores redirect capital toward cellulosic ethanol facilities in the Midwest and Southeast. Archer Daniels Midland operates large-scale fermentation infrastructure in Illinois and Iowa. The Corn Belt's agricultural residue proximity anchors first-generation biofuel scale while advanced bioprocessing clusters emerge around research universities in Massachusetts and California.
Germany
EU Green Deal industrial emissions rules and REACH registration advantages accelerate enzyme-based pharmaceutical manufacturing. BASF SE and Evonik Industries AG maintain integrated biotechnology operations in Ludwigshafen and Marl. The Rhine-Ruhr chemical corridor concentrates cGMP fermentation retrofit activity as EMA guidelines tighten facility standards.
China
NMPA biologics oversight and GB standards for industrial biotechnology create dedicated compliance fast-tracks for multinational firms. Zhejiang and Jiangsu provinces host contract fermentation capacity serving global active pharmaceutical ingredient demand. Shanghai's Zhangjiang Hi-Tech Park clusters CRISPR-edited microbial strain development platforms.
Switzerland
Swissmedic pharmaceutical regulations and cGMP enforcement sustain premium positioning for therapeutic enzyme exports. Lonza Group Ltd leverages its Basel-region manufacturing network for cross-border supply into EU and US markets. The country's neutrality framework attracts dual supply chain investments from firms hedging regulatory divergence.
India
PLI scheme incentives for bulk drug manufacturing create openings for enzyme-based API production serving domestic formulation and export markets. Maharashtra and Gujarat concentrate fermentation capacity with FSSAI-aligned food processing enzyme operations. Hyderabad's Genome Valley anchors contract research organizations supporting strain optimization for Western pharmaceutical clients.
White Biotech Market Competitive Landscape
Concentration sits with diversified chemical conglomerates that have backward integrated into biotechnology through acquisition and capacity expansion. The vendor base stratifies across three tiers: integrated life science platforms commanding pharmaceutical-grade margins, industrial enzyme specialists capturing detergent and textile volumes, and regional fermentation houses competing on agricultural feedstock access. Strategic moves center on cGMP facility retrofitting to capture EU Green Deal-driven pharmaceutical demand, and long-term offtake contracting to lock in detergent and bio-detergent procurement relationships.
Within the integrated life science tier, Lonza Group Ltd and DSM-Firmenich AG exemplify the convergence of pharmaceutical manufacturing compliance with industrial biotechnology scale. Novozymes occupies a position as the reference industrial enzyme supplier for detergent and textile applications. Among diversified chemical conglomerates, BASF SE and Evonik Industries AG represent the pattern of petrochemical majors capturing fermentation-derived intermediate markets through capital deployment rather than organic technology development.
| Leading Market Players |
|---|
| Lonza Group Ltd |
| International Flavors & Fragrances Inc. |
| Corbion NV |
| DSM-Firmenich AG |
| BASF SE |
| Novozymes |
| DuPont de Nemours Inc. |
| Evonik Industries AG |
| Archer Daniels Midland Company |
| Others |
Value Network & Pricing Analysis
Enzyme substitution for petrochemical catalysts redraws procurement geography and pricing power across fermentation-derived intermediates. EU REACH registration advantages for bio-based feedstocks compress approval timelines while elevating documentation costs, forcing buyers to absorb premium tiers for verified lifecycle emissions data.
Pricing Analysis
Industrial OEM buyers anchor contract manufacturing structures through five-year offtake agreements with agricultural input-indexed escalation clauses. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and commodity fermentation tiers separates cGMP-validated enzymes from detergent biocatalysts. Cost compression in first-generation ethanol runs through Brazilian and United States corn price volatility. Detergent manufacturers in Germany and the Netherlands exhibit highest price sensitivity due to bulk volume procurement, while Swiss pharmaceutical firms accept premium tiers for cross-border regulatory compliance.
Supply Chain Analysis
Inventory buffers stretch 12-16 weeks for CRISPR-edited microbial strains due to narrow patent concentration and single-source licensing dependencies. Supply concentrates in China, Germany, and Switzerland for cGMP fermentation capacity, with Brazil and the United States anchoring first-generation biofuel scale. Corn and sugarcane feedstock costs hinge on agricultural commodity futures. Single-source vulnerability sits with cellulase cocktail suppliers for cellulosic ethanol pathways. Distribution runs through bulk chemical terminals for bioplastics and dedicated cold-chain logistics for therapeutic enzymes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
White biotechnology offers substantial service-attach potential through strain optimization contracts and continuous processing retrofits expanding faster than commodity fermentation hardware sales. Recurring revenue from real-time analytics integration and perfusion fermentation support layers outpaces capital equipment margins.
For Market Incumbents: Compound defensive moats by backward integrating into agricultural feedstock origination in Brazil and the United States, securing margin insulation against sugar price volatility. Accelerate cGMP facility retrofitting in the Rhine-Ruhr corridor to capture EU Green Deal-driven pharmaceutical enzyme demand before 18-24 month validation cycles congest qualified capacity. Patent thickets around CRISPR-edited chassis represent the primary threat vector requiring licensing alliance construction. For New Entrants and Emerging Players: Anchor in India's PLI scheme corridors for bulk drug manufacturing, where enzyme-based API production serves underpenetrated domestic formulation and export markets. Target bioremediation applications as the fastest-expanding white-space segment, leveraging project-based municipal tendering structures that bypass incumbent long-term contracting dominance. Lead with engineered microbial consortia for soil decontamination as the specific go-to-market wedge. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract fermentation houses possessing cGMP validation but lacking integrated strain development platforms. Five-to-ten year viability hinges on carbon border adjustment mechanism expansion rewarding verified lifecycle emissions advantages. Monitor EU CBAM implementation timelines as the critical inflection signal for bioplastics import competitiveness versus petrochemical polymers.| Strategic Initiative | Industry Significance |
|---|---|
| cGMP Facility Retrofit | EMA compliance timelines concentrate qualified capacity for EU pharmaceutical enzyme demand. |
| Long-term Supply Agreement | Five-year offtake contracts with agricultural indexation lock detergent manufacturer procurement relationships. |
| Backward Integration | Corn and sugarcane origination in Brazil and the United States secures feedstock cost predictability. |
| Platform Integration | Real-time analytics with perfusion fermentation displaces batch operations in therapeutic protein manufacturing. |
| Green Manufacturing Transition | EU REACH registration pathways accelerate regulatory approval for fermentation-derived intermediates. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation plant managers, pharmaceutical regulatory affairs leads, detergent procurement directors, and strain development scientists and refined through secondary validation. Bottom-up capacity assessments triangulated with top-down demand modeling across customs trade data, EMA GMP inspection databases, EPA Renewable Fuel Standard compliance filings, and SEC 10-K disclosures from diversified chemical conglomerates.
Variance decomposition separates volume drivers from price mix effects across the projection horizon. Segmentation dimensions span product type, technology maturity tier, end-use industry, and regional regulatory cluster. CAGRs derive from installed base growth rates and replacement cycle timing. Forecast inputs incorporate NMPA biologics oversight trajectory and EU CBAM lifecycle emissions verification rollout pace.
Decision-makers should treat outputs as directional under sustained EU Green Deal implementation and stable agricultural commodity regimes; material deviation would warrant model refresh. Specific risks include CRISPR patent pool fragmentation, natural gas cost spikes affecting steam sterilization economics, and divergent carbon border adjustment mechanisms. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Xylanase Market
Industrial Biotechnology
Unnatural Amino Acids Market
Industrial Biotechnology
Europe Biocatalyst Market
Industrial Biotechnology
Pyruvate Synthase Market
Industrial Biotechnology
Protease Market
Industrial Biotechnology
Haematococcus Pluvialis Market
Industrial Biotechnology
North America Biocatalysts Market
Industrial Biotechnology
Hydrolase Enzymes Market
Industrial Biotechnology
Inulinase Market
Industrial Biotechnology
Americas Enzymes Market
Industrial Biotechnology
Protease Enzyme Market
Industrial Biotechnology
Bio-Refinery Market
Industrial Biotechnology
Global Enzymes Market
Industrial Biotechnology
Beta-Glucanase Market
Industrial Biotechnology
Global Carbohydrase Market
Industrial Biotechnology
White Biotechnology Market