
 Europe Biocatalyst Market | 2026-2036
Europe Biocatalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biocatalyst Market Intelligence
Enzyme engineering talent scarcity is reorganizing competitive dynamics across the European biocatalyst landscape. Novozymes A/S leverages its Danish R&D base to sustain leadership in industrial enzyme platforms. BASF SE anchors its position through backward integration into fermentation capacity at its Ludwigshafen complex. Chr. Hansen Holding A/S specializes in food-grade biocatalysts, occupying a defensible niche within dairy and beverage applications.
Biocatalysts are protein-based biological molecules, typically enzymes or whole-cell systems, that accelerate chemical reactions under mild temperature and pH conditions with high substrate specificity. Their primary industrial purpose is to replace energy-intensive petrochemical routes with selective, low-waste transformations in pharmaceutical intermediate synthesis and food processing. Hydrolases command the largest share of the European type landscape due to their established deployment in starch processing and detergent formulations. The pharmaceutical application segment is expanding fastest as batch-to-continuous manufacturing transitions favor enzymatic cascades for chiral molecule production. Immobilized enzyme forms capture premium pricing because their reusability reduces downstream purification costs in multi-step syntheses.
EMA guidelines on biocatalytic processes in drug manufacturing, REACH substance registration requirements, and the EU Green Deal industrial emissions targets collectively mandate cleaner production methodologies across European chemical operations. These frameworks push manufacturers toward enzymatic alternatives that reduce solvent volumes and eliminate heavy-metal catalyst residues. Stakeholders must monitor how the EU AI Act and proposed CSRD reporting standards will reshape documentation requirements for biocatalytic process validation and supply chain transparency.
Market Dynamics
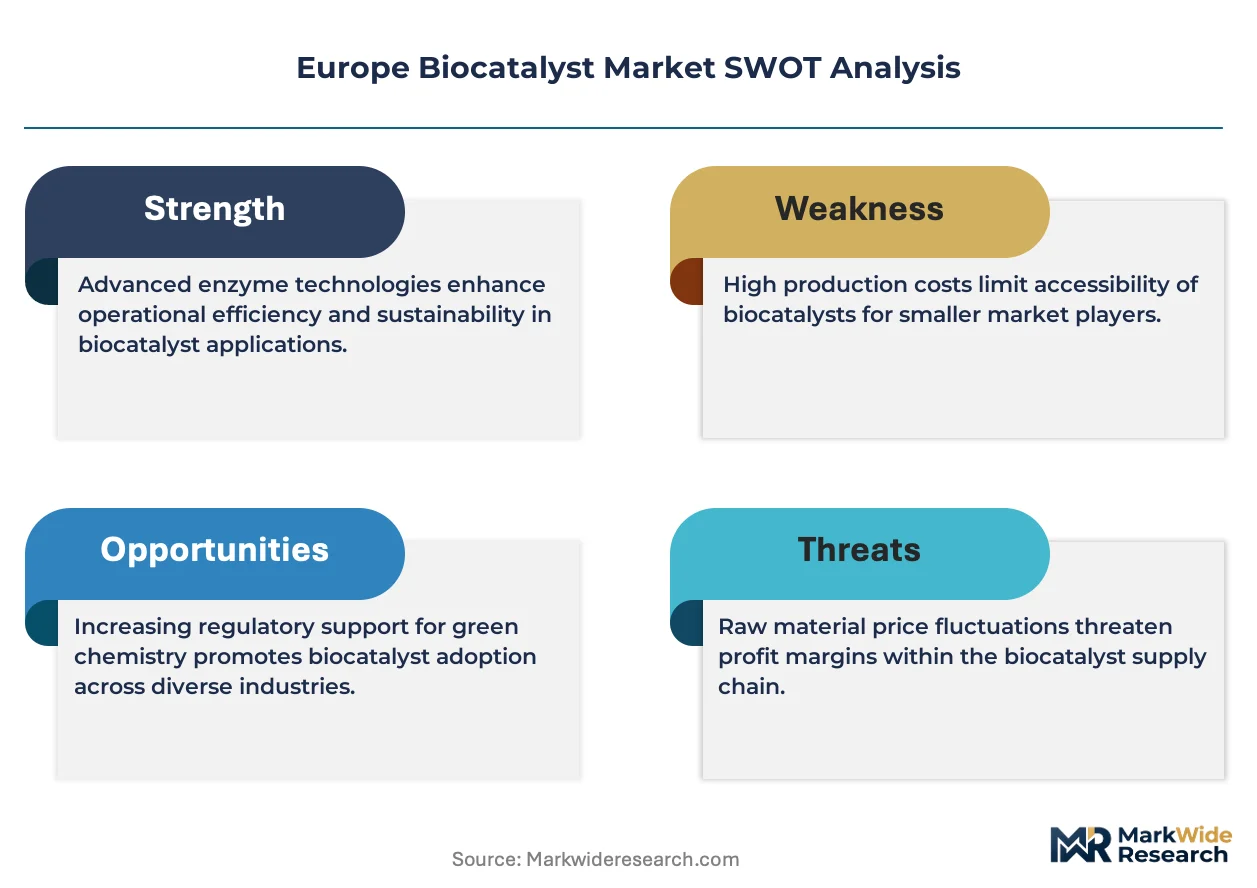
The EU Green Deal's industrial emissions targets are compressing the timeline for chemical manufacturers to transition from petrochemical catalysts to enzymatic alternatives, creating a structural pull that reorganizes capital allocation across European production facilities.
Growth Catalysts
- REACH compliance deadlines:Chemical manufacturers face mandatory substance registration requirements that favor biocatalytic routes eliminating heavy-metal residues from pharmaceutical intermediates.
- Netherlands biotech corridor expansion:Concentrated fermentation infrastructure around Leiden and Delft accelerates pilot-to-production scaling for enzyme manufacturers serving Western European demand.
- Continuous manufacturing transition:Pharmaceutical batch-to-continuous process conversions favor immobilized enzyme cascades for chiral molecule synthesis, expanding addressable volume.
Market Restraints
- Feedstock concentration risk:Specialized fermentation media and cell-line supply concentrate among a limited set of German and Danish bioprocess suppliers, creating input vulnerability.
- Capital intensity barrier:GMP-grade enzyme production facilities require eight-figure euro investments that exclude mid-scale chemical manufacturers from backward integration.
- Performance ceiling in extreme chemistries:Enzyme stability limitations in non-aqueous solvents and high-temperature conditions restrict substitution potential in certain specialty chemical segments.
Strategic Opportunities
- CSRD reporting mandates:The EU's Corporate Sustainability Reporting Directive creates first-mover advantage for biocatalyst suppliers offering documented carbon-intensity reductions to Scope 3-conscious chemical buyers.
- Spain and Italy fermentation capacity:Underutilized bioprocessing infrastructure in Southern European chemical parks presents acquisition targets for enzyme producers seeking geographic diversification.
- AI-driven enzyme discovery convergence:Machine learning platforms for protein structure prediction compress R&D timelines, enabling faster customization for niche pharmaceutical intermediates.
Industry Challenges
- Protein engineering talent scarcity:European universities produce insufficient computational biologists and enzymologists to staff expanding industrial biotech R&D functions, inflating compensation costs.
- EMA process validation timelines:Biocatalytic route changes in approved drug manufacturing trigger 18-24 month regulatory review cycles that delay revenue realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biocatalyst Market |
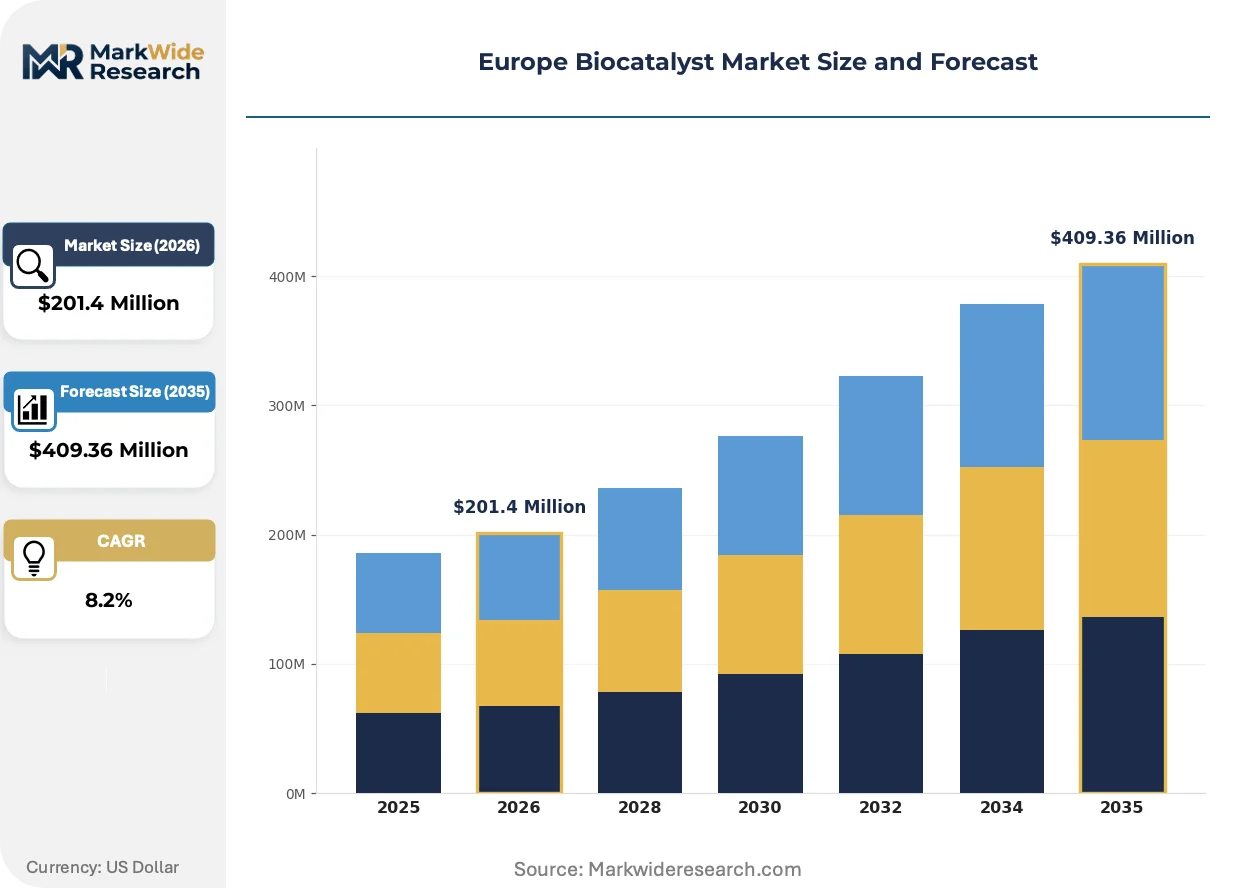
| Market Size in 2026 | $201.4 Million |
| Market Size in 2035 | $409.36 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hydrolases, Oxidoreductases, Transferases, Lyases Application: Food & Beverage, Biofuels, Pharmaceuticals, Agriculture Form: Liquid, Powder, Immobilized, Freeze-Dried End User: Chemical Industry, Pharmaceutical Companies, Food Processing, Research Institutions |
| Companies Covered | Chr. Hansen Holding A/S, Amano Enzyme Europe Ltd., Novozymes A/S, Lonza Group Ltd., Biocatalysts Ltd., BASF SE, AB Enzymes GmbH, Enzymicals AG, DSM N.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biocatalyst Market Strategic Shifts & Innovations
Enzyme immobilization techniques and cell-free synthetic biology are converging to expand the operational window for biocatalytic processes, while regulatory pressure and buyer procurement evolution simultaneously reshape competitive requirements.
Directed evolution platforms combined with high-throughput screening is supplanting traditional rational design approaches for enzyme optimization. Contract development and manufacturing organizations across Germany and Switzerland are adopting these tools to compress client project timelines from years to months. This acceleration is enabling smaller pharmaceutical innovators to access customized biocatalysts previously reserved for large-scale internal programs.
The EU AI Act's risk-classification framework for automated decision-making in manufacturing processes is forcing biocatalyst suppliers to document algorithmic transparency in enzyme discovery workflows. Industrial biotech firms must now maintain audit trails for machine-learning-generated protein variants used in regulated pharmaceutical applications. Dutch and Belgian CDMOs are responding by segregating AI-assisted and traditional discovery projects to manage compliance exposure.
Long-term offtake agreements with fixed-volume commitments are displacing spot-market enzyme purchases among European pharmaceutical manufacturers. Chemical procurement functions at mid-sized generic drug producers are locking in three-to-five year supply contracts to secure capacity amid fermentation bottleneck concerns. This shift is most pronounced in the Rhine-Ruhr chemical cluster, where buyers prioritize supply security over price flexibility.
Europe Biocatalyst Market Segmentation
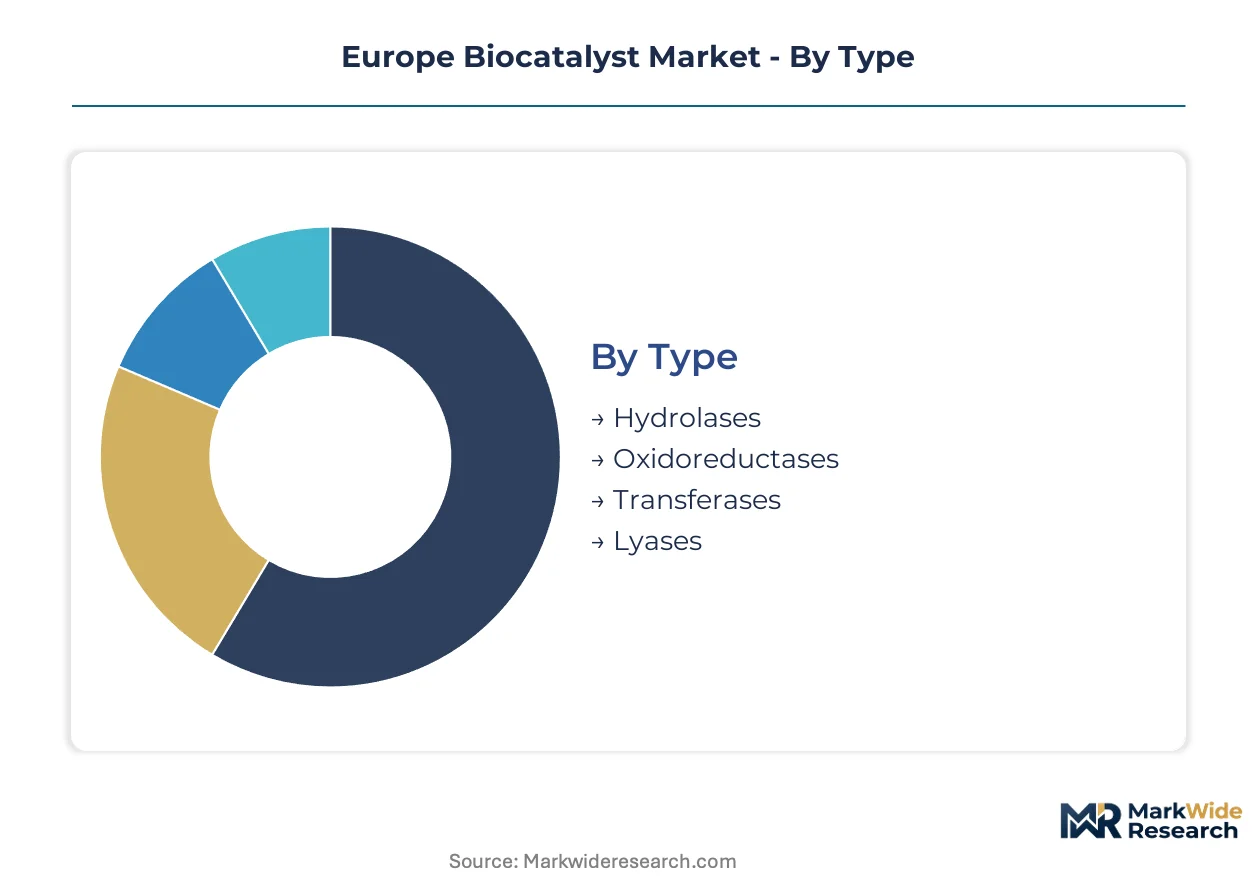
Regulatory differentiation across EMA, REACH, and EU Green Deal frameworks fragments demand patterns by biocatalyst type and application. Pharmaceutical and chemical end-users face divergent compliance burdens that reshape procurement specifications and supplier selection criteria.
Type:
REACH substance registration requirements and EMA biocatalytic process guidelines create tiered compliance burdens that concentrate demand among enzyme classes with established safety dossiers.
- Hydrolases:These enzymes catalyze bond cleavage through water addition, with amylases, lipases, and proteases dominating starch processing and detergent formulations. Demand concentrates in Germany's chemical clusters where BASF and Evonik deploy hydrolases for intermediate synthesis under REACH-registered substance profiles.
- Oxidoreductases:Catalyzing electron transfer reactions, these enzymes enable selective oxidations without heavy-metal catalysts. Pharmaceutical applications across Switzerland and the Netherlands favor oxidoreductases for chiral alcohol production as EMA guidelines push elimination of toxic metal residues from API synthesis.
- Transferases:Enzymes that shift functional groups between molecules, essential for glycosylation and phosphorylation cascades.
- Lyases:Catalysts for non-hydrolytic bond cleavage and formation, deployed in specialty chemical C-C bond constructions.
Hydrolases handles the majority of throughput; Oxidoreductases is the fastest mover on share.
Application:
Cost tier differentiation separates commodity-scale deployments from premium-priced pharmaceutical applications requiring GMP validation.
- Pharmaceuticals:Enzymatic synthesis of chiral intermediates and active pharmaceutical ingredients under EMA quality guidelines. Batch-to-continuous manufacturing transitions across German and Swiss CDMOs favor immobilized enzyme cascades that reduce solvent volumes and accelerate regulatory approval timelines.
- Food & Beverage:Dairy processing, baking, and beverage clarification applications governed by EFSA food enzyme regulations. Chr. Hansen and DSM-Firmenich anchor demand in Denmark and the Netherlands with culture-integrated biocatalyst systems for cheese ripening and lactose hydrolysis.
- Biofuels:Cellulase and amylase cocktails for lignocellulosic ethanol production, pressured by EU renewable energy directive compliance costs.
- Agriculture:Soil amendment and crop protection enzymes, constrained by fragmented distribution networks across Southern European farming regions.
Pharmaceuticals commands the steepest expansion trajectory; Food & Beverage retains the largest installed base.
Form:
Volume economics and handling logistics concentrate procurement preferences among large-scale chemical processors versus specialized pharmaceutical manufacturers.
- Liquid:Ready-to-use enzyme solutions with standardized activity units, preferred by high-throughput food processors and detergent manufacturers. Tanker-scale deliveries to Rotterdam and Antwerp chemical terminals minimize handling costs for commodity applications.
- Immobilized:Enzymes fixed on solid supports for continuous reactor operation and reusability. Premium pricing reflects downstream purification cost savings in multi-step pharmaceutical syntheses across Basel and Leiden manufacturing corridors.
- Powder:Spray-dried formulations for stable storage and flexible dosing in distributed processing operations.
- Freeze-Dried:Lyophilized preparations for maximum shelf stability in research and clinical-scale production.
Liquid form dominates total volume throughput; Immobilized form is climbing the fastest on value share.
End User:
Customer type determines specification stringency, with GMP-grade requirements separating pharmaceutical procurement from industrial chemical purchasing.
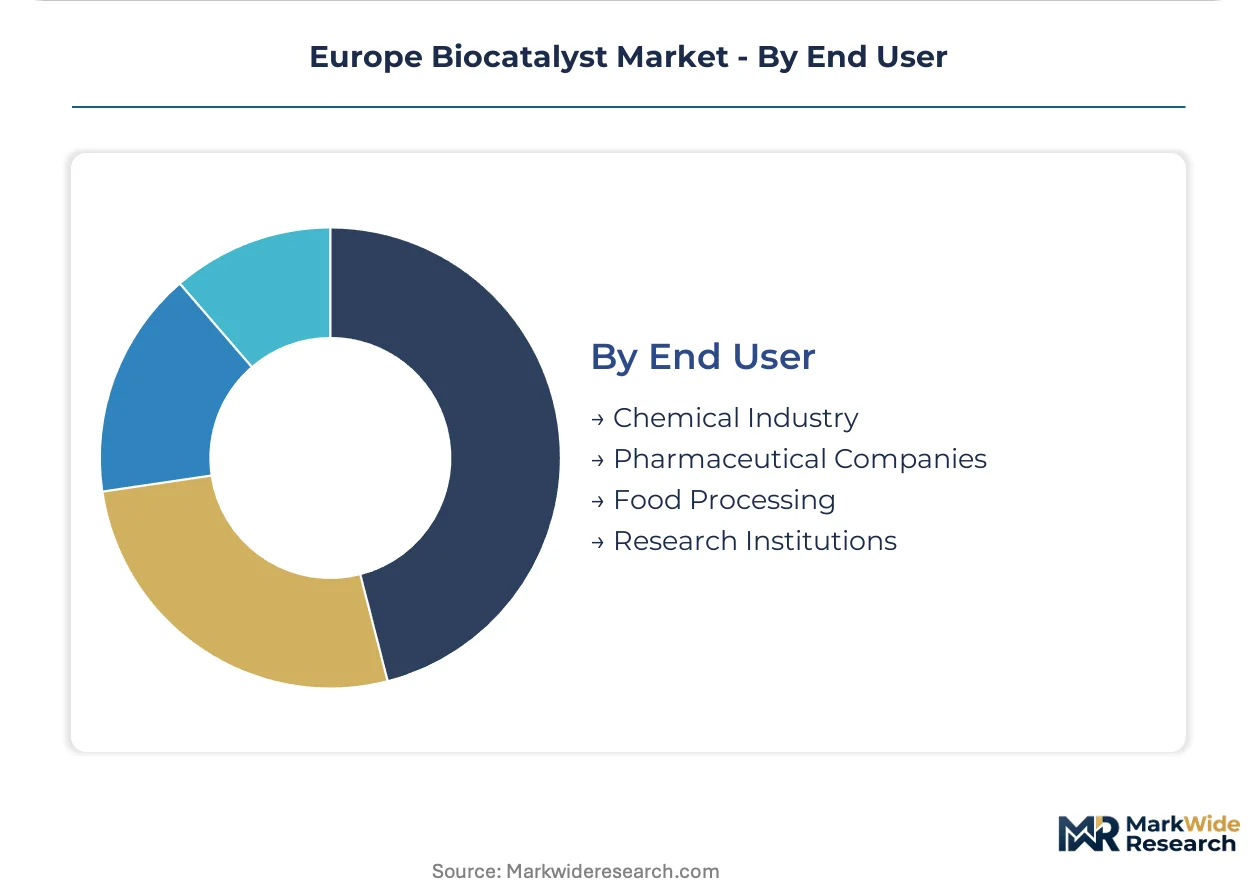
- Pharmaceutical Companies:Developers and manufacturers of small-molecule drugs requiring biocatalytic route validation under EMA guidelines. Long-term offtake agreements with fixed-volume commitments now displace spot purchases as fermentation capacity constraints tighten across Western European suppliers.
- Chemical Industry:Commodity and specialty chemical producers seeking petrochemical substitution under EU Green Deal emissions targets. Ludwigshafen and Marl chemical parks anchor demand for hydrolase-driven process intensification.
- Food Processing:Dairy, bakery, and beverage manufacturers operating under EFSA enzyme registration requirements.
- Research Institutions:Academic and contract research organizations piloting novel enzymatic transformations.
Pharmaceutical Companies absorb the premium-tier volume; Chemical Industry represents the broadest addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes biocatalysts primarily for pharmaceutical intermediate synthesis under REACH compliance, while the Netherlands deploys them for food-grade fermentation at scale, and France emphasizes agro-industrial enzyme applications. This tripartite demand split distinguishes European consumption patterns from the pharmaceutical-heavy profiles seen in North American or Asia-Pacific markets.
Germany
EMA biocatalytic process guidelines and EU Green Deal emissions targets drive pharmaceutical manufacturers toward enzymatic routes for chiral molecule production. The Rhine-Ruhr chemical cluster anchors demand, with Ludwigshafen and Marl hosting backward-integrated enzyme production for hydrolase-driven process intensification.
Netherlands
EFSA food enzyme regulations and concentrated fermentation infrastructure around Leiden and Delft accelerate pilot-to-production scaling for dairy and beverage applications. The Randstad biotech corridor serves as Western Europe's primary distribution hub for liquid enzyme formulations shipped via Rotterdam chemical terminals.
France
ANSM pharmaceutical manufacturing oversight and national bioeconomy investment programs support enzymatic synthesis adoption among Paris-region CDMOs. The Lyon-Saint-Étienne chemical corridor specializes in agro-industrial biocatalyst deployment for crop protection and soil amendment formulations.
Switzerland
Swissmedic GMP validation requirements and Basel's pharmaceutical manufacturing density create premium demand for immobilized enzyme systems in continuous manufacturing transitions. The country's contract development organizations favor long-term offtake agreements to secure fermentation capacity amid regional supply constraints.
Denmark
National biotech cluster policies and Copenhagen-region enzyme engineering talent pools sustain leadership in industrial enzyme platform development. The country's fermentation infrastructure supports both food-grade and pharmaceutical-grade biocatalyst production serving Nordic and broader European markets.
Europe Biocatalyst Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding GMP-grade fermentation capacity and the lower tier occupying application-specific niches. Market structure reflects consolidation around enzyme engineering capabilities and regulatory dossier depth rather than manufacturing scale alone. Three archetypes dominate: vertically integrated chemical conglomerates with captive enzyme production, dedicated industrial biotech firms with platform technologies, and contract manufacturers serving pharmaceutical innovators. Competitive moves concentrate on strategic partnerships for AI-driven enzyme discovery and geographic expansion into underutilized Southern European fermentation capacity.
Within the integrated leader tier, Novozymes A/S and BASF SE exemplify divergent strategic positions—one representing pure-play biotech platform depth, the other chemical-industry backward integration. Chr. Hansen Holding A/S occupies a defensible specialist position anchored in food-grade regulatory expertise. These three entities collectively illustrate how European biocatalyst competition maps onto compliance capability and fermentation infrastructure control rather than price positioning alone.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| Amano Enzyme Europe Ltd. |
| Novozymes A/S |
| Lonza Group Ltd. |
| Biocatalysts Ltd. |
| BASF SE |
| AB Enzymes GmbH |
| Enzymicals AG |
| DSM N.V. |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements with fixed-volume commitments now lock in both fermentation capacity access and price visibility for pharmaceutical manufacturers across the Rhine-Ruhr cluster, compressing spot-market liquidity as buyers prioritize supply security over price flexibility under REACH compliance timelines.
Pricing Analysis
Contract-based long-term offtake structures dominate pharmaceutical procurement, with pricing stratifying across GMP-certified premium, REACH-registered standard, and commodity-grade economy tiers based on regulatory dossier depth and immobilization technology. Cost compression in the economy tier is intensifying because hydrolase oversupply from German chemical parks erodes spot-market premiums. Generic drug producers in the mid-market exhibit acute price sensitivity, while Swiss CDMOs accept premium immobilized enzyme pricing for continuous manufacturing validation.
Supply Chain Analysis
Port congestion at Rotterdam chemical terminals elevates inbound logistics costs for liquid enzyme formulations shipped from Danish and German fermentation facilities, forcing inventory pre-positioning at Antwerp distribution hubs. Supply concentration in Denmark, Germany, and the Netherlands draws from specialized fermentation media, proprietary cell-line banks, and GMP-grade filtration equipment. Single-source vulnerability in Danish cell-line supply creates systemic risk. Distribution runs through Rotterdam-Antwerp liquid bulk terminals and Basel pharmaceutical logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among mid-sized pharmaceutical manufacturers locking in multi-year supply contracts, fragmenting pricing leverage across the supplier base as fermentation capacity constraints tighten procurement timelines.
For Market Incumbents: Shield market position by deepening backward integration into Spanish and Italian fermentation assets before competitors acquire underutilized Southern European capacity. Anchor GMP-grade certification investment against emerging AI-driven enzyme discovery platforms that threaten to commoditize protein engineering services. Prioritize long-term offtake contract renewal with Rhine-Ruhr generic drug producers facing EMA process validation urgency. For New Entrants and Emerging Players: Custom enzyme engineering services for niche pharmaceutical intermediates represent the most penetrable white-space target, as incumbent platforms under-serve small-molecule innovators requiring rapid turnaround on chiral molecule cascades. Target Southern European chemical parks with distributed bioprocessing infrastructure for geographic arbitrage. Lead with AI-assisted protein structure prediction capabilities to compress client R&D timelines below traditional rational design cycles. For Investors and Strategic Acquirers: Specialized CDMOs with validated immobilized enzyme platforms and established EMA regulatory dossiers present the most compelling acquisition archetype for exposure to pharmaceutical manufacturing transition tailwinds. Long-term viability hinges on differentiation through regulatory compliance depth rather than manufacturing scale alone. Monitor EMA biocatalytic process validation timeline compression as the critical inflection signal for revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation | Captures margin from cell-line supply and insulates against REACH feedstock registration bottlenecks. |
| AI-Driven Enzyme Discovery Platform | Compresses protein engineering timelines for EMA-compliant pharmaceutical intermediate customization. |
| Long-term Supply Agreement | Locks in capacity amid fermentation infrastructure constraints across the Leiden-Delft corridor. |
| Geographic Expansion into Southern Europe | Accesses underutilized bioprocessing infrastructure in Spain and Italy for cost-advantaged scale. |
| Green Manufacturing Transition | Aligns with EU Green Deal emissions targets and CSRD reporting mandates for Scope 3 carbon reduction. |
Research Approach
Desk research of EMA biocatalytic process guidelines, REACH substance registration databases, and EU Green Deal policy frameworks preceded structured interviews with fermentation facility managers, pharmaceutical procurement leads, enzyme engineering R&D directors, and regulatory affairs specialists at CDMOs across Germany, Switzerland, and the Netherlands. Secondary validation drew from customs trade data, Cefic chemical industry reports, and SEC filings of publicly traded industrial biotech firms. Bottom-up volume estimates triangulated against top-down market sizing.
Variance decomposition across biocatalyst type, application segment, and end-user industry shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include enzyme class specificity, pharmaceutical versus food-grade regulatory tier, liquid versus immobilized formulation, and geographic production cluster. CAGRs derived from regression analysis against EMA approval velocity, REACH compliance adoption curves, and EU Green Deal investment flows. Industry-specific inputs encompassed fermentation capacity utilization rates and protein engineering talent pipeline data from European university programs.
Forecasts assume regulatory continuity in EMA biocatalytic process validation, REACH substance registration, and EU Green Deal industrial emissions frameworks; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
China Specialty Enzymes Market
Industrial Biotechnology
Haematococcus Pluvialis Market
Industrial Biotechnology
Biocatalysis and Biocatalysts Market
Industrial Biotechnology
Styrene Monooxygenase Market
Industrial Biotechnology
Biocatalyst Market
Industrial Biotechnology
Esterase Market
Industrial Biotechnology
White Biotech Market
Industrial Biotechnology
Unnatural Amino Acids Market
Industrial Biotechnology
White Biotechnology Market
Industrial Biotechnology
Marine Enzymes Market
Industrial Biotechnology
Global Protein Hydrolysis Enzymes Market
Industrial Biotechnology
Industrial Enzymes Market
Industrial Biotechnology
Inulinase Market
Industrial Biotechnology
Protease Enzyme Market
Industrial Biotechnology
GCC Biocatalyst Market
Industrial Biotechnology
Xylanase Market