
 Xylanase Market | 2026-2036
Xylanase Market Size, Share, and Industry Trends Forecast 2026-2036
Xylanase Market Outlook
Food-grade and feed-grade certification tiers is bifurcating the competitive landscape as buyers enforce stricter purity and activity specifications. Novozymes A/S leverages its Danish fermentation infrastructure to sustain premium-grade supply contracts across Europe. AB Enzymes GmbH anchors its position through specialized xylanase blends tailored for wheat-processing applications in Central European mills. Advanced Enzyme Technologies Ltd. competes on cost-engineered formulations serving price-sensitive Asian feed compounders.
Xylanase denotes a class of glycoside hydrolases (EC 3.2.1.8) that catalyze the endohydrolysis of 1,4-beta-D-xylosidic linkages in xylan, the dominant hemicellulose in plant cell walls, typically exhibiting optimal activity between pH 4.5 and 6.5 and temperatures of 50–60°C. Industrial production proceeds via submerged fermentation of recombinant Aspergillus or Trichoderma strains, yielding enzyme preparations standardized to specific activity units per gram for consistent dosing in commercial processes. Liquid formulations dominate volume in beverage and food processing channels where metered dosing integrates with continuous production lines, while powder and granular grades capture margin pools in animal feed premix operations where shelf stability and blend uniformity command price premiums. The pulp and paper application segment shows structural momentum as mills retrofit bleach plants to reduce chlorine dioxide consumption through xylanase-assisted biobleaching sequences.
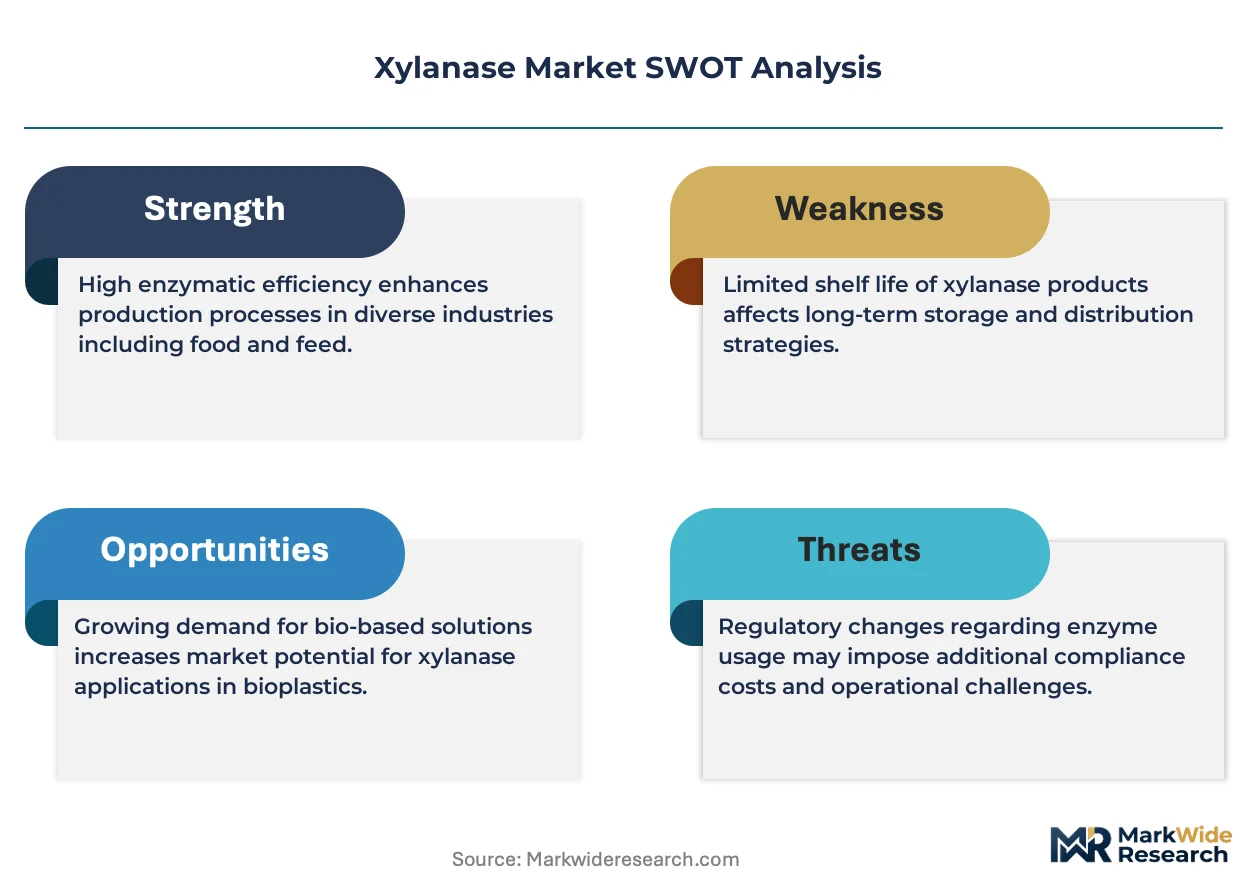
FDA enzyme preparation regulations and the EPA's biofuel pathway requirements shape product registration and environmental claims in the United States, while REACH compliance and EFSA feed additive authorizations govern market access across European Union member states. China's NMPA and GB standards for food enzyme safety create additional certification layers for imported and domestically produced xylanase preparations. Stakeholders must monitor evolving enzyme classification frameworks and substrate-specific efficacy data as buyers shift procurement criteria toward verified performance in target applications rather than generic activity metrics.
Market Dynamics
Fermentation capacity concentration in China and the EU Green Deal's tightening F-Gas Regulation are compressing legacy supply routes while accelerating biotechnology investments in state-backed facilities.
Growth Catalysts
- EU F-Gas Regulation:Industrial enzyme producers retrofit plants to phase down fluorinated greenhouse gases, opening procurement windows for low-carbon fermentation alternatives.
- Poultry feed compounding:Brazilian and Southeast Asian formulators expand xylanase inclusion to improve wheat and corn digestibility in high-density broiler operations.
- Biobleaching retrofit:Pulp mills in Scandinavia and Canada install xylanase-assisted sequences to reduce chlorine dioxide consumption and meet effluent discharge limits.
Market Restraints
- Feedstock volatility:Corn steep liquor and wheat bran prices fluctuate with grain futures, squeezing fermentation input costs for Aspergillus and Trichoderma strain cultivation.
- Supply concentration:Recombinant strain IP and large-scale bioreactor capacity cluster in Chinese state-owned facilities and Danish contract manufacturing sites.
- Technical limitation:Thermostability ceilings in standard fungal xylanases restrict performance above 65°C in high-temperature feed pelleting processes.
Strategic Opportunities
- Cellulosic ethanol integration:Xylanase cocktails optimized for simultaneous saccharification of C5 and C6 sugars align with EPA biofuel pathway requirements for second-generation ethanol.
- India feed additive formalization:BIS standards for enzyme safety in animal nutrition create first-mover positioning for certified suppliers as compound feed sector consolidates.
- Precision fermentation:CRISPR-edited Pichia pastoris strains expressing hyperactive xylanase variants compress production timelines and reduce downstream purification burden.
Industry Challenges
- EFSA feed additive authorization timelines:Novel enzyme preparations face 18-24 month evaluation windows for dossier completeness and toxicological data requirements.
- Cross-contamination protocols:Multi-product fermentation facilities require validated CIP sequences to prevent carryover between food-grade and feed-grade enzyme campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Xylanase Market |
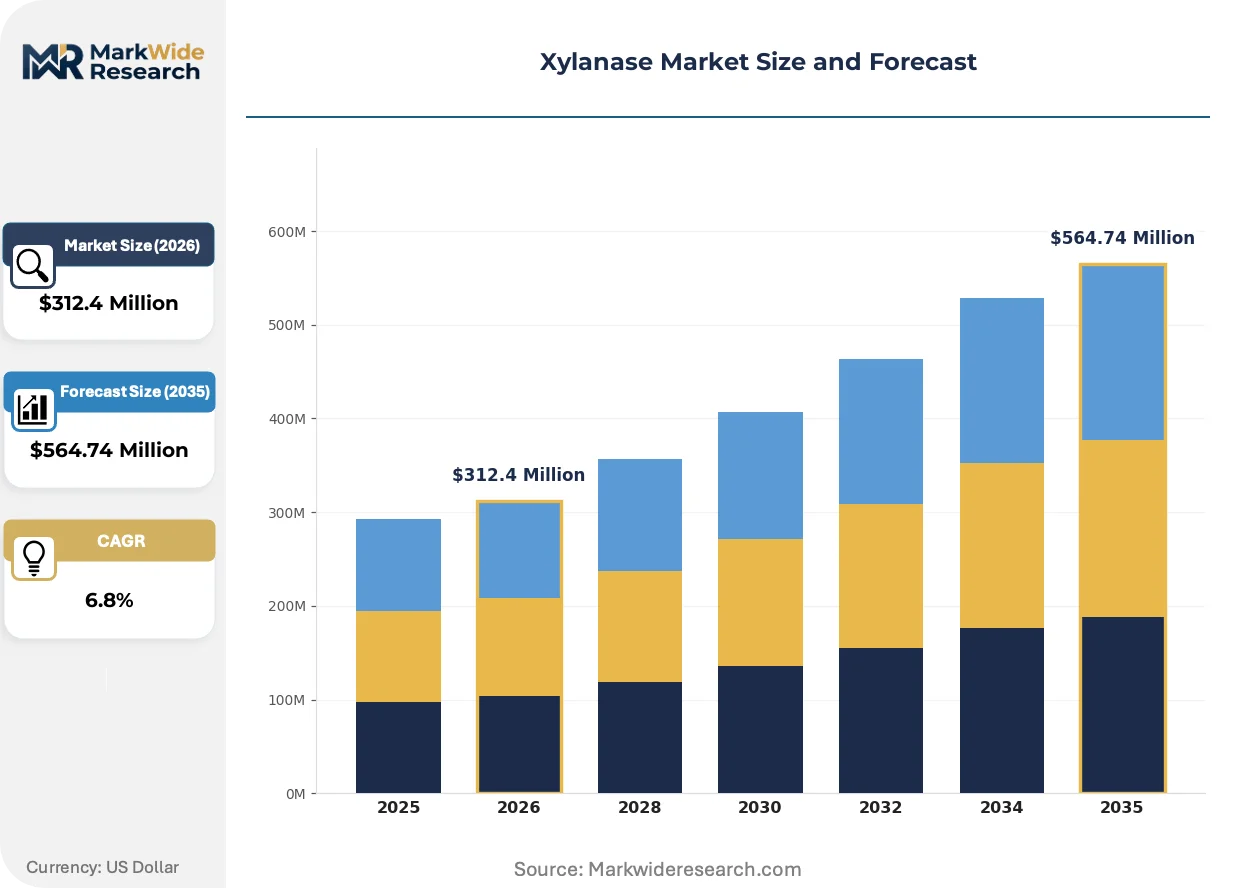
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Tablet Application: Baking, Animal Feed, Biofuel, Pulp & Paper End User: Beverage Industry, Food Processing, Agriculture, Biotechnology Distribution Channel: Online, Direct Sales, Distributors, Wholesalers |
| Companies Covered | AB Enzymes GmbH, Royal DSM N.V., Novozymes A/S, Amano Enzyme Inc., Adisseo France SAS, DuPont de Nemours, Inc., Advanced Enzyme Technologies Ltd., Enzyme Development Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Xylanase Market Strategic Shifts
Enzyme engineering and regulatory chemistry are converging to reshape production economics and market access criteria across feed, food, and industrial applications.
Directed evolution of thermophilic xylanases sourced from Thermotoga maritima is decomposing the temperature-performance tradeoff that has constrained feed pelleting applications. Poultry integrators in Thailand and Vietnam pilot these variants at 80-85°C conditioning temperatures. The technology is decomposing the historical segmentation between liquid food-grade and powder feed-grade product lines.
REACH registration requirements for enzyme protein substances are extending safety data obligations to downstream formulated products. Industrial users in German and Dutch paper mills now demand full substance identity disclosure for biobleaching preparations. Specialty chemical distributors are restructuring portfolios to exclude non-registered enzyme intermediates.
Compounders in Brazil and Indonesia consolidate procurement around activity-verified contracts rather than generic unit pricing. Large integrators deploy near-infrared spectroscopy to validate xylanase activity in delivered premixes, displacing certificate-based acceptance. This pattern concentrates volume with suppliers maintaining in-house analytical laboratories and regional technical service presence.
Xylanase Market Segmentation
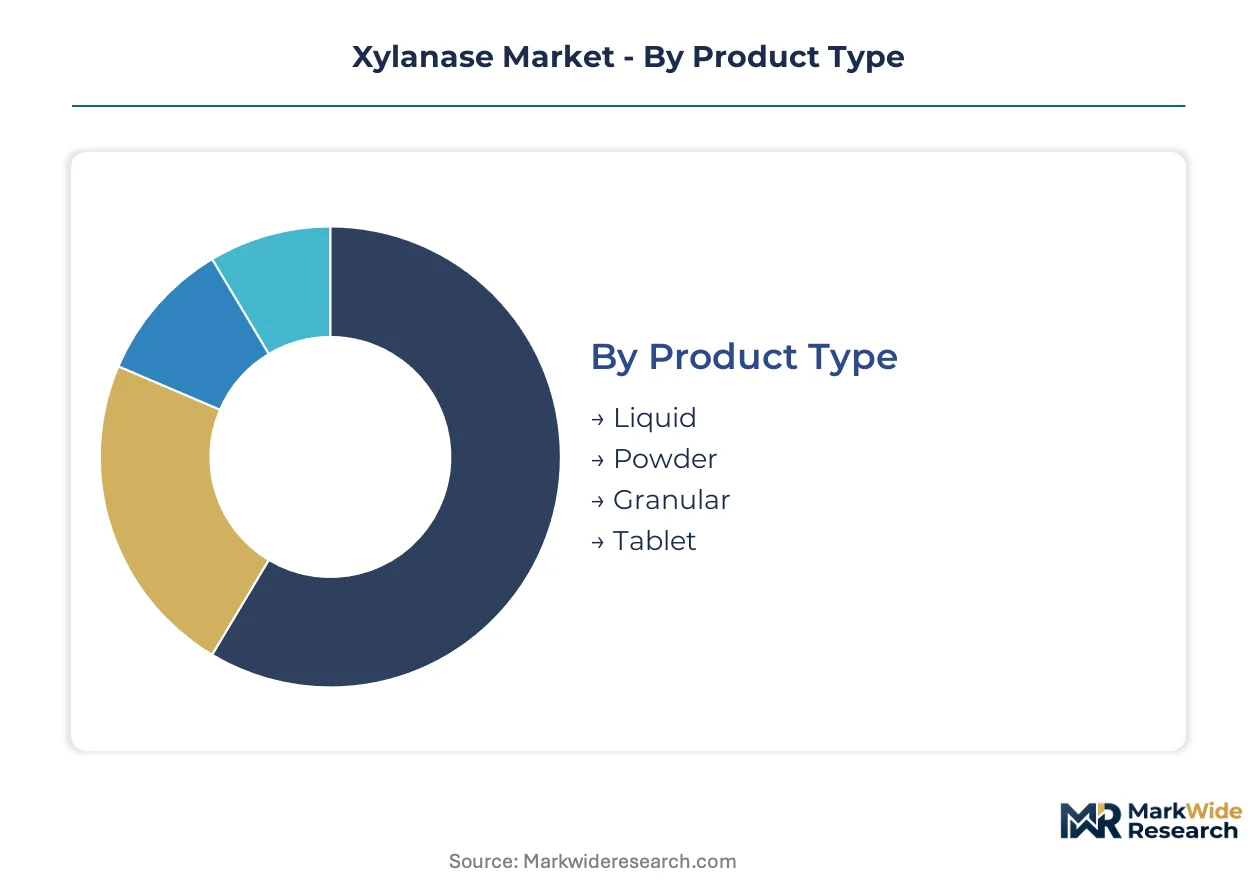
Xylanase formulations diverge sharply in stability requirements and dosing economics across food, feed, and industrial channels. Each segment category carries distinct substitution pressures from alternative enzymes, chemical additives, and process redesigns that reshape procurement priorities.
Product Type:
Liquid preparations face the strongest substitution threat from engineered solid formats that reduce freight costs and extend ambient shelf life in tropical supply chains.
- Liquid:Aqueous enzyme concentrates standardized to specific activity units enable precise metered dosing in continuous beverage and starch processing lines. Brazilian juice processors and Southeast Asian ethanol plants specify liquid xylanase for seamless CIP-compatible integration. This format anchors the volume base while granular grades gain share at the steepest rate.
- Powder:Spray-dried preparations with maltodextrin carriers achieve 12-18 month stability in temperate storage, capturing margin pools in European compound feed premix operations where blend uniformity commands certification premiums. Thermostability limitations above 65°C constrain inclusion in high-temperature pelleting unless coated variants are specified.
- Granular:Fluid-bed agglomerated particles with enteric coatings protect enzyme activity through 85°C conditioning temperatures, displacing standard powders in Thai and Vietnamese broiler integrator contracts. The format climbs fastest as pellet mill retrofits accelerate across Southeast Asia.
- Tablet:Compressed unit-dose formats serve small-scale artisanal bakeries and specialty food producers in India and Latin America where precise batch measurement outweighs per-unit cost premiums.
Powder formats retain the largest installed base while granular products expand most quickly in high-temperature feed applications.
Application:
Cost tier differentiation separates commodity feed enzymes from precision-formulated food-grade and industrial specialty preparations.
- Baking:Fungal xylanases modify arabinoxylan structure to improve dough rheology and bread volume in European and North American artisanal and industrial bakeries. EFSA and FDA enzyme preparation regulations govern GRAS self-determination pathways for dough conditioners. This application anchors the volume base while biofuel integration gains share at the steepest rate.
- Animal Feed:Wheat and corn digestibility enhancement drives inclusion in Brazilian swine and Southeast Asian poultry rations, with activity-verified contracts displacing generic unit pricing among large integrators.
- Biofuel:Xylanase cocktails optimized for C5 sugar release align with EPA biofuel pathway requirements for cellulosic ethanol, though thermostability engineering remains critical for simultaneous saccharification processes.
- Pulp & Paper:Biobleaching sequences in Scandinavian and Canadian mills reduce chlorine dioxide consumption and effluent discharge loads, with REACH registration requirements extending substance identity obligations to downstream formulated products.
Feed applications dominate current procurement volumes while biofuel integration represents the steepest expansion trajectory as second-generation ethanol capacity scales.
End User:
Customer type determines certification tier requirements, with food and beverage processors enforcing stricter purity specifications than agricultural compounders.
- Beverage Industry:Juice and brewing applications require liquid xylanase with documented absence of side activities that could generate off-flavors, with NMPA and GB standards creating additional certification layers for suppliers into China.
- Food Processing:Wheat starch and gluten separation processes specify fungal xylanases with narrow pH-activity profiles, with EFSA feed additive authorization timelines creating 18-24 month windows for novel preparation approvals.
- Agriculture:Compound feed manufacturers in Brazil and Indonesia consolidate procurement around suppliers maintaining in-house analytical laboratories and regional technical service presence.
- Biotechnology:Cellulosic ethanol developers and precision fermentation platforms source xylanase as process inputs, with CRISPR-edited Pichia pastoris strains expressing hyperactive variants compressing production timelines.
Agriculture commands the largest volume commitment while biotechnology applications climb fastest as precision fermentation capacity expands.
Distribution Channel:
Supply concentration shapes channel selection, with large-scale fermentation output flowing through direct contracts and specialty formulations relying on distributor technical support.
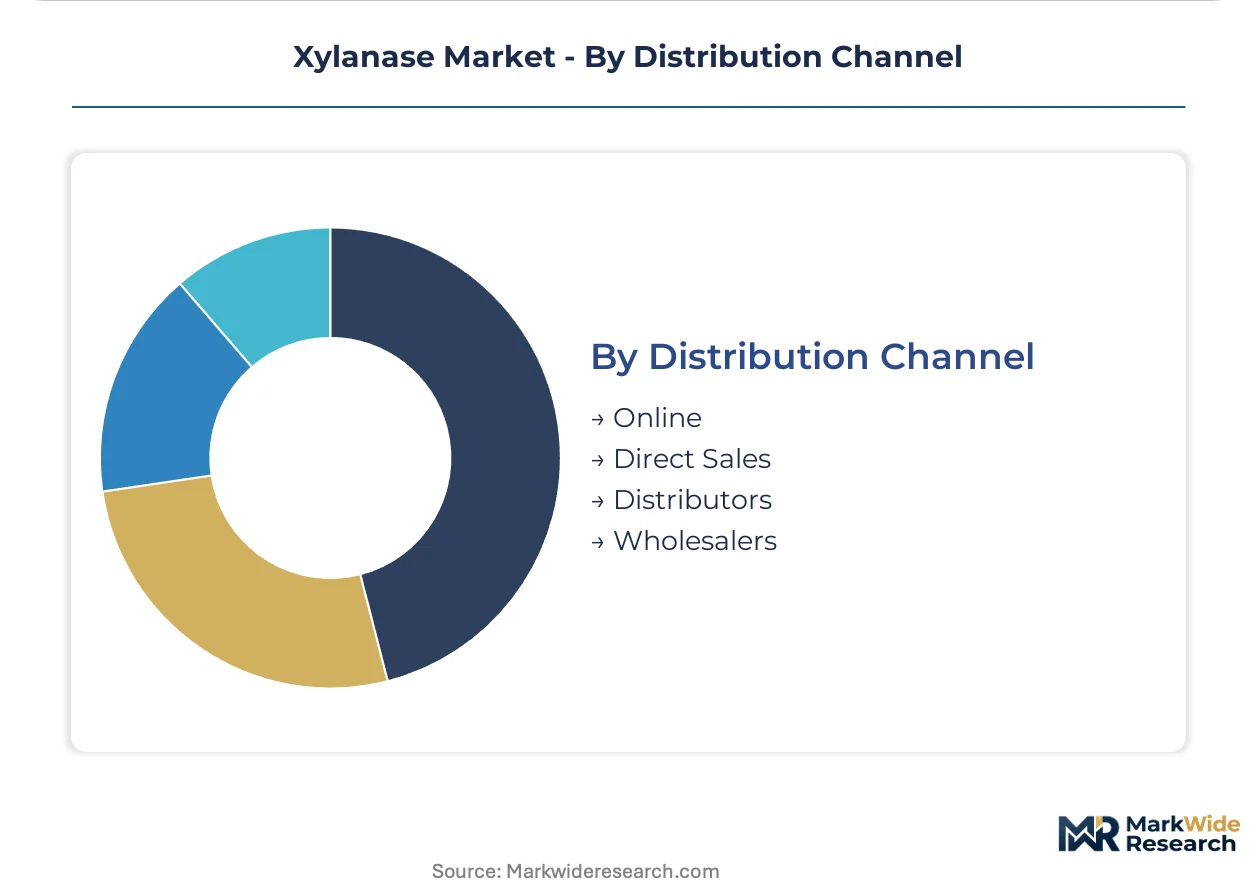
- Online:E-procurement platforms serve small and mid-scale compounders in India and Southeast Asia with standardized activity grades, though certificate-based acceptance is displacing toward activity-verified contracts.
- Direct Sales:Novozymes and AB Enzymes maintain technical service teams for premium-grade supply contracts across European food and feed processors, with formulation customization supporting price realization.
- Distributors:Specialty chemical distributors in Germany and the Netherlands restructure portfolios to exclude non-registered enzyme intermediates under REACH requirements.
- Wholesalers:Regional agricultural supply wholesalers capture price-sensitive Asian feed compounders with cost-engineered formulations, though margin compression limits technical service depth.
Direct sales anchor volume in premium tiers while online channels expand most quickly in price-sensitive emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Southeast Asia and Brazil enforce strict price ceilings on feed-grade xylanase, while European food processors absorb premiums for certified purity. Chinese state-backed fermentation facilities compress global supply costs. Danish and German technical service providers capture margin pools through formulation customization.
China
Domestic fermentation capacity expansion and NMPA enzyme safety standards are accelerating local supply substitution for imported preparations. State-backed biotechnology investments in Shandong and Jiangsu provinces scale recombinant strain production. Yangtze River Delta bioreactor clusters now supply regional feed compounders at 15-20% below import parity.
Brazil
Poultry integrators in São Paulo and Paraná states expand xylanase inclusion in wheat-based broiler rations as corn prices fluctuate. ANVISA feed additive registration requirements create compliance barriers for non-certified imports. The Sorocaba feed manufacturing corridor consolidates procurement around activity-verified supply contracts.
Germany
REACH registration obligations for enzyme protein substances extend to downstream biobleaching formulations in paper mills. EFSA feed additive authorization timelines shape novel preparation introduction schedules. The North Rhine-Westphalia industrial enzyme cluster retrofits plants to comply with EU F-Gas Regulation phase-down mandates.
United States
FDA enzyme preparation regulations and EPA biofuel pathway requirements govern product registration for food and cellulosic ethanol applications. Midwest ethanol developers source xylanase cocktails optimized for C5 sugar release. Iowa and Illinois biorefinery corridors pilot simultaneous saccharification processes with thermostable variants.
Thailand
Broiler integrators in the Central Plains region pilot thermophilic xylanase variants at 80-85°C conditioning temperatures. Near-infrared spectroscopy validation of enzyme activity in delivered premixes displaces certificate-based acceptance. Bangkok-based compounders consolidate procurement with suppliers maintaining regional analytical laboratories.
Xylanase Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Premium-grade supply concentrates with Danish and German fermentation specialists maintaining EFSA-registered facilities. Cost-engineered formulations flow from Indian and Chinese producers serving price-sensitive Asian feed markets. Three archetypes dominate: integrated fermentation-platform multinationals, application-specialist enzyme houses, and contract-manufacturing-scale regional suppliers. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure recombinant strain IP and bioreactor access.
Within the premium-tier vector, Novozymes A/S and AB Enzymes GmbH occupy positions anchored by European regulatory registrations and technical service depth. Advanced Enzyme Technologies Ltd. exemplifies the cost-engineered archetype serving price-sensitive compounders through standardized activity grades. BASF SE and DuPont de Nemours, Inc. sit within diversified chemical platforms where enzymes represent adjacent portfolio extensions rather than core specialization.
| Leading Market Players |
|---|
| AB Enzymes GmbH |
| Royal DSM N.V. |
| Novozymes A/S |
| Amano Enzyme Inc. |
| Adisseo France SAS |
| DuPont de Nemours, Inc. |
| Advanced Enzyme Technologies Ltd. |
| Enzyme Development Corporation |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Large-scale bioreactor utilization rates in Shandong and Jiangsu provinces compress unit production costs for recombinant Aspergillus strains, anchoring price floors for feed-grade formulations while Danish fermentation specialists sustain premium tiers through EFSA-registered technical service depth.
Pricing Analysis
EFSA feed additive authorization timelines dictate the pricing tier structure across European procurement channels, separating rapid-turnaround standard grades from 18-24 month certified premium tiers. Pricing stratifies across food-grade purity certifications, feed-grade activity specifications, and industrial biobleaching performance tiers. Cost compression in Asian feed-grade supply is intensifying because Yangtze River Delta capacity expansion undercuts import parity by 15-20%. Brazilian poultry integrators exhibit the highest price sensitivity, while Scandinavian pulp mills absorb premiums for REACH-registered biobleaching preparations with full substance identity disclosure.
Supply Chain Analysis
Inventory cycles for liquid enzyme concentrates extend 8-12 weeks in tropical storage conditions, forcing Southeast Asian compounders toward granular formats with superior ambient stability. Manufacturing gravity centers on China, Denmark, and Germany, with recombinant strain IP and large-scale bioreactor capacity clustering in these jurisdictions. Production draws from corn steep liquor, wheat bran, and maltodextrin carrier inputs, all tethered to grain futures volatility. Single-source vulnerability concentrates in Chinese state-owned fermentation facilities, which now supply regional Asian markets at compressed cost structures. Distribution runs through direct technical service contracts for premium tiers and regional agricultural wholesalers for price-sensitive feed markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The xylanase market is recovering from a cyclical trough as cellulosic ethanol capacity buildouts and precision fermentation platform investments absorb excess enzyme production capacity.
For Market Incumbents: Consolidate fermentation capacity utilization through long-term offtake agreements with Brazilian poultry integrators and Southeast Asian feed compounders, anchoring volume commitments against Chinese state-backed cost competition. Deepen backward integration into recombinant strain development to protect IP moats as CRISPR-edited Pichia pastoris platforms compress production timelines for rivals. Prioritize EFSA-registered facility status to defend European premium-tier positioning against REACH compliance pressure on non-registered intermediates. For New Entrants and Emerging Players: Regional analytical laboratory service gaps in Thailand, Vietnam, and Indonesia present white-space opportunities where incumbents under-serve with activity-verified contract capabilities. Target Indonesian feed additive formalization as BIS-aligned standards create first-mover windows for certified suppliers. Deploy near-infrared spectroscopy validation services as a go-to-market wedge to displace certificate-based acceptance among consolidating compounders. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation platforms with CRISPR-edited strain libraries and compressed downstream purification economics. Long-term viability hinges on cellulosic ethanol pathway approval velocity and second-generation biofuel capacity scaling. Watch EPA biofuel pathway requirement modifications as the critical inflection signal for xylanase cocktail demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Shandong province bioreactor clusters scale recombinant Aspergillus output for Asian feed compounders. |
| Backward Integration | In-house strain development protects IP against CRISPR-edited Pichia pastoris platform proliferation. |
| Long-term Supply Agreement | Brazilian poultry integrators lock activity-verified contracts displacing generic unit pricing. |
| Green Manufacturing Transition | EU F-Gas Regulation retrofit opens procurement for low-carbon fermentation alternatives. |
| Joint Venture | Danish-German technical service partnerships capture biobleaching formulation customization margins. |
Study Parameters
A spread of perspectives from fermentation plant managers, feed compounder procurement leads, pulp mill technical directors, enzyme distribution channel partners, and regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EFSA feed additive authorization databases, EPA biofuel pathway filings, NMPA enzyme safety standards, REACH registration disclosures, and customs trade flow records. Bottom-up volume modeling triangulated against top-down capacity assessments across Chinese state-owned facilities and Danish contract manufacturing sites.
Segmentation dimensions modeled include formulation type, application channel, end-user certification tier, and regional regulatory cluster across the projection horizon. CAGRs were derived from trend extrapolation of fermentation capacity utilization, feed additive inclusion rate trajectories, and biobleaching retrofit adoption curves. Industry-specific forecast inputs incorporated cellulosic ethanol plant commissioning schedules and precision fermentation platform investment flows.
Forecasts assume regulatory continuity in EFSA, EPA, and NMPA regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Global Specialty Enzymes Market
Industrial Biotechnology
Global Carbohydrase Market
Industrial Biotechnology
Redox Enzymes Market
Industrial Biotechnology
Fungal Amylase Market
Industrial Biotechnology
Unnatural Amino Acids Market
Industrial Biotechnology
Phospholipase Enzyme Market
Industrial Biotechnology
Protease Market
Industrial Biotechnology
Marine Enzymes Market
Industrial Biotechnology
Cellulose Enzyme Market
Industrial Biotechnology
Lipase Enzymes Market
Industrial Biotechnology
Inulinase Market
Industrial Biotechnology
White Biotech Market
Industrial Biotechnology
Tannase Market
Industrial Biotechnology
Beta-Glucanase Market
Industrial Biotechnology
Protease Enzyme Market
Industrial Biotechnology
Pyruvate Synthase Market