
 Microbial-Derived Fiber Market | 2026-2036
Microbial-Derived Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial-Derived Fiber Market Analytics
Food and beverage formulation is hardening around clean-label, gut-health positioning as the dominant demand vector for microbial-derived inputs. Greenfiber leverages its fermentation scale to supply soluble fiber grades to multinational beverage brands. BASF anchors European supply through its biotechnology platform, while Modern Synthesis specializes in bacterial cellulose for premium cosmetic and textile applications.
Microbial-derived fiber comprises polysaccharides, proteins, and structural biopolymers synthesized through controlled bacterial, yeast, or fungal fermentation, typically achieving purity levels above 85% with tunable viscosity and water-binding capacity for industrial integration. Its primary purpose is to replace petroleum-based or resource-intensive natural fibers in food systems, medical materials, and functional textiles. Soluble fiber dominates current revenue pools due to established incorporation protocols in processed foods and beverages, while prebiotic fiber commands premium positioning as clinical validation for microbiome modulation accumulates. Fermentation technology leads capital deployment because strain optimization and bioreactor yield improvements directly determine unit economics across all product grades.
EFSA novel food authorization requirements shape European market entry timelines and safety documentation burdens for new microbial strains. The EU Green Deal carbon accounting rules and REACH chemical registration standards further constrain processing chemistry choices and supply chain transparency obligations. Stakeholders must monitor regulatory divergence between EFSA pathways and FDA GRAS determinations, as asynchronous approvals will fragment product launch sequencing and regional inventory strategies.
Market Dynamics
Fermentation scale economics now dominate competitive positioning as bioreactor yield improvements compress unit costs faster than extraction-based fiber alternatives can achieve.
Growth Catalysts
- EU Green Deal carbon accounting:The framework mandates supply chain transparency for bio-based inputs, accelerating capital flows into verified low-carbon fermentation infrastructure across member states.
- Prebiotic clinical validation:Accumulating microbiome research is expanding incorporation protocols into functional food and beverage formulations targeting digestive health positioning.
- German fermentation clusters:Concentrated expertise in bacterial cellulose processing around Hamburg and Munich enables scaled production with shorter development cycles for new substrate grades.
Market Restraints
- EFSA novel food timelines:Strain-specific safety documentation requirements extend market entry by 18-36 months, freezing inventory deployment until authorization completion.
- Sugar feedstock volatility:Beet and cane price swings directly compress margin structures for producers lacking long-term agricultural supply contracts.
- Petroleum-based fiber substitution:Polypropylene and polyester remain cost-competitive for non-food applications where biodegradability carries no regulatory premium.
Strategic Opportunities
- Medical-grade bacterial cellulose:Wound dressing and surgical mesh applications command pricing multiples exceeding food-grade equivalents due to purity and biocompatibility requirements.
- REACH-compliant processing chemistry:Green chemistry substitution mandates create first-mover advantages for suppliers with solvent-free extraction capabilities.
- Direct-to-brand formulation services:Bypassing ingredient distributors to embed microbial fiber into finished product development shortens commercialization cycles for multinational food manufacturers.
Industry Challenges
- Strain optimization talent scarcity:Industrial microbiology and metabolic engineering expertise concentrates in academic and startup ecosystems, constraining scale-up execution for mid-tier producers.
- Bioreactor capex intensity:Stainless steel fermentation vessels and downstream purification equipment require dedicated financing structures distinct from conventional chemical processing assets.
- Cross-regulatory filing complexity:Asynchronous EFSA and FDA approval pathways force parallel documentation investments without guaranteed reciprocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial-Derived Fiber Market |
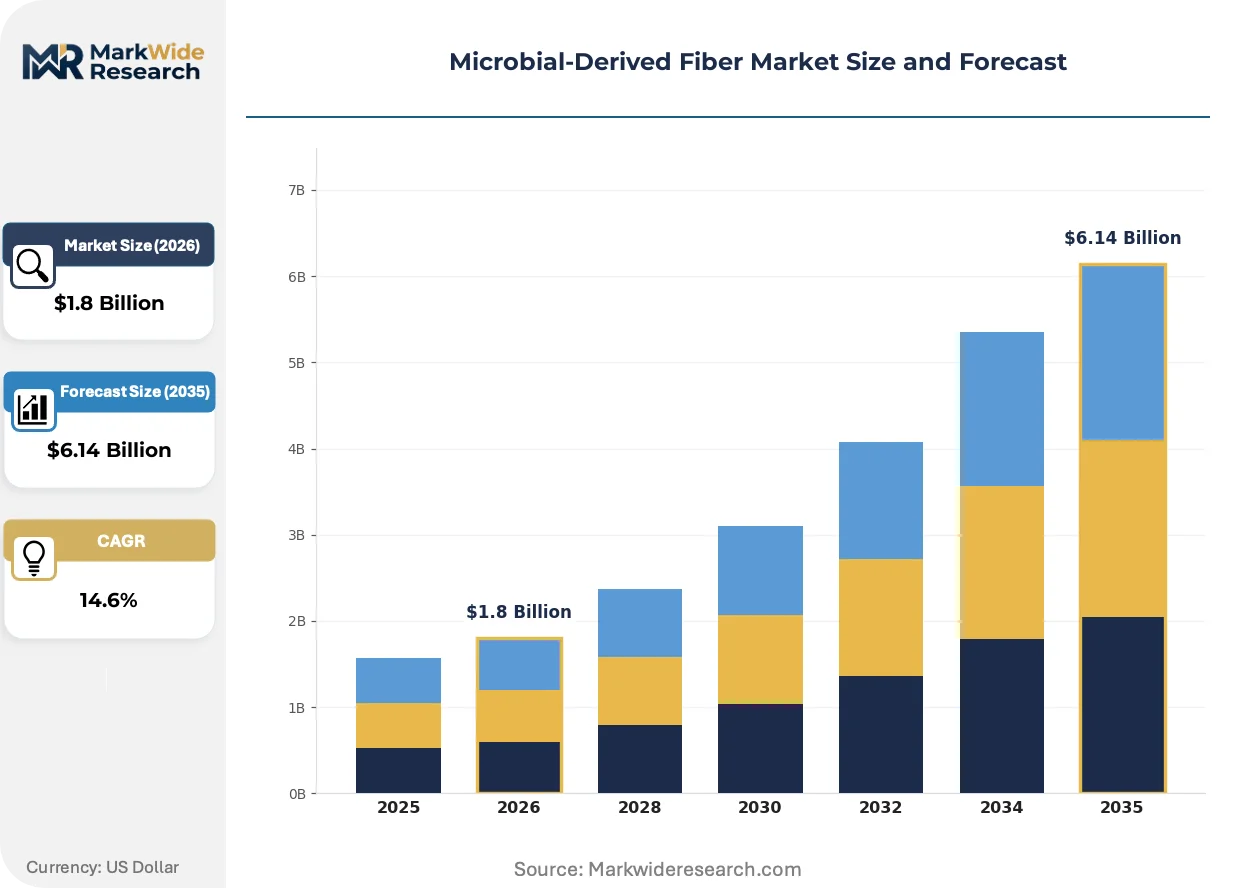
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soluble Fiber, Insoluble Fiber, Prebiotic Fiber, Fermented Fiber Application: Food & Beverages, Pharmaceuticals, Nutraceuticals, Animal Feed End User: Food Manufacturers, Dietary Supplement Companies, Healthcare Providers, Animal Nutritionists Technology: Fermentation, Extraction, Processing, Blending |
| Companies Covered | Greenfiber, Nata de Coco, ScobyTech, CelluForce, Evonik, BASF, Modern Synthesis, JNC, Biotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial-Derived Fiber Market Evolving Landscape
Precision fermentation is collapsing the boundary between food-grade and technical-grade fiber production, enabling substrate tunability that responds to application-specific viscosity and purity requirements without dedicated facility reconfiguration.
Continuous fermentation technology is converging with real-time metabolite monitoring to enable dynamic process control. Beverage manufacturers in North America are piloting these systems for soluble fiber integration at reduced holding inventory levels. The structural result is compressing minimum efficient scale thresholds for regional supply models.
REACH chemical registration standards are tightening solvent residue limits for extraction protocols. European processors are retrofitting facilities with aqueous purification trains at capital costs that exclude smaller competitors. Medical-grade bacterial cellulose manufacturers face the steepest compliance burden given implant-contact applications.
Formulation partnerships now precede offtake agreements as the dominant commercial structure. Multinational food brands embed microbial fiber suppliers into early-stage product development rather than sourcing commoditized grades through distributors. This pattern is most pronounced in Germany and the Netherlands where ingredient innovation clusters support co-development infrastructure.
Microbial-Derived Fiber Market Segmentation
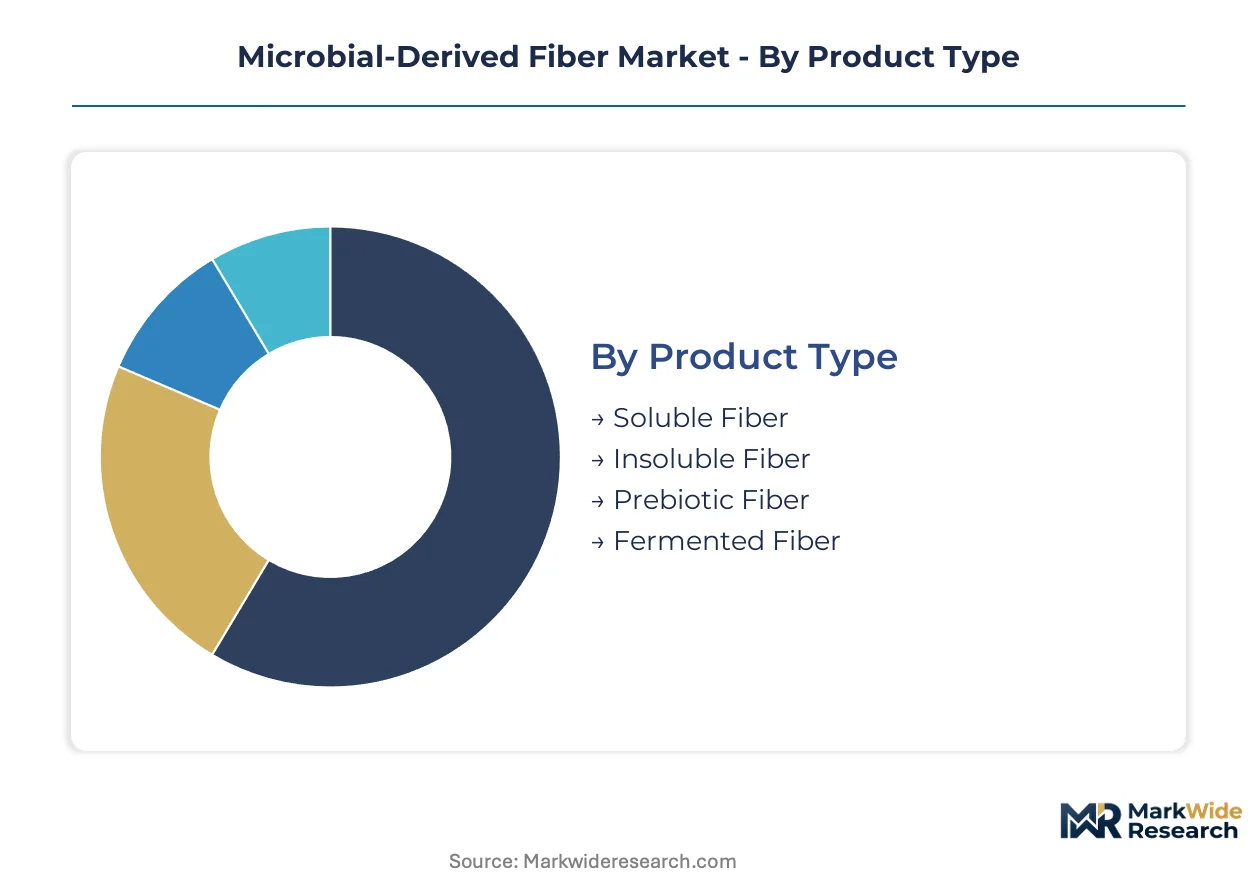
Microbial-derived fiber markets fragment across four distinct classification systems. Each dimension carries specific certification requirements that shape supplier positioning and customer procurement protocols.
Product Type:
EFSA novel food authorization applies differentially across these grades, with prebiotic and fermented categories facing extended safety documentation timelines compared to conventional fiber classifications.
- Soluble Fiber:Polysaccharide structures with tunable viscosity profiles above 85% purity. Beverage manufacturers in Germany concentrate procurement here for clean-label texture modification, driven by EU Green Deal carbon accounting preferences for fermentation-derived inputs.
- Prebiotic Fiber:Substrates with demonstrated microbiome modulation capacity requiring clinical validation dossiers. Dietary supplement companies command premium positioning as EFSA health claim substantiation accumulates, though authorization timelines extend 18-36 months.
- Insoluble Fiber:Structural biopolymers with high water-binding capacity for bakery and meat analog applications.
- Fermented Fiber:Bacterial cellulose and yeast-derived substrates processed through controlled bioreactor systems.
Leading the category by volume: Soluble Fiber. Growing fastest: Prebiotic Fiber.
Application:
Margin structures diverge sharply across these end-uses, with pharmaceutical and nutraceutical applications commanding multiples of food-grade pricing due to purity and documentation requirements.
- Food & Beverages:The largest volume sink incorporating soluble and insoluble grades into processed products. Multinational brands in the Netherlands and Germany embed suppliers into co-development partnerships rather than spot procurement, shortening commercialization cycles.
- Pharmaceuticals:Medical-grade bacterial cellulose for wound dressings and surgical meshes. Hamburg-based processors supply this segment under REACH-compliant solvent-free extraction protocols, with EMA medical device regulations layering additional compliance burdens.
- Nutraceuticals:Prebiotic formulations targeting digestive health positioning in capsule and powder formats.
- Animal Feed:Fermented fiber substrates for gut health modulation in livestock and companion animal nutrition.
Highest margin capture: Pharmaceuticals. Volume expansion steepest: Food & Beverages.
End User:
Procurement sophistication varies dramatically, with dietary supplement companies and healthcare providers demanding batch-level traceability that food manufacturers often bypass.
- Food Manufacturers:Multinational beverage and bakery brands with established incorporation protocols for soluble fiber grades. These buyers prioritize supply security through long-term offtake agreements with German fermentation clusters.
- Dietary Supplement Companies:Formulators seeking prebiotic fiber with EFSA-substantiated health claims. Clinical validation requirements concentrate procurement among suppliers with dedicated regulatory affairs capabilities.
- Healthcare Providers:Hospitals and clinics sourcing medical-grade bacterial cellulose for advanced wound care.
- Animal Nutritionists:Feed formulators integrating fermented fiber into ruminant and monogastric diets.
Most stringent specification demands: Healthcare Providers. Fastest procurement scale-up: Dietary Supplement Companies.
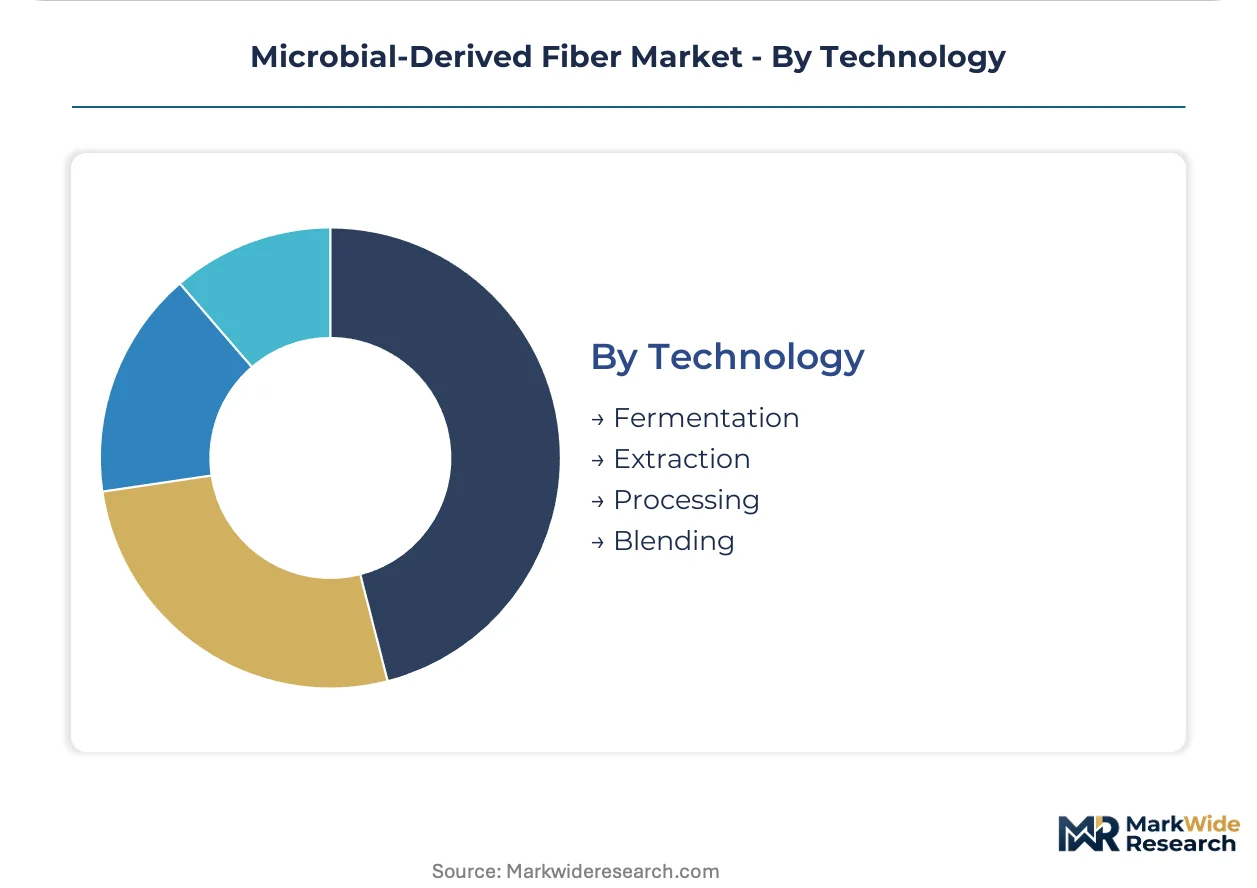
Technology:
Capital intensity and yield economics separate these process categories, with fermentation commanding dedicated financing structures distinct from extraction-based alternatives.
- Fermentation:Controlled bacterial, yeast, or fungal bioreactor systems achieving strain-specific polysaccharide synthesis. Continuous fermentation with real-time metabolite monitoring is compressing minimum efficient scale thresholds for regional supply models.
- Extraction:Downstream purification protocols facing REACH solvent residue limits. European processors retrofit aqueous purification trains at capital costs excluding smaller competitors.
- Processing:Physical modification of fiber structure for viscosity and water-binding tuning.
- Blending:Formulation services embedding microbial fiber into finished product development.
Dominant capex deployment: Fermentation. Fastest regulatory compliance pressure: Extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of microbial-derived fiber concentrates in Germany's fermentation clusters, while consumption spreads across European food manufacturers and North American nutraceutical formulators. This geographic split creates logistics complexity for suppliers balancing bioreactor scale against regional formulation partnerships.
Germany
Beverage manufacturers in Hamburg and Munich drive soluble fiber procurement for clean-label product lines. EFSA novel food authorization timelines extend 18-36 months, freezing inventory deployment for new prebiotic grades. The Hamburg bacterial cellulose processing corridor supplies medical-grade substrates under REACH-compliant solvent-free extraction protocols.
United States
Dietary supplement companies in California and New Jersey scale prebiotic fiber incorporation into gut health formulations. FDA GRAS determinations run asynchronous to EFSA pathways, forcing parallel documentation investments. Boston-area biotech clusters pilot continuous fermentation systems with real-time metabolite monitoring for beverage integration.
Netherlands
Multinational food brands embed suppliers into co-development partnerships rather than spot procurement. EU Green Deal carbon accounting mandates accelerate verified low-carbon fermentation infrastructure investments. Wageningen University corridors anchor ingredient innovation clusters supporting joint product development pipelines.
China
Domestic fermentation capacity expands for bacterial cellulose serving textile and cosmetic applications. SAMR food safety registration requirements layer compliance burdens distinct from Western authorization frameworks. Yangtze River Delta bioprocessing zones scale soluble fiber production for regional beverage manufacturers.
Japan
Functional food manufacturers integrate prebiotic fibers into aging-population targeted digestive health products. PMDA novel food consultations shape strain-specific safety documentation requirements for microbiome-modulating substrates. Osaka-Kobe industrial corridors concentrate fermentation expertise for high-purity medical-grade outputs.
Microbial-Derived Fiber Market Competitive Landscape
Top-tier vendors anchor European fermentation infrastructure, while mid-scale specialists occupy application-specific niches in medical-grade bacterial cellulose and cosmetic substrates. The vendor base stratifies across three tiers: multinational chemical conglomerates with biotechnology platforms, dedicated fermentation specialists with regional scale, and startup-stage precision fermentation operators. Two strategic archetypes dominate competitive positioning: backward-integrated suppliers controlling sugar feedstock contracts, and formulation-service providers embedding directly into brand product development cycles. Capacity expansion and strategic partnerships represent the dominant competitive moves, with German clusters attracting joint venture investments for REACH-compliant aqueous purification retrofits.
Within the multinational chemical tier, BASF anchors European supply through its biotechnology platform, while Evonik occupies a position in specialty biopolymer synthesis. Among dedicated fermentation specialists, Greenfiber represents the scale-driven archetype supplying soluble fiber grades to multinational beverage brands, and Modern Synthesis exemplifies the premium-application focus in bacterial cellulose for cosmetic and textile segments. These named entities illustrate how competitive positioning fragments across production scale versus application specialization rather than consolidating around integrated portfolios.
| Leading Market Players |
|---|
| Greenfiber |
| Nata de Coco |
| ScobyTech |
| CelluForce |
| Evonik |
| BASF |
| Modern Synthesis |
| JNC |
| Biotec |
| Others |
Value Network & Pricing Analysis
Captive integration into German fermentation infrastructure anchors supply security and pricing power for microbial-derived fiber suppliers, with Hamburg and Munich processing clusters enabling just-in-time inventory deployment that commands premium positioning against spot-market alternatives.
Pricing Analysis
Short lead-time premiums dominate pricing structures for medical-grade bacterial cellulose, with Hamburg-based processors commanding substantial markups over standard food-grade equivalents due to REACH-compliant solvent-free extraction protocols and EMA medical device documentation. Three-tier pricing structure across medical, food-grade, and feed-grade levels separates purity-certified substrates from commodity alternatives. Pricing pressure stems from sugar feedstock volatility in beet and cane markets, compressing margins for producers lacking long-term agricultural contracts. Dietary supplement companies demonstrate highest price sensitivity due to extended EFSA authorization timelines freezing inventory capital, while pharmaceutical buyers accept premium positioning for biocompatibility-certified grades.
Supply Chain Analysis
Workforce availability constraints in German bacterial cellulose processing corridors and Dutch formulation partnerships are tightening supplier selection criteria, with metabolic engineering talent scarcity extending development cycles for new substrate grades. Supply concentrates in Germany, the Netherlands, and the United States, with Yangtze River Delta zones emerging for textile-grade outputs. Raw material dependencies center on beet sugar, cane molasses, and nitrogen-rich fermentation media. Single-source vulnerability runs through German stainless steel bioreactor fabrication capacity. Distribution runs through direct-to-brand formulation partnerships rather than commodity distributors, with multinational food manufacturers embedding suppliers into co-development pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microbial-derived fiber markets sit in a fermentation-technology transition phase, with precision fermentation and continuous bioreactor systems displacing batch-process legacy infrastructure across food-grade and medical-grade production tiers.
For Market Incumbents: Anchor fermentation scale advantages through captive sugar feedstock contracts and REACH-compliant aqueous purification retrofits that exclude smaller competitors. Defend against precision fermentation startups by locking long-term offtake agreements with multinational beverage brands before clinical validation timelines compress. Prioritize strain optimization talent acquisition from Wageningen and Boston academic corridors to sustain yield improvement trajectories. For New Entrants and Emerging Players: Continuous fermentation technology with real-time metabolite monitoring offers a technology-first wedge into North American beverage manufacturing pilots seeking reduced holding inventory levels. Target medical-grade bacterial cellulose for wound dressing applications, where Hamburg processing capacity constraints create supply gaps and pricing multiples exceed food-grade equivalents. Pursue direct-to-brand formulation partnerships rather than distributor channel entry to shorten commercialization cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational chemical conglomerates seeking biotechnology platform expansion, with BASF and Evonik archetypes representing logical strategic buyers. Five-to-ten year viability hinges on EFSA-FDA regulatory convergence enabling synchronized product launches without parallel documentation investments. Watch for EFSA novel food authorization batch approvals as inflection signal for inventory deployment velocity and working capital efficiency improvements.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Scale-Up | Real-time metabolite monitoring compresses minimum efficient scale thresholds for regional beverage supply models. |
| REACH-Compliant Aqueous Purification Retrofit | Solvent-free extraction capabilities create first-mover compliance advantages under tightening ECHA residue limits. |
| Direct-to-Brand Formulation Partnership | Embedding microbial fiber into early-stage product development shortens commercialization cycles for multinational food manufacturers. |
| Medical-Grade Bacterial Cellulose Certification | EMA medical device regulations and biocompatibility documentation command pricing multiples exceeding food-grade equivalents. |
| Strain Optimization Talent Acquisition | Industrial microbiology expertise from academic corridors directly determines bioreactor yield economics and unit cost compression. |
Research Methodology
Multi-period observation of EFSA novel food authorization timelines, fermentation capacity utilization rates, and prebiotic clinical validation pipelines anchored the trend analysis, supplemented by interviews with fermentation plant managers, regulatory affairs leads at dietary supplement companies, procurement directors at multinational beverage brands, and bacterial cellulose processing engineers. Secondary validation drew from EFSA novel food catalogs, REACH registration databases, EU Green Deal carbon accounting disclosures, and customs trade data for fermentation equipment imports. Bottom-up facility capacity modeling triangulated against top-down end-use demand estimates across food, pharmaceutical, and nutraceutical applications.
Input-output matrices mapped sugar feedstock flows through bioreactor systems to finished fiber grades, with segmentation across product type, application, end user, and technology dimensions modeled throughout the forecast period. CAGRs derived from strain yield improvement curves, regulatory authorization velocity assumptions, and substitution elasticity estimates for petroleum-based fiber alternatives. Industry-specific forecast inputs included EFSA-FDA approval pathway divergence scenarios and continuous fermentation adoption rates in North American beverage manufacturing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under asynchronous regulatory authorization delays, sugar price volatility spikes, or precision fermentation breakthroughs disrupting batch-process economics. Forecasts reflect documented assumptions regarding strain optimization timelines and carbon accounting rule enforcement intensity. Material deviation in EFSA novel food batch approval velocity or German fermentation cluster capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Microbial Protein Used in Feed Market
Industrial Microbiology
Galactosidase Market
Industrial Microbiology
Bacterial Antigens Market
Industrial Microbiology
Europe Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Automated Microbiology Market
Industrial Microbiology
Anti-Microbial Anti-Fungal Test Market
Industrial Microbiology
Salinomycin Market
Industrial Microbiology
Benzoate-Free Enzymes Market
Industrial Microbiology
Global Microbial Products Market
Industrial Microbiology
Microbial Biosurfactants Market
Industrial Microbiology
Mesophilic Bacteria Market
Industrial Microbiology
Microbial Rennet Market
Industrial Microbiology
Lactobacillus Strains Market
Industrial Microbiology
Global Starter Culture Market
Industrial Microbiology
Bacillus Coagulans Market
Industrial Microbiology
Cultured Dextrose Market