
 Pyruvate Synthase Market | 2026-2036
Pyruvate Synthase Market Size, Share, and Industry Trends Forecast 2026-2036
Pyruvate Synthase Market Analytics
ISO 9001 certification is bifurcating the supplier base into qualified industrial vendors and uncertified commodity traders. Lonza Group leverages its GMP-grade fermentation infrastructure to anchor European pharmaceutical supply chains. Thermo Fisher Scientific sustains broad catalog distribution across North American research institutions through direct channel control.
Pyruvate synthase is a thiamine pyrophosphate-dependent enzyme that catalyzes the reversible conversion of pyruvate to acetyl-CoA and carbon dioxide, operating optimally at pH 7.0-8.5 and requiring magnesium or manganese cofactors for catalytic activity. Recombinant pyruvate synthase dominates commercial supply due to higher batch consistency and scalable E. coli expression systems, while stabilized formulations command premium positioning for ambient-temperature logistics in field diagnostic deployments. Lyophilized powder delivery modes retain structural preference in academic procurement channels where cold-chain infrastructure remains limited.
FDA oversight of enzyme-based diagnostic reagents under 21 CFR 820 quality system regulation shapes product validation requirements for US market entry, while REACH chemical registration in Europe imposes substance characterization burdens on imported enzyme preparations. The EU AI Act's emerging classification frameworks for automated laboratory systems will cascade into procurement specifications for enzyme-integrated diagnostic platforms. Stakeholders must monitor how divergent qualification regimes between FDA and EMA reshape total cost of ownership for dual-territory suppliers.
Market Dynamics
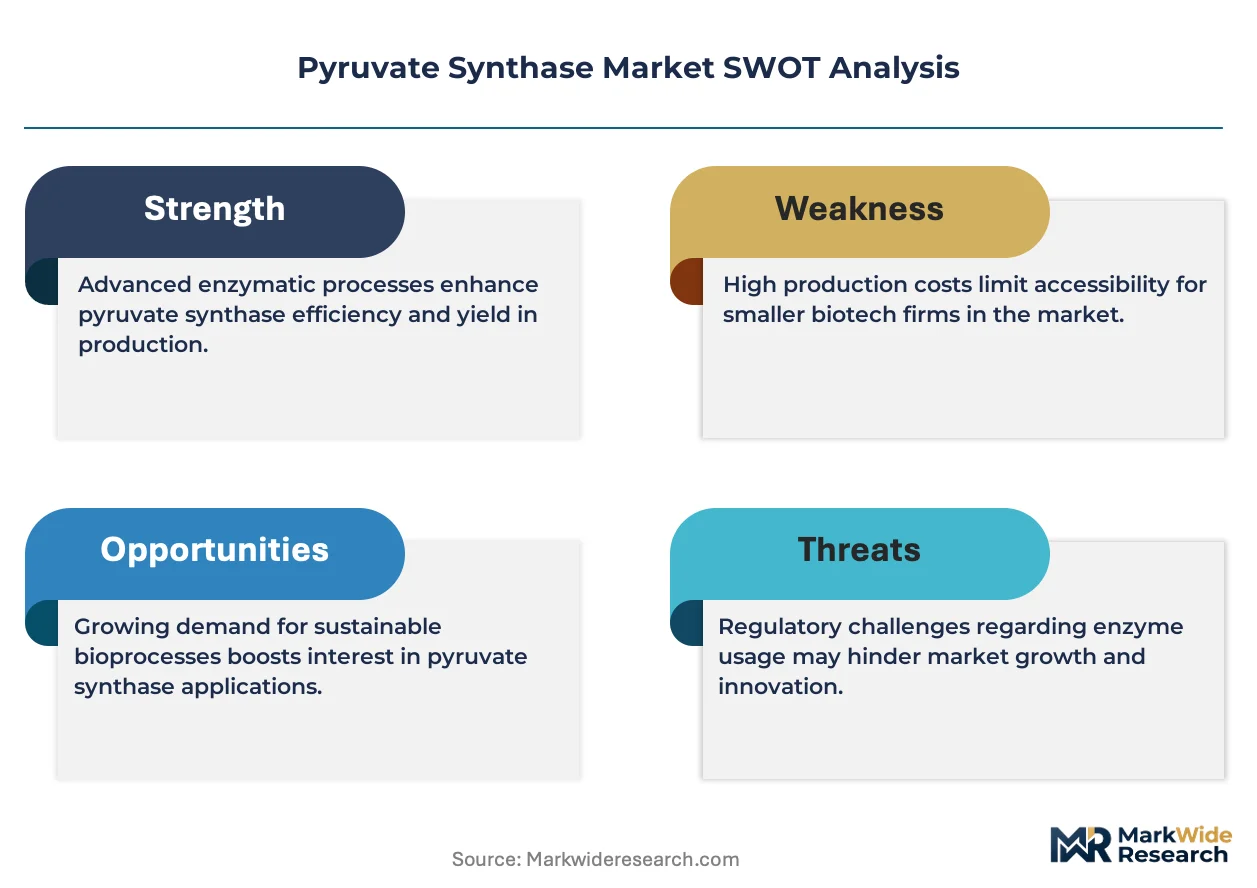
CRISPR-based metabolic engineering is pulling enzyme volumes into pharmaceutical pipelines at unprecedented scale, while ISO 13485 certification barriers are consolidating supplier tiers around qualified fermentation infrastructure.
Growth Catalysts
- NIH Synthetic Biology Consortia:Federated research funding in the United States is aggregating demand for diagnostic-grade enzymes around Boston and San Diego contract manufacturing clusters.
- FDA 21 CFR 820 Alignment:Quality system regulation enforcement for enzyme-based diagnostic reagents is accelerating validation investments among suppliers targeting US market entry.
- Lyophilized Formulation Advances:Ambient-temperature stable enzyme preparations are unlocking field diagnostic deployments in cold-chain-constrained academic procurement channels.
Market Restraints
- Thiamine Pyrophosphate Input Volatility:Cofactor cost fluctuations and magnesium/manganese supply concentration create margin compression for bulk enzyme manufacturers.
- REACH Characterization Burden:ECHA substance registration requirements impose documentation costs on European importers of recombinant enzyme preparations.
- Native Enzyme Substitution:Non-recombinant pyruvate synthase from specialized fermentation retains niche preference in certain legacy analytical protocols.
Strategic Opportunities
- EU AI Act Laboratory Integration:Emerging classification frameworks for automated diagnostic platforms will cascade into enzyme-integrated system procurement specifications.
- Stabilized Formulation Premium Tier:Logistics-robust enzyme products command price positioning in decentralized point-of-care testing networks.
- India CDSCO Diagnostic Pathway:Streamlined enzyme reagent registration under revised medical device rules offers first-mover positioning in South Asian contract research expansion.
Industry Challenges
- GMP Fermentation Talent Scarcity:Qualified bioprocess engineers capable of scaling E. coli expression systems to pharmaceutical-grade specifications remain concentrated in established manufacturing hubs.
- Dual-Territory Qualification Cost:Divergent FDA and EMA validation timelines force parallel track investments, inflating total cost of ownership for transatlantic suppliers.
- Batch Consistency Validation:Recombinant enzyme lot-to-lot variability documentation consumes analytical resources and extends release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyruvate Synthase Market |
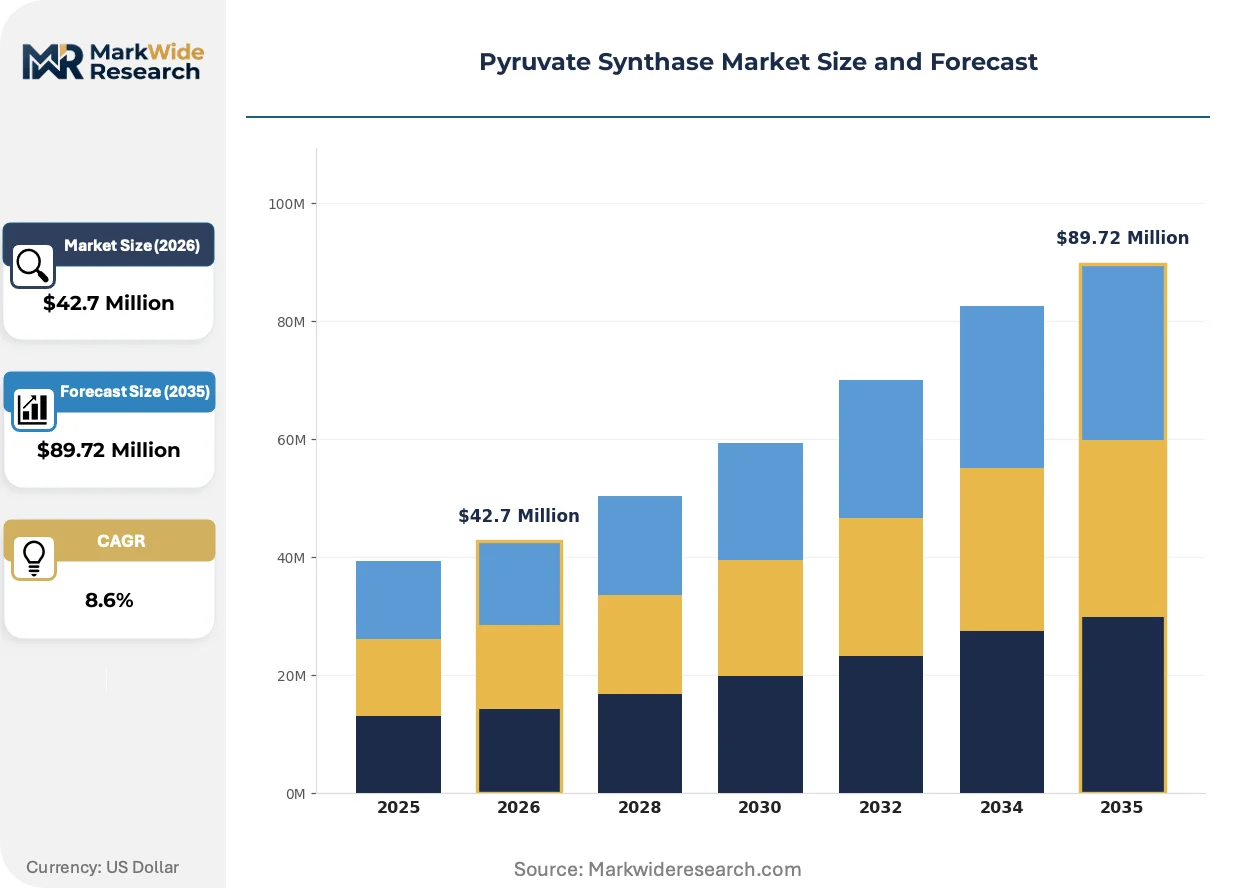
| Market Size in 2026 | $42.7 Million |
| Market Size in 2035 | $89.72 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Pyruvate Synthase, Natural Pyruvate Synthase, Enzyme Mixtures, Stabilized Formulations Application: Biochemical Research, Pharmaceutical Development, Agricultural Biotechnology, Diagnostic Tools End User: Academic Institutions, Pharmaceutical Companies, Biotech Firms, Research Laboratories Delivery Mode: Liquid Formulation, Lyophilized Powder, Tablet Form, Automated Systems |
| Companies Covered | Musashino Chemical Laboratory, Toray Industries, Lonza Group, Minakem, Tianjin Shengdao Technology, Shanghai Jinli Bio-tech, Zhonglan Industry, Sigma-Aldrich, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyruvate Synthase Market Evolving Landscape
Recombinant expression platforms and regulatory digitization are compressing development cycles, while procurement centralization is reshaping channel economics across institutional buyers.
Engineered E. coli expression systems with optimized codon usage and chaperone co-expression are displacing traditional fermentation-derived enzyme supplies in high-throughput screening applications. Pharmaceutical contract manufacturers in Massachusetts and California are adopting these platforms for CRISPR-edited cell line development. The shift is displacing legacy native enzyme inventories and consolidating purchasing power around suppliers with captive recombinant infrastructure.
EMA's Medical Device Regulation enforcement is tightening post-market surveillance requirements for enzyme-integrated diagnostic platforms across European member states. Manufacturers must now maintain updated technical documentation and periodic safety reporting for reagent components. In vitro diagnostic developers in Germany and the Netherlands are responding by dual-sourcing enzyme supply to mitigate single-supplier audit risks.
Academic procurement consortia are consolidating enzyme purchasing through shared service organizations rather than individual laboratory ordering. Research institutions in the United Kingdom and Australia are migrating toward framework agreements with pre-qualified enzyme catalog distributors. This concentration is squeezing smaller regional suppliers and rewarding vendors with direct channel control and ISO 9001-certified quality management systems.
Pyruvate Synthase Market Segmentation
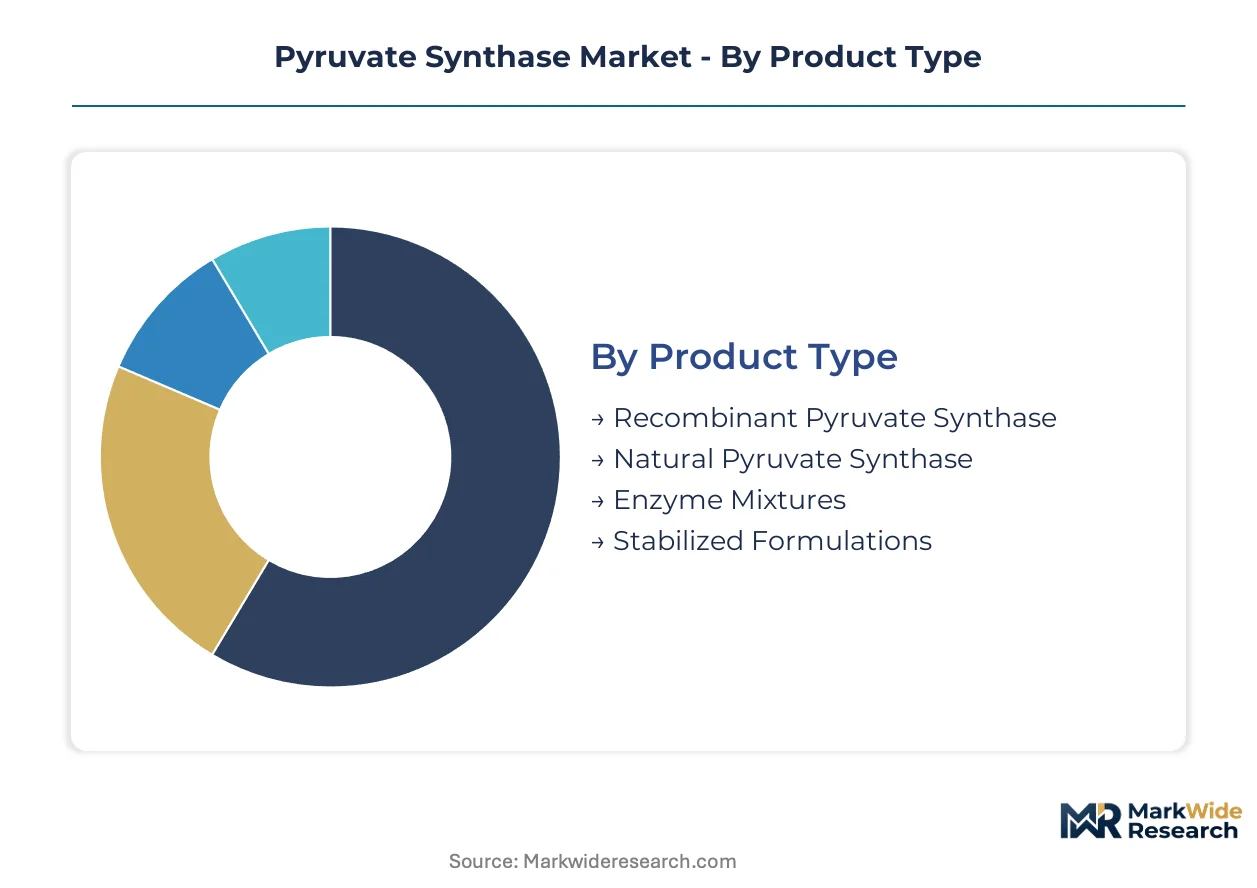
Segmentation in the pyruvate synthase market reveals how regulatory qualification tiers and application-specific performance requirements create distinct procurement channels. Each dimension—product type, application, end user, and delivery mode—carries unique compliance burdens and pricing implications that reshape supplier positioning.
Product Type:
FDA 21 CFR 820 quality system regulation and ISO 13485 certification requirements create sharp differentiation between qualified and unqualified enzyme grades, bifurcating procurement pools.
- Recombinant Pyruvate Synthase:Engineered E. coli expression systems with optimized codon usage deliver higher batch consistency than native fermentation sources. Pharmaceutical contract manufacturers in Massachusetts and California absorb the largest volumes for CRISPR-edited cell line development pipelines. ISO 13485-certified suppliers capture premium positioning through validated release documentation.
- Natural Pyruvate Synthase:Traditional fermentation-derived enzyme retains niche preference in legacy analytical protocols where protocol validation costs discourage substitution. REACH characterization burdens under ECHA substance registration requirements disadvantage European importers of these preparations. Academic procurement channels in cold-chain-constrained environments sustain residual demand.
- Enzyme Mixtures:Pre-formulated cofactor blends reduce thiamine pyrophosphate input volatility for high-throughput screening operations.
- Stabilized Formulations:Ambient-temperature logistics capability commands price premiums in decentralized point-of-care testing networks.
Recombinant pyruvate synthase handles the majority of throughput; stabilized formulations are expanding most quickly on share.
Application:
Volume concentration follows NIH funding geography, with synthetic biology consortia aggregating demand around specific metropolitan clusters.
- Pharmaceutical Development:CRISPR-based metabolic engineering pulls unprecedented enzyme volumes into drug discovery and cell therapy manufacturing. FDA-registered contract manufacturers around Boston and San Diego dominate procurement, with validation requirements under 21 CFR 820 shaping supplier qualification protocols. CDSCO diagnostic pathway streamlining in India offers first-mover positioning for South Asian contract research expansion.
- Biochemical Research:Academic consortia in the United Kingdom and Australia are migrating toward framework agreements with pre-qualified catalog distributors. Shared service organization purchasing concentrates buying power and squeezes smaller regional suppliers. Lyophilized powder preference persists where laboratory cold-chain infrastructure remains limited.
- Diagnostic Tools:EMA Medical Device Regulation enforcement tightens post-market surveillance for enzyme-integrated platforms across Germany and the Netherlands.
- Agricultural Biotechnology:Crop metabolic engineering applications absorb stabilized formulations for field-deployable testing protocols.
Pharmaceutical development absorbs the dominant share of qualified-grade supply; diagnostic tools are climbing the fastest on volume trajectory.
End User:
Procurement centralization patterns separate institutional buyers with captive quality systems from fragmented laboratory purchasing.
- Pharmaceutical Companies:GMP-grade fermentation infrastructure requirements and dual-territory FDA/EMA qualification costs consolidate supply relationships around Lonza Group and Thermo Fisher Scientific channel control. Batch consistency validation documentation consumes substantial analytical resources, extending release timelines and favoring suppliers with captive recombinant platforms.
- Academic Institutions:Framework agreement migration through shared service organizations rewards ISO 9001-certified vendors with direct channel presence. Procurement concentration is displacing individual laboratory ordering patterns across research-intensive universities.
- Biotech Firms:Venture-funded startups prioritize lyophilized formulations to minimize capital equipment requirements for cold-chain infrastructure.
- Research Laboratories:Government-funded facilities face budget pressure from divergent qualification regime compliance costs between FDA and EMA jurisdictions.
Pharmaceutical companies dominate qualified-grade procurement; biotech firms are gaining share fastest in stabilized formulation uptake.
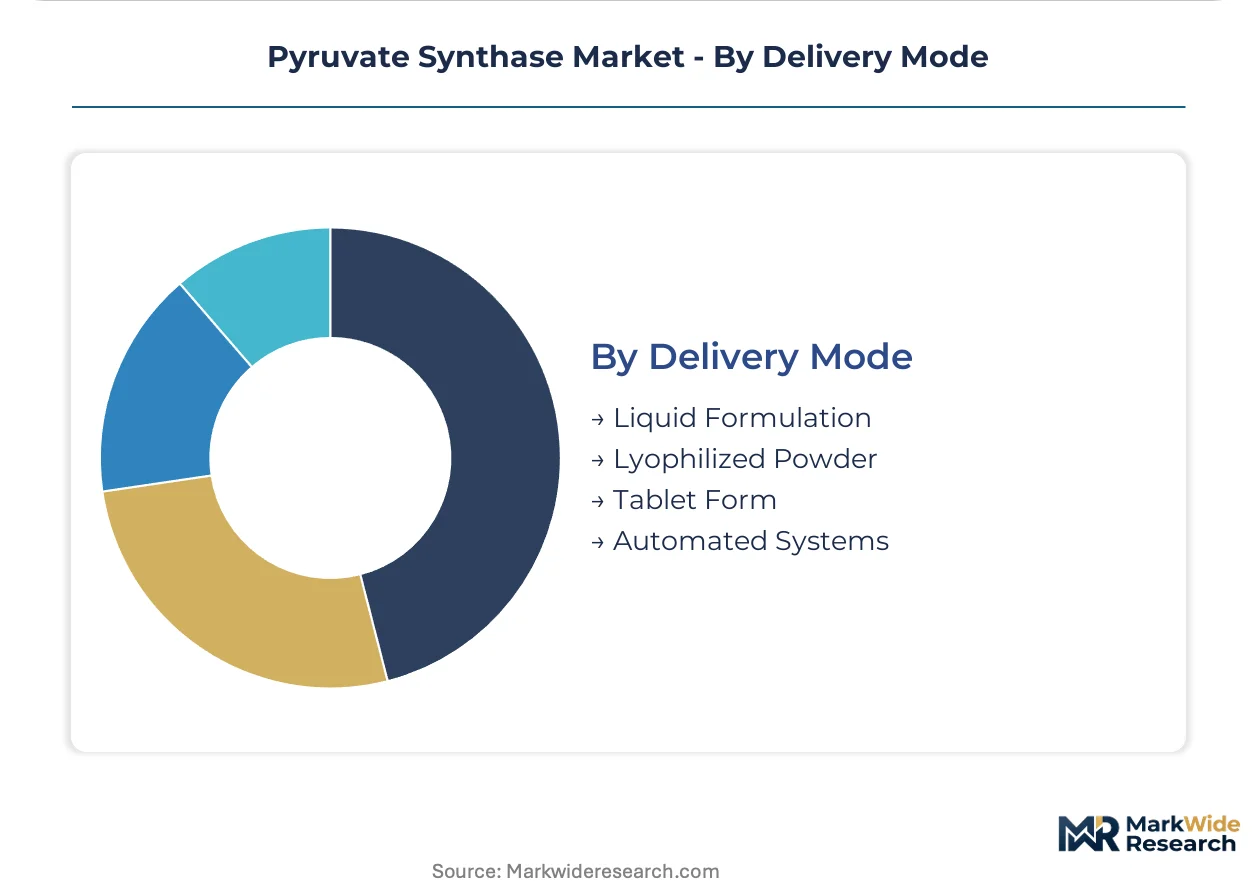
Delivery Mode:
Logistics robustness requirements separate premium-tier ambient-stable products from commodity cold-chain dependent supply.
- Lyophilized Powder:Structural preference in academic procurement channels where cold-chain infrastructure investment remains capital-constrained. Ambient-temperature stability unlocks field diagnostic deployments in decentralized testing networks. Shelf-life extension commands measurable price premiums over liquid alternatives.
- Liquid Formulation:Higher specific activity and convenience sustain preference in high-throughput screening applications with established cold-chain logistics. Pharmaceutical contract manufacturers absorb the largest volumes for continuous process integration.
- Tablet Form:Unit-dose convenience serves point-of-care testing portability requirements with minimal reconstitution steps.
- Automated Systems:EU AI Act classification frameworks for laboratory automation will cascade into procurement specifications for enzyme-integrated diagnostic platforms.
Liquid formulation retains the majority of current throughput; automated systems represent the steepest expansion trajectory on emerging platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal research funding and diagnostic regulatory pathways are concentrating pyruvate synthase procurement in specific national clusters. NIH appropriations, EMA Medical Device Regulation enforcement, and CDSCO pathway streamlining each reshape supplier qualification requirements within their jurisdictions.
United States
NIH synthetic biology consortia aggregate enzyme demand around Boston and San Diego contract manufacturing clusters. FDA 21 CFR 820 quality system regulation enforcement accelerates validation investments for diagnostic-grade enzyme suppliers. Massachusetts-based CRISPR-edited cell line developers absorb the largest qualified-grade volumes.
Germany
EMA Medical Device Regulation post-market surveillance tightens technical documentation requirements for enzyme-integrated diagnostic platforms. ECHA REACH substance registration imposes characterization burdens on recombinant enzyme importers. Bavarian and North Rhine-Westphalian in vitro diagnostic developers dual-source supply to mitigate single-supplier audit risks.
India
CDSCO streamlined enzyme reagent registration under revised medical device rules attracts contract research expansion. BIS quality certification requirements filter supplier eligibility for institutional procurement. Maharashtra and Karnataka biotech corridors absorb stabilized formulation volumes for field-deployable testing protocols.
United Kingdom
Academic procurement consortia migrate toward framework agreements with pre-qualified enzyme catalog distributors. Shared service organization purchasing concentrates buying power across research-intensive universities. London and Southeast England institutions lead the shift from individual laboratory ordering patterns.
Japan
PMDA quality system requirements for diagnostic reagents shape supplier validation protocols for pharmaceutical-grade enzyme entry. METI funding for synthetic biology infrastructure expands academic and industrial research demand. Kanto and Kansai metropolitan clusters concentrate bioprocess engineering talent for GMP fermentation scale-up.
Pyruvate Synthase Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with ISO 13485-qualified fermentation infrastructure separating qualified pharmaceutical-grade suppliers from commodity catalog distributors. The supplier base consolidates around captive recombinant expression platforms and direct channel control capabilities. Three archetypes dominate: GMP-grade fermentation specialists with dual-territory FDA/EMA qualification, broad-catalog distributors with ISO 9001-certified quality systems, and regional chemical manufacturers serving legacy analytical protocols. Competitive moves center on strategic partnerships for automated diagnostic platform integration and capacity expansion in E. coli expression systems.
Among Japan-based chemical specialists, Musashino Chemical Laboratory and Toray Industries occupy positions within the precision fermentation tier. Lonza Group anchors the GMP-grade contract manufacturing segment with European pharmaceutical supply chain integration. Sigma-Aldrich and Thermo Fisher Scientific exemplify broad-catalog distribution archetypes with North American research institution channel control. These five entities represent the dominant competitive anchors across certification-qualified, scale-driven, and geography-focused positioning vectors.
| Leading Market Players |
|---|
| Musashino Chemical Laboratory |
| Toray Industries |
| Lonza Group |
| Minakem |
| Tianjin Shengdao Technology |
| Shanghai Jinli Bio-tech |
| Zhonglan Industry |
| Sigma-Aldrich |
| Thermo Fisher Scientific |
| Others |
Value Network & Pricing Analysis
Recombinant E. coli expression systems displacing traditional fermentation-derived enzymes are simultaneously redrawing supply geography toward Massachusetts and California contract manufacturing clusters while compressing price premiums for native enzyme alternatives. This substitution dynamic concentrates pricing power with ISO 13485-certified suppliers possessing captive GMP fermentation infrastructure.
Pricing Analysis
Certification level creates the primary spread between qualified pharmaceutical-grade and commodity research-grade supply. Three-tier pricing structure separates ISO 13485-certified diagnostic grades from ISO 9001 industrial catalog products and uncertified commodity preparations. Cost compression in the research-grade tier intensifies as academic procurement consortia consolidate purchasing through shared service organizations. Biotech startups exhibit highest price sensitivity due to venture capital constraints, while pharmaceutical contract manufacturers prioritize batch consistency documentation over unit cost.
Supply Chain Analysis
Inventory lead times stretch longest for thiamine pyrophosphate cofactor inputs sourced from concentrated magnesium and manganese suppliers. Manufacturing concentrates in the United States, Germany, and Japan where GMP fermentation talent pools anchor production. Raw material dependencies on thiamine pyrophosphate, magnesium salts, and manganese trace elements expose margins to commodity volatility. Single-source vulnerability in cofactor supply creates qualification bottlenecks for dual-territory FDA and EMA suppliers. Distribution runs through direct channel relationships with research institutions and pharmaceutical contract manufacturers rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated pharmaceutical contract manufacturers around Boston and San Diego, fragmenting negotiating leverage for smaller academic purchasers. This consolidation rewards suppliers with validated release documentation and captive recombinant platforms.
For Market Incumbents: Consolidate supply relationships through GMP fermentation capacity expansion in established Massachusetts and California clusters. Deepen backward integration into thiamine pyrophosphate cofactor supply to defend margins against input volatility. Prioritize dual-territory FDA and EMA qualification investments to capture pharmaceutical contract manufacturing volumes. For New Entrants and Emerging Players: Differentiate on stabilized formulation capabilities for ambient-temperature logistics in cold-chain-constrained academic and field diagnostic channels. Target India's CDSCO streamlined diagnostic reagent registration pathway for first-mover positioning in South Asian contract research expansion. Pursue direct channel partnerships with United Kingdom and Australian academic procurement consortia migrating toward framework agreements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed GMP fermentation specialists possessing ISO 13485 certification but limited recombinant platform scale. Long-term viability hinges on CRISPR-based metabolic engineering pipeline durability and diagnostic platform integration mandates under the EU AI Act. Watch for EMA Medical Device Regulation enforcement tightening post-market surveillance requirements as an inflection signal for dual-sourcing acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Fermentation Capacity Expansion | Captures NIH-funded synthetic biology consortia demand in Boston and San Diego clusters. |
| Dual-Territory Qualification Investment | Reduces total cost of ownership for transatlantic pharmaceutical contract manufacturers. |
| Stabilized Formulation Development | Unlocks price premiums in decentralized point-of-care testing networks with ambient logistics. |
| Backward Integration into Cofactor Supply | Mitigates thiamine pyrophosphate input volatility compressing bulk enzyme margins. |
| Academic Procurement Consortium Partnership | Secures framework agreement positioning as United Kingdom and Australian institutions consolidate purchasing. |
Research Methodology
Operator-level perspectives from bioprocess engineers, pharmaceutical procurement managers, diagnostic platform developers, and academic shared service organization directors anchored the qualitative base. Primary interviews combined with secondary validation from FDA 21 CFR 820 guidance documents, EMA Medical Device Regulation technical documentation requirements, CDSCO medical device registration databases, and NIH synthetic biology consortium funding disclosures. Bottom-up enzyme volume modeling triangulated against top-down pharmaceutical and diagnostic market sizing.
Sensitivity analysis tested forecast robustness across cofactor cost volatility scenarios and regulatory timeline variations throughout the projection horizon. Segmentation dimensions modeled include product type, application, end user, and delivery mode alongside regional regulatory cluster differentiation. CAGRs derived from volume trajectory analysis incorporating CRISPR pipeline expansion rates and diagnostic platform integration mandates. Forecast inputs included E. coli expression system yield improvements and lyophilization technology advancement curves.
Material uncertainties — thiamine pyrophosphate supply disruptions, divergent FDA and EMA validation timeline extensions, and native enzyme substitution persistence in legacy protocols — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Cellulose Enzyme Market
Industrial Biotechnology
Inulinase Market
Industrial Biotechnology
Haematococcus Pluvialis Market
Industrial Biotechnology
United States Biocatalyst Market
Industrial Biotechnology
Biocatalyst Market
Industrial Biotechnology
Beta-Glucanase Market
Industrial Biotechnology
Styrene Monooxygenase Market
Industrial Biotechnology
Phospholipase Enzyme Market
Industrial Biotechnology
Unnatural Amino Acids Market
Industrial Biotechnology
Bio-Refinery Market
Industrial Biotechnology
Hydrolase Enzymes Market
Industrial Biotechnology
Redox Enzymes Market
Industrial Biotechnology
Global Specialty Enzymes Market
Industrial Biotechnology
GCC Biocatalyst Market
Industrial Biotechnology
Fungal Amylase Market
Industrial Biotechnology
Global Protein Hydrolysis Enzymes Market