
 Protease Market | 2026-2036
Protease Market Size, Share, and Industry Trends Forecast 2026-2036
Protease Market Analysis
Biologics downstream processing revenue is reshaping margin distribution across the protease value chain. Novonesis Group leverages its microbial fermentation expertise to dominate industrial-scale enzyme supply. BASF SE anchors its position through backward integration into strain development and proprietary expression systems. DSM-Firmenich AG differentiates via recombinant protease portfolios tailored to pharmaceutical-grade specifications.
Proteases constitute a class of hydrolytic enzymes that cleave peptide bonds in proteins, typically operating at optimal temperatures between 37°C and 60°C and pH ranges from 2 to 11 depending on source organism. These enzymes catalyze protein breakdown for applications spanning food tenderization, detergent formulation, therapeutic digestion aids, and biopharmaceutical processing. Microbial proteases command the largest volume share due to scalable fermentation production and broad pH stability profiles. Recombinant proteases represent the fastest-expanding category as pharmaceutical applications demand batch-to-batch consistency and defined purity grades. Plant proteases maintain niche positions in food processing where clean-label positioning supports premium positioning.
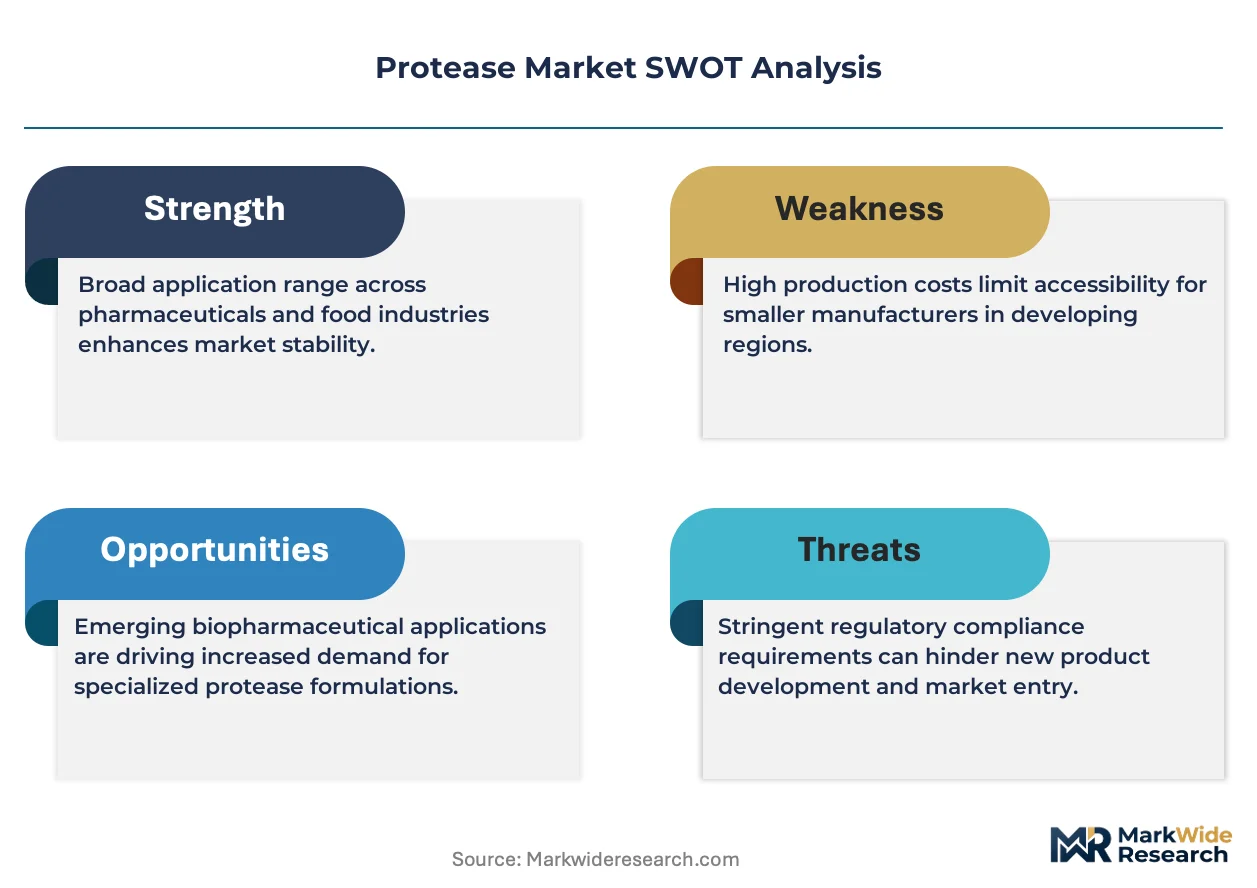
FDA process analytical technology guidelines and EMA's good manufacturing practice standards for biologics enforce stringent purity and activity specifications on therapeutic-grade proteases. ISO 9001 quality management and ICH Q7 guidelines further constrain supplier qualification pathways for pharmaceutical end users. REACH registration requirements in Europe add compliance costs for imported enzyme preparations. Stakeholders must monitor evolving pharmacopeial monographs and emerging biosimilar regulations to anticipate specification shifts that will reshape supplier competitive standing.
Market Dynamics
FDA process analytical technology guidelines are compressing batch release timelines for therapeutic-grade proteases, forcing manufacturers to embed real-time quality analytics into fermentation and downstream processing workflows rather than relying on end-point testing.
Growth Catalysts
- Biologics downstream processing expansion:Contract manufacturing organizations are scaling dedicated protease purification suites to meet monoclonal antibody production demand. Single-use bioreactor adoption accelerates enzyme consumption per batch.
- REACH registration harmonization:ECHA's consolidated enzyme registration pathways reduce compliance duplication across EU member states. Industrial users gain supplier qualification efficiency.
- Cell-cultured meat processing:Precision fermentation facilities in Singapore and the Netherlands require food-grade proteases for texture modification and protein hydrolysate production.
Market Restraints
- Specialized fermentation feedstock volatility:Soy peptone and yeast extract prices fluctuate with agricultural commodity cycles, compressing margins for bulk industrial protease producers.
- German Rhine-Main cluster concentration:Over 40% of European pharmaceutical-grade protease fermentation capacity sits within 150 kilometers of Frankfurt, creating geographic single-point-of-failure exposure.
- Recombinant expression yield ceilings:Pichia pastoris and CHO cell systems face productivity plateaus above 5 grams per liter for complex proteases with disulfide bonds.
Strategic Opportunities
- Indian biosimilar manufacturing scale-up:CDSCO's accelerated approval pathways for biosimilar enzymes create entry points for contract fermentation services targeting export markets.
- Cold-active protease development:Psychrophilic enzymes from Antarctic microbial sources enable low-temperature detergent formulations that reduce household energy consumption.
- Continuous bioprocessing integration:Perfusion bioreactor technology convergence with in-line protease digestion steps collapses residence times for viral vector manufacturing.
Industry Challenges
- Pharmacopeial monograph alignment:USP, EP, and JP protease activity assay methods diverge in substrate specifications, forcing manufacturers to maintain three parallel validation protocols for international supply.
- Containment engineering for allergenic strains:Bacillus subtilis-derived protease production requires ISO 8 cleanroom upgrades and dedicated HVAC isolation that extends facility commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protease Market |
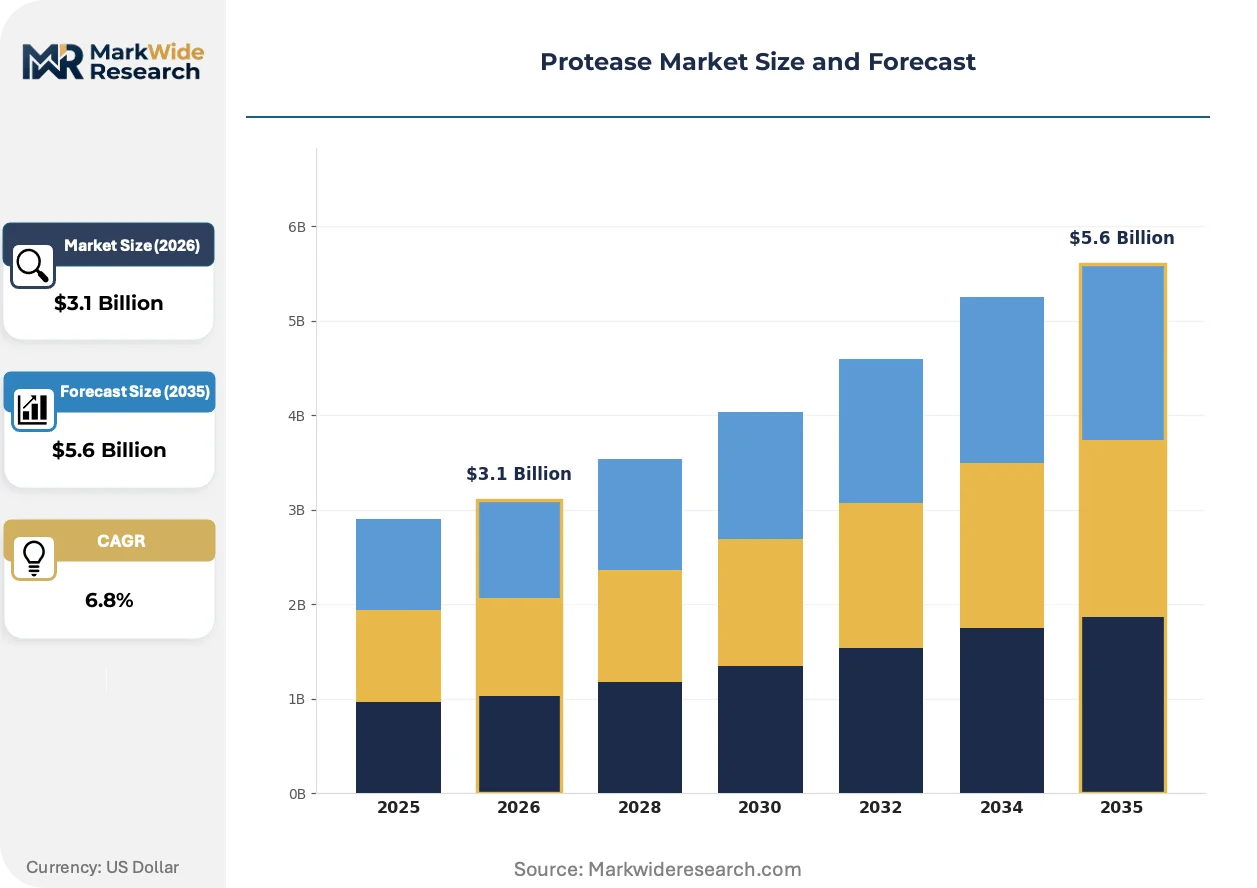
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Animal Proteases, Plant Proteases, Microbial Proteases, Recombinant Proteases Application: Food Processing, Pharmaceuticals, Diagnostics, Animal Feed End User: Healthcare, Food Industry, Research Laboratories, Agriculture Form: Liquid, Powder, Granular, Tablet |
| Companies Covered | Associated British Foods plc, BASF SE, Novonesis Group, Biocatalysts Ltd., Advanced Enzyme Technologies Limited, DSM-Firmenich AG, Amano Enzyme Inc., Kemin Industries Inc., International Flavors & Fragrances Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protease Market Emerging Trajectories
Enzyme engineering platforms are compressing development cycles for proteases with tailored substrate specificity, while regulatory pressure on biologics manufacturing purity is reshaping supplier qualification criteria across pharmaceutical value chains.
Computational protein design is hybridizing directed evolution with structure-based modeling to generate proteases with engineered pH profiles. Biopharmaceutical process developers at CDMOs are adopting these variants for integrated capture-and-cleave workflows. The technology is collapsing the traditional separation between upstream fermentation and downstream purification process design.
EMA's revised good manufacturing practice Annex 1 guidelines mandate enhanced environmental monitoring for sterile enzyme manufacturing. Facilities must implement continuous viable particle detection in Grade A/B zones. Aseptic protease producers in Ireland and Switzerland are retrofitting isolator technology to avoid batch disqualification risks.
Biopharmaceutical procurement teams are consolidating protease suppliers to reduce audit burden, awarding multi-year framework agreements to qualified vendors with dedicated pharmaceutical-grade production lines. CDMOs in Germany and Massachusetts are accepting price premiums for single-source supply security. This concentration is visible most acutely in gene therapy viral vector manufacturing where protease digestion steps require vendor-locked process validation packages.
Protease Market Segmentation
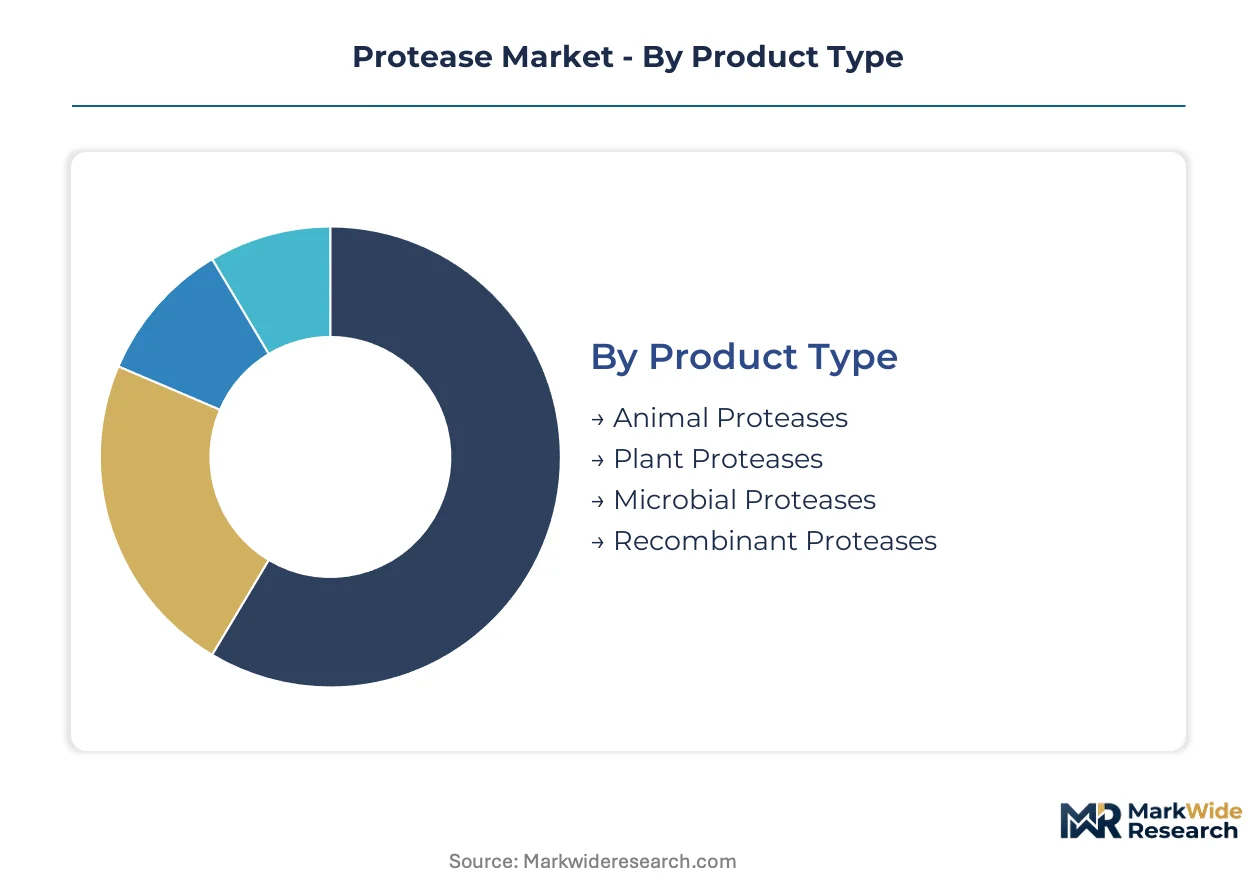
Protease segmentation reflects divergent purity requirements and production economics across industrial and therapeutic applications. Manufacturers configure fermentation capacity and downstream processing suites differently depending on which segments they target.
Product Type:
Mature fermentation-based categories dominate current volume, while recombinant technologies are reshaping pharmaceutical-grade supply.
- Microbial Proteases:Bacillus and Aspergillus-derived enzymes deliver broad pH stability from 4 to 11 and thermal tolerance to 60°C. Bulk detergent and food processing demand concentrates in Germany's Rhine-Main cluster where 40% of European fermentation capacity resides.
- Recombinant Proteases:Genetically engineered variants achieve batch-to-batch consistency exceeding 98% purity with defined glycosylation patterns. Gene therapy viral vector manufacturing in Massachusetts and Basel drives demand for vendor-locked process validation packages.
- Animal Proteases:Pancreatic extracts such as trypsin and chymotrypsin retain positions in cell culture media formulations.
- Plant Proteases:Papain and bromelain serve clean-label food processing segments in premium positioning applications.
Microbial proteases retain volume leadership; recombinant proteases hold the steepest expansion curve.
Application:
Cost tier differentiation separates commodity enzyme sales from pharmaceutical-grade contracts with audit-intensive qualification requirements.
- Pharmaceuticals:Therapeutic proteases for digestive disorders and biologics downstream processing require ISO 9001 certification and ICH Q7 compliance. FDA process analytical technology guidelines compress batch release timelines and force real-time quality analytics adoption.
- Food Processing:Meat tenderization, cheese making, and protein hydrolysate production consume high-volume, lower-purity grades. Singapore and Netherlands precision fermentation facilities for cell-cultured meat are emerging demand centers.
- Diagnostics:Proteases enable sample preparation and immunoassay workflows in clinical laboratory settings.
- Animal Feed:Exogenous enzymes improve protein digestibility in poultry and swine nutrition formulations.
Food processing commands absolute volume; pharmaceuticals generates the highest margin per kilogram.
End User:
Customer type determines procurement complexity, with healthcare and research buyers imposing qualification burdens that industrial users avoid.
- Healthcare:Hospitals and specialty clinics prescribe digestive enzyme replacement therapies. EMA's revised GMP Annex 1 mandates enhanced environmental monitoring for sterile manufacturing, forcing isolator retrofits in Ireland and Switzerland.
- Food Industry:Multinational processors negotiate long-term supply agreements for standardized activity units. REACH registration harmonization through ECHA reduces compliance duplication across EU member states.
- Research Laboratories:Academic and biopharma R&D facilities purchase small-batch, high-specificity proteases for assay development.
- Agriculture:Compound feed manufacturers integrate proteases into premix formulations for livestock operations.
Food industry procurement scales largest; healthcare compliance requirements filter supplier participation most aggressively.
Form:
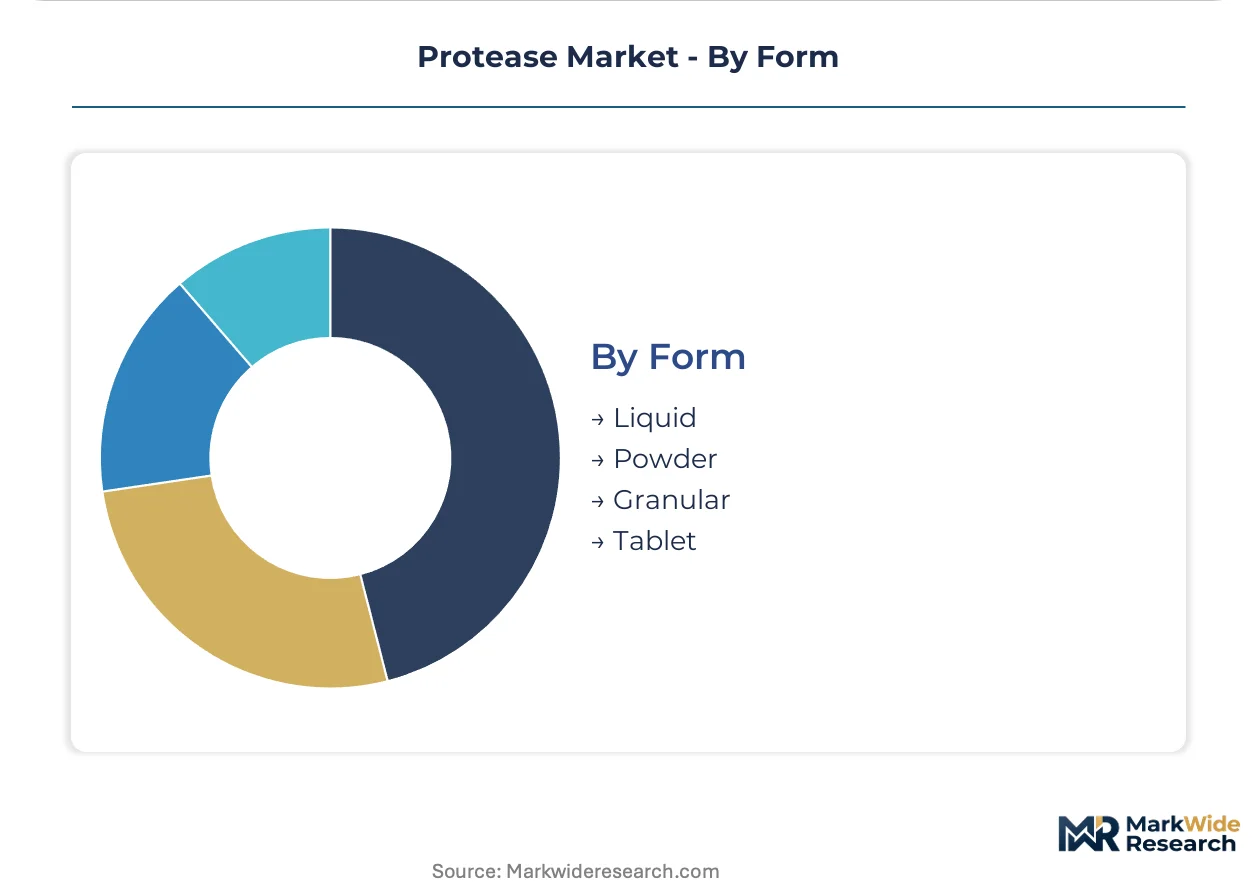
Supply concentration in liquid formulations reflects biopharmaceutical process integration trends, while powder and granular forms serve cost-sensitive industrial segments.
- Liquid:Ready-to-use concentrates integrate directly into automated bioprocessing workflows. Single-use bioreactor adoption accelerates consumption per batch in contract manufacturing organizations.
- Powder:Spray-dried preparations offer extended shelf stability and reduced shipping costs for bulk industrial buyers.
- Granular:Dust-free formulations address occupational exposure concerns in detergent manufacturing.
- Tablet:Unit-dose presentations serve over-the-counter digestive aid markets and clinical prescription channels.
Liquid formulations align with continuous bioprocessing adoption; tablets capture retail pharmacy distribution efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade buyers in Germany and Switzerland absorb price premiums for compliance assurance, while detergent and feed manufacturers in India and Brazil negotiate aggressively on activity-unit costs. Food processors in the Netherlands and Singapore occupy a middle tier, balancing clean-label positioning against fermentation scale economics.
United States
Gene therapy viral vector manufacturing in Massachusetts drives demand for vendor-locked recombinant protease validation packages. FDA process analytical technology guidelines compress batch release timelines and mandate real-time quality analytics integration. The Greater Boston biotech corridor concentrates contract manufacturing capacity for monoclonal antibody downstream processing.
Germany
The Rhine-Main cluster hosts over 40% of European pharmaceutical-grade protease fermentation capacity within 150 kilometers of Frankfurt. EMA's revised GMP Annex 1 guidelines enforce enhanced environmental monitoring for sterile manufacturing, forcing isolator retrofits. BASF SE and Novonesis Group anchor industrial-scale supply from backward-integrated strain development facilities.
India
CDSCO's accelerated approval pathways for biosimilar enzymes attract contract fermentation investment targeting export markets. Bulk industrial protease consumption concentrates in Gujarat and Maharashtra for detergent and textile processing. Domestic manufacturers leverage agricultural commodity proximity to manage soy peptone and yeast extract feedstock costs.
Singapore
Precision fermentation facilities for cell-cultured meat processing require food-grade proteases for texture modification and protein hydrolysate production. The national food regulator enforces strict safety standards for novel protein production inputs. Biopolis and Tuas Biomedical Park cluster contract manufacturing capacity for Asia-Pacific biologics markets.
Switzerland
Swissmedic oversight of therapeutic-grade enzyme manufacturing maintains premium positioning for Basel-area producers. Aseptic protease facilities retrofit isolator technology to avoid batch disqualification risks under tightening environmental monitoring rules. DSM-Firmenich AG differentiates through recombinant portfolios tailored to pharmaceutical-grade specifications.
Protease Market Vendor Landscape
Capability concentration sits with specialized fermentation houses possessing proprietary expression systems; scale advantage sits with diversified chemical conglomerates with captive raw material streams. The market structures around three tiers: global enzyme specialists with microbial platform dominance, diversified nutrition-science conglomerates with backward integration into strain development, and regional contract manufacturers serving price-sensitive industrial segments. Dominant competitive moves include capacity expansion in pharmaceutical-grade fermentation suites and strategic partnerships for continuous bioprocessing technology access.
Within the global enzyme specialist tier, Novonesis Group and Amano Enzyme Inc. exemplify platform-scale microbial fermentation expertise. BASF SE anchors the diversified conglomerate archetype through integrated chemical-enzyme production networks. DSM-Firmenich AG occupies a hybrid position, combining recombinant specialization with nutrition-science distribution reach.
| Leading Market Players |
|---|
| Associated British Foods plc |
| BASF SE |
| Novonesis Group |
| Biocatalysts Ltd. |
| Advanced Enzyme Technologies Limited |
| DSM-Firmenich AG |
| Amano Enzyme Inc. |
| Kemin Industries Inc. |
| International Flavors & Fragrances Inc. |
| Others |
Supply Flow & Price Mechanics
The Rhine-Main biotech cluster's specialized fermentation capacity expansion is compressing margins for bulk industrial proteases while amplifying pricing power for pharmaceutical-grade suppliers with isolator-equipped suites. Feedstock volatility in soy peptone and yeast extract markets feeds directly into contract renegotiation cycles across detergent and food processing tiers.
Pricing Analysis
After-sales revenue from multi-year framework agreements and vendor-locked process validation packages drives lifetime value for qualified pharmaceutical-grade suppliers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels separates audit-intensive certification tiers from commodity activity-unit sales. Pricing pressure stems from REACH registration harmonization reducing compliance duplication and enabling supplier qualification efficiency. Industrial detergent manufacturers in India and Brazil exhibit highest price sensitivity, while gene therapy CDMOs in Massachusetts and Basel absorb premiums for single-source security.
Supply Chain Analysis
Supplier-financing through extended payment terms and supply-chain finance facilities has become standard for bulk industrial buyers managing agricultural commodity cycle exposure. Production gravity centers on Germany, India, and Singapore, with the Rhine-Main cluster anchoring European pharmaceutical-grade capacity. Raw material dependencies include soy peptone, yeast extract, and specialized fermentation media formulations. Single-source vulnerability concentrates in the 150-kilometer Frankfurt radius where over 40 percent of European pharmaceutical-grade capacity resides. Distribution runs through direct pharmaceutical procurement teams, industrial chemical distributors, and contract manufacturing organization supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The protease market sits in early-cycle expansion as recombinant expression platforms displace traditional fermentation for biologics downstream processing, with cell-cultured meat precision fermentation adding parallel demand vectors.
For Market Incumbents: Build regulatory moats through dedicated pharmaceutical-grade isolator retrofits and vendor-locked process validation packages that lock in gene therapy CDMO relationships. BASF SE and Novonesis Group should expand backward integration into proprietary strain development to defend against emerging recombinant specialists. Containment engineering investments for allergenic Bacillus subtilis strains create qualification barriers that extend facility commissioning timelines for challengers. For New Entrants and Emerging Players: Establish a beachhead in cold-active protease development for low-temperature detergent formulations targeting energy-conscious European consumers. Indian contract fermentation services targeting CDSCO-accelerated biosimilar export pathways offer the most penetrable geography. A go-to-market angle anchored in continuous bioprocessing technology partnerships with perfusion bioreactor manufacturers collapses residence times for viral vector manufacturing clients. For Investors and Strategic Acquirers: Long-term, this sits as a platform-chemistry play because microbial fermentation expertise and proprietary expression systems compound defensibility across therapeutic, food, and industrial applications. Acquisition targets should prioritize mid-cap specialists with recombinant portfolios and existing ICH Q7 compliance rather than bulk industrial players facing feedstock margin compression. The signal to watch is EMA GMP Annex 1 enforcement intensity driving isolator retrofit demand and consolidating supplier qualification pools.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Isolator Retrofit | EMA's revised GMP Annex 1 mandates continuous viable particle detection in Grade A/B zones for sterile enzyme manufacturing. |
| Backward Integration into Strain Development | Proprietary expression systems in Pichia pastoris and CHO cells differentiate recombinant protease suppliers for gene therapy applications. |
| Cold-Active Protease Platform Development | Psychrophilic enzymes from Antarctic microbial sources enable detergent formulations that reduce household energy consumption. |
| Continuous Bioprocessing Technology Partnership | Perfusion bioreactor convergence with in-line protease digestion collapses residence times for viral vector manufacturing. |
| Multi-Year Framework Agreement Consolidation | CDMO procurement teams in Germany and Massachusetts accept price premiums for single-source supply security and reduced audit burden. |
Methodological Framework
A spread of perspectives from fermentation process engineers, pharmaceutical procurement managers, regulatory affairs specialists, and contract manufacturing organization executives converged on the working assumptions for capacity expansion timelines and qualification pathway durations. Primary interviews combined with secondary validation from FDA process analytical technology guidelines, EMA GMP Annex 1 revisions, CDSCO biosimilar approval pathways, and REACH registration databases. Bottom-up triangulation across product type, application, and end-user segments was cross-checked against top-down macroeconomic drivers.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by product type (microbial, recombinant, animal, plant), application (pharmaceuticals, food processing, diagnostics, animal feed), and end user (healthcare, food industry, research laboratories, agriculture). CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trends across purity grades. Industry-specific forecast inputs included single-use bioreactor adoption rates in contract manufacturing organizations and precision fermentation facility buildouts for cell-cultured meat processing.
Stress conditions across feedstock price volatility, regulatory enforcement intensity, and recombinant expression yield plateaus were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EMA GMP Annex 1 implementation timelines and CDSCO approval pathway efficiency. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
China Specialty Enzymes Market
Industrial Biotechnology
Biocatalyst Market
Industrial Biotechnology
Japan Biocatalyst Market
Industrial Biotechnology
Esterase Market
Industrial Biotechnology
Haematococcus Pluvialis Market
Industrial Biotechnology
Pyruvate Synthase Market
Industrial Biotechnology
Global Carbohydrase Market
Industrial Biotechnology
Styrene Monooxygenase Market
Industrial Biotechnology
Unnatural Amino Acids Market
Industrial Biotechnology
Hydrolase Enzymes Market
Industrial Biotechnology
Fungal Amylase Market
Industrial Biotechnology
Glucoamylase Market
Industrial Biotechnology
Europe Biocatalyst Market
Industrial Biotechnology
Global Enzymes Market
Industrial Biotechnology
Americas Enzymes Market
Industrial Biotechnology
Marine Enzymes Market