
 Bio-Refinery Market | 2026-2036
Bio-Refinery Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Refinery Market Outlook
Project finance structures with offtake-linked debt is tilting competitive access toward firms with balance-sheet depth and utility partnerships. Neste leverages its Singapore and Rotterdam refining complexes to sustain multi-feedstock flexibility across waste oils and residues. Valero anchors its position through captive ethanol logistics and pipeline-connected distribution. ADM competes by extending its origination network from farm gate to biorefinery intake, controlling input cost volatility.
A bio-refinery converts lignocellulosic, oleochemical, or waste-derived feedstocks into fuels, chemicals, and energy products through thermochemical or biochemical processing at temperatures ranging from 50°C to 700°C depending on the conversion pathway. The primary purpose is displacing fossil carbon in hard-to-abate sectors where electrification remains impractical. Thermochemical platforms dominate current installed capacity due to faster throughput and lower water intensity, while biochemical routes capture margin pools in specialty chemicals where enantiomeric purity commands premium pricing. Agricultural residues lead feedstock intake volume, though energy crops represent the fastest-expanding category as per-acre yield genetics improve.
The EPA's Renewable Fuel Standard, the EU Green Deal's Fit for 55 framework, and Brazil's ANP biodiesel blending mandates collectively shape demand floors and product qualification standards across the three largest demand centers. These frameworks penalize fossil carbon intensity and restrict market access to certified low-ILUC feedstocks, forcing facility designers to embed traceability systems from inception. Stakeholders must monitor feedstock certification fragmentation, as diverging land-use criteria between jurisdictions threaten to bifurcate trade flows and strand assets in non-compliant regions.
Market Dynamics
Capital allocation in bio-refining is pivoting toward thermochemical platforms as feedstock traceability requirements harden under the EU F-Gas Regulation and Brazil's ANP mandates. Project developers now embed certification systems at the engineering phase to secure offtake-linked debt.
Growth Catalysts
- Aviation sector decarbonization:Airlines under CORSIA and ICAO carbon-offsetting rules are contracting long-term renewable fuel offtake, pulling investment into hydroprocessed esters and fatty acids infrastructure.
- EU Green Deal Fit for 55:The framework's transport fuel carbon-intensity targets create binding demand floors for certified low-ILUC feedstocks, redirecting refinery retrofit capital toward second-generation pathways.
- Midwest feedstock clustering:Corn stover and soybean oil collection networks across Iowa, Illinois, and Nebraska reduce logistics costs below break-even thresholds for cellulosic ethanol producers.
Market Restraints
- Feedstock cost volatility:Agricultural residue prices swing with corn and soybean futures, compressing margin predictability for biochemical platform operators lacking origination control.
- Capital intensity barriers:Thermochemical gasification units require $400-600 million per facility, restricting viable project sponsors to utility-backed developers with balance-sheet depth.
- Certification fragmentation:Divergent land-use criteria between EU RED III and U.S. EPA RFS2 threaten to bifurcate trade flows and strand assets in non-compliant sourcing regions.
Strategic Opportunities
- Indonesia biodiesel expansion:The B40 blending mandate trajectory creates import demand for waste oil and residue-based methyl esters, opening arbitrage for Southeast Asian collection infrastructure.
- Specialty chemical enantiomers:Biochemical fermentation platforms targeting pharmaceutical-grade purity command 3-5x fuel-equivalent margins, rewarding precision strain engineering.
- Pipeline-connected distribution:Midstream partnerships with existing refined product networks eliminate trucking costs and unlock military and marine fuel offtake channels.
Industry Challenges
- Process engineering talent scarcity:Deep expertise in pyrolysis reactor design and enzymatic hydrolysis optimization concentrates at a handful of research universities and incumbent technology licensors.
- Integrated traceability system deployment:Blockchain-enabled feedstock provenance tracking must interface with legacy elevator and crushing plant IT architectures, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Refinery Market |
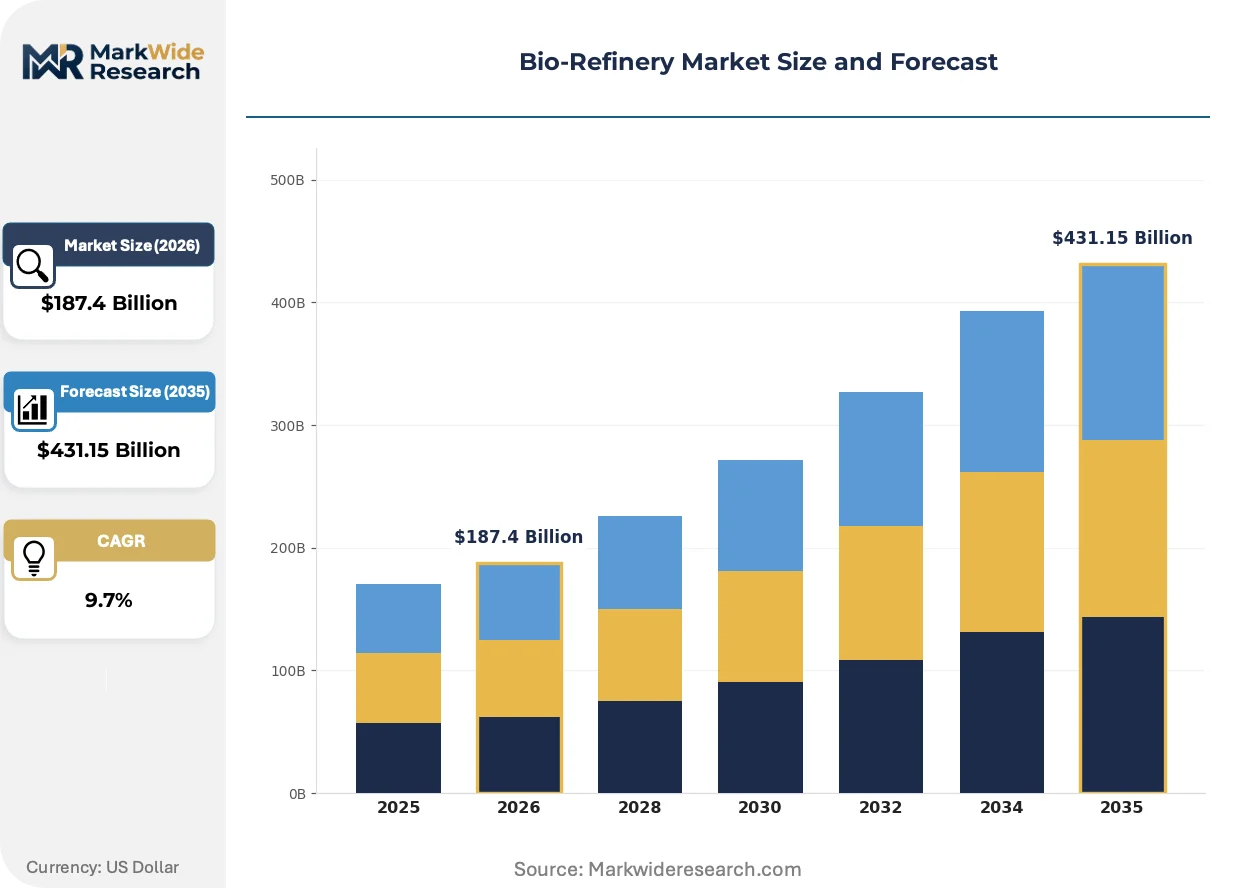
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $431.15 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Wood Biomass, Agricultural Residues, Animal Waste, Energy Crops Technology: Thermochemical, Biochemical, Hybrid, Gasification End User: Transportation, Power Generation, Chemicals, Packaging Product Type: Biofuels, Biochemicals, Biomaterials, Bioenergy |
| Companies Covered | ADM, Neste, Valero, Chevron, TotalEnergies, POET, Green Plains, Cargill, UPM Biofuels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Refinery Market Strategic Shifts
Digital twin technology is compressing commissioning risk for first-of-a-kind bio-refinery designs while regulatory carbon-accounting rules harden product qualification standards across aviation and marine fuel markets.
Advanced process control software is virtualizing reactor performance optimization across thermochemical gasification units. Engineering firms deploying these systems reduce startup duration by 30-40% versus conventional commissioning. Refinery operators in Rotterdam and Singapore are adopting these platforms to manage multi-feedstock switching without offline transitions.
The EU F-Gas Regulation's phase-down schedule for fluorinated greenhouse gases is forcing refrigerant-dependent separation processes toward ammonia and hydrocarbon alternatives. Equipment suppliers are redesigning compression trains and heat exchanger networks to accommodate lower-global-warming-potential working fluids. This retrofit wave concentrates in Nordic and German facilities where enforcement timelines are most aggressive.
Airlines are consolidating renewable fuel procurement through multi-year offtake consortiums rather than spot market exposure. United, Delta, and Lufthansa Group have pooled demand commitments to underwrite dedicated production capacity, shifting risk allocation onto project developers. This buyer concentration is most visible in North American and European aviation hubs where carbon disclosure requirements are binding.
Bio-Refinery Market Segmentation
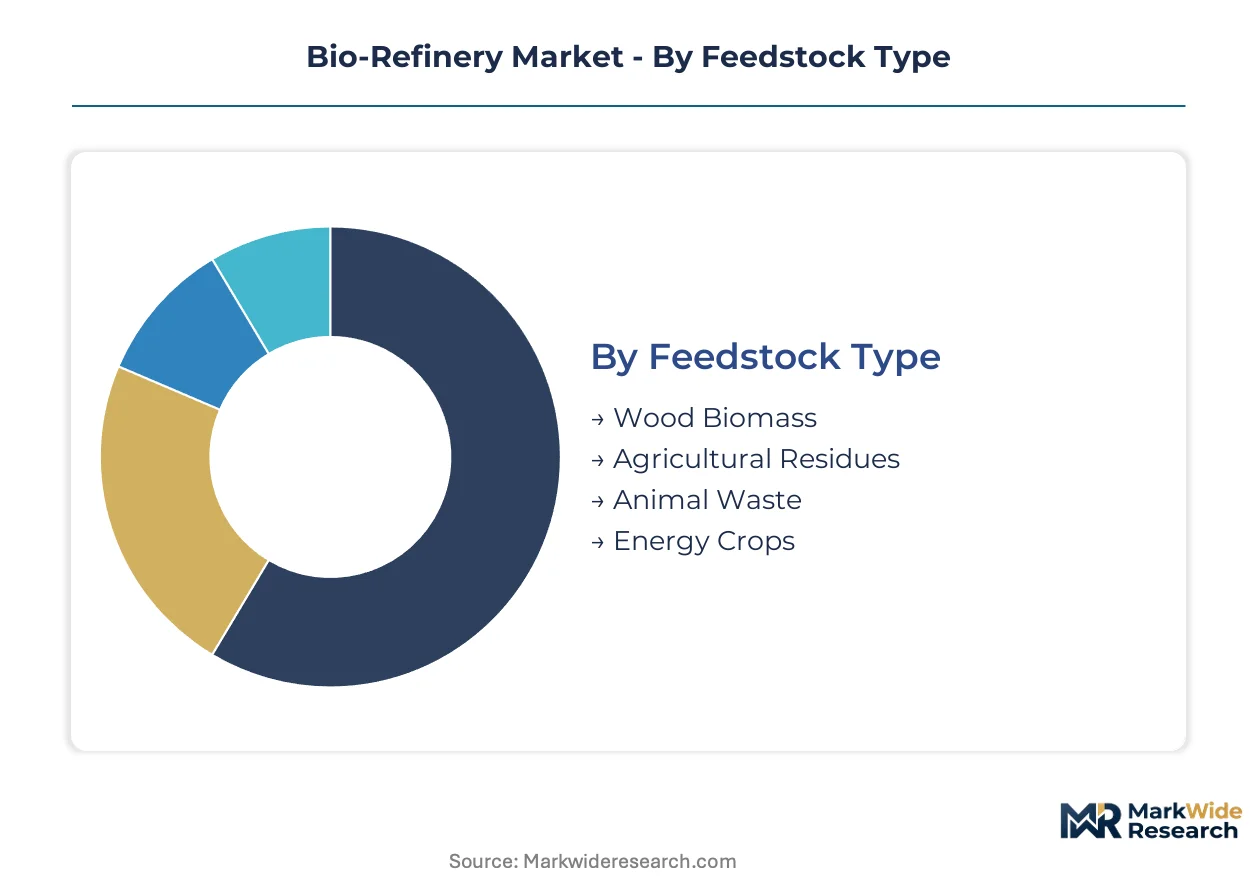
Feedstock heterogeneity and conversion pathway selection determine capital efficiency, carbon intensity scores, and offtake eligibility across bio-refinery configurations. Segment boundaries increasingly blur as facilities pursue multi-product output to hedge input cost volatility and regulatory qualification risk.
Feedstock Type:
The use-case spectrum spans municipal collection systems, dedicated energy plantations, and integrated agricultural processing chains, each imposing distinct traceability and land-use compliance burdens.
- Agricultural Residues:Corn stover, wheat straw, and rice husks supply existing cellulosic ethanol capacity in the U.S. Midwest and Brazilian sugarcane regions. Demand concentrates where collection radius economics align with EPA RFS2 and EU RED III certification requirements, though seasonal availability forces inventory carrying costs.
- Energy Crops:Miscanthus, switchgrass, and short-rotation coppice deliver per-acre yield advantages improving through CRISPR-assisted breeding programs. Plantings are expanding fastest in marginal land zones of Poland and Ukraine where ILUC restrictions are less binding.
- Wood Biomass:Forest residues and sawmill waste feed Nordic combined heat-and-power facilities and Baltic Sea pellet export terminals.
- Animal Waste:Manure and rendering fats supply anaerobic digestion and renewable diesel hydrotreaters with waste-derived methane and tallow feedstocks.
Established volume favors Agricultural Residues; emerging adoption favors Energy Crops.
Technology:
Capital deployment and operating cost tiers separate incumbent thermal platforms from precision fermentation approaches commanding specialty chemical premiums.
- Thermochemical:Pyrolysis and gasification units process heterogeneous feedstocks at 400-700°C with minimal preprocessing. Installed base concentrates in Rotterdam and Singapore where Neste and similar operators exploit multi-feedstock arbitrage across waste oils and residues.
- Biochemical:Enzymatic hydrolysis and fermentation pathways achieve enantiomeric purity for pharmaceutical intermediates. Margin pools in chiral chemical synthesis reward strain engineering precision, with demand clustering at GSK and Sanofi supplier qualification programs.
- Hybrid:Sequential thermochemical pretreatment followed by biological conversion maximizes carbon yield from lignocellulosic fractions.
- Gasification:High-temperature partial oxidation produces syngas for Fischer-Tropsch aviation fuel synthesis.
Capacity additions are climbing the fastest for Thermochemical configurations; margin capture is climbing the fastest for Biochemical platforms.
End User:
Customer procurement scale and carbon disclosure bindingness differentiate aviation consortium demand from dispersed chemical sector purchasing.
- Transportation:Airlines under CORSIA and ICAO frameworks contract 5-10 year renewable fuel offtakes, underwriting hydroprocessed ester production facilities. United, Delta, and Lufthansa Group procurement pools dominate North Atlantic route decarbonization commitments.
- Chemicals:Specialty and commodity chemical producers source bio-based platform molecules to meet Scope 3 reduction targets. BASF and Dow qualification programs drive fermentation capacity expansion for bio-succinic acid and bio-adipic acid.
- Power Generation:Grid operators and industrial cogeneration plants burn biomass pellets and biogas for dispatchable renewable output.
- Packaging:Consumer goods brands specify bio-polyethylene and bio-PET for bottle and film applications.
Contract duration favors Transportation; margin expansion favors Chemicals.
Product Type:
Output category selection locks facilities into fuel-commodity pricing or specialty chemical value capture with divergent feedstock flexibility requirements.
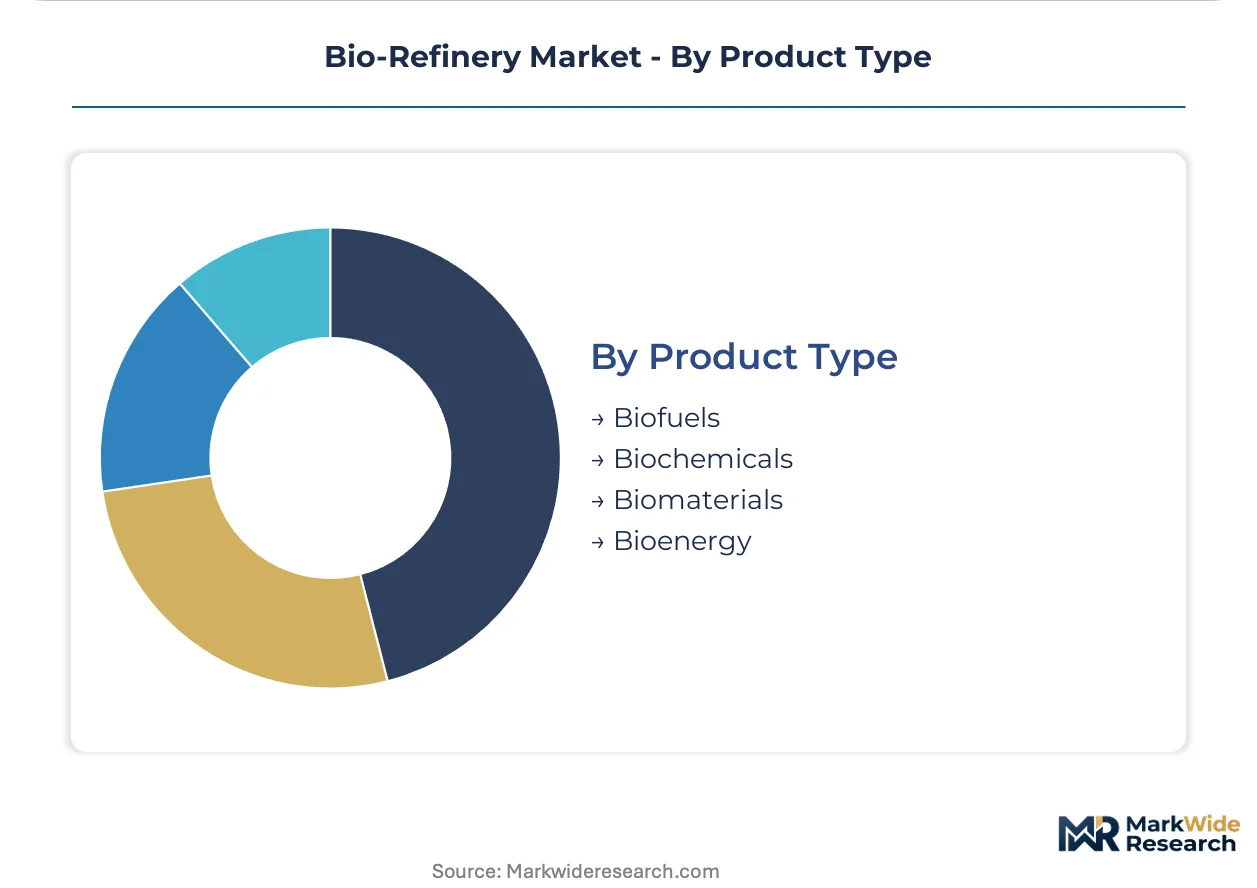
- Biofuels:Renewable diesel, sustainable aviation fuel, and cellulosic ethanol trade against fossil fuel benchmarks with carbon credit overlays. ASTM D7566 and DEF STAN 91-91 certification gates restrict supply to hydrotreatment and Fischer-Tropsch pathways.
- Biochemicals:Organic acids, alcohols, and platform molecules replace petrochemical precursors in polymer and solvent applications. purity grades separate fuel-adjacent outputs from pharmaceutical-grade enantiomers commanding 3-5x equivalent margins.
- Bioenergy:Biogas, biomethane, and solid biomass feed district heating and power generation with lower processing intensity.
- Biomaterials:Bio-based plastics, composites, and carbon fiber precursors target durable goods substitution.
Scale economics favor Biofuels; value capture per ton favors Biochemicals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation and Brazil's ANP biodiesel mandates are redirecting capital toward second-generation bio-refinery pathways. National blending quotas in Indonesia and the U.S. EPA's Renewable Fuel Standard create divergent compliance requirements that shape facility location decisions. Project developers embed traceability systems from inception to secure offtake-linked debt across these jurisdictions.
United States
Midwest corn stover and soybean oil collection networks reduce logistics costs below break-even thresholds for cellulosic ethanol producers. The EPA's Renewable Fuel Standard penalizes fossil carbon intensity and restricts market access to certified low-ILUC feedstocks. Iowa, Illinois, and Nebraska host the densest concentration of agricultural residue intake infrastructure.
Brazil
Sugarcane bagasse and second-generation ethanol expansion attract refinery retrofit capital under ANP biodiesel blending mandates. The country's national biofuel regulator enforces rising blend floors that pull investment into thermochemical platforms. São Paulo state anchors the largest integrated sugarcane-to-ethanol processing corridor.
Germany
Industrial demand for bio-based platform molecules concentrates in the Rhine-Ruhr and Bavarian chemical corridors under EU Green Deal Fit for 55 transport fuel targets. The EU F-Gas Regulation's phase-down schedule forces refrigerant-dependent separation processes toward ammonia alternatives. Hamburg and Rotterdam-connected facilities exploit multi-feedstock arbitrage across waste oils.
Indonesia
The B40 blending mandate trajectory creates import demand for waste oil and residue-based methyl esters. The country's national energy regulator enforces palm oil diversion quotas that open arbitrage for Southeast Asian collection infrastructure. Java and Sumatra host expanding hydrotreatment capacity serving domestic diesel substitution.
Singapore
Marine and aviation fuel bunkering demand pulls renewable diesel and sustainable aviation fuel production into Jurong Island refining complexes. The Maritime and Port Authority's carbon intensity disclosure requirements bind marine fuel suppliers to certified low-carbon pathways. Neste and similar operators leverage multi-feedstock flexibility across waste oils and residues.
Bio-Refinery Market Competitive Environment
Channel-controlling players compete with product-specialist players for procurement access and offtake contract security. Consolidation concentrates around agricultural processors with captive origination networks and petroleum refiners with hydrotreatment infrastructure. Three archetypes dominate: farm-gate integrators controlling input cost volatility, multi-feedstock refiners exploiting geographic arbitrage, and specialty chemical fermenters capturing pharmaceutical-grade purity premiums. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure utility-backed project finance.
Among North American agricultural processors, ADM and POET exemplify the farm-gate integrator archetype through origination network extension. Neste anchors the multi-feedstock refiner position with Singapore and Rotterdam complex operations. Valero represents petroleum refiner participation through captive ethanol logistics and pipeline-connected distribution infrastructure.
| Leading Market Players |
|---|
| ADM |
| Neste |
| Valero |
| Chevron |
| TotalEnergies |
| POET |
| Green Plains |
| Cargill |
| UPM Biofuels |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European hydrotreatment capacity is pulling waste oil premiums upward while forcing buyers into longer-term offtake commitments. This utilization squeeze rewards suppliers with certified low-ILUC inventory and pressures biochemical platform operators toward spot market exposure.
Pricing Analysis
Certification level under EU RED III and EPA RFS2 creates the primary spread between fuel-grade and pharmaceutical-grade outputs. Contract-based long-term offtake dominates transportation fuel procurement, with aviation consortiums locking in five-to-ten-year supply agreements. Price differentiation rests on carbon intensity scores and traceability system maturity, with low-ILUC certified feedstocks commanding substantial premiums. Cost compression in first-generation ethanol is intensifying because corn and soybean futures volatility erodes margin predictability for operators lacking origination control. Chemical sector buyers show least price sensitivity, accepting 3-5x fuel-equivalent margins for enantiomeric purity, while independent fuel blenders face acute margin pressure.
Supply Chain Analysis
Export control regimes on pyrolysis reactor technology and enzymatic catalyst IP limit equipment flows into certain jurisdictions, concentrating advanced platform deployment among licensed technology holders. Geographic supply concentrates in the United States, Brazil, and Indonesia, where agricultural residue collection networks and palm oil processing infrastructure anchor feedstock intake. Raw material dependencies center on corn stover, waste cooking oils, and sugarcane bagasse, with equipment sourcing tethered to German and Nordic engineering suppliers. Single-source vulnerability runs through specialized fermentation strain licensors and hydrotreatment catalyst providers. Distribution runs through pipeline-connected terminals and marine bunkering hubs rather than dispersed trucking networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bio-refinery market reads as a service-attach opportunity where feedstock traceability-as-a-service and carbon accounting subscriptions expand faster than processing hardware sales. Recurring revenue from certification compliance monitoring and blockchain-enabled provenance tracking outpaces capital equipment margins.
For Market Incumbents: Build captive origination networks as the defensive moat against margin volatility. ADM and POET exemplify this through farm-gate control extending from Iowa collection points to biorefinery intake. Secure utility-backed project finance partnerships to defend access to offtake-linked debt structures. Invest in multi-feedstock flexibility at Rotterdam and Singapore complexes to arbitrage waste oil price swings across jurisdictions. For New Entrants and Emerging Players: Establish a beachhead in specialty biochemical fermentation where pharmaceutical-grade purity commands premium pricing unavailable to fuel commodity producers. Target the Rhine-Ruhr and Bavarian chemical corridors where BASF and Dow supplier qualification programs create structured demand for bio-succinic acid and bio-adipic acid. Pursue precision strain engineering partnerships with research universities as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across thermochemical gasification as digital twin technology compresses commissioning risk and startup duration. Long-term viability over the next decade favors agricultural processors with backward integration into feedstock origination rather than pure-play technology licensors. Watch for feedstock certification fragmentation between EU RED III and U.S. EPA RFS2 as the signal indicating asset stranding risk in non-compliant sourcing regions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Origination | ADM's farm-gate network extension controls input cost volatility across Iowa and Illinois collection zones. |
| Multi-Feedstock Refinery Retrofit | Neste's Singapore and Rotterdam complexes arbitrage waste oil price swings under EU F-Gas Regulation compliance. |
| Long-Term Aviation Offtake Consortium | United, Delta, and Lufthansa pooled demand commitments underwrite dedicated hydroprocessed ester production capacity. |
| Specialty Chemical Fermentation Scale-Up | GSK and Sanofi supplier qualification programs reward precision strain engineering with 3-5x fuel-equivalent margins. |
| Pipeline-Connected Distribution Partnership | Valero's captive ethanol logistics eliminate trucking costs and unlock military and marine fuel offtake channels. |
Study Parameters
Desk research of EU regulatory filings, EPA RFS2 compliance databases, and ANP biodiesel mandate records preceded structured interviews with bio-refinery project developers, agricultural procurement directors, and aviation fuel sustainability officers. Primary fieldwork with thermochemical platform operators and biochemical fermentation specialists combined with secondary validation against customs trade data and SEC 10-K filings from agricultural processors. Bottom-up capacity installation tracking and top-down demand modeling from transport fuel mandates were triangulated to cross-verify volume estimates.
Assumptions held fixed include current EU F-Gas Regulation phase-down schedules and Indonesia's B40 blending mandate trajectory, while feedstock cost volatility and certification fragmentation scenarios were varied across sensitivity runs. Segmentation dimensions modeled span feedstock type, conversion technology, end-use sector, and product category, with carbon intensity scoring and traceability system maturity as industry-specific overlay variables. CAGRs were derived from installed capacity buildout pipelines and offtake contract visibility rather than extrapolation of historical trends. Forecast inputs incorporated aviation sector decarbonization commitments under CORSIA and ICAO frameworks alongside marine fuel carbon intensity disclosure requirements.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity futures, energy prices, or capital cost regimes would shift the trajectory of project finance viability and capacity expansion timing. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and low-ILUC feedstock availability. Material shifts in EU-U.S. certification alignment or breakthroughs in energy crop yield genetics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Global Specialty Enzymes Market
Industrial Biotechnology
North America Biocatalysts Market
Industrial Biotechnology
GCC Biocatalyst Market
Industrial Biotechnology
Europe Biocatalyst Market
Industrial Biotechnology
Industrial Enzymes Market
Industrial Biotechnology
Haematococcus Pluvialis Market
Industrial Biotechnology
Japan Biocatalyst Market
Industrial Biotechnology
Global Enzymes Market
Industrial Biotechnology
White Biotechnology Market
Industrial Biotechnology
White Biotech Market
Industrial Biotechnology
Protease Market
Industrial Biotechnology
Fungal Amylase Market
Industrial Biotechnology
Xylanase Market
Industrial Biotechnology
Glucoamylase Market
Industrial Biotechnology
Global Protein Hydrolysis Enzymes Market
Industrial Biotechnology
Global Carbohydrase Market