
 Phospholipase Enzyme Market | 2026-2036
Phospholipase Enzyme Market Size, Share, and Industry Trends Forecast 2026-2036
Phospholipase Enzyme Market Outlook
Cell-free enzyme engineering is fragmenting traditional fermentation-based production architectures for phospholipase enzymes. Novozymes A/S leverages its microbial strain libraries to dominate recombinant PLA2 supply chains. BASF SE anchors European pharmaceutical-grade phospholipase capacity through dedicated biotech manufacturing assets. Amano Enzyme Inc. specializes in thermostable variants for high-temperature food processing applications in East Asian markets.
Phospholipase enzymes catalyze the hydrolysis of phospholipid ester bonds, with PLA2 variants cleaving the sn-2 acyl position to yield lysophospholipids and free fatty acids for industrial emulsification and lipid modification. These biocatalysts operate across pH ranges of 4.0 to 9.0 and temperature optima between 35°C and 60°C, enabling deployment in dairy processing, pharmaceutical lipid nanoparticle formulation, and nutraceutical phosphatidylserine production. The PLA2 product category captures the largest volume share due to its established role in cheese manufacturing and egg yolk modification, while recombinant-source enzymes represent the fastest-expanding supply channel as microbial expression systems displace animal-derived extracts in kosher and halal-certified applications. Pharmaceutical and nutraceutical end users command premium pricing tiers owing to stringent purity requirements for parenteral lipid formulations and cognitive health supplements.
FDA enzyme preparation regulations and EFSA food additive safety evaluations govern phospholipase approval pathways in North America and Europe, with India's FSSAI and China's SAMR imposing additional localization requirements for imported biocatalysts. The EU Green Deal's bio-based manufacturing targets and REACH chemical registration obligations are redirecting procurement toward microbial and recombinant enzyme sources with traceable supply chains. Stakeholders must monitor evolving novel food enzyme authorization timelines across multiple jurisdictions to anticipate competitive positioning shifts.
Market Dynamics
Cell-free enzyme engineering is fragmenting traditional fermentation-based production architectures, forcing suppliers to rebuild manufacturing footprints around recombinant expression systems rather than animal-derived extraction.
Growth Catalysts
- Clean-label emulsification mandates:Food processors across Asia-Pacific are reformulating products to eliminate synthetic emulsifiers, creating pull for phospholipase-modified lecithin in bakery and dairy applications.
- EFSA novel food enzyme authorizations:Streamlined approval pathways for microbial-source phospholipases are accelerating commercial deployment in European cheese manufacturing and egg processing.
- High-temperature food processing:Thermostable phospholipase variants enable continuous processing lines in East Asian noodle and oil refining operations where conventional enzymes denature.
Market Restraints
- Recombinant enzyme capex intensity:Building GMP-compliant microbial fermentation capacity requires substantial upfront investment, limiting new entrants to contract manufacturing arrangements.
- Animal-derived extract dependency:Pancreatic phospholipase supply chains remain concentrated in specific geographies with kosher and halal certification constraints creating sourcing friction.
- Cross-contamination detection limits:Current analytical methods struggle to distinguish trace animal-derived phospholipase from microbial equivalents in finished food matrices.
Strategic Opportunities
- India's pharmaceutical enzyme sector:Contract research and manufacturing organizations in Hyderabad and Bangalore are building dedicated phospholipase capacity for lipid nanoparticle drug delivery systems.
- EU Green Deal bio-based targets:Mandatory substitution quotas for petroleum-derived surfactants in industrial cleaning applications are opening phospholipase-biosurfactant hybrid formulations.
- Direct-to-bakery enzyme distribution:Bypassing traditional ingredient distributors, enzyme suppliers are building technical service teams to embed formulation expertise directly with mid-size bakery chains.
Industry Challenges
- Protein engineering talent scarcity:Rational design of phospholipase variants with altered substrate specificity requires computational biologists and enzymologists that compete with broader biotech salary benchmarks.
- Multi-jurisdiction dossier compilation:Securing FDA, EFSA, and China's SAMR approvals simultaneously demands divergent toxicology and stability data packages that extend time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phospholipase Enzyme Market |
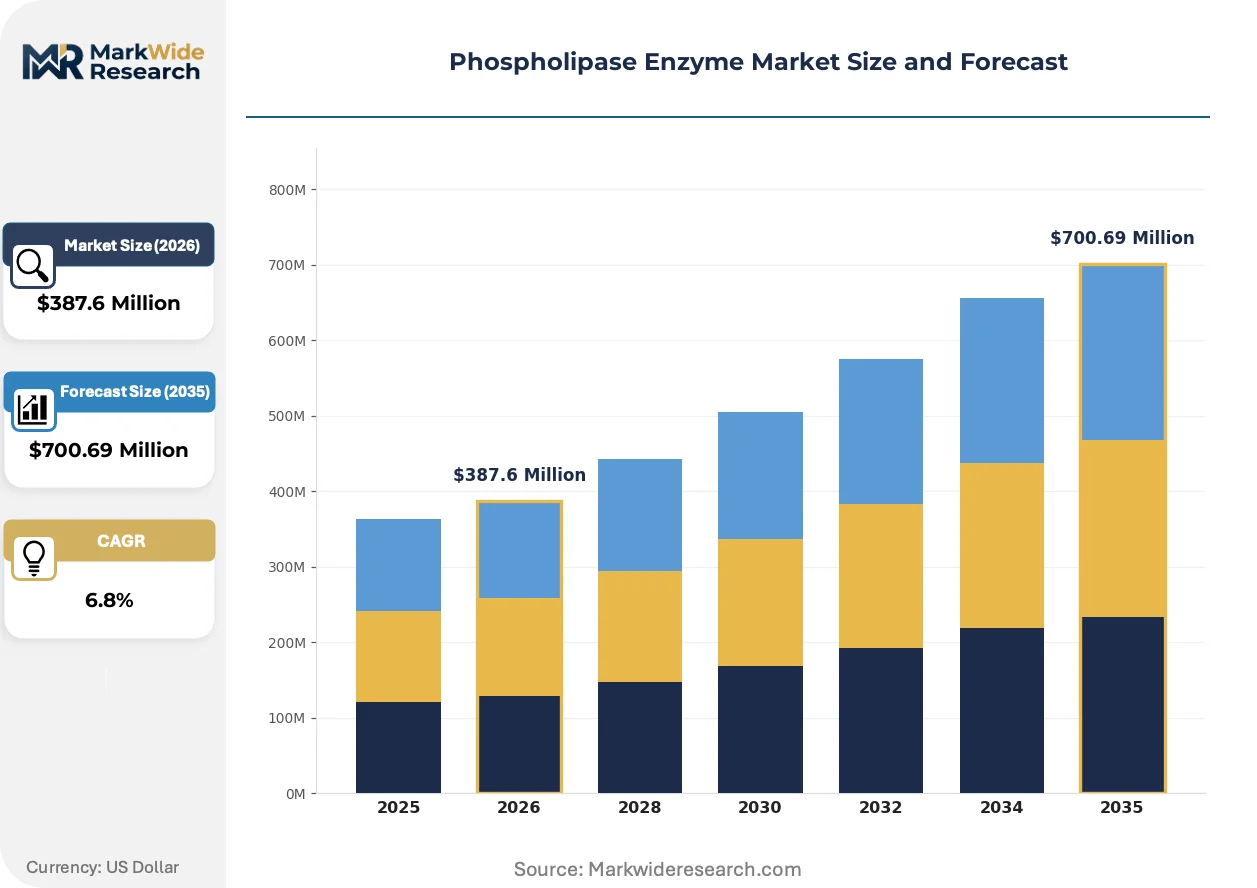
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA2, PLC, PLD, LPA Application: Food Industry, Pharmaceutical, Nutraceutical, Cosmetics Source: Animal, Plant, Microbial, Recombinant End User: Food Manufacturers, Drug Developers, Cosmetic Brands, Research Institutions |
| Companies Covered | Novozymes A/S, DuPont de Nemours, Inc., BASF SE, DSM N.V., Kerry Group, Cargill, Incorporated, Archer Daniels Midland Company, Evonik Industries, Amano Enzyme Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phospholipase Enzyme Market Strategic Shifts
Enzyme engineering platforms are compressing development cycles for phospholipase variants, while regulatory frameworks and procurement models co-evolve around traceable, non-animal supply chains.
Directed evolution combined with machine learning is hybridizing phospholipase development pipelines, enabling rapid screening of variant libraries for pH and temperature optima. Pharmaceutical formulators are adopting these engineered enzymes for lipid nanoparticle production at accelerated qualification timelines. The technology is hybridizing what were separate food-grade and pharma-grade supply chains into unified microbial production platforms.
REACH chemical registration obligations and the EU Green Deal's bio-based manufacturing targets are redirecting procurement toward microbial phospholipase sources with full supply chain traceability. Industrial users must now document carbon intensity and biodegradability credentials alongside enzyme activity specifications. European dairy processors are responding by locking in long-term offtake agreements with recombinant enzyme suppliers who have secured EFSA novel food approvals.
Buyer concentration among multinational food manufacturers is compressing supplier qualification timelines and unbundling technical service from base enzyme supply contracts. Mid-size regional dairies and specialty oil processors are losing access to dedicated application support as vendor resources concentrate on top-tier accounts. This pattern is most visible in China's processed food corridor, where local enzyme distributors are acquiring formulation expertise to fill the service gap left by global suppliers.
Phospholipase Enzyme Market Segmentation
Phospholipase enzyme procurement patterns diverge sharply across product chemistry and certification requirements. End-use specifications determine whether buyers prioritize thermal stability, kosher compliance, or GMP-grade purity.
Product Type:
Mature industrial enzymes dominate commercial volumes, while engineered variants capture premium positioning.
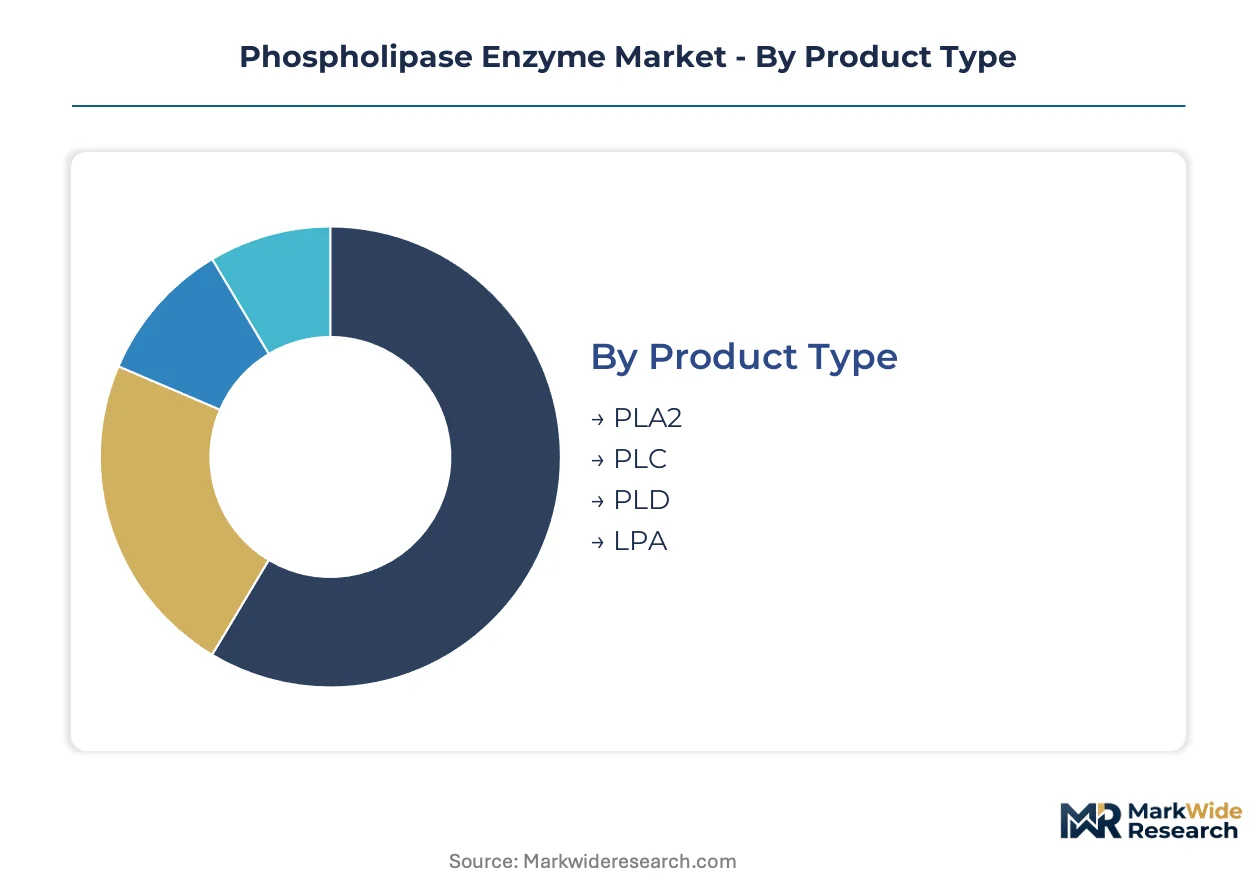
- PLA2:Cleaves the sn-2 acyl position of phospholipids to yield lysophospholipids and free fatty acids. Cheese manufacturers in Italy and Wisconsin concentrate demand here for emulsification control and flavor development.
- PLC:Hydrolyzes the phosphodiester bond at the sn-3 position, releasing diacylglycerol and phosphate head groups. Pharmaceutical lipid nanoparticle formulators in Massachusetts and Basel drive specialized procurement for mRNA delivery systems.
- PLD:Catalyzes phospholipid hydrolysis and transphosphatidylation reactions. Asian oil refiners deploy PLD for degumming operations in high-temperature processing environments.
- LPA:Lysophosphatidic acid-specific enzymes with narrower substrate scope. Research institutions constitute the primary demand channel for specialized biochemical assays.
PLA2 handles the majority of throughput; PLC is the fastest mover on share.
Application:
Cost tiers separate commodity food processing from regulated pharmaceutical manufacturing.
- Food Industry:Dairy, bakery, and oil processing operations employ phospholipases for clean-label emulsification. China's processed food corridor and India's bakery chains are expanding microbial-source enzyme procurement under evolving safety frameworks.
- Pharmaceutical:Parenteral lipid formulations and lipid nanoparticle drug delivery demand GMP-grade phospholipases with documented endotoxin limits. Hyderabad and Bangalore contract manufacturers are building dedicated capacity for this segment.
- Nutraceutical:Phosphatidylserine extraction and cognitive health supplements require food-grade or pharma-grade certification depending on jurisdiction. Japanese and South Korean buyers lead premium positioning here.
- Cosmetics:Skin conditioning and emulsification applications in personal care formulations. European cosmetic brands prioritize REACH-registered microbial sources with full supply chain traceability.
Food Industry absorbs the largest volume base; Pharmaceutical applications are climbing the fastest on margin contribution.
Source:
Supply concentration shifts from animal extraction facilities toward recombinant fermentation capacity.
- Animal:Pancreatic extracts historically supplied industrial phospholipase volumes. Kosher and halal certification constraints now limit deployment in Middle Eastern and Southeast Asian markets.
- Plant:Oilseed-derived enzymes with moderate activity profiles. Specialty oil processors in Brazil and Argentina trial plant-source alternatives for organic-certified product lines.
- Microbial:Fungal and bacterial fermentation yields thermostable variants suited to continuous processing. East Asian noodle manufacturers and European dairy processors drive procurement expansion.
- Recombinant:Engineered microbial expression systems deliver consistent activity and full traceability. EFSA novel food enzyme approvals and FDA enzyme preparation regulations favor this channel for cross-regional supply security.
Microbial sources command the dominant procurement share; Recombinant enzymes are expanding most quickly on authorization breadth.
End User:
Customer type determines technical service intensity and contract structure.
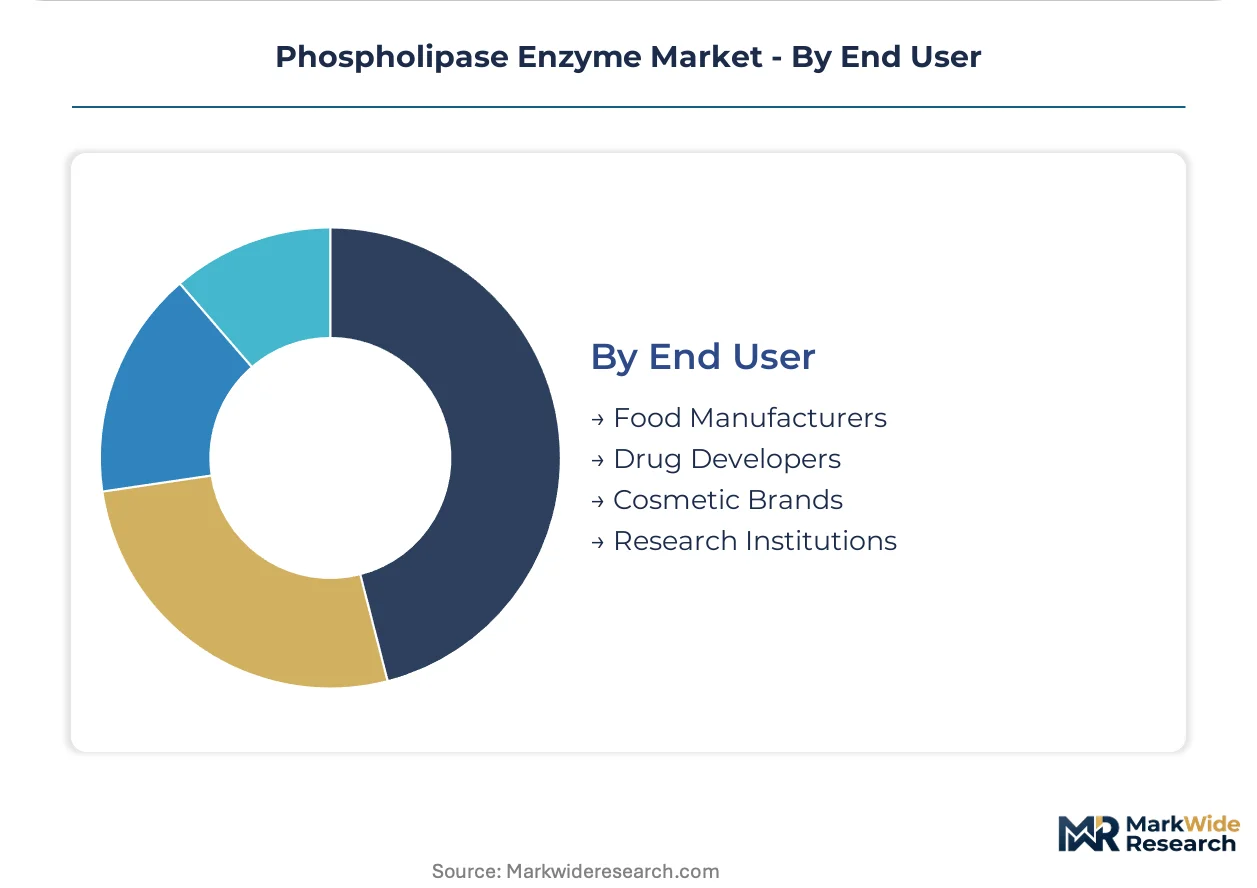
- Food Manufacturers:Multinational dairy and bakery processors negotiate multi-year offtake agreements with embedded formulation support. Mid-size regional operators face service gaps as vendor resources concentrate on top-tier accounts.
- Drug Developers:Biopharma companies sourcing phospholipases for lipid nanoparticle production require GMP documentation and regulatory submission support. CDMO partnerships in India and Switzerland anchor this demand.
- Cosmetic Brands:Personal care formulators prioritize REACH compliance and biodegradability credentials. European procurement teams lead specification tightening here.
- Research Institutions:Academic and government laboratories purchase small-volume, high-specificity enzyme preparations for assay development and mechanistic studies.
Food Manufacturers represent the largest installed base; Drug Developers are gaining share fastest on per-unit pricing premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese phospholipase exports flow primarily to Southeast Asian food processors and European pharmaceutical compounders, establishing the Yangtze River Delta as the dominant supply corridor for microbial-source enzymes.
China
Processed food manufacturers in Jiangsu and Zhejiang provinces drive phospholipase procurement for clean-label emulsification in dairy and bakery applications. SAMR's evolving food enzyme safety frameworks require localization documentation for imported biocatalysts. The Shanghai-Suzhou corridor concentrates recombinant enzyme fermentation capacity serving both domestic dairy processors and export markets.
United States
Wisconsin cheese manufacturers and Massachusetts lipid nanoparticle formulators generate divergent demand for PLA2 and PLC variants respectively. FDA enzyme preparation regulations govern approval pathways for microbial-source phospholipases in food and pharmaceutical applications. The Midwest dairy belt and Greater Boston biotech cluster operate as distinct procurement zones with separate certification requirements.
Germany
European dairy processors and industrial cleaning compounders source phospholipases under REACH registration obligations and EU Green Deal bio-based manufacturing targets. EFSA novel food enzyme authorizations accelerate commercial deployment in cheese manufacturing. The Rhine-Ruhr industrial region anchors pharmaceutical-grade phospholipase capacity through dedicated biotech manufacturing assets.
India
Hyderabad and Bangalore contract research organizations build dedicated phospholipase capacity for lipid nanoparticle drug delivery systems serving global biopharma clients. FSSAI imposes additional localization requirements for imported biocatalysts beyond international standards. The Deccan Plateau pharmaceutical corridor represents the fastest-expanding demand node for GMP-grade enzyme supply.
Japan
Nutraceutical manufacturers in Osaka and Nagoya procure phospholipases for phosphatidylserine extraction and cognitive health supplement formulations. METI standards and PMDA pharmaceutical regulations create dual-track certification requirements for food-grade and pharma-grade enzymes. The Kansai industrial region leads premium positioning for high-purity phospholipase applications.
Phospholipase Enzyme Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base organizes around multinational enzyme houses with microbial strain libraries, diversified chemical conglomerates with biotech manufacturing assets, and regional specialists in thermostable or high-purity variants. Three archetypes dominate: recombinant fermentation specialists, integrated nutrition ingredient suppliers, and contract manufacturing organizations. Competitive moves concentrate on capacity expansion in GMP-compliant microbial fermentation and strategic partnerships for novel food enzyme authorization dossiers.
Among Danish and German enzyme houses, Novozymes A/S and BASF SE occupy positions spanning recombinant PLA2 supply chains and pharmaceutical-grade manufacturing infrastructure. Japanese specialists including Amano Enzyme Inc. exemplify the thermostable variant segment serving high-temperature food processing applications. These entities represent distinct competitive vectors rather than overlapping market contests, with each anchoring different certification and application requirements.
| Leading Market Players |
|---|
| Novozymes A/S |
| DuPont de Nemours, Inc. |
| BASF SE |
| DSM N.V. |
| Kerry Group |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Evonik Industries |
| Amano Enzyme Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in GMP-compliant microbial fermentation across the Deccan Plateau and Yangtze River Delta is compressing supplier margins while amplifying pricing power for EFSA-authorized producers. This utilization squeeze forces buyers into longer offtake commitments and accelerates the shift from spot procurement to contract-based supply security.
Pricing Analysis
Next-generation recombinant phospholipases command substantial premiums over animal-derived extracts and first-generation microbial variants, with price differentiation driven by EFSA novel food authorization status and kosher-halal certification tier. Three-tier pricing structure across premium, standard, and economy levels separates GMP-grade pharmaceutical enzymes from food-grade microbial sources and commodity animal extracts. Cost compression in standard-tier food-grade supply is intensifying because Chinese and Indian manufacturers are expanding microbial fermentation capacity. Mid-size regional dairies exhibit highest price sensitivity, while Massachusetts lipid nanoparticle formulators show lowest elasticity due to regulatory submission dependencies.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for phospholipase procurement, with SAMR localization mandates and FDA enzyme preparation regulations creating divergent compliance pathways. Manufacturing concentrates in China, India, and Germany, with the Yangtze River Delta, Deccan Plateau, and Rhine-Ruhr region anchoring distinct production ecologies. Raw material flows draw from corn-derived fermentation feedstocks, specialized microbial strain libraries, and pharmaceutical-grade buffer chemicals. Single-source vulnerability persists in thermostable variant supply where Amano Enzyme Inc. maintains technical leadership. Distribution runs through enzyme houses with embedded technical service teams rather than traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phospholipase incumbents face substitution pressure from synthetic emulsifier reformulations and plant-source lecithin alternatives that threaten to displace enzyme-modified phospholipids in clean-label applications.
For Market Incumbents: Harden regulatory moats by accelerating EFSA and SAMR dossier submissions for next-generation variants before patent cliffs erode recombinant enzyme exclusivity. Deepen backward integration into microbial strain libraries to reduce dependency on external fermentation partners. Lock in multi-year offtake agreements with top-tier food manufacturers to preempt contract manufacturing organization encroachment. For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical enzyme sector where GMP-grade capacity scarcity creates procurement gaps for lipid nanoparticle formulators. Target mid-size European dairy processors abandoned by global suppliers consolidating technical service resources on multinational accounts. Lead with direct-to-bakery distribution models that embed formulation expertise and bypass traditional ingredient distributor markups. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across recombinant fermentation capacity as GMP compliance costs and protein engineering talent premiums compound. Long-term viability favors platforms with dual food-pharma certification and captive strain development capabilities. Watch for EFSA authorization timeline acceleration as the signal indicating regulatory arbitrage windows are closing.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Submission | Accelerates commercial deployment in European cheese manufacturing under streamlined approval pathways. |
| GMP Fermentation Capacity Expansion | Captures pharmaceutical-grade phospholipase demand from Massachusetts and Basel lipid nanoparticle formulators. |
| Direct-to-Bakery Technical Service Buildout | Bypasses ingredient distributors to embed formulation expertise with mid-size bakery chains directly. |
| Microbial Strain Library Acquisition | Secures recombinant PLA2 supply chain control and reduces dependency on external fermentation partners. |
| Long-Term Offtake Agreement Structuring | Locks in volume commitments from multinational food manufacturers facing supplier qualification compression. |
Study Parameters
Initial hypotheses were tested against primary input from enzyme procurement managers at multinational food manufacturers, regulatory affairs leads at fermentation houses, pharmaceutical formulators in lipid nanoparticle development, and technical directors at dairy processing cooperatives and refined through secondary validation. FDA enzyme preparation regulations, EFSA novel food enzyme authorization databases, SAMR food safety framework updates, and customs trade data on biocatalyst imports anchored the evidentiary base. Bottom-up capacity assessments across the Yangtze River Delta and Deccan Plateau triangulated against top-down demand modeling from cheese manufacturing and pharmaceutical formulation sectors.
Demand-supply balance dynamics across recombinant fermentation capacity, animal-derived extract availability, and thermostable variant production shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled include phospholipase chemistry type, application vertical, source certification tier, and regional regulatory cluster. CAGRs derived from capacity expansion timelines, authorization pathway velocities, and substitution elasticity estimates for synthetic emulsifiers. Forecast inputs incorporated EFSA dossier approval trajectories and SAMR localization mandate implementation patterns.
Sensitivities concentrate around EFSA authorization timeline delays, SAMR enforcement intensity on imported biocatalysts, and breakthrough advances in plant-source phospholipase activity profiles. Forecasts reflect assumptions on regulatory pathway efficiency and capacity utilization trajectories that could shift with macroeconomic or technological developments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Biocatalysis and Biocatalysts Market
Industrial Biotechnology
Global Enzymes Market
Industrial Biotechnology
White Biotechnology Market
Industrial Biotechnology
Protease Enzyme Market
Industrial Biotechnology
Marine Enzymes Market
Industrial Biotechnology
Pyruvate Synthase Market
Industrial Biotechnology
Americas Enzymes Market
Industrial Biotechnology
Beta-Glucanase Market
Industrial Biotechnology
Fungal Amylase Market
Industrial Biotechnology
North America Biocatalysts Market
Industrial Biotechnology
United States Biocatalyst Market
Industrial Biotechnology
Global Specialty Enzymes Market
Industrial Biotechnology
Biocatalyst Market
Industrial Biotechnology
Hydrolase Enzymes Market
Industrial Biotechnology
Protease Market
Industrial Biotechnology
Cellulose Enzyme Market