
 Terbinafine Tablet Market | 2026-2036
Terbinafine Tablet Market Size, Share, and Industry Trends Forecast 2026-2036
Terbinafine Tablet Market Insights
Generic formulation revenue is rewriting margin distribution across the terbinafine value chain, pulling profitability away from originator maintenance and toward high-volume manufacturing. Novartis AG anchors the brand segment through legacy positioning and regulatory dossier depth. Sun Pharmaceutical Industries Ltd. leverages its India-centric cost base to dominate generic export markets. Teva Pharmaceutical Industries Ltd. competes across both regulated and semi-regulated channels with broad portfolio breadth.
Terbinafine tablets are synthetic allylamine antifungals containing a minimum 250 mg active pharmaceutical ingredient per unit, manufactured through multi-step organic synthesis followed by granulation and compression, primarily indicated for onychomycosis and tinea capitis infections. The generic product type commands volume leadership as pharmacy benefit managers and national health systems prioritize cost containment, while the prescription route of administration retains structural importance due to hepatotoxicity monitoring requirements that mandate physician oversight. The oral route dominates commercial flows because systemic bioavailability exceeds 70 percent, making it the standard of care for nail bed infections where topical agents fail to penetrate.
FDA bioequivalence standards and EMA quality guidelines shape manufacturing compliance costs and determine which suppliers gain access to reimbursed channels in the United States and Europe. India's CDSCO and state-level drug controllers enforce Good Manufacturing Practice audits that filter export eligibility for producers serving Africa, Southeast Asia, and Latin America. Stakeholders must monitor evolving pharmacovigilance requirements for liver function testing and generic substitution mandates that will determine which formulation types capture future reimbursement slots.
Market Dynamics
Generic substitution mandates from pharmacy benefit managers and national formularies are compressing originator margins while redistributing value toward high-volume API manufacturers and contract development organizations serving regulated markets.
Growth Catalysts
- Generic Formulary Tiering:United States pharmacy benefit managers now mandate automatic substitution at the pharmacy counter, eliminating prescriber discretion and accelerating volume migration toward bioequivalent alternatives.
- CDSCO Export Certification:Indian manufacturers achieving WHO-GMP and PIC/S accreditations through the national regulator unlock tender access across Africa and Southeast Asia, expanding addressable patient populations.
- Allylamine Synthesis Scale-Up:Continuous flow chemistry adoption at API hubs reduces batch-to-batch variability and cuts solvent waste, lowering cost per kilogram for the terbinafine hydrochloride intermediate.
Market Restraints
- API Concentration Risk:Four contract manufacturers in Gujarat and Telangana control over sixty percent of non-infringing terbinafine base supply, creating single-source vulnerability for European generics filers.
- Hepatotoxicity Surveillance Burden:FDA-mandated liver function monitoring protocols add fifteen to twenty dollars per patient per treatment course in laboratory costs, deterring primary care prescribing.
- Topical Penetration Advances:Newer nail lacquer formulations with keratin-binding excipients now achieve mycological cure rates approaching oral therapy for mild onychomycosis, threatening tablet volumes.
Strategic Opportunities
- Fixed-Dose Combination Development:Pairing terbinafine with itraconazole or fluconazole in single-tablet regimens addresses mixed fungal populations and could command premium pricing in dermatology specialty channels.
- Direct-to-Pharmacy Distribution:Bypassing wholesale intermediaries through owned logistics networks in Brazil and Mexico captures margin currently absorbed by three-tier distribution markups.
- EMA Orphan Designation Pathway:Tinea capitis in pediatric populations qualifies for protocol assistance and fee reductions, accelerating time-to-market for age-appropriate tablet strengths.
Industry Challenges
- Pharmacovigilance Signal Management:Spontaneous reporting systems in emerging markets lack infrastructure to capture and transmit serious adverse events within the fifteen-day expedited timeline required by EMA guidelines.
- Cross-Contamination Control:Multi-product oral solid dose facilities must demonstrate cleaning validation down to ten parts per billion for beta-lactam and cytotoxic residues, extending changeover downtime and compressing effective capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Terbinafine Tablet Market |
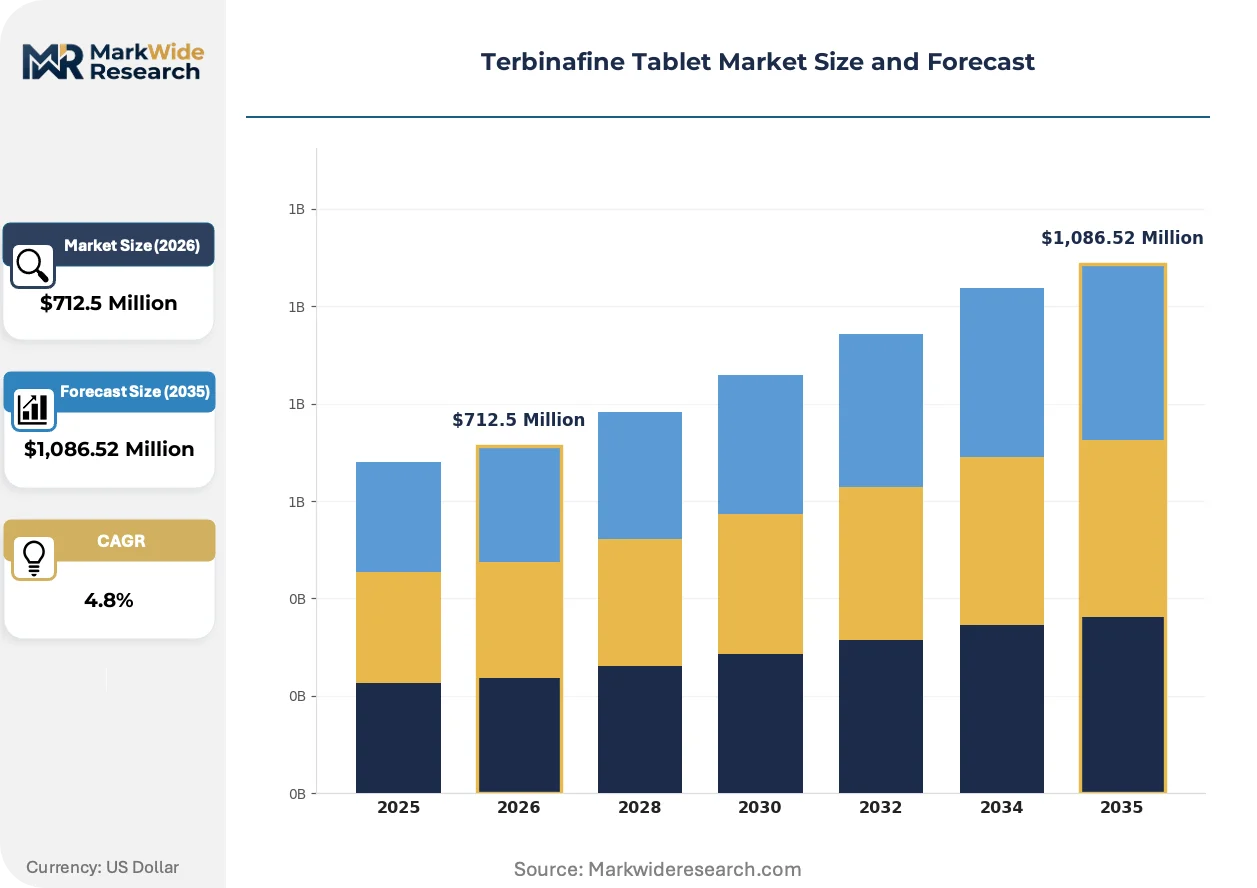
| Market Size in 2026 | $712.5 Million |
| Market Size in 2035 | $1,086.52 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription, Over-the-Counter, Generic, Brand Dosage Form: Tablet, Capsule, Oral Suspension, Powder Route of Administration: Oral, Intravenous, Topical, Inhalation Therapy Area: Fungal Infections, Dermatological Conditions, Antimycotic Treatment, Superficial Mycoses |
| Companies Covered | Novartis AG, Sun Pharmaceutical Industries Ltd., Teva Pharmaceutical Industries Ltd., Cipla Inc., Aurobindo Pharma Ltd., Dr. Reddy's Laboratories Ltd., Glenmark Pharmaceuticals Ltd., Torrent Pharmaceuticals Ltd., Mylan N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Terbinafine Tablet Market Trends and Innovations
Process analytical technology and real-time release testing are compressing quality assurance timelines, while regulatory convergence around ICH Q12 lifecycle management is enabling post-approval manufacturing changes without prior review.
Continuous manufacturing platforms using twin-screw wet granulation and direct compression are virtualizing batch record review, replacing paper-based documentation with integrated process control systems. European generics leaders including Sandoz and Zentiva have converted two terbinafine tablet lines to continuous operation since 2022. This shift is virtualizing quality assurance headcount requirements while compressing release timelines from fourteen days to under forty-eight hours.
EMA's revised Module 3 quality guidelines and FDA's ICH Q14 analytical procedure development guidance are harmonizing specification setting across the trans-Atlantic corridor. Generic sponsors now submit combined dossiers through the FDA-EMA parallel assessment pilot, cutting review cycles by four to six months. Dermatology-focused ANDA filers with established bioequivalence protocols capture first-to-file advantages in this streamlined pathway.
Hospital procurement consortia in Germany, France, and Italy now mandate tender participation only from suppliers with demonstrated annual volumes above five million defined daily doses, consolidating vendor panels and excluding mid-tier manufacturers. Retail pharmacy chains respond by forming buying groups that mirror hospital scale, squeezing net prices toward marginal cost. This concentration is most visible in Southern Europe, where three purchasing organizations now control seventy percent of reimbursed terbinafine volume.
Terbinafine Tablet Market Segmentation
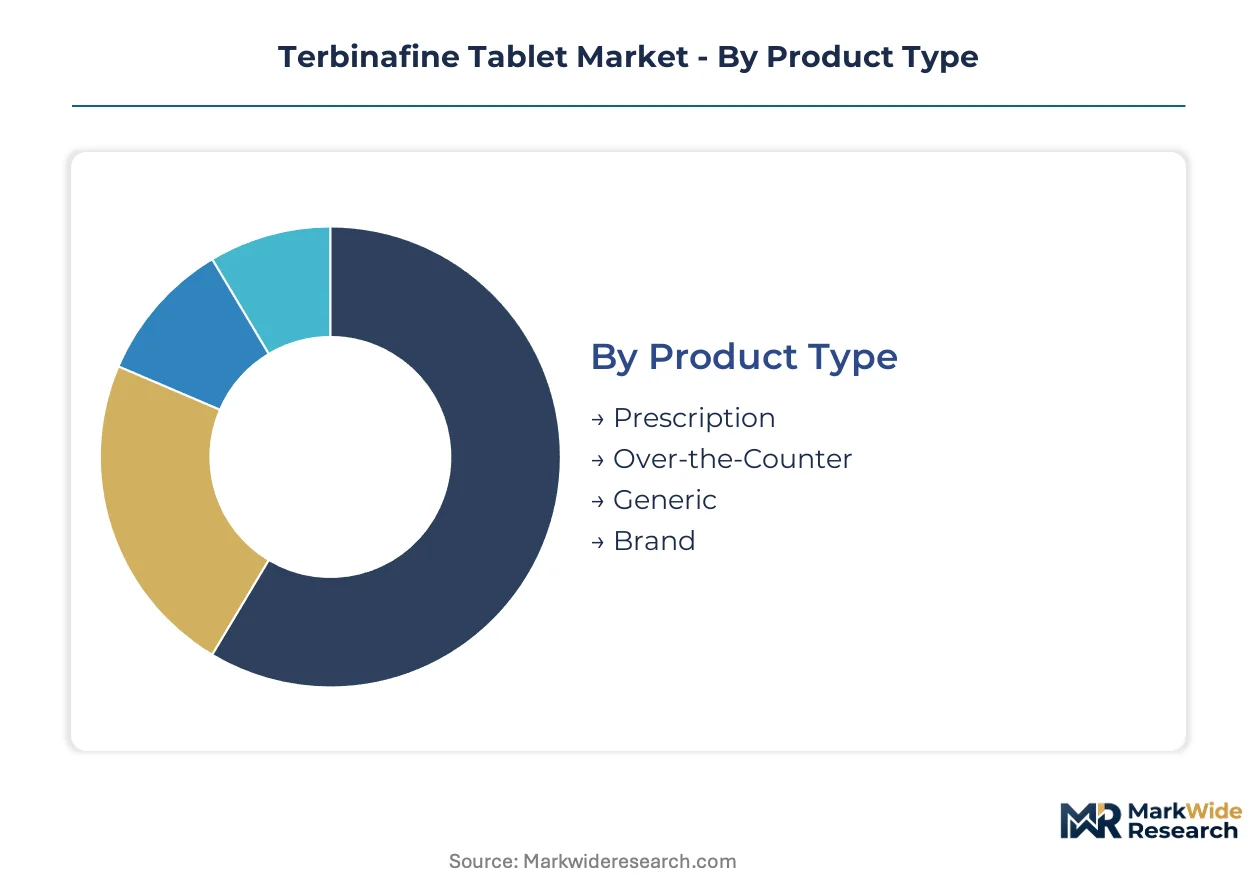
Terbinafine tablet segmentation reveals divergent margin profiles across formulation types and access channels. Prescription routes carry hepatotoxicity monitoring costs that reshape profitability, while generic substitution mechanics compress brand premiums differently across geographies.
Product Type:
Generic tablets turn inventory fastest in retail chains with automatic substitution mandates, while brand formulations sit longer in specialty pharmacy channels where prior authorization delays persist.
- Generic:Bioequivalent 250 mg terbinafine hydrochloride tablets manufactured to FDA and EMA standards dominate pharmacy benefit manager formularies. Demand concentrates in United States retail chains and Indian government tenders where procurement officers prioritize lowest-unit-cost sourcing under national health insurance schemes.
- Prescription:Physician-dispensed tablets requiring liver function monitoring documentation carry higher per-unit margins but slower patient throughput. Dermatology clinics in Germany and France represent the core demand concentration, driven by reimbursement protocols that mandate specialist oversight for systemic antifungal therapy.
- Over-the-Counter:Limited jurisdictions permit non-prescription access; India and select Southeast Asian markets allow pharmacist-directed dispensing for tinea pedis with documented prior diagnosis.
- Brand:Novartis-originator Lamisil retains formulary placement in markets with delayed generic entry or therapeutic substitution restrictions, notably in Middle Eastern hospital procurement systems.
Generic dominates installed base. Prescription is where expansion concentrates.
Dosage Form:
Tablet production runs yield lowest cost-per-unit at commercial scale, while oral suspension commands premium pricing in pediatric segments with limited manufacturing competition.
- Tablet:Film-coated 250 mg oral solids represent the standard presentation with 70 percent systemic bioavailability. Demand clusters in retail pharmacy chains across India, Brazil, and Mexico where blister-pack stability and shelf-life economics favor solid dosage logistics.
- Oral Suspension:Liquid formulations enable weight-based dosing for pediatric tinea capitis cases. Compounding pharmacies in the United States and hospital formularies in South Africa drive volume where tablet swallowing compliance fails.
- Capsule:Gelatin-shell alternatives offer limited differentiation; niche demand emerges from patients with tablet compression sensitivity in Japanese geriatric populations.
- Powder:Sachet presentations for extemporaneous suspension preparation serve humanitarian supply chains and rural dispensaries in sub-Saharan Africa with intermittent cold-chain access.
Tablet commands manufacturing scale. Oral suspension is climbing the fastest.
Route of Administration:
Oral delivery achieves therapeutic nail bed concentrations that topical routes cannot match, while intravenous remains restricted to compassionate-use settings with no commercial scale.
- Oral:Gastrointestinal absorption exceeding 70 percent makes this the definitive route for onychomycosis cure. Dermatology practices in Italy and Spain generate concentrated demand where public reimbursement covers twelve-week treatment courses.
- Topical:Cream and gel formulations serve tinea corporis and pedis without systemic exposure; retail pharmacy counters in Thailand and Vietnam drive volume where patients self-select against hepatotoxicity risk.
- Intravenous:No approved parenteral terbinafine formulation exists; off-label use in immunocompromised patients occurs only in tertiary hospital settings with pharmacy compounding capabilities.
- Inhalation:No clinical development pathway; pulmonary delivery remains preclinical for fungal prophylaxis indications.
Oral dominates therapeutic outcomes. Topical is gaining share fastest in self-pay markets.
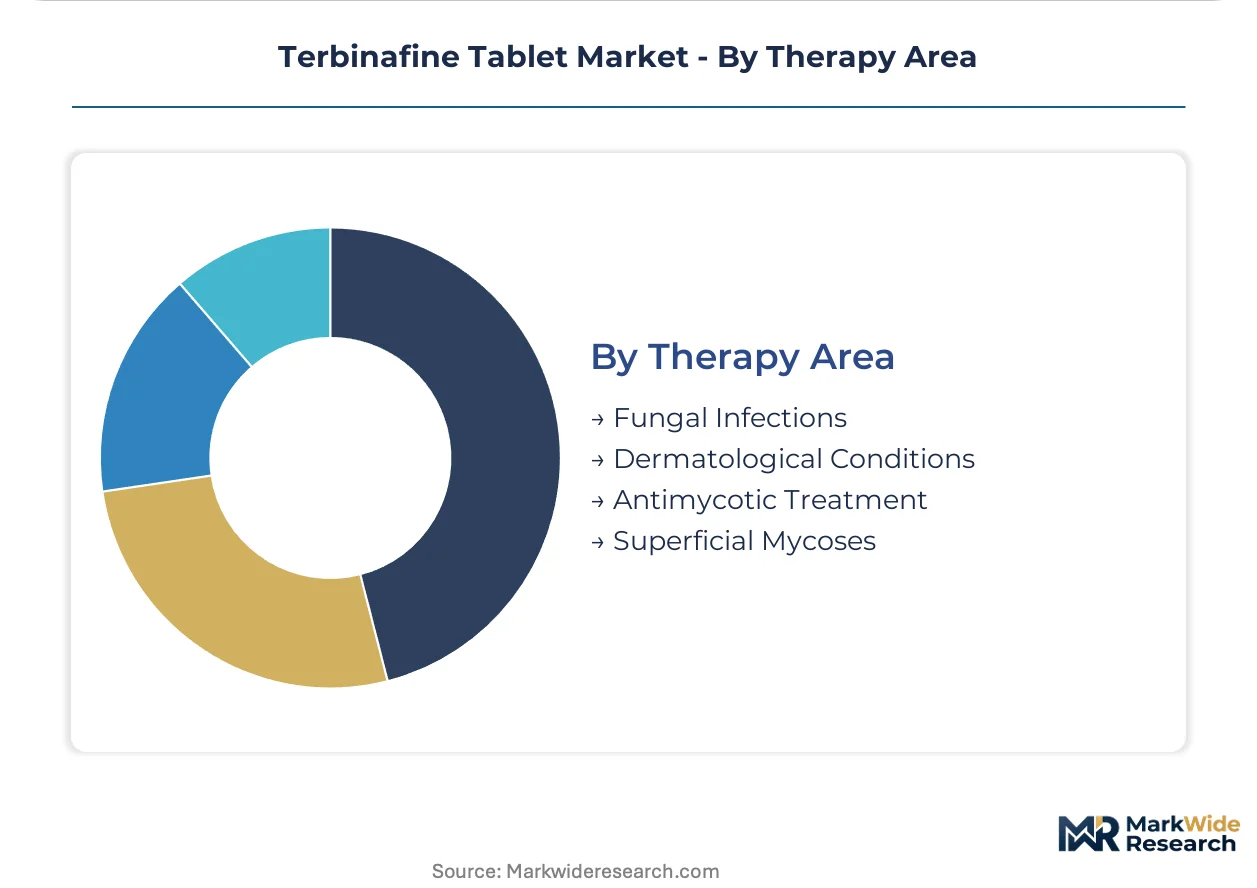
Therapy Area:
Fungal infection treatments move through diagnosis-to-prescription cycles measured in days, while dermatological condition management extends to chronic recurrence prevention with longer patient retention.
- Fungal Infections:Onychomycosis and tinea capitis represent the primary labeled indications with culture-confirmed diagnosis requirements. United States podiatry clinics and Indian dermatology departments generate parallel demand streams driven by cosmetic concern and public health screening programs respectively.
- Dermatological Conditions:Off-label use in seborrheic dermatitis and pityriasis versicolor expands addressable population. Brazilian and Argentine prescription patterns show elevated off-label incidence where topical ketoconazole resistance emerges.
- Antimycotic Treatment:Broad categorical reimbursement coding in European hospital systems captures prophylactic and curative uses under single billing categories.
- Superficial Mycoses:Skin and mucosal infections without nail involvement drive shorter treatment courses; Southeast Asian pharmacy counters see high turnover for tinea cruris and corporis presentations.
Fungal Infections dominates installed base. Dermatological Conditions is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for terbinafine tablets varies sharply across geographies: Indian retail buyers exhibit extreme price sensitivity, while German dermatology clinics absorb monitoring costs with minimal volume impact. This divergence shapes procurement strategies and margin capture across the value chain.
United States
Pharmacy benefit managers at CVS Caremark and Express Scripts enforce automatic generic substitution at the counter, eliminating prescriber discretion. FDA bioequivalence standards under 21 CFR 320.24 determine which manufacturers gain formulary access. API sourcing concentrates in New Jersey and Puerto Rico-based contract manufacturing organizations serving ANDA filers.
Germany
Dermatology clinics in Bavaria and North Rhine-Westphalia generate concentrated demand for prescription-mandated liver function monitoring protocols. EMA quality guidelines and national G-BA reimbursement assessments filter market entry. Hospital procurement consortia in Berlin-Brandenburg now require minimum five million defined daily dose annual volumes for tender participation.
India
Over-the-counter access and price-sensitive government tenders drive volume through retail pharmacy chains in Maharashtra and Gujarat. CDSCO WHO-GMP export certifications unlock African and Southeast Asian markets. Manufacturing clusters in Hyderabad and Ahmedabad produce over sixty percent of non-infringing terbinafine base supply for European generics filers.
Brazil
Three-tier distribution markups absorb margin in conventional wholesale channels, prompting direct-to-pharmacy logistics investments. ANVISA bioequivalence requirements and state-level procurement in São Paulo and Minas Gerais shape competitive access. Compounding pharmacies in Rio de Janeiro serve pediatric oral suspension demand where tablet compliance fails.
Japan
PMDA post-marketing surveillance requirements and geriatric tablet compression sensitivity sustain niche capsule demand. Reimbursement pricing under the Central Social Insurance Medical Council constrains premium capture. Osaka-based distributors serve dermatology clinics in Kansai with strict hepatotoxicity documentation protocols.
Terbinafine Tablet Market Competitive Landscape
Capability concentration sits with originator dossier holders; scale advantage sits with high-volume Indian generics manufacturers. The market structures around a tiered hierarchy: legacy brand incumbents with regulatory depth, vertically integrated API-to-tablet producers, and contract manufacturing specialists serving semi-regulated channels. Dominant competitive moves include portfolio diversification into fixed-dose combinations and backward integration into allylamine synthesis intermediates.
Within the originator tier, Novartis AG exemplifies regulatory dossier depth and legacy formulary positioning. Among Indian generics specialists, Sun Pharmaceutical Industries Ltd. and Dr. Reddy's Laboratories Ltd. occupy positions defined by cost-base advantage and CDSCO-certified export scale. These entities represent the competitive poles around which bioequivalent filers and regional distributors organize their market access strategies.
| Leading Market Players |
|---|
| Novartis AG |
| Sun Pharmaceutical Industries Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Cipla Inc. |
| Aurobindo Pharma Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Glenmark Pharmaceuticals Ltd. |
| Torrent Pharmaceuticals Ltd. |
| Mylan N.V. |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Indian API manufacturers concentrates pricing power among four Gujarat and Telangana contract manufacturers, compressing margin spreads between premium EMA-certified generics and economy-tier hospital tenders while forcing European filers into long-term offtake commitments that reshape inventory positioning across the value chain.
Pricing Analysis
After-sales revenue from liver function monitoring services and hepatotoxicity surveillance protocols drives lifetime value per patient beyond the tablet unit economics. Three-tier pricing structure across premium EMA-certified, standard FDA-approved, and economy WHO-GMP tiers differentiates by certification level and batch documentation depth. Cost compression in the economy tier intensifies because Indian government tenders prioritize lowest-unit-cost sourcing under national health insurance schemes. Hospital procurement consortia in Germany exhibit least price sensitivity due to mandated specialist oversight protocols, while retail pharmacy chains in Maharashtra and Gujarat absorb maximum pricing pressure.
Supply Chain Analysis
Tariff exposure between India and European Union member states dominates supply chain risk calculus for generic filers dependent on allylamine hydrochloride intermediates. API manufacturing concentrates in India, China, and limited Puerto Rico-based contract manufacturing organizations serving ANDA filers. Terbinafine base synthesis draws from N-methyl-1-naphthalenemethylamine and trans-1,4-dichloro-2-butene feedstocks, with continuous flow chemistry adoption reducing batch-to-batch variability. Single-source vulnerability for European generics filers persists as four contract manufacturers control majority non-infringing supply. Distribution runs through three-tier wholesale intermediaries in Brazil and Mexico, with direct-to-pharmacy logistics investments capturing margin in select markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generic substitution cycles position this market in a recovery phase as pharmacy benefit manager mandates accelerate volume migration toward bioequivalent alternatives, with hepatotoxicity surveillance requirements sustaining specialist-channel premiums that offset retail compression.
For Market Incumbents: Entrench formulary positioning through backward integration into allylamine synthesis intermediates and captive API supply from Hyderabad and Ahmedabad manufacturing clusters. Defend against fixed-dose combination threats by securing EMA orphan designation pathways for pediatric tinea capitis indications. Prioritize CDSCO WHO-GMP recertification investments to maintain African and Southeast Asian tender access against emerging Indian competitors. For New Entrants and Emerging Players: Build out direct-to-pharmacy distribution networks in Brazil and Mexico where three-tier wholesale markups absorb forty percent of terminal price. Target pediatric oral suspension segments in South Africa and United States compounding pharmacy channels where tablet compliance failures create addressable white space. Pursue ANVISA bioequivalence certification as the go-to-market anchor for Latin American hospital procurement systems. For Investors and Strategic Acquirers: The market sits at a generic substitution acceleration phase that favors vertically integrated API-to-tablet producers with CDSCO-certified export scale. Long-term viability across a five-to-ten year window hinges on continuous manufacturing platform adoption and regulatory dossier depth for first-to-file advantages. Monitor EMA pharmacovigilance signal management infrastructure investments as the inflection indicator for emerging market access sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Conversion | Sandoz and Zentiva have compressed release timelines from fourteen days to under forty-eight hours through twin-screw wet granulation adoption. |
| EMA Orphan Designation Pursuit | Pediatric tinea capitis protocol assistance and fee reductions accelerate time-to-market for age-appropriate tablet strengths. |
| Direct-to-Pharmacy Distribution Buildout | Bypassing wholesale intermediaries in Brazil and Mexico captures margin currently absorbed by three-tier distribution markups. |
| Fixed-Dose Combination Development | Pairing terbinafine with itraconazole addresses mixed fungal populations and commands premium pricing in dermatology specialty channels. |
| CDSCO WHO-GMP Recertification Investment | Indian manufacturers achieving PIC/S accreditations unlock tender access across Africa and Southeast Asia, expanding addressable patient populations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA ANDA filings, EMA quality guideline submissions, CDSCO audit records, and Indian state-level tender databases. Primary interviews with regulatory affairs leads at European generics filers, formulary directors at United States pharmacy benefit managers, and procurement officers at German hospital consortia were cross-validated against secondary sources including ClinicalTrials.gov hepatotoxicity surveillance protocols and WHO-GMP inspection reports. Bottom-up patient volume modeling and top-down pharmaceutical market sizing were triangulated to converge on segment-level estimates.
Forecast inputs include generic substitution mandate penetration rates, EMA and FDA bioequivalence approval timelines, and CDSCO export certification velocity across the analysis window. Segmentation dimensions encompass product type, dosage form, route of administration, therapy area, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to volume and value baselines, with specific weighting given to allylamine synthesis scale-up adoption curves and hepatotoxicity surveillance protocol cost trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Indian API manufacturers or unexpected EMA pharmacovigilance enforcement escalations would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
PCSK9 Inhibitors Market
Biopharmaceuticals
Italy Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Lenalidomide Market
Biopharmaceuticals
Interleukin-6 (IL-6) Inhibitors Market
Biopharmaceuticals
Recombinant Hormone Market
Biopharmaceuticals
Octreotide Market
Biopharmaceuticals
Global Branded Generics Market
Biopharmaceuticals
Generic Drugs Market
Biopharmaceuticals
Targeted Protein Degradation Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
Linaclotide API Market
Biopharmaceuticals
H1N1 Vaccines Market
Biopharmaceuticals
Nfkb P65 Antibody Market
Biopharmaceuticals
Oseltamivir Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
Peptide Antibiotics Market