
 Glucoamylase Market | 2026-2036
Glucoamylase Market Size, Share, and Industry Trends Forecast 2026-2036
Glucoamylase Market Foresight
Bioethanol production is pivoting toward higher-purity fermentation streams as fuel-blending mandates tighten across multiple jurisdictions. Novozymes leverages its recombinant DNA platform to dominate high-performance enzyme supply for corn-to-ethanol facilities. Genencor anchors North American demand through backward integration into strain development and bioprocess engineering. BASF competes on manufacturing scale, operating multi-thousand-ton fermentation capacity across European and Asian sites.
Glucoamylase is an exo-acting amylase that hydrolyzes alpha-1,4 and alpha-1,6 glycosidic bonds at the non-reducing ends of starch chains, typically operating at pH 4.0-5.0 and temperatures of 55-65°C to release glucose units for downstream fermentation or sweetener production. The enzyme serves as the terminal saccharification catalyst in starch processing, converting dextrinized substrates into fermentable sugars for bioethanol, brewing, and high-fructose syrup manufacture. Liquid formulations lead volume due to ease of dosing in continuous-flow bioreactors, while recombinant DNA technology commands the fastest growth as engineered strains deliver higher specific activity and thermal stability. Submerged fermentation remains the mature production backbone, though solid-state fermentation gains traction in cost-sensitive Asian supply chains where substrate flexibility matters.
The EPA's Renewable Fuel Standard and the EU Green Deal's biofuel targets shape demand trajectories by mandating specific ethanol blending percentages that cascade into enzyme procurement volumes. China's GB standards for industrial enzyme quality and India's BIS certification requirements for food-grade biocatalysts create layered compliance thresholds that filter market access. Stakeholders must monitor how regulatory tightening on carbon intensity scores in fuel programs redirects investment toward enzyme systems with superior conversion efficiency.
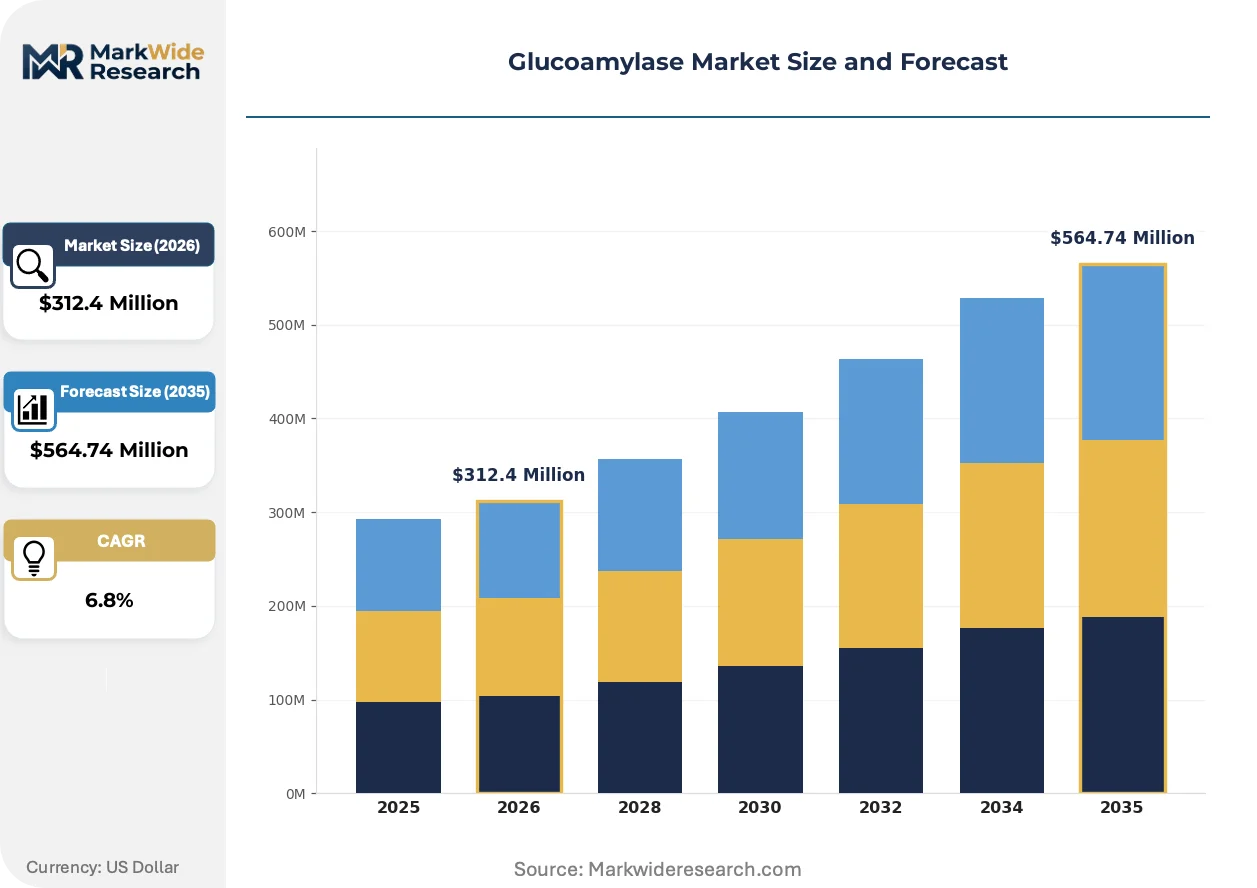
Market Dynamics
Recombinant DNA engineering is compressing enzyme production costs while tightening performance specifications across bioethanol and starch processing value chains. Engineered strain development now determines competitive position more than fermentation scale alone.
Growth Catalysts
- EPA Renewable Fuel Standard:Mandated ethanol blending volumes in the United States are accelerating enzyme procurement cycles at corn-to-ethanol facilities.
- China's provincial clean energy targets:State-backed biorefinery buildouts are industrializing enzyme demand across Shandong and Jilin provinces.
- Submerged fermentation optimization:Continuous-flow bioreactor designs are improving specific activity yields and reducing batch-to-batch variability.
Market Restraints
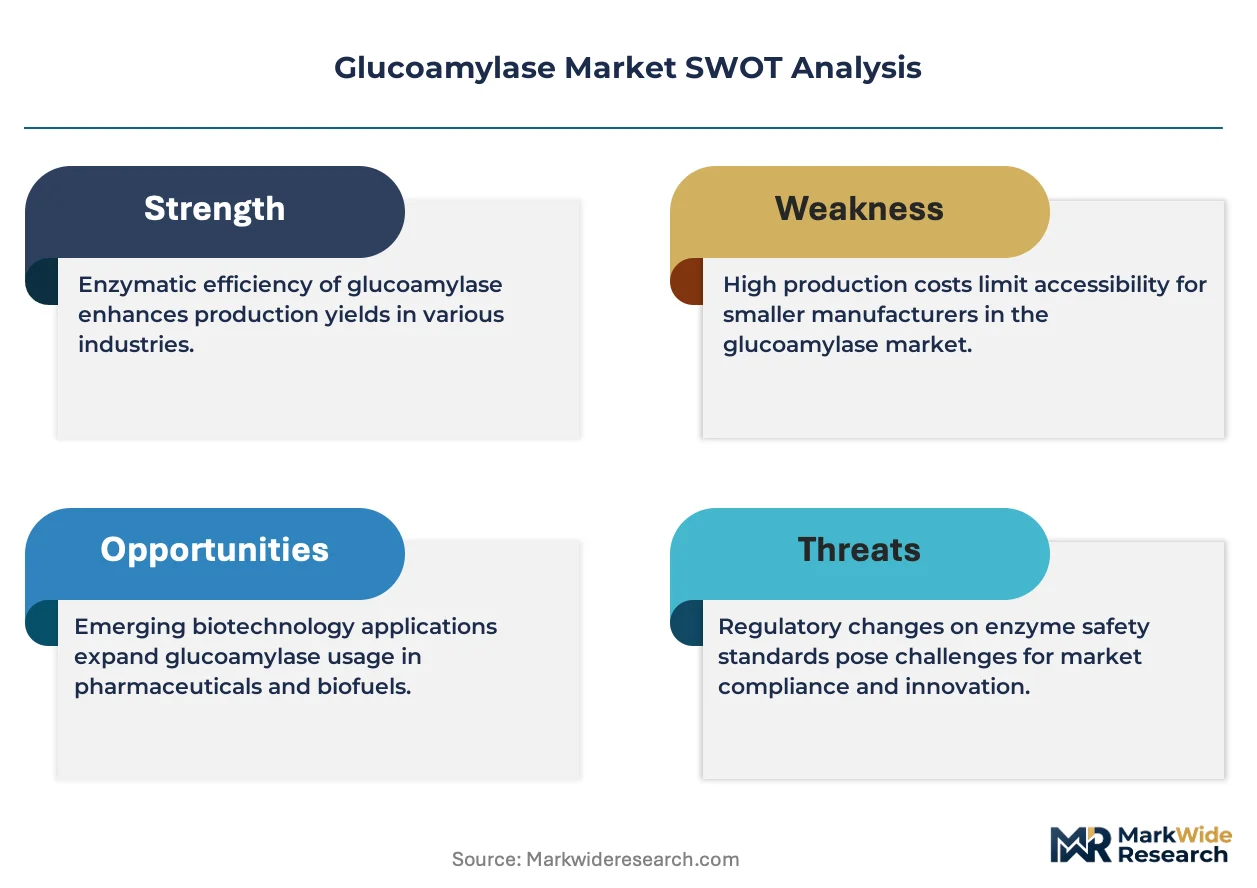
- Agricultural input volatility:Corn starch and wheat substrate costs fluctuate with commodity harvest cycles, squeezing margin structures for cost-sensitive Asian supply chains.
- Supplier concentration in Denmark:Recombinant strain IP and high-performance enzyme supply clusters with a narrow set of biotechnology developers.
- Technical substitution risk:Pullulanase and isoamylase co-formulations in saccharification steps can partially displace standalone glucoamylase dosing.
Strategic Opportunities
- India's BIS certification expansion:Food-grade biocatalyst standards are creating compliant market entry for quality-differentiated suppliers.
- Second-generation feedstock processing:Lignocellulosic biomass hydrolysis is opening adjacent enzyme application streams beyond starch-based substrates.
- EU Green Deal biofuel targets:Carbon intensity scoring in fuel programs is redirecting investment toward high-conversion-efficiency enzyme systems.
Industry Challenges
- Strain engineering talent scarcity:Molecular biology and bioprocess engineering skill gaps constrain in-house R&D scaling for mid-tier producers.
- Multi-jurisdiction certification timelines:Sequential GB standards, BIS, and FDA food-contact approvals extend product commercialization cycles by 18-24 months.
- Legacy dosing equipment incompatibility:Thermal-stable engineered enzymes require retrofitting existing continuous-flow infrastructure at mature processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucoamylase Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Tablet Application: Brewing, Baking, Bioethanol Production, Detergents End User Industry: Food & Beverage, Renewable Energy, Household Care, Pharmaceuticals Technology: Recombinant DNA, Solid-State Fermentation, Submerged Fermentation, Enzyme Immobilization |
| Companies Covered | Novozymes, Genencor, Amano Enzyme, DSM, AB Enzymes, Shandong Longda, Sunson, BASF, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucoamylase Market Shifts & Advancements
Enzyme engineering platforms are collapsing the traditional trade-off between thermal stability and specific activity. This convergence is reshaping procurement criteria and supplier qualification protocols across fuel ethanol and food processing sectors.
CRISPR-guided strain development is unifying multiple performance traits—thermostability, pH tolerance, and reduced product inhibition—within single enzyme variants. Corn-to-ethanol facilities in the United States are adopting these engineered catalysts at accelerated refresh cycles. The technology is unifying what previously required blended enzyme cocktails into streamlined single-dose formulations, compressing supply chain complexity and dosing logistics.
REACH registration requirements for industrial biocatalysts are tightening substance characterization and environmental fate documentation obligations. European enzyme suppliers are restructuring formulation disclosure protocols to meet ECHA compliance thresholds. Fuel ethanol producers operating under EU Green Deal carbon accounting rules are most affected, with many qualifying suppliers through third-party lifecycle certification bodies.
Buyers are consolidating enzyme procurement under multi-year performance contracts that tie pricing to conversion efficiency guarantees rather than per-kilogram unit costs. This model is displacing spot purchasing in large-scale bioethanol operations. The shift is most visible in China, where state-owned biorefineries are leveraging procurement volume to secure dedicated strain development partnerships with technology providers.
Glucoamylase Market Segmentation
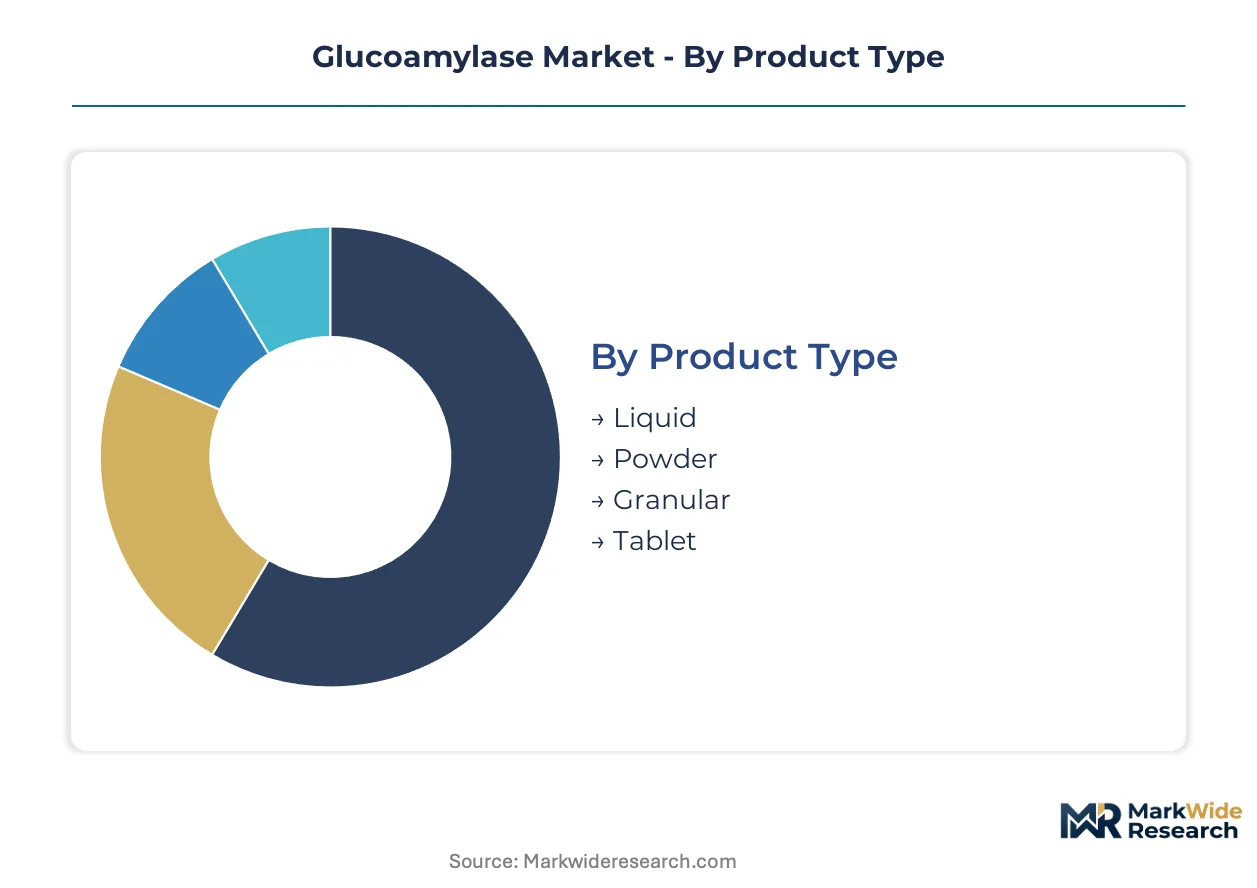
Glucoamylase procurement patterns diverge sharply across formulation physics, production biotechnology, and end-use fermentation requirements. Each segmentation axis carries distinct margin structures and supplier qualification protocols that reshape competitive positioning.
Product Type:
Liquid, powder, granular, and tablet formats each map to dosing infrastructure maturity and supply chain cost sensitivity across starch processing facilities.
- Liquid:Aqueous enzyme concentrates enable precise flow-rate injection into continuous saccharification reactors. Corn-to-ethanol facilities in the United States favor liquid dosing for integration with automated process control systems. Liquid formulations dominate procurement volumes due to compatibility with existing tank-farm infrastructure.
- Powder:Spray-dried enzyme preparations offer extended ambient-temperature stability and reduced shipping weights for intercontinental supply chains. Asian biorefineries in Shandong and Jilin provinces source powder formats to offset cold-chain logistics costs. Powder leads on momentum as state-backed biorefineries industrialize enzyme uptake.
- Granular:Agglomerated solid preparations suit small-scale brewing operations lacking liquid dosing pumps. Craft breweries in Germany and Belgium specify granular glucoamylase for batch-to-batch flexibility.
- Tablet:Compressed unit-dose formats serve artisanal baking and specialty starch modification where precise small-scale addition matters. Artisan bakeries in France prefer tablet convenience over bulk powder handling.
Liquid leads on scale; powder leads on momentum.
Application:
Bioethanol mandates, brewing traditions, and detergent formulation science each generate distinct enzyme performance specifications and procurement contract structures.
- Bioethanol Production:Fuel-ethanol facilities demand glucoamylase variants with exceptional thermal stability for simultaneous saccharification-fermentation processes. EPA Renewable Fuel Standard compliance drives enzyme refresh cycles at US corn-processing plants. This application commands premium pricing tied to conversion efficiency guarantees.
- Brewing:Lager and ale production requires glucoamylase for attenuation control and residual sugar management. Large-scale breweries in Denmark and the Netherlands specify enzyme systems for consistent fermentability across malt batches. Brewing represents established demand with long-term supply agreements.
- Baking:Bread improver formulations leverage glucoamylase for controlled starch modification and crumb structure optimization. Industrial bakeries in Germany integrate enzyme blends for standardized product output.
- Detergents:Stain-removal formulations incorporate glucoamylase for carbohydrate-based soil hydrolysis. Household care manufacturers in Western Europe specify enzyme stability under alkaline wash conditions.
Bioethanol production leads on scale; brewing leads on contract maturity.
End User Industry:
Food safety certification, renewable energy policy, and pharmaceutical GMP standards create divergent compliance thresholds that filter supplier access.
- Food & Beverage:Starch sweetener and brewing operations require food-grade enzyme certification under FDA, EFSA, and FSSAI jurisdictions. High-fructose corn syrup manufacturers in the United States represent concentrated demand with multi-year supply contracts.
- Renewable Energy:Bioethanol producers operate under carbon intensity scoring regimes that reward high-conversion-efficiency enzyme systems. State-owned biorefineries in China leverage procurement volume for dedicated strain development partnerships. This industry expands most quickly as provincial clean energy targets accelerate buildouts.
- Household Care:Detergent manufacturers specify enzyme stability under variable pH and temperature storage conditions. European formulators face REACH registration requirements for biocatalyst environmental fate documentation.
- Pharmaceuticals:Excipient and active ingredient production demands GMP-compliant enzyme supply with full batch traceability. Injectable-grade starch hydrolysis applications require validated manufacturing processes.
Food & Beverage leads on scale; renewable energy leads on momentum.
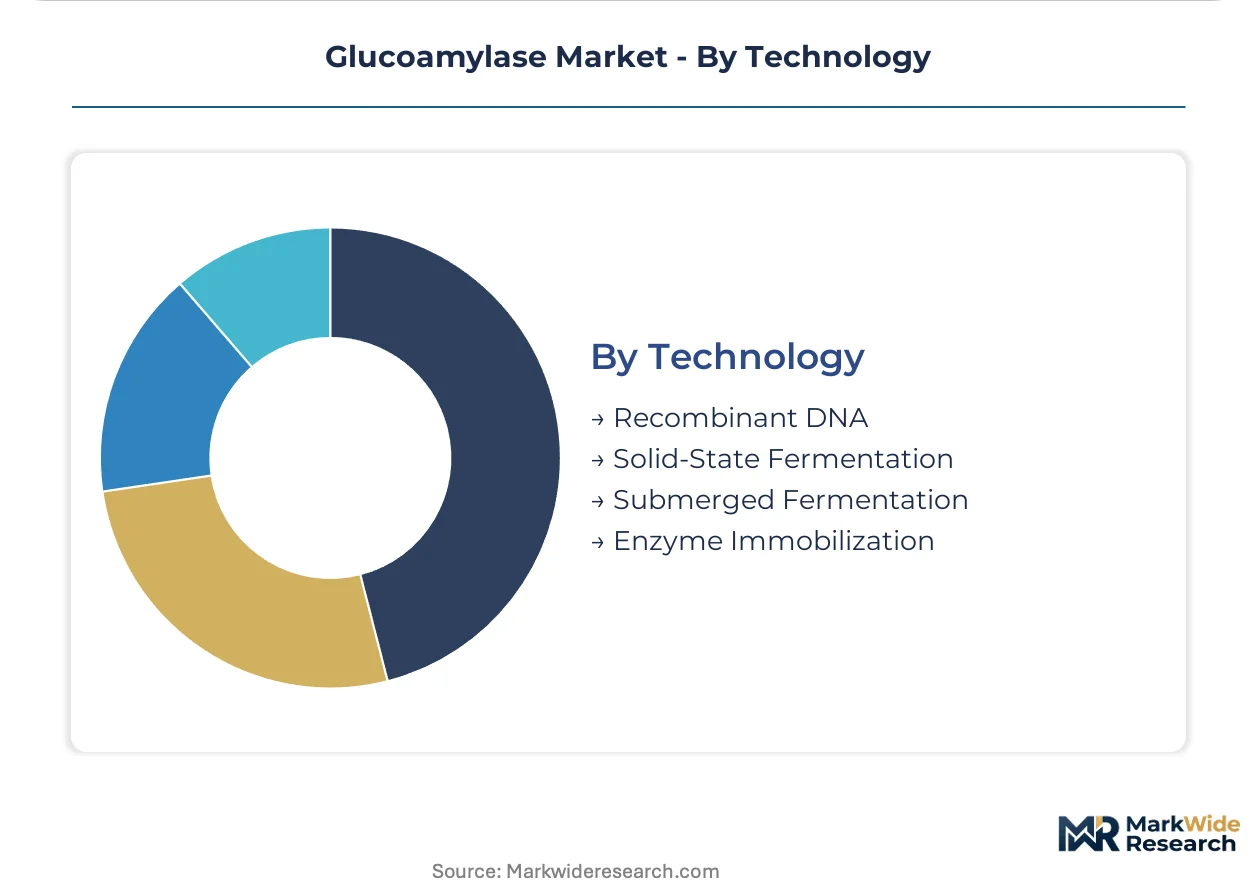
Technology:
Strain engineering platforms and bioprocess modalities determine cost position, performance specifications, and intellectual property barriers across supplier tiers.
- Recombinant DNA:Engineered fungal and bacterial strains deliver elevated specific activity, thermal tolerance, and reduced product inhibition. CRISPR-guided development unifies multiple performance traits within single enzyme variants. Corn-to-ethanol facilities adopt recombinant catalysts at accelerated refresh cycles, climbing the fastest among technology categories.
- Submerged Fermentation:Conventional tank-based production using Aspergillus niger or Rhizopus strains remains the mature cost backbone. Multi-thousand-ton fermentation capacity across European and Asian sites anchors supply security for price-sensitive buyers.
- Solid-State Fermentation:Growth on moist solid substrates offers capital efficiency and feedstock flexibility for cost-sensitive Asian supply chains. Smaller-scale operators in India leverage agricultural residue substrates to offset starch-based media costs.
- Enzyme Immobilization:Covalent or adsorptive attachment to solid supports enables enzyme recovery and reuse in continuous processing systems. Starch sweetener manufacturers evaluate immobilized systems for reduced enzyme consumption per ton of glucose produced.
Submerged fermentation leads on scale; recombinant DNA leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province anchors industrial enzyme demand through state-backed biorefinery clusters serving corn-to-ethanol conversion. Provincial clean energy targets in Jilin and Henan accelerate buildouts of starch-processing infrastructure. Regulatory mandates across multiple jurisdictions reshape procurement patterns for saccharification catalysts.
United States
Corn-to-ethanol facilities in Iowa and Illinois drive enzyme procurement volumes under EPA Renewable Fuel Standard mandates. The EPA's escalating ethanol blending requirements compress refresh cycles for high-performance catalysts. Processing plants along the Mississippi River corridor integrate automated dosing systems for continuous-flow saccharification.
China
State-owned biorefineries in Shandong and Jilin provinces industrialize enzyme uptake through provincial dual carbon targets. GB standards for industrial enzyme quality filter market access for foreign suppliers. The Yangtze River Delta bioprocessing corridor concentrates submerged fermentation capacity for domestic glucoamylase production.
Germany
Brewing operations in Bavaria and North Rhine-Westphalia sustain established demand for attenuation-control enzymes. REACH registration requirements tighten environmental fate documentation for biocatalyst suppliers. The Rhine-Ruhr industrial cluster hosts multi-thousand-ton fermentation facilities serving European starch-processing markets.
India
Food-grade enzyme demand concentrates in Maharashtra and Gujarat as FSSAI certification requirements mature. BIS standards for industrial biocatalysts create compliant entry pathways for quality-differentiated suppliers. Solid-state fermentation operators in Tamil Nadu leverage agricultural residue substrates to offset production costs.
Brazil
Sugarcane-to-ethanol processors in São Paulo and Minas Gerais states diversify into corn-based feedstocks requiring glucoamylase conversion. ANVISA pharmaceutical-grade standards shape excipient enzyme supply requirements. The Center-South ethanol belt expands enzyme procurement as flex-fuel blending mandates tighten.
Glucoamylase Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers secure dedicated strain development relationships with state-owned biorefineries. The vendor base concentrates around recombinant DNA platforms and submerged fermentation scale, with three distinct tiers emerging: integrated biotechnology conglomerates, regional fermentation specialists, and application-focused formulators. Capacity expansion and technology licensing represent the primary competitive vectors, with backward integration into strain IP separating premium-tier suppliers from commodity producers.
Among Danish biotechnology developers, Novozymes exemplifies the integrated platform archetype through its recombinant DNA capabilities. Genencor anchors North American positioning within the strain development tier. BASF occupies a scale-driven position across European and Asian manufacturing sites. Shandong Longda and Sunson represent Chinese fermentation specialists competing on substrate flexibility and provincial supply chain proximity.
| Leading Market Players |
|---|
| Novozymes |
| Genencor |
| Amano Enzyme |
| DSM |
| AB Enzymes |
| Shandong Longda |
| Sunson |
| BASF |
| DuPont |
| Others |
Supply & Pricing Matrix
Backward integration into strain development anchors pricing power for recombinant glucoamylase suppliers, as in-house molecular biology capabilities eliminate licensing costs while enabling proprietary performance guarantees that command contract premiums. Corn-to-ethanol facilities in Iowa and Illinois negotiate multi-year offtake agreements tied to conversion efficiency metrics rather than per-kilogram unit costs, compressing spot-market exposure for integrated biotechnology developers.
Pricing Analysis
Input-cost pass-through from agricultural substrate volatility shapes margin structures across fermentation-based production tiers. Three-tier pricing structure across premium recombinant, standard submerged fermentation, and economy solid-state levels reflects certification grade and specific activity differentials. Cost compression in the economy tier is intensifying because wheat and corn starch prices fluctuate with commodity harvest cycles. State-owned biorefineries in China exhibit highest price sensitivity due to procurement volume leverage, while pharmaceutical GMP-compliant buyers accept premium positioning for batch traceability.
Supply Chain Analysis
Returns and refurbishment flows are minimal in enzyme supply chains, though expired liquid concentrates from continuous-flow bioreactors occasionally feed back into agricultural applications as soil amendments. Manufacturing concentrates in Denmark, China, and Germany, with recombinant strain IP clustering around Danish biotechnology developers. Raw material dependencies center on corn starch, wheat bran, and fungal inoculum stocks. Single-source vulnerability in engineered strain supply creates concentration risk. Distribution runs through direct technical sales teams for large bioethanol accounts and regional chemical distributors for smaller brewing and baking operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in glucoamylase supply rests on recombinant DNA platforms collapsing production costs while enabling premium-tier positioning through conversion efficiency guarantees.
For Market Incumbents: Hedge against technical substitution risk by securing exclusive strain development partnerships with state-owned biorefineries in Shandong and Jilin provinces. Deepen backward integration into CRISPR-guided engineering platforms to maintain performance leadership as pullulanase-isomaltase co-formulations encroach on standalone glucoamylase dosing. Prioritize REACH registration completion for European fuel ethanol producers facing EU Green Deal carbon accounting requirements.
For New Entrants and Emerging Players: Begin with solid-state fermentation capacity in Tamil Nadu and Maharashtra to exploit agricultural residue substrate flexibility and BIS certification entry pathways. Target India's food-grade enzyme segment as the most penetrable white space, where FSSAI compliance requirements filter out unqualified suppliers. Pursue technical service bundling with provincial biorefinery buildouts to secure anchor demand before scaling recombinant capabilities.
For Investors and Strategic Acquirers: Roll-up economics work for regional fermentation specialists because strain engineering talent scarcity constrains organic R&D scaling for mid-tier producers. The five-to-ten year viability window favors acquisition of solid-state operators with provincial supply chain proximity in India and China. Monitor EPA Renewable Fuel Standard blending mandate revisions as the inflection signal directing enzyme procurement volume trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Strain Development Partnership | Secures dedicated enzyme supply relationships with state-backed biorefineries in Shandong Province. |
| REACH Registration Completion | Enables compliant market access for European fuel ethanol producers under ECHA substance characterization rules. |
| CRISPR Platform Investment | Unifies thermostability and pH tolerance traits within single enzyme variants for corn-to-ethanol facilities. |
| Solid-State Fermentation Expansion | Reduces capital intensity and feedstock costs for cost-sensitive Asian supply chains using agricultural residues. |
| Performance Contract Structuring | Shifts pricing from per-kilogram units to conversion efficiency guarantees in large-scale bioethanol procurement. |
Research Methodology
Coverage spans the United States, China, Germany, India, and Brazil, with primary inputs from each market cluster combining executive interviews with plant managers at corn-to-ethanol facilities, procurement leads at state-owned biorefineries, technical R&D directors at enzyme suppliers, and regulatory affairs specialists navigating GB standards and BIS certification pathways. Secondary validation draws from EPA Renewable Fuel Standard filings, ECHA REACH registration databases, FSSAI certification records, and customs trade data on industrial enzyme imports. Bottom-up facility-level capacity estimates triangulate against top-down market sizing from procurement volume analysis.
Granularity-level modeling operates at the intersection of formulation physics, production biotechnology, and end-use fermentation requirements across the projection horizon. Segmentation dimensions include product type, application, end user industry, and technology platform, with regional regulatory clusters and carbon intensity scoring regimes as cross-cutting variables. CAGRs derive from trend extrapolation of enzyme procurement cycles, biorefinery buildout pipelines, and strain refresh rates. Industry-specific forecast inputs incorporate EPA mandate escalation schedules and China's provincial dual carbon target implementation timelines.
Several conditions sit outside the modeled scope, including unforeseen regulatory reversals on ethanol blending mandates, breakthrough displacement of starch-based feedstocks by lignocellulosic conversion technologies, and trade policy disruptions affecting Danish-Chinese enzyme supply corridors. Forecasts reflect documented assumptions on strain development productivity gains and biorefinery capacity utilization rates. Practitioners should monitor EPA rulemaking dockets and China's National Development and Reform Commission biorefinery approval announcements for early signals of procurement volume inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
North America Biocatalysts Market
Industrial Biotechnology
Biocatalyst Market
Industrial Biotechnology
Global Carbohydrase Market
Industrial Biotechnology
Cellulose Enzyme Market
Industrial Biotechnology
Beta-Glucanase Market
Industrial Biotechnology
Esterase Market
Industrial Biotechnology
Haematococcus Pluvialis Market
Industrial Biotechnology
Hydrolase Enzymes Market
Industrial Biotechnology
Marine Enzymes Market
Industrial Biotechnology
Tannase Market
Industrial Biotechnology
Protease Market
Industrial Biotechnology
Europe Biocatalyst Market
Industrial Biotechnology
Biocatalysis and Biocatalysts Market
Industrial Biotechnology
Lipase Enzymes Market
Industrial Biotechnology
GCC Biocatalyst Market
Industrial Biotechnology
Xylanase Market