
 White Biotechnology Market | 2026-2036
White Biotechnology Market Size, Share, and Industry Trends Forecast 2026-2036
White Biotechnology Market Intelligence
Revenue from bespoke enzyme development for specific industrial processes is fragmenting as platform technologies become more accessible. Novonesis leverages its extensive enzyme portfolio and fermentation scale to serve high-volume applications. BASF SE competes by integrating bio-based chemicals into its vast production network. Meanwhile, Codexis Inc specializes in protein engineering platforms that accelerate the design of novel biocatalysts for pharmaceutical and food manufacturing.
White biotechnology utilizes microorganisms and enzymes to manufacture products like chemicals, biofuels, and bioplastics. The process typically involves fermentation or bioconversion, where renewable feedstocks are converted into high-value compounds. Bio-based chemicals and biofuels constitute the largest product segments due to their scale. Fermentation technology remains the dominant processing method, while applications of genetic engineering are expanding capabilities in the pharmaceutical sector.
Regulatory frameworks are a significant market influence. The European Union's REACH and the US EPA's programs for sustainable chemistry incentivize the replacement of petroleum-derived substances with bio-based alternatives. These regulations directly impact material selection in consumer goods and industrial applications. The key strategic decision for incumbents is balancing investment between scaling proven fermentation capacity and exploring novel bioconversion pathways.
Market Dynamics
The central dynamic in white biotechnology is the strategic tension between scaling established fermentation processes for commodity bio-chemicals and investing in high-risk, high-reward bioconversion platforms for specialty and pharmaceutical applications. This defines capital allocation and competitive strategy.
Growth Catalysts
- EU Green Deal:This policy framework directly stimulates demand for bio-based and biodegradable materials in sectors like packaging and textiles, creating regulatory tailwinds for replacing petroleum-derived polymers with bio-alternatives inside the European Union.
- Consumer Goods Demand:Requirements from consumer-packaged goods companies for sustainable ingredients are driving adoption of bio-based surfactants, fragrances, and preservatives, particularly in the personal care and home cleaning product segments.
- Bioprocessing Technology:Advances in high-throughput screening, synthetic biology, and fermentation optimization are reducing production costs and expanding the range of molecules that can be produced economically at an industrial scale.
Market Restraints
- Feedstock Volatility:The market's reliance on agricultural feedstocks like corn, sugarcane, and vegetable oils exposes producers to price fluctuations and supply disruptions driven by weather, crop yields, and competition with the food supply chain.
- High Capital Intensity:Constructing and scaling up commercial-scale biorefineries requires significant upfront capital investment, creating high barriers to entry and long payback periods that can deter new investment compared to established petrochemical infrastructure.
- Petrochemical Competition:Bio-based chemicals must compete on price and performance with highly optimized, incumbent petroleum-derived products, a challenge that intensifies when oil prices are low, reducing the economic incentive for substitution.
Strategic Opportunities
- Sustainable Aviation Fuel:Emerging mandates and corporate commitments for sustainable aviation fuel (SAF) create a large-scale, long-term opportunity for technologies that convert biomass and waste into drop-in biofuels for the aviation industry.
- Specialty Food Ingredients:Precision fermentation offers a pathway to produce high-value food ingredients such as proteins, flavors, and colorants with improved sustainability metrics and supply chain stability compared to traditional agricultural or animal sources.
- Waste Stream Valorization:Technologies that convert industrial, agricultural, or municipal waste streams into valuable chemicals and materials offer a compelling circular economy model, turning a disposal cost into a revenue source for various industries.
Industry Challenges
- Process Scaling Complexity:Transferring a bioprocess from a laboratory setting to a commercial-scale production facility is a significant technical challenge, often encountering issues with yield, purity, and consistency that require extensive process engineering expertise.
- Regulatory Pathway Navigation:Bringing novel bio-based products to market requires navigating complex and sometimes lengthy regulatory approval processes, such as those governed by the EPA for chemicals or the FDA for food ingredients in the United States.
- Talent Scarcity:The industry faces a shortage of skilled professionals with interdisciplinary expertise in microbiology, chemical engineering, data science, and automation, which are all critical for operating and optimizing modern biomanufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Biotechnology Market |
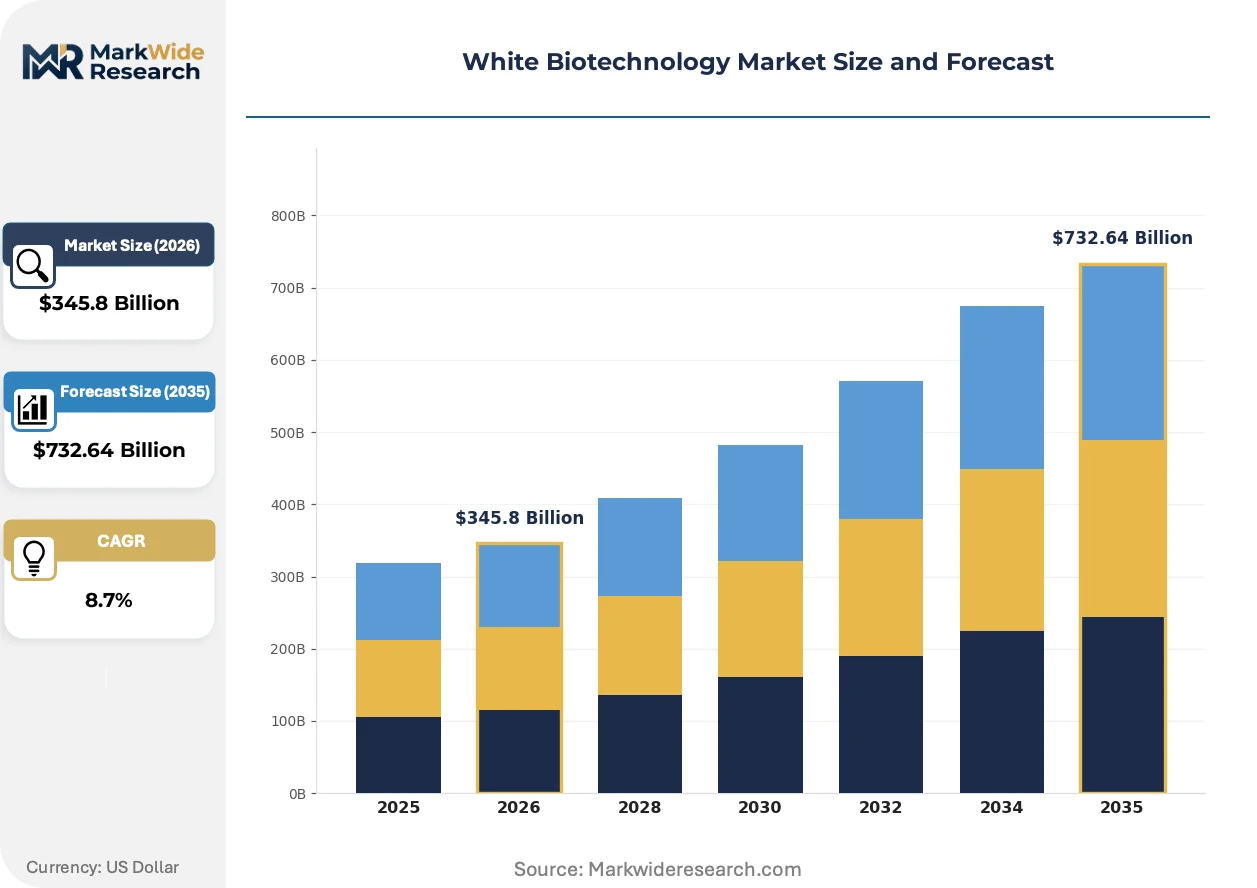
| Market Size in 2026 | $345.8 Billion |
| Market Size in 2035 | $732.64 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Biofuels, Bioplastics, Bio-based Chemicals Technology: Fermentation, Genetic Engineering, Microbial Processing, Bioconversion Application: Agriculture, Food Industry, Pharmaceuticals, Energy Production End User: Agricultural Sector, Food Manufacturers, Chemical Industries, Energy Companies |
| Companies Covered | DSM-Firmenich AG, Novonesis, Lonza Group Ltd, Codexis Inc, Evonik Industries AG, International Flavors & Fragrances Inc., BASF SE, Amyris Inc, Corbion NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Biotechnology Market Strategic Shifts & Innovations
Industrialization of biological systems is the core theme, shifting white biotechnology from a niche R&D function to a central pillar of manufacturing. This transition prioritizes scalability, process control, and integration with existing industrial value chains.
Protein engineering platforms are accelerating the discovery of novel biocatalysts. These systems use AI and high-throughput screening to design enzymes with specific traits for industrial conditions. Pharmaceutical and food ingredient manufacturers are early adopters, seeking to improve process efficiency and create novel products. This technology is collapsing the timeline for custom enzyme development from years to months.
Mandates for corporate environmental disclosure are creating auditable demand for bio-based products. The EU's Corporate Sustainability Reporting Directive (CSRD) and incentives within the US Inflation Reduction Act (IRA) push companies to measure and report their supply chain emissions. This directly impacts material procurement in the automotive and construction sectors, which are now seeking low-carbon alternatives to meet reporting requirements.
Certification-driven procurement is altering purchasing patterns for bio-based materials. Consumer goods brands are specifying materials that meet standards like the USDA BioPreferred Program or carry compostability certifications. This shift empowers brand owners to dictate material specifications directly to suppliers, often bypassing traditional chemical distribution channels. The trend is most prominent in packaging and textiles across North America and Europe.
White Biotechnology Market Segmentation
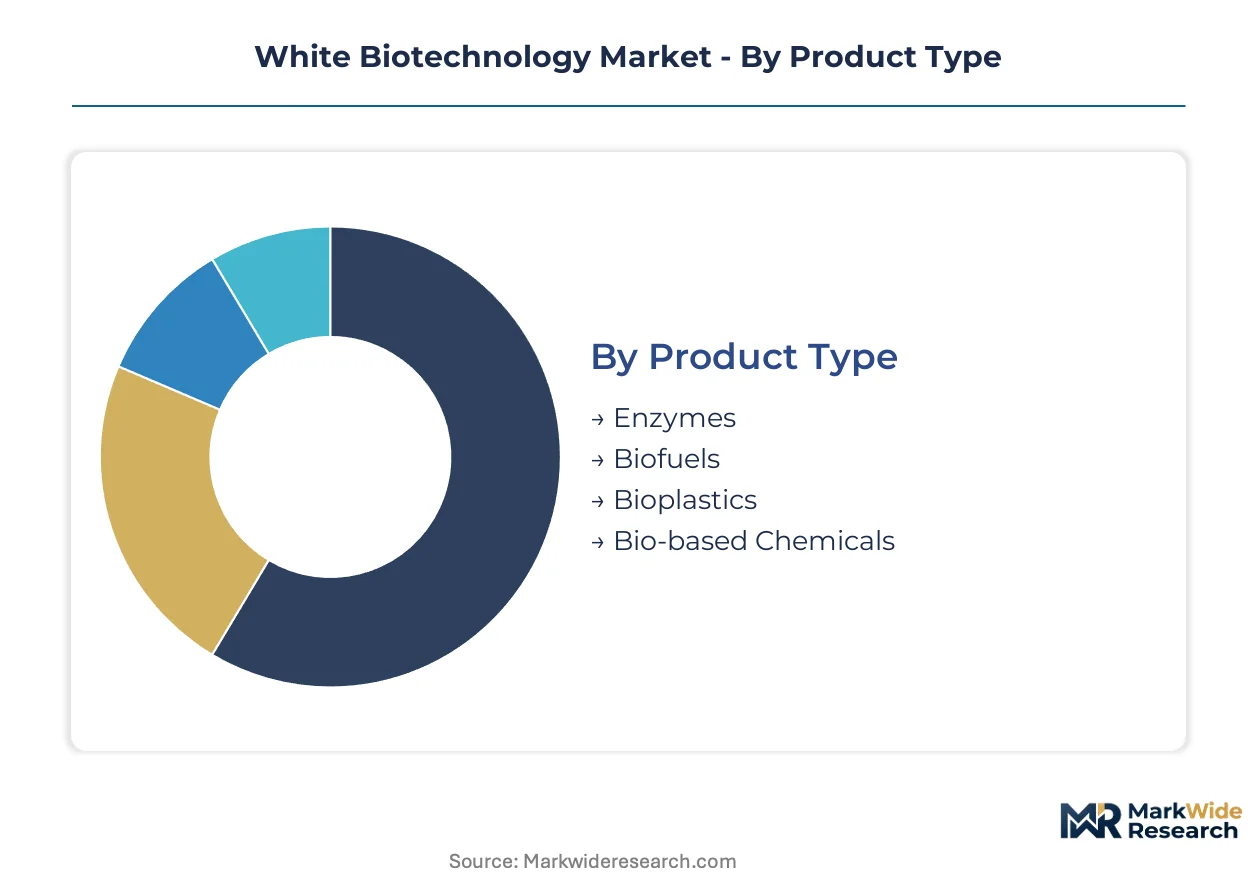
Understanding white biotechnology market segmentation is critical for strategic resource allocation and identifying specific value pools. Each segment presents unique operational requirements, regulatory hurdles, and competitive dynamics, influencing market entry and expansion strategies for participants.
Product Type:
The after-sales service intensity for bio-based products varies significantly, from complex enzyme formulations requiring application support to bulk biofuels with standardized delivery protocols. This differentiation impacts customer relationship management and technical service investments.
- Bio-based Chemicals:These compounds are derived from renewable biomass sources, serving as sustainable alternatives to petroleum-derived chemicals in various industrial processes. Demand concentrates in Germany and the United States, driven by mandates for sustainable material sourcing.
- Biofuels:Biofuels are liquid or gaseous fuels produced from biomass, such as ethanol and biodiesel, offering renewable energy solutions for transportation and industrial power. The aviation sector's push for sustainable aviation fuel creates significant demand in Europe and North America.
- Enzymes:These biological catalysts facilitate specific chemical reactions, improving efficiency and sustainability in diverse industrial applications.
- Bioplastics:Bioplastics are biodegradable or bio-based polymers offering environmentally friendly packaging and material solutions.
Bio-based Chemicals holds the largest share; momentum sits with Biofuels.
Technology:
The volume scalability of white biotechnology technologies dictates their commercial viability and market penetration. Technologies demonstrating high throughput and consistent output gain significant competitive advantage in commodity markets.
- Fermentation:This established bioprocess utilizes microorganisms to convert renewable feedstocks into target chemicals, fuels, or enzymes on an industrial scale. Fermentation remains the dominant processing method for high-volume bio-based products across various sectors.
- Genetic Engineering:This technology involves modifying an organism's genetic material to enhance its capacity for producing desired compounds or to create novel biocatalysts. Applications of genetic engineering are expanding capabilities in the pharmaceutical sector.
- Microbial Processing:This broad category encompasses various bioprocesses utilizing microorganisms for product synthesis or transformation.
- Bioconversion:Bioconversion processes transform biomass into valuable products using biological agents like enzymes or microbes.
Fermentation technology dominates current production, while Genetic Engineering is poised for rapid advancement.
Application:
Customer type variations strongly influence product specifications and regulatory compliance across white biotechnology applications. Each sector demands tailored solutions, impacting research and development focus.
- Energy Production:This application focuses on generating biofuels, such as ethanol and sustainable aviation fuel, from biomass to power transportation and industrial operations. Emerging mandates for sustainable aviation fuel create a large-scale opportunity.
- Pharmaceuticals:Biotechnology enables the production of active pharmaceutical ingredients, novel drug candidates, and protein-based therapeutics through advanced biomanufacturing processes. Protein engineering platforms accelerate the design of novel biocatalysts for drug manufacturing.
- Agriculture:White biotechnology in agriculture involves developing bio-pesticides, bio-fertilizers, and enzymes for crop enhancement.
- Food Industry:This segment utilizes enzymes, precision fermentation, and bio-based ingredients for food processing, preservation, and novel food product development.
Energy Production represents a significant strategic focus, with Pharmaceuticals driving high-value innovation.
End User:
The maturity level of end-user industries in adopting bio-based solutions impacts investment cycles and market readiness. Established sectors with strong sustainability goals show higher adoption rates.
- Chemical Industries:These industries integrate bio-based chemicals and polymers into their production processes, replacing petroleum-derived feedstocks for a more sustainable product portfolio. Strong uptake in chemical industries for producing bio-based polymers is a primary factor.
- Energy Companies:Energy companies invest in white biotechnology for producing biofuels and other bio-based energy carriers, aligning with decarbonization targets. Mandates for sustainable aviation fuel create a long-term opportunity for energy companies.
- Agricultural Sector:This sector uses bio-based products for crop protection, soil health, and animal feed additives.
- Food Manufacturers:Food manufacturers adopt bio-based ingredients, enzymes, and precision fermentation products to improve sustainability and product quality.
Chemical Industries demonstrate high adoption, while Energy Companies are increasing their investment in bio-based solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The white biotechnology market exhibits a differential consumption mix across various geographies. Demand for bio-based polymers in chemical industries is particularly strong in Germany and the United States. Conversely, emerging economies prioritize biofuels and sustainable ingredients for consumer goods.
United States
Bio-based chemicals and sustainable aviation fuel represent significant demand drivers. The US EPA's programs for sustainable chemistry and IRA incentives support market growth. Biotech hubs in the San Francisco Bay Area are accelerating novel biocatalyst development through protein engineering platforms.
Germany
Strong uptake for bio-based polymers in the chemical industries defines demand. The EU Green Deal's circular economy goals provide significant tailwinds for these technologies. Industrial clusters within North Rhine-Westphalia integrate bio-based chemicals into their extensive production networks.
China
Biofuels for energy security and bioplastics for sustainable packaging drive market expansion. China's dual carbon goals incentivize the adoption of bio-based alternatives across industrial sectors. The Yangtze River Delta region sees substantial investment in large-scale biorefineries for commodity bio-chemicals.
India
Bio-based ingredients for consumer goods and agricultural bio-pesticides are gaining traction. The PLI scheme encourages domestic manufacturing of advanced bio-based products and technologies. Bengaluru's biotech corridor is developing advanced fermentation techniques for high-value specialty food ingredients.
Brazil
Ethanol production from sugarcane remains a primary application for white biotechnology. The National Biofuels Policy (RenovaBio) promotes increased biofuel blending and production targets. São Paulo state anchors a robust ecosystem for sugarcane-derived ethanol and associated bio-chemical industries.
White Biotechnology Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another within the white biotechnology market. The competitive landscape is tiered, featuring specialized technology developers and large diversified chemical producers. Strategic archetypes include innovation-focused biotechs, integrated chemical giants, and enzyme solution providers. Diversified players pursue portfolio expansion, while specialized firms focus on technology licensing.
Specialized technology developers like Codexis Inc. occupy a position at the forefront of protein engineering platforms. These firms accelerate the design of novel biocatalysts for pharmaceutical and food manufacturing. Meanwhile, integrated chemical giants such as BASF SE exemplify the strategy of integrating bio-based chemicals into vast production networks. Novonesis represents a key enzyme solution provider, leveraging its extensive enzyme portfolio and fermentation scale for high-volume applications.
| Leading Market Players |
|---|
| DSM-Firmenich AG |
| Novonesis |
| Lonza Group Ltd |
| Codexis Inc |
| Evonik Industries AG |
| International Flavors & Fragrances Inc. |
| BASF SE |
| Amyris Inc |
| Corbion NV |
| Others |
Cost & Logistics Intelligence
Undercapacity in specialized protein engineering platforms drives supplier behavior and allows premium pricing for novel biocatalysts. This utilization level directly influences capital allocation decisions for expansion and technology development across the value chain.
Pricing Analysis
Long-term offtake agreements dominate pricing for commodity bio-chemicals, providing stability for large-scale producers. Price differentiation stems from product purity and specific application certifications, particularly for pharmaceutical ingredients. Pricing pressure stems from competition with highly optimized petroleum-derived products, especially when oil prices are low. Industrial chemical buyers exhibit high price sensitivity, while pharmaceutical manufacturers prioritize performance and regulatory compliance.
Supply Chain Analysis
Feedstock volatility, particularly for agricultural inputs like corn and sugarcane, represents a significant structural risk across the white biotechnology supply chain. Geographic supply concentration centers on agricultural powerhouses such as Brazil and the United States for feedstocks, while Europe and the US host key biomanufacturing hubs. Raw material dependencies include fermentation sugars and specific microbial strains. Distribution typically runs through established chemical and ingredient distributors, with direct sales for high-value custom enzymes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The white biotechnology market functions as a substitution defense against petroleum-derived chemicals, with incumbents needing to navigate the ongoing threat of cost-optimized fossil alternatives.
For Market Incumbents: Build intellectual property moats around novel bioconversion pathways to protect against emerging generic threats. Consolidate fermentation capacity in strategic geographies like the US and Europe to leverage existing infrastructure and regulatory tailwinds. Invest in process engineering expertise to reduce production costs, directly countering the price advantage of petrochemicals. Focus R&D on high-value specialty molecules that offer clear performance or sustainability differentiation.
For New Entrants and Emerging Players: Build out niche application expertise within precision fermentation, targeting underpenetrated segments like specialty food ingredients or advanced materials. The pharmaceutical sector, specifically for novel biocatalysts, represents a penetrable segment due to its high-value, performance-driven requirements. A go-to-market angle should emphasize superior performance or unique sustainability attributes, bypassing direct commodity competition.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downwards across novel bioconversion technologies, reducing barriers to entry for specialized firms. Long-term viability hinges on technologies that can valorize diverse waste streams, aligning with circular economy principles. Target acquisition archetypes include agile biotech firms with validated protein engineering platforms or advanced fermentation capabilities. A signal to watch is the increasing number of successful scale-up demonstrations for complex molecules.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Biofuels | Addresses growing mandates for sustainable aviation fuel, securing long-term supply contracts. |
| Precision Fermentation Platform Development | Enables efficient production of high-value food ingredients with improved sustainability metrics. |
| Waste-to-Chemicals Technology Licensing | Converts industrial and agricultural waste into valuable products, creating new revenue streams. |
| Investment in Synthetic Biology R&D | Accelerates the design of novel microorganisms for enhanced bioproduction efficiency. |
| Global Certification Standard Harmonization | Facilitates broader market acceptance and reduces regulatory hurdles for bio-based products. |
Research Approach
A standing panel of bioprocess engineers, regulatory affairs specialists, and procurement leads provided ongoing calibration for market sizing. This involved combining primary interviews with industry stakeholders and rigorous secondary validation. Data sources included academic journals, government reports from the EPA and EU Green Deal, and corporate sustainability disclosures. Both bottom-up and top-down triangulation methods were employed to ensure data accuracy.
Scenario-bracketing framed the market's future trajectory, accounting for variations in policy incentives and feedstock availability over the projection horizon. Segmentation dimensions modeled included product type, technology, application, and end-user, alongside an industry-specific focus on bioconversion efficiency. Compound annual growth rates were derived from historical trends and projected technological advancements. Key forecast inputs included anticipated regulatory mandates and agricultural feedstock price trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated chemical giants or rapid shifts in oil prices would shift outcomes. Forecasts reflect assumptions regarding continued R&D investment and stable regulatory support. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Pyruvate Synthase Market
Industrial Biotechnology
Biocatalysis and Biocatalysts Market
Industrial Biotechnology
Japan Biocatalyst Market
Industrial Biotechnology
Tannase Market
Industrial Biotechnology
Global Protein Hydrolysis Enzymes Market
Industrial Biotechnology
Americas Enzymes Market
Industrial Biotechnology
Cellulose Enzyme Market
Industrial Biotechnology
GCC Biocatalyst Market
Industrial Biotechnology
Glucoamylase Market
Industrial Biotechnology
Fungal Amylase Market
Industrial Biotechnology
Industrial Enzymes Market
Industrial Biotechnology
Biocatalyst Market
Industrial Biotechnology
United States Biocatalyst Market
Industrial Biotechnology
Global Specialty Enzymes Market
Industrial Biotechnology
Beta-Glucanase Market
Industrial Biotechnology
White Biotech Market