
 GCC Biocatalyst Market | 2026-2036
GCC Biocatalyst Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Biocatalyst Market Intelligence
Premium-grade immobilized enzymes for pharmaceutical synthesis is decoupling from commodity food-processing enzymes in pricing and technical specifications. Novozymes A/S anchors the Gulf region through its fermentation technology leadership and established distribution networks. BASF SE competes via its specialty enzyme portfolio tailored to regional petrochemical integration. DSM differentiates through co-factor formulations that address high-temperature industrial conditions prevalent in Saudi manufacturing.
Biocatalysts comprise protein-based enzymes, non-protein co-factors, and viable microbial or whole-cell systems that accelerate chemical reactions under mild temperature and pH conditions, typically operating at 30–60°C with substrate specificity exceeding 95% for pharmaceutical-grade applications. Their primary industrial purpose centers on replacing metal-catalyzed or solvent-intensive processes with selective biological pathways that reduce waste generation and energy consumption. Enzymes command the dominant product position due to established supply chains and reproducible batch performance, while microbial cells represent the fastest-expanding category as Gulf biorefineries adopt consolidated bioprocessing for lignocellulosic feedstock conversion. Immobilization technology leads the technology dimension because carrier-bound enzymes permit continuous-flow operations and catalyst recovery, whereas fermentation capacity is expanding fastest to serve regional biofuel mandates.
Saudi Food and Drug Authority and UAE Ministry of Industry and Advanced Technology shape biocatalyst import standards through Good Manufacturing Practice alignment and halal certification requirements for food-grade enzymes. Environmental regulations from the Gulf Cooperation Council Standardization Organization are pushing chemical manufacturers toward enzymatic processes that eliminate heavy-metal catalyst residues. Stakeholders must monitor evolving national biotechnology strategies in Saudi Arabia and the UAE, where sovereign investment funds are building domestic enzyme production capabilities that could reshape supplier relationships and technology licensing terms.
Market Dynamics
Immobilization technology is compressing batch-cycle economics for pharmaceutical-grade enzymes across Saudi Arabia and the UAE, while halal certification requirements from Gulf regulators are fragmenting supplier qualification pathways.
Growth Catalysts
- SFDA Green Chemistry Mandates:Saudi Food and Drug Authority tightening of purity thresholds for imported biocatalysts is forcing domestic pharmaceutical manufacturers toward enzyme-based synthesis pathways.
- Specialty Chemical Free Zones:UAE's Jebel Ali cluster concentration creates captive demand pull for high-performance immobilized enzymes in continuous-flow operations.
- Lignocellulosic Biorefinery Buildout:Consolidated bioprocessing adoption across Gulf biorefineries accelerates microbial cell category expansion for biofuel feedstock conversion.
Market Restraints
- Fermentation Input Volatility:Sugar feedstock price swings and specialized media component scarcity compress margin predictability for enzyme manufacturers serving the region.
- Carrier Material Supply Concentration:Immobilization support matrices—porous ceramics and functionalized polymers—remain concentrated among European specialty chemical suppliers, creating import dependency.
- Co-factor Stability Limitations:NADH and ATP regeneration inefficiencies at high-temperature Saudi manufacturing conditions constrain whole-cell catalysis adoption in petrochemical-adjacent processes.
Strategic Opportunities
- Domestic Fermentation Capacity:Saudi sovereign investment fund deployment into enzyme production infrastructure creates technology licensing and joint-venture white space for established technology holders.
- High-Temperature Co-factor Formulations:DSM's existing thermal-stability expertise points toward unmet need for engineered co-factor systems in 50–70°C industrial conditions prevalent across Gulf manufacturing.
- Halal-Certified Food-Grade Channels:UAE Ministry of Industry and Advanced Technology alignment with GCC Standardization Organization halal frameworks opens differentiated positioning for regionally certified enzyme suppliers.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Fermentation scale-up expertise and immobilization protocol optimization skills remain concentrated outside the Gulf, constraining domestic operational independence.
- Dual Certification Timelines:SFDA Good Manufacturing Practice alignment combined with halal authority approvals extends product registration cycles for food-grade enzyme entrants.
- Legacy Petrochemical Integration Friction:Existing metal-catalyzed process infrastructure at Saudi and UAE chemical complexes creates capital-intensive retrofit requirements for enzymatic pathway adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Biocatalyst Market |
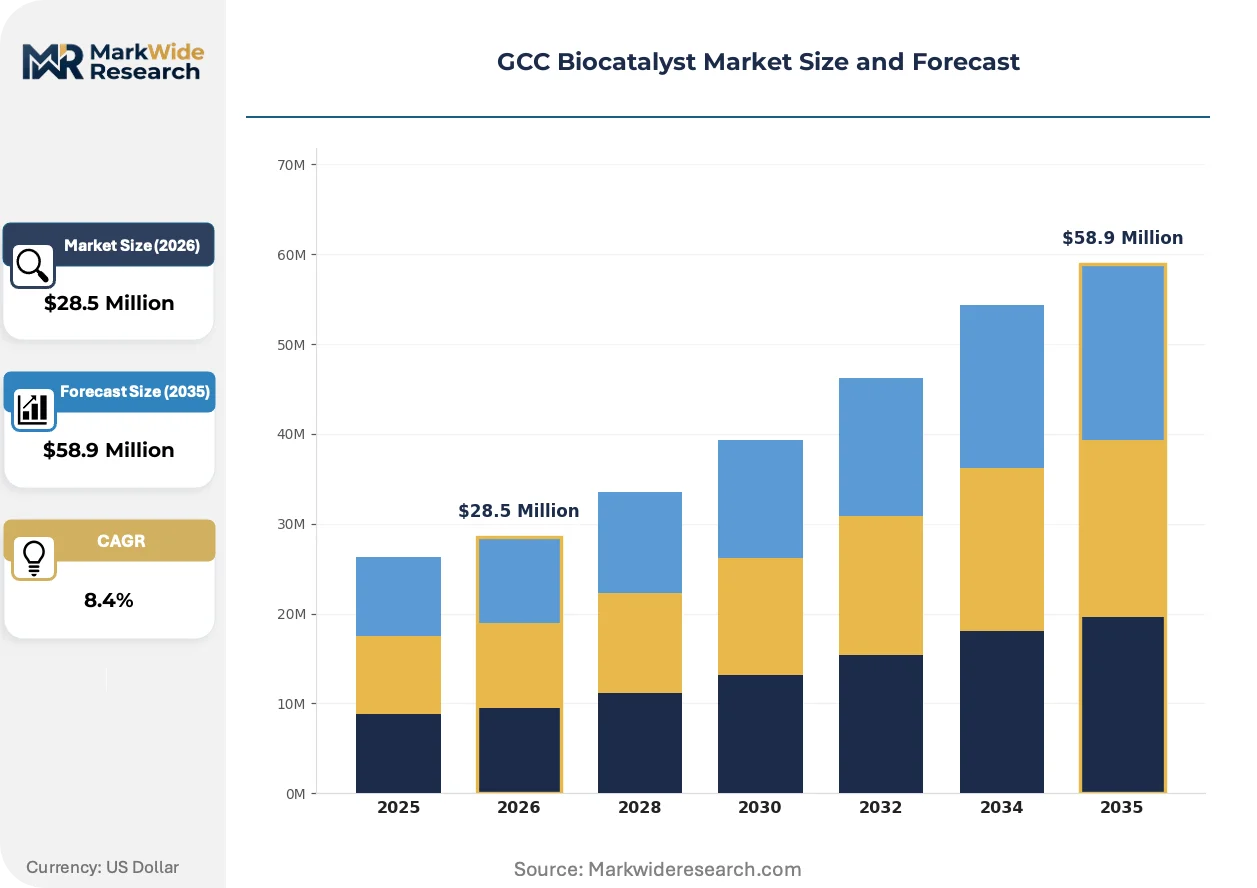
| Market Size in 2026 | $28.5 Million |
| Market Size in 2035 | $58.9 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Co-factors, Microbial Cells, Whole Cells Application: Beverages, Pharmaceuticals, Biofuels, Food Processing Technology: Immobilization, Filtration, Fermentation, Extraction End User: Food Industry, Chemical Industry, Pharmaceutical Companies, Agriculture |
| Companies Covered | DSM, Codexis Inc., Novozymes A/S, Amano Enzyme Inc., AB Enzymes GmbH, BASF SE, DuPont de Nemours Inc., Chr. Hansen Holding A/S, Evonik Industries AG, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Biocatalyst Market Strategic Shifts & Innovations
Continuous-flow biocatalysis is displacing batch operations across pharmaceutical synthesis, while regulatory convergence on green chemistry metrics is reshaping supplier qualification criteria throughout the Gulf.
Automated immobilization workstations are automating enzyme carrier loading and activity testing protocols. Saudi pharmaceutical manufacturers are adopting these systems at pilot scale before full production deployment. This automation is compressing catalyst validation timelines from months to weeks and reducing batch-to-batch performance variance.
GCC Standardization Organization environmental regulations are mandating elimination of heavy-metal catalyst residues in chemical manufacturing effluent streams. Industrial consequence includes accelerated enzymatic process substitution for palladium and rhodium-catalyzed transformations. Petrochemical-adjacent manufacturers in Saudi Arabia's Jubail Industrial City are retrofitting hydrogenation and oxidation steps with engineered oxidoreductases.
Buyer consolidation among UAE specialty chemical distributors is shifting procurement toward multi-year supply agreements with technical service bundling. Small and mid-sized pharmaceutical formulators in Dubai Science Park are losing direct supplier access and migrating to distributor-managed inventory programs. This channel restructuring is most visible in high-value immobilized enzyme categories where cold-chain logistics and application support carry premium pricing.
GCC Biocatalyst Market Segmentation
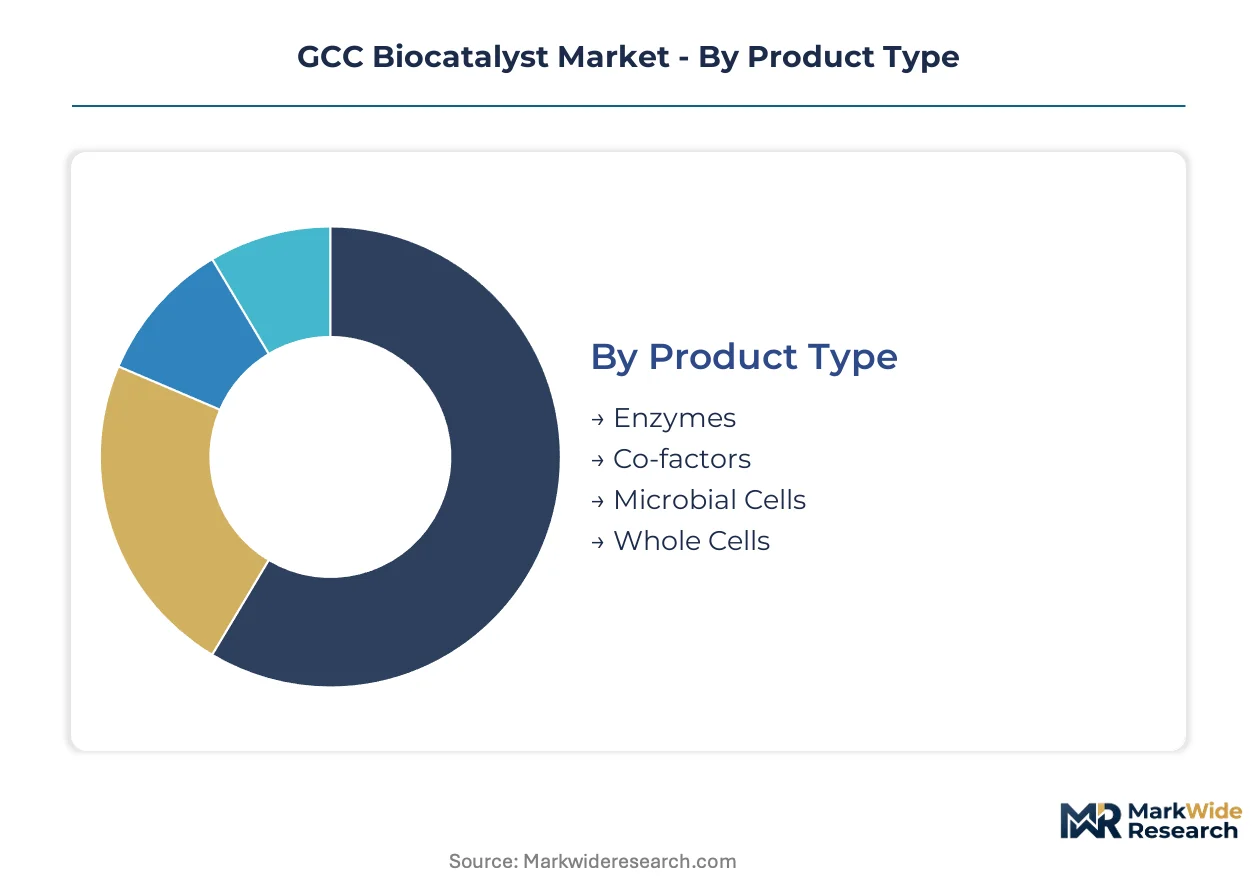
Biocatalyst procurement in the GCC fragments across four distinct dimensions, each carrying unique regulatory certification burdens and technical qualification pathways. Pharmaceutical-grade enzymes demand SFDA Good Manufacturing Practice alignment, while food-grade variants require halal authority approvals from multiple Gulf jurisdictions. Understanding these segment boundaries enables suppliers to navigate the dual-track approval systems governing regional market entry.
Product Type:
SFDA pharmaceutical-grade biocatalysts carry the heaviest certification burden, requiring documented purity thresholds and batch reproducibility protocols. Food-grade enzymes face parallel halal certification demands from UAE and Saudi religious authorities.
- Enzymes:Protein catalysts operating at 30–60°C with substrate specificity exceeding 95% for pharmaceutical applications. Demand concentrates in Saudi pharmaceutical manufacturing clusters around Riyadh and Jeddah, driven by SFDA tightening of green chemistry compliance mandates for imported synthesis materials.
- Microbial Cells:Viable bacterial, yeast, or fungal systems enabling consolidated bioprocessing. UAE biorefinery buildout near Jebel Ali free zones accelerates adoption for lignocellulosic feedstock conversion into biofuel precursors.
- Co-factors:Non-protein molecules including NADH and ATP essential for redox reactions. DSM's thermal-stability formulations address high-temperature manufacturing conditions prevalent across Saudi petrochemical-adjacent processes.
- Whole Cells:Intact cellular systems preserving native metabolic pathways. Baker's yeast and engineered E. coli strains serve regional food processing and specialty chemical synthesis applications.
Enzymes sit at the top of the volume ranking, with microbial cells climbing the fastest.
Application:
Cost tier stratification separates premium pharmaceutical-grade biocatalysts from commodity food-processing enzymes, with biofuel applications occupying an intermediate performance-price position.
- Pharmaceuticals:High-purity immobilized enzymes for active pharmaceutical ingredient synthesis. Saudi manufacturers expanding enzyme-based programs in Riyadh and Jeddah drive specification tightening around impurity profiles and batch consistency.
- Food Processing:Proteases, lipases, and carbohydrases for dairy, baking, and oil modification. Halal certification requirements from Gulf religious authorities fragment supplier qualification pathways for entrants targeting UAE and Saudi markets.
- Beverages:Enzymatic clarification and flavor modification systems. Regional juice concentrate production and date processing operations in Al Ain and Al Qassim generate steady demand pull.
- Biofuels:Cellulases and hemicellulases for lignocellulosic ethanol production. Saudi and UAE sovereign investment into domestic biorefinery capacity accelerates microbial cell category expansion for consolidated processing.
Pharmaceuticals command the premium pricing tier, while biofuels gain share fastest on state-backed infrastructure deployment.
Technology:
Application maturity separates established immobilization protocols from emerging fermentation capacity buildout across Gulf industrial zones.
- Immobilization:Carrier-bound enzyme systems enabling continuous-flow operations with catalyst recovery. Porous ceramics and functionalized polymer support matrices remain concentrated among European specialty chemical suppliers, creating import dependency for regional manufacturers.
- Fermentation:Bioreactor-based enzyme production and whole-cell cultivation. Saudi sovereign investment funds are building domestic production infrastructure that could reshape technology licensing terms for established holders.
- Filtration:Membrane-based separation and purification of biocatalytic products. Cross-flow and dead-end configurations serve downstream processing in pharmaceutical and food-grade applications.
- Extraction:Solvent and aqueous recovery of intracellular enzymes and co-factors. Less prevalent in Gulf markets due to environmental regulations from GCC Standardization Organization restricting organic solvent effluent.
Immobilization dominates current deployment, with fermentation expanding most quickly on domestic capacity investments.
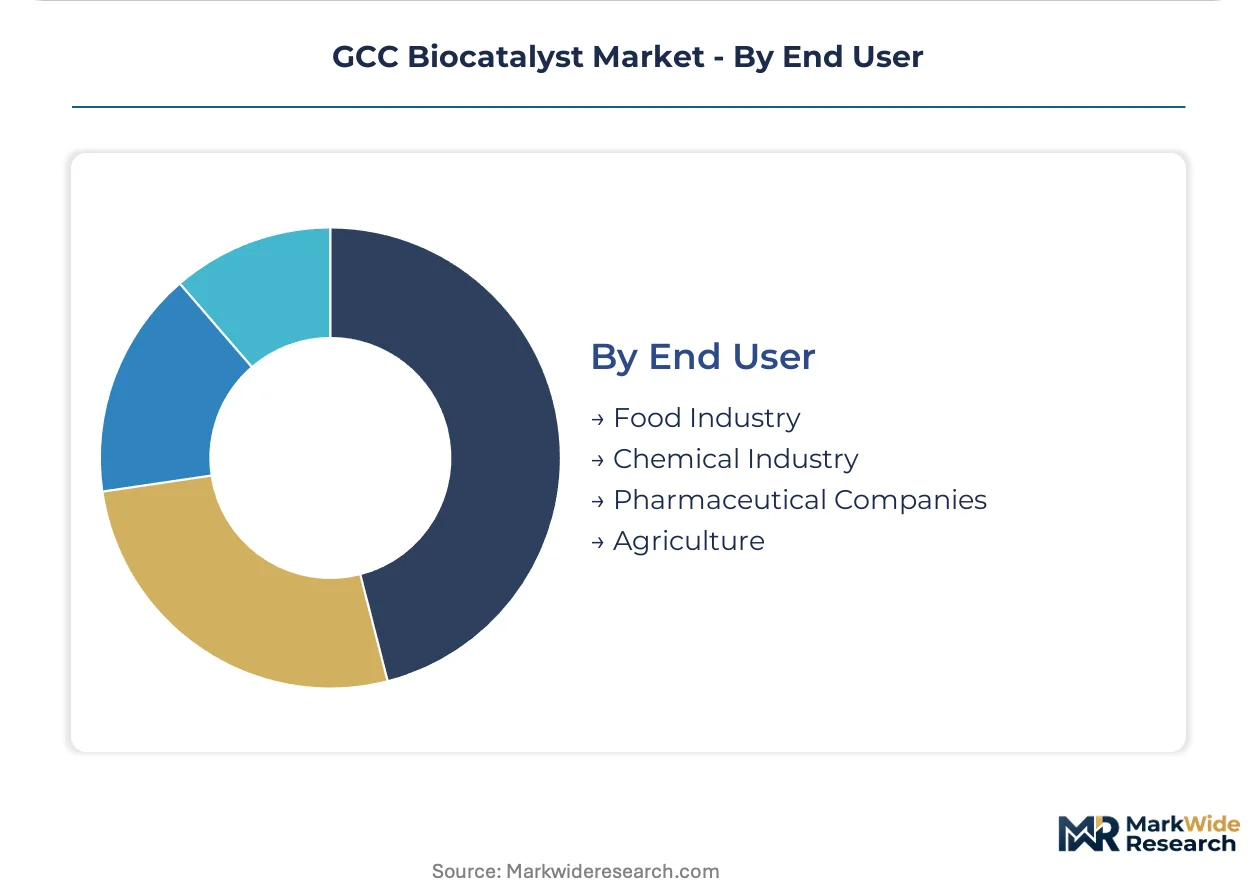
End User:
Customer type determines procurement channel structure, with pharmaceutical companies demanding direct technical service relationships while food industry buyers consolidate through distributor-managed inventory programs.
- Pharmaceutical Companies:SFDA-regulated manufacturers requiring GMP-aligned biocatalysts with documented purity certificates. Automated immobilization workstations compress catalyst validation timelines from months to weeks at Saudi pilot-scale facilities.
- Chemical Industry:Petrochemical-adjacent manufacturers in Jubail Industrial City retrofitting hydrogenation and oxidation steps with engineered oxidoreductases to eliminate heavy-metal catalyst residues per GCC environmental mandates.
- Food Industry:Halal-certified enzyme procurement for dairy, baking, and processing applications. UAE specialty chemical distributor consolidation shifts procurement toward multi-year supply agreements with technical service bundling.
- Agriculture:Feed enzyme applications and crop processing biocatalysts. Smaller addressable market in GCC context relative to pharmaceutical and food processing verticals.
Pharmaceutical companies anchor premium demand, with chemical industry adoption showing the steepest expansion trajectory on environmental compliance retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation engineering talent concentrates in Riyadh and Jeddah, anchoring Saudi Arabia's domestic enzyme production ambitions. UAE technical specialists cluster around Dubai Science Park and Jebel Ali free zones. This workforce distribution shapes where biocatalyst procurement decisions concentrate across the Gulf.
Saudi Arabia
Pharmaceutical manufacturers in Riyadh and Jeddah are expanding enzyme-based synthesis programs to meet tightening purity mandates. The Saudi Food and Drug Authority enforces Good Manufacturing Practice alignment for all imported biocatalysts. Jubail Industrial City hosts petrochemical-adjacent manufacturers retrofitting hydrogenation steps with engineered oxidoreductases.
United Arab Emirates
Specialty chemical free zones near Jebel Ali generate captive demand for high-performance immobilized enzymes in continuous-flow operations. The Ministry of Industry and Advanced Technology coordinates halal certification requirements with GCC Standardization Organization frameworks. Dubai Science Park consolidates pharmaceutical formulator procurement through distributor-managed inventory programs.
Qatar
State-backed biorefinery feasibility studies are evaluating consolidated bioprocessing for lignocellulosic feedstock conversion. The national investment authority screens enzyme technology licensing opportunities for domestic capacity buildout. Ras Laffan Industrial City infrastructure could support fermentation scale-up if sovereign deployment proceeds.
Kuwait
Food processing modernization programs in dairy and baking sectors sustain steady enzyme demand from regional suppliers. The national standards body tracks GCC environmental regulations mandating elimination of heavy-metal catalyst residues. Shuwaikh Industrial Area maintains smaller-scale biocatalyst consumption relative to Saudi and UAE clusters.
Bahrain
Pharmaceutical packaging and formulation activities create downstream enzyme demand without primary synthesis operations. The national health regulator references SFDA guidelines for import quality thresholds. Sitra Industrial Area chemical manufacturers represent a marginal addressable market for high-purity biocatalyst categories.
GCC Biocatalyst Market Key Industry Players
Top-tier vendors anchor premium-grade immobilized enzyme supply, while mid-scale regional distributors compete on halal certification speed and technical service bundling. The supplier base organizes around three archetypes: multinational fermentation technology leaders, specialty co-factor formulators, and regional distributor-integrators with cold-chain logistics capabilities. Capacity expansion and strategic technology licensing dominate competitive moves as sovereign funds build domestic production infrastructure.
Within the multinational technology tier, Novozymes A/S and BASF SE exemplify contrasting geographic anchoring strategies for Gulf market penetration. DSM occupies a position representing thermal-stability formulation specialization relevant to high-temperature Saudi manufacturing conditions. Codexis Inc. sits within the engineered enzyme archetype addressing pharmaceutical-grade specificity requirements. These three named entities collectively illustrate how supplier positioning fragments across performance attributes rather than consolidating around undifferentiated volume supply.
| Leading Market Players |
|---|
| DSM |
| Codexis Inc. |
| Novozymes A/S |
| Amano Enzyme Inc. |
| AB Enzymes GmbH |
| BASF SE |
| DuPont de Nemours Inc. |
| Chr. Hansen Holding A/S |
| Evonik Industries AG |
| Others |
Cost & Logistics Intelligence
Captive fermentation capacity in Saudi Arabia anchors both supply security and pricing leverage for domestic pharmaceutical manufacturers. Sovereign investment funds building enzyme production infrastructure compress import dependency while creating localized cost advantages against European-sourced immobilized enzymes.
Pricing Analysis
Service bundling separates distributor-managed inventory programs from direct technical service relationships. Three-tier pricing structure across premium pharmaceutical-grade, mid-tier food-grade, and economy biofuel-grade enzymes reflects certification burden differentials. Pricing pressure stems from carrier material import dependency and European specialty chemical supplier concentration. Small pharmaceutical formulators in Dubai Science Park exhibit highest price sensitivity due to distributor consolidation, while Saudi manufacturers with sovereign-backed domestic capacity gain cost insulation.
Supply Chain Analysis
Catalyst recovery and enzyme regeneration flows create reverse-logistics complexity for immobilized systems in continuous-flow pharmaceutical operations. Supply concentrates in Denmark, Germany, and the Netherlands for fermentation technology and carrier matrices. Raw material dependencies span sugar feedstocks, specialized media components, and functionalized polymer supports. Single-source vulnerability runs through European immobilization matrix suppliers. Distribution runs through UAE specialty chemical distributors consolidating procurement for mid-scale formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Saudi domestic production subsidies and UAE free-zone logistics efficiency creates structural cost advantages. SFDA regulatory alignment costs in Saudi Arabia trade off against Jebel Ali's halal certification speed and distributor density.
For Market Incumbents: Cement technology licensing relationships with Saudi sovereign funds before domestic fermentation capacity achieves operational independence. Deepen application engineering presence in Jubail Industrial City to capture petrochemical retrofit cycles. Defend against DSM's thermal-stability formulations by accelerating high-temperature co-factor R&D programs. For New Entrants and Emerging Players: Capture halal-certified food-grade enzyme white space in UAE dairy and baking modernization programs. Target Saudi pharmaceutical clusters with automated immobilization workstation partnerships that compress validation timelines. Lead with technical service bundling to offset Novozymes' distribution network advantages. For Investors and Strategic Acquirers: Roll-up economics work for regional distributor-integrators with cold-chain capabilities because buyer consolidation among UAE specialty chemical formulators is shifting procurement toward multi-year supply agreements with technical service bundling. Five-to-ten year viability hinges on positioning ahead of Saudi domestic capacity buildout. Monitor SFDA domestic production incentive announcements as inflection signals for import substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Fermentation Capacity Buildout | Saudi sovereign fund deployment reshapes technology licensing terms for established holders. |
| Halal Certification Fast-Track Investment | UAE Ministry of Industry alignment with GCC Standardization Organization creates differentiated positioning. |
| High-Temperature Co-factor R&D Partnership | Engineered NADH regeneration systems address 50–70°C manufacturing conditions in Jubail. |
| Automated Immobilization Workstation Deployment | Pilot-scale Saudi pharmaceutical facilities compress catalyst validation from months to weeks. |
| Long-term Supply Agreement with Technical Bundling | Distributor consolidation in Dubai Science Park shifts procurement toward multi-year relationships. |
Research Approach
Bottom-up pharmaceutical and food processing demand modeling reconciled against top-down fermentation capacity and trade flow tracking forms the analytical core. Primary interviews with SFDA regulatory affairs leads, UAE distributor procurement heads, Saudi plant managers, and European enzyme technology licensors combined with secondary validation from SFDA import filings, GCC Standardization Organization environmental regulations, and sovereign fund investment disclosures. Triangulation across these sources anchors volume estimates.
Historical trendline analysis of enzyme import volumes and domestic production announcements informed projection frameworks across the analysis window. Segmentation dimensions modeled include product grade tier, application vertical, technology maturity, and end-user procurement channel. CAGRs derived from weighted average of demand-pull factors and supply-push capacity additions. Forecast inputs incorporated SFDA green chemistry mandate implementation pace and UAE biorefinery buildout timelines.
Underlying measurement precision varies by segment; pharmaceutical-grade biocatalysts carry tighter precision than food-grade categories due to documented purity threshold requirements. Forecasts reflect assumptions around regulatory enforcement consistency and sovereign fund deployment schedules. Practitioners should monitor SFDA domestic production incentive announcements and UAE halal certification framework updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Hydrolase Enzymes Market
Industrial Biotechnology
Haematococcus Pluvialis Market
Industrial Biotechnology
Europe Biocatalyst Market
Industrial Biotechnology
Lipase Enzymes Market
Industrial Biotechnology
Unnatural Amino Acids Market
Industrial Biotechnology
Cellulose Enzyme Market
Industrial Biotechnology
Biocatalysis and Biocatalysts Market
Industrial Biotechnology
Tannase Market
Industrial Biotechnology
Redox Enzymes Market
Industrial Biotechnology
Biocatalyst Market
Industrial Biotechnology
China Specialty Enzymes Market
Industrial Biotechnology
Beta-Glucanase Market
Industrial Biotechnology
Esterase Market
Industrial Biotechnology
Styrene Monooxygenase Market
Industrial Biotechnology
Protease Enzyme Market
Industrial Biotechnology
Marine Enzymes Market