
 Carbohydrate Enzyme Preparation Market | 2026-2036
Carbohydrate Enzyme Preparation Market Size, Share, and Industry Trends Forecast 2026-2036
Carbohydrate Enzyme Preparation Market Intelligence
China is fragmenting carbohydrate enzyme production capacity as provincial biotech parks in Jiangsu and Shandong attract fermentation-focused investments. Novozymes leverages its Danish R&D heritage to sustain technology leadership in thermostable amylases for starch processing. BASF SE anchors its position through backward integration into specialty enzyme formulations for the baking sector. DSM-Firmenich AG differentiates via microbial strain optimization capabilities that reduce production costs for pharmaceutical-grade preparations.
Carbohydrate enzyme preparation comprises biocatalytic proteins derived from microbial fermentation, typically exhibiting activity optima between 50°C and 70°C and pH ranges of 4.5 to 6.5, designed to hydrolyze polysaccharides into fermentable sugars or functional oligosaccharides. These preparations serve as process aids across food manufacturing, biofuel production, and pharmaceutical synthesis where selective glycosidic bond cleavage determines product yield and quality. Amylase dominates product type volumes due to its ubiquity in starch liquefaction, while pullulanase commands premium positioning in high-glucose syrup applications requiring complete starch conversion. Powder delivery mode leads in shipping economics and shelf stability, though liquid formats are gaining traction in continuous brewing operations where direct dosing integration reduces handling steps.
FDA food additive regulations and EPA industrial biotechnology guidelines shape U.S. market access pathways, requiring GRAS self-affirmation or food contact notification for novel enzyme sources. REACH registration in Europe mandates toxicological dossiers for enzyme concentrates above one tonne annual volume, elevating compliance costs for smaller fermentation houses. China's NMPA and GB standards enforce potency labeling and contaminant limits that diverge from Codex Alimentarius parameters, creating dual-certification burdens for multinational suppliers. Stakeholders must monitor regulatory divergence between major jurisdictions to anticipate reformulation requirements and avoid supply chain disruptions from non-compliant inventory.
Market Dynamics
Starch processors are consolidating procurement around thermostable enzyme cocktails that slash liquefaction cycle times, while REACH and EU Green Deal compliance costs are forcing mid-tier fermentation houses toward contract manufacturing arrangements with larger biotech platforms.
Growth Catalysts
- Clean-label baking mandates:European bakers under EU Green Deal pressure are replacing chemical dough conditioners with fungal amylases and xylanases to achieve additive-free positioning on retail packaging.
- Cellulosic ethanol targets:US biofuel producers responding to EPA renewable volume obligations are deploying cellulase-hemicellulase blends to unlock C5 and C6 sugars from agricultural residues.
- Provincial biotech clustering:Jiangsu and Shandong fermentation parks in China are capturing amylase and glucoamylase capacity expansion through tax incentives and shared utilities infrastructure.
Market Restraints
- Feedstock cost volatility:Corn steep liquor and wheat bran prices fluctuate with agricultural commodity cycles, compressing margin predictability for glucoamylase producers serving high-fructose syrup manufacturers.
- Supply concentration risk:Thermostable alpha-amylase production for starch liquefaction clusters among three Danish and Dutch fermentation platforms, creating single-source vulnerability for Asian starch processors.
- Regulatory friction:China's NMPA potency labeling requirements diverge from Codex Alimentarius standards, forcing dual-certification overhead on multinational suppliers serving both domestic Chinese and export markets.
Strategic Opportunities
- Precision fermentation scale-up:Microbial strain engineering platforms are enabling pharmaceutical-grade oligosaccharide synthesis for prebiotic applications, opening margin premiums above commodity starch processing.
- Continuous brewing integration:Liquid enzyme dosing systems are displacing powder reconstitution in Brazilian and Mexican brewery operations, reducing handling labor and dosing variability.
- Carbon-intensity labeling:EU Green Deal carbon border adjustment mechanisms will favor enzyme producers with renewable-powered fermentation, creating first-mover advantage for biogas-integrated Danish and Dutch facilities.
Industry Challenges
- Strain optimization talent scarcity:CRISPR-guided microbial engineering for thermostability enhancement requires rare combinations of bioinformatics and fermentation science expertise, lengthening R&D timelines for novel enzyme variants.
- Legacy equipment retrofit costs:Continuous dosing infrastructure for liquid enzyme formats demands stainless steel tank farm upgrades that mid-sized Brazilian and Indian starch processors defer due to capital rationing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbohydrate Enzyme Preparation Market |
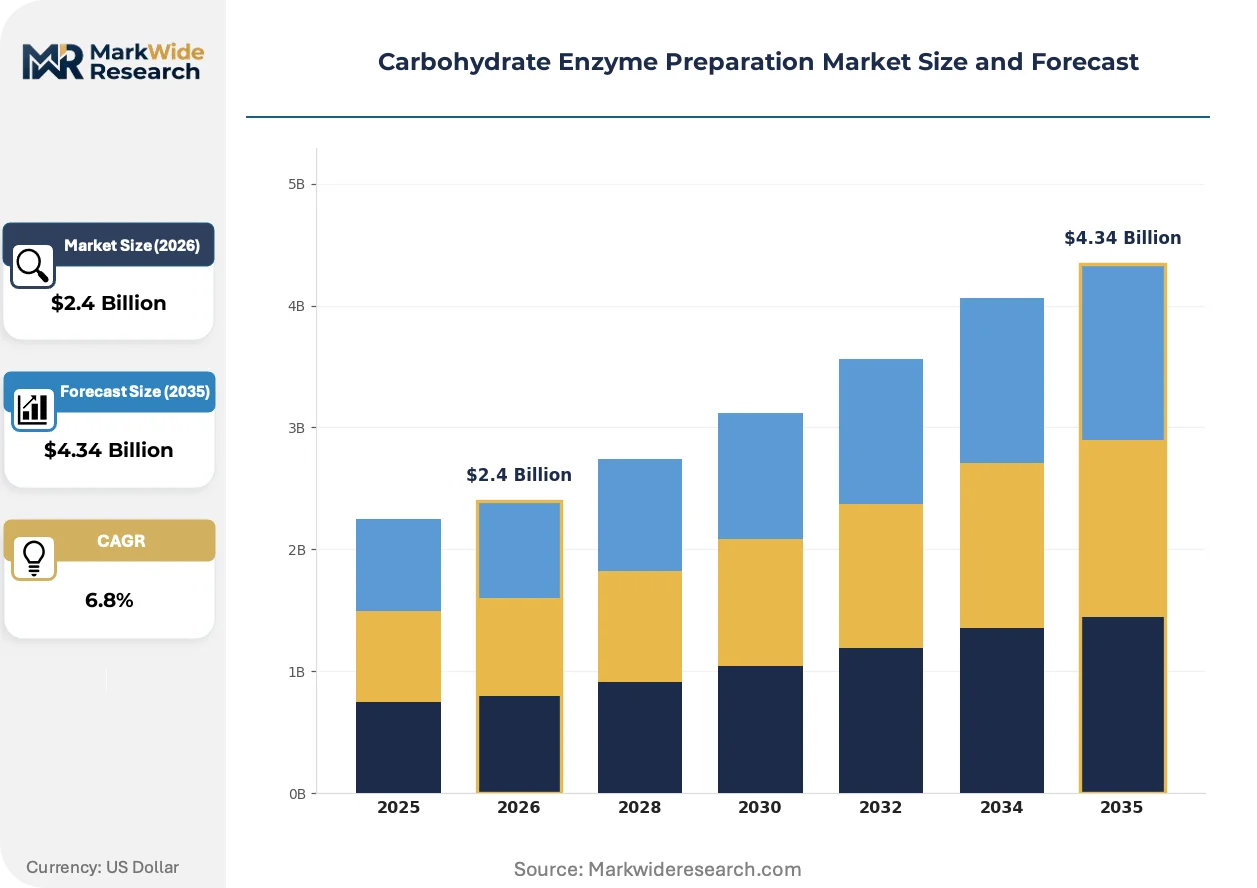
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Glucoamylase, Invertase, Pullulanase Application: Baking, Brewing, Animal Feed, Pharmaceutical End User: Food Industry, Beverage Industry, Feed Industry, Healthcare Delivery Mode: Liquid, Powder, Granulated, Concentrated |
| Companies Covered | Novozymes, BASF SE, DSM-Firmenich AG, DuPont de Nemours, Inc., Chr. Hansen Holding A/S, Amano Enzyme Inc., Advanced Enzyme Technologies Ltd., Kerry Group plc, AB Enzymes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbohydrate Enzyme Preparation Market Strategic Shifts & Innovations
Digital process control architectures are penetrating fermentation operations, while regulatory carbon accounting and buyer procurement centralization are restructuring how enzyme value chains capture and distribute margin.
Inline spectroscopy coupled with machine learning algorithms is digitizing real-time enzyme activity monitoring during starch liquefaction campaigns. North American corn wet millers are piloting these systems at three facilities to compress quality control cycle times from hours to minutes. The data infrastructure is digitizing batch record compliance and enabling predictive maintenance contracts that lock in multi-year supply agreements.
REACH registration dossiers for enzyme concentrates above one tonne annual volume now require expanded toxicological endpoints under ECHA's 2023 updated guidance. European fermentation houses are absorbing elevated compliance costs through consortium arrangements that share mammalian toxicity study expenses. The regulatory burden is concentrating supply relationships toward larger platforms with dedicated regulatory affairs functions, marginalizing smaller specialty enzyme houses.
Centralized procurement desks at multinational food manufacturers are consolidating enzyme category management under single-source frameworks with performance guarantees. Large baking and brewing groups in Western Europe are replacing fragmented regional supplier relationships with global master service agreements that bundle technical support, inventory management, and price volatility hedging. The purchasing transformation is most visible in Germany and the Netherlands, where co-manufacturing networks demand supply chain transparency down to fermentation feedstock origin.
Carbohydrate Enzyme Preparation Market Segmentation
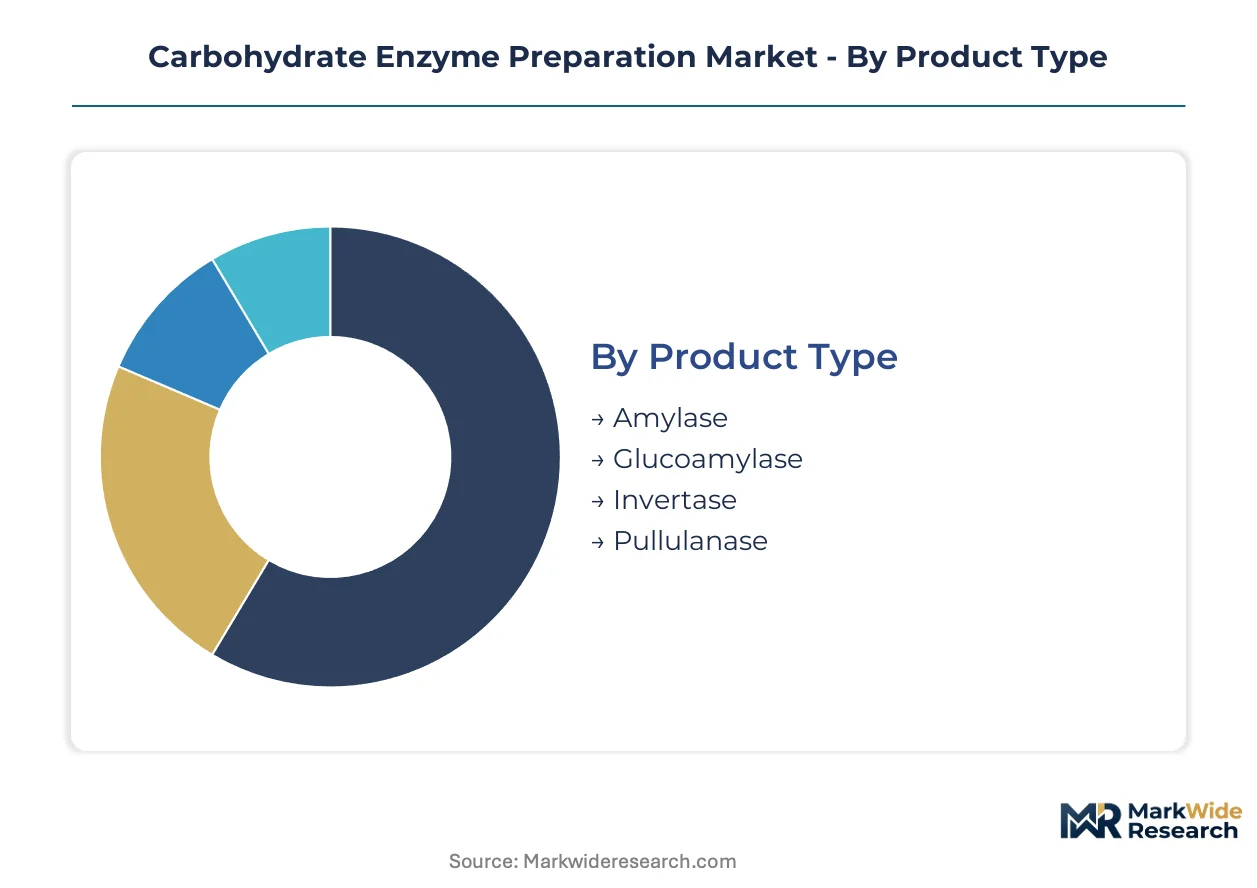
Carbohydrate enzyme preparation markets fragment across technical specifications and end-use requirements. Each segmentation dimension carries distinct margin profiles, regulatory burdens, and service intensity demands that shape supplier positioning.
Product Type:
After-sales technical support intensity varies sharply across enzyme classes, with thermostable variants demanding sustained formulation assistance.
- Amylase:These alpha-1,4-glucan hydrolases cleave starch polymers into dextrins and maltose units. Baking operations in Germany and the Netherlands consolidate procurement around fungal amylases that reduce dough conditioning chemical loads. Food processors demand on-site enzyme activity calibration support.
- Glucoamylase:Exo-acting enzymes hydrolyze terminal glucose units from starch chains with high specificity. Chinese high-fructose syrup manufacturers in Shandong province scale glucoamylase dosing to maximize glucose yield from corn wet milling. Suppliers provide continuous pH optimization consulting.
- Invertase:Beta-fructofuranosidase enzymes catalyze sucrose hydrolysis into glucose-fructose mixtures. Confectionery applications in Belgium and Switzerland drive demand for invertase with controlled activity profiles.
- Pullulanase:Debranching enzymes attack alpha-1,6-glycosidic linkages in amylopectin. Premium glucose syrup producers deploy pullulanase to achieve complete starch conversion.
Amylase holds the largest share; momentum sits with glucoamylase as Chinese starch processing capacity expands.
Application:
Cost tier differentiation separates commodity process aids from pharmaceutical-grade preparations with tenfold price multiples.
- Baking:Fungal amylases and xylanases replace chemical dough conditioners in clean-label bread production. EU Green Deal compliance pressures drive enzyme adoption across French and Italian industrial bakeries.
- Brewing:Beta-glucanases and limit dextrinases improve wort filtration and attenuation. Brazilian and Mexican breweries integrate liquid enzyme dosing systems for continuous operations.
- Animal Feed:Non-starch polysaccharide enzymes enhance nutrient digestibility in poultry and swine rations. Feed compounders in Iowa and North Carolina specify enzyme heat stability for pelleting survival.
- Pharmaceutical:Precision-fermented enzymes synthesize prebiotic oligosaccharides and active pharmaceutical intermediates. DSM-Firmenich and specialized biotech platforms capture margin premiums through microbial strain optimization.
Baking commands volume leadership; pharmaceutical applications climb the fastest as precision fermentation scales.
End User:
Customer type determines procurement sophistication, with multinational food manufacturers centralizing category management under global master service agreements.
- Food Industry:Starch processors and baked goods manufacturers constitute the foundational demand base. Corn wet millers in the US Midwest negotiate multi-year supply contracts with performance guarantees.
- Beverage Industry:Brewing and distilled spirits operations require enzyme cocktails for starch liquefaction and sugar conversion. Large brewing groups in Western Europe consolidate supplier relationships under single-source frameworks.
- Feed Industry:Compound feed manufacturers specify enzyme stability under thermal processing conditions. Asian poultry integrators drive demand growth as antibiotic reduction mandates spread.
- Healthcare:Pharmaceutical manufacturers source enzymes for diagnostic reagents and therapeutic oligosaccharide synthesis. Regulatory compliance burdens exceed food-grade requirements.
Food industry end users dominate procurement volumes; healthcare represents the steepest expansion trajectory.
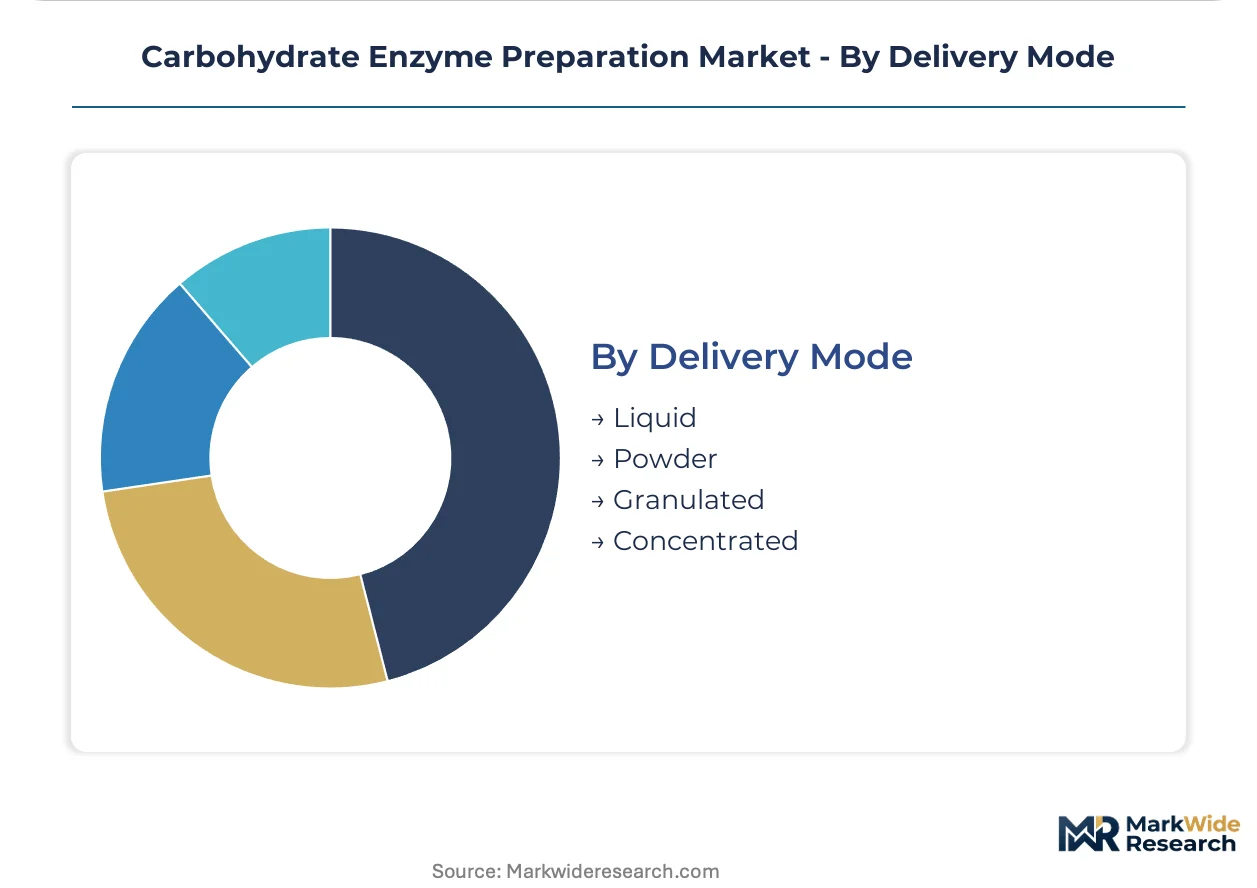
Delivery Mode:
Supply concentration in powder formats is displacing as liquid dosing infrastructure penetrates continuous processing operations.
- Liquid:Ready-to-dose enzyme solutions integrate directly into automated brewing and starch processing lines. Brazilian facilities retrofit tank farms to enable direct injection systems.
- Powder:Spray-dried enzyme concentrates optimize shipping economics and shelf stability. Powder dominates intercontinental trade and long-dated inventory positions.
- Granulated:Dust-free formulations improve handling safety in feed milling operations. Granulation technology reduces respiratory exposure for production workers.
- Concentrated:High-activity enzyme preparations minimize transport volumes for industrial-scale users. Concentrated formats require on-site dilution infrastructure.
Powder retains the largest share; liquid formats gain share fastest as continuous processing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Danish and Dutch fermentation platforms concentrate thermostable alpha-amylase capacity, while Chinese provincial biotech parks fragment glucoamylase supply. Regulatory divergence between REACH, FDA, and NMPA frameworks reshapes trade flows for industrial enzyme concentrates.
United States
Corn wet millers in Iowa and Illinois consolidate procurement around multi-year enzyme supply contracts with performance guarantees. EPA renewable volume obligations for cellulosic ethanol drive cellulase-hemicellulase deployment at agricultural residue processing facilities. The Midwest starch processing corridor anchors North American demand for thermostable liquefaction enzymes.
Germany
Industrial bakeries under EU Green Deal pressure replace chemical dough conditioners with fungal amylase formulations. ECHA's 2023 updated REACH guidance elevates toxicological study costs for enzyme concentrates above one tonne annual volume. The Rhine-Ruhr fermentation cluster houses regulatory affairs functions serving continental European markets.
China
High-fructose syrup manufacturers in Shandong province scale glucoamylase dosing to maximize glucose yield from corn wet milling. NMPA potency labeling requirements diverge from Codex Alimentarius standards, forcing dual-certification overhead on multinational suppliers. Jiangsu biotech parks attract fermentation investments through tax incentives and shared utilities infrastructure.
Brazil
Breweries retrofit tank farms to enable liquid enzyme direct injection systems for continuous operations. ANVISA regulatory frameworks govern food-grade enzyme importation and local formulation standards. São Paulo state beverage processors consolidate supplier relationships under single-source frameworks with technical support bundling.
Netherlands
Co-manufacturing networks demand supply chain transparency down to fermentation feedstock origin for carbon accounting compliance. EU Green Deal carbon border adjustment mechanisms favor biogas-integrated fermentation facilities. Rotterdam-area logistics hubs optimize powder enzyme shipping economics for intercontinental trade.
Carbohydrate Enzyme Preparation Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in strain optimization and precision fermentation. Three Danish and Dutch houses consolidate thermostable amylase capacity for starch liquefaction, while mid-tier fermentation houses migrate toward contract manufacturing arrangements. Competitive positioning stratifies across full-service biotech platforms, specialty enzyme houses, and regional fermentation contractors. Capacity expansion and strategic partnerships dominate competitive moves as REACH compliance costs concentrate supply relationships.
Among Danish heritage platforms, Novozymes anchors the thermostable enzyme tier through sustained R&D investment in starch processing applications. BASF SE exemplifies backward integration strategy into specialty formulations for the baking sector. DSM-Firmenich AG occupies a position in microbial strain optimization capabilities that reduce production costs for pharmaceutical-grade preparations.
| Leading Market Players |
|---|
| Novozymes |
| BASF SE |
| DSM-Firmenich AG |
| DuPont de Nemours, Inc. |
| Chr. Hansen Holding A/S |
| Amano Enzyme Inc. |
| Advanced Enzyme Technologies Ltd. |
| Kerry Group plc |
| AB Enzymes |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Danish and Dutch thermostable alpha-amylase platforms compresses margin predictability for Asian starch processors while simultaneously widening pricing tier spreads between commodity glucoamylase and precision-fermented pharmaceutical-grade preparations. This concentration dynamic forces buyers into long-term offtake contracts with technical support bundling, reshaping procurement economics across the value chain.
Pricing Analysis
REACH registration dictates the pricing tier structure by elevating compliance overhead for enzyme concentrates above one tonne annual volume, forcing consortium cost-sharing arrangements that concentrate supply relationships. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade oligosaccharide synthesis enzymes from food-grade starch processing preparations and commodity feed-grade formulations. Cost compression in standard-tier food-grade enzymes is intensifying because Chinese provincial biotech parks in Jiangsu and Shandong are scaling amylase and glucoamylase output for export markets. Multinational food manufacturers with centralized procurement desks exhibit lowest price sensitivity due to performance guarantee requirements, while mid-sized Brazilian and Indian starch processors defer capital upgrades and gravitate toward economy-tier powder formats.
Supply Chain Analysis
Contract manufacturing concentration among three Danish and Dutch fermentation platforms anchors thermostable alpha-amylase capacity for starch liquefaction applications. Raw material dependencies rest on corn steep liquor and wheat bran feedstocks whose agricultural commodity cycles compress margin stability, while stainless steel tank farm infrastructure for liquid enzyme dosing draws from Brazilian and Mexican equipment suppliers. Single-source vulnerability for Asian starch processors creates structural risk given minimal alternative sourcing for high-temperature liquefaction enzymes. Distribution runs through Rotterdam-area logistics hubs optimizing powder enzyme shipping economics for intercontinental trade, with liquid formats bypassing traditional warehousing through direct tanker injection at continuous brewing operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of CRISPR-guided microbial engineering talent capable of thermostability enhancement creates a persistent bottleneck that elongates R&D timelines and limits novel enzyme variant introduction, fundamentally constraining competitive dynamics across all tiers.
For Market Incumbents: Entrench technology leadership by deepening backward integration into specialty enzyme formulations for baking sector applications, while simultaneously expanding biogas-integrated fermentation capacity to capture EU Green Deal carbon border adjustment advantages. Novozymes-class platforms must defend against precision fermentation scale-up threats from microbial strain optimization specialists by locking in multi-year predictive maintenance contracts with North American corn wet millers piloting inline spectroscopy systems. For New Entrants and Emerging Players: Brazilian brewery retrofit demand for liquid enzyme direct injection systems represents the most penetrable white-space target, given deferred capital rationing by mid-sized processors and absence of established local formulation capabilities. Target pharmaceutical-grade oligosaccharide synthesis for prebiotic applications where margin premiums exceed commodity starch processing by order of magnitude, leveraging precision fermentation scale-up to bypass incumbent thermostable enzyme dominance. A technical service bundling go-to-market angle displaces powder reconstitution handling steps and captures continuous processing expansion momentum. For Investors and Strategic Acquirers: ECHA's updated REACH guidance reshapes the acquisition landscape by elevating toxicological study costs that marginalize smaller specialty enzyme houses and concentrate supply relationships toward larger platforms with dedicated regulatory affairs functions. Five-to-ten year viability favors contract manufacturing arrangements with mid-tier fermentation houses migrating toward biotech platform partnerships. Acquisition target archetypes include microbial strain optimization capabilities and precision fermentation scale-up infrastructure. The signal to watch is carbon-intensity labeling adoption velocity under EU Green Deal frameworks, which will determine first-mover advantage for renewable-powered fermentation facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Enables pharmaceutical-grade oligosaccharide synthesis capturing margin premiums above commodity processing. |
| Backward Integration into Specialty Formulations | BASF SE exemplifies this approach anchoring position through captive supply of baking sector enzyme cocktails. |
| Biogas-Integrated Fermentation Capacity | Danish and Dutch facilities capture EU Green Deal carbon border adjustment first-mover advantages. |
| Predictive Maintenance Contract Lock-In | North American corn wet millers piloting inline spectroscopy systems enable multi-year supply agreement capture. |
| Liquid Enzyme Dosing Infrastructure | Brazilian and Mexican breweries reduce handling labor and dosing variability through direct injection retrofit. |
Research Approach
Initial hypotheses were tested against primary input from fermentation science directors, regulatory affairs leads at enzyme manufacturers, starch processing procurement managers, and pharmaceutical formulation scientists, and refined through secondary validation against customs and trade data, ECHA REACH registration dossiers, SEC 10-K filings, and industry association reports from ACC and Cefic. Bottom-up triangulation across product type, application, end user, and delivery mode segmentation dimensions combined with top-down macroeconomic factor integration anchored volume and value estimates.
Demand-supply balance framing across the analysis window modeled enzyme procurement patterns by food processors, beverage manufacturers, feed compounders, and pharmaceutical synthesizers against fermentation capacity expansion in Danish heritage platforms, Chinese provincial biotech parks, and contract manufacturing arrangements. Segmentation dimensions included product type technical specifications, application cost tiers, end user procurement sophistication, and delivery mode infrastructure requirements. CAGRs were derived from installed capacity trajectories, regulatory compliance cost absorption curves, and continuous processing adoption rates in brewing and starch liquefaction operations.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic biotech firms or rapid precision fermentation scale-up by specialized platforms would shift outcomes beyond modeled parameters. Quarterly review of ECHA guidance updates, NMPA potency labeling enforcement patterns, and corn steep liquor commodity price volatility is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Glucose Oxidase Market
Food Biotechnology
Colostrum Market
Food Biotechnology
Perilla Protein Market
Food Biotechnology
Global Feed Enzymes Market
Food Biotechnology
Salmon Polynucleotide (PN) Market
Food Biotechnology
Prebiotics Market
Food Biotechnology
Trans-Galactooligosaccharides Market
Food Biotechnology
Red Seaweed Extract Market
Food Biotechnology
Bovine Colostrum Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Global GMO Testing Market
Food Biotechnology
Research-Grade Proteins Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Phycocyanin Market
Food Biotechnology
Zein Protein Market
Food Biotechnology
Bangladesh Starch and Starch Derivative Market