
 Lawful Interception Market | 2026-2036
Lawful Interception Market Size, Share, and Industry Trends Forecast 2026-2036
Lawful Interception Market Intelligence
Government agencies are rotating toward cloud-native and virtualized interception architectures, displacing traditional hardware-dependent procurement by telecom operators. Verint Systems leverages its speech analytics heritage to anchor positions in government-led deployments. SS8 Networks specializes in real-time data mediation for law enforcement workflows. Utimaco competes through cryptographic key management integration within hybrid deployment models.
Lawful interception denotes the legally authorized capture, processing, and delivery of communications content and metadata to designated authorities, typically requiring deep packet inspection capabilities, standardized handover interfaces such as ETSI or 3GPP specifications, and tamper-evident audit trails. Its primary purpose enables criminal and national security investigations while preserving chain-of-custody requirements for judicial admissibility. Hardware solutions dominate current installed bases but carry heavier maintenance burdens, while cloud-based solutions represent the fastest-expanding margin pool as agencies prioritize elastic scalability and reduced capital expenditure. Managed services attract mid-tier telecom operators lacking in-house forensic engineering capacity, concentrating recurring revenue with specialized vendors.
The European Telecommunications Standards Institute shapes technical mandates for handover interfaces across EU member states, while the FCC enforces Communications Assistance for Law Enforcement Act compliance upon US carriers, and India's Department of Telecommunications mandates centralized monitoring systems through licensing conditions. Regulatory fragmentation across jurisdictions forces vendors to maintain multiple certification tracks, elevating barriers for entrants lacking established compliance infrastructure. Stakeholders must monitor evolving encryption standards and quantum-resistant protocols that threaten existing interception methodologies.
Market Dynamics
Cloud-native interception architectures are displacing hardware-dependent systems across government procurement pipelines, compressing deployment timelines from months to weeks while forcing established vendors to rearchitect legacy product lines around containerized delivery models.
Growth Catalysts
- CALEA Mandates:The FCC enforces Communications Assistance for Law Enforcement Act compliance upon US carriers, compelling continuous infrastructure investment in intercept-ready switching equipment and standardized handover interfaces.
- Encrypted Traffic Proliferation:Law enforcement agencies demand advanced deep packet inspection capabilities to address signal obfuscation from end-to-end encryption protocols in consumer messaging platforms.
- India:The Department of Telecommunications mandates centralized monitoring systems through licensing conditions, creating recurring procurement obligations for domestic and international equipment suppliers.
Market Restraints
- Regulatory Fragmentation:ETSI mandates in Europe, FCC requirements in the United States, and India's DOT specifications force vendors to maintain parallel certification tracks, elevating compliance overhead.
- Technical Limitation:Quantum-resistant encryption protocols threaten existing interception methodologies, requiring fundamental reengineering of cryptographic key management systems.
- Substitution Threat:Open-source packet capture tools and in-house development by large national telecom operators reduce reliance on specialized commercial vendors.
Strategic Opportunities
- Managed Services Channel:Mid-tier telecom operators lacking in-house forensic engineering capacity create recurring revenue pools for vendors offering fully outsourced interception operations.
- France:CNIL oversight of data retention practices generates demand for privacy-preserving interception architectures that balance lawful access with GDPR-aligned audit controls.
- 5G Core Convergence:Service-based architectures in next-generation networks enable real-time mediation integration with network function virtualization orchestration layers.
Industry Challenges
- Forensic Engineering Talent Scarcity:Vendors and agencies compete for specialists capable of bridging telecommunications protocol expertise with judicial evidence handling protocols.
- Legacy Integration Complexity:Hybrid deployment models require seamless interoperability between virtualized cloud instances and existing hardware-based interception probes in carrier networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lawful Interception Market |
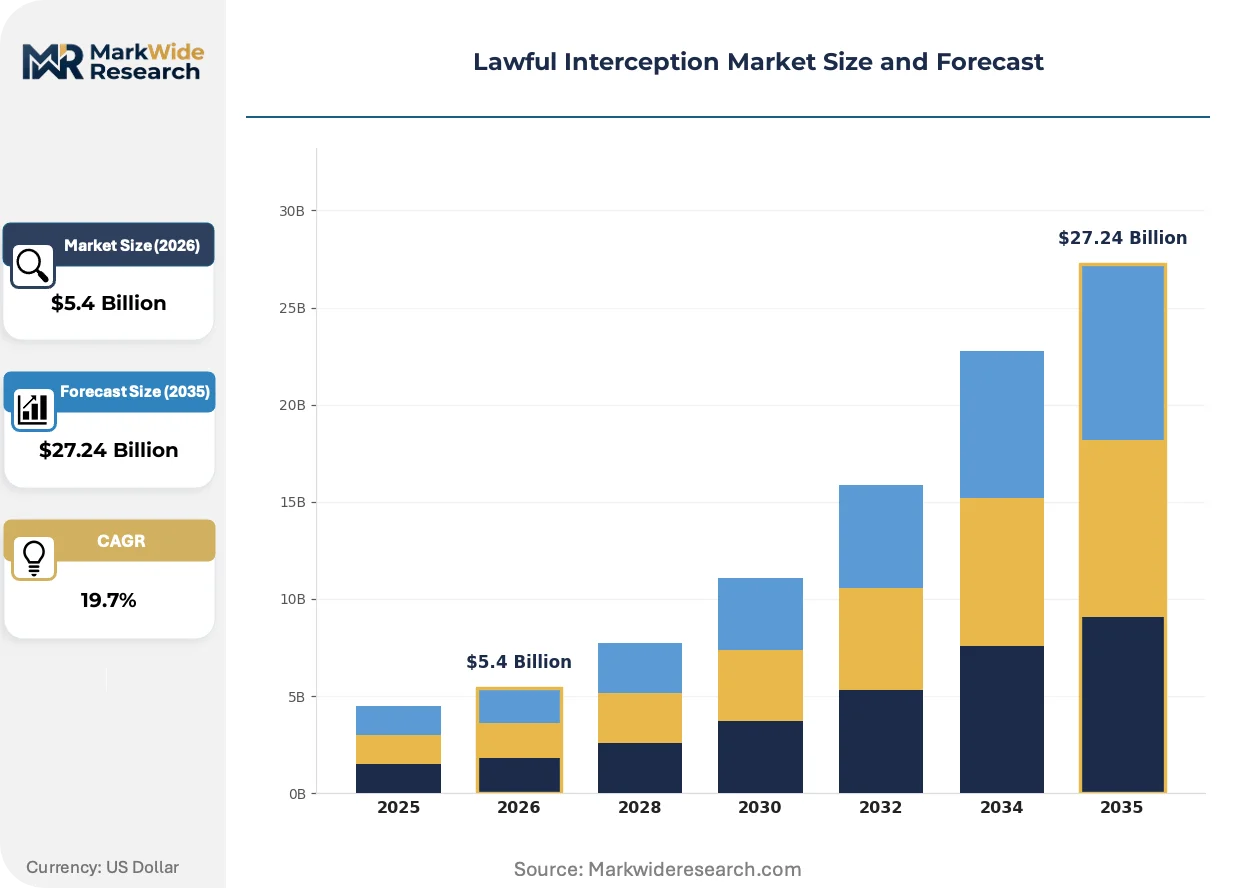
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $27.24 Billion |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Hardware, Software, Cloud-Based Solutions, Managed Services Application Area: Telecommunications, Internet Service Providers, Government Agencies, Law Enforcement Deployment Model: On-Premises, Cloud, Hybrid, Virtualized End User: Telecom Operators, ISPs, Security Agencies, Enterprises |
| Companies Covered | BAE Systems, Vocal Technologies, Verint Systems, Ericsson, Cisco Systems, SS8 Networks, AQSACOM, IPS S.p.A., Utimaco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lawful Interception Market Strategic Shifts & Innovations
Virtualization technologies are fragmenting traditional procurement patterns across the lawful interception value chain, enabling new entrants to compete through software-only delivery while incumbents accelerate containerization roadmaps.
Network function virtualization is decomposing monolithic interception appliances into disaggregated software components. Tier-one carriers in Germany and the United Kingdom are deploying these modular architectures at scale. This decomposition is compressing hardware refresh cycles and shifting margin pools toward orchestration software licenses.
GDPR Article 15 access requests and national implementing laws are tightening chain-of-custody documentation requirements across EU member states. Vendors must now embed tamper-evident audit trails as standard features rather than optional modules. France and Germany are driving the most stringent interpretations, with CNIL and BSI respectively issuing binding technical specifications.
Agency buyers are consolidating vendor relationships around platforms offering elastic scalability. Traditional perpetual licensing is yielding to consumption-based models in the United States and India. This pattern is most visible in federal and state-level procurement in the US, where budget volatility favors operational expenditure treatment over capital appropriations.
Lawful Interception Market Segmentation
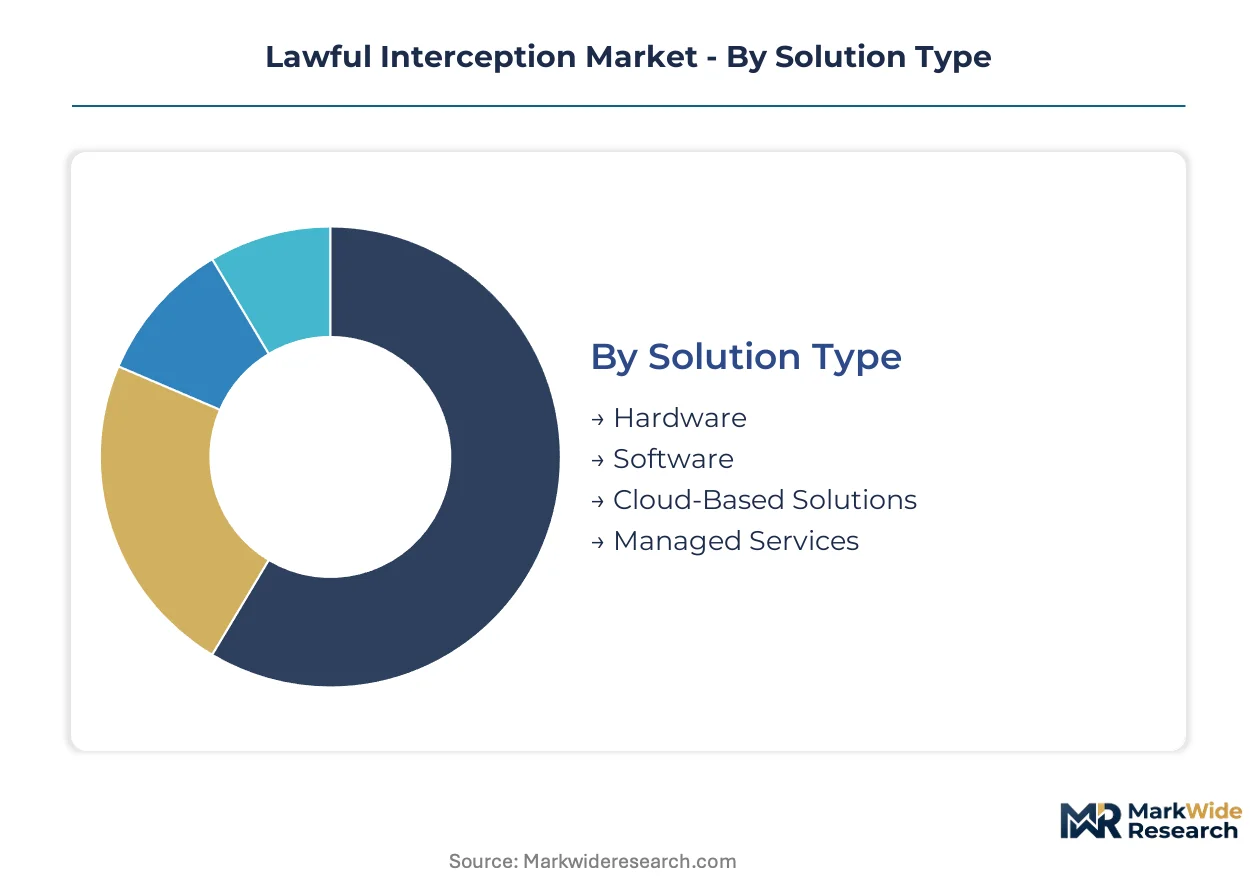
Segmentation in lawful interception reveals divergent procurement patterns across carrier types and government buyers. Each dimension exposes distinct technical requirements, compliance burdens, and margin structures that vendors must navigate.
Solution Type:
Domestic procurement concentrates in hardware and managed services, while cloud-based solutions attract cross-border licensing from agencies seeking elastic capacity.
- Hardware:Physical interception probes and mediation devices dominate installed bases at tier-one carriers. German and UK operators maintain extensive legacy deployments despite rising maintenance costs.
- Software:Deep packet inspection engines and protocol analyzers run on standard servers. Indian security agencies drive demand for software-only deployments that bypass hardware import restrictions.
- Cloud-Based Solutions:Containerized interception functions deliver scalability without capital expenditure. US federal procurement pipelines favor these models for budget flexibility.
- Managed Services:Fully outsourced interception operations appeal to mid-tier telecom operators lacking forensic engineering capacity. France's CNIL oversight creates demand for privacy-compliant managed architectures.
Hardware holds the largest share; momentum sits with cloud-based solutions.
Application Area:
Cost tier separation is pronounced: telecommunications carriers fund infrastructure from operational budgets, while government agencies command dedicated capital appropriations.
- Telecommunications:Mobile and fixed-line operators deploy intercept-ready switching equipment under regulatory compulsion. FCC CALEA enforcement in the United States and ETSI mandates in Europe shape procurement specifications.
- Internet Service Providers:Cable and fiber providers face expanding obligations as voice-over-IP and messaging traffic migrates from traditional telcos. Deep packet inspection investments climb at US regional ISPs.
- Government Agencies:National security and intelligence services procure direct access systems with specialized chain-of-custody features. India's Department of Telecommunications mandates centralized monitoring through licensing conditions.
- Law Enforcement:Police and judicial authorities rely on standardized handover interfaces from carrier networks. French and German agencies enforce the most stringent audit trail requirements under GDPR-aligned national laws.
Telecommunications generates the highest volume; government agencies show the steepest expansion trajectory.
Deployment Model:
Customer type determines architecture preference: security agencies favor on-premises control, while commercial carriers experiment with virtualized elasticity.
- On-Premises:Dedicated physical infrastructure within carrier facilities or government data centers. Remains mandatory for classified interception workloads in France and Germany.
- Cloud:Third-party hosted interception functions with consumption-based pricing. US state-level agencies adopt these models to bypass capital appropriation cycles.
- Hybrid:Split architectures retaining sensitive functions on-premises while offloading analytics to cloud instances. UK tier-one carriers deploy hybrid models for 5G core integration.
- Virtualized:Network function virtualization decomposes monolithic appliances into software components. German carriers lead European deployment of containerized mediation functions.
On-premises retains regulatory preference; virtualized deployments gain share fastest among commercial carriers.
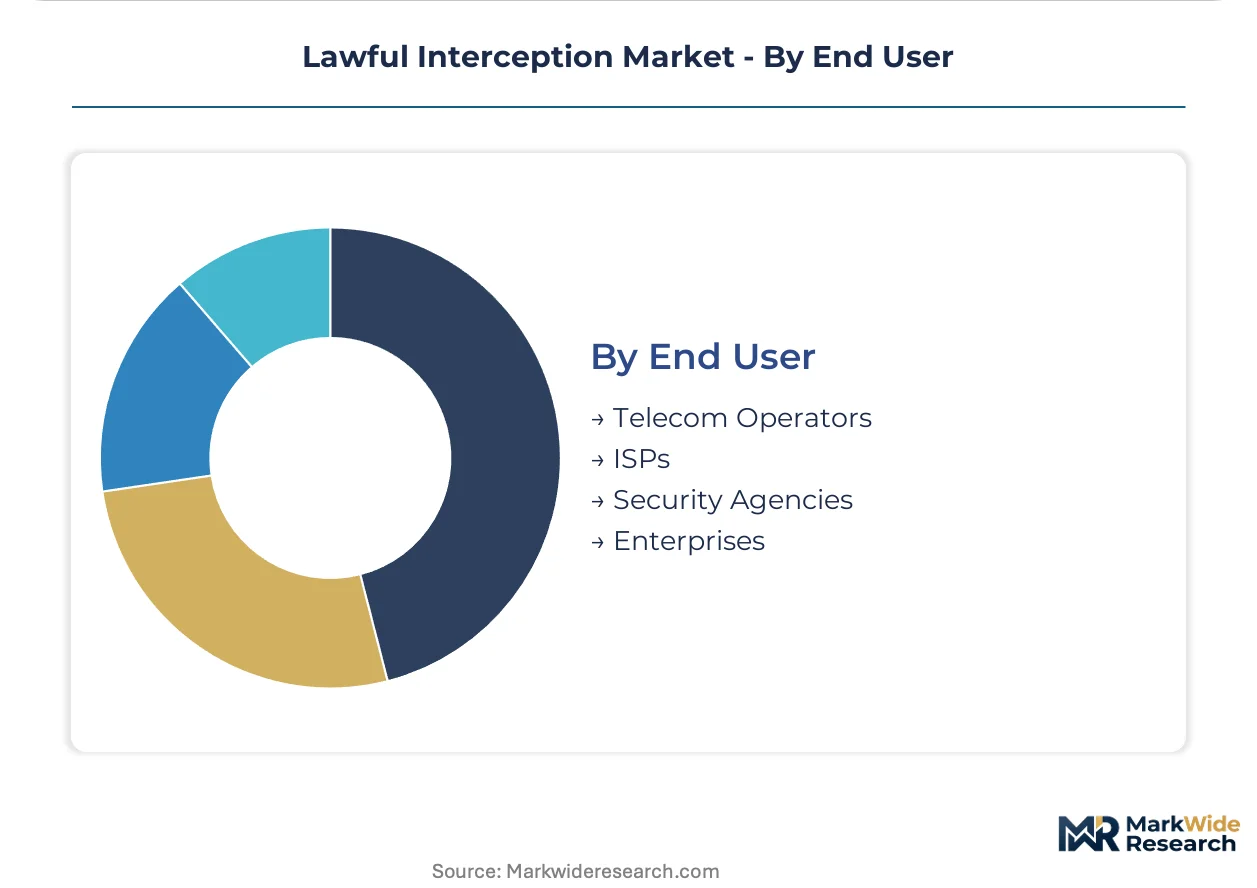
End User:
Supply concentration varies sharply: telecom operators consolidate procurement through established vendor relationships, while enterprises represent fragmented, price-sensitive demand.
- Telecom Operators:Mobile network operators and fixed-line incumbents constitute the foundational customer base. Verizon and Vodafone-scale carriers negotiate multi-year framework agreements with specialized vendors.
- ISPs:Broadband and cable providers face intercept obligations as voice and messaging traffic shifts to IP networks. Mid-tier US cable operators drive managed services adoption.
- Security Agencies:Intelligence and counter-terrorism units demand real-time mediation with minimal latency. India's intelligence services operate dedicated procurement channels outside standard telecom regulation.
- Enterprises:Financial institutions and critical infrastructure operators deploy internal interception for compliance and insider threat detection. GDPR Article 15 access requests motivate audit trail investments at French and German corporations.
Telecom operators dominate current revenue; security agencies command premium pricing tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel exports interception technologies to Western European security agencies and Indian intelligence services. German carriers import cloud-native mediation platforms from US vendors. French government procurement channels draw equipment from domestic and cross-border suppliers.
United States
Federal and state-level agencies drive consumption-based procurement for budget flexibility. FCC CALEA enforcement compels carriers to maintain intercept-ready switching infrastructure. Virginia and Maryland host dense concentrations of federal security contractors serving intelligence community requirements.
Germany
Bundesamt für Sicherheit in der Informationstechnik issues binding technical specifications for classified workloads. Tier-one carriers in North Rhine-Westphalia deploy containerized mediation functions at scale. Berlin-Brandenburg clusters anchor government procurement for national security applications.
United Kingdom
Investigatory Powers Act mandates technical capability notices upon telecommunications operators. BT and Vodafone-scale carriers negotiate multi-year framework agreements with specialized vendors. London and Southeast England concentrate vendor engineering resources and carrier headquarters functions.
France
CNIL oversight of data retention practices generates demand for privacy-preserving interception architectures. ANSM-aligned technical specifications govern chain-of-custody documentation for judicial admissibility. Île-de-France hosts the primary concentration of domestic equipment suppliers and agency procurement channels.
India
Department of Telecommunications mandates centralized monitoring systems through licensing conditions. Intelligence services operate dedicated procurement channels outside standard telecom regulation. Delhi-NCR and Bangalore anchor domestic system integrators serving government security requirements.
Lawful Interception Market Key Industry Players
Player mix skews toward defense-electronics conglomerates and specialized telecommunications vendors. Market structure concentrates around established vendors with multi-jurisdiction certification infrastructure. Two strategic archetypes dominate: integrated platform providers delivering end-to-end interception stacks, and component specialists focusing on cryptographic key management or real-time data mediation. Competitive moves center on containerization roadmaps and managed services partnerships with mid-tier carriers.
Within the integrated platform tier, BAE Systems and Ericsson exemplify defense-telecom hybrid positioning. Cisco Systems occupies a position bridging enterprise networking heritage with carrier-grade interception requirements. SS8 Networks and Utimaco represent specialists in real-time mediation and cryptographic integration respectively. Verint Systems anchors the speech analytics vector within government-led deployments. AQSACOM and IPS S.p.A. sit within the European specialist tier serving regulatory-intensive jurisdictions.
| Leading Market Players |
|---|
| BAE Systems |
| Vocal Technologies |
| Verint Systems |
| Ericsson |
| Cisco Systems |
| SS8 Networks |
| AQSACOM |
| IPS S.p.A. |
| Utimaco |
| Others |
Cost & Logistics Intelligence
Cloud-native containerization displacing hardware-dependent mediation appliances is simultaneously redrawing procurement geography toward US and Indian software vendors while collapsing price premiums previously commanded by European hardware specialists. This substitution dynamic compresses margin pools for legacy probe manufacturers and redistributes value capture toward orchestration-layer providers.
Pricing Analysis
The hardware-to-virtualization pricing gap separates three distinct tiers: legacy physical probes commanding premium maintenance contracts, transitional hybrid deployments at mid-market rates, and fully containerized solutions sold on consumption-based SaaS models. Price differentiation rests on certification depth—ETSI-compliant handover interfaces versus national-grade tamper-evident audit trails—and deployment scale. Cost compression in hardware tiers is intensifying because carrier procurement committees favor operational expenditure treatment. Mid-tier telecom operators exhibit highest price sensitivity; intelligence agencies show least.
Supply Chain Analysis
Extended lead times for cryptographic acceleration modules and specialized network processors have compressed vendor inventory buffers to four-to-six weeks. Component sourcing concentrates in Taiwan for semiconductors, Germany for precision engineering, and Israel for security-specific firmware. Raw material dependencies include FPGA chipsets, tamper-resistant hardware security modules, and deep packet inspection licensure. Single-source vulnerability in EAL4+ certified component supply creates procurement risk. Distribution runs through direct government procurement channels and carrier framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lawful interception sits in early-cycle expansion as 5G service-based architectures and encrypted traffic proliferation compel infrastructure refresh across carrier networks and security agencies.
For Market Incumbents: Fortify certification infrastructure across multiple jurisdiction tracks—simultaneous ETSI, FCC, and India's DOT compliance—to defend against specialized entrants lacking parallel approval capacity. Deepen managed services partnerships with mid-tier carriers facing forensic engineering talent scarcity. Containerization roadmaps must accelerate to match procurement velocity of cloud-native government buyers. For New Entrants and Emerging Players: Managed services gaps in France's CNIL-regulated environment and India's licensing-mandated deployments present accessible entry points. Privacy-preserving interception architectures for GDPR-aligned audit controls represent the most penetrable segment. Go-to-market leverage should anchor on consumption-based pricing models that bypass capital appropriation cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed specialists holding dormant ETSI certifications and established carrier relationships but lacking containerization roadmaps. Five-to-ten year viability hinges on quantum-resistant cryptographic integration capabilities. The signal to monitor is CALEA enforcement intensity and India's DOT licensing expansion pace.| Strategic Initiative | Industry Significance |
|---|---|
| Containerization Roadmap Acceleration | Compresses deployment timelines from months to weeks for federal agency buyers. |
| Multi-Jurisdiction Certification Investment | Creates compliance moats against software-only entrants lacking audit infrastructure. |
| Managed Services Partnership Expansion | Captures recurring revenue from mid-tier carriers lacking forensic engineering capacity. |
| Quantum-Resistant Cryptographic Integration | Future-proofs interception methodologies against encryption protocol obsolescence. |
| Privacy-Preserving Architecture Development | Aligns product portfolios with CNIL and BSI technical specifications for judicial admissibility. |
Research Approach
Desk research of ETSI technical specifications, FCC enforcement orders, and India's DOT licensing conditions preceded structured interviews with carrier network architects, government procurement officers, lawful interception system integrators, and forensic engineering specialists. Primary intelligence was cross-validated against carrier capex disclosures, security agency budget appropriations, and vendor certification registries. Bottom-up segmentation modeling was triangulated with top-down regulatory mandate analysis.
Variance decomposition across solution type, deployment model, and end-user category shaped the analytical framework over the projection horizon. Modeled dimensions included hardware-software-cloud solution mix, on-premises-virtualized-hybrid deployment architecture, and telecommunications-government-agency-law enforcement application split. CAGRs were derived from elasticity-adjusted procurement pipeline analysis incorporating 5G core migration timelines and encryption protocol evolution curves.
Forecasts assume regulatory continuity in FCC CALEA enforcement, ETSI mandate adherence, and India's DOT licensing framework; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Riot Control System Market
Security and Surveillance
Vietnam Private Security Market
Security and Surveillance
Middle East Manned Security Services Market
Security and Surveillance
Destructible Security Labels Market
Security and Surveillance
Asia-Pacific Urban Security Screening Market
Security and Surveillance
Global Physical Security Software Market
Security and Surveillance
North America Security Testing Market
Security and Surveillance
Maritime Security Market
Security and Surveillance
Security Services Market
Security and Surveillance
North America People Screening Market
Security and Surveillance
Threat Detection Systems Market
Security and Surveillance
Private Military Security Services Market
Security and Surveillance
Door and Window Alarm Market
Security and Surveillance
Situational Awareness System Market
Security and Surveillance
Baggage Scanner Market
Security and Surveillance
Resale Authentication Services Market