
 Germany Personal Protective Equipment (PPE) Market | 2026-2036
Germany Personal Protective Equipment (PPE) Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Personal Protective Equipment (PPE) Market Insights
Modular PPE kit configurations is expanding across German industrial procurement, letting buyers mix respiratory, hand, and eye protection rather than accepting fixed bundles. Drägerwerk AG & Co. KGaA leverages its integrated breathing apparatus and gas detection portfolio to anchor premium positioning in chemical plant contracts. UVEX Safety Group sustains dominance across eye and head protection through its vertically controlled German manufacturing base. Honeywell International competes on connected safety platforms that merge PPE with real-time environmental monitoring.
Personal protective equipment encompasses garments, helmets, gloves, and respiratory devices engineered to shield workers from mechanical, chemical, thermal, and biological hazards, typically constructed from materials meeting EN ISO performance thresholds for impact resistance and permeation blocking. Its primary purpose is reducing occupational injury incidence and employer liability within hazardous work environments. Protective clothing and gloves represent mature volume categories where procurement runs on multi-year framework agreements, while industrial safety applications command the deepest margin pools due to certification complexity and replacement frequency. Medical use and chemical handling segments exhibit faster structural expansion as German healthcare employers and BASF-cluster chemical operators upgrade to higher-specification barrier materials.
DGUV (German Social Accident Insurance) and the Federal Institute for Occupational Safety and Health (BAuA) enforce product conformity through CE marking under the EU PPE Regulation 2016/425, compelling manufacturers to maintain notified body certifications for market access. KBA and state-level trade supervisory offices conduct workplace inspections that convert regulatory non-compliance into immediate procurement orders. Stakeholders must monitor the EU's forthcoming restriction proposals under REACH for per- and polyfluoroalkyl substances, which threatens existing chemical-resistant glove and garment formulations.
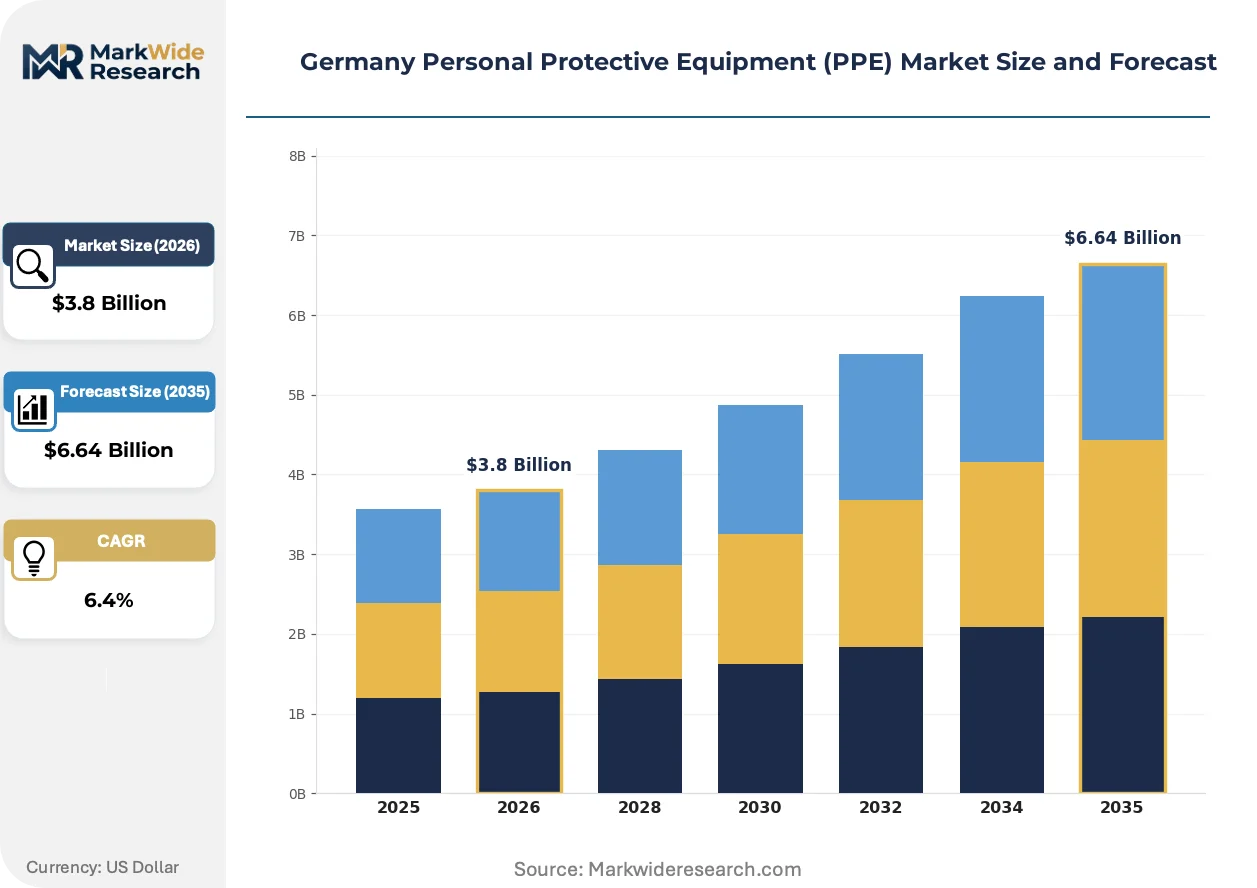
Market Dynamics
German PPE procurement is tightening around modular kit configurations that let industrial buyers unbundle respiratory, hand, and eye protection rather than accepting fixed supplier bundles, compressing traditional full-line manufacturers into component specialization.
Growth Catalysts
- Occupational Safety Act enforcement:DGUV inspection protocols are converting non-compliance findings into immediate procurement orders across Bavarian automotive plants.
- Chemical cluster expansion:BASF Ludwigshafen and surrounding operators are upgrading to higher-specification barrier materials for chemical-resistant gloves and garments.
- Healthcare infrastructure:German hospital employers are replacing legacy protective clothing with EN ISO-certified barrier systems amid post-pandemic stockpile refresh cycles.
Market Restraints
- PFAS formulation dependency:REACH restriction proposals targeting per- and polyfluoroalkyl substances threaten existing chemical-resistant glove and garment chemistries.
- Notified body certification backlog:EU 2016/425 conformity assessment delays are extending time-to-market for new respiratory device introductions.
- Raw material concentration:Aramid fiber supply for cut-resistant gloves concentrates among a limited set of European specialty chemical producers.
Strategic Opportunities
- Connected safety platforms:Real-time environmental monitoring integration with respiratory protection is opening premium positioning in chemical handling applications.
- Rhineland-Palatinate chemical corridor:Underpenetrated mid-tier operators between Ludwigshafen and Krefeld present kit-upgrade potential.
- DGUV prevention campaigns:Targeted sectoral safety initiatives are creating funded procurement windows for hearing and eye protection in metalworking SMEs.
Industry Challenges
- CE marking documentation complexity:Technical file maintenance for multi-component PPE kits is stretching regulatory affairs capacity at mid-sized manufacturers.
- Legacy system integration:Connected PPE platforms face interoperability friction with existing plant safety management software in German automotive assembly lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Personal Protective Equipment (PPE) Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloves, Helmets, Safety Shoes, Protective Clothing End User: Construction, Healthcare, Manufacturing, Oil & Gas Material: Rubber, Polycarbonate, Kevlar, Polyester Application: Industrial Safety, Medical Use, Fire Safety, Chemical Handling |
| Companies Covered | UVEX Safety Group, Brady GmbH, Drägerwerk AG & Co. KGaA, 3M, Franz Mensch GmbH, MSA Deutschland GmbH, Kroschke Sign-International GmbH, Honeywell International, Bosch, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Personal Protective Equipment (PPE) Market Trends and Innovations
Sensor-embedded respiratory devices and modular procurement platforms are compressing traditional PPE value chains, forcing manufacturers to choose between hardware commoditization and data-service monetization.
Smart breathing apparatus with integrated gas detection and biometric monitoring is consolidating premium positioning in German chemical plant contracts. Bayer Leverkusen and Evonik Marl operations are specifying these systems for confined-space entry protocols. The technology is consolidating standalone gas detector and basic SCBA markets into unified connected safety platforms.
EU REACH restriction proposals for PFAS in chemical-resistant textiles are forcing reformulation investments across German garment manufacturers. BAuA guidance documents are accelerating substitution timelines for fluorinated water-repellent finishes. Bavarian automotive paint shops are most affected, with operators testing silicone-based alternatives ahead of anticipated enforcement.
Framework agreement unbundling is fragmenting volume concentration previously held by full-line distributors. German industrial buyers are awarding separate respiratory, hand, and eye protection contracts to specialized component suppliers. This pattern is most visible in Baden-Württemberg's automotive supplier tier, where procurement teams are negotiating direct relationships with category-specific manufacturers.
Germany Personal Protective Equipment (PPE) Market Segmentation
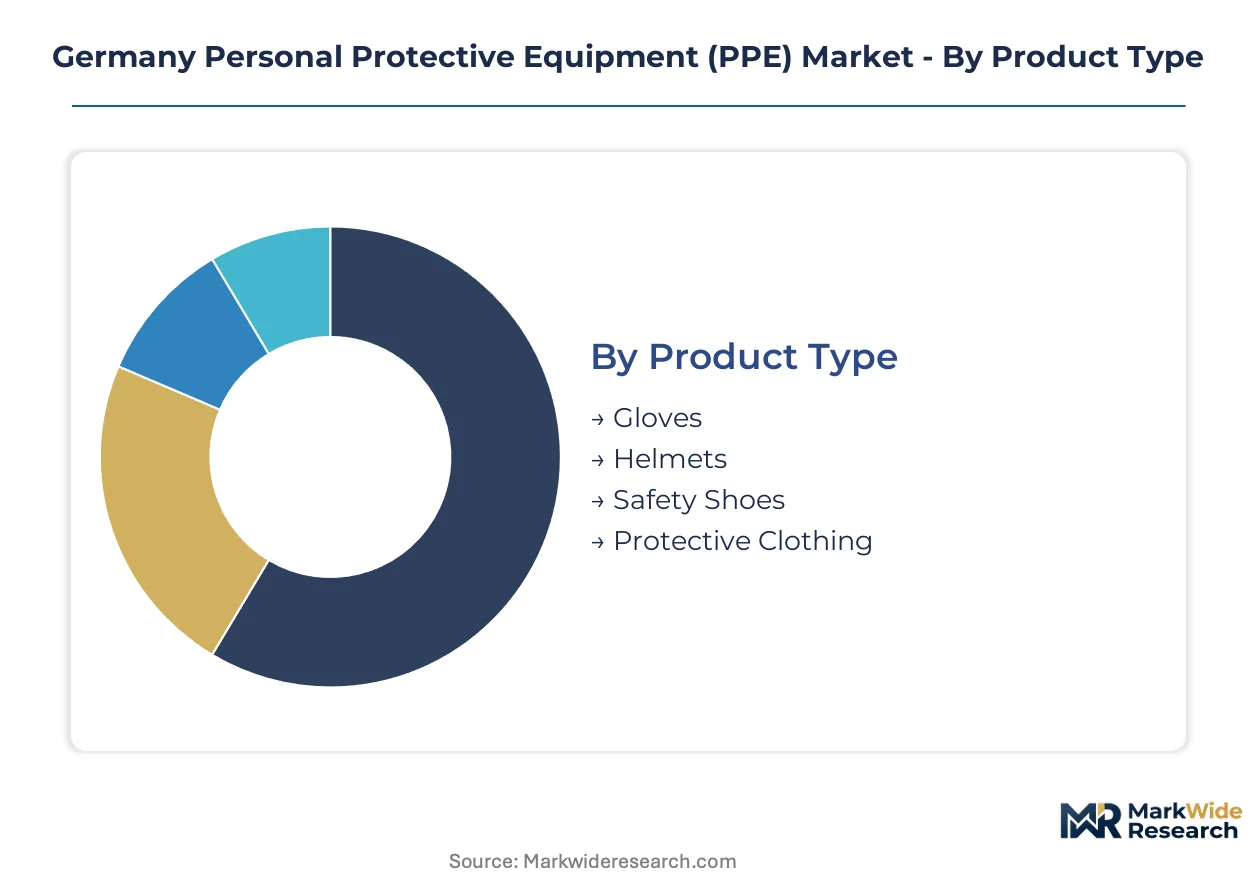
German PPE procurement patterns diverge sharply across product categories, with chemical-resistant materials commanding certification premiums and healthcare applications driving specification upgrades. Segmentation reveals where capital deployment concentrates and which material technologies face regulatory pressure.
Product Type:
Capital intensity peaks in respiratory and integrated protection systems, while hand and foot protection operate on volume manufacturing economics with lower barrier to entry.
- Gloves:Cut-resistant and chemical-barrier variants dominate procurement spend, with aramid fiber formulations and nitrile multilayer constructions specified across BASF Ludwigshafen operations. DGUV inspection protocols are accelerating replacement cycles for high-dexterity assembly applications in Baden-Württemberg automotive plants.
- Helmets:Industrial head protection integrates mounting systems for visors and hearing protection, with KBA workplace inspections mandating EN 397 compliance across construction sites. Bavarian infrastructure projects are specifying modular helmet platforms that accommodate task-specific attachments.
- Safety Shoes:S3 and S5 protection classes with composite toe caps and puncture-resistant midsoles serve logistics and manufacturing floors. German footwear manufacturers maintain domestic production for rapid customization to plant-specific hazard profiles.
- Protective Clothing:Disposable coveralls and reusable chemical suits span divergent cost structures, with Tyvek-equivalent breathable barriers replacing legacy cotton blends in pharmaceutical cleanrooms.
Gloves absorb the bulk of installed capacity; protective clothing is expanding most quickly amid healthcare stockpile refresh cycles.
End User:
Demand concentration tracks Germany's industrial geography, with chemical corridor density and automotive cluster scale creating distinct procurement rhythms.
- Construction:Fall protection and high-visibility ensembles dominate, with DGUV prevention campaigns funding hearing protection upgrades for metalworking subcontractors.
- Healthcare:EN ISO 22612-certified barrier gowns and splash-resistant aprons are replacing legacy cotton garments, with hospital employers in North Rhine-Westphalia specifying higher-breathability laminates.
- Manufacturing:Bavarian automotive assembly lines and Rhineland-Palatinate chemical plants drive the deepest specification complexity, with connected safety platforms penetrating confined-space protocols.
- Oil & Gas:Flame-resistant coveralls and emergency breathing apparatus serve limited but high-value maintenance operations, with North Sea supply chain linkages influencing procurement standards.
Manufacturing commands the largest procurement volumes; healthcare is climbing the fastest as post-pandemic specification upgrades persist.
Material:
Raw material selection determines regulatory compliance pathways and substitution risk exposure, particularly under REACH restriction timelines.
- Rubber:Nitrile and neoprene formulations provide chemical permeation resistance for glove and boot applications, with latex alternatives retreating amid allergy liability concerns.
- Polycarbonate:Impact-resistant lens materials anchor eye protection portfolios, with UVEX Safety Group maintaining captive extrusion capacity for optical clarity control.
- Kevlar:Cut-resistant glove liners and heat-protective apparel depend on European aramid fiber supply concentration, with German manufacturers securing multi-year framework agreements for filament access.
- Polyester:High-visibility fabrics and moisture-wicking base layers serve comfort-critical applications, with recycled content specifications emerging in public procurement tenders.
Kevlar-dependent segments face supply concentration constraints; polyester-based products are gaining share fastest in sustainability-driven tenders.
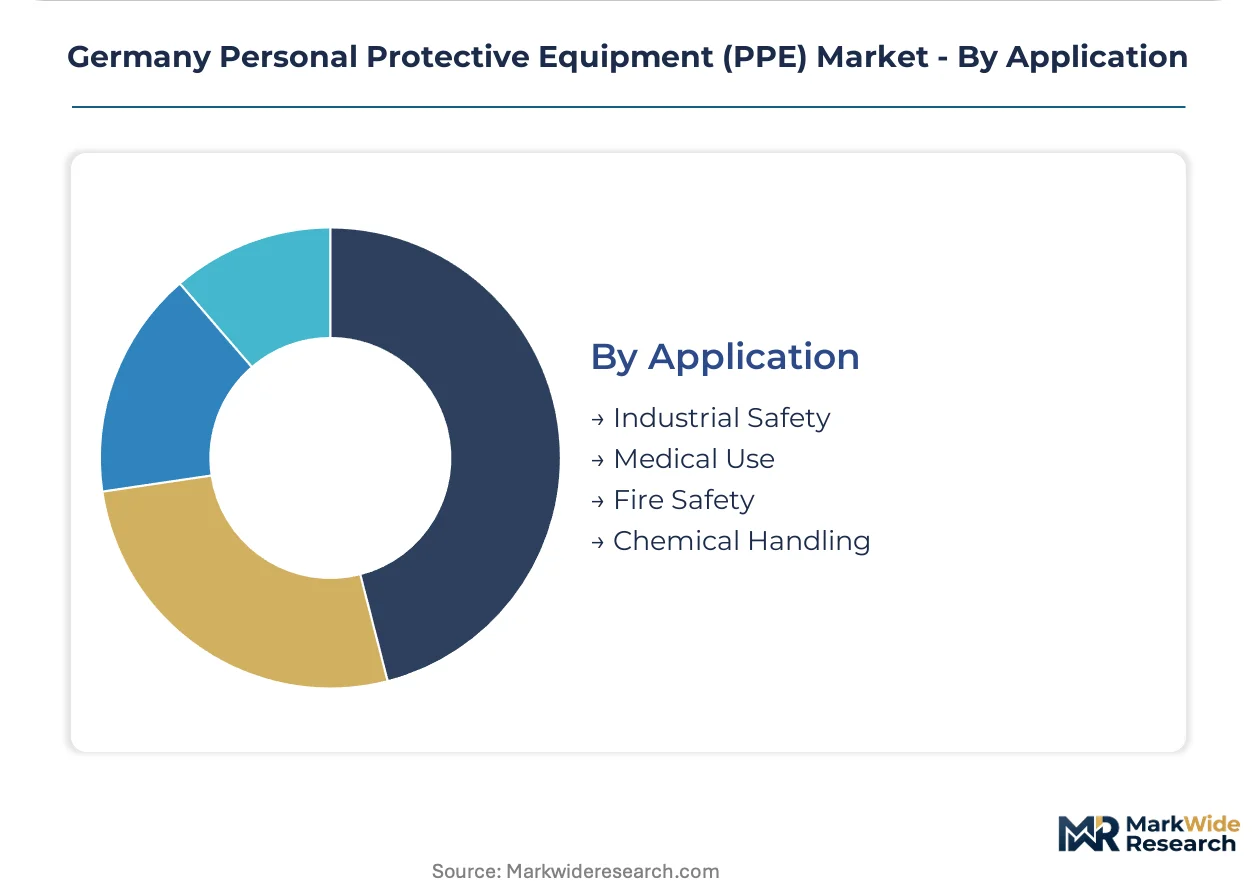
Application:
Use-case segmentation separates commodity replacement cycles from premium integrated systems, with certification burden and replacement frequency determining margin structure.
- Industrial Safety:Multi-hazard protection across mechanical, thermal, and electrical risks commands the deepest expertise requirements, with full-line distributors fragmenting into component specialists.
- Medical Use:Sterile barrier systems and splash protection for bloodborne pathogen exposure are upgrading from legacy cotton to synthetic laminates, with EN 14126 certification becoming standard.
- Fire Safety:Turnout gear and emergency response equipment serve professional fire services and industrial brigades, with limited volume but extreme performance specifications.
- Chemical Handling:Permeation-tested gloves and encapsulating suits for BASF-cluster operations face PFAS formulation pressure, with silicone-based alternatives undergoing validation trials.
Industrial safety anchors revenue concentration; chemical handling shows the steepest expansion trajectory amid regulatory-driven material upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial concentration zones across Germany's federal states generate distinct procurement rhythms, with DGUV enforcement intensity and sectoral specialization creating regional demand patterns.
Bavaria
Automotive assembly lines and aerospace suppliers dominate procurement volumes, with BMW and Audi operations specifying connected respiratory platforms for paint shop environments. DGUV inspection protocols in Munich and Ingolstadt plants convert safety violations into immediate equipment orders. The Ingolstadt automotive cluster drives premium-tier demand for integrated hearing and eye protection systems.
North Rhine-Westphalia
Chemical corridor density between Cologne and Düsseldorf sustains demand for chemical-resistant gloves and encapsulating suits. Bayer Leverkusen operations and Evonik Marl facilities specify EN 943-certified barrier materials under BAuA guidance. The Leverkusen chemical complex anchors Germany's highest-specification PPE procurement for confined-space entry protocols.
Baden-Württemberg
Automotive supplier tiers and precision machinery manufacturers fragment procurement across specialized component contracts. Bosch and Porsche operations in Stuttgart specify cut-resistant aramid gloves for assembly applications. The Stuttgart industrial basin exhibits the most advanced unbundling of framework agreements into category-specific supplier relationships.
Lower Saxony
Volkswagen Wolfsburg operations and offshore wind supply chains drive demand for high-visibility ensembles and safety footwear. KBA workplace inspections enforce EN ISO 20471 compliance across construction sites in Hanover and Braunschweig. The Wolfsburg automotive complex sustains volume demand for standardized hand and foot protection.
Hesse
Frankfurt airport logistics and pharmaceutical cleanrooms in Marburg specify disposable coveralls and sterile barrier systems. Fraport cargo operations drive S3 safety shoe procurement for ground handling crews. The Frankfurt-Rhine-Main logistics corridor exhibits fastest adoption of recycled-content polyester specifications in public tenders.
Germany Personal Protective Equipment (PPE) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Germany's PPE procurement landscape. The market structure tilts toward consolidation in respiratory and integrated protection systems, while hand and foot protection segments fragment across mid-sized component suppliers. Three archetypes dominate: vertically integrated German manufacturers with captive production, multinational technology platforms with connected safety offerings, and specialized distributors with deep sectoral relationships. Competitive intensity concentrates on modular kit unbundling and real-time monitoring integration.
Within the German pure-play tier, UVEX Safety Group and Drägerwerk AG & Co. KGaA exemplify divergent specialization strategies, with the former anchoring eye and head protection and the latter commanding respiratory and gas detection integration. Among diversified multinationals, Honeywell International occupies a position representing connected platform architecture, while 3M sits within the broad portfolio archetype spanning multiple protection categories. Brady GmbH represents the safety identification and lockout-tagout specialist segment that complements core PPE procurement.
| Leading Market Players |
|---|
| UVEX Safety Group |
| Brady GmbH |
| Drägerwerk AG & Co. KGaA |
| 3M |
| Franz Mensch GmbH |
| MSA Deutschland GmbH |
| Kroschke Sign-International GmbH |
| Honeywell International |
| Bosch |
| Others |
Pricing and Supply Chain Analysis
Sensor-embedded respiratory platforms and modular kit configurations are compressing traditional PPE value chains, simultaneously fragmenting volume concentration among specialized component suppliers and compressing margins for full-line manufacturers unable to pivot toward data-service monetization. This production-method transition reshapes cost economics by forcing certification investments in connected safety architectures while eroding pricing power for commodity hand and foot protection categories.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations, with Bavarian automotive plants paying significant markups for same-week respiratory device delivery amid DGUV inspection-driven urgency. Pricing stratifies across premium connected platforms, standard certified components, and economy bulk contracts, with certification grade and volume scale as the primary differentiation drivers. Cost compression in standard protective clothing is intensifying because healthcare employers are consolidating purchasing through GPO frameworks. Mid-sized metalworking SMEs exhibit the highest price sensitivity, while BASF-cluster chemical operators prioritize permeation performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by German industrial buyers are fragmenting supplier relationships, with automotive procurement teams qualifying separate respiratory, hand, and eye protection vendors rather than relying on single full-line distributors. Manufacturing concentrates in Germany, China, and Poland, with domestic production favored for rapid customization and Asian sourcing dominating volume categories. Aramid fiber, nitrile rubber, and polycarbonate lens materials constitute critical input dependencies. Single-source vulnerability in European aramid supply poses structural risk. Distribution runs through specialized industrial distributors with deep sectoral relationships rather than broad-line wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected safety platforms with integrated biometric monitoring and real-time environmental sensing are displacing standalone respiratory and gas detection equipment, compressing legacy product margins while opening premium positioning for vendors with software capabilities.
For Market Incumbents: Anchor premium positioning through backward integration into sensor hardware and cloud analytics platforms, defending against modular kit unbundling by bundling connected respiratory systems with predictive maintenance services. Certification investment in EN ISO 943 for chemical barrier materials represents a critical lever as REACH restrictions threaten existing PFAS-dependent formulations. For New Entrants and Emerging Players: Begin with underpenetrated mid-tier chemical operators in the Rhineland-Palatinate corridor between Ludwigshafen and Krefeld, where legacy procurement relationships remain vulnerable to specialized entrants offering silicone-based alternatives to fluorinated chemical-resistant garments. Direct sales engagement with plant safety officers bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking connected safety capabilities, with financial sponsor interest strongest in pure-play respiratory and gas detection specialists. Long-term viability hinges on software recurring revenue attachment rates. The signal to watch is DGUV funding allocation shifts toward prevention campaign procurement windows.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Platform Integration | Merges respiratory protection with real-time gas detection for BASF-cluster contracts. |
| PFAS Alternative Development | Silicone-based barrier materials address REACH restriction timelines for chemical garments. |
| Modular Kit Specialization | Unbundles full-line portfolios into category-specific supplier relationships with automotive OEMs. |
| Notified Body Certification Investment | Accelerates EU 2016/425 conformity assessment for respiratory device introductions. |
| DGUV Prevention Campaign Alignment | Captures funded procurement windows for hearing and eye protection in metalworking SMEs. |
Research Methodology
BAuA technical guidance documents, DGUV accident statistics databases, and EU customs trade records formed the secondary backbone, supplemented by primary interviews with plant safety officers at BASF Ludwigshafen and Bayer Leverkusen, procurement directors at Bavarian automotive OEMs, notified body certification specialists, and industrial distributor category managers. Bottom-up demand modeling triangulated against top-down sectoral spend analysis validated volume estimates.
Historical trendline analysis across installed PPE base and replacement frequency patterns anchored the projection framework, with segmentation across product type, end-user industry, material technology, and application use-case informing demand disaggregation. CAGRs derived from regression analysis of procurement cycle data and regulatory enforcement intensity trajectories. Forecast inputs incorporated REACH restriction implementation timelines and DGUV prevention campaign funding allocations.
REACH restriction enforcement delays, notified body certification backlogs, and raw material supply disruptions are the dominant revision risks to modeled demand. A model refresh is warranted upon material change in EU PFAS regulatory timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Scuba Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Isolation Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Machine Safeguarding Solution Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Explosion Proof Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Biodegradable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
US Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Traffic Baton Market
Safety Equipment and Personal Protective Equipment (PPE)
Padlock Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Emergency Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above-The-Neck PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market