
 Prison Management Systems Market | 2026-2036
Prison Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Prison Management Systems Market Analysis
State correctional facilities is expanding their procurement of integrated digital platforms as legacy paper-based intake and classification systems reach end-of-life. Tyler Technologies leverages its public-sector ERP footprint to cross-sell jail management modules into county governments. GUARDIAN RFID anchors its position through proprietary real-time location tracking hardware deployed across midwestern detention centers. Syscon Elite differentiates via deep specialization in offender financial management and commissary transaction processing.
Prison Management Systems encompass software and hardware platforms designed to automate inmate booking, classification, movement tracking, visitation scheduling, and facility security operations, typically integrating biometric authentication and role-based access controls to maintain chain-of-custody integrity. The primary commercial purpose is to reduce administrative overhead while enhancing officer safety and regulatory compliance through centralized data visibility. Cloud-Based deployments are capturing the fastest expansion as correctional agencies abandon capital-intensive server farms for subscription models with automatic security patching. Inmate Management remains the largest product category by installed base, though Security Systems command premium pricing due to hardware-software bundling requirements and longer replacement cycles.
The National Institute of Corrections and state-level procurement boards are mandating CJIS-compliant data handling and multi-factor authentication standards that disqualify non-certified vendors from RFP eligibility. The FBI's Criminal Justice Information Services division audits facility compliance annually, creating recurring demand for security module upgrades and audit preparation services. Stakeholders must monitor evolving federal grant conditions tied to recidivism reduction metrics, as these funding streams increasingly require demonstrated interoperability with community supervision databases.
Market Dynamics
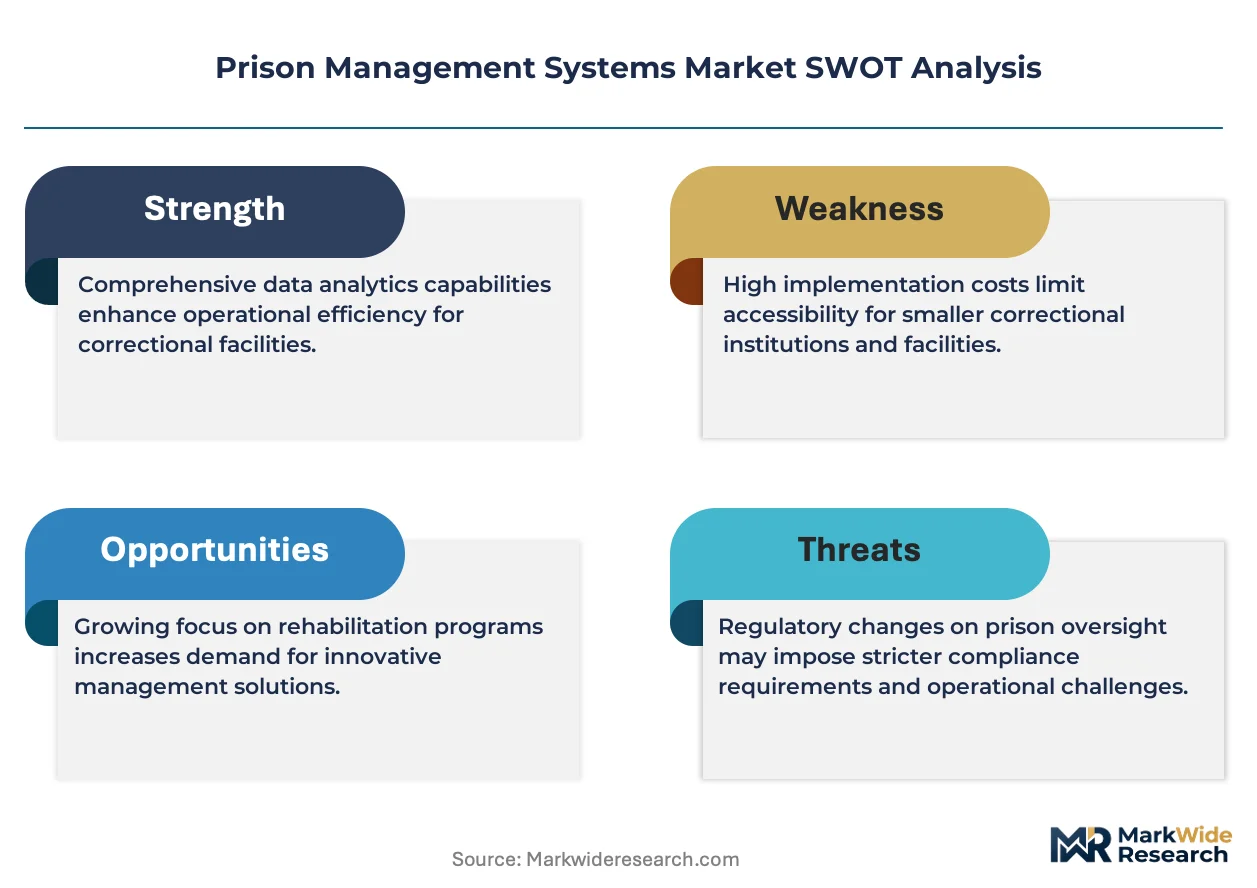
Cloud migration mandates from state procurement offices are compressing replacement cycles for on-premise jail management infrastructure, forcing vendors to requalify under CJIS-compliant subscription frameworks.
Growth Catalysts
- CJIS Security Policy mandates:The FBI's Criminal Justice Information Services division requires multi-factor authentication and encrypted data handling, disqualifying non-certified vendors from state RFP eligibility and accelerating security module procurement.
- Jail overcrowding pressures:County correctional facilities in high-incarceration states are expanding digital intake and classification automation to process higher inmate volumes with static staffing levels.
- Recidivism reduction grant conditions:Federal funding streams now mandate interoperability with community supervision databases, creating pull-through demand for integrated offender management platforms.
Market Restraints
- Capital intensity of hardware-software bundling:Security Systems category requires proprietary biometric terminals and real-time location tracking infrastructure that locks facilities into single-vendor upgrade cycles.
- Concentrated vendor qualification:State procurement boards maintain narrow approved-vendor lists, creating barriers for emerging cloud-native entrants lacking legacy public-sector ERP relationships.
- Substitution from paper-based workarounds:Smaller rural detention centers continue manual intake and movement logging to avoid subscription costs and staff retraining requirements.
Strategic Opportunities
- Underpenetrated county jail segment:Mid-sized county facilities lag state prisons in digital adoption, presenting white space for modular, lower-cost cloud deployments.
- Convergence of RFID tracking with biometric authentication:Real-time location systems integrated with iris and fingerprint verification are enabling continuous chain-of-custody automation.
- Subscription model channel innovation:Correctional agencies are piloting SaaS procurement through state cooperative purchasing agreements, bypassing traditional capital budget cycles.
Industry Challenges
- CJIS certification timeline compression:Vendors face 12-18 month audit cycles to maintain compliance, delaying product releases and straining engineering resources.
- Integration friction with legacy mainframes:State correctional databases running decades-old offender records systems require costly middleware development for API connectivity.
- Officer technology adoption resistance:Frontline correctional staff require extensive retraining on mobile-based incident reporting, slowing rollout schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prison Management Systems Market |
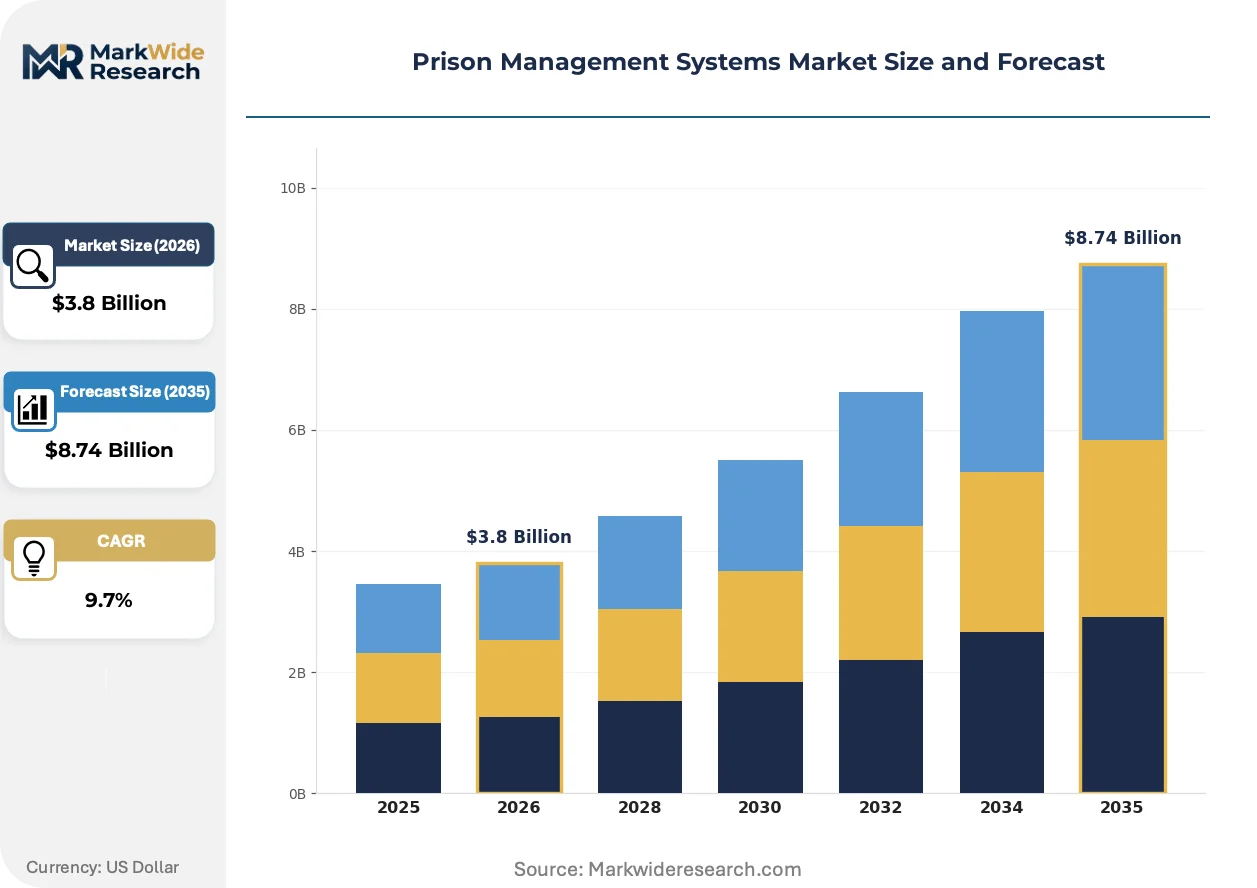
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inmate Management, Security Systems, Communication Tools, Reporting Software Technology: Cloud-Based, On-Premise, Mobile Applications, Integrated Systems End User: Correctional Facilities, Law Enforcement Agencies, Government Institutions, Private Operators Solution: Monitoring Solutions, Data Management Systems, Security Solutions, Automation Tools |
| Companies Covered | Tyler Technologies, Prism Corrections Suite, Offender360, Omnigo, GUARDIAN RFID, JailTracker, SmartJAIL, eFORCE, Syscon Elite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prison Management Systems Market Emerging Trajectories
Biometric authentication layers and predictive analytics modules are displacing static rule-based security protocols across correctional facilities. Procurement patterns favor integrated platforms over point solutions.
Artificial intelligence-driven risk scoring is rewriting how facilities classify inmates and allocate housing assignments. State departments of corrections in high-throughput jurisdictions are deploying machine learning models to replace manual classification reviews. This compression of assessment timelines is enabling dynamic housing reassignments that respond to real-time behavioral data rather than static intake scores.
The FBI's CJIS Security Policy updates are mandating zero-trust architecture for all systems touching criminal history data. Vendors must now segment networks and enforce continuous authentication rather than perimeter-based security. Cloud-Based deployment models are capturing preference as native zero-trust frameworks, while legacy on-premise installations face costly retrofit requirements.
Subscription pricing is displacing perpetual license models as correctional agencies shift capital expenditure to operational budgets. State procurement offices are structuring multi-year SaaS agreements with automatic security patching provisions. This transition is most visible in the United States, where federal grant conditions increasingly require demonstrated interoperability that cloud-native architectures deliver more readily than legacy client-server systems.
Prison Management Systems Market Segmentation
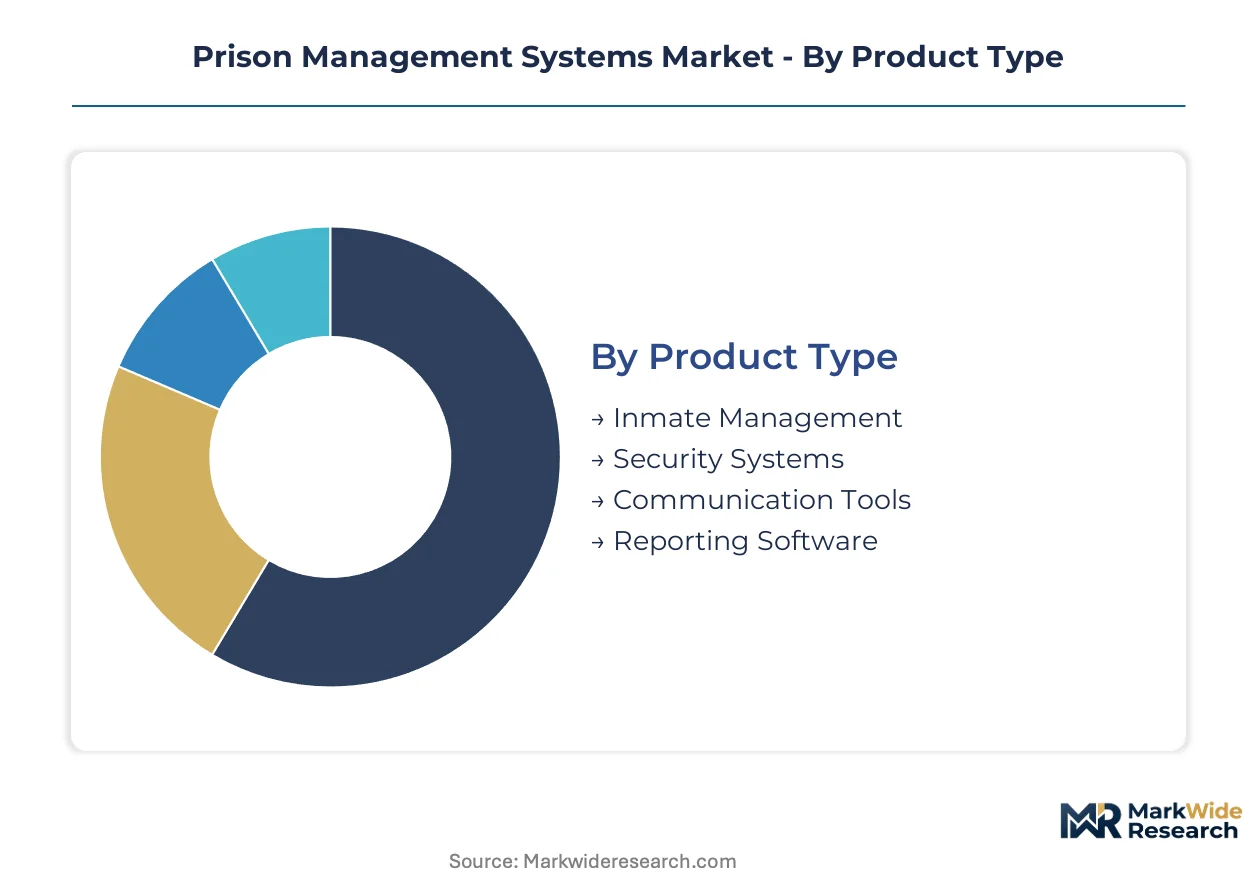
Correctional procurement cycles differ sharply across product architectures and deployment models. Facility operators weigh upfront capital requirements against compliance mandates when selecting system categories. Segmentation reveals where subscription economics are displacing perpetual licenses.
Product Type:
Capital intensity varies dramatically across this category, with hardware-software bundles demanding multi-year amortization while pure software modules convert faster to recurring revenue.
- Inmate Management:Core software platforms automate booking, classification, housing assignment, and release processing through centralized databases. County facilities in high-incarceration states deploy these systems to process rising intake volumes without proportional staff expansion. CJIS-compliant data handling requirements are accelerating replacement of legacy client-server installations.
- Security Systems:Integrated hardware-software stacks encompass biometric terminals, perimeter sensors, and real-time location tracking infrastructure. State prisons command premium pricing here due to mandatory hardware refresh cycles and longer vendor lock-in periods. The FBI's annual CJIS audits drive continuous security module upgrades.
- Communication Tools:Inmate telephony, video visitation, and secure messaging platforms connecting facilities with external networks.
- Reporting Software:Compliance documentation and incident reporting modules for regulatory submission and internal analytics.
Most installed capacity flows through Inmate Management. Expansion is steepest in Security Systems.
Technology:
Deployment architecture determines procurement pathway eligibility, with state cooperative purchasing agreements increasingly restricting RFP participation to cloud-native vendors.
- Cloud-Based:Subscription-delivered platforms with automatic security patching and CJIS-compliant zero-trust segmentation. Federal grant conditions mandating interoperability with community supervision databases are pulling agencies toward these architectures. State procurement offices in the United States are compressing replacement cycles for on-premise infrastructure through explicit cloud migration mandates.
- On-Premise:Capital-intensive server installations requiring facility-managed security patching and perimeter-based network defenses. Legacy state correctional databases running decades-old offender records systems create costly middleware requirements for API connectivity. Smaller rural detention centers persist with these models to avoid subscription costs.
- Mobile Applications:Officer-facing incident reporting and movement tracking tools running on hardened tablets and smartphones.
- Integrated Systems:Unified platforms spanning multiple functional domains through single-vendor contracts.
Cloud-Based deployments are gaining share fastest. On-Premise retains the largest legacy installed base.
End User:
Customer type dictates funding mechanism and decision timeline, with federal grant eligibility varying across institutional categories.
- Correctional Facilities:State prisons and county jails operating under state procurement board oversight. These entities face the most stringent CJIS compliance deadlines and represent the primary revenue concentration for integrated platform vendors. Jail overcrowding pressures in high-incarceration states are accelerating digital intake automation budgets.
- Law Enforcement Agencies:Police departments and sheriff offices requiring booking and temporary detention management. Booking system integration with state criminal history databases creates demand for real-time data synchronization capabilities.
- Government Institutions:Courts, probation departments, and parole boards requiring interoperability with correctional databases.
- Private Operators:Contract facility management companies operating under government service agreements.
Correctional Facilities absorb the majority of procurement volume. Law Enforcement Agencies are expanding fastest as booking automation extends downstream.
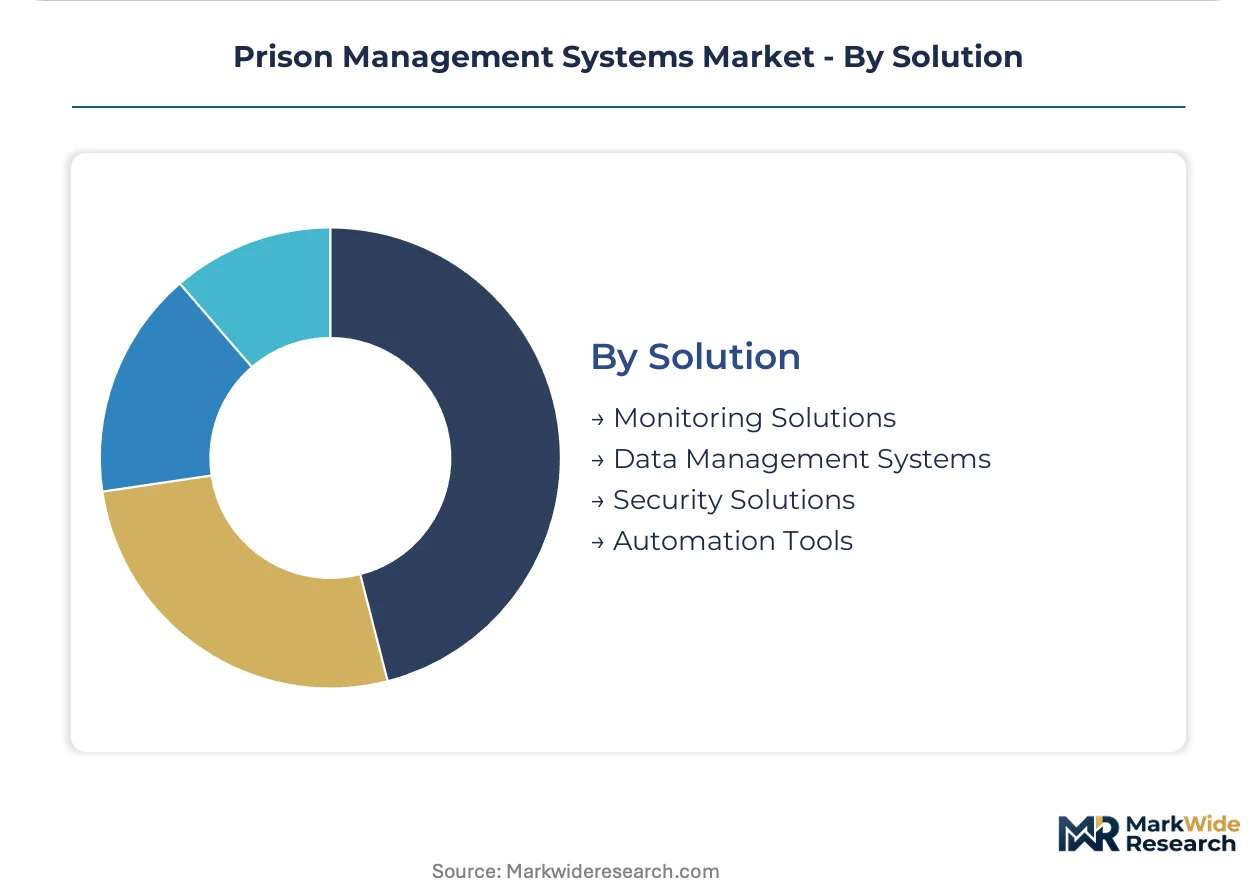
Solution:
Functional purpose determines integration depth, with monitoring and security solutions commanding higher per-seat pricing than administrative automation.
- Monitoring Solutions:Continuous surveillance and behavioral tracking systems incorporating RFID location data and video analytics. Real-time location systems integrated with biometric verification enable continuous chain-of-custody automation. Predictive risk scoring modules are displacing static classification protocols in high-throughput jurisdictions.
- Security Solutions:Access control, perimeter defense, and emergency response coordination platforms. Zero-trust architecture mandates from the FBI's CJIS Security Policy updates are forcing network segmentation and continuous authentication retrofits.
- Data Management Systems:Offender records, commissary transactions, and financial management databases.
- Automation Tools:Workflow engines for classification reviews, visitation scheduling, and release processing.
Monitoring Solutions carry the highest average contract value. Data Management Systems are expanding most quickly as financial management digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Correctional technology procurement gravitates toward jurisdictions with standardized federal compliance frameworks, where CJIS certification costs create barriers for smaller vendors and concentrate contract awards among pre-qualified suppliers.
United States
State procurement boards in Texas and California drive the majority of cloud migration contracts, with county jail overcrowding accelerating digital intake automation. The FBI's CJIS Security Policy mandates multi-factor authentication and zero-trust architecture, disqualifying non-certified vendors from RFP eligibility. Tyler Technologies leverages its public-sector ERP footprint to cross-sell jail management modules into county governments across the Midwest and Southeast.
Canada
Provincial correctional services in Ontario and Quebec are modernizing legacy offender management systems through cooperative purchasing agreements. Health Canada and the RCMP coordinate data handling standards that align with CJIS-equivalent security protocols. Vancouver-based detention centers pilot integrated biometric authentication layers for real-time inmate tracking.
United Kingdom
Her Majesty's Prison and Probation Service contracts favor integrated platforms over point solutions, with procurement concentrated through the Crown Commercial Service framework. The UK Information Commissioner's Office enforces GDPR-compliant data segmentation for criminal justice databases. London-area facilities lead deployment of predictive risk scoring modules for dynamic housing reassignment.
Germany
Land-level justice ministries in Bavaria and North Rhine-Westphalia specify modular architectures that accommodate federal-state data sharing requirements. The Federal Office for Information Security audits correctional IT systems for compliance with BSI baseline protection standards. Stuttgart-based system integrators specialize in middleware development for legacy mainframe connectivity.
Australia
State correctional departments in New South Wales and Victoria prioritize interoperability with community supervision databases under federal grant conditions. The Australian Criminal Intelligence Commission mandates ACIC data handling certifications for vendors accessing national criminal history records. Sydney-area facilities represent the largest installed base of RFID-integrated biometric terminals in the Asia-Pacific region.
Prison Management Systems Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors capturing premium pricing in state prison contracts while modular point-solution providers penetrate county jail white space. The vendor base concentrates around three strategic archetypes: public-sector ERP cross-sellers, hardware-integrated security specialists, and cloud-native workflow automators. M&A activity targets middleware capabilities for legacy system connectivity, while strategic partnerships with state cooperative purchasing agreements bypass traditional capital budget cycles.
Within the public-sector ERP cross-seller tier, Tyler Technologies exemplifies the archetype of leveraging existing government relationships to expand into adjacent correctional modules. GUARDIAN RFID occupies a position among hardware-integrated security specialists, anchoring real-time location tracking deployments across midwestern detention centers. Syscon Elite sits within the financial management specialization segment, representing deep vertical focus on offender commissary transaction processing.
| Leading Market Players |
|---|
| Tyler Technologies |
| Prism Corrections Suite |
| Offender360 |
| Omnigo |
| GUARDIAN RFID |
| JailTracker |
| SmartJAIL |
| eFORCE |
| Syscon Elite |
| Others |
Supply Flow & Price Mechanics
Cloud-native zero-trust architecture migration is compressing both development cycles and vendor qualification economics, concentrating procurement power among CJIS-certified incumbents while forcing subscription pricing models that reshape downstream distributor economics. State cooperative purchasing agreements in the United States and provincial frameworks in Canada now dictate margin structures that legacy hardware-software bundlers struggle to match.
Pricing Analysis
Direct-to-agency SaaS subscriptions bypass traditional systems integrator markups, compressing channel margins from 25-35% toward 12-18% for cloud-native entrants. Three-tier pricing structure across premium, standard, and economy levels stratifies by CJIS certification tier and API integration depth, with state prison contracts commanding 40-60% premiums over county jail deployments. Cost compression in the mid-tier is intensifying because federal grant interoperability mandates favor integrated platforms over point solutions. County facilities with constrained operational budgets exhibit highest price sensitivity, while state departments of corrections prioritize compliance assurance over unit economics.
Supply Chain Analysis
Freight and customs costs for biometric hardware components draw heavily from Taiwan semiconductor fabs, South Korea sensor manufacturers, and domestic final assembly operations in Texas and Arizona. Proprietary RFID tags, hardened tablet enclosures, and encrypted communication modules rest on specialized electronics supply chains vulnerable to tariff exposure on Chinese-manufactured circuit boards. Distribution runs through state cooperative purchasing agreements and GSA schedules rather than open-market channels, locking vendors into multi-year qualification cycles that limit supplier switching.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Prison Management Systems Market functions as a regulatory compounder where CJIS Security Policy zero-trust mandates create recurring upgrade revenue streams that compound vendor lifetime value.
For Market Incumbents: Lock in county jail white space through modular SaaS offerings that undercut integrated platform pricing by 30-40%, while accelerating CJIS re-certification investments to maintain RFP eligibility against cloud-native challengers. Vertical integration into proprietary biometric hardware manufacturing defends margin position against commoditization of pure software modules. For New Entrants and Emerging Players: State cooperative purchasing agreement administrators represent the critical channel partner type for bypassing capital budget cycles, enabling SaaS procurement through operational expenditure lines that incumbent ERP vendors dominate. Underpenetrated mid-sized county facilities in high-incarceration states offer the most penetrable segment, with API-first middleware for legacy mainframe connectivity as the essential go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among hardware-integrated security specialists lacking cloud subscription revenue streams, presenting acquisition targets with embedded customer bases ripe for SaaS conversion. Long-term viability across the analysis window hinges on demonstrated interoperability with community supervision databases. The signal to watch is federal grant condition tightening that accelerates replacement cycles for non-compliant legacy installations.| Strategic Initiative | Industry Significance |
|---|---|
| CJIS Re-Certification Investment | Maintains RFP eligibility under FBI Security Policy updates that disqualify non-compliant vendors. |
| API-First Middleware Development | Unlocks county jail contracts requiring legacy mainframe connectivity without full system replacement. |
| State Cooperative Purchasing Partnership | Bypasses traditional capital budget cycles through operational expenditure SaaS procurement pathways. |
| Biometric Hardware Backward Integration | Captures premium pricing in Security Systems category through proprietary terminal manufacturing. |
| Community Supervision Database Interoperability | Satisfies federal grant conditions that increasingly mandate demonstrated data exchange capabilities. |
Methodological Framework
Multiple input streams — correctional facility IT directors, state procurement board officials, CJIS audit specialists, and offender management software engineers — were reconciled against federal grant databases, CJIS Security Policy documentation, and state RFP archives. Secondary validation drew from SEC filings of public-sector technology vendors, cooperative purchasing agreement records, and FBI Criminal Justice Information Services division compliance reports. Bottom-up county-level deployment estimates and top-down state budget appropriations were triangulated to anchor volume projections.
Data-stream reconciliation across product architecture, deployment model, and facility tier dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from fitted adoption curves weighted by CJIS compliance deadline clustering and federal grant condition evolution. Forecast inputs incorporated cloud migration mandate penetration rates and hardware-software bundle replacement cycle compression observed in state prison versus county jail procurement patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CJIS Security Policy amendment timing and federal recidivism reduction grant reauthorization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Cargo Container X-Ray Inspection Systems Market
Security and Surveillance
Security System Integrators Market
Security and Surveillance
Home Security Market
Security and Surveillance
Global Integration Security Services Market
Security and Surveillance
Europe Baggage and Parcel Screening Market
Security and Surveillance
Europe Anti-Piracy Protection Market
Security and Surveillance
Security Services Market
Security and Surveillance
Global X-Ray Security Scanner Market
Security and Surveillance
Mass Transit Security Market
Security and Surveillance
Specialized Threat Analysis and Protection Market
Security and Surveillance
Global Cargo Inspection Market
Security and Surveillance
Door and Window Alarm Market
Security and Surveillance
Shock Sensor Market
Security and Surveillance
Europe Rockfall Radar Market
Security and Surveillance
Electronic Alarms Market
Security and Surveillance
Middle East and Africa Cargo Inspection Market