
 Private Security Market | 2026-2036
Private Security Market Size, Share, and Industry Trends Forecast 2026-2036
Private Security Market Analysis
Direct-to-enterprise sales channels is narrowing as integrators consolidate procurement power across multisite contracts. Allied Universal leverages its national guard force footprint to anchor long-term facilities management agreements. Securitas AB competes through technology-led outsourcing models that blend manned guarding with remote monitoring centers. G4S controls specialized event security and cash logistics segments where certification barriers limit new entrants.
Private security encompasses protective services, surveillance systems, and risk mitigation infrastructure delivered through personnel deployment, electronic monitoring, and armored transport. Video surveillance platforms integrate AI-powered analytics with edge computing architectures to enable real-time threat detection across distributed sites. Manned guarding retains the largest revenue share but carries thinner margins due to labor intensity and wage pressures. Electronic security, spanning access control and alarm systems, captures expanding margin pools as software subscriptions replace hardware-only sales. Cybersecurity within security portfolios is growing fastest as physical-digital convergence forces unified threat management.
The EU AI Act, GDPR, and CE marking frameworks impose strict algorithmic transparency and data residency requirements on biometric surveillance deployments across Europe. The US FAA and FCC regulate drone-based perimeter monitoring and radio-frequency equipment used in integrated security networks. Stakeholders must monitor regulatory divergence between privacy-first jurisdictions and surveillance-permissive markets when allocating R&D and compliance resources.
Market Dynamics
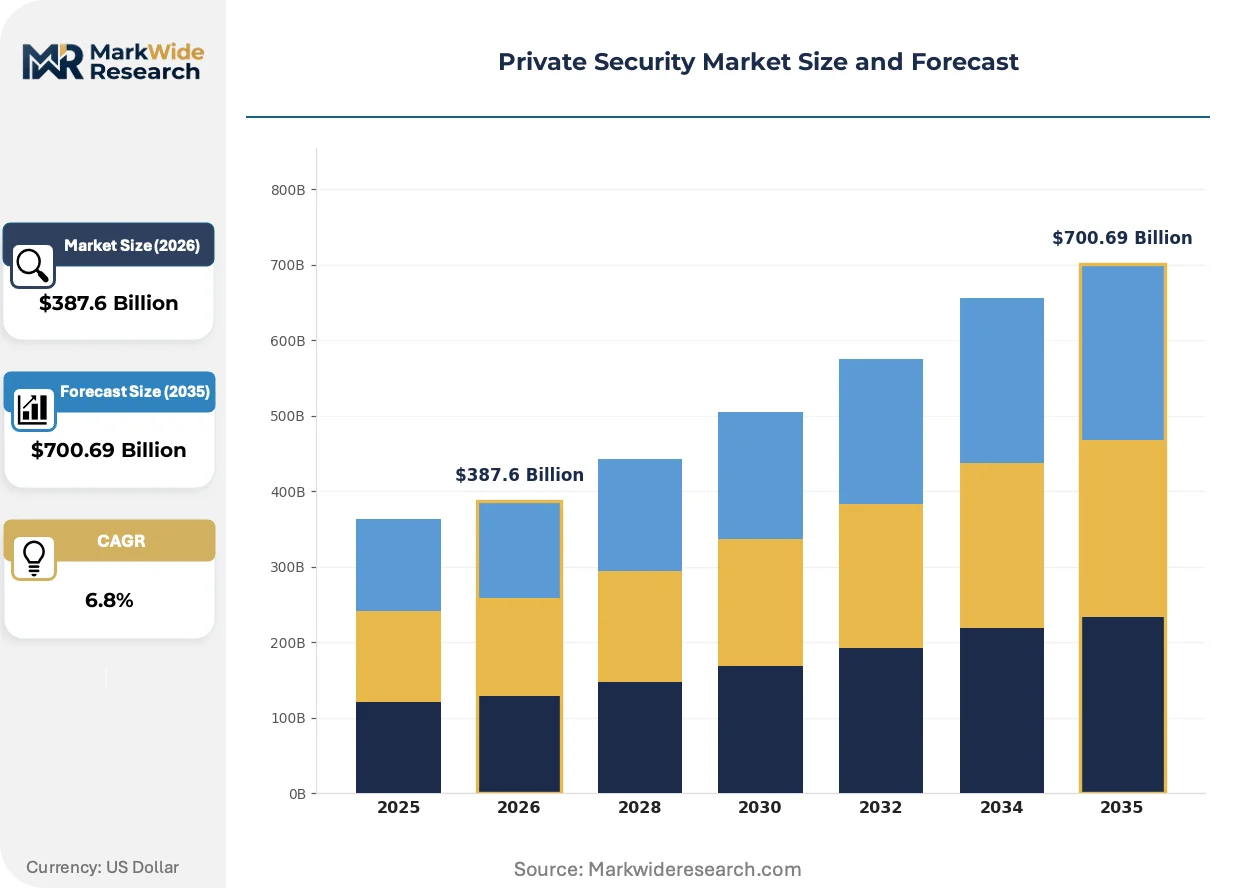
Convergence between physical guarding and cyber threat detection is restructuring procurement priorities across corporate security departments. The EU AI Act's biometric surveillance restrictions and rising minimum wage mandates in the United States are compressing margins for labor-intensive service models while accelerating capital deployment into autonomous monitoring infrastructure.
Growth Catalysts
- Critical Infrastructure Outsourcing:Energy utilities and transportation hubs in the United States are transferring perimeter protection to specialized contractors to meet NERC-CIP and TSA mandates. Federal compliance deadlines are expanding addressable contract values.
- EU AI Act Algorithmic Transparency:European biometric surveillance deployments now require documented training data provenance and human oversight protocols. Compliance consulting services attached to security installations are generating recurring revenue streams.
- Edge Computing Architectures:Video analytics processing at the network edge reduces bandwidth costs and latency for real-time threat detection. Retail and logistics campuses in India are adopting these systems to monitor distributed warehouse footprints.
Market Restraints
- Labor Cost Volatility:Guard wages in the United States and Germany are rising faster than contract escalation clauses allow. Fixed-price multi-year agreements are becoming structurally unprofitable for service providers.
- Semiconductor Supply Concentration:Camera system-on-chip and edge AI processors depend on Taiwanese and South Korean fabrication capacity. Geopolitical risk in the Taiwan Strait threatens hardware delivery timelines.
- GDPR Data Residency Friction:Cross-border cloud video storage faces national implementation variations of GDPR across France, Germany, and Italy. Fragmented compliance requirements inflate architectural complexity for multinational deployments.
Strategic Opportunities
- Drone-Based Perimeter Monitoring:FAA Part 107 waivers and beyond-visual-line-of-sight authorizations are opening autonomous aerial patrol for remote infrastructure sites in Texas and California oil fields.
- Physical-Cyber Fusion Centers:Converged security operations centers that correlate badge access logs with network intrusion attempts address CISO-CISO coordination failures at Fortune 500 headquarters.
- India Smart City Mandates:Ministry of Home Affairs funding for Safe City projects in Mumbai, Delhi, and Bangalore specifies integrated command-and-control platforms. Municipal procurement channels bypass traditional enterprise sales cycles.
Industry Challenges
- Multi-Domain Analyst Scarcity:Personnel capable of correlating physical sensor feeds with SIEM alerts command premium compensation. Training pipelines for converged security operations have not scaled with demand.
- Retrofit Integration Complexity:Legacy access control systems using proprietary Wiegand protocols resist API-based integration with modern cloud platforms. Rip-and-replace capex requirements stall upgrade cycles at mid-market facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Private Security Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Manned Guarding, Electronic Security, Armored Transport, Consulting End User: Residential, Commercial, Government, Industrial Technology: Video Surveillance, Access Control, Alarm Systems, Cybersecurity Market Segment: Event Security, Personal Protection, Risk Assessment, Facilities Management |
| Companies Covered | ADT, Honeywell, Allied Universal, Prosegur, Secom, Securitas AB, GardaWorld, Paragon Systems, G4S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Private Security Market Emerging Trajectories
Artificial intelligence inference at the network edge is eliminating the latency and connectivity dependencies that previously constrained automated threat response. Regulatory frameworks are hardening around biometric data collection, forcing architectural redesigns. Enterprise procurement patterns are fragmenting as facilities management platforms absorb security spending.
Edge AI video analytics is collapsing the distinction between centralized monitoring centers and on-site guard response. Large distribution centers in the United States are deploying GPU-enabled cameras that classify anomalies locally and dispatch roving guards only for verified intrusions. The technology is collapsing response times from minutes to seconds while reducing headcount requirements for overnight shifts.
GDPR Article 35 data protection impact assessments now mandate documented necessity tests for biometric surveillance across Germany, France, and the Netherlands. Security providers must demonstrate proportionality between intrusion detection goals and privacy infringement risks. High-traffic transportation hubs in London and Paris are responding by replacing facial recognition with behavioral gait analysis that processes silhouettes rather than identifiable features.
Enterprise buyers are consolidating security procurement under integrated facilities management contracts that bundle cleaning, HVAC, and guarding into single vendor relationships. Real estate investment trusts with multisite portfolios in the United States are driving this consolidation to reduce vendor management overhead. The shift is compressing margins for standalone guarding contracts while expanding total contract values for full-service operators.
Private Security Market Segmentation
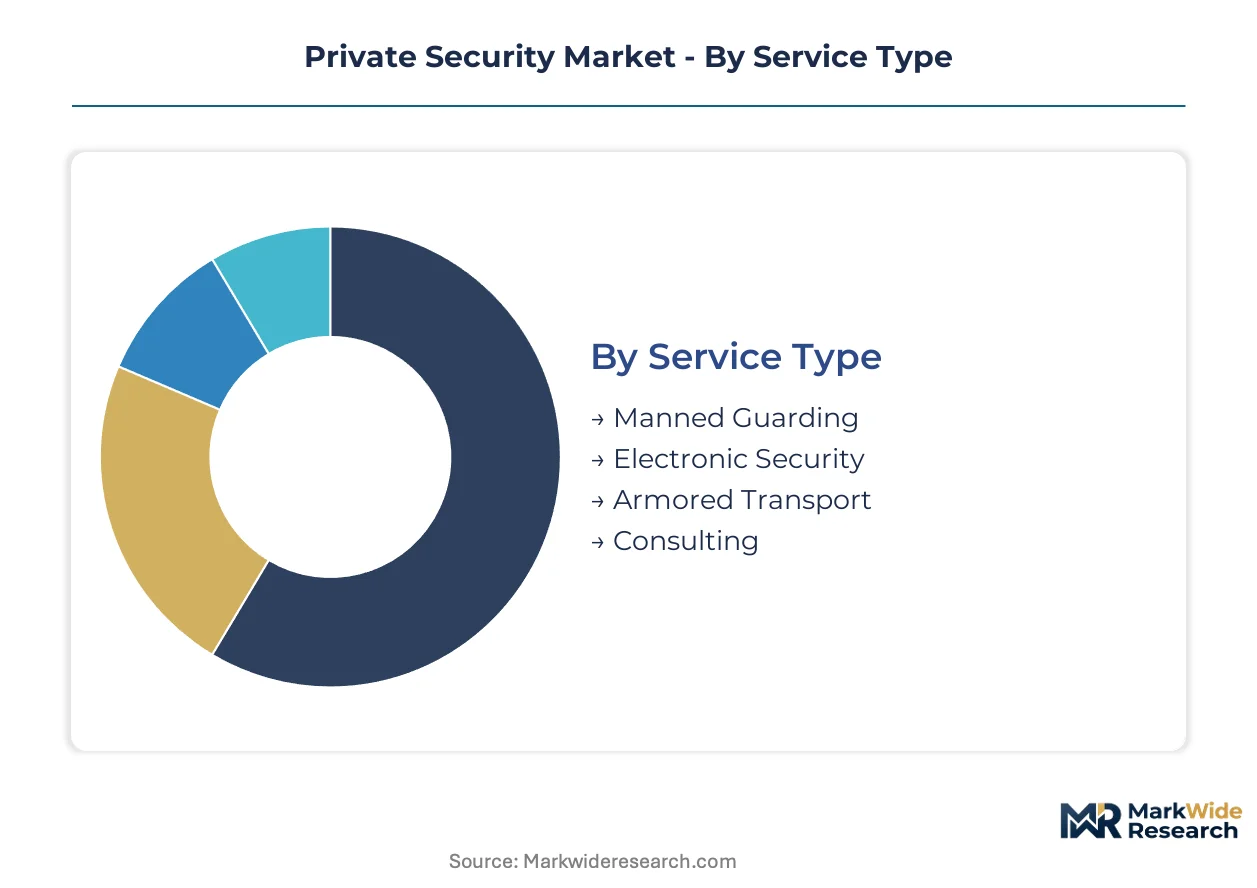
Segmentation in private security reveals how procurement priorities diverge across labor-intensive services, capital-heavy electronic systems, and emerging cyber-physical convergence. Understanding these splits enables vendors to align capability investments with margin profiles and compliance burdens.
Service Type:
Service portfolios span from wage-driven personnel deployment to technology-enabled monitoring and specialized logistics.
- Manned Guarding:Personnel-based perimeter protection and access control at corporate campuses and critical infrastructure sites. Demand concentrates in the United States and India where urbanization and outsourcing accelerate, though rising minimum wage mandates compress margins for fixed-price contracts.
- Electronic Security:Integrated sensor networks, video analytics platforms, and remote monitoring infrastructure. Energy utilities in Texas and California are expanding deployments to meet NERC-CIP compliance deadlines, shifting procurement from hardware sales toward software subscriptions.
- Armored Transport:Secure cash and valuables logistics with specialized vehicle fleets and certified personnel. Banking and retail sectors in Germany and France maintain steady demand despite digital payment displacement.
- Consulting:Risk assessment, compliance advisory, and security architecture design services. EU AI Act documentation requirements for biometric surveillance are expanding addressable contract values across European markets.
The dominant share belongs to Manned Guarding, while Electronic Security is closing the gap fastest as edge computing architectures displace labor-intensive overnight coverage.
End User:
Customer archetypes range from price-sensitive residential buyers to compliance-driven government agencies with mandated procurement thresholds.
- Residential:Home alarm systems, smart doorbells, and neighborhood patrol subscriptions. Middle-class households in India and China are adopting video doorbells and community guard services as urban density increases.
- Commercial:Office buildings, retail chains, and hospitality venues requiring integrated access control and loss prevention. Real estate investment trusts in the United States are consolidating procurement under facilities management contracts.
- Government:Municipal smart city projects, embassy protection, and critical infrastructure guarding. India's Ministry of Home Affairs Safe City mandates in Mumbai, Delhi, and Bangalore specify integrated command platforms.
- Industrial:Manufacturing plants, warehouses, and energy facilities with perimeter protection and insider threat programs. Oil field operators in Texas are securing FAA Part 107 waivers for drone-based patrol.
Commercial buyers generate the largest contract volumes, though Government procurement is expanding most quickly through municipal technology mandates.
Technology:
Technology stacks reflect a transition from standalone hardware to software-defined platforms with AI inference capabilities.
- Video Surveillance:Camera networks with edge analytics, thermal imaging, and behavioral recognition. GDPR Article 35 impact assessments in Germany and France are forcing architectural shifts from facial recognition to gait analysis.
- Access Control:Badge readers, biometric scanners, and mobile credential systems. Legacy Wiegand protocol systems resist cloud integration, stalling upgrade cycles at mid-market facilities.
- Alarm Systems:Intrusion detection sensors with central station monitoring and verified response protocols. Residential and small commercial segments dominate volume.
- Cybersecurity:SIEM correlation, network monitoring, and converged physical-cyber threat detection. CISO-CSO coordination failures at Fortune 500 headquarters are driving fusion center investments.
Video Surveillance retains the installed base leadership, while Cybersecurity is climbing the fastest as physical-digital convergence forces unified threat management.
Market Segment:
Application contexts determine pricing power, certification requirements, and contract duration structures.
- Event Security:Temporary crowd management, VIP protection, and emergency response for sporting and entertainment venues. Certification barriers limit new entrants in high-profile assignments.
- Personal Protection:Executive security details and family office services for high-net-worth individuals. Demand clusters in financial centers and emerging market capitals.
- Risk Assessment:Threat intelligence, vulnerability analysis, and business continuity planning. EU AI Act compliance consulting is attaching recurring revenue to surveillance installations.
- Facilities Management:Bundled services integrating guarding, cleaning, HVAC, and maintenance. Margin compression on standalone guarding is accelerating consolidation into full-service contracts.
Facilities Management commands expanding share through procurement consolidation, while Risk Assessment is gaining traction fastest via regulatory compliance attachments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where regulatory compliance mandates inflate contract values, while cost-sensitive markets in India compress margins through competitive tendering and labor arbitrage.
United States
Critical infrastructure operators in Texas and California oil fields are expanding perimeter protection budgets to meet NERC-CIP and TSA compliance deadlines. FAA Part 107 waivers enable autonomous drone patrol across remote energy sites. Houston and Midland anchor the drone-based monitoring cluster where service providers secure multi-year federal contracts.
Germany
GDPR Article 35 data protection impact assessments now mandate documented necessity tests for biometric surveillance deployments. The EU AI Act's algorithmic transparency requirements force architectural redesigns of facial recognition systems. Frankfurt and Berlin transportation hubs are replacing facial recognition with behavioral gait analysis to satisfy proportionality requirements.
India
Ministry of Home Affairs Safe City mandates in Mumbai, Delhi, and Bangalore specify integrated command-and-control platforms for municipal procurement. Urbanization accelerates demand for community guard services and video doorbells among middle-class households. The Delhi-NCR corridor concentrates smart city security spending through direct government channels.
China
Urbanization and private sector outsourcing accelerate demand for electronic security across manufacturing campuses and logistics hubs. National standards for video surveillance data residency shape procurement specifications. The Yangtze River Delta cluster around Shanghai drives adoption of AI-powered analytics in retail and warehouse applications.
United Kingdom
High-profile event security assignments face certification barriers that limit new entrants and sustain premium pricing. The Information Commissioner's Office enforces GDPR biometric restrictions across London transportation and entertainment venues. The Greater London area concentrates specialized cash logistics and executive protection services for financial sector clients.
Private Security Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying edge AI processors and camera modules. The vendor base consolidates around three structural tiers: multinational full-service operators with facilities management capabilities, technology-led specialists blending manned guarding with remote monitoring, and regional contractors competing on labor cost. Dominant competitive moves include M&A to absorb multisite facilities management contracts and strategic partnerships to embed cybersecurity capabilities within physical security portfolios.
Within the multinational tier, Allied Universal, Securitas AB, and G4S occupy positions that exemplify divergent strategic archetypes. Allied Universal leverages national guard force scale to anchor integrated facilities management agreements across corporate campuses. Securitas AB represents the technology-led outsourcing model that blends manned presence with remote monitoring center architectures. G4S sits within specialized segments where certification barriers limit competitive entry, particularly in event security and cash logistics operations.
| Leading Market Players |
|---|
| ADT |
| Honeywell |
| Allied Universal |
| Prosegur |
| Secom |
| Securitas AB |
| GardaWorld |
| Paragon Systems |
| G4S |
| Others |
Supply Flow & Price Mechanics
Taiwan Strait geopolitical exposure governs both the premium commanded by dual-source component suppliers and the geographic diversification imperatives reshaping hardware procurement. Semiconductor supply concentration for edge AI processors and camera system-on-chip modules forces security integrators to absorb tariff volatility or pass through cost escalation to end-users.
Pricing Analysis
Configured-to-order pricing for integrated command-and-control platforms commands substantial premiums over standard alarm-monitoring subscriptions. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service bundling. Cost compression in the manned guarding tier intensifies because fixed-price multi-year agreements lag wage inflation in the United States and Germany. Residential buyers in India exhibit the highest price sensitivity, while critical infrastructure operators in Texas and California oil fields prioritize compliance-grade solutions over unit cost.
Supply Chain Analysis
Supplier-financing facilities from Taiwanese and South Korean fabrication partners extend payment terms to 90-120 days for volume camera module purchasers. Hardware procurement draws from Taiwan, South Korea, and China for edge AI processors, image sensors, and lens assemblies. Single-source vulnerability for advanced GPU-enabled camera chips threatens delivery timelines across North American and European deployments. Distribution runs through national systems integrators who consolidate multisite procurement for real estate investment trusts and energy utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The private security market sits in early-cycle expansion as physical-cyber convergence forces unified threat management adoption across Fortune 500 headquarters and critical infrastructure sites.
For Market Incumbents: Pre-empt margin erosion in labor-intensive guarding segments by accelerating capital deployment into autonomous monitoring infrastructure. Anchor long-term facilities management agreements that bundle electronic security subscriptions with manned presence. Vertical integration into edge AI processor sourcing mitigates Taiwan Strait supply disruption risks. For New Entrants and Emerging Players: Municipal smart city procurement channels in India present the most penetrable white-space opportunity, bypassing traditional enterprise sales cycles dominated by established integrators. Target drone-based perimeter monitoring for remote energy infrastructure in Texas and California where FAA Part 107 waivers lower certification barriers. Lead with compliance consulting services attached to biometric surveillance installations to capture recurring revenue under EU AI Act mandates. For Investors and Strategic Acquirers: The EU AI Act's biometric surveillance restrictions reshape the acquisition landscape toward technology-led specialists with documented algorithmic transparency capabilities. Position for a 5-10 year horizon where converged security operations centers capture expanding procurement budgets from CISO-CSO coordination failures. Monitor FAA beyond-visual-line-of-sight authorization velocity as the inflection signal for autonomous aerial patrol market readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Physical-Cyber Fusion Center Deployment | Addresses CISO-CSO coordination failures at Fortune 500 headquarters with unified threat correlation. |
| Edge AI Video Analytics Integration | Reduces overnight guarding headcount for retail distribution centers through local anomaly classification. |
| EU AI Act Compliance Consulting Attachment | Generates recurring revenue streams from documented training data provenance and human oversight protocols. |
| Drone-Based Perimeter Monitoring Scale-Up | Captures NERC-CIP compliance contracts across Texas and California remote energy infrastructure sites. |
| Facilities Management Contract Consolidation | Absorbs standalone guarding procurement into bundled real estate investment trust vendor relationships. |
Methodological Framework
A spread of perspectives from security operations center directors, federal compliance officers at energy utilities, municipal procurement managers in Indian smart city projects, and systems integration specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings from publicly traded operators, FAA waiver application databases, EU regulatory implementation notices, and customs records for camera module imports. Bottom-up deployment tracking across end-use segments triangulated against top-down market sizing from service provider revenue disclosures.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling adoption curves for edge computing architectures against semiconductor fabrication capacity expansion. Segmentation dimensions included service type, end-user archetype, technology stack, and regional regulatory cluster. CAGRs derived from logistic diffusion curves for autonomous monitoring penetration and wage escalation trajectories for labor-intensive segments. Industry-specific inputs incorporated NERC-CIP compliance deadline schedules and EU AI Act implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese video analytics specialists or accelerated FAA beyond-visual-line-of-sight rulemaking would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Middle East and Africa Cargo Inspection Market
Security and Surveillance
Security Operations Center Market
Security and Surveillance
Stadium Security Market
Security and Surveillance
Global Physical Security Software Market
Security and Surveillance
Air Cargo Security Equipment Market
Security and Surveillance
Crowdsourced Security Market
Security and Surveillance
North America Urban Security Screening Market
Security and Surveillance
North America People Screening Market
Security and Surveillance
Security Holograms Market
Security and Surveillance
Europe People Screening Market
Security and Surveillance
Explosive Detection Technology Market
Security and Surveillance
Prescriptive Security Market
Security and Surveillance
Door and Window Alarm Market
Security and Surveillance
Europe Security Screening Market
Security and Surveillance
India Electronic Security Market
Security and Surveillance
Global Cargo Inspection Market