
 Global Manned Security Service Market | 2026-2036
Global Manned Security Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Manned Security Service Market Foresight
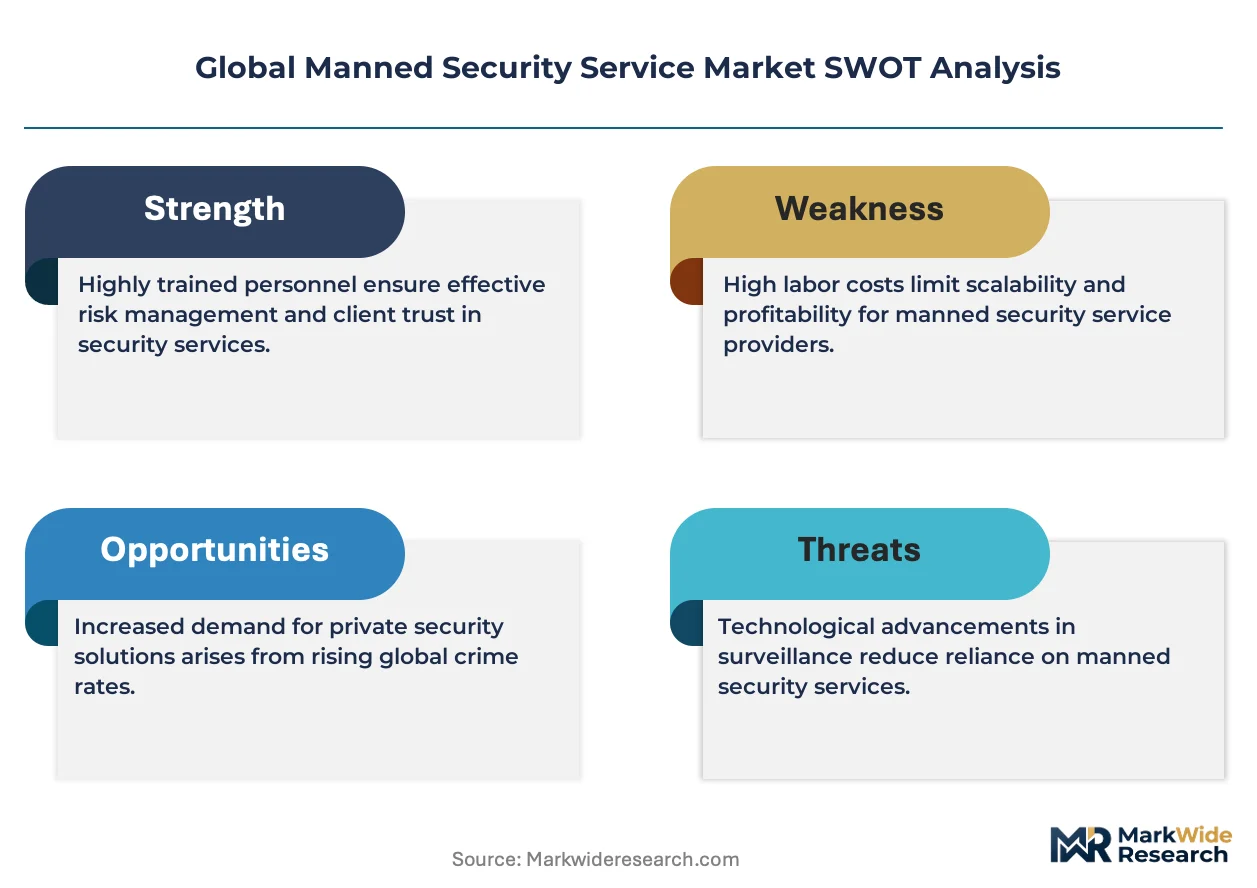
AI-augmented surveillance is fragmenting traditional manned security into hybrid human-machine service models. Securitas AB leverages its technology-forward command centers to blend live guards with real-time analytics. Allied Universal sustains scale advantages through its national account footprint across North American commercial real estate. G4S anchors its competitive stance with specialized risk consulting bundled into frontline guarding contracts.
Manned security services deploy trained personnel for physical asset protection, access control, and incident response, typically operating through 24/7 shift rotations with GPS-tracked patrol routes and centralized dispatch coordination. The service type segment shows armed guard deployments retaining premium pricing in high-risk environments while remote guarding gains traction as a cost-layered alternative. Within security application, commercial facilities and event management represent divergent margin structures—long-term facility contracts stabilize revenue against event-driven volatility. Client type segmentation reveals government entities and financial firms as the most compliance-intensive buyers, driving demand for cleared personnel and audit-ready reporting protocols.
The US Department of Homeland Security and the UK's Security Industry Authority shape guard licensing standards, while India's Private Security Agencies Regulation Act mandates training minimums that filter market entry. OSHA workplace safety rules and EU GDPR provisions on surveillance data handling further constrain how guarding firms deploy body cameras and biometric access logs. Stakeholders must weigh regulatory compliance costs against the pricing power that certified, well-trained guard forces command in contract negotiations.
Market Dynamics
The EU AI Act mandates human-in-the-loop verification for automated surveillance, forcing security providers to retain live personnel alongside algorithmic systems. This regulatory architecture is compressing pure-play technology vendors while elevating trained guard forces to compliance-critical infrastructure.
Growth Catalysts
- Critical Infrastructure Protection Mandates:Nuclear facilities, airports, and power grids across Germany, France, and Japan require cleared personnel for perimeter defense under national security directives.
- Data Center Physical Security Expansion:Hyperscale cloud operators in Virginia, Dublin, and Singapore are scaling guard forces to satisfy insurer requirements for on-site incident response.
- Event Security Liability Pressures:Mass gathering organizers in Brazil, Saudi Arabia, and Australia face strict venue certification standards that mandate licensed crowd control specialists.
Market Restraints
- Wage Compression in Labor Supply:Guard turnover rates spike when regional minimum wage ordinances in California, Ontario, and New South Wales outpace contract escalation clauses.
- Insurance Premium Volatility:Armed guard deployments carry liability coverage costs that fluctuate with firearms incident frequency in high-crime urban corridors.
- Biometric Surveillance Substitution:Facial recognition access systems at Frankfurt and Dubai airports are displacing manual ID verification roles in controlled zones.
Strategic Opportunities
- India Industrial Corridor Expansion:The Dedicated Freight Corridor and semiconductor fabrication plants in Gujarat and Tamil Nadu require integrated guarding for construction through operational phases.
- Healthcare Facility Security Gaps:Emergency departments in Chicago, London, and Melbourne report rising violence incidents, creating demand for de-escalation-trained personnel.
- Drone-Guard Convergence:Patrolling algorithms from Israeli and South Korean defense contractors enable single operators to supervise multiple autonomous aerial surveillance units.
Industry Challenges
- Cleared Personnel Pipeline Constraints:Background investigation backlogs at national security agencies in the US, UK, and Australia delay deployment of guards to sensitive sites.
- Legacy Access System Integration:Decades-old badging infrastructure at federal buildings and corporate campuses resists API connectivity with modern guard tour verification platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Manned Security Service Market |
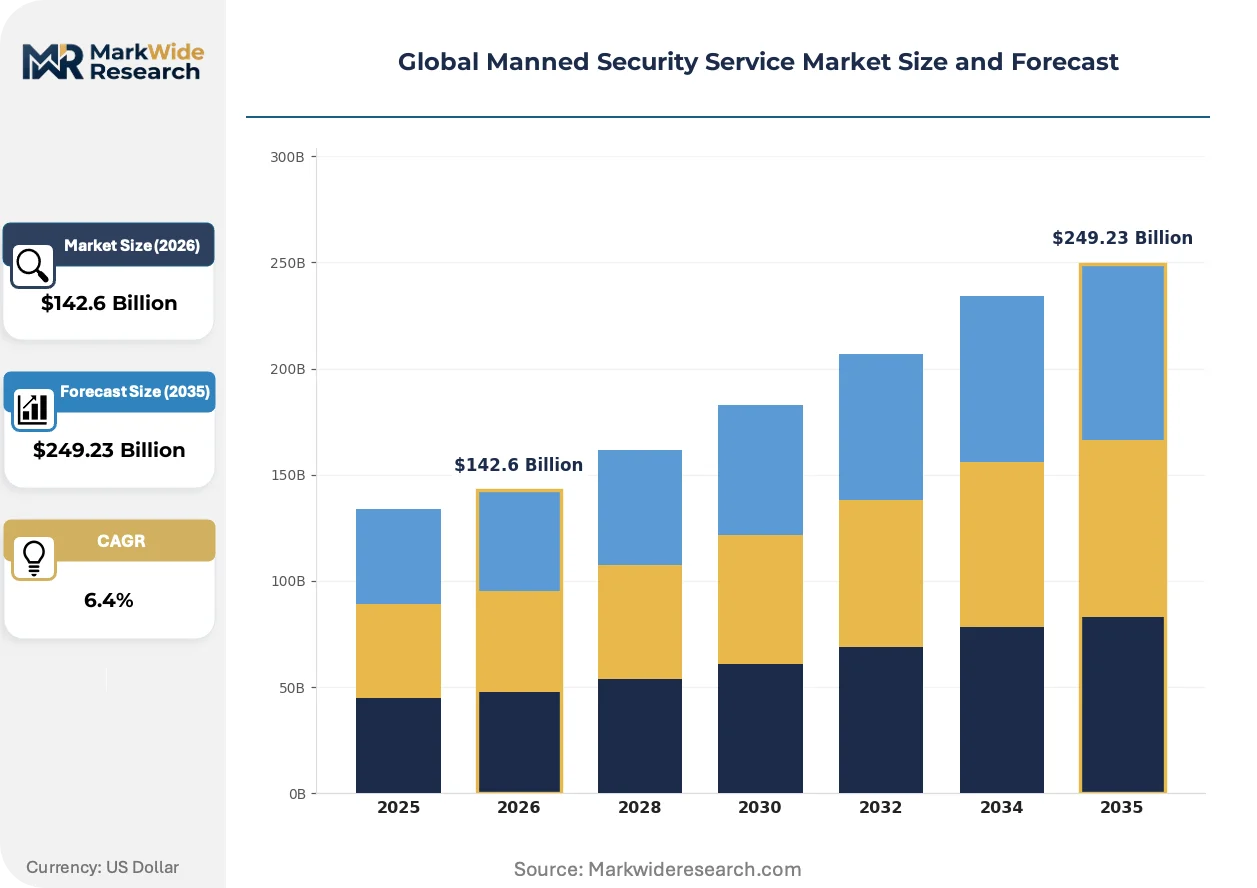
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $249.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Armed Guard, Unarmed Guard, Mobile Patrol, Remote Guarding, Concierge Services Security Application: Residential, Commercial Facilities, Industrial Plants, Construction Sites, Event Management Client Type: Corporations, Government Entities, Educational Institutions, Hospitality Sector, Financial Firms Contract Duration: Short Term, Long Term, Project Based, Retainer Agreements |
| Companies Covered | G4S, Securitas AB, Allied Universal, Prosegur, GardaWorld, ICTS Europe, SIS India, Axis Security, Transguard Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Manned Security Service Market Shifts & Advancements
Physical security operations are converging with real-time data analytics, compressing response timelines while expanding the scope of guard responsibilities beyond static observation.
Video analytics platforms with edge-computing capability are hybridizing guard deployment models. Casino operators in Macau and Native American gaming jurisdictions deploy AI-enhanced surveillance that flags behavioral anomalies for immediate human verification. This architecture preserves regulatory compliance while reducing floor-walking headcount by concentrating guard attention on algorithmically prioritized incidents.
GDPR Article 9 restrictions on biometric data processing are forcing European security buyers to retain manual identity verification protocols. Financial institutions in Frankfurt, Amsterdam, and Zurich cannot deploy facial recognition for employee access without explicit consent frameworks, sustaining demand for reception-based guard verification that US counterparts are automating.
Buyers are unbundling long-term guarding contracts into modular service components. Pharmaceutical manufacturers in Basel, Boston, and Hyderabad now source patrol services, executive protection, and emergency response through separate vendors rather than single-source national accounts. This fragmentation rewards regional specialists with cleared personnel networks while pressuring integrated providers to demonstrate cost transparency.
Global Manned Security Service Market Segmentation
Service differentiation in manned security determines pricing power, training requirements, and liability exposure. Buyers segment contracts by risk profile, regulatory intensity, and operational continuity needs rather than uniform hourly rates.
Service Type:
Cost tier stratification separates premium armed deployments from scalable unarmed and technology-augmented alternatives.
- Armed Guard:Personnel carry licensed firearms with state-mandated qualification protocols and continuous firearms proficiency testing. Nuclear facilities in France and Japan require cleared armed personnel for perimeter defense under national security directives. Insurance premiums and liability coverage costs fluctuate with regional firearms incident frequency.
- Remote Guarding:Centralized operators monitor video feeds and sensor networks to dispatch mobile response units on verified triggers. Hyperscale data centers in Virginia and Singapore deploy remote guarding to satisfy insurer requirements for continuous surveillance coverage at reduced headcount.
- Unarmed Guard:Access control and observation-focused personnel deployed in retail, corporate reception, and low-risk industrial settings.
- Mobile Patrol:Vehicle-based guards conducting randomized route inspections with GPS-tracked verification for commercial and residential portfolios.
- Concierge Services:Customer-facing security-reception hybrid roles in luxury residential and corporate environments requiring hospitality training.
Armed Guard commands the established base. The steepest expansion runs through Remote Guarding.
Security Application:
Application context dictates margin structure—long-term facility contracts stabilize revenue against event-driven volatility.
- Commercial Facilities:Office complexes, retail centers, and mixed-use developments require 24/7 lobby presence and after-hours patrol. Long-term contracts with national real estate investment trusts in Germany and the United States provide recurring revenue bases with annual escalation clauses tied to labor indices.
- Event Management:Temporary deployments for sports venues, concerts, and conventions with surge staffing and crowd control specialization. Mass gathering organizers in Brazil and Australia face strict venue certification standards that mandate licensed crowd control specialists and drive premium pricing during peak seasons.
- Residential:Gated communities and high-rise buildings requiring access control and emergency response coordination.
- Industrial Plants:Manufacturing and chemical processing sites with hazardous material protocols and union coordination requirements.
- Construction Sites:Temporary perimeter protection for active developments with equipment theft prevention and vandalism deterrence.
Commercial Facilities anchor contract volume. Event Management captures the highest margin volatility.
Client Type:
Customer type determines compliance burden—government and financial buyers impose cleared personnel mandates and audit-ready reporting.
- Government Entities:Federal, state, and municipal contracts requiring security clearance eligibility and chain-of-custody documentation. Background investigation backlogs at national security agencies in the United States, United Kingdom, and Australia delay deployment to sensitive sites and constrain supplier capacity.
- Financial Firms:Banks, insurance companies, and asset managers with regulatory mandates for physical access logs and business continuity planning. Frankfurt and Zurich institutions retain manual identity verification to satisfy GDPR Article 9 restrictions on biometric consent frameworks.
- Corporations:Private sector commercial and industrial buyers with standardized procurement and multi-site contract consolidation.
- Educational Institutions:Universities and K-12 districts with campus safety mandates and parent communication protocols.
- Hospitality Sector:Hotels, resorts, and entertainment venues requiring guest-facing security with de-escalation training.
Corporations generate the broadest contract flow. Government Entities impose the strictest qualification barriers.
Contract Duration:
Duration structure balances revenue predictability against pricing flexibility in volatile labor markets.
- Long Term:Multi-year agreements with fixed escalation schedules and dedicated account management. Corporate campuses and data center operators in Ireland and Singapore favor long-term contracts to ensure continuity and reduce procurement overhead.
- Project Based:Defined-scope engagements for construction phases, facility openings, or security system transitions. India's Dedicated Freight Corridor and semiconductor fabrication plants in Gujarat require integrated guarding from construction through operational phases.
- Short Term:Emergency coverage, staff augmentation, and interim security during system failures or threat escalations.
- Retainer Agreements:On-call executive protection and emergency response with guaranteed response times and pre-negotiated rates.
Long Term contracts secure the revenue base. Project Based engagements expand most quickly in infrastructure-heavy economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate campuses and data center operators in the United States, Germany, and India are expanding guard forces for access control and threat response. The EU AI Act is prompting European buyers to retain human verification layers alongside automated surveillance systems.
United States
Hyperscale cloud operators in Virginia and Texas are scaling guard forces to satisfy insurer requirements for on-site incident response. OSHA workplace safety rules constrain how guarding firms deploy body cameras and biometric access logs. The Northern Virginia data center corridor anchors demand for cleared personnel with security clearance eligibility.
Germany
Nuclear facilities and power grids across Bavaria and Baden-Württemberg require cleared personnel for perimeter defense under national security directives. The EU AI Act mandates human-in-the-loop verification for automated surveillance, elevating trained guard forces to compliance-critical infrastructure. Frankfurt financial institutions retain manual identity verification to satisfy GDPR Article 9 restrictions on biometric consent frameworks.
India
The Dedicated Freight Corridor and semiconductor fabrication plants in Gujarat and Tamil Nadu require integrated guarding from construction through operational phases. India's Private Security Agencies Regulation Act mandates training minimums that filter market entry. SIS India and Transguard Group are scaling trained guard forces for industrial and infrastructure clients across the industrial corridor expansion.
United Kingdom
Mass gathering organizers in London and Manchester face strict venue certification standards that mandate licensed crowd control specialists. The Security Industry Authority shapes guard licensing standards with background investigation backlogs delaying deployment to sensitive sites. The London financial district sustains demand for reception-based guard verification that automated systems cannot fully replace.
United Arab Emirates
Airports in Dubai and Abu Dhabi are deploying facial recognition access systems that displace manual ID verification roles in controlled zones. MOHAP regulations govern healthcare facility security where emergency departments report rising violence incidents. The Dubai Expo legacy developments and NEOM construction sustain demand for construction-phase perimeter protection and operational guarding contracts.
Global Manned Security Service Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a consolidated tier-one segment and a fragmented long tail. The market structure concentrates around multinational guard service providers with national account footprints, regional specialists with cleared personnel networks, and technology-forward command center operators. Three strategic archetypes dominate: scale-driven integrated providers bundling risk consulting, technology-augmented operators blending live guards with real-time analytics, and regional specialists serving compliance-intensive government and financial contracts. M&A activity and portfolio diversification into remote guarding capabilities represent the dominant competitive moves as firms respond to wage compression and biometric substitution pressures.
Within the technology-augmented tier, Securitas AB exemplifies the command center-forward model blending live personnel with analytics platforms. Allied Universal occupies a position representing scale-driven national account coverage across North American commercial real estate. G4S anchors the risk consulting-bundled archetype with specialized frontline guarding contracts. SIS India and Transguard Group represent the regional specialist model scaling trained forces for industrial corridor expansion in infrastructure-heavy economies.
| Leading Market Players |
|---|
| G4S |
| Securitas AB |
| Allied Universal |
| Prosegur |
| GardaWorld |
| ICTS Europe |
| SIS India |
| Axis Security |
| Transguard Group |
| Others |
Supply & Pricing Matrix
The Dedicated Freight Corridor's logistics cost dynamics concentrate supply-side guard force deployment around Indian industrial clusters while downstream price differentiation separates premium armed details from scalable unarmed patrols across contract tiers.
Pricing Analysis
Cost-plus contracts with labor indexation dominate long-term facility agreements, particularly for data center operators in Virginia and Singapore seeking rate predictability. Price differentiation rests on security clearance tier and firearms certification level, with cleared armed personnel commanding substantial premiums over standard unarmed guards. Pricing pressure stems from California and Ontario minimum wage ordinances outpacing contract escalation clauses. Government entities exhibit the lowest price sensitivity due to compliance mandates, while retail chains demonstrate acute sensitivity to per-hour rate increases.
Supply Chain Analysis
Contract-manufacturing concentration in India's security training infrastructure filters through SIS India and Transguard Group capacity, with secondary guard force development in the Philippines and Nigeria. Raw material dependencies center on uniform and equipment suppliers, vehicle fleet procurement, and biometric hardware components. Single-source vulnerability runs through national background investigation agencies in the US, UK, and Australia delaying cleared personnel deployment. Distribution runs through regional branch networks with centralized dispatch coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global manned security services are recovering from pandemic-induced contract suspensions as corporate facility reopenings and infrastructure construction normalize guard force utilization rates.
For Market Incumbents: Insulate margin structures by embedding remote guarding capabilities into existing national accounts, reducing headcount exposure to wage compression. Pursue backward integration into proprietary training academies to control cleared personnel pipeline constraints and differentiate against technology-only entrants. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with healthcare facility security gaps in Melbourne and Chicago offering secondary white-space. Drone-guard convergence partnerships with Israeli defense contractors provide a technology-forward go-to-market angle against established patrol providers. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate-owned security subsidiaries lacking standalone technology platforms. Long-term viability favors operators with command center infrastructure capable of hybrid human-machine service delivery. Monitor EU AI Act implementation timelines as the signal to watch for regulatory-driven demand inflection toward human verification layers.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Guarding Platform Deployment | Enables Securitas AB and Allied Universal to satisfy insurer requirements at reduced headcount for Virginia data centers. |
| Cleared Personnel Pipeline Investment | Addresses background investigation backlogs at US national security agencies constraining sensitive site deployment. |
| Drone-Guard Convergence Partnership | Leverages Israeli and South Korean defense contractor algorithms for single-operator multi-drone supervision. |
| Healthcare De-escalation Training Certification | Captures rising violence incident response demand in Chicago and London emergency departments. |
| India Industrial Corridor Expansion | Positions SIS India and Transguard Group for integrated construction-to-operations guarding contracts in Gujarat. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with security operations directors, facility managers at hyperscale data centers, government procurement officers, and insurance risk assessors. Secondary validation drew from SEC filings of listed guard services firms, EU regulatory documentation on the AI Act, India's Private Security Agencies Regulation Act compliance records, and OSHA workplace safety enforcement data. Bottom-up contract value aggregation triangulated against top-down market sizing from national employment statistics.
Calibration against historical contract renewal rates and labor cost indices anchored the analytical framework across the analysis window. Segmentation dimensions modeled include service type tier, security application context, client compliance intensity, and contract duration structure. CAGRs derived from weighted average of guard force headcount projections and hourly rate escalation assumptions, with specific inputs from data center construction pipelines and critical infrastructure protection mandates.
Macroeconomic conditions sit as an overlay; deviation in regional minimum wage trajectories and liability insurance premium volatility would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation timing and technology substitution rates. Quarterly review of guard turnover metrics and background investigation queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Law Enforcement Software Market
Security and Surveillance
Global Alarm Monitoring Market
Security and Surveillance
North America Cargo and Vehicle Screening Market
Security and Surveillance
Full Body Scanner Market
Security and Surveillance
Ballistic Protection Scanners Market
Security and Surveillance
Middle East and Africa Cargo and Vehicle Screening Market
Security and Surveillance
Smart Home Security Market
Security and Surveillance
Situational Awareness System Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
Europe Anti-Piracy Protection Market
Security and Surveillance
Manned Guarding Services Market
Security and Surveillance
Intelligent Fencing Market
Security and Surveillance
Europe Security Screening Market
Security and Surveillance
Global Security Advisory Services Market
Security and Surveillance
Proactive Security Market
Security and Surveillance
Stadium Security Market