
 Night Vision Binoculars Market | 2026-2036
Night Vision Binoculars Market Size, Share, and Industry Trends Forecast 2026-2036
Night Vision Binoculars Market Analysis
Wildlife enthusiast demand is hardening into a credible commercial vertical alongside traditional military procurement. L3Harris anchors defense-grade Gen 3 supply through ITAR-controlled manufacturing in the United States. Pulsar competes across European civilian hunting channels with thermal-digital hybrid architectures. AGM Global Vision specializes in cost-digital entry points for outdoor recreation buyers in North America.
Night vision binoculars amplify ambient or infrared light through image intensifier tubes or digital CMOS sensors paired with near-infrared illuminators, enabling human vision below 10⁻³ lux. Their primary purpose spans tactical maneuvering, nocturnal wildlife observation, and perimeter security in zero-illumination environments. Gen 3 image intensification leads military procurement due to gallium arsenide photocathode sensitivity, while digital binoculars represent the fastest-growing structural segment as CMOS costs fall and thermal fusion expands. Infrared technology occupies the deepest margin pools where sensor fusion commands premium positioning across surveillance applications.
ITAR restrictions in the United States limit Gen 3 tube export, while the EU Green Deal pushes mercury-free photocathode alternatives under REACH substance controls. CE marking and the EU AI Act increasingly govern digital units with embedded scene analytics. Stakeholders must monitor photocathode material substitutions and thermal-digital fusion roadmaps as regulatory and operational requirements diverge across defense and civilian channels.
Market Dynamics
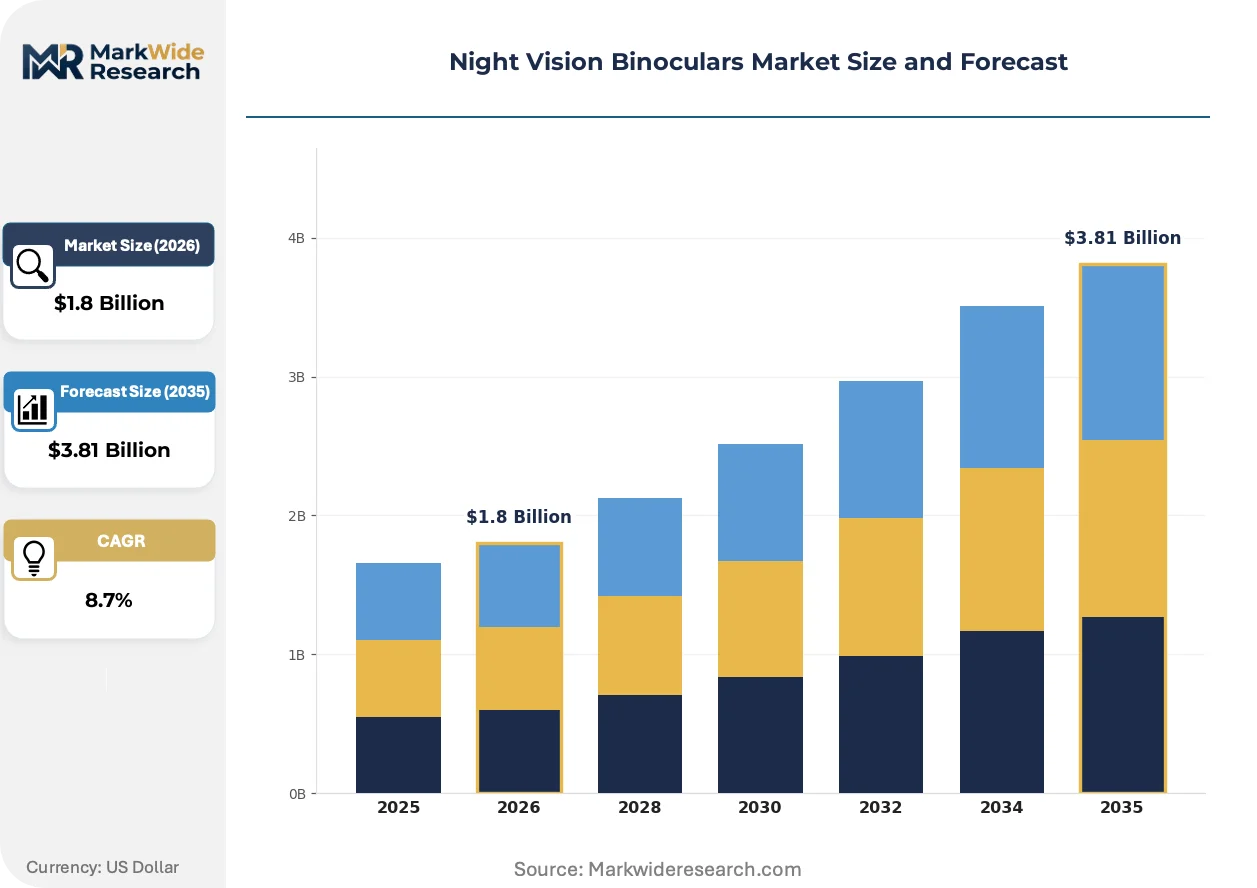
ITAR-controlled gallium arsenide photocathode supply from the United States is concentrating military-grade Gen 3 image intensifier procurement, while falling CMOS costs are absorbing demand across commercial thermal-digital hybrid segments.
Growth Catalysts
- Defense procurement hardening:United States, Germany, and China are expanding night operations capabilities across border security and special operations units, anchoring volume demand for Gen 3 systems.
- REACH substance controls:The EU Green Deal is accelerating mercury-free photocathode R&D, creating regulatory pull for alternative intensifier chemistries in European defense tenders.
- Thermal-digital fusion:CMOS sensor cost curves are enabling multi-spectral architectures that combine near-infrared intensification with uncooled thermal cores for surveillance applications.
Market Restraints
- ITAR export friction:United States State Department controls on Gen 3 tube technology limit cross-border transfer to NATO allies, fragmenting supply access for non-aligned defense buyers.
- Photocathode material concentration:Gallium arsenide substrate supply chains center on specialized compound semiconductor foundries with limited surge capacity.
- Digital latency limitations:CMOS-based digital night vision exhibits microsecond display lag unsuitable for high-velocity targeting applications, preserving Gen 3 dominance in military procurement.
Strategic Opportunities
- Wildlife tourism vertical:Kenya, Botswana, and South Africa are developing night safari experiences, creating demand for ruggedized civilian binoculars with extended battery autonomy.
- EU AI Act compliance:Embedded scene analytics in digital units face emerging algorithmic transparency requirements, opening certification services and firmware localization markets.
- Thermal-digital convergence:Fusion of uncooled microbolometer arrays with low-light CMOS is enabling single-eyepiece multi-spectral devices for search-and-rescue operations.
Industry Challenges
- Image intensifier tube craftsmanship:Hand-assembly of Gen 3 photocathodes requires skilled technicians with decade-long training curves, constraining output scaling at established manufacturers.
- Dual-use classification complexity:Export control harmonization between ITAR, Wassenaar Arrangement, and national dual-use lists creates licensing delays for thermal-digital hybrid systems.
- Legacy system integration:NATO-standard helmet mount interfaces differ from proprietary rail systems, forcing accessory manufacturers to maintain multiple mechanical adapter SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Night Vision Binoculars Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Binoculars, Gen 1, Gen 2, Gen 3 End User: Military, Wildlife Enthusiasts, Security, Sport Shooters Technology: Infrared, Image Intensification, Low-Light, Thermal Application: Surveillance, Hunting, Outdoor Recreation, Search and Rescue |
| Companies Covered | Nightfox, Akaso, ATN, CIGMAN, WOSPORTS, L3Harris, Bushnell, Pulsar, AGM Global Vision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Night Vision Binoculars Market Emerging Trajectories
Thermal-digital hybrid architectures are compressing the performance gap with Gen 3 image intensification, while regulatory pressure on hazardous substances and AI-enabled analytics is reshaping product roadmaps across defense and civilian channels.
Uncooled vanadium oxide microbolometer arrays are absorbing price points previously occupied by entry-level Gen 2+ image intensifiers. European hunting cooperatives and North American predator control operators are adopting these thermal-digital units for positive target identification without supplemental infrared illumination. The technology is absorbing market share from pure digital night vision in scenarios where ambient light is unreliable.
The EU AI Act's risk classification framework is imposing documentation burdens on digital binoculars with embedded object detection algorithms. Manufacturers serving European law enforcement must now maintain technical files demonstrating algorithmic transparency and human oversight protocols. Border security agencies in Germany and France are requiring CE-marked units with explicit AI conformity assessments, favoring suppliers with pre-positioned compliance infrastructure.
Direct-to-consumer channels are displacing traditional sporting goods distribution for civilian night vision in North America. Specialty retailers with technical demonstration capabilities are capturing enthusiast buyers who previously purchased through generalist outdoor chains. This channel rotation is most pronounced in Texas, Arizona, and Florida, where hog hunting and predator management drive recurring equipment upgrades.
Night Vision Binoculars Market Segmentation
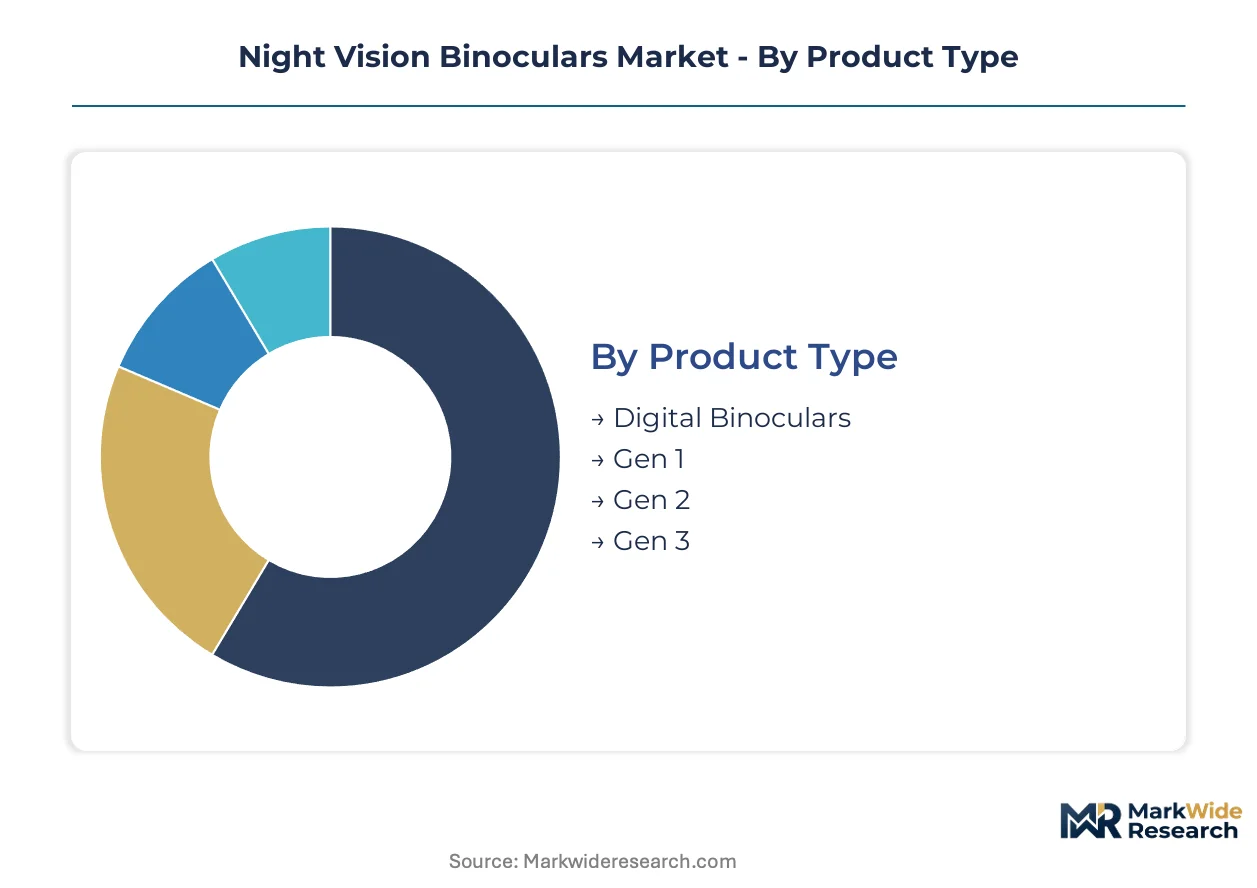
Segmentation in night vision binoculars reveals how procurement cycles diverge between defense-grade image intensification and consumer digital adoption. Technology tiers and end-use applications create distinct margin pools with incompatible replacement rhythms.
Product Type:
Upgrade cycles vary dramatically across generations, with military procurement favoring decade-long Gen 3 service intervals while digital platforms refresh every 2-3 years.
- Gen 3:Gallium arsenide photocathodes deliver sensitivity below 10⁻⁴ lux for special operations and border security units. United States ITAR controls restrict export, concentrating demand within NATO-aligned defense agencies with approved Foreign Military Sales channels.
- Digital Binoculars:CMOS sensors paired with near-infrared illuminators offer onboard recording and wireless transmission for law enforcement documentation. European border agencies in Germany and France are specifying these units for checkpoint identity verification under EU AI Act transparency requirements.
- Gen 2:Multi-alkali photocathode technology serves cost-constrained security contractors with adequate performance for perimeter monitoring.
- Gen 1:Entry-level vacuum tube architecture persists in emerging market civilian channels with minimal ambient light amplification.
Gen 3 sits at the top of the volume ranking, with Digital Binoculars climbing the fastest.
End User:
Customer types fragment procurement authority across classified defense budgets, commercial retail channels, and institutional security frameworks.
- Military:Special operations forces and infantry units drive specifications for helmet-mounted binocular systems with weapon interface compatibility. United States Army PEO Soldier and German Bundeswehr BAAINBw procurement offices anchor volume through multi-year framework agreements.
- Security:Private critical infrastructure operators and municipal law enforcement purchase digital and thermal units for perimeter surveillance. German federal police specifications under BSI technical guidelines favor CE-marked devices with documented cybersecurity protocols.
- Wildlife Enthusiasts:Safari operators in Kenya and Botswana specify ruggedized housings with extended battery autonomy for multi-hour nocturnal observation.
- Sport Shooters:Predator control operators in Texas and Florida drive demand for thermal-positive identification without supplemental illumination.
Military commands the largest revenue share, with Security expanding most quickly through infrastructure hardening mandates.
Technology:
Core sensing architectures determine performance ceilings and regulatory exposure across defense and civilian deployment scenarios.
- Image Intensification:Vacuum tube technology amplifies ambient photons through multi-stage microchannel plates. ITAR-controlled Gen 3 supply from United States manufacturers limits accessible volume for non-aligned defense buyers.
- Thermal:Uncooled vanadium oxide microbolometer arrays detect emitted infrared radiation independent of ambient illumination. European hunting cooperatives are absorbing price-competitive units previously occupied by Gen 2+ intensifiers.
- Infrared:Active near-infrared illumination paired with digital sensors enables zero-light operation with detectable signature trade-offs.
- Low-Light:Enhanced CMOS sensitivity without supplemental illumination serves moonlit observation scenarios with minimal power draw.
Image Intensification retains the highest unit values, with Thermal gaining share fastest through cost curve compression.
Application:
Use-case requirements dictate optical specifications, durability standards, and integration complexity across deployed environments.
- Surveillance:Fixed and mobile observation posts demand extended-range identification with tripod-mounted stability. German Federal Police and French Gendarmerie procurement specifications prioritize fusion-capable units combining thermal cores with digital intensification.
- Hunting:Mobile stalking applications require lightweight head-mounted or handheld configurations with rapid target acquisition. Direct-to-consumer channels in Texas, Arizona, and Florida are displacing traditional sporting goods distribution for technical demonstration and upgrade cycles.
- Search and Rescue:Multi-spectral fusion enables victim location through heat signature detection in low-visibility terrain.
- Outdoor Recreation:Camping and hiking users prioritize battery efficiency and weather sealing over optical performance extremes.
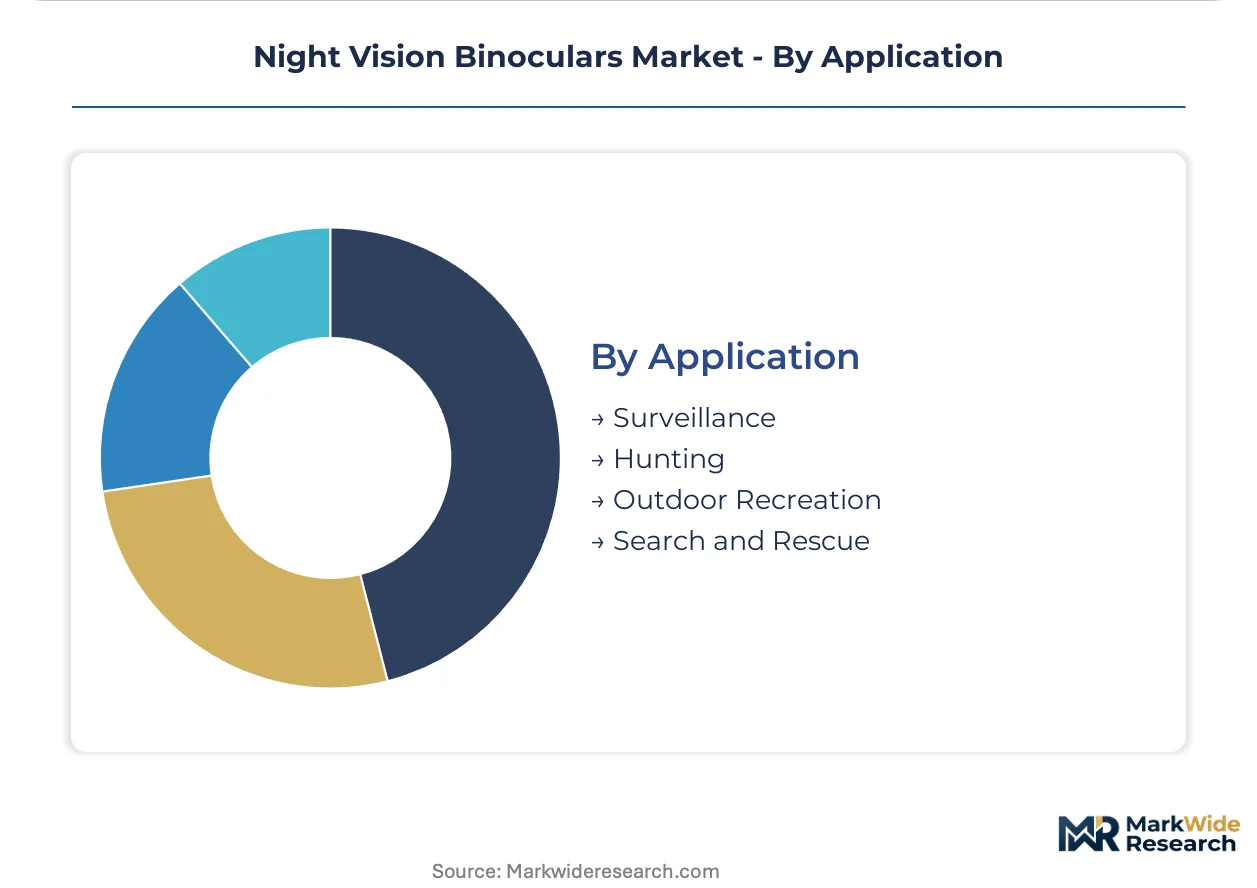
Surveillance generates the highest average selling prices, with Hunting showing the steepest volume expansion through civilian channel rotation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investment toward jurisdictions with lower compliance burdens on photocathode materials and AI-enabled sensor systems. Production migration patterns reflect divergent substance controls and export licensing frameworks across major defense procurement markets.
United States
ITAR-controlled gallium arsenide photocathode supply anchors military-grade Gen 3 procurement through Foreign Military Sales channels. The State Department's Directorate of Defense Trade Controls restricts tube technology transfer to NATO-aligned buyers. Rochester, New York hosts concentrated image intensifier craftsmanship clusters where L3Harris maintains specialized manufacturing.
Germany
Bundeswehr BAAINBw procurement offices drive framework agreements for helmet-mounted binocular systems with NATO-standard interfaces. The EU Green Deal accelerates mercury-free photocathode alternatives under REACH substance controls. Oberkochen and Wetzlar optics clusters specialize in precision glass and coating technologies for intensifier tubes.
China
Domestic defense agencies expand night operations capabilities across border security and special operations units. MIIT standards govern dual-use technology classification for thermal-digital hybrid exports. Shenzhen and Chengdu electronics corridors concentrate CMOS sensor and microbolometer array manufacturing.
France
Gendarmerie procurement specifications prioritize fusion-capable units combining thermal cores with digital intensification under EU AI Act transparency requirements. ANSM and CNIL oversight extends to algorithmic documentation for embedded scene analytics. Paris-Saclay research clusters advance multi-spectral sensor fusion architectures.
South Africa
Safari operators in Kruger and Kgalagadi regions develop night tourism experiences demanding ruggedized civilian binoculars with extended battery autonomy. The country's national defense regulator oversees import licensing for ITAR-controlled technologies. Pretoria-Tshwane manufacturing corridors assemble entry-level digital units for regional distribution.
Night Vision Binoculars Market Vendor Landscape
Technology licensing dominates the current landscape as manufacturers navigate ITAR restrictions and REACH substance controls. The vendor base stratifies across defense-grade intensifier specialists, thermal-digital hybrid innovators, and cost-optimized digital entrants. Three archetypes anchor competitive positioning: ITAR-captive Gen 3 manufacturers serving NATO defense agencies, European thermal-digital integrators exploiting regulatory arbitrage on mercury-free alternatives, and Asian CMOS-scale producers capturing civilian price points. Portfolio diversification and geographic licensing partnerships represent the dominant competitive vectors.
Within the ITAR-captive tier, L3Harris represents concentrated gallium arsenide photocathode supply. Among European thermal-digital specialists, Pulsar exemplifies multi-spectral architecture development. At the cost-optimized digital entry point, AGM Global Vision occupies a position serving North American outdoor recreation channels.
| Leading Market Players |
|---|
| Nightfox |
| Akaso |
| ATN |
| CIGMAN |
| WOSPORTS |
| L3Harris |
| Bushnell |
| Pulsar |
| AGM Global Vision |
| Others |
Supply Flow & Price Mechanics
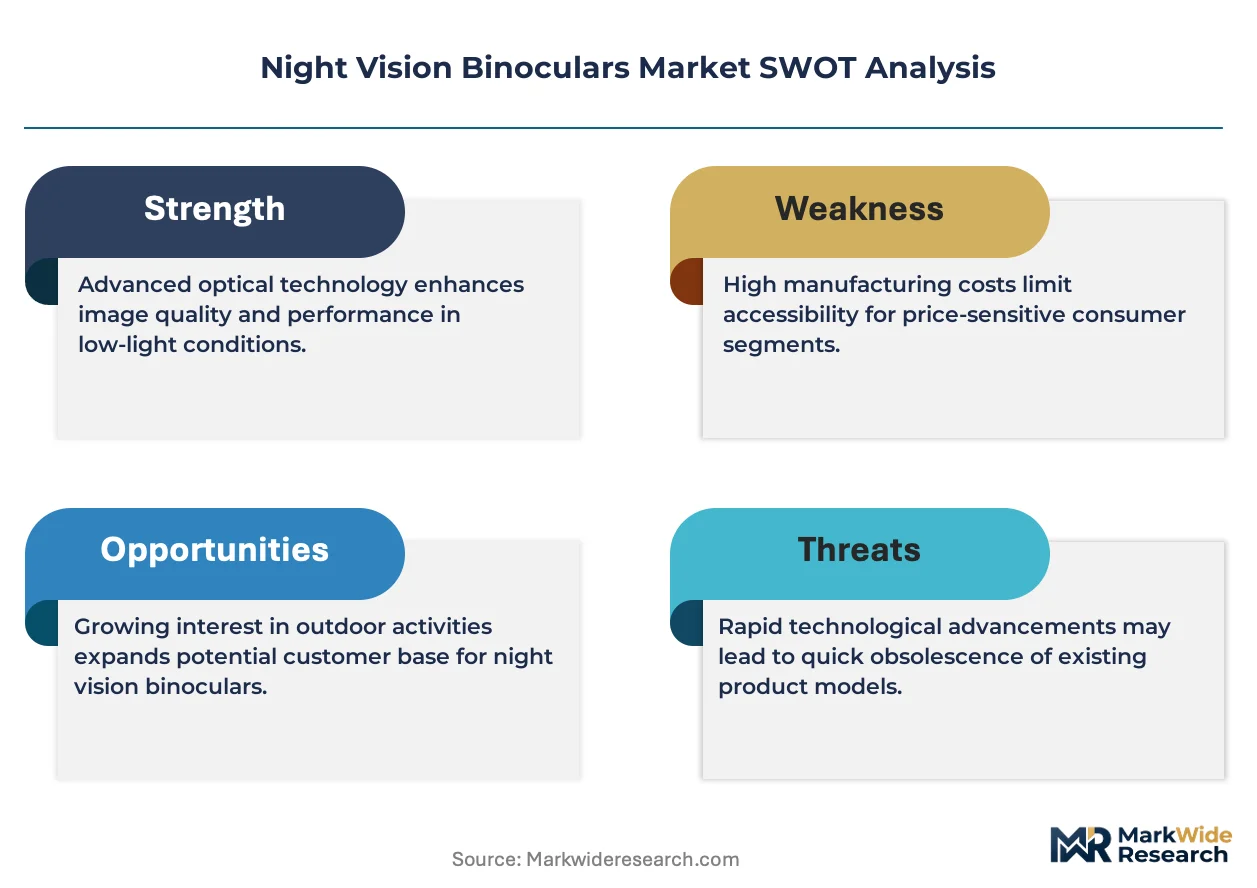
Defense procurement offices in the United States, Germany, and China are mandating helmet-mount compatibility and multi-spectral fusion capabilities, forcing suppliers to absorb certification costs and source specialized compound semiconductors that compress margins on fixed-price framework agreements.
Pricing Analysis
Distributor margins on ITAR-controlled Gen 3 systems absorb 25-35 points before Foreign Military Sales channels, while direct-to-consumer thermal-digital hybrids command slimmer retail markups through specialty hunting retailers. Three-tier pricing structure across ITAR-restricted defense grade, CE-marked professional tier, and uncertified consumer entry level separates procurement authorization levels. Cost compression in thermal sensor tiers stems from vanadium oxide microbolometer oversupply out of Chinese electronics corridors. Wildlife tourism operators in southern Africa exhibit highest price sensitivity due to battery replacement and ruggedization requirements, while United States special operations units show lowest sensitivity given decade-long service intervals and total cost of ownership frameworks.
Supply Chain Analysis
CE marking and ITAR qualification gates fragment supplier access, with only L3Harris and two European optics houses holding concurrent NATO-standard and EU AI Act documentation. Gallium arsenide photocathode supply centers on Rochester, New York and Oberkochen, Germany, while uncooled microbolometer arrays draw from Shenzhen and Chengdu manufacturing corridors. Image intensifier tube hand-assembly depends on mercury-based and mercury-free photocathode chemistries, microchannel plate glass substrates, and precision optical coating chambers. Single-source vulnerability concentrates in gallium arsenide substrate supply from specialized compound semiconductor foundries with decade-long technician training curves. Distribution runs through defense procurement offices with Foreign Military Sales authorization, European hunting cooperative buying groups, and direct-to-consumer specialty retailers with technical demonstration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in thermal-digital fusion architectures where CMOS cost curves enable premium positioning previously occupied by ITAR-restricted Gen 3 systems, and in certification services for EU AI Act compliance on embedded scene analytics.
For Market Incumbents: Cement ITAR-captive supply relationships through multi-year gallium arsenide photocathode offtake agreements with United States compound semiconductor foundries, while acquiring mercury-free photocathode R&D capabilities ahead of REACH substance control deadlines. Thermal-digital hybrid entrants from Asian electronics corridors threaten mid-tier professional positioning; vertical integration into microbolometer array calibration and firmware development preserves differentiation. For New Entrants and Emerging Players: Enter via wildlife tourism verticals in Kenya, Botswana, and South Africa where ruggedization and extended battery specifications outrank optical performance in procurement criteria. Safari operator cooperatives represent the most penetrable buyer segment given limited incumbent presence and price-sensitive volume demand. Go-to-market through regional hunting and outdoor recreation distributors with field demonstration capabilities rather than generalist retail chains. For Investors and Strategic Acquirers: Asymmetric upside sits with thermal-digital fusion specialists holding pre-positioned EU AI Act technical documentation and CE marking infrastructure. Long-term viability favors suppliers with dual-use technology licensing flexibility across defense and civilian channels, given diverging regulatory requirements. Acquisition targets include European thermal core integrators with algorithmic transparency protocols already filed with French ANSM and German BSI. Watch for ITAR export license expansion or contraction as the primary inflection signal on addressable market breadth.| Strategic Initiative | Industry Significance |
|---|---|
| Mercury-Free Photocathode R&D Partnership | REACH compliance under EU Green Deal secures German Bundeswehr tender eligibility ahead of substance bans. |
| Thermal-Digital Fusion Platform Launch | Uncooled microbolometer-CMOS integration captures surveillance demand from French Gendarmerie fusion specifications. |
| ITAR Manufacturing Footprint Expansion | Rochester, New York intensifier craftsmanship clusters anchor NATO Foreign Military Sales channel access. |
| EU AI Act Technical File Development | Algorithmic transparency documentation opens German federal police procurement under BSI cybersecurity guidelines. |
| Safari Distribution Channel Partnership | Kruger and Kgalagadi region operator relationships establish ruggedized civilian product validation and recurring battery revenue. |
Methodological Framework
Multiple input streams — primary interviews with defense procurement officers at United States Army PEO Soldier and German BAAINBw, thermal core engineering leads at European optics houses, and safari operator equipment buyers — were reconciled against customs records for image intensifier tube and microbolometer array trade flows, SEC filings from L3Harris and listed defense electronics suppliers, and EU tender documentation for CE-marked digital binocular specifications. Bottom-up unit shipment estimates by technology tier and top-down defense budget allocation analysis were triangulated against disclosed Foreign Military Sales values.
Historical procurement cycle analysis was cross-referenced against panel input from export control attorneys and compound semiconductor supply chain managers to establish technology transition timelines. Segmentation modeling spanned product generation, end-user procurement authority, core sensing architecture, and application environment across the projection horizon. CAGRs were derived from fitted adoption curves on thermal-digital hybrid penetration rates and documented replacement intervals for Gen 3 helmet-mounted systems. Forecast inputs included disclosed United States defense appropriations for night vision equipment, EU Green Deal implementation schedules for mercury-free alternatives, and CMOS sensor cost curve projections from electronics manufacturing databases.
Inputs from NATO defense procurement offices and European hunting cooperative purchasing managers were available through the study window; gaps in Chinese MIIT dual-use classification enforcement and non-aligned defense buyer access to ITAR-controlled supply introduce uncertainty bands on thermal-digital hybrid volume assumptions. Forecasts reflect documented procurement frameworks, substance control implementation timelines, and sensor cost trajectories. A model refresh is warranted upon material change in United States State Department export license policy or REACH substance ban acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Signal Jamming Systems Market
Security and Surveillance
Alarm Monitoring Software Market
Security and Surveillance
Global Container Security Market
Security and Surveillance
Prison Management Systems Market
Security and Surveillance
Global Wireless Doorbells Market
Security and Surveillance
North America Security Testing Market
Security and Surveillance
Underwater Security (Systems and Services) Market
Security and Surveillance
Sirens Market
Security and Surveillance
Global Police and Law Enforcement Equipment Market
Security and Surveillance
North America Security Services Market
Security and Surveillance
Europe Security Services Market
Security and Surveillance
Shock Sensor Market
Security and Surveillance
North America Wireless Monitoring and Surveillance Market
Security and Surveillance
Stadium Security Market
Security and Surveillance
Asia-Pacific Security Screening Market
Security and Surveillance
Private Military Security Services Market