
 Middle East and Africa Baggage and Parcel Screening Market | 2026-2036
Middle East and Africa Baggage and Parcel Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Baggage and Parcel Screening Market Insights
Saudi Arabia's aviation infrastructure expansion is fragmenting procurement patterns across the Middle East and Africa Baggage and Parcel Screening Market. Smiths Detection Group Ltd leverages its installed base at Heathrow-style hub airports to sustain service revenue across Riyadh and Jeddah installations. Nuctech Company Limited anchors its position through direct government relationships in African markets where price sensitivity dominates tender evaluations. Rapiscan Systems differentiates via computed tomography portfolios that meet emerging hold-baggage screening mandates.
Middle East and Africa baggage and parcel screening encompasses automated inspection systems utilizing ionizing radiation, dual-energy x-ray absorption, and computed tomography reconstruction to detect contraband, explosives, and weapons in luggage, cargo, and mail. These systems operate at 140-180 kV tube voltages with 0.5-2.0 mm steel penetration resolution, serving aviation security, critical infrastructure protection, and customs enforcement applications. Computed Tomography technology occupies the fastest-expanding margin pool as airports transition from 2-D x-ray to 3-D automated threat recognition. Airports application demand leads absolute volume, though Events segmentation accelerates as stadium and conference venue operators deploy parcel screening for VIP protection. Security Agencies end users control the largest procurement budget share through national aviation authority mandates.
Saudi Arabia's General Authority of Civil Aviation, South Africa's Civil Aviation Authority, and the UAE's General Civil Aviation Authority enforce hold-baggage and checkpoint screening standards that shape vendor certification requirements and product development priorities. Compliance with these national aviation regulators forces system upgrades when protocols incorporate new explosive detection sensitivity thresholds. Stakeholders must monitor how Egypt and Morocco adopt similar regulatory stringency, as these markets will determine whether regional vendors achieve scale or remain fragmented across bilateral procurement relationships.
Market Dynamics
The transition from 2-D x-ray to 3-D computed tomography screening is compressing upgrade cycles across Middle East and African aviation hubs, forcing capital redeployment toward automated threat recognition platforms.
Growth Catalysts
- UAE Federal Transport Standards:Mandates for explosive detection sensitivity at Dubai International Airport and Abu Dhabi terminals are accelerating replacement of legacy single-view systems.
- Saudi GACA Protocols:Hold-baggage screening mandates at Riyadh and Jeddah hubs are creating sustained procurement pipelines for certified CT platforms.
- Port Modernization:Nigeria's customs infrastructure investments at Lagos and Port Harcourt are expanding parcel screening demand beyond aviation into maritime security applications.
Market Restraints
- Helium-3 Supply Concentration:Neutron detection systems face input scarcity as US Department of Energy export controls limit alternative sourcing for explosive trace detectors.
- Technical Limitation:Battery-powered portable screening units lack the 140-180 kV tube voltage required for dense cargo penetration, constraining deployment flexibility at remote African checkpoints.
- Regulatory Friction:Divergent certification timelines between Saudi Arabia's General Authority of Civil Aviation and South Africa's Civil Aviation Authority fragment vendor compliance costs across the region.
Strategic Opportunities
- Underpenetrated Geography:Egypt's Cairo International Airport and Morocco's Casablanca Mohammed V Airport represent untapped volume as regulatory stringency converges with Gulf standards.
- Technology Convergence:Integration of artificial intelligence threat libraries with CT reconstruction algorithms is opening automated screening retrofits for mid-tier African terminals.
- Events Application:Stadium and conference venue operators in Qatar and the UAE are deploying parcel screening for VIP protection, diversifying demand beyond aviation infrastructure.
Industry Challenges
- Certification Timeline Compression:Vendor qualification periods with national aviation authorities now extend 18-24 months, delaying revenue recognition for new platform introductions.
- Integration Complexity:Legacy 2-D x-ray installations at secondary African airports require extensive conveyor reconfiguration to accommodate 3-D CT footprint specifications.
- Talent Scarcity:Qualified service technicians for high-voltage tube maintenance remain concentrated in Gulf hubs, inflating aftermarket response times for remote deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Baggage and Parcel Screening Market |
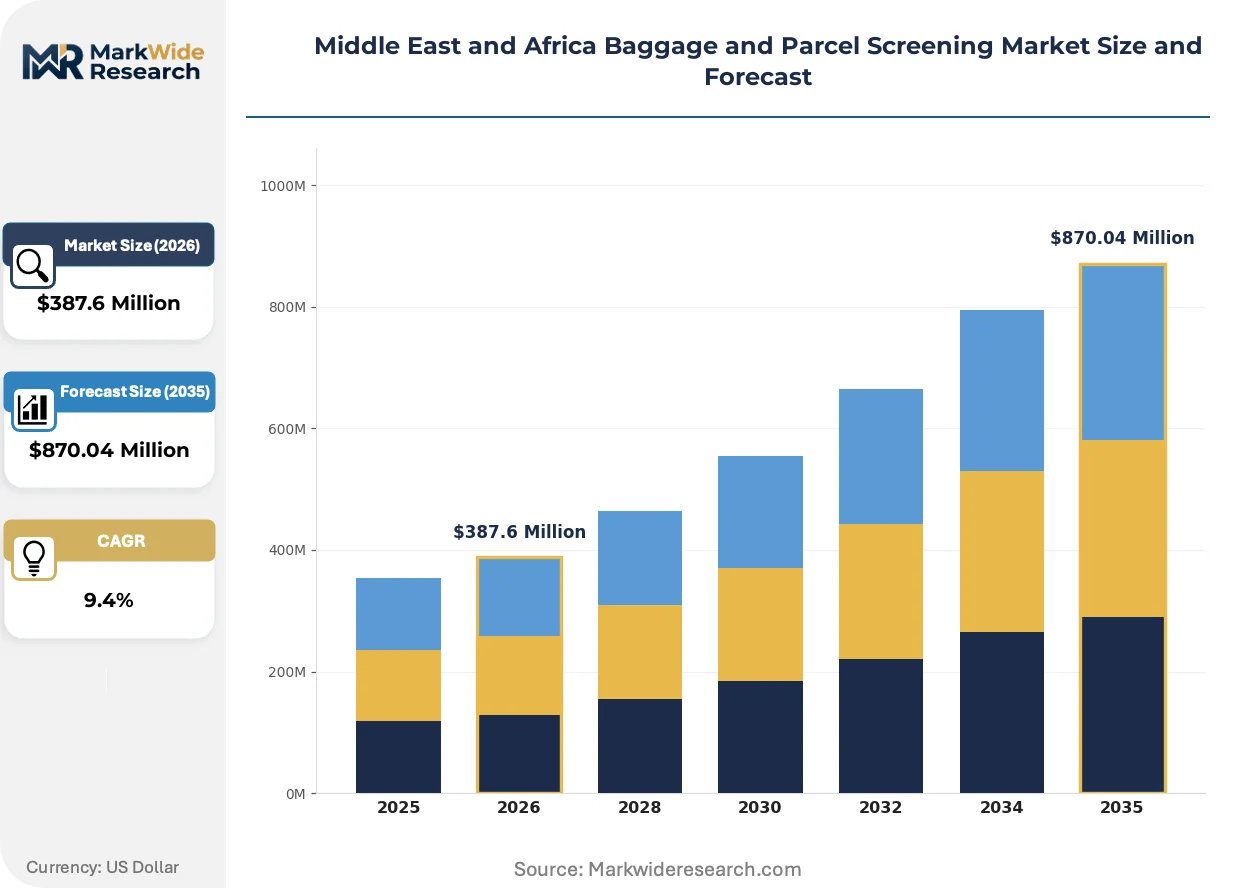
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $870.04 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: X-Ray, Computed Tomography, Explosive Detection, Metal Detection Application: Airports, Train Stations, Government Buildings, Events End User: Transportation Services, Security Agencies, Logistics Providers, Event Organizers Sales Channel: Direct Sales, Distributors, Online Sales, Service Agreements |
| Companies Covered | Smiths Detection Group Ltd, LINEV Systems, Rapiscan Systems, X-Ray Center (XRC), Westminster Group PLC, Nuctech Company Limited, Leidos, Astrophysics Inc, Teledyne ICM SA, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Baggage and Parcel Screening Market Trends and Innovations
Computed tomography reconstruction algorithms are compressing the functional gap between human operator judgment and machine-automated threat detection, redrawing competitive boundaries among screening system vendors.
Deep-learning threat recognition software is rendering obsolete the two-operator verification protocols that dominated checkpoint screening for three decades. Saudi Arabia's General Authority of Civil Aviation is mandating single-operator CT lanes at Riyadh's new terminal complexes, cutting staffing costs while tightening detection thresholds. The structural consequence is collapsing demand for conventional dual-view x-ray systems that cannot integrate neural network libraries.
South Africa's Civil Aviation Authority has adopted hold-baggage screening standards mirroring EU Regulation 2015/1998 annex provisions, forcing equipment recertification for suppliers serving Johannesburg and Cape Town airports. This regulatory convergence is compressing vendor product development cycles toward unified global platform architectures. African operators lacking dedicated compliance teams are consolidating procurement through Gulf-based system integrators who carry pre-certified inventory.
After-sales service contracts are unbundling from initial hardware sales as price-sensitive African port authorities and event venue operators demand modular maintenance arrangements. Smiths Detection and Rapiscan are responding with tiered service tiers spanning remote diagnostics, field engineer dispatch, and full operational outsourcing. Nigeria's port modernization programs exemplify this shift, with Lagos terminals now procuring screening hardware and service subscriptions through separate tender processes.
Middle East and Africa Baggage and Parcel Screening Market Segmentation
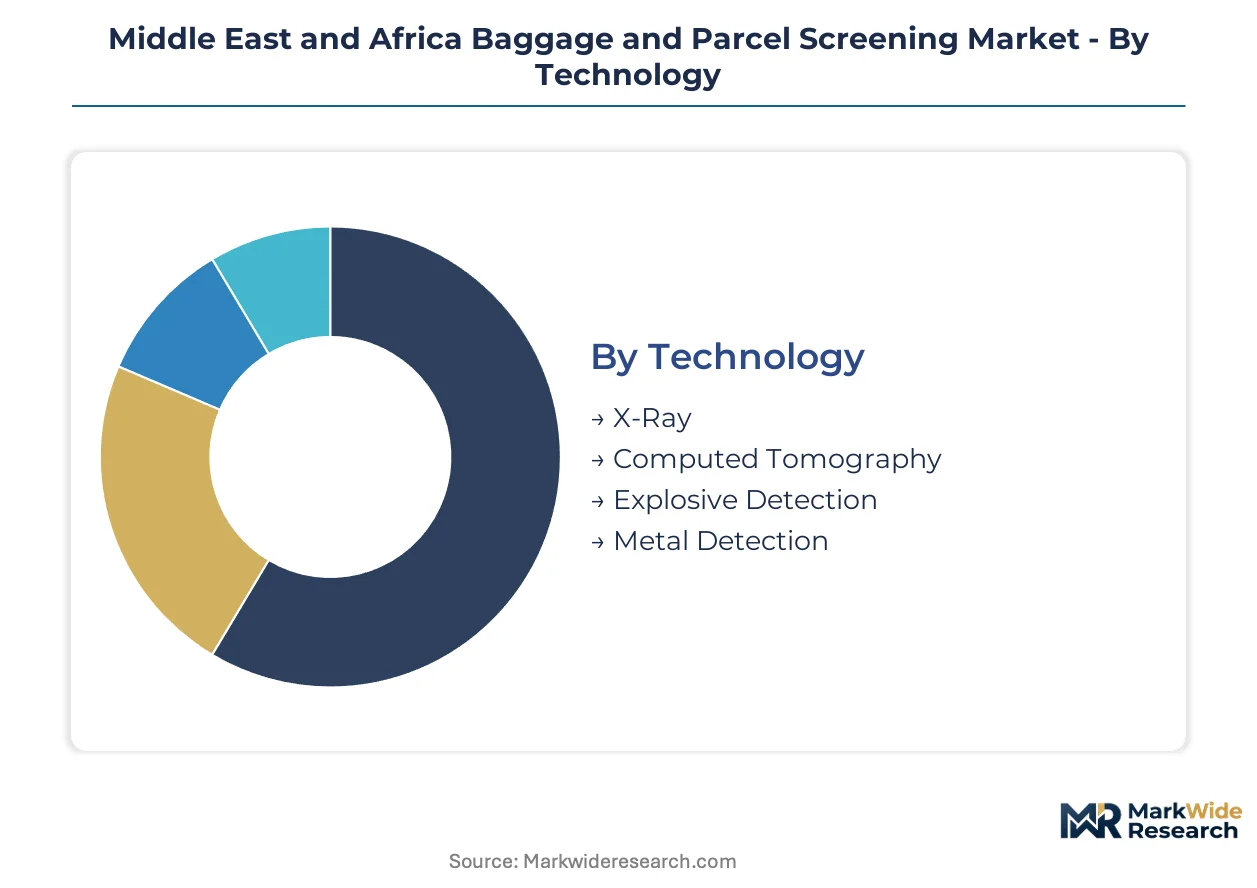
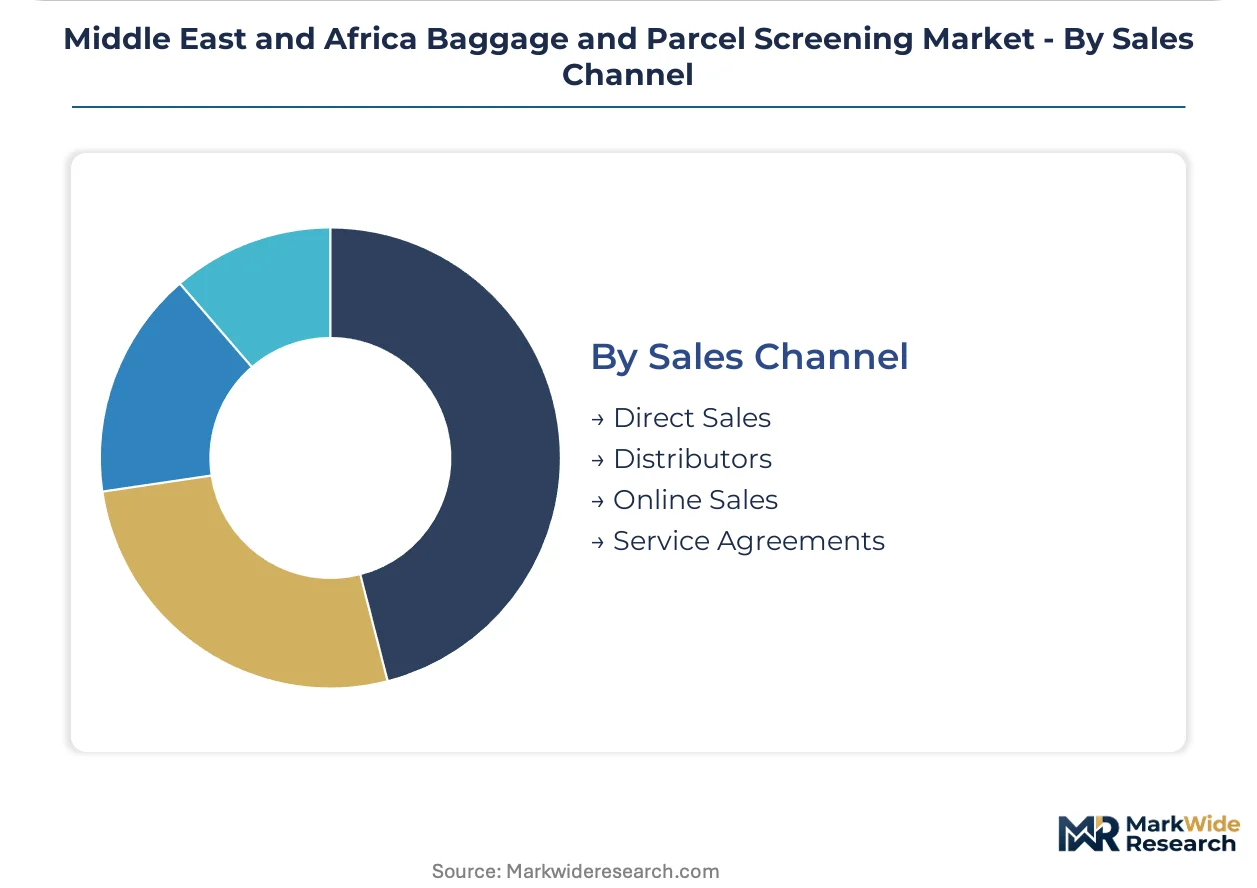
Technology choices in Middle East and Africa baggage and parcel screening determine detection thresholds, throughput capacity, and regulatory compliance trajectories across aviation and critical infrastructure deployments. Application contexts shape system specifications from 140-180 kV tube voltages at airport hubs to portable configurations for event security. End-user procurement patterns and sales channel preferences further segment vendor engagement strategies across price-sensitive African markets and specification-driven Gulf aviation authorities.
Technology:
Technology selection maps directly to detection sophistication tiers, with capital intensity escalating from electromagnetic induction through multi-sensor fusion platforms.
- Computed Tomography:Three-dimensional reconstruction algorithms process volumetric x-ray data to automate threat recognition without human interpretation. Dubai International Airport's terminal expansion and Riyadh's new hub complexes are mandating CT lanes for hold-baggage screening, displacing legacy dual-view systems.
- X-Ray:Dual-energy absorption systems operate at variable kV settings to discriminate organic from inorganic materials via atomic number differential. Secondary African airports and Nigerian port facilities continue procuring 2-D x-ray platforms where budget constraints outweigh automated detection requirements.
- Explosive Detection:Trace particle analyzers and neutron-based systems identify vapor or particulate explosive residue at sensitivity thresholds below nanogram concentrations. Helium-3 supply constraints under US Department of Energy export controls are limiting deployment scalability for neutron detection variants.
- Metal Detection:Electromagnetic induction coils detect ferrous and non-ferrous weapons through doorway or handheld configurations. Event venue operators in Qatar and the UAE deploy portable metal detection as perimeter screening for VIP protection.
X-Ray holds installed capacity. Computed Tomography is rotating up the share rankings.
Application:
Application contexts segment procurement specifications from high-throughput aviation conveyor systems to discrete parcel inspection at government checkpoints.
- Airports:Integrated hold-baggage and checkpoint screening infrastructure processes thousands of items hourly through certified detection lanes. Saudi Arabia's General Authority of Civil Aviation and the UAE's federal transport standards mandate explosive detection capabilities at Riyadh, Jeddah, Dubai, and Abu Dhabi terminals.
- Events:Temporary screening deployments protect stadium and conference venues through modular conveyor and walk-through configurations. Qatar's stadium infrastructure and UAE conference centers are procuring parcel screening for VIP protection, diversifying demand beyond permanent aviation installations.
- Train Stations:Urban rail transit checkpoints require compact footprint systems balancing passenger flow velocity with threat detection sensitivity. Cairo's metro network and Johannesburg's Gautrain stations represent emerging procurement volumes as rail security standards tighten.
- Government Buildings:Fixed-site parcel and personnel screening protects critical administrative facilities against weapon and explosive intrusion. Nigeria's federal complexes and South African parliamentary facilities drive demand for lobby-integrated screening architectures.
Airports dominates procurement volume. Events is expanding most quickly as non-aviation security applications proliferate.
End User:
End-user categories distinguish between regulatory-mandated aviation security budgets and discretionary procurement by logistics and event management operators.
- Security Agencies:National aviation authorities and federal law enforcement control the largest procurement budgets through mandatory screening infrastructure programs. Saudi Arabia's General Authority of Civil Aviation, South Africa's Civil Aviation Authority, and the UAE's General Civil Aviation Authority enforce certification standards that shape vendor product development priorities.
- Transportation Services:Airport authorities and port operators procure screening systems as operational infrastructure integrated with baggage handling and customs processing. Dubai Airports and Lagos Port Complex exemplify integrated procurement combining hardware with multi-year service agreements.
- Logistics Providers:Express courier and freight forwarder networks deploy parcel screening for customs compliance and supply chain security. Nigerian customs infrastructure investments at Lagos and Port Harcourt are expanding maritime screening demand beyond aviation applications.
- Event Organizers:Stadium operators and conference venue managers procure temporary or permanent screening for attendee protection. Qatar's stadium infrastructure for international sporting events drives concentrated procurement cycles with discrete deployment timelines.
Security Agencies holds installed capacity. Logistics Providers is rotating up the share rankings.
Sales Channel:
Sales channel configuration reflects capital equipment procurement patterns versus recurring service revenue structures across price-differentiated market tiers.
- Direct Sales:Manufacturer-led contracting for large-scale aviation infrastructure projects with customized system integration requirements. Gulf hub airports and Saudi GACA-mandated procurements favor direct vendor relationships for complex CT platform deployments.
- Service Agreements:Unbundled aftermarket contracts covering maintenance, remote diagnostics, and operational outsourcing. Nigerian port authorities and African event venue operators are demanding modular service subscriptions separate from hardware acquisition.
- Distributors:Regional system integrators carrying pre-certified inventory for mid-tier African terminals lacking dedicated compliance teams. Gulf-based integrators are consolidating procurement channels for Cairo, Casablanca, and Johannesburg secondary airports.
- Online Sales:Standardized portable screening equipment procured through digital channels for small-scale security applications. Remote African checkpoints and private event operators utilize online channels for handheld metal detection and compact x-ray systems.
Direct Sales holds installed capacity. Service Agreements is climbing the fastest as aftermarket revenue unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor certification requirements cluster around Gulf aviation authorities, fragmenting compliance costs across secondary African terminals lacking dedicated regulatory teams. Smiths Detection sustains service revenue through Heathrow-style hub installations at Riyadh and Jeddah. Nuctech anchors African market position via direct government relationships where price sensitivity dominates tender evaluations.
Saudi Arabia
Riyadh's new terminal complexes and Jeddah hub expansions are mandating single-operator CT lanes under General Authority of Civil Aviation protocols. The GACA hold-baggage screening mandates create sustained procurement pipelines for certified platforms. King Abdulaziz International Airport exemplifies where demand concentrates for automated threat recognition systems.
United Arab Emirates
Dubai International Airport's terminal expansion and Abu Dhabi terminals are accelerating replacement of legacy single-view systems under federal transport standards. The UAE's General Civil Aviation Authority enforces explosive detection sensitivity thresholds that shape vendor product development priorities. Dubai Airports exemplifies integrated procurement combining hardware with multi-year service agreements.
South Africa
Johannesburg and Cape Town airports are forcing equipment recertification under Civil Aviation Authority standards mirroring EU Regulation 2015/1998 annex provisions. The regulatory convergence compresses vendor product development cycles toward unified global platform architectures. OR Tambo International Airport represents the primary procurement volume for hold-baggage screening upgrades.
Nigeria
Lagos and Port Harcourt customs infrastructure investments are expanding parcel screening demand beyond aviation into maritime security applications. Nigerian port authorities are demanding modular maintenance arrangements separate from hardware acquisition. Lagos terminals now procure screening hardware and service subscriptions through separate tender processes.
Egypt
Cairo International Airport represents untapped volume as regulatory stringency converges with Gulf standards. The country's national aviation regulator is adopting hold-baggage screening protocols comparable to Saudi GACA mandates. Cairo's metro network adds emerging procurement volumes as rail security standards tighten.
Middle East and Africa Baggage and Parcel Screening Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying high-voltage tubes and detector arrays. The vendor base consolidates around three to four full-stack suppliers with certified CT platforms, while regional distributors fragment the mid-tier African market. Two strategic archetypes dominate: Gulf-based integrators carrying pre-certified inventory, and direct-government contractors anchoring price-sensitive tenders. Competitive moves center on unbundled service contract offerings and AI threat library integration partnerships.
Within the platform integrator tier, Smiths Detection Group Ltd and Rapiscan Systems exemplify archetypes competing on CT reconstruction algorithm sophistication. Nuctech Company Limited occupies a position among direct-government contractors leveraging Chinese state-linked financing for African tender participation. Westminster Group PLC represents the regional specialist archetype, anchoring service responsiveness for remote deployments where qualified technicians remain scarce.
| Leading Market Players |
|---|
| Smiths Detection Group Ltd |
| LINEV Systems |
| Rapiscan Systems |
| X-Ray Center (XRC) |
| Westminster Group PLC |
| Nuctech Company Limited |
| Leidos |
| Astrophysics Inc |
| Teledyne ICM SA |
| Others |
Pricing and Supply Chain Analysis
Helium-3 export controls under US Department of Energy regulations determine both the pricing tier spreads for neutron-based explosive detection systems and the supply chain shape for trace analyzer manufacturing across Middle East and African procurement channels. The regulatory chokepoint forces buyers toward alternative technologies or premium-priced secured supply contracts, compressing margins at the standard tier while elevating certified CT platforms.
Pricing Analysis
Saudi GACA hold-baggage screening mandates dictate the pricing tier structure across Middle East and African aviation procurement. Three-tier pricing structure across certified CT, dual-energy x-ray, and portable metal detection levels separates premium automated threat recognition platforms from standard conveyor systems and economy handheld units. Cost compression in the x-ray tier is intensifying because Nigerian port authorities and African event operators unbundle service contracts from hardware acquisition. Security Agencies controlling GACA-mandated procurements show least price sensitivity, while Logistics Providers at Lagos and Port Harcourt terminals drive hardest bargain negotiations.
Supply Chain Analysis
Tariff exposure between China and Gulf Cooperation Council member states dominates component sourcing strategies for high-voltage x-ray tubes and detector arrays. Manufacturing concentrates in China, Germany, and the United States for CT reconstruction hardware and AI threat recognition software modules. Raw material dependencies include tungsten filament supplies, scintillator crystals, and helium-3 isotope reserves. Single-source vulnerability persists for 140-180 kV tube voltage components where qualified suppliers number fewer than five globally. Distribution runs through Dubai-based system integrators carrying pre-certified inventory for mid-tier African terminals lacking dedicated compliance teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service agreement unbundling now expands faster than hardware sales across Nigerian port authorities and African event venue operators, transforming capital equipment markets into recurring revenue platforms. This structural shift rewards vendors who retrofit installed bases with remote diagnostics and tiered maintenance subscriptions.
For Market Incumbents: Pre-empt CT platform commoditization by embedding proprietary AI threat libraries that lock in software renewal cycles at Riyadh and Dubai hub installations. Defend against Nuctech's state-linked financing in African tenders through Gulf-based integrator partnerships that carry pre-certified inventory. Deepen backward integration into high-voltage tube refurbishment capabilities to compress aftermarket response times for remote deployments. For New Entrants and Emerging Players: Pursue Cairo International Airport and Casablanca Mohammed V Airport as regulatory stringency converges with Gulf standards before certification timelines extend further. Target Egypt's metro network rail security upgrades as the most penetrable application segment outside saturated aviation hubs. Lead with portable screening units for Qatar stadium infrastructure and UAE conference venue VIP protection where procurement cycles remain discrete and less encumbered by 18-24 month aviation authority qualification periods. For Investors and Strategic Acquirers: Regional service specialists with qualified technician networks across secondary African airports represent the priority acquisition archetype as talent scarcity inflates response times for remote deployments. Long-term viability hinges on whether AI-augmented CT retrofits can sustain pricing power against Chinese state-subsidized platform entrants across the analysis window. Monitor Saudi GACA adoption of single-operator lane mandates as the inflection signal for automated threat recognition penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| AI Threat Library Integration | Automated recognition algorithms at Riyadh terminals displace dual-view x-ray verification protocols. |
| Service Contract Unbundling | Lagos port authorities now procure hardware and maintenance through separate tender processes. |
| Regional Integrator Partnership | Dubai-based distributors consolidate procurement channels for Cairo and Casablanca secondary airports. |
| Helium-3 Alternative Sourcing | Trace detector manufacturers pivot toward neutron generator technologies under US export controls. |
| Portable Unit Certification | Battery-powered screening systems lack voltage capacity for dense cargo penetration at remote checkpoints. |
Research Methodology
The analysis maps CT platform deployments, x-ray system retrofits, and portable screening applications, each validated through airport procurement directors, national aviation authority certification officers, port customs infrastructure managers, and aftermarket service technicians. Primary interviews with these stakeholders combined with secondary validation against GACA protocol documentation, South African Civil Aviation Authority filings, Nigerian customs modernization tenders, and EU Regulation 2015/1998 annex provisions. Bottom-up equipment shipment tracking and top-down aviation security budget appropriations triangulate market sizing across technology tiers.
Forecasts assume sustained GACA mandate enforcement, stable helium-3 export control regimes, and linear CT adoption curves at Gulf hub terminals while varying African regulatory convergence timelines and port modernization funding availability. Segmentation dimensions modeled include technology sophistication tier, application context from aviation through maritime and events, end-user budget authority, and sales channel configuration across direct, distributor, and service agreement structures. CAGRs derive from equipment replacement cycle compression and unbundled service revenue expansion rates calibrated against historical aviation security procurement patterns.
Sensitivities concentrate around Egyptian and Moroccan regulatory adoption timelines, US Department of Energy helium-3 license renewal decisions, and Chinese state-linked financing penetration in African tenders. Forecasts reflect these assumptions without certainty of realization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Wireless Doorbells Market
Security and Surveillance
Ballistic Protection Scanners Market
Security and Surveillance
Global Alarm Monitoring Market
Security and Surveillance
Global Wireless Monitoring and Surveillance Market
Security and Surveillance
Middle East Manned Security Services Market
Security and Surveillance
Global Traveler Security Services Market
Security and Surveillance
Riot Control System Market
Security and Surveillance
Airport Security Market
Security and Surveillance
Manned Guarding Services Market
Security and Surveillance
Situational Awareness System Market
Security and Surveillance
Global Cargo Inspection Market
Security and Surveillance
Explosive Detection Technology Market
Security and Surveillance
Night Vision Scopes Market
Security and Surveillance
Forensic Technologies Market
Security and Surveillance
Anti-Piracy Protection Market
Security and Surveillance
Global Security Policy Management Market