
 Ballistic Protection Scanners Market | 2026-2036
Ballistic Protection Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
Ballistic Protection Scanners Market Outlook
Millimeter-wave and deep learning fusion is reconfiguring how ballistic protection scanners detect concealed threats in real time. BAE Systems plc leverages integrated radar-to-image processing pipelines for military checkpoint applications. Rheinmetall AG anchors European defense procurement through permanent-installation scanner networks. Honeywell International Inc. competes across commercial facilities with modular mobile setups that reduce deployment timelines.
Ballistic protection scanners are electronic threat-detection systems that combine electromagnetic sensing, acoustic profiling, or computer vision to identify weapons, explosives, or anomalous materials concealed on personnel or vehicles, typically operating at frequencies between 24 GHz and 300 GHz with detection resolutions under 5 millimeters. These systems serve military perimeters, law enforcement checkpoints, airport security lanes, and commercial facility access points where human screening must balance throughput against threat sensitivity. Handheld scanners and fixed scanners together occupy the largest installed base, though portable scanners and under-vehicle scanners represent the fastest-expanding categories as forces prioritize rapid redeployment and layered perimeter defense. Deep learning and radar technology command the highest R&D allocation, while acoustic sensors remain a niche segment for specialized underwater or electromagnetic-denied environments.
The U.S. Department of Homeland Security and TSA enforce screening performance standards that shape product development cycles for airport security suppliers. EU CE marking under the MDR framework and the EU AI Act's risk-classification rules constrain how deep learning algorithms deploy in law enforcement contexts. India's BIS certification and PLI scheme for domestic security manufacturing create localized supply obligations for foreign entrants. Stakeholders must monitor how divergent AI governance models between the United States and Europe fragment software certification pathways.
Market Dynamics
Millimeter-wave radar fusion with deep learning inference is compressing detection latency from seconds to milliseconds, forcing incumbent suppliers to rebuild signal-processing architectures around GPU-accelerated edge computing rather than legacy CPU-based pipelines.
Growth Catalysts
- EU AI Act risk-classification framework:Mandatory algorithmic transparency for high-risk security applications is accelerating R&D investment in explainable threat-detection models across European law enforcement agencies.
- India's PLI scheme for domestic security manufacturing:Production-linked incentives are pulling foreign component suppliers toward joint ventures with Indian electronics manufacturers to satisfy BIS certification requirements.
- Acoustic profiling arrays:Underwater and electromagnetic-denied environment scanning is opening new procurement channels for naval perimeter defense and critical subsea infrastructure protection.
Market Restraints
- Gallium nitride semiconductor supply concentration:Foundry capacity for high-frequency radar front-ends concentrates among Taiwanese and Korean suppliers, exposing scanner manufacturers to single-source vulnerability.
- CE marking under MDR framework:Extended conformity assessment timelines for software-as-medical-device classifications are delaying European commercialization of biometric-integrated screening systems.
- Passive millimeter-wave standoff limitations:Atmospheric attenuation above 200 GHz degrades detection reliability beyond 15 meters, constraining deployment architectures for wide-area perimeter coverage.
Strategic Opportunities
- Underpenetrated Indian critical infrastructure:Metro rail networks and nuclear facilities are expanding procurement of layered checkpoint systems as domestic manufacturing capabilities mature under PLI incentives.
- Modular mobile scanner platforms:Rapid-redeployment configurations are displacing fixed-installation networks for temporary event security and expeditionary military operations.
- Convergence of radar and computer vision:Sensor fusion architectures that combine 77 GHz automotive radar modules with thermal imaging are reducing unit costs for commercial facility access control.
Industry Challenges
- RF engineer talent scarcity:Design expertise in phased-array antenna calibration and beamforming algorithms concentrates among defense contractors, constraining commercial supplier scaling.
- Dual-use export control compliance:ITAR and EAR classification reviews for millimeter-wave components above 90 GHz extend procurement lead times for international customers by 6-12 months.
- Legacy checkpoint integration complexity:Retrofitting existing X-ray baggage systems with AI-augmented threat overlays requires proprietary middleware development for each airport operator.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ballistic Protection Scanners Market |
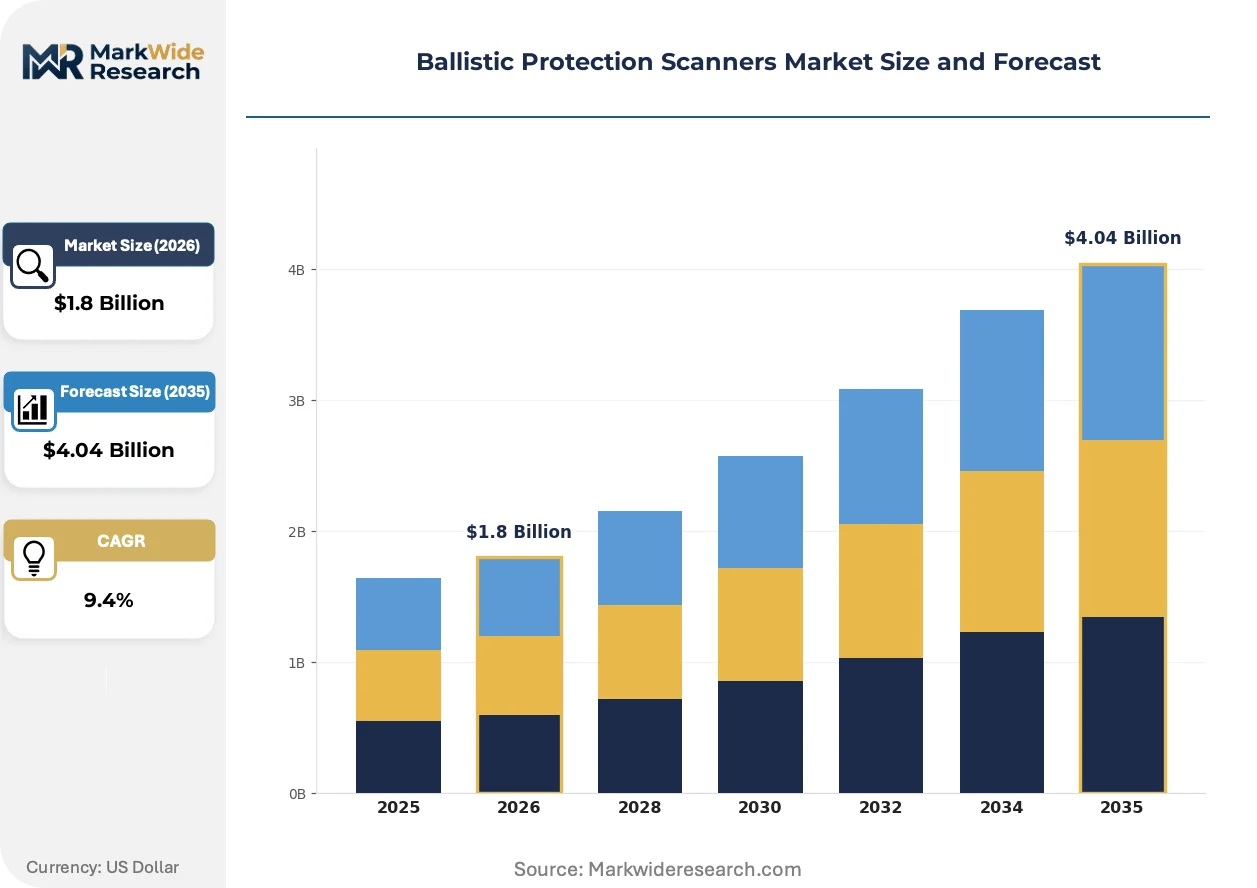
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Scanners, Fixed Scanners, Portable Scanners, Under vehicle Scanners Technology: Image Processing, Deep Learning, Radar Technology, Acoustic Sensors End User: Military, Law Enforcement, Airport Security, Commercial Facilities Installation: Permanent Installation, Temporary Installation, Mobile Setup, Fixed Positioning |
| Companies Covered | BAE Systems plc, Rheinmetall AG, Honeywell International Inc., Avon Protection plc, Point Blank Enterprises, DuPont, Saab AB, 3M Ceradyne, TenCate Advanced Armor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ballistic Protection Scanners Market Strategic Shifts
Deep learning inference at the network edge is collapsing the traditional separation between raw sensor acquisition and centralized threat analysis, enabling real-time adaptive scanning that adjusts sensitivity based on crowd density and environmental conditions.
Passive millimeter-wave imaging arrays operating at 94 GHz are collapsing the cost-performance tradeoff that previously forced airports to choose between high-resolution body scanners and lower-cost metal detectors. TSA procurement specifications now prioritize systems capable of detecting non-metallic anomalies under clothing without requiring passenger pose adjustments. Deployment timelines for checkpoint retrofits are compressing from 18-month capital cycles to 90-day modular installations.
The EU AI Act's high-risk system classification is mandating algorithmic audit trails and human-in-the-loop decision protocols for law enforcement screening deployments. European border agencies are restructuring procurement contracts to require continuous model retraining documentation and bias testing against standardized threat libraries. Scanner suppliers are responding by partitioning software architectures between EU-compliant constrained inference engines and unrestricted military variants.
Defense and critical infrastructure buyers are unbundling hardware acquisition from algorithm licensing, treating threat-detection models as separately renewable subscription assets. Airport authorities in Germany and India are piloting usage-based pricing for screening lanes where algorithm updates and false-positive optimization carry recurring fees rather than upfront perpetual licenses. This shift is most visible in high-throughput terminals where detection sensitivity must adapt to evolving threat signatures without full system replacement.
Ballistic Protection Scanners Market Segmentation
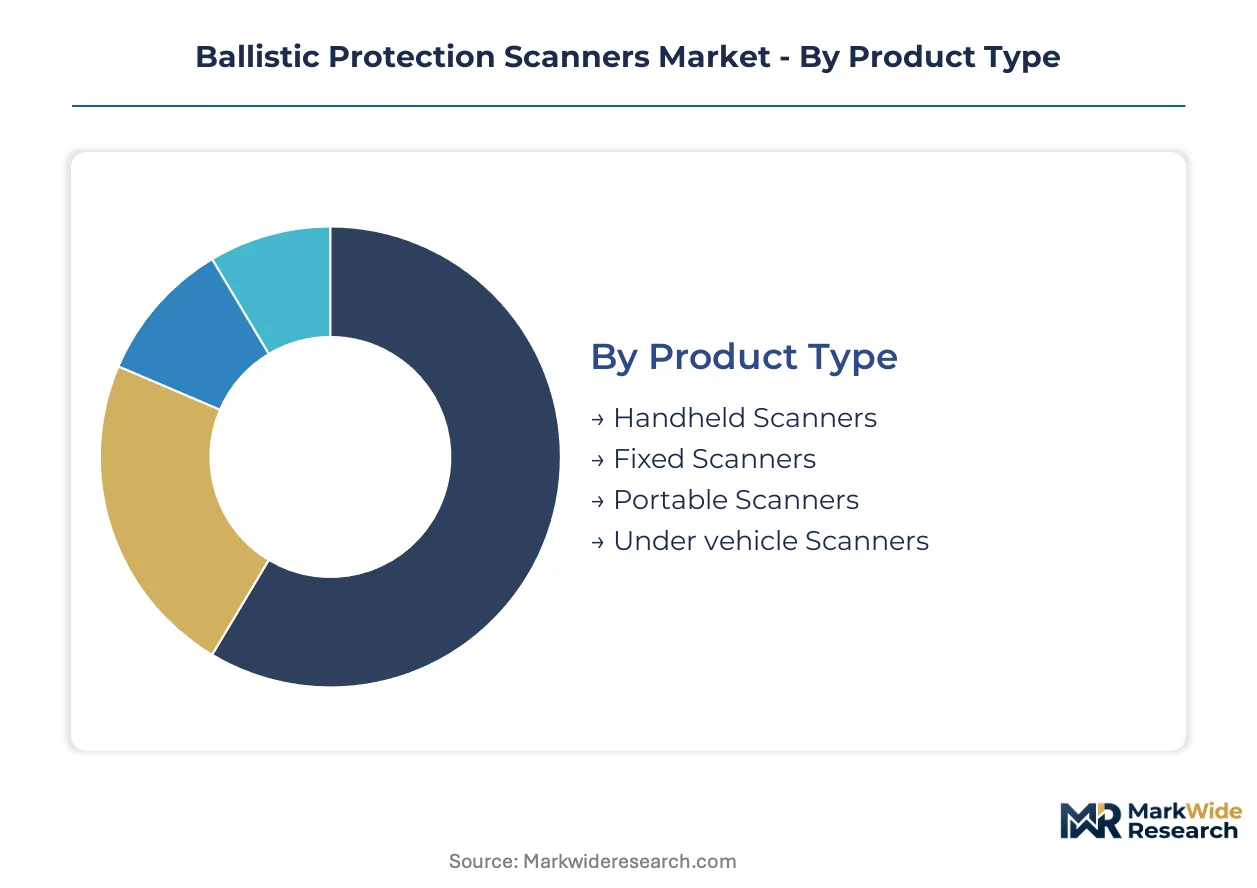
Segmentation in ballistic protection scanners reveals how procurement priorities diverge across threat environments, technology readiness levels, and deployment flexibility requirements. Each dimension shapes supplier R&D allocation, certification pathways, and margin structures differently.
Product Type:
Cost tier differentiation separates mass-deployable screening tools from capital-intensive infrastructure investments.
- Handheld Scanners:Compact millimeter-wave units weighing under 2 kilograms enable close-range personnel screening at checkpoints with limited power infrastructure. German federal police and TSA field units are standardizing procurement around 94 GHz variants that resolve anomalies under clothing without physical pat-downs.
- Fixed Scanners:Permanent-installation gantry systems integrate multiple sensor modalities—millimeter-wave arrays, backscatter X-ray, and thermal profiling—into coordinated screening lanes. Rheinmetall AG anchors European defense procurement through hardened checkpoint networks at military perimeters.
- Portable Scanners:Rapid-deployment configurations collapse into transit cases for expeditionary military operations and temporary event security.
- Under vehicle Scanners:Acoustic and radar fusion systems detect anomalies beneath vehicle chassis at speeds up to 30 kilometers per hour.
Fixed scanners command the established base. The steepest expansion runs through portable scanners.
Technology:
Application maturity determines which sensing modalities absorb R&D investment versus maintenance-phase optimization.
- Deep Learning:GPU-accelerated edge inference enables real-time threat classification without cloud dependency, compressing detection latency from seconds to milliseconds. EU AI Act compliance requirements are forcing architecture partitioning between explainable European variants and unrestricted military deployments.
- Radar Technology:Millimeter-wave phased arrays operating at 77-94 GHz penetrate clothing and light barriers with sub-5-millimeter resolution. Gallium nitride semiconductor supply concentration among Taiwanese and Korean foundries exposes manufacturers to single-source vulnerability.
- Image Processing:Conventional computer vision pipelines remain cost-competitive for commercial facility access control where threat libraries are narrower.
- Acoustic Sensors:Sonar profiling arrays serve electromagnetic-denied environments including underwater naval perimeters and subsea infrastructure protection.
Radar technology commands the established base. The steepest expansion runs through deep learning.
End User:
Customer type dictates threat library complexity, throughput requirements, and regulatory oversight intensity.
- Military:Hardened systems must operate across electromagnetic-contested environments with degraded GPS and communication links. Procurement prioritizes modular sensor fusion and rapid field reconfiguration over civilian-optimized throughput metrics.
- Airport Security:TSA performance standards mandate detection of both metallic and non-metallic anomalies under clothing without passenger pose adjustments. Deployment timelines compress from 18-month capital cycles to 90-day modular installations.
- Law Enforcement:Mobile checkpoint applications balance detection sensitivity against civil liberties constraints, particularly under EU AI Act algorithmic audit requirements.
- Commercial Facilities:Corporate campuses and critical infrastructure sites prioritize cost-optimized screening that integrates with existing access control systems.
Military applications command the established base. The steepest expansion runs through airport security.
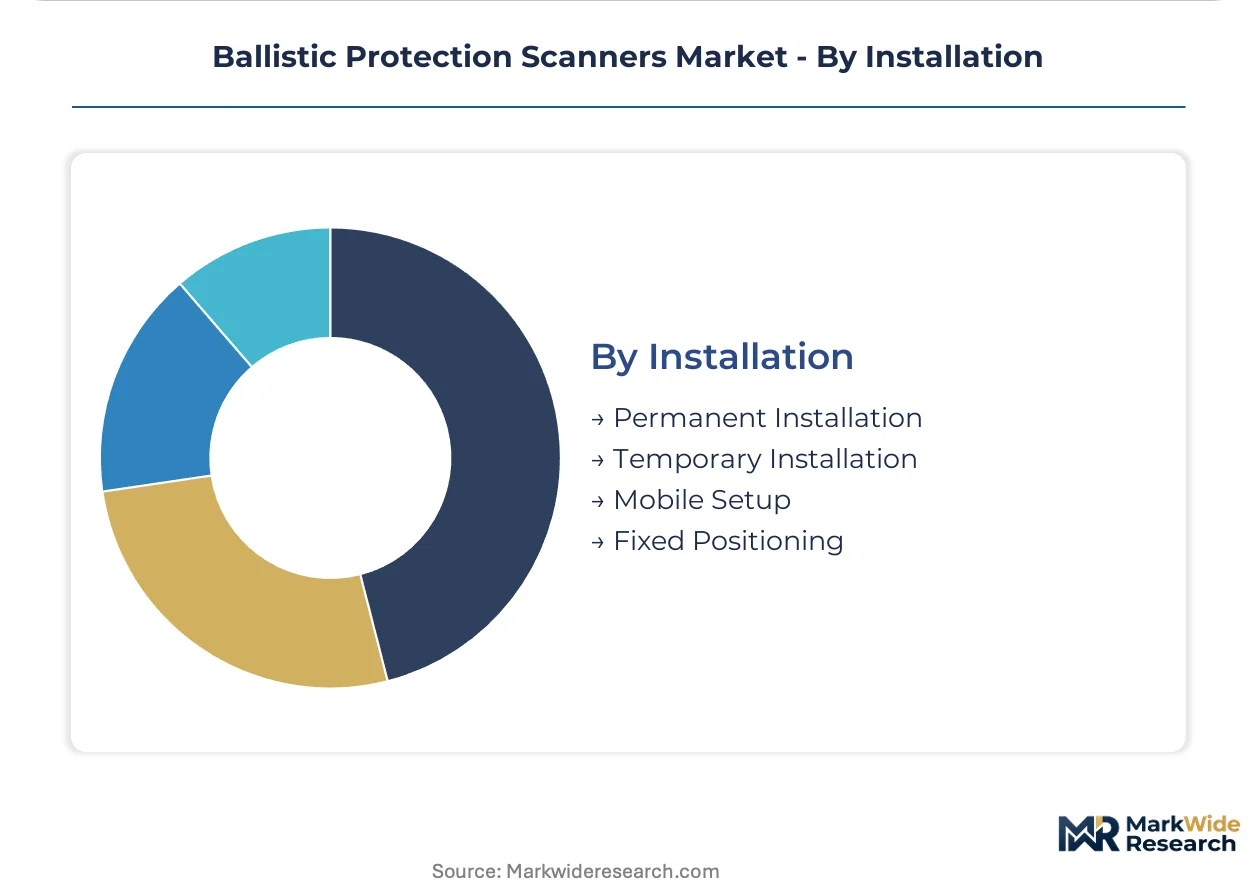
Installation:
Volume scalability depends on whether deployment architecture prioritizes throughput permanence or operational flexibility.
- Permanent Installation:Hardened gantry networks with buried sensor conduits and dedicated power infrastructure serve high-threat military perimeters and major international airports. Capital recovery cycles extend 10-15 years with algorithm licensing treated as separately renewable subscription assets.
- Mobile Setup:Rapid-redeployment platforms on trailer or vehicle mounts displace fixed networks for temporary event security and expeditionary operations. Honeywell International Inc. competes across commercial facilities with modular configurations that reduce deployment timelines.
- Temporary Installation:Semi-permanent deployments serve construction phases or seasonal demand surges without full capital commitment.
- Fixed Positioning:Anchored but non-hardened systems balance durability against relocation feasibility for evolving threat landscapes.
Permanent installation commands the established base. The steepest expansion runs through mobile setup.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense ministries and critical infrastructure operators concentrate procurement authority across distinct national regulatory environments, with airport authorities and border agencies driving specification standards that cascade through supplier development cycles.
United States
TSA procurement specifications prioritize millimeter-wave systems capable of detecting non-metallic anomalies without passenger pose adjustments. The Department of Homeland Security enforces screening performance standards that compress deployment timelines from 18-month capital cycles to 90-day modular installations. Dallas-Fort Worth and Atlanta airport authorities anchor demand for checkpoint retrofit programs.
Germany
Federal police standardization around 94 GHz handheld variants for close-range personnel screening drives component supplier alignment. CE marking under the MDR framework and EU AI Act risk-classification rules constrain algorithm deployment in law enforcement contexts. Rheinmetall AG anchors European defense procurement through hardened checkpoint networks at military perimeters in Bavaria and Lower Saxony.
India
Metro rail networks and nuclear facilities expand procurement of layered checkpoint systems as domestic manufacturing capabilities mature. BIS certification and PLI scheme incentives pull foreign component suppliers toward joint ventures with Indian electronics manufacturers. Mumbai and Delhi-NCR concentrate deployment of under-vehicle and handheld screening systems for critical infrastructure protection.
United Kingdom
Border Force restructuring of procurement contracts mandates continuous model retraining documentation and bias testing against standardized threat libraries. Algorithmic audit trails and human-in-the-loop decision protocols reshape software architecture requirements. London Heathrow and Manchester airport authorities pilot usage-based pricing for screening lanes with recurring algorithm licensing fees.
France
ANSM and CNIL oversight of biometric-integrated screening systems extends conformity assessment timelines for commercialization. Naval perimeter defense procurement channels open for acoustic profiling arrays in electromagnetic-denied environments. Marseille and Toulouse industrial clusters concentrate subsystem integration for Mediterranean maritime security applications.
Ballistic Protection Scanners Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement channels where defense contractors, commercial security integrators, and component suppliers occupy distinct margin tiers. Consolidation concentrates among systems integrators serving military perimeters and airport authorities, while modular mobile specialists fragment across temporary event security and expeditionary operations. Three archetypes dominate: hardened fixed-installation specialists, rapid-deployment platform suppliers, and algorithm licensing pure-plays. Competitive moves center on M&A for sensor fusion capabilities and strategic partnerships for gallium nitride semiconductor supply security.
Among defense-anchored systems integrators, BAE Systems plc and Rheinmetall AG represent the hardened infrastructure archetype, while Honeywell International Inc. occupies a position exemplifying modular commercial deployment. These three entities anchor distinct competitive vectors without overlapping procurement channel dominance, permitting parallel specialization rather than direct confrontation across customer segments.
| Leading Market Players |
|---|
| BAE Systems plc |
| Rheinmetall AG |
| Honeywell International Inc. |
| Avon Protection plc |
| Point Blank Enterprises |
| DuPont |
| Saab AB |
| 3M Ceradyne |
| TenCate Advanced Armor |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in gallium nitride foundry capacity across Taiwan and South Korea is amplifying pricing power for radar front-end suppliers while forcing scanner manufacturers toward long-term offtake commitments and alternative semiconductor architectures.
Pricing Analysis
Cost-plus contracts with gallium nitride wafer price indexation dominate procurement between Taiwanese foundries and millimeter-wave module suppliers. Three-tier pricing structure across military-grade hardened systems, commercial airport installations, and portable expeditionary units separates certification tiers. Cost compression in commercial portable segments is intensifying because automotive radar module reuse reduces bill-of-materials overlap. Airport authorities exhibit lowest price sensitivity due to TSA-mandated performance specifications, while commercial facility operators drive hardest bargain negotiations.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for phased-array antenna substrates and FPGA processing units. Manufacturing concentrates in Taiwan, South Korea, and Germany for high-frequency semiconductors, precision optics, and hardened mechanical enclosures. Raw material dependencies span gallium nitride wafers, low-loss PCB laminates, and precision-machined aluminum radar housings. Single-source vulnerability in Taiwanese gallium nitride foundry capacity exposes manufacturers to allocation constraints. Distribution runs through defense prime contractor networks, commercial security integrators, and direct airport authority procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ballistic protection scanners sit in early-cycle expansion as EU AI Act compliance mandates and Indian PLI incentives accelerate procurement beyond traditional defense budgets into critical infrastructure and law enforcement channels.
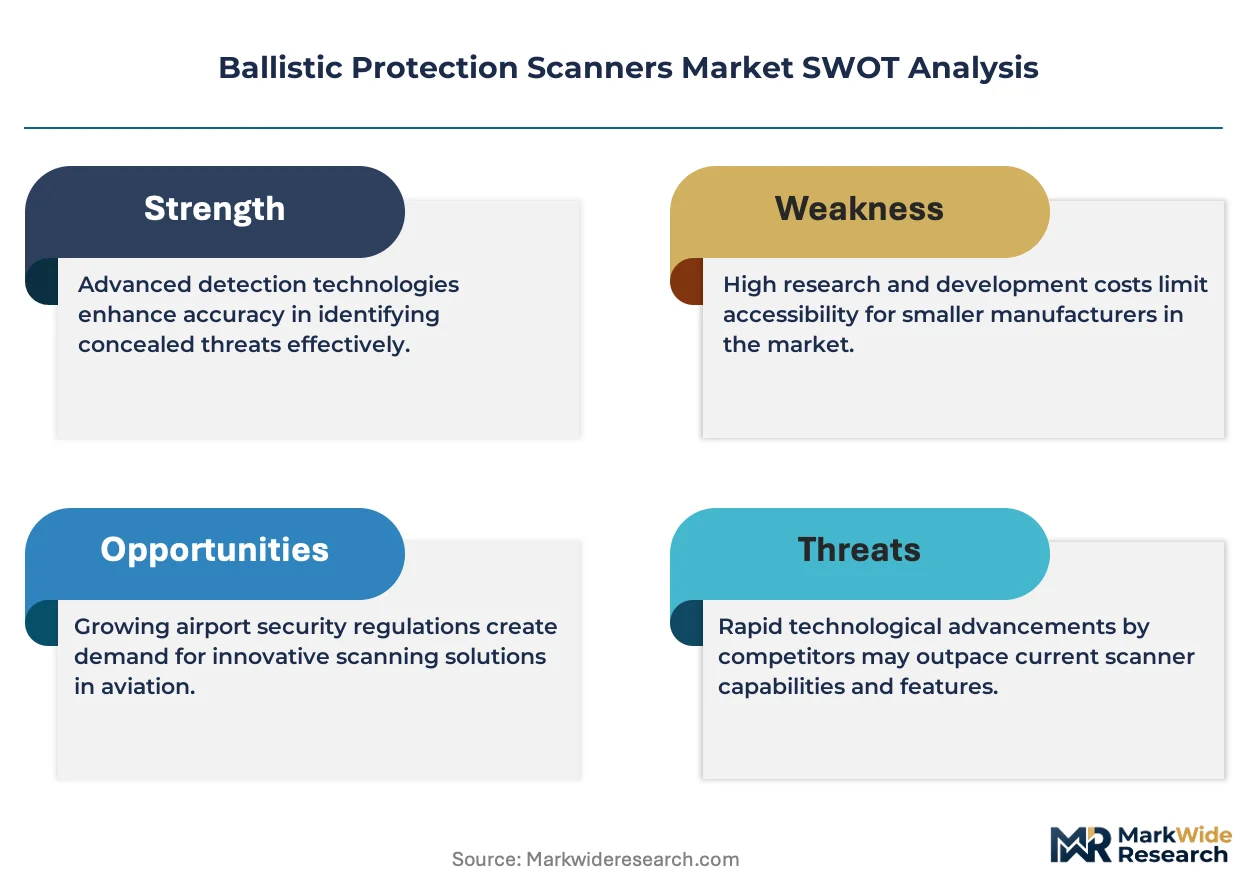
For Market Incumbents: Pre-empt algorithmic audit trail requirements by partitioning software architectures between EU-compliant constrained inference engines and unrestricted military variants before CE marking timelines extend. Secure gallium nitride semiconductor supply through joint venture structures with Taiwanese or Korean foundries to mitigate single-source vulnerability. Deepen backward integration into radar module assembly to capture margin compression from automotive radar reuse in commercial segments. For New Entrants and Emerging Players: Pursue underpenetrated Indian metro rail and nuclear facility procurement where PLI scheme incentives reduce effective competitive barriers for joint venture structures. Target acoustic profiling arrays for naval perimeter defense as electromagnetic-denied environment specialization avoids direct confrontation with established millimeter-wave suppliers. Lead with modular mobile configurations that compress deployment timelines below fixed-installation incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among algorithm licensing pure-plays serving high-throughput airport terminals where usage-based pricing models displace perpetual licenses. Long-term viability hinges on sensor fusion capabilities spanning radar, thermal, and acoustic modalities rather than single-technology specialists. Monitor gallium nitride foundry capacity utilization as inflection indicator for input cost pressure and supplier margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Licensing Subscription Conversion | Airport authorities in Germany and India pilot usage-based pricing with recurring fees for threat-detection model updates. |
| Gallium Nitride Supply Security Partnership | Joint ventures with Taiwanese foundries mitigate single-source vulnerability for 77-94 GHz radar front-end components. |
| EU AI Act Compliance Architecture Partitioning | Software separation between explainable European variants and unrestricted military deployments accelerates CE marking pathways. |
| Modular Mobile Platform Development | Rapid-redeployment configurations displace fixed-installation networks for temporary event security and expeditionary operations. |
| Acoustic Profiling Array Specialization | Naval perimeter defense procurement opens electromagnetic-denied environment channels beyond contested millimeter-wave segments. |
Study Parameters
The analysis maps handheld scanner, fixed gantry, portable expeditionary, and under-vehicle screening sub-sectors, each validated through procurement officers at airport authorities, defense ministry acquisition leads, and commercial security integrators. Primary interviews with TSA specification engineers, EU border agency technology directors, and Indian BIS certification consultants combined with secondary validation against EU AI Act implementation guidance, TSA screening performance standards, and Indian PLI scheme notifications. Bottom-up unit deployment estimates and top-down defense budget allocation triangulation anchored market sizing across the projection horizon.
Assumptions held fixed include current EU AI Act risk-classification enforcement intensity and existing gallium nitride foundry capacity expansion plans; scenarios varied gallium nitride supply disruption severity and Indian domestic manufacturing capability maturation speed. Segmentation dimensions modeled span product type, technology modality, end-user category, and installation architecture alongside regional regulatory cluster differentiation. CAGRs derived from deployment timeline compression observed in TSA procurement cycles and algorithm licensing revenue transition patterns. Industry-specific forecast inputs encompass checkpoint retrofit program announcements and naval perimeter defense procurement pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by automotive radar suppliers entering security applications or Chinese component manufacturers capturing BIS certification would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Physical Security Software Market
Security and Surveillance
Asia-Pacific Security Services Market
Security and Surveillance
Vietnam Private Security Market
Security and Surveillance
India Perimeter Intrusion Detection and Prevention Market
Security and Surveillance
Underwater Security (Systems and Services) Market
Security and Surveillance
Security Holograms Market
Security and Surveillance
Residential Security Market
Security and Surveillance
Asia-Pacific Security Screening Market
Security and Surveillance
Urban Security Screening Market
Security and Surveillance
Face Smart Lockers Market
Security and Surveillance
Integrated Security Services Market
Security and Surveillance
Integrated Security Solutions Market
Security and Surveillance
Global Security Orchestration Market
Security and Surveillance
Global Bot Security Market
Security and Surveillance
Smart Home Security Market
Security and Surveillance
Private Military Security Services Market