
 Italy Video Surveillance Market | 2026-2036
Italy Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Video Surveillance Market Insights
High-resolution 4K specification tiers is rotating through municipal and enterprise procurement cycles across Italy. Dahua Technology leverages its manufacturing scale to supply cost-competitive IP camera arrays for large infrastructure bids. Hangzhou Hikvision Digital Technology Company Limited anchors the professional installer channel with extensive technical training programs. Honeywell Security Group differentiates through integrated building management platforms that bundle surveillance with access control and fire safety systems.
Video surveillance encompasses networked camera systems, video management software, and storage infrastructure designed to capture, transmit, and analyze visual data for security and operational intelligence purposes. IP cameras dominate Italian deployments, offering Power over Ethernet connectivity, H.265 compression, and edge-based analytics processing at resolutions exceeding 8 megapixels. The commercial end-user segment generates the deepest margin pools, as banks, logistics hubs, and hospitality chains require multi-site centralized monitoring with forensic-grade archival retention. Cloud-based installation types represent the fastest-expanding architecture, displacing legacy on-premise NVR configurations in mid-sized retail and residential applications.
Italy's Data Protection Authority enforces GDPR-compliant video retention and facial recognition limitations, while the EU AI Act imposes risk-classification requirements on automated surveillance analytics. CE marking under the EU Radio Equipment Directive governs wireless transmission standards for IP camera deployments. Stakeholders must monitor evolving algorithmic transparency obligations that will determine which AI-powered analytics features remain permissible for public-space deployment.
Market Dynamics
Italy's video surveillance sector faces structural compression from the EU AI Act's risk-classification framework, which is forcing manufacturers to redesign analytics architectures and revalidate algorithms for public-space deployments across Lombardy, Veneto, and Emilia-Romagna industrial corridors.
Growth Catalysts
- National Recovery and Resilience Plan mandates:Critical infrastructure operators must upgrade security protocols, triggering replacement cycles at ports, energy facilities, and transportation hubs throughout the peninsula.
- Smart city procurement waves:Milan, Rome, and Turin are deploying AI-enabled IP camera networks for traffic management, crowd analytics, and environmental monitoring under municipal digital transformation budgets.
- Edge analytics processing:On-camera GPU chips now enable real-time object detection and behavior analysis without cloud dependency, reducing latency for manufacturing perimeter protection systems.
Market Restraints
- GDPR retention limitations:Italy's Data Protection Authority enforces strict video archival periods and facial recognition prohibitions that compress data monetization opportunities and increase compliance overhead.
- Semiconductor supply concentration:Image sensor and SoC fabrication concentrates in East Asian foundries, exposing Italian integrators to lead-time volatility and currency fluctuation risks.
- Legacy analog infrastructure:Thousands of small retail and residential installations still operate coaxial-based CCTV systems, creating friction for IP migration projects due to rewiring costs.
Strategic Opportunities
- Cloud-native VMS architectures:Mid-sized retail chains and multi-site hospitality operators are abandoning on-premise NVR configurations for subscription-based centralized monitoring platforms.
- Integrated building management convergence:Surveillance vendors can bundle video analytics with access control, fire safety, and HVAC systems through BACnet and ONVIF protocol interoperability.
- Southern Italy underpenetration:Campania, Sicily, and Calabria exhibit lower camera density per capita than northern regions, presenting whitespace for regional system integrators and managed service providers.
Industry Challenges
- Cybersecurity certification complexity:CE marking under the EU Radio Equipment Directive and emerging EU Cybersecurity Act requirements demand extended testing timelines for wireless IP camera launches.
- AI ethics governance gaps:Algorithmic transparency obligations remain undefined in Italian implementing decrees, creating uncertainty for product roadmaps and feature development priorities.
- Installer channel capability deficits:Network engineering and cybersecurity skills lag demand across the professional installer base, constraining deployment velocity for complex multi-site projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Video Surveillance Market |
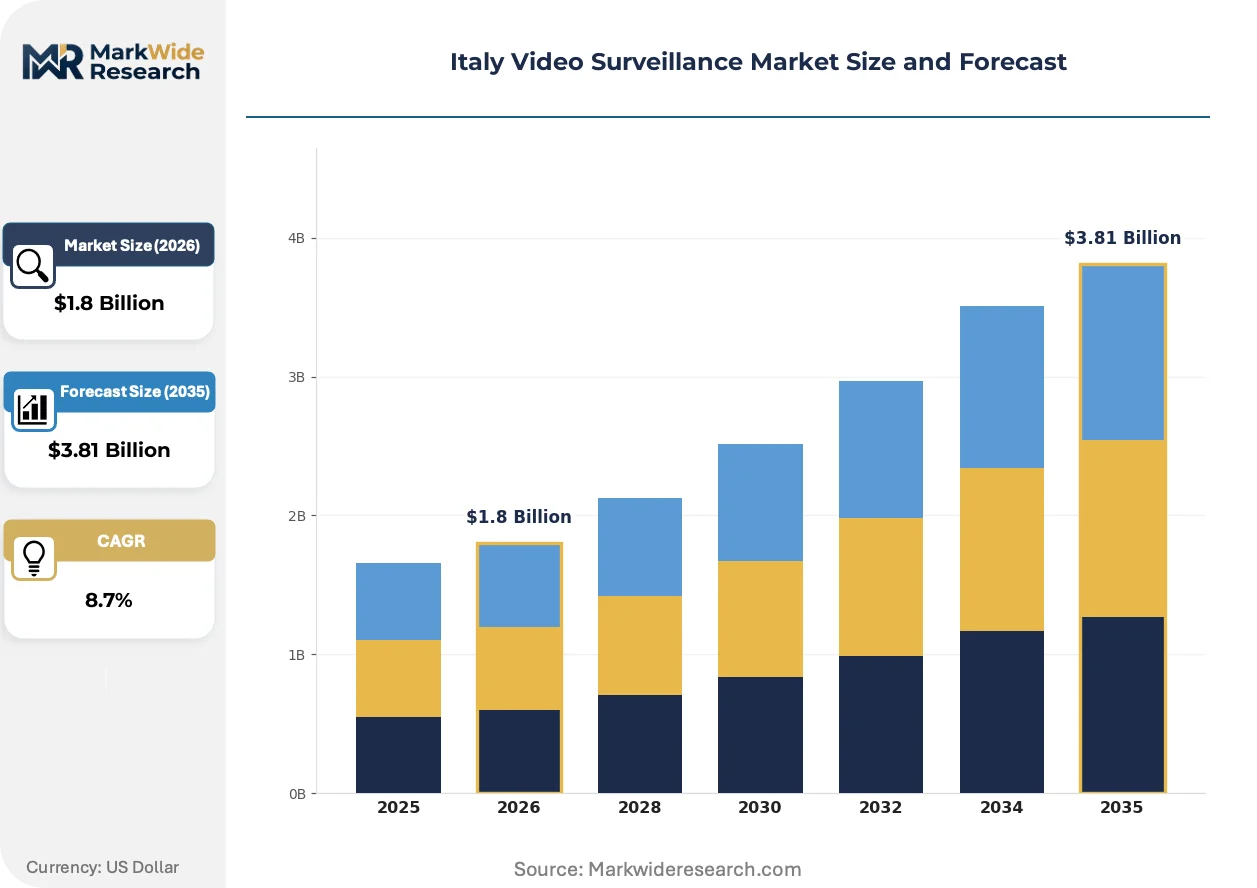
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Analog Cameras, IP Cameras, PTZ Cameras, Thermal Cameras End User: Residential, Commercial, Government, Industrial Installation Type: Wired, Wireless, Cloud-Based, On-Premise Application: Traffic Monitoring, Building Security, Remote Surveillance, Retail Analytics |
| Companies Covered | Teledyne Flir LLC, Videotec SRL, Honeywell Security Group, Dahua Technology, Hangzhou Hikvision Digital Technology Company Limited, Esprinet S.p.A, Bettini S.r.l., Aitek SpA, Johnson Controls, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Video Surveillance Market Trends and Innovations
Three interconnected developments are restructuring Italy's video surveillance value chain: computational migration toward network edge, algorithmic governance frameworks from Brussels, and procurement model evolution among commercial end-users seeking operational expenditure flexibility.
Edge-based GPU acceleration is supplanting centralized server analytics in Italian industrial and municipal deployments. Manufacturing facilities in Turin's automotive corridor and logistics hubs near Milan Malpensa are adopting cameras with onboard inference engines for real-time anomaly detection. This distributed architecture reduces backbone bandwidth requirements and enables sub-100-millisecond response times for perimeter intrusion alerts.
The EU AI Act's risk-classification system imposes conformity assessment obligations on biometric identification and emotion recognition systems deployed in public spaces. Italian municipalities must now document algorithmic impact assessments and human oversight protocols before activating facial recognition capabilities. System integrators serving transportation and smart city verticals are restructuring service contracts to include ongoing compliance monitoring and algorithm retraining provisions.
Commercial buyers are consolidating vendor relationships and demanding outcome-based service level agreements rather than capital equipment purchases. Banking and logistics sectors now specify guaranteed detection accuracy thresholds and uptime commitments, shifting financial risk to integrators and managed security providers. This transformation concentrates procurement authority among national-scale facilities management firms with multi-region service capabilities.
Italy Video Surveillance Market Segmentation
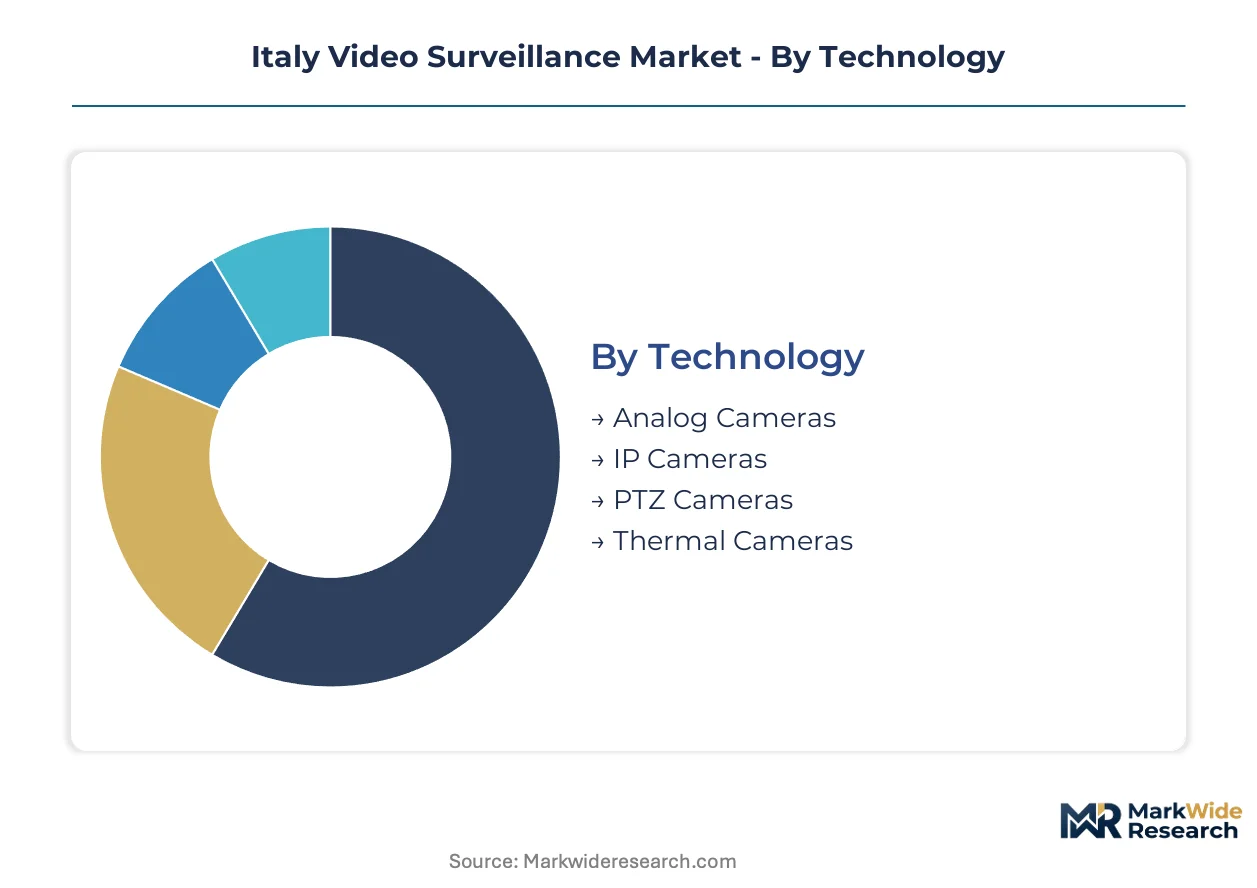
Segmentation in Italy's video surveillance market reveals distinct procurement patterns across technology tiers and installation architectures. Channel strategies diverge sharply between legacy analog replacement cycles and cloud-native greenfield deployments, with integrator capabilities and compliance requirements shaping vendor selection.
Technology:
Channel mix varies significantly across technology tiers, with professional installers dominating IP and PTZ deployments while electrical contractors handle analog maintenance and thermal specialist firms serving energy and defense verticals.
- IP Cameras:Networked devices with Power over Ethernet connectivity, H.265 compression, and edge-based analytics processing at 8+ megapixel resolutions. Demand concentrates in Milan's financial district and Turin automotive corridors where manufacturing facilities require integrated video analytics for perimeter protection and operational monitoring under National Recovery and Resilience Plan mandates.
- Analog Cameras:Coaxial-based CCTV systems with limited resolution and no native analytics capabilities. Thousands of small retail and residential installations across Campania and Sicily still operate these legacy configurations, creating friction for migration projects due to rewiring costs and installer channel capability deficits.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms enabling operator-controlled coverage of wide areas. Municipal traffic management contracts in Rome and smart city infrastructure bids specify these for dynamic incident response.
- Thermal Cameras:Infrared sensors detecting heat signatures for zero-light operation. Port security operators at Genoa and energy facilities in Basilicata deploy these for intrusion detection in perimeter zones.
IP Cameras dominate installed base across northern industrial corridors. Thermal Cameras are where expansion concentrates for critical infrastructure hardening.
End User:
Cost tier stratification separates enterprise-grade deployments with forensic archival requirements from budget-constrained residential installations.
- Commercial:Banks, logistics hubs, and hospitality chains requiring multi-site centralized monitoring with guaranteed uptime commitments and outcome-based service level agreements. This segment generates the deepest margin pools as facilities management firms consolidate vendor relationships.
- Government:Municipal digital transformation budgets funding AI-enabled networks for traffic management, crowd analytics, and environmental monitoring across Milan, Rome, and Turin smart city corridors. EU AI Act risk-classification requirements impose conformity assessment obligations on biometric identification deployments.
- Industrial:Manufacturing facilities deploying edge-analytics cameras for real-time anomaly detection and perimeter intrusion alerts with sub-100-millisecond response times.
- Residential:Single-family homes and small apartment buildings with basic deterrent-focused installations, often through retail channels rather than professional integrators.
Commercial end-users anchor procurement volume in value terms. Government verticals are climbing the fastest as Recovery and Resilience Plan disbursements accelerate.
Installation Type:
Application context determines architecture selection, with bandwidth availability and cybersecurity posture driving cloud versus on-premise decisions.
- Cloud-Based:Subscription-based centralized monitoring platforms displacing legacy NVR configurations. Mid-sized retail chains and multi-site hospitality operators in Lombardy and Veneto favor this model for operational expenditure flexibility and reduced IT overhead.
- On-Premise:Local network video recorders with dedicated storage arrays maintaining complete data sovereignty. Banking and critical infrastructure operators prefer this architecture for GDPR compliance and latency-sensitive applications.
- Wired:Ethernet or fiber-optic backbone connections delivering guaranteed bandwidth for high-resolution multi-camera feeds. Standard for industrial and municipal deployments.
- Wireless:Wi-Fi or cellular transmission enabling rapid deployment in heritage buildings or temporary sites where cabling is impractical. CE marking under EU Radio Equipment Directive governs certification timelines.
On-Premise systems retain installed base dominance in regulated sectors. Cloud-Based architectures are gaining share fastest among mid-market commercial adopters.
Application:
Customer type and maturity level shape feature requirements, with operational intelligence demands separating advanced analytics deployments from basic security monitoring.
- Building Security:Integrated access control, intrusion detection, and video verification for corporate campuses and public facilities. Honeywell and similar vendors bundle surveillance with fire safety and HVAC through BACnet protocol interoperability.
- Retail Analytics:Heat mapping, dwell time measurement, and queue management converting surveillance infrastructure into merchandising intelligence. Chains in Milan's fashion district deploy these for footfall optimization.
- Traffic Monitoring:Automatic number plate recognition and incident detection for municipal authorities managing congestion in Rome and Turin metropolitan areas.
- Remote Surveillance:Mobile-enabled monitoring of construction sites, agricultural properties, and temporary event venues across southern regions with lower permanent camera density.
Building Security commands the broadest deployment footprint. Retail Analytics represents the steepest expansion trajectory as merchants monetize existing camera networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian component fabrication dominates upstream supply chains for Italian integrators, while procurement demand clusters along northern industrial corridors and major metropolitan centers. Local deployment patterns reflect sharp divergence between smart city infrastructure investments and legacy system replacement cycles across the peninsula.
Lombardy
Milan's financial district and Malpensa logistics corridor drive enterprise-grade IP camera procurement for banking and freight security. The National Recovery and Resilience Plan channels funds through regional infrastructure budgets. Manufacturing facilities around Bergamo deploy edge-analytics cameras for real-time perimeter protection under industrial automation mandates.
Piedmont
Turin's automotive corridor generates concentrated demand for video analytics in assembly plant security and quality control integration. GDPR retention limitations enforced by Italy's Data Protection Authority shape archival architecture decisions. The metropolitan traffic management authority specifications favor PTZ cameras with automated incident detection protocols.
Lazio
Rome's municipal digital transformation budget funds AI-enabled networks for crowd analytics and heritage site monitoring. EU AI Act risk-classification requirements impose conformity assessments on biometric identification deployments. Central government facility security upgrades concentrate procurement authority among national-scale integrators with multi-region service capabilities.
Veneto
Port security operators at Venice and industrial zones near Verona drive thermal camera adoption for zero-light perimeter detection. CE marking under the EU Radio Equipment Directive governs wireless transmission certification timelines. Mid-sized retail chains across the region favor cloud-native VMS architectures for operational expenditure flexibility.
Campania
Naples exhibits lower camera density per capita than northern regions, presenting whitespace for regional system integrators and managed service providers. Small retail installations still operate legacy analog CCTV systems, creating friction for IP migration due to rewiring costs and installer channel capability deficits. Southern underpenetration attracts subscription-based monitoring platforms seeking expansion beyond saturated northern markets.
Italy Video Surveillance Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, producing a tiered market structure with limited overlap between premium integrated systems and volume hardware supply. The vendor base spans multinational conglomerates with building management convergence capabilities, specialized regional integrators, and East Asian manufacturers leveraging fabrication scale. Two strategic archetypes dominate: full-stack platform providers bundling surveillance with access control and fire safety, and component specialists supplying IP camera arrays for large infrastructure bids. Competitive moves concentrate on M&A for cybersecurity certification capabilities and strategic partnerships to address installer channel capability deficits.
Among East Asian manufacturers, Dahua Technology and Hangzhou Hikvision Digital Technology Company Limited exemplify scale-driven positions in the cost-leadership tier, supplying networked camera hardware for municipal and enterprise procurement cycles. Honeywell Security Group occupies a position within the integrated systems archetype, representing the building management convergence strategy that bundles surveillance with broader facility automation protocols. These three companies anchor distinct competitive vectors—hardware scale, installer channel depth, and platform integration—that structure vendor selection criteria across Italian end-user segments.
| Leading Market Players |
|---|
| Teledyne Flir LLC |
| Videotec SRL |
| Honeywell Security Group |
| Dahua Technology |
| Hangzhou Hikvision Digital Technology Company Limited |
| Esprinet S.p.A |
| Bettini S.r.l. |
| Aitek SpA |
| Johnson Controls |
| Others |
Pricing and Supply Chain Analysis
Project-based procurement contracts for municipal smart city infrastructure lock in multi-year supply commitments for IP camera arrays while fixing unit pricing visibility for Italian systems integrators bidding on National Recovery and Resilience Plan disbursements. This contract structure concentrates purchasing power among national-scale facilities management firms while exposing smaller regional installers to spot-market component volatility.
Pricing Analysis
CE marking under the EU Radio Equipment Directive dictates the pricing tier structure across Italian video surveillance deployments, separating certified wireless IP cameras from uncertified imports. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by cybersecurity certification grade and after-sales service bundling. Pricing pressure stems from East Asian manufacturers leveraging fabrication scale to undercut European integrators on hardware-only bids. Small retail chains in southern regions exhibit highest price sensitivity, while banking and critical infrastructure operators prioritize guaranteed uptime over unit cost.
Supply Chain Analysis
Inventory buffers at Italian distributors currently stretch to sixteen weeks for edge-analytics cameras with onboard GPU chips, reflecting foundry allocation constraints in Taiwan and South Korea. Image sensor fabrication concentrates in Taiwan, South Korea, and Japan, while SoC assembly feeds from Chinese packaging facilities. Raw material dependencies span silicon wafers, rare earth elements for thermal sensors, and copper for PoE cabling. Single-source vulnerability in advanced CMOS image sensors exposes integrators to allocation cuts during semiconductor cycle peaks. Distribution runs through specialized security distributors and electrical wholesale channels rather than broad-line electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across installer capability tiers creates acquisition opportunities as cloud-native deployments demand network engineering skills that legacy electrical contractors lack. The shift from capital equipment sales to subscription-based monitoring services fragments end-user relationships and opens niches for managed security specialists.
For Market Incumbents: Consolidate installer channel control through certified training programs that address cybersecurity skills deficits constraining complex multi-site deployments. Acquire regional system integrators in Campania and Sicily to capture whitespace before subscription-based entrants establish footholds. Defend against East Asian hardware scale by bundling video analytics with access control and fire safety through BACnet protocol interoperability. For New Entrants and Emerging Players: Managed service gaps in southern Italy's underpenetrated markets offer immediate white-space where camera density per capita lags northern industrial corridors by substantial margins. Target Campania's small retail segment with wireless rapid-deployment kits that bypass rewiring friction blocking IP migration. Pursue outcome-based service level agreements with guaranteed detection accuracy thresholds to differentiate from hardware-centric incumbents. For Investors and Strategic Acquirers: The market sits at a compliance-driven consolidation phase that favors cybersecurity-certified mid-cap specialists with multi-region service capabilities. Long-term viability hinges on EU AI Act implementation creating barriers for uncertified analytics vendors. Watch algorithmic transparency obligations in Italian implementing decrees as the signal indicating which AI-powered features remain permissible for public-space deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | CE marking and EU Cybersecurity Act compliance accelerates product launches for wireless IP camera deployments. |
| Cloud-Native VMS Platform Development | Subscription architectures capture mid-sized retail chains abandoning on-premise NVR configurations in Lombardy. |
| Installer Channel Capability Building | Technical training programs address network engineering deficits constraining complex multi-site project velocity. |
| Southern Italy Geographic Expansion | Campania and Sicily whitespace offers managed service providers escape from saturated northern municipal markets. |
| Integrated Building Management Convergence | Bundling surveillance with access control and fire safety through BACnet protocols deepens enterprise relationships. |
Research Methodology
Operator-level perspectives from municipal procurement officers, security systems integrators, facilities management executives, and professional installer network managers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against CE marking databases, EU AI Act implementation tracking, and National Recovery and Resilience Plan disbursement records. Customs data on IP camera imports, Garante per la Protezione dei Dati Personali enforcement actions, and smart city tender announcements provided quantitative anchors. Bottom-up segment sizing triangulated against top-down infrastructure budget allocations.
Sensitivity analysis tested forecast robustness across alternative scenarios for EU AI Act implementation timing and semiconductor supply normalization. The analytical framework modeled technology tiers, installation architectures, end-user verticals, and regional adoption patterns across the projection horizon. CAGRs derived from segment-level growth drivers weighted by procurement cycle visibility and compliance timeline uncertainty. Edge analytics penetration rates and cloud-native VMS adoption curves served as industry-specific forecast inputs.
Underlying assumptions cover steady National Recovery and Resilience Plan disbursement continuity and stable East Asian foundry allocation for image sensors, with deviation risk concentrated in GDPR enforcement intensity and EU AI Act secondary legislation timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Night Vision System (NVS) Market
Video Surveillance Systems
Latin America Surveillance Camera Market
Video Surveillance Systems
Europe Video Surveillance Storage Market
Video Surveillance Systems
Crawler Camera System Market
Video Surveillance Systems
Under-Vehicle Surveillance Market
Video Surveillance Systems
North America Smart Home Security Cameras Market
Video Surveillance Systems
Brazil Surveillance Camera Market
Video Surveillance Systems
Aircraft Video Surveillance Systems Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
Smart Doorbell Camera Market
Video Surveillance Systems
France Video Surveillance Market
Video Surveillance Systems
United States Surveillance Analog Camera Market
Video Surveillance Systems
India Surveillance IP Cameras Market
Video Surveillance Systems
Coastal Surveillance Systems Market
Video Surveillance Systems
Night Vision (IR) Surveillance Cameras Market
Video Surveillance Systems
Global Video Surveillance Systems Market