
 Baggage Scanner Market | 2026-2036
Baggage Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Baggage Scanner Market Analysis
The buyer base for baggage screening equipment is broadening beyond traditional aviation authorities to encompass mass transit operators and large-scale event venues. Smiths Detection leverages its installed base at Heathrow and Dubai International to sustain recurring service revenue streams. Leidos anchors its position through deep integration with U.S. government security programs. Nuctech Company Limited competes aggressively on manufacturing scale, offering turnkey checkpoint solutions across emerging markets in Africa and Southeast Asia.
A baggage scanner is a security inspection system that uses ionizing radiation, millimeter-wave sensors, or computed tomography to generate cross-sectional images of luggage contents, typically resolving objects below one millimeter in dense materials. These systems serve to detect contraband, explosives, and weapons without manual bag opening, primarily at transportation checkpoints and high-security facilities. X-ray scanners still occupy the largest installed base globally, though computed tomography scanners are displacing legacy systems where regulatory mandates require automatic explosive detection. Portable installation types are gaining traction among customs agencies and temporary event security teams seeking rapid deployment without fixed infrastructure.
The U.S. Transportation Security Administration sets operational requirements that directly shape product development cycles for domestic manufacturers, while the EU's EASA and CE marking frameworks enforce harmonized detection standards across member states. China's MIIT and NMPA impose domestic certification barriers that favor local suppliers like Nuctech for government procurement. Stakeholders must monitor how divergent national certification timelines affect product rollout schedules and aftermarket service commitments across jurisdictions.
Market Dynamics
Computed tomography retrofit programs are compressing replacement cycles across major aviation hubs, forcing manufacturers to reconfigure service architectures around faster deployment timelines and modular hardware upgrades.
Growth Catalysts
- EU EASA Certification Mandates:European aviation authorities require automatic explosive detection capabilities at Category A airports, compelling wholesale replacement of legacy X-ray infrastructure with 3D imaging systems.
- Mass Transit Security Expansion:High-speed rail operators in France, Japan, and South Korea are installing baggage screening checkpoints at central stations to mirror aviation-grade threat detection protocols.
- Millimeter-Wave Convergence:Hybrid scanners combining active millimeter-wave sensors with CT reconstruction are reducing false alarm rates below three percent in dense luggage environments.
Market Restraints
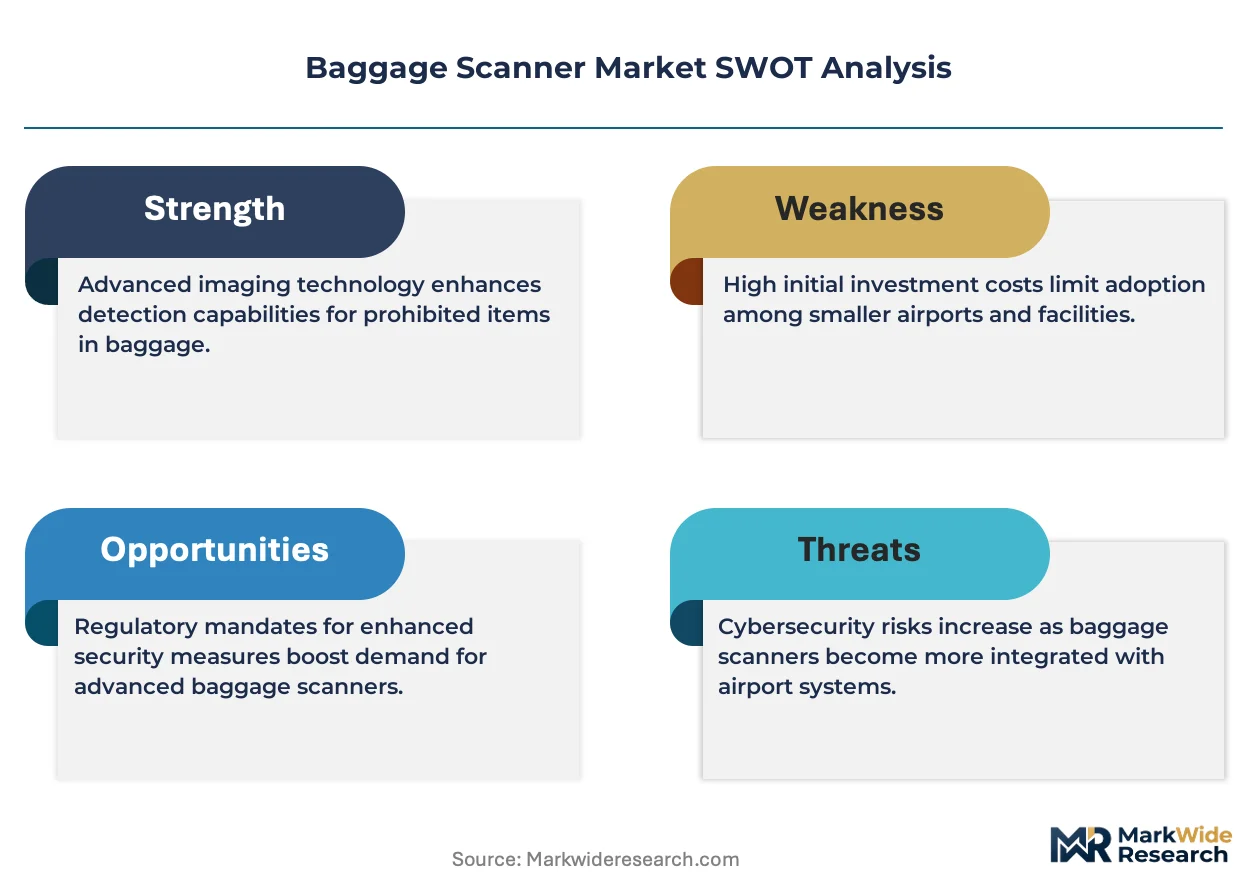
- Helium-3 Supply Concentration:Thermal neutron detection systems depend on helium-3 reserves concentrated in United States and Russian federal stockpiles, creating isotope scarcity for explosive detection modules.
- High-Density Tungsten Shielding Costs:Radiation containment requirements for CT scanners require tungsten alloy components whose spot prices fluctuate with aerospace and defense procurement cycles.
- Legacy Analog Archive Incompatibility:Existing security operations centers lack digital infrastructure to store and retrieve terabyte-scale CT scan datasets, forcing parallel IT capital commitments.
Strategic Opportunities
- India Metro Rail Expansion:The Delhi Metro Rail Corporation and Mumbai Metro are tendering for integrated baggage and passenger screening systems across twenty-three new corridor phases.
- Outcome-Based Service Contracts:Saudi Arabia's General Authority of Civil Aviation is piloting availability-based payment models where contractors guarantee system uptime rather than selling hardware outright.
- AI-Assisted Threat Recognition:Convolutional neural networks trained on synthetic CT datasets are enabling automated prohibited item detection without human operator image interpretation.
Industry Challenges
- Certification Timeline Compression:TSA's ACSTL laboratory queue for new CT platform validation extends eighteen to twenty-four months, delaying product launches for domestic manufacturers.
- Legacy System Integration Complexity:Airports operating 1990s-era single-view X-ray tunnels face structural constraints on power, cooling, and conveyor mechanics that resist CT retrofit without terminal reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baggage Scanner Market |
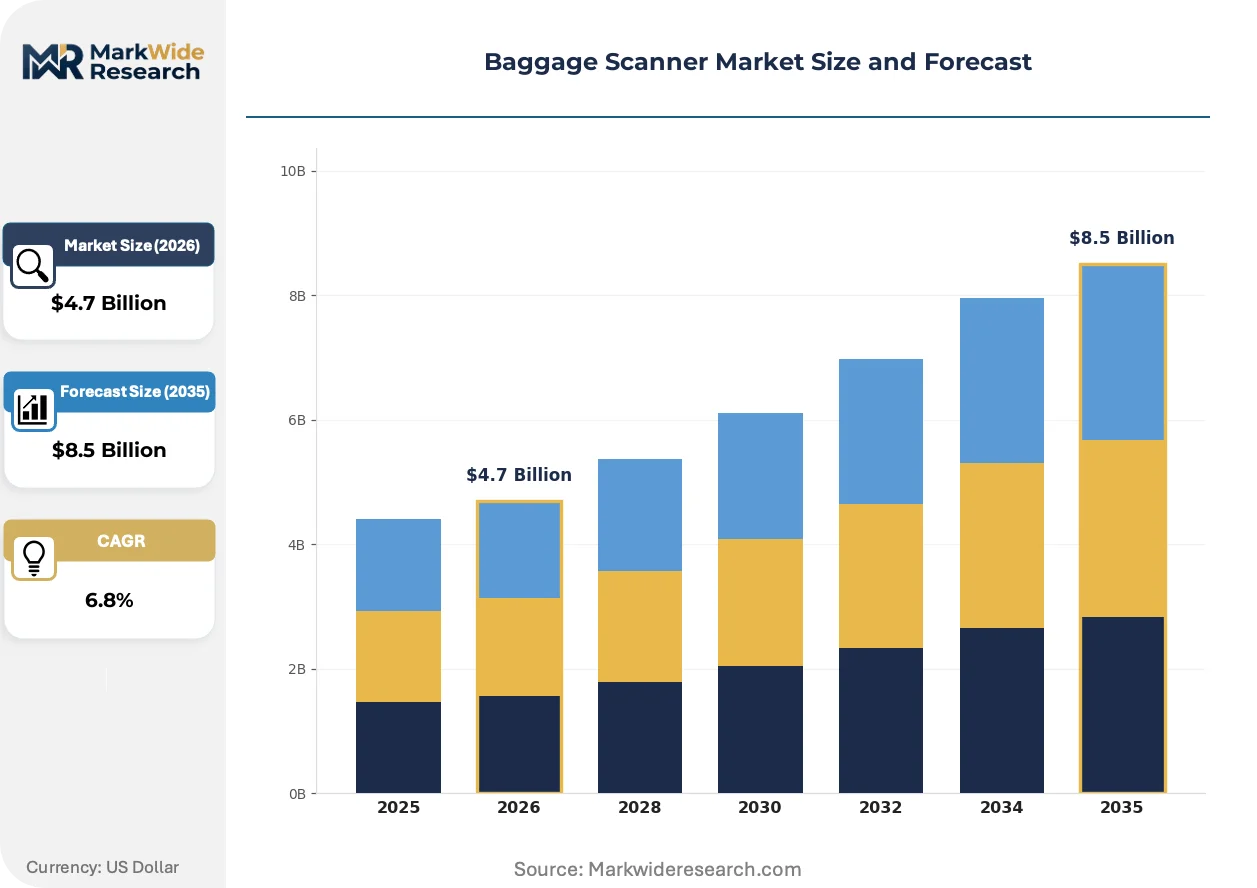
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
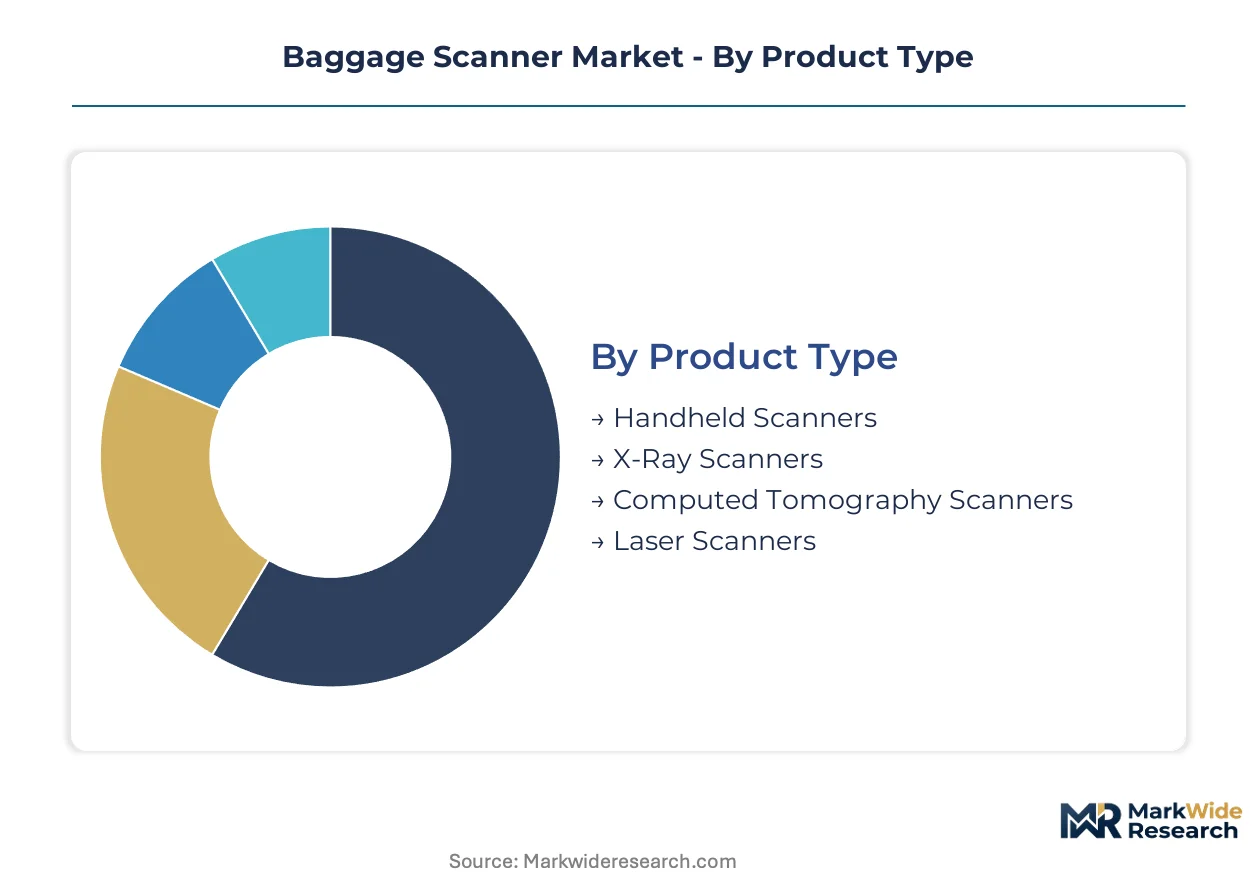
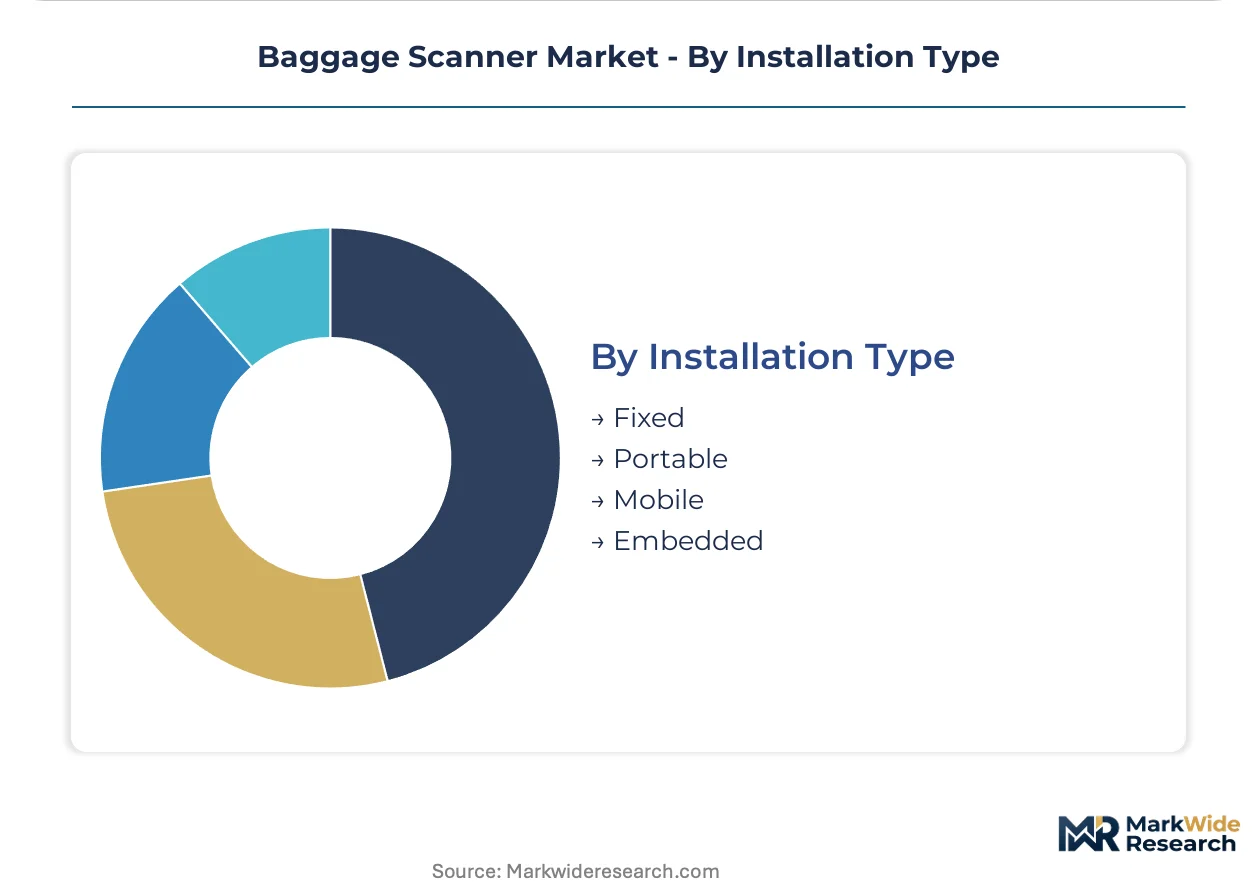
| Segmentation | Product Type: Handheld Scanners, X-Ray Scanners, Computed Tomography Scanners, Laser Scanners End User: Aviation, Transportation Hubs, Events, Customs Technology: Linear Accelerators, Backscatter Technology, 3D Imaging, Explosive Detection Installation Type: Fixed, Portable, Mobile, Embedded |
| Companies Covered | OSI Systems, Leidos, Smiths Detection, Astrophysics Inc., Analogic Corporation, Rapiscan Systems, L3Harris Technologies, CEIA S.p.A., Nuctech Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baggage Scanner Market Emerging Trajectories
Deep learning inference at the edge is restructuring how threat detection algorithms deploy, shifting computational loads from centralized servers to scanner-embedded GPUs and enabling real-time decision-making without network latency.
Dual-energy CT reconstruction is automating material discrimination between organic explosives and benign plastics at molecular density resolutions below 0.5 millimeters. Airport authorities in Germany and the Netherlands are deploying these systems at transfer checkpoints where passenger re-screening previously caused connection delays. The technology is automating the elimination of manual bag opening for approximately forty percent of alarm-triggered luggage.
REACH restrictions on lead-based shielding materials are compelling manufacturers to substitute bismuth-tin alloys in radiation containment architectures. The European Chemicals Agency's 2024 sunset date for lead exemptions in industrial equipment is accelerating reformulation programs across scanner OEM supply chains. German component suppliers are certifying tungsten-polymer composites that maintain attenuation performance while satisfying substance restriction mandates.
Buying committees at major hub airports are unbundling hardware procurement from decade-long service agreements, creating separate competitive arenas for installation contractors and aftermarket maintenance providers. This fragmentation is most visible in the United States, where TSA's Screening Partnership Program allows airports to opt out of federal maintenance contracts and source independent service operators.
Baggage Scanner Market Segmentation
Equipment specifications diverge sharply across deployment contexts, with aviation checkpoints demanding certified explosive detection while customs operations prioritize throughput velocity. Manufacturers configure platform architectures around these distinct operational profiles, creating specialized product lines that resist easy substitution between segments.
Product Type:
Capital intensity peaks with computed tomography platforms requiring precision-machined detector arrays and radiation-shielded tunnel structures, whereas handheld units operate at fractional fixed-asset thresholds.
- Computed Tomography Scanners:Multi-slice detector arrays rotate around conveyor-fed luggage to generate volumetric reconstructions at sub-millimeter resolution. Category A airports in Germany and the Netherlands are replacing legacy checkpoints with these systems to satisfy EASA automatic explosive detection mandates.
- X-Ray Scanners:Dual-energy transmission imaging remains the dominant installed base, using high-frequency generators to discriminate organic from inorganic materials through atomic number analysis. Secondary screening lanes at mid-tier aviation facilities in India and Southeast Asia continue specifying these units for cost-constrained procurement cycles.
- Handheld Scanners:Battery-operated backscatter units enable customs inspectors to examine suspect items without unloading cargo containers.
- Laser Scanners:Raman spectroscopy systems identify chemical signatures through non-contact laser excitation for explosive trace detection.
X-Ray scanners absorb the bulk of installed capacity; computed tomography scanners are expanding most quickly.
End User:
Application context dictates detection sensitivity thresholds, with aviation authorities operating under the strictest certification regimes while event security prioritizes rapid passenger processing.
- Aviation:Checkpoint configurations must achieve TSA ACSTL or EASA certification for automatic threat recognition, requiring redundant sensor arrays and centralized image archival infrastructure. Major hub airports in the United States are modernizing federal screening checkpoints under TSA procurement programs.
- Transportation Hubs:High-speed rail terminals in France, Japan, and South Korea are installing aviation-grade screening lanes to mirror threat detection protocols for intercity passengers.
- Customs:Port and border facilities emphasize cargo throughput and contraband detection over passenger convenience.
- Events:Temporary venues require rapid-deployment screening architectures with minimal fixed infrastructure.
Aviation commands the dominant share of equipment revenue; transportation hubs are gaining share fastest as rail operators replicate aviation security models.
Technology:
Performance differentiation stems from radiation source architecture and image reconstruction algorithms, with linear accelerator platforms delivering the highest penetration capability for dense cargo.
- Explosive Detection:Automated recognition algorithms analyze CT density signatures to flag threats without operator interpretation. EASA mandates are accelerating deployment at European Category A airports.
- 3D Imaging:Volumetric reconstruction eliminates blind spots inherent in projection radiography, enabling automated prohibited item identification.
- Linear Accelerators:High-energy electron beams generate penetrating radiation for examining densely packed containerized cargo.
- Backscatter Technology:Compton scattering detection highlights low-atomic-number contraband against metallic backgrounds.
Explosive detection technology claims the steepest expansion trajectory; 3D imaging is displacing legacy projection systems in premium checkpoint installations.
Installation Type:
Site permanence determines infrastructure integration depth, with fixed installations requiring civil engineering and embedded units demanding seamless architectural incorporation.
- Fixed:Permanent tunnel structures with integrated power distribution and climate control dominate high-volume aviation checkpoints. Dubai International and Heathrow operate extensive fixed-lane networks.
- Portable:Self-contained units on wheeled frames deploy without construction for temporary events or emergency response. Saudi customs agencies are procuring these for seasonal pilgrimage surges.
- Mobile:Vehicle-mounted screening systems serve border patrol and remote checkpoint applications.
- Embedded:Concealed detection arrays integrate into building architecture for aesthetic or operational discretion.
Fixed installations retain the largest operational footprint; portable configurations are climbing the fastest as customs agencies seek operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States aviation authorities drive the largest equipment procurement volumes, with federal modernization programs replacing legacy checkpoints at major hubs. European regulators are compressing replacement cycles through mandatory explosive detection standards. Asian markets are expanding fastest as rail operators replicate aviation security protocols.
United States
The Transportation Security Administration operates the world's largest deployed base of aviation screening equipment, with ongoing ACSTL certification programs validating next-generation CT platforms. Federal procurement schedules prioritize automated screening lane expansion at Atlanta, Dallas-Fort Worth, and Denver International. Domestic manufacturers anchor production clusters in California and Massachusetts, supplying integrated checkpoint solutions under multi-year service contracts.
Germany
Category A airports in Frankfurt, Munich, and Berlin are executing wholesale X-ray infrastructure replacement to satisfy EASA automatic explosive detection mandates. The Federal Office for Information Security enforces cybersecurity certification for connected screening systems, extending validation timelines. Industrial concentration in Bavaria and Baden-Württemberg hosts precision detector array fabrication facilities serving European hub modernization programs.
China
MIIT and NMPA certification barriers favor domestic suppliers for government procurement of metro rail and aviation checkpoint systems. High-speed rail operators in the Yangtze River Delta and Pearl River Delta are installing integrated passenger and baggage screening at central stations. Beijing Capital and Shanghai Pudong are deploying domestically manufactured CT platforms under centralized procurement frameworks.
India
The Delhi Metro Rail Corporation and Mumbai Metro are tendering for integrated screening systems across twenty-three new corridor phases under the Ministry of Housing and Urban Affairs urban transit expansion. Bureau of Indian Standards certification requirements for explosive detection equipment are accelerating local assembly partnerships. Industrial clusters in Maharashtra and Karnataka are emerging as service hubs for South Asian customs and rail installations.
Saudi Arabia
The General Authority of Civil Aviation is piloting availability-based payment models where contractors guarantee system uptime rather than selling hardware outright. Seasonal pilgrimage surges at Jeddah and Medina airports are driving demand for rapid-deployment portable screening units. Domestic procurement frameworks are integrating screening infrastructure with NEOM and Red Sea Project tourism corridor developments.
Baggage Scanner Market Vendor Landscape
North American producers anchor one tier; Chinese specialists hold manufacturing scale advantages in emerging markets. The vendor structure concentrates around systems integrators with federal certification relationships and component suppliers with detector array fabrication capabilities. Two strategic archetypes dominate: established security contractors with government program integration and emerging-scale manufacturers with turnkey export capabilities. Competitive positioning depends on certification timeline navigation and modular hardware upgrade architectures.
Within the government-integrated tier, Leidos and Smiths Detection occupy positions shaped by deep federal and international aviation authority relationships. Nuctech Company Limited exemplifies the scale-driven archetype, competing through manufacturing capacity and emerging market turnkey deployment. These three anchors illustrate how competitive advantage separates between certification-intensive program execution and volume-oriented export positioning.
| Leading Market Players |
|---|
| OSI Systems |
| Leidos |
| Smiths Detection |
| Astrophysics Inc. |
| Analogic Corporation |
| Rapiscan Systems |
| L3Harris Technologies |
| CEIA S.p.A. |
| Nuctech Company Limited |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between TSA ACSTL-validated CT platforms and uncertified dual-energy X-ray units manifests in pricing spreads exceeding threefold, with premium-tier suppliers capturing service-anchored revenue streams while commodity manufacturers compete on detector array cost curves and regional logistics arbitrage.
Pricing Analysis
Volume-driven procurement by U.S. federal programs compresses unit margins on CT platforms, while aftermarket service bundling restores profitability through decade-long maintenance commitments. Price differentiation centers on EASA certification status and tungsten shielding alloy specifications. Pricing pressure intensifies as Chinese manufacturers scale detector array fabrication, eroding European component premiums. Customs agencies exhibit highest price sensitivity due to throughput-centric procurement mandates, whereas major hub airports prioritize certification compliance over acquisition cost.
Supply Chain Analysis
Freight costs for precision-machined tungsten radiation shielding and helium-3 neutron detection modules concentrate supply risk on trans-Pacific routes and U.S. federal stockpile releases. Manufacturing clusters in Germany, China, and the United States anchor detector array fabrication and final system assembly. Raw material dependencies include high-purity tungsten, bismuth-tin alloys substituting for REACH-restricted lead, and specialized scintillator crystals. Single-source vulnerability persists for helium-3 isotope supply controlled by U.S. and Russian strategic reserves. Distribution runs through systems integrators with federal certification relationships rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computed tomography platforms are displacing legacy X-ray infrastructure across Category A aviation checkpoints, compressing replacement cycles and restructuring vendor competitive dynamics around certification velocity and modular upgrade architectures.
For Market Incumbents: Extend service contract penetration at Heathrow-scale installations to lock out independent maintenance competitors emerging under TSA's Screening Partnership Program. Deepen backward integration into scintillator crystal production to insulate margins from helium-3 supply volatility and tungsten price cyclicality. Accelerate AI-assisted threat recognition R&D to differentiate against emerging Chinese CT platforms competing on manufacturing scale. For New Entrants and Emerging Players: Temporary event security teams and seasonal customs operations represent underserved buyer archetypes seeking rapid-deployment portable screening without fixed infrastructure commitments. Target India's twenty-three metro rail corridor phases with turnkey checkpoint solutions bundling passenger and baggage screening. Pursue outcome-based payment pilots mirroring Saudi Arabia's availability-based contracting models to bypass upfront capital barriers. For Investors and Strategic Acquirers: Re-rating potential sits with detector array fabricators possessing EASA and TSA certification relationships given EU mandate-driven replacement cycles and U.S. federal modernization programs. Long-term viability hinges on AI inference hardware and edge computing capabilities enabling automated threat recognition. Monitor TSA ACSTL validation queue compression as inflection signal for domestic manufacturer product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CT Platform Certification Acceleration | TSA ACSTL validation reduces time-to-revenue for domestic manufacturers competing against established suppliers. |
| Helium-3 Alternative Detection Development | Thermal neutron substitution insulates explosive detection modules from U.S. and Russian federal stockpile constraints. |
| AI-Assisted Threat Recognition Deployment | Convolutional neural networks trained on synthetic CT datasets reduce false alarm rates below three percent. |
| Outcome-Based Service Contract Expansion | Availability-based payment models at Saudi Arabia's General Authority of Civil Aviation shift risk from airport operators to vendors. |
| Bismuth-Tin Shielding Alloy Certification | REACH-compliant radiation containment satisfies European Chemicals Agency substance restrictions while maintaining attenuation performance. |
Methodological Framework
Regulatory filing databases, customs trade records, and aviation authority procurement disclosures formed the secondary backbone, supplemented by primary interviews with TSA program managers, EASA certification engineers, airport procurement directors, and detector array fabrication specialists. Bottom-up equipment shipment tracking across thirty-seven countries was triangulated against top-down federal budget appropriation analysis for U.S. and European modernization programs.
Historical trendline analysis of replacement cycle compression and certification timeline extensions informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, end-user application context, technology architecture, and installation permanence. CAGRs were derived from equipment procurement schedules, regulatory mandate effective dates, and rail operator security expansion commitments. Forecast inputs incorporated EASA Category A airport compliance deadlines and TSA automated screening lane deployment targets.
Revisions become necessary when helium-3 supply disruptions, tungsten price volatility, or certification timeline delays materialize beyond baseline assumptions. Forecasts reflect documented procurement schedules and regulatory mandate calendars. Stakeholders should weight assumptions against their own operating context and supply chain exposure to critical isotope and alloy inputs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Security Inspection Market
Security and Surveillance
Global Wireless Monitoring and Surveillance Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
North America Urban Security Screening Market
Security and Surveillance
Global Alarm Monitoring Market
Security and Surveillance
Security Product Integration Services Market
Security and Surveillance
Smart Home Security Market
Security and Surveillance
Global Container Security Market
Security and Surveillance
Lawful Interception Market
Security and Surveillance
Global Security As a Service Market
Security and Surveillance
Shock Sensor Market
Security and Surveillance
Narcotics Scanner Market
Security and Surveillance
Consumer Security Market
Security and Surveillance
Global Wireless Doorbells Market
Security and Surveillance
Night Vision Binoculars Market
Security and Surveillance
Global Corporate Travel Security Market