
 Electron Microscopy Market | 2026-2036
Electron Microscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Electron Microscopy Market Analysis
The EU Green Deal is hardening sustainability requirements for scientific instrumentation procurement across European academic research institutions. Thermo Fisher Scientific leverages its cryo-electron microscopy portfolio to anchor structural biology workflows in pharmaceutical laboratories. JEOL sustains its dominance in transmission electron microscope manufacturing through integrated column production and proprietary electron source technology. Bruker differentiates via spectroscopy-integrated imaging platforms that combine elemental analysis with nanoscale morphological mapping.
Electron microscopy employs focused electron beams to achieve sub-angstrom spatial resolution, utilizing electromagnetic lenses to magnify specimens beyond the diffraction limits of visible light. Systems operate under high vacuum conditions with accelerating voltages ranging from tens to thousands of kilovolts, enabling atomic-scale imaging of crystalline structures, biological macromolecules, and semiconductor device architectures. Scanning electron microscopes occupy the largest installed base due to versatile surface imaging and lower operational complexity relative to transmission variants. Cryo-electron microscopes represent the fastest-expanding product category as pharmaceutical companies adopt single-particle analysis for therapeutic protein characterization. Semiconductor inspection applications command premium pricing tiers driven by zero-defect tolerance at advanced process nodes.
The FDA governs electron microscopy use in medical device characterization and pharmaceutical quality control through Good Manufacturing Practice guidelines. EPA regulations restrict hazardous material handling in electron microscopy sample preparation, particularly heavy metal stains and fixatives. ISO 17025 accreditation requirements shape laboratory purchasing decisions for metrology-grade systems. Semiconductor manufacturers must monitor evolving export control classifications for dual-use electron optics technology.
Market Dynamics
Semiconductor node shrinkage below three nanometers is compressing inspection tolerances and forcing fabs to replace electron microscopy fleets faster than historical depreciation cycles.
Growth Catalysts
- EU Chips Act capital redirection:Sovereign semiconductor initiatives in Europe are funding domestic fabrication facilities that require high-resolution metrology tools for process control.
- Cryo-electron microscopy workflows:Pharmaceutical laboratories are embedding single-particle analysis into therapeutic protein characterization pipelines for structural biology applications.
- Zero-defect semiconductor inspection:Advanced process nodes in Taiwan, South Korea, and the United States demand inspection-grade systems with sub-angstrom resolution capabilities.
Market Restraints
- Helium supply concentration:Superconducting electron source cooling depends on helium sourcing concentrated in Qatar, Algeria, and Russia, creating input cost volatility.
- Dual-use export controls:Electron optics technology faces tightening classification under Wassenaar Arrangement restrictions, limiting cross-border system transfers.
- Transmission electron microscope complexity:TEM systems require specialized facilities with vibration isolation and electromagnetic shielding that constrains installation sites.
Strategic Opportunities
- India semiconductor ecosystem buildout:The country's PLI scheme for electronics manufacturing is attracting fab investments that will require metrology infrastructure.
- Spectroscopy-integrated imaging platforms:Converging elemental analysis with nanoscale morphological mapping opens workflows in materials science and failure analysis.
- EU Green Deal procurement mandates:Sustainability requirements for scientific instrumentation are creating preference shifts toward energy-efficient system designs in European academic institutions.
Industry Challenges
- Cryo-EM specialist technician scarcity:Single-particle analysis and vitrification protocols require trained personnel that outpace university pipeline output.
- ISO 17025 accreditation timelines:Metrology-grade system qualification for semiconductor fabs extends procurement cycles by six to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electron Microscopy Market |
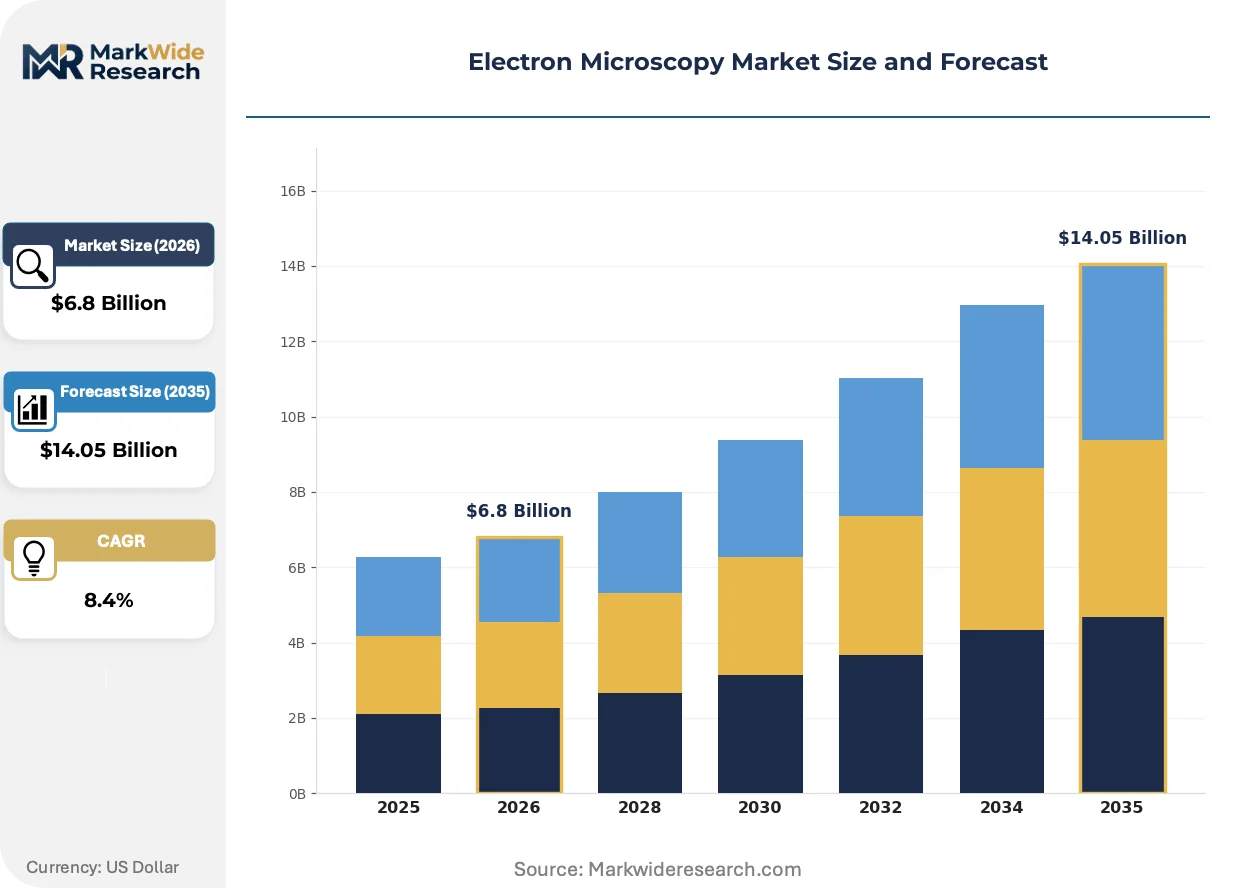
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transmission Electron Microscopes, Scanning Electron Microscopes, Hybrid Electron Microscopes, Cryo-Electron Microscopes Application: Nanotechnology, Materials Science, Life Sciences, Semiconductor Inspection End User: Academic Research Institutions, Pharmaceutical Companies, Semiconductor Manufacturers, Government Research Labs Distribution Channel: Direct Sales, Online Sales, Distributors, Resellers |
| Companies Covered | Carl Zeiss, Leica Microsystems, Thermo Fisher Scientific, Danaher, Oxford Instruments, JEOL, Bruker, AMETEK, Hitachi High-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electron Microscopy Market Emerging Trajectories
Electron microscopy vendors are racing to embed artificial intelligence into image reconstruction while sovereign semiconductor policies rewrite geographic demand patterns.
Direct electron detection sensors are integrating with complementary metal-oxide-semiconductor architectures to replace traditional charge-coupled device cameras. Pharmaceutical laboratories and academic structural biology cores are adopting these sensors at accelerated replacement cycles. The technology is integrating machine learning-based denoising algorithms that compress data acquisition times from days to hours for single-particle analysis.
REACH restrictions on perfluorinated compounds are forcing electron microscope manufacturers to reformulate vacuum pump sealing materials and lubricants. The industrial consequence extends to service intervals and component replacement protocols across installed bases. Semiconductor fabs in Germany and the Netherlands are responding by negotiating extended compliance timelines with ECHA while qualifying alternative fluorine-free compounds.
Academic consortia are consolidating electron microscopy access through national facility networks rather than individual institutional ownership. Core facilities with full-time staff are displacing department-level instruments in North American and European research universities. South Korea's KBSI and Taiwan's NCHC operate the most visible national models, concentrating capital investment while expanding user access through remote operation capabilities.
Electron Microscopy Market Segmentation
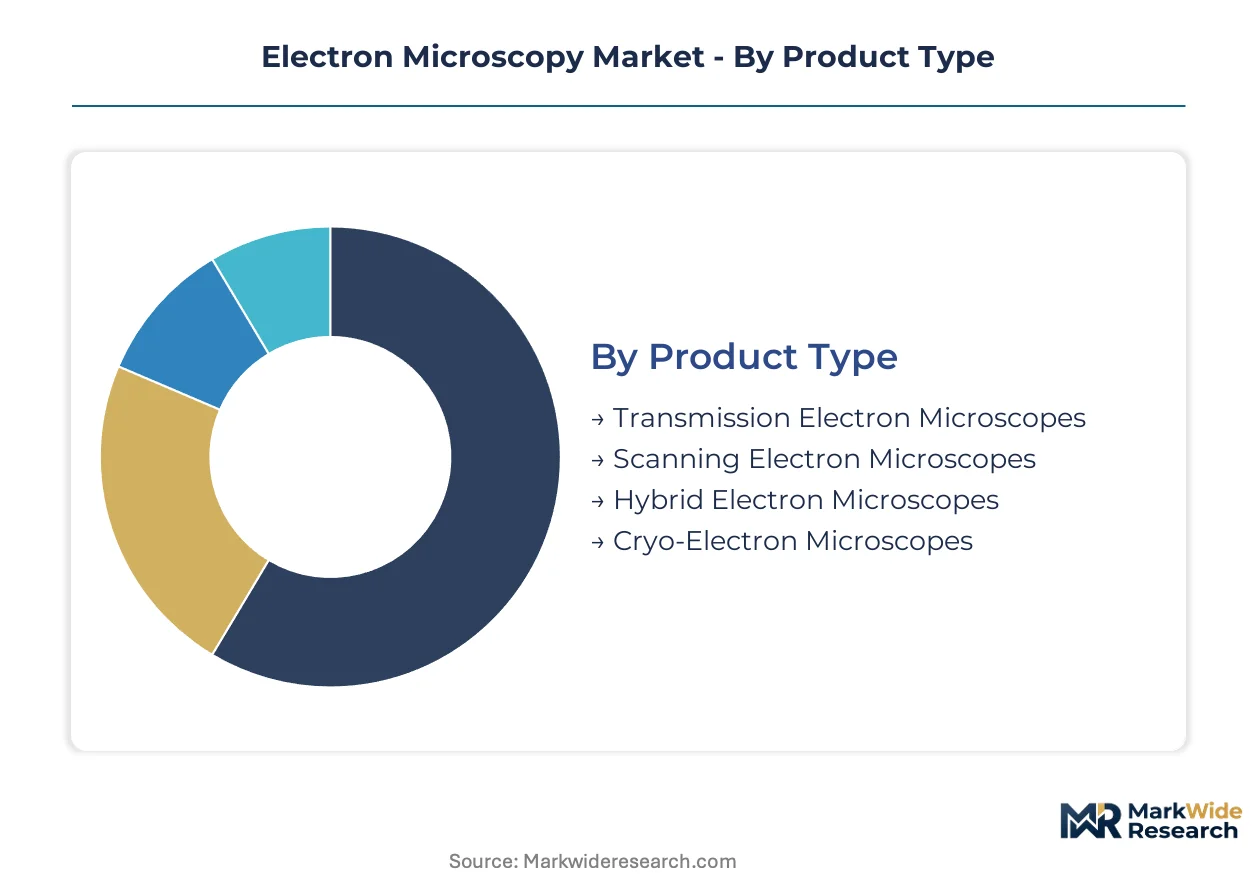
Electron microscopy procurement patterns diverge sharply across user categories, with semiconductor fabs demanding metrology-grade systems at price points tenfold above academic configurations. Product architecture and end-use specifications create distinct commercial segments with incompatible performance benchmarks and service expectations.
Product Type:
Capital intensity varies by three orders of magnitude across this category, with cryogenic variants commanding facility investments beyond the instrument itself.
- Transmission Electron Microscopes:These systems accelerate electrons through ultra-thin specimens using electromagnetic lens arrays to achieve atomic-scale lattice resolution. Taiwan Semiconductor Manufacturing and Samsung Foundry deploy TEM fleets for defect characterization at sub-three-nanometer nodes, though helium-cooled superconducting sources create supply chain exposure concentrated in Qatar and Algeria.
- Cryo-Electron Microscopes:Vitrification chambers flash-freeze biological specimens in amorphous ice, preserving native protein conformations for single-particle reconstruction. Pfizer, Moderna, and academic structural biology cores in Boston and Cambridge are expanding cryo-EM capacity for therapeutic protein characterization, driving the steepest demand trajectory across all electron microscopy categories.
- Scanning Electron Microscopes:Surface imaging systems using focused electron beams with secondary electron detection dominate materials science laboratories and failure analysis workflows.
- Hybrid Electron Microscopes:Combined SEM-TEM architectures serve multi-modal research environments requiring both surface and transmission capabilities without duplicate capital outlays.
Scanning electron microscopes absorb the bulk of installed capacity; cryo-electron microscopes are expanding most quickly.
Application:
Application selection determines regulatory exposure, with semiconductor inspection facing export control classifications under the Wassenaar Arrangement.
- Semiconductor Inspection:Zero-defect tolerance at advanced process nodes demands sub-angstrom resolution with automated wafer handling. Intel, TSMC, and SK Hynix are replacing electron microscopy fleets faster than historical depreciation cycles as node shrinkage compresses inspection tolerances.
- Life Sciences:Structural biology, virology, and vaccine development workflows require cryogenic preservation and single-particle analysis capabilities. The NIH and Wellcome Trust are funding national cryo-EM facility networks rather than institutional ownership.
- Materials Science:Alloy characterization, catalyst morphology, and battery electrode analysis drive demand across automotive and energy storage supply chains.
- Nanotechnology:Graphene, quantum dot, and carbon nanotube research programs require high-resolution morphological mapping with elemental spectroscopy integration.
Semiconductor inspection commands premium pricing tiers; life sciences applications are gaining share fastest.
End User:
End-user type shapes procurement authority, with semiconductor manufacturers consolidating purchasing decisions at headquarters level while academic institutions delegate to department heads.
- Semiconductor Manufacturers:Fabs in Taiwan, South Korea, and the United States specify metrology-grade systems with ISO 17025 accreditation requirements that extend procurement cycles by six to eighteen months. The EU Chips Act is redirecting capital toward domestic fabrication facilities in Germany and France.
- Academic Research Institutions:Universities face EU Green Deal sustainability mandates for scientific instrumentation procurement, creating preference shifts toward energy-efficient system designs. Core facility consolidation is displacing department-level instruments at North American and European research universities.
- Pharmaceutical Companies:Therapeutic protein characterization pipelines embed single-particle analysis into drug discovery workflows, with specialist technician scarcity constraining operational expansion.
- Government Research Labs:National facilities in South Korea's KBSI and Taiwan's NCHC concentrate capital investment while expanding remote user access.
Semiconductor manufacturers deploy the highest-value installed base; pharmaceutical companies are accelerating procurement most rapidly.
Distribution Channel:
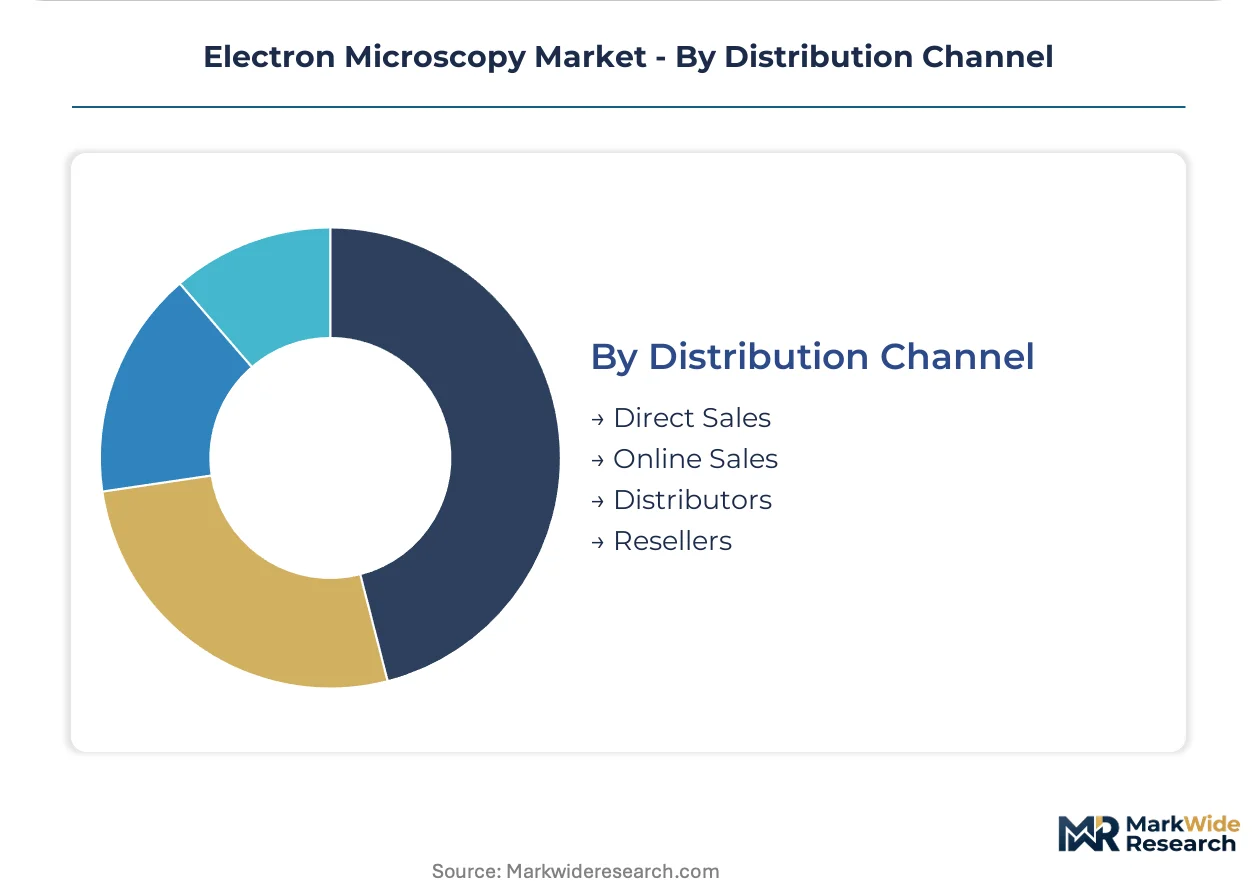
Channel selection correlates with system complexity, with direct sales dominating high-end configurations requiring installation engineering.
- Direct Sales:Manufacturers deploy field service engineers for vibration isolation, electromagnetic shielding, and vacuum system commissioning. Thermo Fisher Scientific and JEOL maintain captive sales organizations for transmission and cryo-electron microscopy platforms.
- Distributors:Regional partners handle scanning electron microscope placements in emerging markets with limited manufacturer presence.
- Resellers:Refurbished system brokers serve budget-constrained academic laboratories and small materials science departments.
- Online Sales:Consumables, spare parts, and entry-level desktop scanning systems migrate to digital procurement portals.
Direct sales capture the majority of primary system revenue; distributor networks are extending geographic coverage fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors the densest concentration of electron microscopy demand, with Taiwan Semiconductor Manufacturing operating inspection-grade fleets for sub-three-nanometer node validation. Sovereign semiconductor initiatives and pharmaceutical research investments are redrawing procurement geography across four distinct national markets.
United States
Intel and SK Hynix fabs in Arizona and Oregon are replacing electron microscopy systems faster than depreciation cycles as node shrinkage compresses tolerances. The FDA governs medical device characterization through Good Manufacturing Practice guidelines that shape pharmaceutical laboratory procurement. Boston and Cambridge academic cores are expanding cryo-electron microscopy capacity for therapeutic protein workflows.
Germany
Carl Zeiss and Leica Microsystems anchor precision optics manufacturing in Baden-Württemberg and Hesse, supplying metrology-grade columns for semiconductor inspection. The EU Green Deal is hardening sustainability requirements for scientific instrumentation procurement across academic research institutions. Fraunhofer Institutes in Dresden and Munich operate national facility networks that consolidate electron microscopy access through remote operation capabilities.
Japan
JEOL maintains integrated column production and proprietary electron source technology from its Akishima headquarters, serving materials science laboratories throughout Asia. METI coordinates national technology roadmaps that prioritize atomic-scale imaging capabilities for next-generation semiconductor research. Tsukuba Science City hosts concentrated government research labs with full-time cryo-EM specialist staffing.
South Korea
Samsung Foundry and SK Hynix fabs in Giheung and Icheon command premium pricing tiers for zero-defect inspection systems at advanced process nodes. The Korea Basic Science Institute operates the most visible national electron microscopy facility model, concentrating capital investment while expanding user access. Seoul National University and KAIST are embedding single-particle analysis into structural biology pipelines.
India
The Production Linked Incentive scheme for electronics manufacturing is attracting fab investments in Gujarat and Karnataka that will require metrology infrastructure. The Central Electricity Authority and Bureau of Indian Standards shape laboratory equipment procurement standards for research institutions. Indian Institute of Science in Bangalore and IIT Bombay are consolidating department-level instruments into core facilities with trained cryo-EM technicians.
Electron Microscopy Market Vendor Landscape
Premium-margin players sit above commodity-margin players across the resolution-performance spectrum, with superconducting source technology and integrated spectroscopy commanding price multiples over standard scanning configurations. The vendor base concentrates around three strategic archetypes: integrated column manufacturers with captive electron source production, spectroscopy-integrated platform specialists, and diversified life sciences conglomerates with cryogenic workflow anchoring. Dominant competitive moves include strategic partnerships for artificial intelligence embedding and geographic expansion through national facility network concessions.
Among diversified life sciences conglomerates, Thermo Fisher Scientific and Danaher occupy positions exemplifying the cryo-electron microscopy workflow anchoring archetype. JEOL represents the integrated column manufacturing archetype with proprietary electron source technology. These three companies illustrate how vendor strategy diverges between pharmaceutical laboratory embedding and semiconductor metrology-grade system supply.
| Leading Market Players |
|---|
| Carl Zeiss |
| Leica Microsystems |
| Thermo Fisher Scientific |
| Danaher |
| Oxford Instruments |
| JEOL |
| Bruker |
| AMETEK |
| Hitachi High-Tech |
| Others |
Supply Flow & Price Mechanics
Resolution-performance divergence between metrology-grade semiconductor inspection systems and standard academic configurations manifests in pricing multiples exceeding tenfold, with helium-cooled superconducting sources and ISO 17025 certification tiers anchoring value capture while supply chain concentration in Qatar and Algeria for cryogenic cooling inputs creates parallel procurement risk profiles.
Pricing Analysis
Yield-guarantee pricing anchors metrology-grade electron microscopy contracts, with semiconductor fabs in Taiwan and South Korea absorbing premium tiers tied to zero-defect throughput commitments. Price differentiation rests on resolution certification grade and after-sales service bundling rather than hardware alone. Cost compression in academic configurations is intensifying because EU Green Deal sustainability mandates favor energy-efficient system redesigns. Pharmaceutical laboratories show least price sensitivity due to therapeutic protein characterization workflow embedding, while Indian research institutions under PLI scheme constraints exhibit highest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with helium feedstock concentration in Qatar, Algeria, and Russia, where superconducting electron source cooling draws from geopolitically exposed extraction. Proprietary electron source technology and integrated electromagnetic lens arrays rest on Japanese and German precision optics manufacturing. Tariff exposure runs through Wassenaar Arrangement dual-use export classifications constraining cross-border system transfers. Distribution runs through direct sales with captive field service engineering for high-end configurations, while regional distributors handle scanning electron microscope placements in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electron microscopy procurement operates as a cost-of-compliance story, with ISO 17025 accreditation timelines creating six-to-eighteen-month barrier-to-entry moats that favor incumbents with established metrology-grade qualification protocols.
For Market Incumbents: Cement dominance in semiconductor inspection through captive helium supply agreements and backward integration into superconducting source technology, while defending against spectroscopy-integrated platform specialists by accelerating AI-embedded image reconstruction R&D. JEOL's integrated column production model offers a template for vertical control over electron source supply.
For New Entrants and Emerging Players: Begin with cryo-electron microscopy service contracts in India's consolidating core facility ecosystem, where PLI scheme fab investments outpace trained technician supply. Target pharmaceutical laboratories seeking outsourced single-particle analysis capacity as the most penetrable segment, leveraging remote operation capabilities as the primary go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with spectroscopy-integrated platform specialists given convergence of elemental analysis and nanoscale morphological mapping demand across materials science workflows. Long-term viability favors vendors with demonstrated AI embedding partnerships and national facility network concessions. Watch helium supply contract renegotiation cycles as the inflection signal for input cost volatility exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Helium Supply Contract Securement | Qatari and Algerian sourcing agreements insulate superconducting source production from geopolitical disruption. |
| AI-Embedded Image Reconstruction Partnership | Machine learning denoising algorithms compress pharmaceutical single-particle analysis timelines from days to hours. |
| National Facility Network Concession | South Korea's KBSI and Taiwan's NCHC models concentrate capital while expanding remote user access. |
| Cryogenic Workflow Certification Investment | ISO 17025 accreditation protocols extend procurement cycles and lock in metrology-grade vendor relationships. |
| Spectroscopy Platform Integration | Bruker's elemental analysis-nanoscale mapping convergence opens materials science and failure analysis workflows. |
Methodological Framework
Document review covered SEC filings from precision optics manufacturers, EU regulatory filings on F-Gas and REACH compliance, and semiconductor industry capex disclosures, complemented by interviews with electron microscopy core facility directors, fab metrology engineers, pharmaceutical structural biology leads, and vacuum system component procurement managers. Secondary sources included Wassenaar Arrangement dual-use technology classifications, ECHA restriction timelines, and national research facility annual reports. Bottom-up instrument shipment tracking and top-down end-user budget allocation surveys were triangulated against vendor revenue segment disclosures.
Historical shipment data cross-referenced against expert panel input on node shrinkage acceleration and cryo-EM adoption curves shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, application workflow, end-user procurement authority, and regional regulatory cluster. CAGRs were derived from instrument replacement cycle compression analysis and sovereign semiconductor initiative capital flow tracking. Helium supply contract renewal schedules and academic consortia formation timelines served as industry-specific forecast inputs.
Export control reclassification, helium supply disruption, and cryo-EM specialist training pipeline expansion are the dominant revision risks that could accelerate or delay vendor revenue recognition. Forecasts reflect documented assumptions on node transition timing and facility consolidation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Semiconductor CD-SEM Systems Market
Imaging
Visualiser Market
Imaging
Asia Pacific IP Camera Market
Imaging
Global High-Speed Digital Camera Market
Imaging
Handheld Backscatter X-Ray Devices Market
Imaging
Live Cell Imaging Market
Imaging
Camcorder Market
Imaging
Cinematographic Camera Market
Imaging
Virtual Reality Camera Market
Imaging
Machine Vision Camera Market
Imaging
Latin America Surveillance Analog Camera Market
Imaging
Digital X-Ray Technology Market
Imaging
Ingaas Image Sensor Market
Imaging
Contact Image Sensor Market
Imaging
Microwave Imaging Market
Imaging
Industrial Machine Vision Market