
 Hyperspectral Imaging Camera Market | 2026-2036
Hyperspectral Imaging Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperspectral Imaging Camera Market Foresight
Finland is narrowing its hyperspectral imaging supply chain through concentrated R&D investment and specialized component manufacturing. Specim Spectral Imaging Ltd leverages decades of spectral calibration expertise to dominate airborne and ground-based system deployments. Headwall Photonics Inc. sustains its position through in-house diffraction-grating production and precision optical assembly. Imec competes by advancing CMOS-integrated spectral sensor architectures that reduce form factors for drone and satellite platforms.
A hyperspectral imaging camera captures contiguous narrow spectral bands across ultraviolet through shortwave infrared wavelengths, typically achieving spectral resolutions of 5-10 nanometers to generate data cubes where each pixel contains a full spectral signature. This capability enables material identification, chemical composition mapping, and anomaly detection across industrial, environmental, and clinical workflows. Pushbroom technology leads installed volume due to its established reliability in airborne remote sensing and satellite payloads, while snapshot architectures represent the fastest-expanding segment as real-time industrial inspection and medical endoscopy applications demand frame-rate performance without scanning motion. Software and analytics layers command disproportionate margin pools as proprietary spectral unmixing algorithms and AI-trained classification models differentiate vendor offerings beyond hardware commoditization.
The European Space Agency's Earth observation programs and the EU Green Deal's environmental monitoring mandates shape procurement specifications for satellite-compatible hyperspectral payloads. FDA 510(k) pathways and ISO 13485 medical device quality standards govern clinical market entry for surgical and diagnostic camera systems. Stakeholders must monitor how REACH chemical compliance and emerging EU AI Act documentation requirements affect spectral database training and algorithm deployment across automated inspection platforms.
Market Dynamics
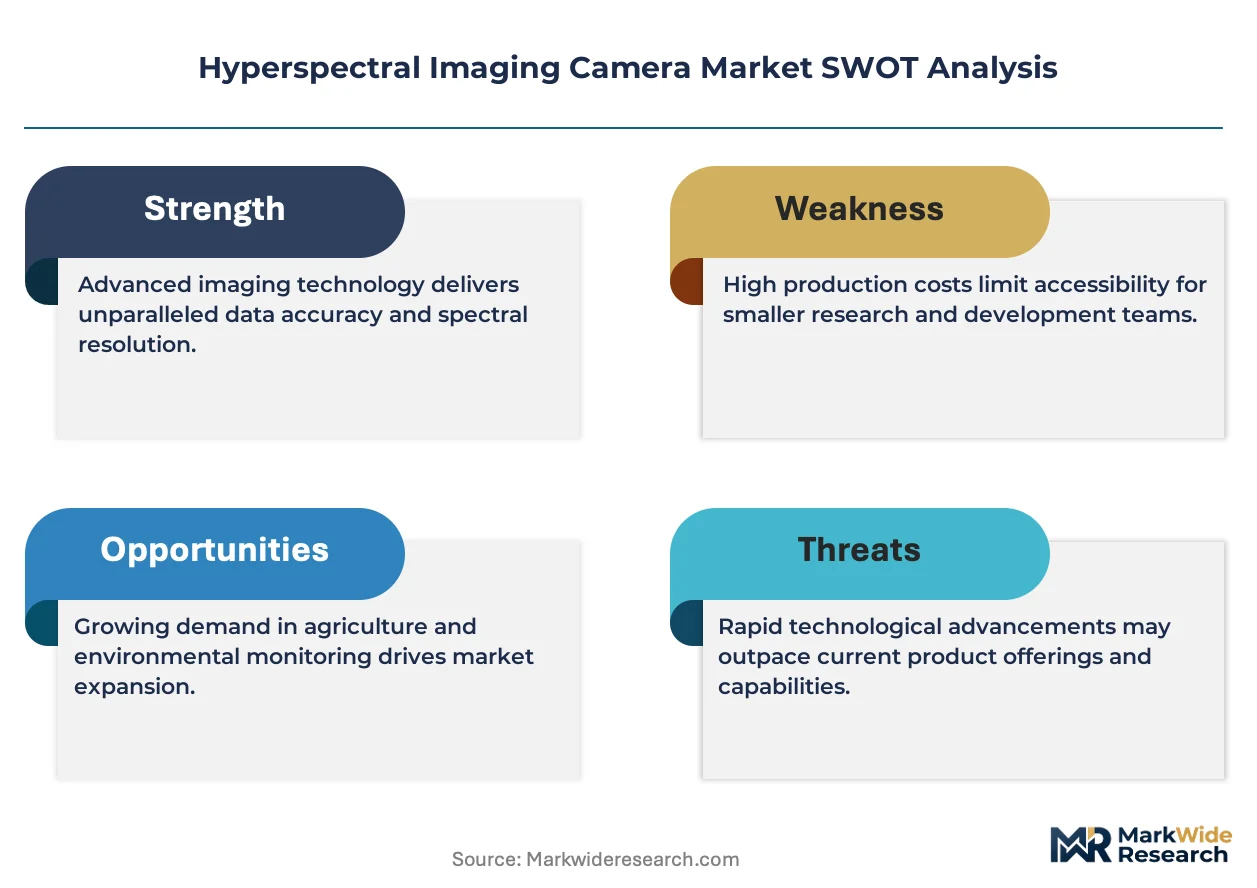
Software-defined spectral analytics is compressing hardware differentiation cycles, forcing camera vendors to embed AI inference engines directly at the sensor edge while optical component suppliers lose pricing power to algorithm licensors.
Growth Catalysts
- EU Green Deal environmental mandates:Satellite constellation operators must deploy hyperspectral payloads for carbon sequestration monitoring and agricultural compliance verification across member states.
- CMOS-integrated spectral sensors:Semiconductor foundries are converging photodetector arrays with thin-film spectral filters, collapsing form factors for drone-mounted agricultural scouts.
- American Midwest precision farming:Cooperative extension services are subsidizing variable-rate fertilizer systems that depend on airborne hyperspectral crop stress mapping.
Market Restraints
- Indium gallium arsenide detector shortages:Shortwave infrared focal plane arrays face captive supply constraints from defense-prioritized foundries in the United States.
- Calibration drift in airborne platforms:Atmospheric correction algorithms require ground truth validation that extends deployment timelines for commercial remote sensing operators.
- ISO 13485 certification costs:Medical device quality system implementation consumes eighteen to twenty-four months for surgical guidance camera developers.
Strategic Opportunities
- FDA 510(k) pathway acceleration:Pre-submission programs for real-time tissue classification systems are compressing regulatory review for oncology surgical suites.
- Industrial automation corridors in Germany:Automotive paint inspection lines are retrofitting snapshot hyperspectral units for defect detection at conveyor speeds.
- AI Act documentation requirements:Automated inspection platform vendors can capture premium positioning by pre-building spectral database provenance trails for EU deployment.
Industry Challenges
- Spectral unmixing algorithm talent scarcity:Machine learning engineers with domain expertise in chemometric modeling command compensation premiums that strain R&D budgets.
- Legacy vision system integration:Manufacturing quality teams face protocol translation complexity when embedding hyperspectral streams into existing PLC architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperspectral Imaging Camera Market |
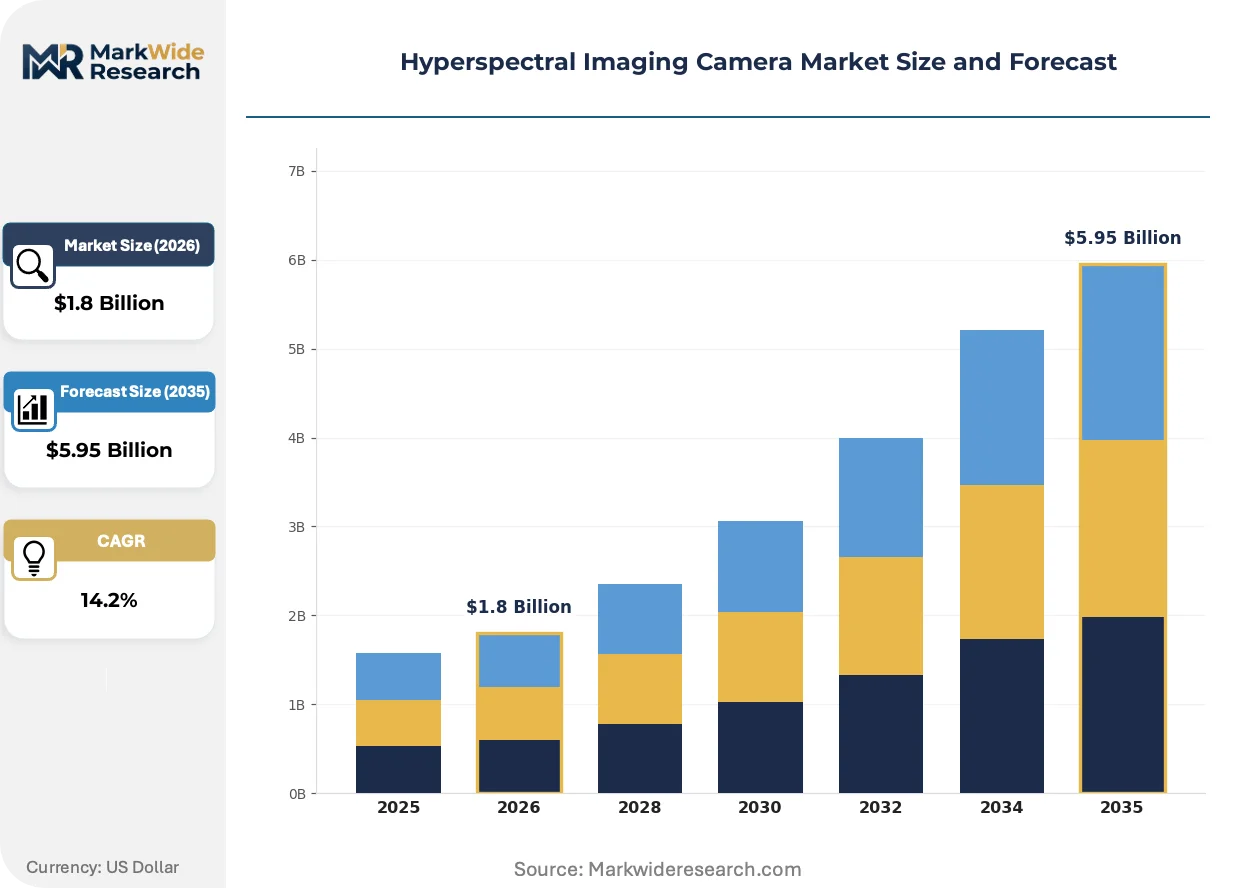
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Software, Sensors, Accessories Application: Agriculture, Environmental Monitoring, Defense, Healthcare End User: Research Institutions, Government Agencies, Industrial Sector, Educational Institutes Technology: Pushbroom, Whiskbroom, Snapshot, Hybrid |
| Companies Covered | Specim Spectral Imaging Ltd, Headwall Photonics Inc., Resonon Inc., Imec, BaySpec Inc., Corning Incorporated, Cubert GmbH, XIMEA GmbH, Norsk Elektro Optikk AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperspectral Imaging Camera Market Shifts & Advancements
Computational spectroscopy is dissolving the boundary between hardware capture and software interpretation, enabling real-time material classification without laboratory-grade reference instrumentation.
Snapshot mosaic filter arrays are digitizing industrial quality control by replacing mechanical scanning stages with single-frame spectral acquisition. Automotive coating inspectors at Stuttgart-area assembly plants are adopting these sensors for throughput rates exceeding sixty parts per minute. The technology is digitizing defect detection workflows that previously required offline laboratory analysis.
REACH chemical compliance is forcing spectral database curators to document training set provenance and eliminate restricted substance references from classification models. European environmental monitoring contractors must now validate that their vegetation indices exclude legacy pesticide spectral signatures. Satellite payload developers are responding by segregating EU-dedicated algorithm versions from export configurations.
After-sales service unbundling is fragmenting the vendor-customer relationship as hyperspectral camera buyers separately procure calibration contracts, software licenses, and predictive maintenance subscriptions. German industrial automation integrators now source hardware from Finnish specialists while contracting analytics from cloud-native software vendors. This pattern concentrates in Bavaria's machine vision cluster where procurement teams prioritize interoperability over single-source accountability.
Hyperspectral Imaging Camera Market Segmentation
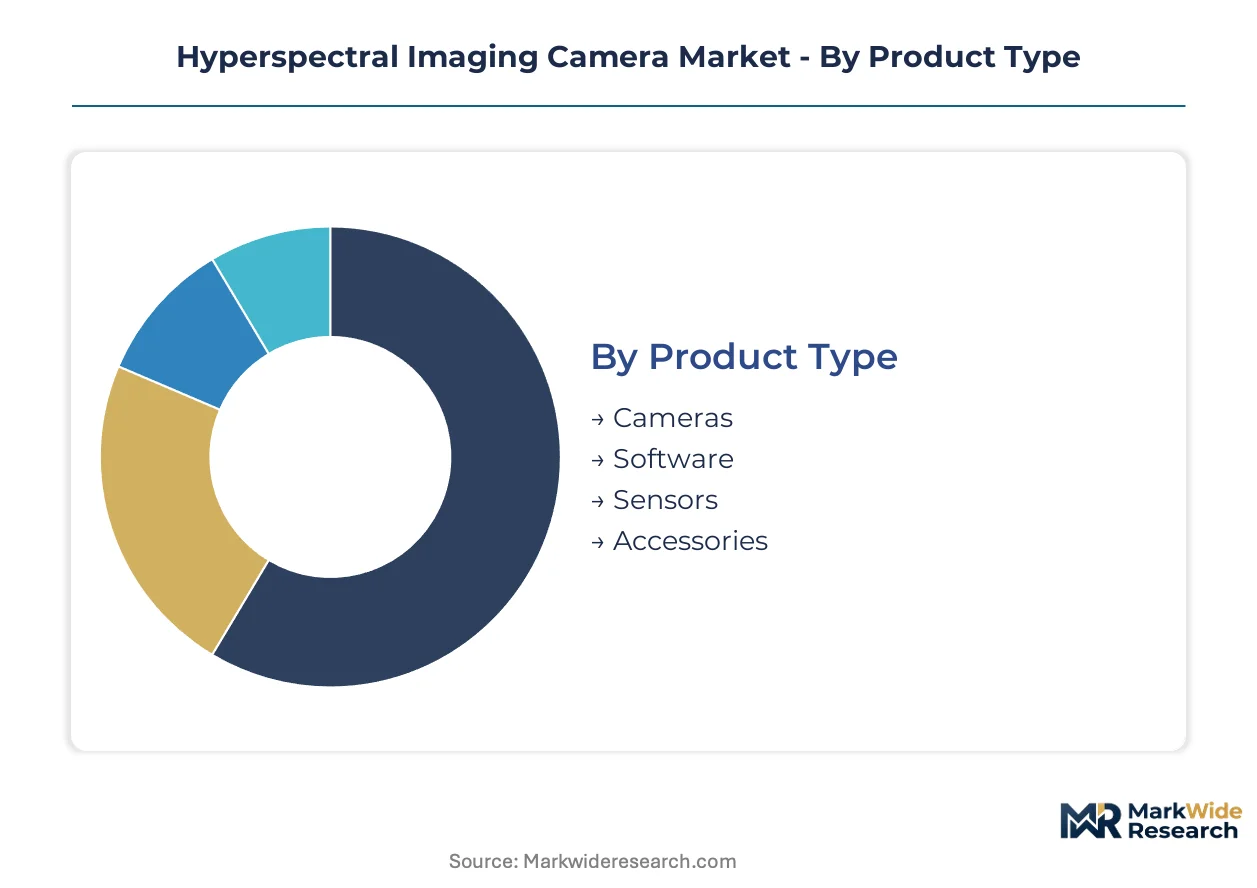
Hyperspectral imaging systems fragment across hardware, software, and service layers where margin capture shifts from optical components toward spectral analytics. Understanding these boundaries clarifies where procurement teams concentrate spending versus where vendors extract profitability.
Product Type:
Mature hardware categories face margin compression while emerging software layers capture expanding value pools.
- Cameras:Pushbroom and snapshot architectures dominate airborne and industrial deployments. German automotive paint inspection lines drive demand for snapshot units capable of sixty parts per minute throughput.
- Software:Proprietary spectral unmixing algorithms and AI-trained classification models differentiate vendor offerings beyond commoditized hardware. Cloud-native analytics vendors now contract separately from hardware suppliers in Bavaria's machine vision cluster.
- Sensors:CMOS-integrated spectral sensors collapse form factors for drone-mounted agricultural scouts.
- Accessories:Calibration targets, mounting systems, and thermal management components complete field-deployable packages.
Cameras retain volume leadership; software holds the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive satellite payloads from accessible ground-based systems.
- Agriculture:Variable-rate fertilizer systems in the American Midwest depend on airborne hyperspectral crop stress mapping. Cooperative extension services subsidize deployment, deepening penetration across precision farming operations.
- Environmental Monitoring:EU Green Deal mandates require satellite constellation operators to deploy hyperspectral payloads for carbon sequestration tracking. ESA Earth observation programs shape procurement specifications for compatible instruments.
- Defense:Shortwave infrared focal plane arrays face captive supply constraints from defense-prioritized foundries in the United States.
- Healthcare:FDA 510(k) pathways govern clinical market entry for surgical guidance systems requiring ISO 13485 quality certification.
Agriculture retains volume leadership; healthcare holds the steepest expansion curve.
End User:
Customer type determines procurement complexity and contract duration.
- Research Institutions:Academic laboratories prioritize spectral resolution and calibration flexibility over throughput metrics.
- Government Agencies:ESA and national space programs drive satellite payload specifications with multi-year procurement cycles.
- Industrial Sector:German automation corridors integrate hyperspectral streams into existing PLC architectures for quality control lines.
- Educational Institutes:Training and demonstration systems emphasize cost accessibility and curriculum alignment.
Industrial sector procurement is expanding most quickly; government agencies maintain the longest contract horizons.
Technology:
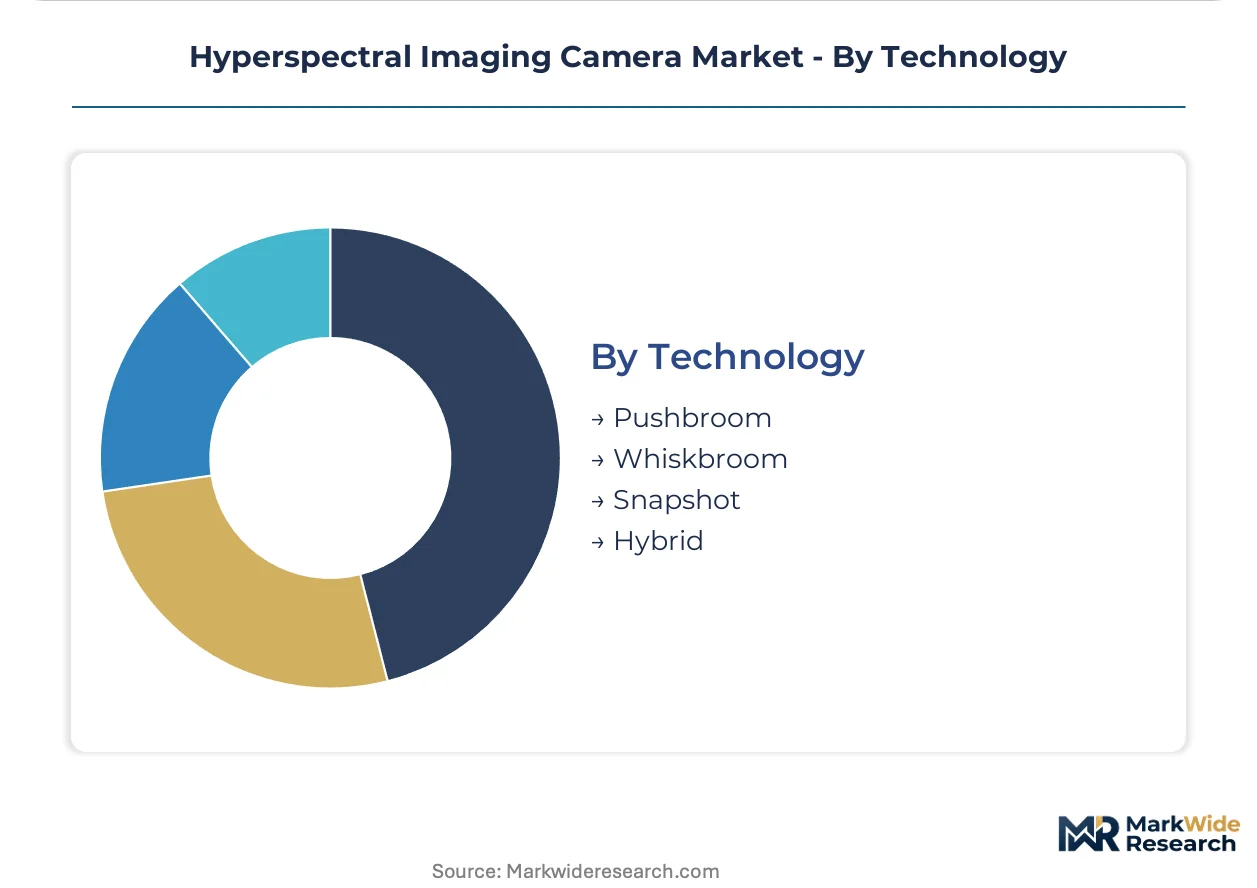
Volume concentration favors established scanning architectures while emerging snapshot designs gain share in time-critical applications.
- Pushbroom:Linear sensor arrays capture spectral data through platform motion. Airborne remote sensing and satellite payloads favor this architecture for its established reliability and calibration stability.
- Snapshot:Mosaic filter arrays enable single-frame spectral acquisition without mechanical scanning. Stuttgart-area automotive plants adopt these sensors for real-time coating inspection at conveyor speeds.
- Whiskbroom:Point-scanning systems collect individual pixel spectra sequentially, suited for laboratory and ground-based mapping.
- Hybrid:Combined architectures merge scanning coverage with snapshot speed for specialized industrial deployments.
Pushbroom retains volume leadership; snapshot gains share fastest in time-critical inspection workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperspectral imaging consumption patterns diverge sharply by geography: American Midwestern farmers deploy airborne systems for crop stress mapping while German automotive plants integrate snapshot cameras for real-time paint inspection, and satellite operators across Scandinavia prioritize environmental monitoring payloads for EU Green Deal compliance.
United States
The American Midwest dominates agricultural deployments through cooperative extension subsidies for variable-rate fertilizer systems. FDA 510(k) pathways accelerate clinical adoption for surgical guidance cameras requiring ISO 13485 certification. Defense-prioritized foundries in the United States face captive supply constraints for indium gallium arsenide shortwave infrared detectors.
Germany
Industrial automation corridors in Bavaria and Baden-Württemberg drive snapshot hyperspectral adoption for automotive coating inspection at sixty parts per minute. REACH chemical compliance mandates force spectral database curators to document training set provenance and eliminate restricted substance references. Stuttgart-area assembly plants retrofit conveyor lines with mosaic filter arrays for real-time defect detection.
Finland
Concentrated R&D investment and specialized component manufacturing narrow the national hyperspectral supply chain. ESA Earth observation programs shape procurement specifications for satellite-compatible payloads from Finnish vendors. Specim Spectral Imaging Ltd leverages decades of spectral calibration expertise to dominate airborne and ground-based system deployments from its Espoo headquarters.
Belgium
Imec advances CMOS-integrated spectral sensor architectures that collapse form factors for drone and satellite platforms from its Leuven research hub. EU AI Act documentation requirements push automated inspection platform vendors to pre-build spectral database provenance trails. Flemish photonics clusters coordinate thin-film filter integration with semiconductor foundry partners.
China
Domestic satellite constellation operators deploy hyperspectral payloads for agricultural compliance verification and carbon sequestration monitoring. MIIT standards govern spectral sensor integration into industrial quality control lines. Yangtze River Delta manufacturing hubs experiment with snapshot architectures for electronics inspection workflows.
Hyperspectral Imaging Camera Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. Specialized optical component manufacturers and spectral calibration houses command technical differentiation through proprietary grating production and thin-film filter expertise. Semiconductor foundries and cloud-native analytics vendors compete on scale and software-defined spectral unmixing. Three archetypes define positioning: vertically integrated hardware specialists, fabless sensor designers, and algorithm-centric software vendors. Competitive moves center on backward integration into diffraction-grating production and strategic partnerships between camera OEMs and AI inference engine licensors.
Among Nordic spectral imaging specialists, Specim Spectral Imaging Ltd and Norsk Elektro Optikk AS exemplify the vertically integrated hardware archetype with decades of airborne system deployment expertise. Resonon Inc. represents the American precision optics tier. Imec occupies a unique position bridging semiconductor research and commercial spectral sensor commercialization from its Belgian R&D base.
| Leading Market Players |
|---|
| Specim Spectral Imaging Ltd |
| Headwall Photonics Inc. |
| Resonon Inc. |
| Imec |
| BaySpec Inc. |
| Corning Incorporated |
| Cubert GmbH |
| XIMEA GmbH |
| Norsk Elektro Optikk AS |
| Others |
Supply & Pricing Matrix
The Rotterdam-Antwerp freight corridor channels optical component shipments from Belgian foundries to German automation clusters, where transport cost dynamics amplify pricing power for indium gallium arsenide detector suppliers while compressing margins for downstream camera assemblers serving price-sensitive agricultural cooperatives in the American Midwest.
Pricing Analysis
Long-term offtake contracts dominate satellite payload procurement, locking ESA program pricing eighteen to twenty-four months ahead of delivery, whereas industrial buyers in Stuttgart automotive plants negotiate spot purchases for snapshot cameras with sixty-day price exposure. Pricing stratifies across premium FDA-cleared surgical tiers, standard industrial inspection grades, and economy-level agricultural scouting units. Cost compression in the standard tier intensifies as CMOS-integrated sensors from Belgian semiconductor foundries displace discrete optical assemblies. Research institutions exhibit lowest price sensitivity due to grant-funded capital cycles, while Midwestern farming cooperatives pressure vendors on per-acre scanning economics.
Supply Chain Analysis
United States export controls on shortwave infrared focal plane arrays restrict indium gallium arsenide detector flows to defense-prioritized domestic foundries, forcing European camera vendors into dual-sourcing negotiations with Finnish and Belgian component specialists. Supply concentrates in Finland for diffraction-grating production, Belgium for CMOS spectral filter integration, and Germany for precision optical assembly. Raw material dependencies span rare-earth substrates for detector epitaxy, fused silica for grating substrates, and thin-film coating materials for filter arrays. Single-source vulnerability concentrates in United States defense-captive InGaAs foundries. Distribution runs through Bavarian machine vision integrators who unbundle hardware procurement from software licensing and calibration service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multispectral imaging systems threaten hyperspectral camera incumbents in agricultural monitoring applications where reduced spectral resolution satisfies crop health mapping requirements at lower cost points, forcing established vendors to defend substitution risk through performance differentiation and software lock-in.
For Market Incumbents: Insulate core revenue streams by embedding proprietary spectral unmixing algorithms into subscription analytics layers that agricultural cooperatives cannot easily port to lower-cost multispectral alternatives. Pursue backward integration into diffraction-grating production to reduce dependency on Headwall Photonics for critical optical components. Accelerate FDA 510(k) pathway investments for surgical guidance systems where regulatory moats deter multispectral competitors from clinical entry. For New Entrants and Emerging Players: Mid-tier environmental monitoring contractors in Scandinavia represent the most penetrable entry point, as EU Green Deal mandates expand payload demand faster than Specim and Norsk Elektro Optikk can scale production capacity. Snapshot camera architectures for electronics inspection in China's Yangtze River Delta manufacturing hubs offer second-mover advantage as domestic MIIT standards mature. Lead with cloud-native analytics pricing that decouples software costs from hardware capital expenditure, matching procurement patterns emerging in Bavaria's unbundled sourcing environment. For Investors and Strategic Acquirers: Fabless spectral sensor designers with proven CMOS integration capabilities and existing foundry relationships present the most defensible acquisition profile for five-to-ten-year horizon positioning. These assets command scarcity premium as semiconductor foundry capacity constraints persist. Monitor ESA Earth observation program procurement acceleration as inflection indicator for satellite payload demand inflection that would lift valuations across Nordic hardware specialists.| Strategic Initiative | Industry Significance |
|---|---|
| AI Inference Engine Integration | Edge-computing spectral classification enables real-time industrial inspection without cloud latency. |
| REACH-Compliant Database Curation | Provenance documentation satisfies EU chemical compliance mandates for automated inspection platforms. |
| FDA Pre-Submission Program Engagement | Accelerated 510(k) review compresses time-to-revenue for oncology surgical guidance systems. |
| Foundry Partnership for InGaAs Supply | Captive detector access insulates against United States defense-prioritization supply constraints. |
| Cloud-Native Analytics Unbundling | Separate software licensing matches procurement patterns in Bavaria's machine vision cluster. |
Research Methodology
Desk research of ESA procurement databases, FDA 510(k) filing records, and EU Green Deal implementation reports preceded structured interviews with biomedical engineers at German university hospitals, precision agriculture specialists at Midwestern cooperative extension services, and procurement managers at Stuttgart-area automotive assembly plants. Secondary validation drew from ISO 13485 certification body disclosures, REACH compliance documentation from spectral database vendors, and customs data tracking optical component trade flows through the Rotterdam-Antwerp corridor. Bottom-up segment sizing triangulated against top-down satellite payload budget allocations and industrial automation capital expenditure surveys.
Assumptions held fixed include ESA Earth observation program funding levels, FDA regulatory pathway timelines, and United States export control classifications for shortwave infrared detectors; variables tested included EU AI Act documentation requirement enforcement intensity and indium gallium arsenide foundry capacity allocation shifts. The analytical framework modeled camera hardware, software, and service revenue streams across pushbroom and snapshot technology architectures, agriculture and healthcare application verticals, and research institution versus industrial end-user procurement patterns. CAGRs derived from segment-level growth rate convergence analysis incorporating CMOS sensor adoption curves and airborne platform deployment timelines.
Practitioners should monitor ESA budget appropriations, FDA pre-submission program queue lengths, and United States Commerce Department export control list revisions for early signals of demand or supply disruption. Forecasts reflect assumptions regarding continued EU Green Deal environmental monitoring mandate enforcement and stable semiconductor foundry capacity allocation to spectral sensor production. Material shifts in United States InGaAs detector export licensing policy or ESA procurement suspension would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Electron Microscopy Market
Imaging
Specific Imaging Solution Market
Imaging
Global CMOS Image Sensors Market
Imaging
TDI Camera Market
Imaging
Brain Imaging and Neuroimaging Market
Imaging
Image Signal Processor and Vision Processor Market
Imaging
Global Pathology Imaging Systems Market
Imaging
Medical X-Ray Detectors Market
Imaging
Micro Computed Tomography Market
Imaging
PET Scanners Market
Imaging
Facial Recognition Machine Market
Imaging
Global 3D Camera Market
Imaging
Computer Aided Detection Market
Imaging
Thermal Imaging Riflescope for Hunting Market
Imaging
Automotive 3D Imaging Market
Imaging
Phosphor Screen Scanner Market