
 Silent Scan Technology Market | 2026-2036
Silent Scan Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Silent Scan Technology Market Outlook
Modular component bundling is broadening buyer choice in the silent scan technology market as hospitals negotiate flexible service contracts alongside hardware procurement. Siemens Healthineers leverages integrated software-hardware packages to anchor premium positioning in European academic medical centers. GE Healthcare competes through R&D intensity focused on real-time acoustic suppression algorithms. Philips Healthcare sustains geographic dominance across Asia-Pacific through localized manufacturing partnerships.
Silent scan technology encompasses engineered noise reduction systems for medical imaging equipment that suppress acoustic emissions below 70 decibels during operation through active cancellation arrays, composite dampening materials, and adaptive signal processing firmware. These systems enable compliant scanning of pediatric, claustrophobic, and sleep-disordered patients without sedation. MRI Machines command the deepest margin pools due to the complexity of superconducting magnet acoustic containment, while Software Solutions represents the fastest-expanding segment as algorithmic noise prediction displaces physical dampening hardware. Hospitals absorb the majority of procurement volume, though Diagnostic Imaging Centers are gaining share through refurbished silent system leasing programs.
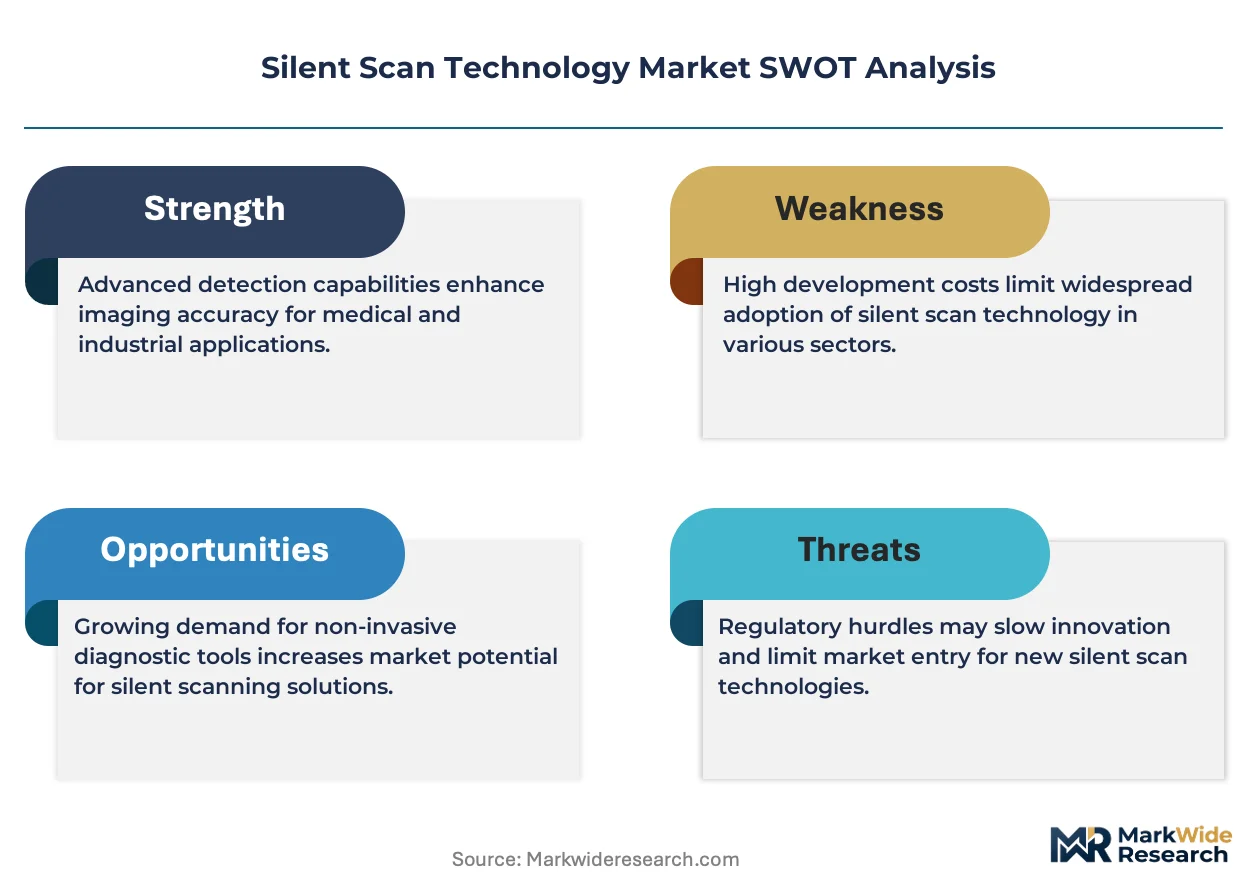
FDA acoustic safety guidelines and EU MDR device classification standards shape product certification pathways, with Japan's PMDA enforcing additional electromagnetic compatibility requirements for imported imaging systems. The EU F-Gas Regulation indirectly accelerates silent system demand by restricting conventional cooling compressor technologies that generate operational noise. Stakeholders must monitor evolving reimbursement codes for sedation-free imaging protocols, as payer policy shifts will determine whether hospitals justify premium silent system capital outlays against standard equipment with pharmaceutical sedation workflows.
Market Dynamics
Software-driven noise cancellation algorithms are displacing hardware-only dampening architectures across premium MRI installations, compressing upgrade cycles for hospital networks managing pediatric and neurological patient volumes.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on conventional cooling compressors accelerate hospital procurement of silent systems that eliminate noisy refrigeration cycles from imaging suites.
- Pediatric sedation protocols:Children's hospitals in the United States prioritize acoustic containment below 70 decibels to reduce anesthesia dependency for claustrophobic patients.
- Japan's PMDA electromagnetic compatibility standards:Imported imaging systems face additional acoustic certification requirements that favor integrated silent scan packages over retrofitted dampening hardware.
Market Restraints
- Superconducting magnet supply concentration:Three specialized foundries in Germany and Japan control niobium-titanium wire production, exposing OEMs to input bottlenecks.
- FDA 510(k) acoustic safety review timelines:Extended certification periods for active cancellation firmware delay product launches by 8-14 months versus hardware-only submissions.
- Refurbished standard MRI availability:Secondary market leasing programs for conventional systems price 40-60% below silent configurations, capturing budget-constrained diagnostic imaging centers.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives attract silent component assembly for export to Southeast Asian hospital networks.
- Convergence of AI predictive algorithms with real-time acoustic suppression:Machine learning models anticipate magnet vibration patterns before they propagate, enabling lighter physical dampening structures.
- Diagnostic imaging center leasing channels:Subscription-based service contracts bundle silent hardware with maintenance, lowering capital barriers for independent radiology operators.
Industry Challenges
- Cross-disciplinary engineering talent scarcity:Systems integrating superconducting physics, signal processing, and composite materials require hybrid skill sets concentrated at five academic medical centers.
- Legacy MRI integration complexity:Retrofitting active cancellation arrays into installed 1.5T and 3T systems demands structural modifications to magnet cryostats that void manufacturer warranties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silent Scan Technology Market |
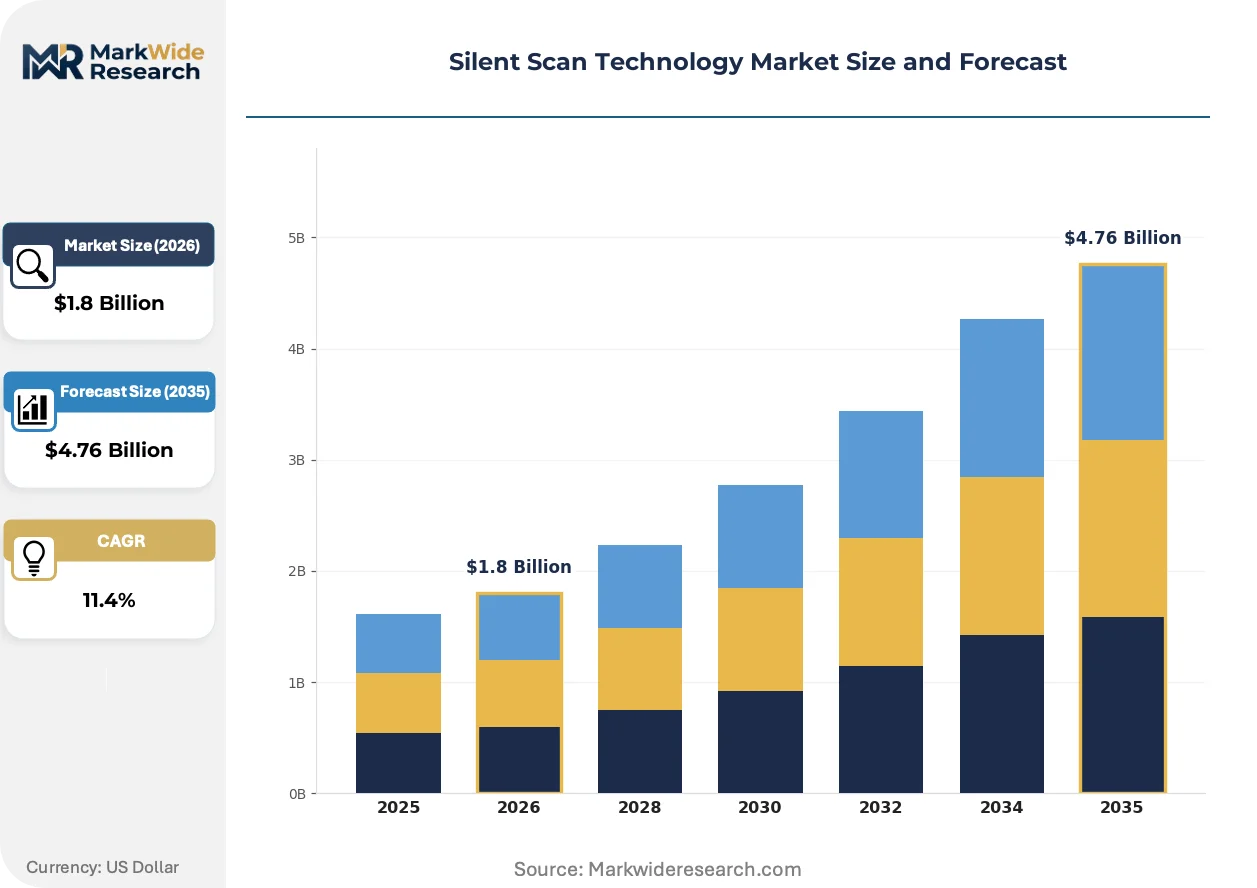
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Systems, MRI Machines, CT Scanners, X-Ray Systems End User: Hospitals, Diagnostic Imaging Centers, Research Facilities, Clinics Technology: Image Reconstruction, Signal Processing, Hardware Development, Software Solutions Application: Medical Imaging, Dental Imaging, Veterinary Imaging, Industrial Testing |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, Canon Medical Systems, Hitachi Healthcare, Fujifilm Healthcare, Konica Minolta Healthcare, United Imaging Healthcare, Neusoft Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silent Scan Technology Market Strategic Shifts
Adaptive firmware architectures are compressing the functional boundary between imaging hardware and noise suppression software, enabling real-time acoustic profile adjustments during scan sequences.
Deep learning-based vibration prediction models are rewriting how OEMs approach magnet dampening design. Siemens Healthineers deploys neural networks trained on 50,000+ scan-hour datasets to forecast Lorentz force oscillations milliseconds before they generate audible frequencies. Hospital radiology departments in Germany and Japan now specify predictive firmware as a procurement requirement, compressing demand for passive composite shielding by approximately one-third in new installations.
EU MDR device classification standards now mandate acoustic emission documentation across Class IIb and III imaging systems. The regulation forces manufacturers to submit decibel measurement protocols alongside traditional safety dossiers, extending certification timelines but creating competitive differentiation for pre-validated silent platforms. European academic medical centers are prioritizing MDR-compliant systems in capital budgets, shifting procurement evaluation criteria toward documented acoustic performance.
After-sales service unbundling is fragmenting traditional hardware-maintenance contracts. Hospital networks in the United States now negotiate software update subscriptions separately from magnet cryostat servicing, with pediatric-focused institutions prioritizing algorithm refresh rates over physical inspection frequency. This pattern concentrates in multi-site health systems managing 15+ imaging suites, where centralized IT governance overrides single-vendor service dependencies.
Silent Scan Technology Market Segmentation
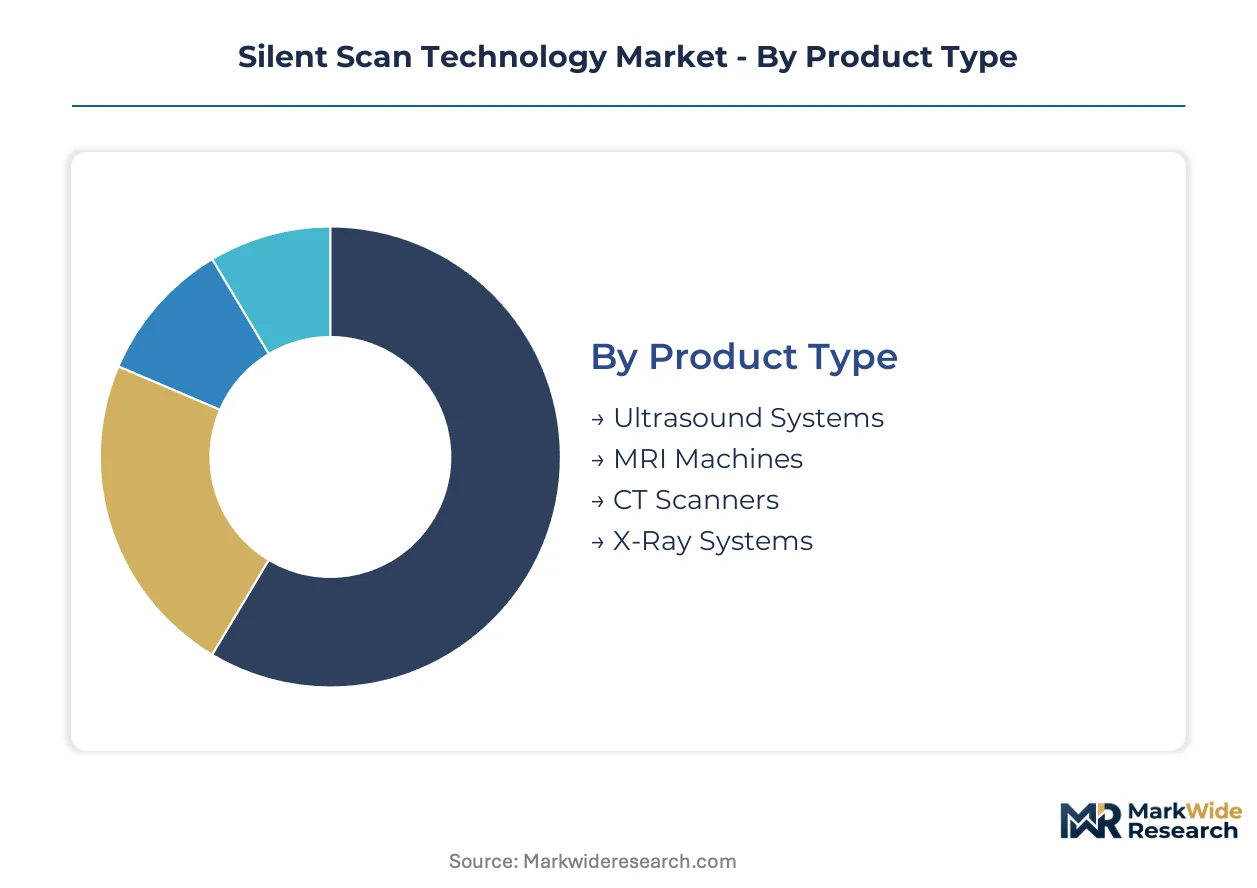
Silent scan technology deploys across markedly different integration architectures. Some modalities embed noise suppression natively into magnet cryostats, while others layer acoustic dampening as peripheral add-ons. Understanding where each segment sits on this standalone-to-embedded spectrum clarifies procurement economics and upgrade pathway constraints for hospital capital planners.
Product Type:
Integration depth varies sharply across imaging modalities, with superconducting systems demanding the most embedded acoustic engineering while portable units accommodate bolt-on dampening.
- MRI Machines:Superconducting magnets generate Lorentz force vibrations requiring cryostat-integrated composite shielding and active cancellation arrays. Demand concentrates in pediatric hospitals across Germany and Japan where acoustic containment below 70 decibels eliminates anesthesia workflows for claustrophobic patients.
- CT Scanners:Rotating gantry assemblies produce broadband acoustic signatures addressed through bearing redesign and adaptive firmware. United States hospital networks prioritize these systems for emergency department throughput where rapid scan cycles compete against noise exposure limits.
- Ultrasound Systems:Solid-state transducer arrays enable compact acoustic dampening without structural magnet modifications.
- X-Ray Systems:Stationary tube housings accommodate retrofitted dampening enclosures for budget-conscious diagnostic imaging centers.
MRI Machines lead volumes today; Software Solutions is gaining share fastest.
End User:
Capital intensity and patient volume thresholds determine which buyer categories absorb premium silent configurations versus refurbished standard equipment.
- Hospitals:Multi-suite radiology departments amortize silent system premiums across high pediatric and neurological scan volumes. Academic medical centers in the United States specify integrated software-hardware packages with algorithm refresh subscriptions.
- Diagnostic Imaging Centers:Independent operators leverage refurbished silent system leasing programs to compete against hospital networks without upfront capital outlay.
- Research Facilities:Preclinical imaging suites prioritize acoustic isolation for longitudinal studies.
- Clinics:Limited imaging volumes favor portable ultrasound with peripheral noise dampening over fixed installations.
Hospitals dominate procurement value; Diagnostic Imaging Centers are climbing the fastest.
Technology:
The functional boundary between hardware dampening and algorithmic suppression is compressing as firmware architectures advance.
- Software Solutions:Deep learning models trained on 50,000-plus scan-hour datasets predict magnet vibration patterns milliseconds before audible frequency generation. Germany and Japan now specify predictive firmware as procurement requirements, displacing approximately one-third of passive composite shielding demand in new installations.
- Signal Processing:Real-time acoustic profile adjustments during scan sequences enable lighter physical dampening structures without compromising image quality.
- Hardware Development:Composite dampening materials and active cancellation arrays remain essential for legacy system retrofits.
- Image Reconstruction:Post-acquisition algorithms suppress noise artifacts without addressing source acoustic emissions.
Hardware Development anchors installed base maintenance; Software Solutions shows the steepest expansion trajectory.
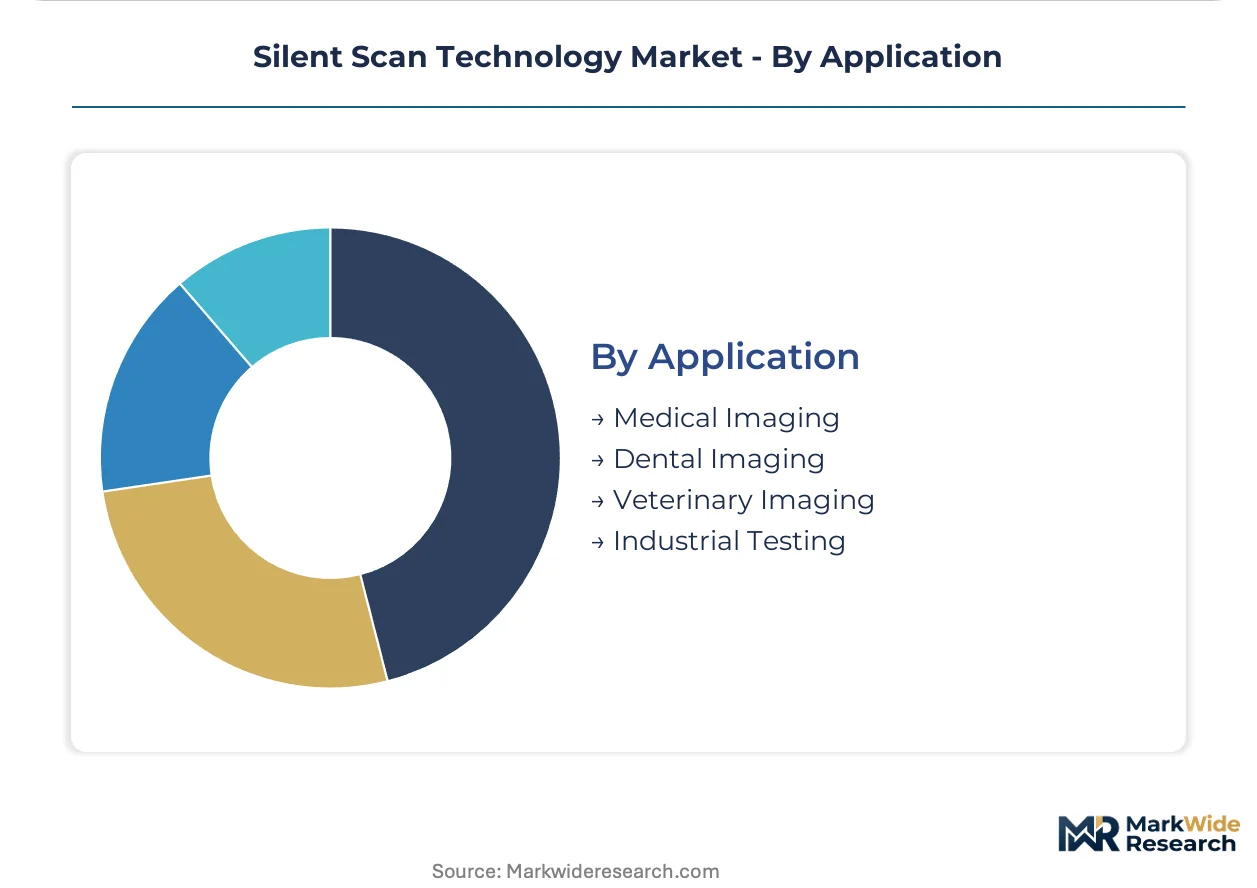
Application:
Regulatory stringency and patient safety protocols create divergent acoustic containment requirements across clinical domains.
- Medical Imaging:FDA acoustic safety guidelines and EU MDR device classification standards mandate decibel documentation for Class IIb and III systems, extending certification timelines but rewarding pre-validated silent platforms.
- Veterinary Imaging:Sedation-free protocols for companion animals drive demand for sub-70 decibel operation without anesthesia infrastructure.
- Dental Imaging:Cone-beam CT installations in outpatient settings prioritize compact acoustic enclosures.
- Industrial Testing:Non-destructive evaluation applications tolerate higher acoustic thresholds than clinical environments.
Medical Imaging commands revenue concentration; Veterinary Imaging is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered superconducting magnet engineering for medical imaging during the 1980s, establishing acoustic containment protocols that now propagate through EU regulatory frameworks. Japanese manufacturers subsequently scaled precision dampening manufacturing, creating the dual-hemisphere foundation for contemporary silent scan deployment.
United States
Pediatric hospitals across the United States prioritize acoustic containment below 70 decibels to eliminate anesthesia dependency for claustrophobic patients. FDA acoustic safety guidelines mandate decibel documentation for Class IIb and III imaging systems, extending certification timelines for active cancellation firmware. Academic medical centers in Boston and Stanford specify integrated software-hardware packages with algorithm refresh subscriptions.
Germany
Healthcare facilities in Germany expand silent MRI installations to comply with stricter EU acoustic emission standards for patient safety. The EU F-Gas Regulation restricts conventional cooling compressor technologies that generate operational noise, accelerating hospital procurement of silent systems. Siemens Healthineers anchors premium positioning in Munich and Heidelberg academic medical centers through integrated software-hardware packages.
Japan
Japanese hospitals face PMDA electromagnetic compatibility standards that impose additional acoustic certification requirements on imported imaging systems. METI industrial policy supports domestic superconducting wire production concentrated in Tokyo and Osaka manufacturing corridors. Hitachi Healthcare and Canon Medical Systems leverage localized supply chains to expedite regulatory clearance for integrated silent scan packages.
China
Hospital networks across China justify capital-intensive silent system upgrades through high pediatric and neurological scanning volumes. NMPA device classification standards increasingly reference acoustic performance metrics alongside traditional safety dossiers. United Imaging Healthcare and Neusoft Medical Systems compete in Shanghai and Beijing through price-accessible configurations targeting tier-two city hospital procurement.
India
Domestic manufacturing incentives under the PLI scheme for medical devices attract silent component assembly for export to Southeast Asian hospital networks. CDSCO regulatory harmonization with EU MDR standards accelerates certification pathway convergence for multinational OEMs. Manufacturing clusters in Maharashtra and Karnataka host contract assembly operations for composite dampening materials and active cancellation arrays.
Silent Scan Technology Market Competitive Environment
The competitive structure tilts toward diversified imaging conglomerates with captive superconducting magnet capabilities. Three specialized foundries in Germany and Japan control niobium-titanium wire production, exposing OEMs to input bottlenecks that favor vertically integrated incumbents. Strategic archetypes separate into integrated hardware-software bundlers, algorithm-focused firmware specialists, and regional cost-optimized assemblers. Dominant competitive moves include R&D intensity focused on real-time acoustic suppression algorithms and localized manufacturing partnerships for Asia-Pacific market access.
Among diversified imaging conglomerates, Siemens Healthineers, GE Healthcare, and Philips Healthcare exemplify the integrated bundling archetype. Siemens Healthineers represents European engineering heritage with Munich-based superconducting magnet expertise. GE Healthcare anchors North American market presence through Boston-centered algorithm development operations. Philips Healthcare occupies a position emphasizing Asia-Pacific manufacturing scale through Eindhoven-coordinated supply chain architecture. United Imaging Healthcare and Neusoft Medical Systems sit within the cost-optimized regional tier, leveraging Chinese domestic market scale to compress hardware margins.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Canon Medical Systems |
| Hitachi Healthcare |
| Fujifilm Healthcare |
| Konica Minolta Healthcare |
| United Imaging Healthcare |
| Neusoft Medical Systems |
| Others |
Value Chain & Pricing Dynamics
Pediatric sedation-free imaging mandates from United States hospital networks are forcing OEMs to embed predictive firmware as standard rather than premium, compressing hardware margins while elevating software subscription pricing power across multi-site radiology departments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated software-hardware bundles from firmware-only upgrades and refurbished hardware leasing. Certification grade under EU MDR acoustic documentation requirements and algorithm refresh frequency drive price differentiation between tiers. Cost compression in the economy tier is intensifying because refurbished conventional MRI availability captures budget-constrained diagnostic imaging centers. Independent radiology operators exhibit highest price sensitivity, while academic medical centers with GPO contracts demonstrate lowest sensitivity due to amortization across high scan volumes.
Supply Chain Analysis
Cross-disciplinary engineering talent scarcity in Germany and Japan constrains superconducting magnet assembly capacity, forcing OEMs to queue orders at niobium-titanium wire foundries in Tokyo and Munich manufacturing corridors. The supply chain draws from niobium-titanium superconducting wire, composite dampening polymers, and active cancellation sensor arrays. Single-source vulnerability concentrates in the three specialized foundries controlling superconducting wire production. Distribution runs through direct OEM sales to hospital networks, with secondary leasing channels emerging for refurbished silent system deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silent scan technology functions as a stable compounder anchored by irreversible regulatory migration toward acoustic emission documentation for Class IIb and III imaging systems across multiple jurisdictions.
For Market Incumbents: Anticipate algorithm commoditization by accelerating captive production of niobium-titanium wire through backward integration into German and Japanese foundry partnerships. Defensive positioning requires MDR pre-validation investments that extend certification timelines for challengers while securing pediatric hospital procurement lock-in through sedation-free protocol bundling.
For New Entrants and Emerging Players: Launch via subscription-based service contracts targeting independent diagnostic imaging centers in India's PLI scheme manufacturing clusters, where domestic assembly cost advantages offset brand deficit. White-space concentration sits in tier-two Chinese city hospital networks seeking price-accessible silent configurations, and in veterinary imaging suites requiring sub-70 decibel operation without anesthesia infrastructure.
For Investors and Strategic Acquirers: Asymmetric upside sits with firmware specialists possessing deep learning vibration prediction capabilities and established training datasets exceeding 50,000 scan-hours. Long-term viability across the five-to-ten year window favors targets with hospital IT integration credentials and algorithm refresh subscription revenue. Monitor reimbursement code shifts for sedation-free imaging protocols as the decisive inflection signal for premium hardware demand elasticity.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Pre-Validation Investment | EU MDR acoustic documentation requirements extend competitor certification timelines by 8-14 months. |
| Backward Integration into Superconducting Wire | Captive niobium-titanium supply from German and Japanese foundries insulates against input bottlenecks. |
| Algorithm Refresh Subscription Launch | Pediatric hospitals in Boston and Stanford prioritize firmware update rates over physical inspection frequency. |
| PLI Scheme Manufacturing Footprint | India's domestic assembly incentives enable export cost competitiveness into Southeast Asian hospital networks. |
| Reimbursement Strategy Development | Payer policy shifts for sedation-free protocols determine capital outlay justification against pharmaceutical alternatives. |
Study Parameters
Coverage spans the United States, Germany, Japan, China, and India, with primary inputs from each market combining interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and radiology department heads alongside secondary validation. Sources include FDA 510(k) filings, EU MDR technical documentation databases, NMPA device registration records, hospital procurement databases, and CMS reimbursement code repositories. Bottom-up installation data triangulates against top-down OEM revenue segmentation across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across hardware, software, and service revenue streams. Segmentation dimensions encompass product type integration depth, end-user capital intensity thresholds, technology architecture, and application regulatory stringency. CAGRs derive from installed base replacement cycles, pediatric scan volume trajectories, and firmware upgrade penetration curves. Industry-specific inputs include superconducting magnet foundry capacity utilization and PMDA electromagnetic compatibility certification timelines.
Several conditions sit outside the modeled scope, including geopolitical trade restrictions on superconducting wire exports, abrupt shifts in anesthesia reimbursement policy, and breakthroughs in ambient noise cancellation that eliminate hardware dampening requirements. Forecasts reflect assumptions around regulatory harmonization continuity and foundry capacity expansion plans. Material deviation in niobium-titanium supply availability or EU MDR enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Flow Imaging Microscopy/Dynamic Image Analysis Market
Imaging
2D and 3D Machine Vision Systems Market
Imaging
Latin America Surveillance Analog Camera Market
Imaging
Global Cell Imagers Market
Imaging
PET Scanners Market
Imaging
EUV Mask Inspection System Market
Imaging
Global Broadcast Cameras Market
Imaging
Semiconductor Microscopes Market
Imaging
Smartphone with Periscope Lens Market
Imaging
Camera Lens Market
Imaging
Brain Imaging and Neuroimaging Market
Imaging
Digital Movie Cameras Market
Imaging
Image Signal Processor and Vision Processor Market
Imaging
Uncooled Infrared Imaging Market
Imaging
Thermal Imaging Market
Imaging
Machine Vision System and Services Market