
 Thermal Imaging Camera Market | 2026-2036
Thermal Imaging Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Imaging Camera Market Intelligence
Modular sensor packaging is expanding buyer choice across the thermal imaging camera landscape, as manufacturers unbundle detector cores from complete camera housings and offer OEM-integrable modules. Teledyne FLIR leverages its vertical integration across detector fabrication and system assembly to sustain pricing flexibility across both module and finished-product tiers. Jenoptik AG anchors its position through specialized LWIR core production for European industrial automation customers. Seek Thermal competes aggressively in the smartphone accessory segment, where compact uncooled vanadium oxide microbolometers dominate cost-sensitive applications.
A thermal imaging camera detects infrared radiation emitted by objects and converts it into visible images using uncooled or cooled detector arrays, typically operating across spectral bands from 7-14 micrometers for long-wave infrared detection. These systems enable non-contact temperature measurement, night vision, and anomaly detection in environments where visible-light imaging fails. Handheld cameras occupy the largest volume tier, serving electrical inspection and building diagnostics where portability outweighs continuous monitoring needs, while robotic systems represent the fastest-expanding configuration as autonomous patrol and drone-mounted inspection programs proliferate. LWIR technology leads unit shipments due to lower cost and maintenance requirements, though MWIR retains critical applications in military targeting and gas leak detection where atmospheric transmission and spectral resolution demands justify cooled indium antimonide or mercury cadmium telluride architectures.
CE marking under the EU Machinery Directive and FDA 510(k) clearance pathways for clinical fever-screening applications shape product development priorities and market access timelines for camera manufacturers. The EU AI Act imposes additional conformity obligations on thermal systems with embedded analytics for automated threat detection or biometric inference, while REACH and RoHS constraints affect detector material selection and supply chain qualification. Stakeholders must monitor evolving cybersecurity certification requirements for networked thermal sensors, as IT-OT convergence exposes industrial deployments to new vulnerability classes that insurance underwriters and facility operators are beginning to price into procurement decisions.
Market Dynamics
Firefighting departments across industrialized economies are accelerating helmet-mounted thermal unit procurement, while factory automation programs in Germany compress deployment cycles for predictive maintenance systems. This dual demand pull is restructuring supplier priorities toward ruggedized, sensor-integrated platforms.
Growth Catalysts
- EU AI Act compliance pathways:The EU AI Act imposes conformity obligations on thermal systems with embedded analytics for automated threat detection, creating certified-product premiums for compliant manufacturers.
- Predictive maintenance adoption:German factory automation programs are accelerating infrared camera deployment for equipment monitoring, displacing scheduled downtime with condition-based intervention.
- Vanadium oxide microbolometer maturation:Uncooled detector architectures are reducing unit costs for smartphone-accessible thermal modules, expanding addressable consumer and prosumer segments.
Market Restraints
- Mercury cadmium telluride supply concentration:Cooled MWIR detector materials depend on limited specialty chemical suppliers, exposing military and gas detection segments to input volatility.
- REACH substance restrictions:The European Chemicals Agency constraints on detector materials complicate supply chain qualification for manufacturers serving EU industrial customers.
- Visible-light AI substitution:Low-light CMOS sensors with computational enhancement are capturing price-sensitive security applications that thermal historically dominated.
Strategic Opportunities
- Drone-mounted inspection expansion:Autonomous patrol programs for infrastructure and agriculture are creating demand for miniaturized, gimbal-stabilized thermal payloads with real-time telemetry.
- CE marking acceleration:The EU Machinery Directive pathway for sensor-integrated safety equipment is shortening time-to-market for compliant helmet-mounted firefighting units.
- IT-OT convergence:Networked thermal sensors with edge analytics are penetrating industrial facilities, merging operational technology monitoring with enterprise data architectures.
Industry Challenges
- Cybersecurity certification complexity:Insurance underwriters and facility operators are pricing IT-OT vulnerability exposure into procurement decisions, requiring manufacturers to obtain evolving network security credentials.
- Detector fabrication capex intensity:In-house uncooled microbolometer production demands semiconductor-grade cleanroom investment, favoring capitalized incumbents over module-assemblers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Imaging Camera Market |
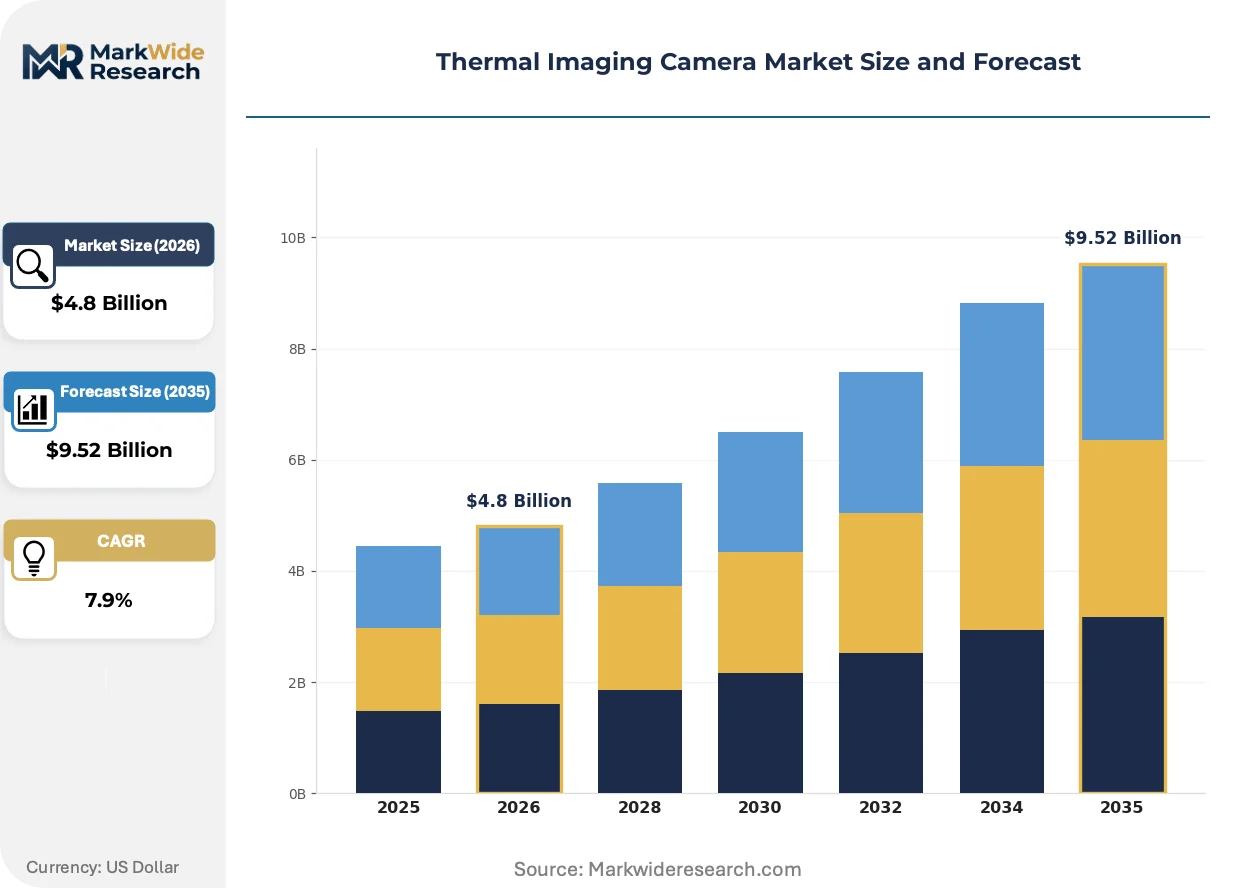
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Cameras, Fixed Cameras, Smartphone Accessories, Robotic Systems Technology: LWIR, MWIR, SWIR, Dual-Use End User: Military, Healthcare, Manufacturing, Firefighting Application: Building Inspection, Surveillance, Electrical Inspection, Search & Rescue |
| Companies Covered | Fluke Corporation, Jenoptik AG, Teledyne FLIR LLC, Raytheon Technologies, Opgal Optronic Industries Ltd., Seek Thermal, Hikvision Digital Technology Co., Lynred, Axis Communications AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Imaging Camera Market Strategic Shifts & Innovations
Modular unbundling of detector cores from finished camera housings is fragmenting the supplier base, while embedded analytics and edge processing are redefining value capture points across hardware and software layers.
Machine learning inference engines deployed directly on thermal camera SoCs are automating anomaly detection in electrical inspection and building diagnostics workflows. Electrical utilities and facility management contractors are adopting these systems for continuous substation monitoring, reducing reliance on periodic manual thermographic surveys. The compression of detection-to-alert latency is automating maintenance dispatch decisions and reshaping service contract structures around predictive rather than scheduled intervention.
The EU AI Act's risk-based classification system for biometric inference and automated threat detection is mandating conformity assessment updates for camera manufacturers deploying embedded analytics. Systems categorized as high-risk must demonstrate accuracy, robustness, and human oversight protocols before CE marking authorization. Firefighting and security equipment vendors serving European public procurement channels are restructuring product roadmaps to segregate analytics-capable and analytics-free SKUs.
Helmet-mounted thermal unit procurement by municipal fire departments is consolidating around integrated sensor platforms that combine thermal, visible, and gas detection modalities. German industrial buyers are extending this preference to predictive maintenance contracts, bundling hardware, software, and analytics subscriptions into multi-year service agreements. This unbundling of capital expenditure into operational expenditure streams is most visible in German factory automation and North American utility infrastructure programs.
Thermal Imaging Camera Market Segmentation
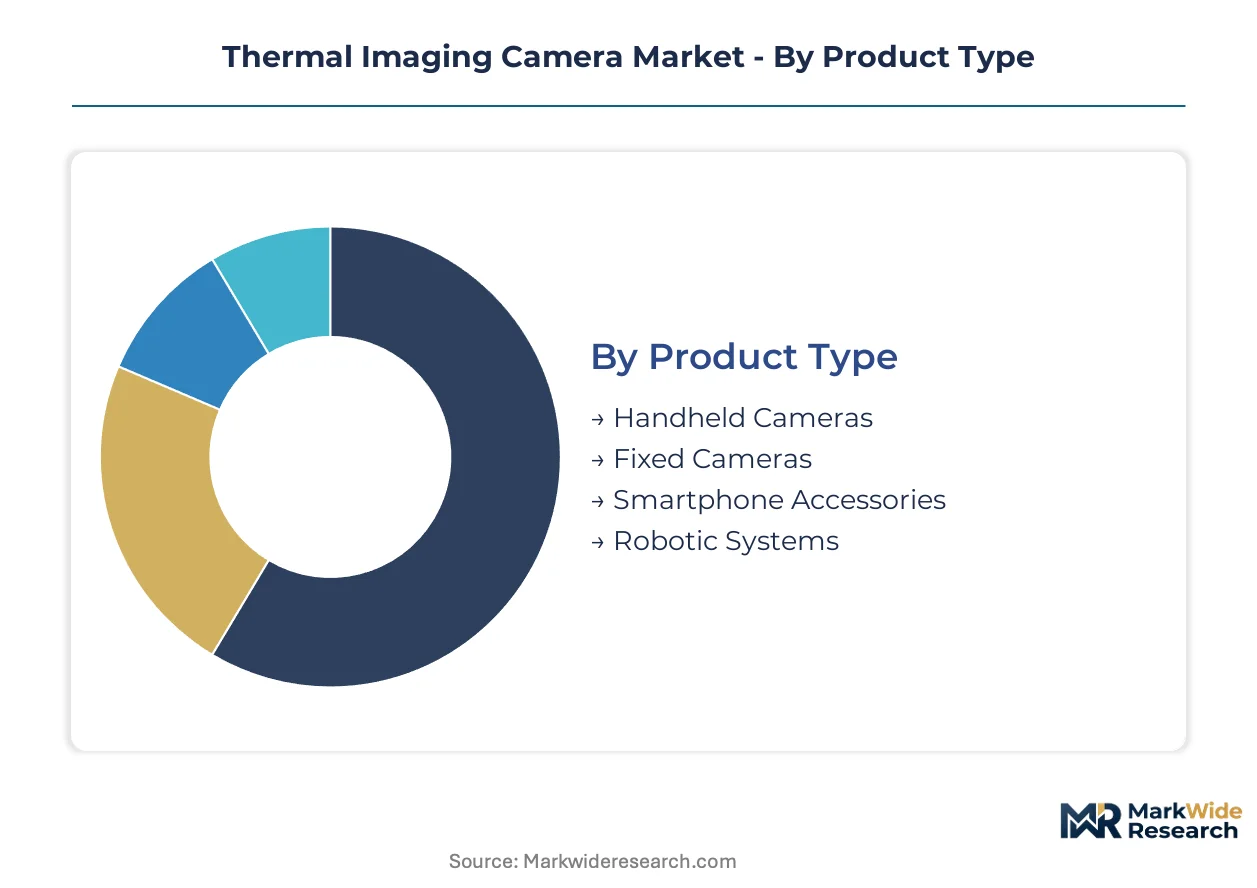
Thermal imaging camera procurement splits across distinct technical and operational dimensions, with buyer priorities shifting between portability, spectral precision, and integration depth. Understanding these segment boundaries clarifies where manufacturers must compete on cost versus performance specialization.
Product Type:
Portability requirements and deployment duration drive buyer selection across form factors, with trade-offs between mobility and continuous monitoring capability.
- Handheld Cameras:Battery-powered units with uncooled microbolometer arrays dominate electrical inspection and building diagnostics where technicians require walk-around flexibility. Facility management contractors in Germany favor these for periodic substation surveys despite the labor intensity of manual rounds.
- Robotic Systems:Gimbal-stabilized payloads with real-time telemetry integration are climbing the fastest as autonomous drone patrol programs expand across infrastructure and agriculture. Payload miniaturization demands are compressing development cycles for embedded thermal modules.
- Fixed Cameras:Permanently mounted systems serve continuous process monitoring in manufacturing environments where stationary vantage points suffice.
- Smartphone Accessories:Compact vanadium oxide modules clip to mobile devices for consumer and prosumer thermal visualization at entry price points.
Volume sits with Handheld Cameras; growth tilts toward Robotic Systems.
Technology:
Spectral band selection hinges on atmospheric transmission needs and cooling infrastructure tolerance, with cost differentials spanning an order of magnitude between architectures.
- LWIR:Uncooled long-wave systems operating at 7-14 micrometers deliver the lowest total cost of ownership through eliminated cryogenic maintenance. German factory automation programs anchor demand for these units in predictive maintenance deployment.
- MWIR:Cooled mid-wave architectures using indium antimonide or mercury cadmium telluride detectors capture military targeting and gas leak detection where spectral resolution justifies complexity. REACH substance restrictions on detector materials constrain European supplier qualification.
- SWIR:Short-wave infrared detection serves specialized applications requiring reflected-light imaging beyond silicon sensor limits.
- Dual-Use:Multi-spectral systems combine thermal and visible channels for analytics-rich deployments under EU AI Act compliance pathways.
Unit economics favor LWIR for volume; MWIR retains premium positioning for mission-critical spectral performance.
End User:
Procurement authority and budget cycles vary sharply across institutional buyers, with public safety and defense channels imposing distinct certification requirements.
- Firefighting:Helmet-mounted thermal unit procurement is accelerating across industrialized economies as departments consolidate around integrated sensor platforms combining thermal, visible, and gas detection modalities. CE marking under the EU Machinery Directive is shortening time-to-market for compliant European vendors.
- Manufacturing:German industrial buyers are bundling hardware, software, and analytics subscriptions into multi-year predictive maintenance service agreements, displacing capital expenditure with operational expenditure structures.
- Military:Cooled MWIR systems dominate targeting and surveillance applications with stringent environmental ruggedization standards.
- Healthcare:FDA 510(k) clearance pathways govern clinical fever-screening camera deployment with accuracy validation requirements.
Firefighting and Manufacturing segments are expanding most quickly as procurement modernizes; Military retains highest per-unit value concentration.
Application:
Workflow integration depth determines whether thermal imaging serves periodic inspection or continuous automated monitoring.
- Electrical Inspection:Machine learning inference engines on thermal camera SoCs are automating anomaly detection for substation monitoring, compressing detection-to-alert latency and reshaping utility service contracts around predictive intervention.
- Building Inspection:Energy audit and moisture detection applications favor handheld portability for residential and commercial property assessment.
- Surveillance:Low-light CMOS substitution is pressuring thermal's historical dominance in price-sensitive security installations.
- Search & Rescue:First responder deployment requires ruggedized platforms with rapid deployment protocols for disaster response scenarios.
Electrical Inspection leads automation integration; Building Inspection sustains highest handheld camera attachment rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dongguan concentrate thermal detector module assembly, drawing component suppliers into clustered manufacturing corridors. Tax incentives for semiconductor fabrication equipment accelerated capital deployment across these corridors during the past five years.
United States
Firefighting departments in California and Texas expanded helmet-mounted thermal procurement through FEMA preparedness grants. FDA 510(k) clearance pathways govern clinical fever-screening deployments in hospital systems. Boston's robotics cluster incubates drone-thermal payload startups serving utility inspection contracts.
Germany
Factory automation programs in Bavaria and Baden-Württemberg compress predictive maintenance deployment cycles for LWIR cameras. CE marking under the EU Machinery Directive shortens time-to-market for safety-integrated sensor platforms. Stuttgart's automotive supplier ecosystem tests thermal modules for battery manufacturing line monitoring.
China
MIIT industrial internet initiatives drive thermal camera integration into smart factory architectures across the Yangtze River Delta. GB standards for machine vision equipment shape product specification requirements for domestic suppliers. Shenzhen's electronics manufacturing services sector produces smartphone-accessible thermal modules at scale.
Japan
METI energy efficiency mandates accelerate building diagnostics camera deployment for commercial retrofit programs. JIS standards for non-contact temperature measurement influence industrial buyer procurement specifications. Nagoya's manufacturing equipment cluster integrates thermal monitoring into machine tool predictive maintenance systems.
United Kingdom
Network Rail infrastructure inspection programs create demand for drone-mounted thermal payloads across England's rail corridor. GDPR constraints on biometric inference affect security camera analytics deployment in public spaces. Cambridge's sensor technology cluster develops uncooled microbolometer arrays for industrial applications.
Thermal Imaging Camera Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across detector fabrication, system assembly, and software analytics layers. The market exhibits tiered concentration: a handful of vertically integrated incumbents control uncooled microbolometer supply, while modular assemblers proliferate at the application-specific tier. Three archetypes dominate: semiconductor-grade detector fabricators, ruggedized system integrators serving defense and firefighting channels, and software-centric analytics platforms. Capacity expansion in Southeast Asian assembly facilities and strategic partnerships for edge-AI inference engines represent the dominant competitive moves.
Among detector fabrication specialists, Teledyne FLIR LLC and Lynred occupy positions spanning module supply and finished system production. Jenoptik AG exemplifies the European industrial automation anchor, while Seek Thermal represents the smartphone-accessible tier. These three names illustrate how geographic clustering—US, French-German, and California-based respectively—maps to distinct buyer segment specializations without requiring identical capability stacks.
| Leading Market Players |
|---|
| Fluke Corporation |
| Jenoptik AG |
| Teledyne FLIR LLC |
| Raytheon Technologies |
| Opgal Optronic Industries Ltd. |
| Seek Thermal |
| Hikvision Digital Technology Co. |
| Lynred |
| Axis Communications AB |
| Others |
Cost & Logistics Intelligence
German factory automation buyers and municipal firefighting procurement departments concentrate demand for thermal imaging cameras, anchoring a pricing model where CE marking under the EU Machinery Directive and embedded analytics certification create tiered premiums for compliant manufacturers.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to helmet-mounted firefighting units required for immediate deployment, while spot inventory of smartphone-accessible vanadium oxide modules trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical fever-screening systems from industrial maintenance tiers and consumer accessories. Cost compression in the prosumer segment is intensifying because Seek Thermal and Shenzhen-based assemblers are flooding the smartphone accessory channel with uncooled microbolometer modules. Municipal fire departments exhibit lowest price sensitivity due to FEMA grant funding and safety-critical procurement protocols, while facility management contractors in building diagnostics show highest sensitivity to per-unit capital expenditure.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore manage hub-and-spoke patterns for detector module fulfillment to European and Asia-Pacific assembly facilities. Detector fabrication concentrates in the United States, France, and China, with Teledyne FLIR and Lynred controlling captive uncooled microbolometer supply. Mercury cadmium telluride for cooled MWIR architectures draws from limited specialty chemical suppliers in Germany and Japan. Single-source vulnerability around indium antimonide substrate processing exposes military and gas detection segments to input disruption. Distribution runs through OEM-direct channels for industrial automation customers and specialized safety equipment distributors for firefighting and security end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom-grade detector fabrication capacity represents the binding constraint propping pricing power for vertically integrated incumbents, as semiconductor-grade microbolometer production demands capital investment that module-assemblers cannot replicate.
For Market Incumbents: Acquire specialized LWIR core production facilities in Baden-Württemberg to anchor European industrial automation demand. Backward integration into vanadium oxide microbolometer wafer processing defends margin position against Shenzhen-based cost competitors. CE marking acceleration under the EU AI Act creates certification leverage that modular assemblers lack. For New Entrants and Emerging Players: Agricultural drone operators represent an underserved buyer archetype requiring miniaturized gimbal-stabilized thermal payloads with real-time telemetry integration. Smartphone-accessible thermal modules for prosumer building diagnostics offer the most penetrable segment given Seek Thermal's channel validation. Partner with DJI-compatible gimbal manufacturers for rapid payload integration. For Investors and Strategic Acquirers: The window for entry favors detector fabrication specialists with in-house uncooled microbolometer capability and established CE marking pathways. Long-term viability rests on semiconductor-grade cleanroom assets rather than module assembly operations. Watch for EU AI Act high-risk system classification expansion as the inflection signal compressing analytics-free SKU margins.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration | EU Machinery Directive compliance shortens time-to-market for helmet-mounted firefighting units in Germany. |
| Backward Integration into Detector Fabrication | In-house uncooled microbolometer production anchors pricing power against Shenzhen module competitors. |
| Drone Payload Miniaturization | Gimbal-stabilized thermal modules capture autonomous patrol demand from Network Rail and agricultural operators. |
| Embedded Analytics Development | Edge-AI inference engines on thermal SoCs automate anomaly detection for electrical utility substation monitoring. |
| Multi-year Service Agreement Structuring | Predictive maintenance contracts displace capital expenditure with operational expenditure for German factory automation buyers. |
Research Approach
Document review covered SEC 10-K filings from Teledyne and Raytheon Technologies, EU AI Act implementation guidance, and FDA 510(k) clearance databases, complemented by interviews with plant engineers at Bavarian automotive suppliers, firefighting equipment procurement officers in California and Texas, and thermal camera product managers at industrial distributors. Secondary validation drew from ECHA REACH substance restriction updates, German factory automation trade association reports, and customs data for detector module imports. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across the projection horizon.
Cross-reference between historical LWIR and MWIR technology adoption curves and expert panel input shaped the analytical framework. Segmentation dimensions modeled include product type, spectral band technology, end-user vertical, and application workflow integration depth. CAGRs derived from regression against industrial automation capital expenditure trends and firefighting department budget allocation patterns. Forecast inputs incorporated EU AI Act compliance timeline assumptions and vanadium oxide microbolometer cost curves.
Revisions become necessary when REACH substance restrictions expand to additional detector materials, when low-light CMOS sensors with computational enhancement capture additional thermal security applications, or when cybersecurity certification requirements for IT-OT converged networks disrupt procurement patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Compact Camera Module Market
Imaging
Latin America Surveillance Analog Camera Market
Imaging
Global Ingaas Camera Market
Imaging
Handheld Retinal Scanners Market
Imaging
Underwater Camera Market
Imaging
Macroscopic Imaging Systems Market
Imaging
Global Phosphor Plate Scanners Market
Imaging
High Dynamic Range Market
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
Europe Thermal Imaging Systems Market
Imaging
Global Image Signal Processor Market
Imaging
Handheld Thermal Imaging Equipment Market
Imaging
Europe Multi Camera Vision Inspection Systems Market
Imaging
Asia Pacific Industrial Computed Tomography Market
Imaging
Photoacoustic Tomography Market
Imaging
Cooled IR Camera Market