
 Asia-Pacific Solar Blanket Market | 2026-2036
Asia-Pacific Solar Blanket Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Solar Blanket Market Insights
China's dual carbon goals under MEE oversight is decoupling solar blanket procurement from pure cost metrics toward efficiency-certified sourcing. LONGi Solar leverages its polysilicon-to-module pipeline to control quality tiers across portable and fixed formats. Trina Solar anchors its position through R&D intensity in hybrid thermal-photovoltaic configurations. JinkoSolar competes on manufacturing scale, sustaining cost advantages in ground-mounted installations across Australian and Indian utility corridors.
Asia-Pacific solar blankets are flexible, weather-resistant membrane systems integrating photovoltaic cells or thermal collectors into rollable or semi-rigid substrates, typically rated between 50W and 400W per square meter and manufactured through lamination processes that bond ETFE or TPU encapsulants to cell matrices. Their primary purpose is delivering off-grid or supplementary power in mobile, temporary, or structurally constrained environments where rigid panels prove impractical. Portable product types lead volume shipments due to military, recreational vehicle, and disaster relief procurement cycles, though fixed and semi-fixed formats carry stronger margin pools in commercial rooftop applications. Agricultural end users represent the fastest-expanding buyer segment as irrigation cooperatives in India and Australia adopt solar blankets for remote water pumping. Photovoltaic technology dominates installed base, yet hybrid thermal-photovoltaic systems are capturing specification share in industrial process heat applications where roof-mounted deployment faces space constraints.
India's BIS certification mandates and Australia's Clean Energy Council accreditation framework shape product entry requirements, forcing exporters to maintain dual testing protocols for cell efficiency and fire resistance. Japan's METI feed-in tariff revisions for distributed generation are redirecting residential demand toward lighter, wall-mountable formats that solar blanket producers must engineer to JIS structural standards. Stakeholders should monitor how China's GB standards evolution and India's PLI scheme for solar manufacturing interact to determine whether local content rules will fragment supply chains or consolidate procurement around integrated domestic producers.
Market Dynamics
China's MEE oversight of dual carbon goals is decoupling procurement from pure cost metrics toward efficiency-certified sourcing, forcing suppliers to requalify products under tightening GB standards while agricultural cooperatives in India and Australia accelerate deployment for decentralized irrigation.
Growth Catalysts
- MEE efficiency mandates:China's tightening GB standards under dual carbon goals are disqualifying low-efficiency imports and redirecting procurement toward certified domestic suppliers.
- Agricultural irrigation cooperatives:India's western states are deploying solar blankets for remote water pumping, creating concentrated demand from decentralized rural electrification.
- ETFE lamination advances:Improved encapsulant bonding processes are extending product lifespans in tropical humidity, reducing replacement cycles for off-grid installations.
Market Restraints
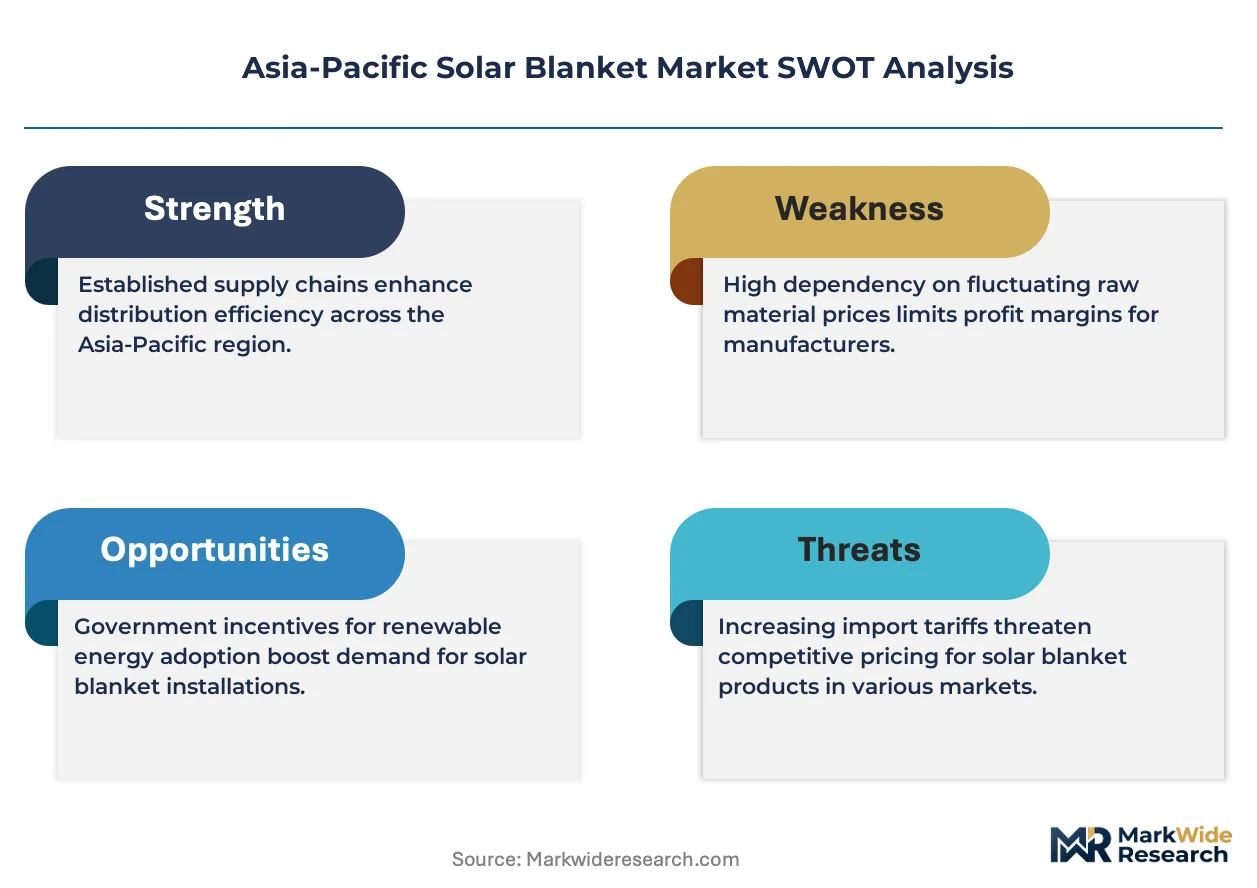
- Polysilicon price volatility:Input cost swings for cell-grade silicon are compressing margins for flexible PV manufacturers without captive supply arrangements.
- BIS certification timelines:India's mandatory testing protocols for fire resistance and cell efficiency are extending product entry cycles by six to nine months for exporters.
- Rigid panel substitution:Ground-mounted crystalline silicon installations in Australian utility corridors are capturing volume that flexible formats cannot match on cost-per-watt.
Strategic Opportunities
- Indonesia's archipelago electrification:Maritime logistics constraints across 17,000 islands favor rollable, lightweight formats over rigid panels for distributed microgrids.
- Japan's wall-mountable formats:METI feed-in tariff revisions for distributed generation are redirecting residential demand toward lighter substrates meeting JIS structural standards.
- Hybrid thermal-photovoltaic convergence:Industrial process heat applications in space-constrained factory rooftops are creating specification pull for dual-output membrane systems.
Industry Challenges
- Dual testing protocol complexity:Exporters must maintain parallel certification tracks for India's BIS fire resistance standards and Australia's Clean Energy Council accreditation, doubling compliance overhead.
- PLI scheme supply chain reconfiguration:India's production-linked incentive scheme for solar manufacturing is forcing importers to evaluate local assembly partnerships or forfeit utility-scale procurement access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Solar Blanket Market |
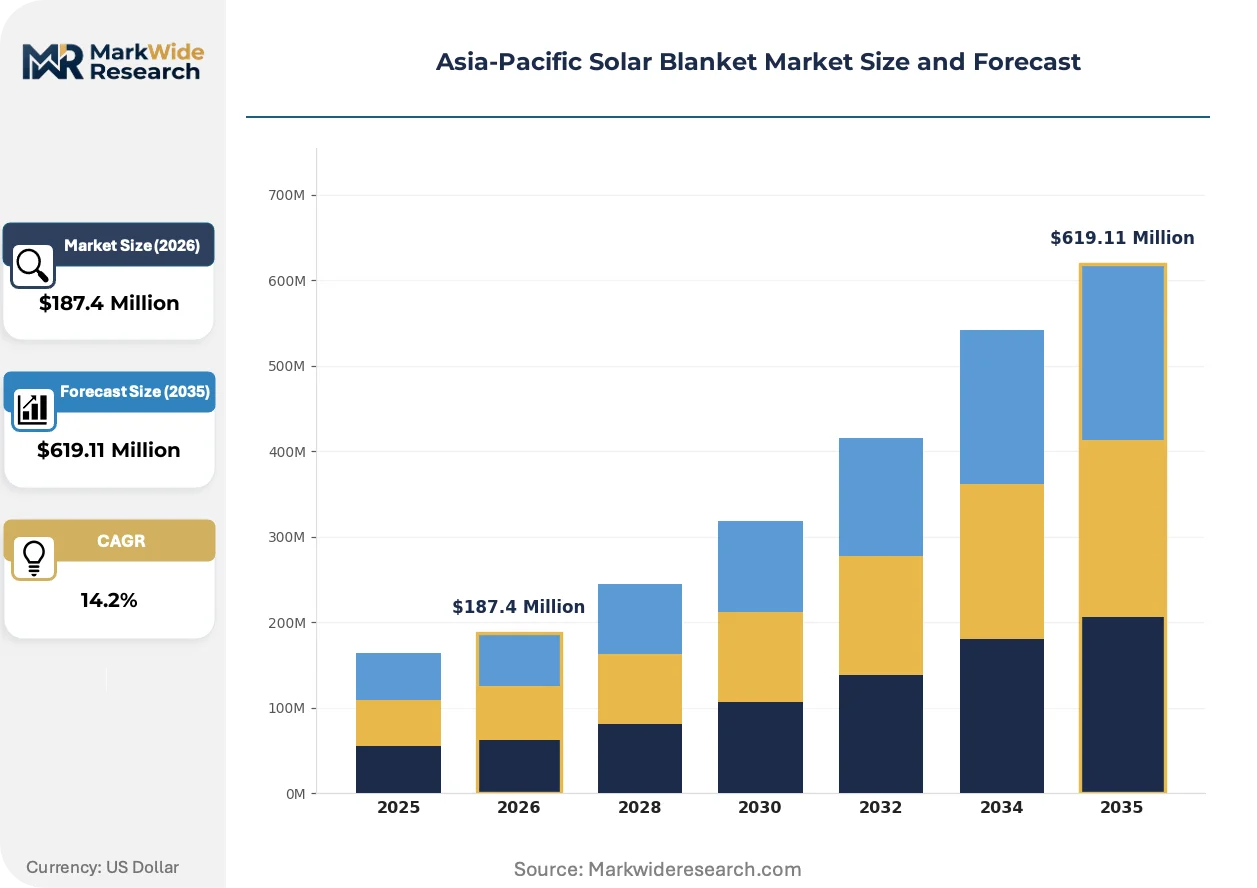
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Semi-Fixed, Custom End User: Residential, Commercial, Industrial, Agricultural Technology: Photovoltaic, Thermal, Hybrid, Concentrated Solar Power Installation: Ground-mounted, Roof-mounted, Wall-mounted, Others |
| Companies Covered | Trina Solar, JinkoSolar, JA Solar, Canadian Solar, LONGi Solar, Hanwha Q CELLS, Yingli Green Energy, Risen Energy, Shenzhen Sungold Solar Co., Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Solar Blanket Market Trends and Innovations
Active reshaping in this market centers on membrane-level technology convergence, regulatory fragmentation across certification regimes, and procurement behavior pivoting from equipment purchase toward performance-guaranteed deployment models.
Hybrid thermal-photovoltaic membranes are converging with industrial process heat demand in Japanese and Australian manufacturing clusters. Food processing and chemical plants with constrained rooftop footprints are specifying dual-output systems that generate electricity while capturing thermal energy for pre-heating applications. This convergence is compressing addressable market boundaries between traditional solar PV and industrial heat pump suppliers.
Japan's METI has revised feed-in tariff structures to favor lighter distributed generation formats, directly impacting solar blanket specification requirements. The policy shift is forcing manufacturers to engineer products meeting JIS structural load standards for wall-mounted deployment. Residential installers in Tokyo and Osaka prefectures are now prioritizing sub-15kg per square meter substrates that rigid panels cannot achieve.
Buyer contracting patterns are rotating from capital equipment purchase toward energy-as-a-service arrangements in Australian agricultural sectors. Irrigation cooperatives in Queensland and New South Wales are signing ten-year output guarantees with third-party owner-operators rather than owning assets directly. This shift is concentrating procurement influence among integrated developers with balance-sheet capacity to underwrite performance risk.
Asia-Pacific Solar Blanket Market Segmentation
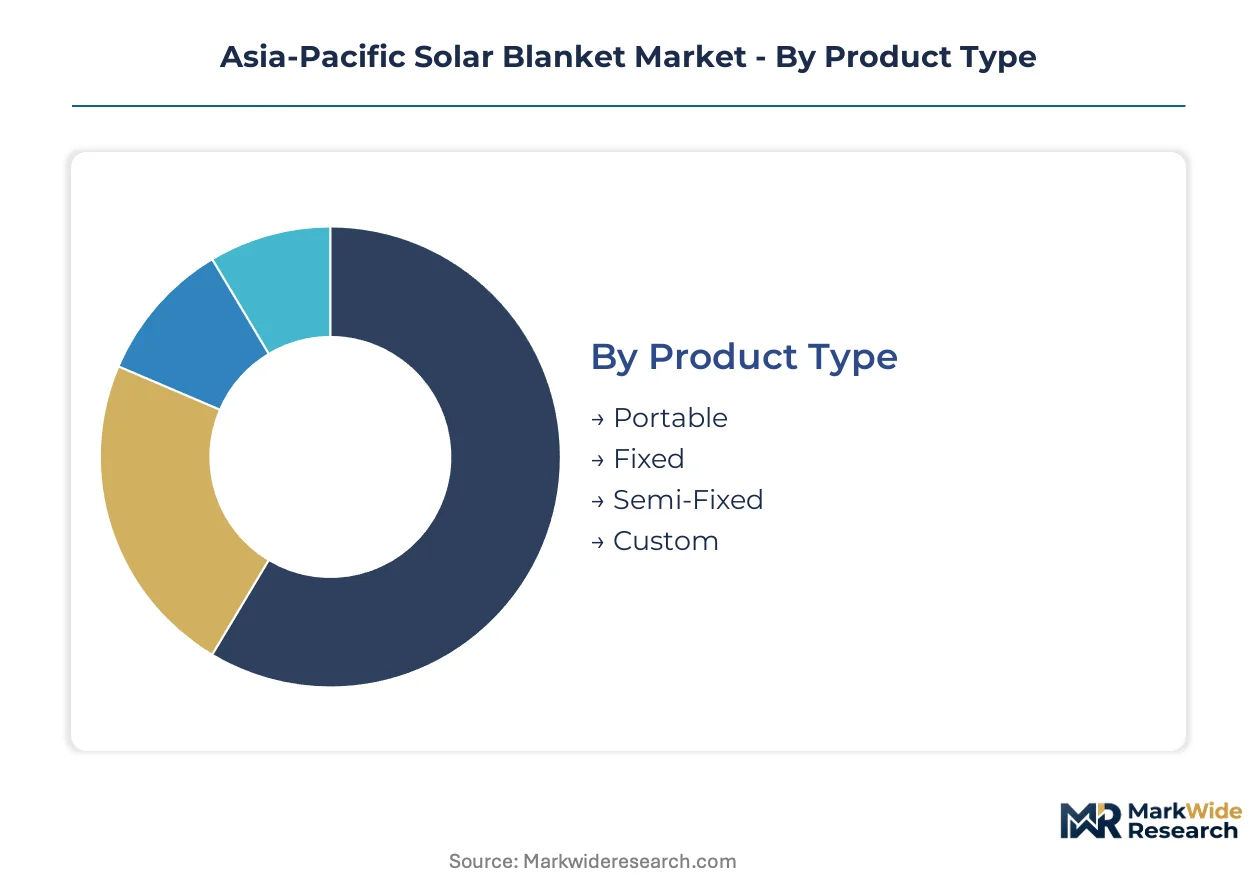
Solar blanket deployment patterns diverge sharply across specification axes. Technology choice determines efficiency thresholds and certification requirements, while installation constraints dictate substrate flexibility and structural load ratings.
Product Type:
Rollability and mounting permanence define the specification-cost tradeoff across deployment scenarios.
- Portable:Military, recreational vehicle, and disaster relief procurement cycles dominate volume shipments. Foldable ETFE-laminated formats rated 50-150W per square meter serve off-grid power needs across Indonesia's archipelago microgrids and Australian remote mining camps.
- Fixed:Permanent membrane installations on commercial rooftops in Japan and Australia carry stronger margin pools through 20-25 year performance guarantees. JIS structural compliance and Clean Energy Council accreditation requirements elevate supplier qualification barriers.
- Semi-Fixed:Seasonally deployable formats serve Indian agricultural cooperatives with irrigation pumping schedules.
- Custom:Project-specific dimensions address irregular rooftop geometries in dense Japanese urban corridors.
Mature deployment sits with Fixed formats in commercial rooftop applications. Newer deployment is concentrated in Portable formats for distributed rural electrification.
End User:
Customer sophistication and procurement scale reshape pricing structures and contract terms.
- Agricultural:Irrigation cooperatives in India's western states and Queensland are expanding fastest. Ten-year energy-as-a-service contracts replace direct equipment purchases, concentrating procurement influence among integrated developers with balance-sheet capacity.
- Residential:Japan's METI feed-in tariff revisions redirect demand toward sub-15kg per square meter wall-mountable formats. Tokyo and Osaka prefectures prioritize lightweight substrates rigid panels cannot achieve.
- Commercial:Food processing and chemical plants in Australian manufacturing clusters specify hybrid thermal-photovoltaic membranes for space-constrained rooftops.
- Industrial:Process heat applications drive dual-output system specifications.
Procurement sophistication clusters with Commercial users. Volume expansion runs through Agricultural cooperatives adopting performance-guaranteed deployment models.
Technology:
Cell architecture and thermal capture capability determine addressable application boundaries.
- Photovoltaic:Silicon cell matrices bonded to ETFE or TPU substrates dominate installed base. India's BIS certification mandates and Australia's Clean Energy Council accreditation shape product entry requirements for cell efficiency and fire resistance.
- Hybrid:Dual thermal-photovoltaic output systems capture specification share in Japanese and Australian industrial process heat applications where rooftop space constraints prevent separate heat pump installations.
- Thermal:Pure heat collection membranes serve specialized pre-heating applications.
- Concentrated Solar Power:Parabolic trough integration remains niche for utility-scale demonstration projects.
Technology maturation centers on Photovoltaic formats with standardized certification protocols. Hybrid configurations are climbing the fastest as industrial heat demand converges with distributed generation.
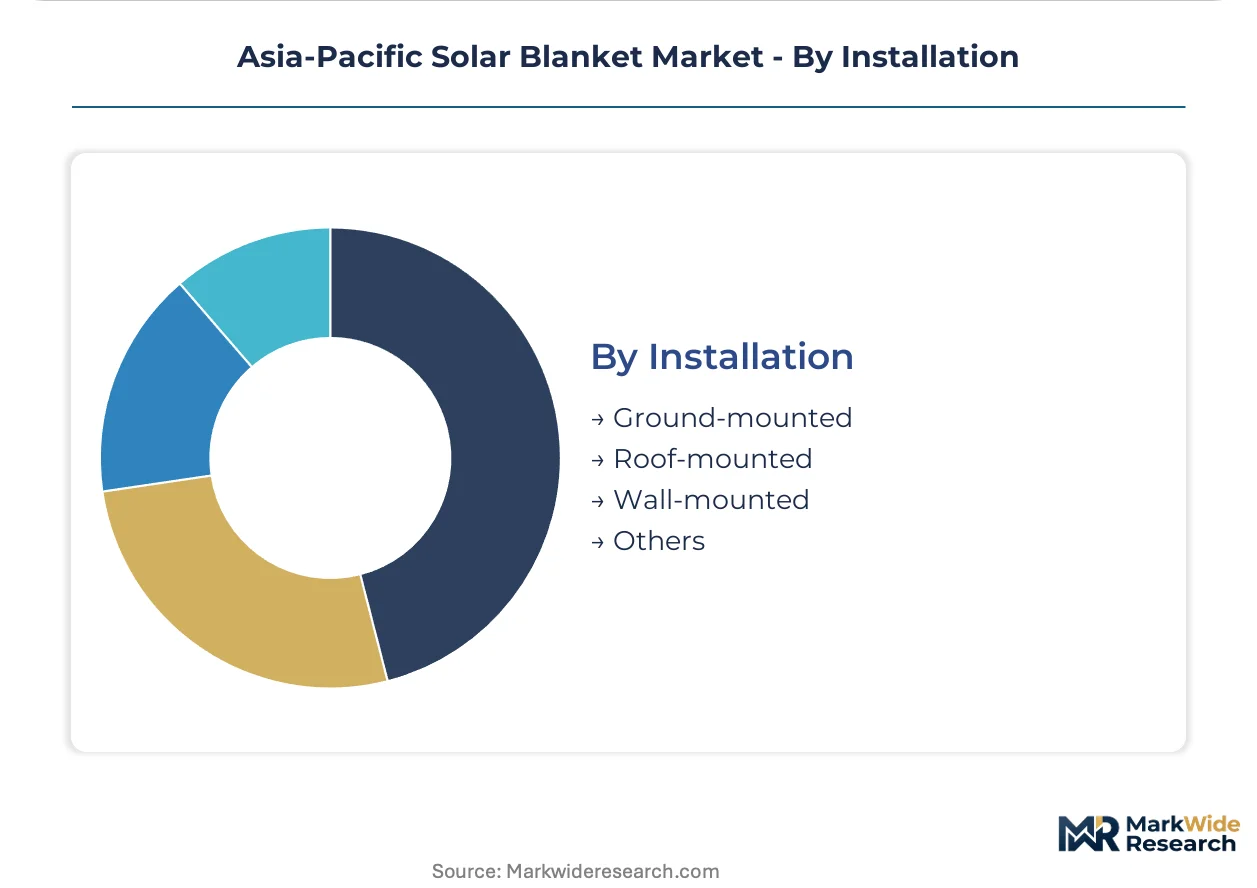
Installation:
Structural attachment method dictates membrane flexibility requirements and regulatory compliance scope.
- Roof-mounted:Commercial applications across Australian manufacturing clusters and Japanese industrial zones require wind load ratings and waterproofing integration. ETFE lamination advances extend product lifespans in tropical humidity.
- Wall-mounted:Japan's METI policy shift creates specification pull for JIS-compliant structural standards. Residential installers in dense urban prefectures prioritize formats under 15kg per square meter.
- Ground-mounted:Indian agricultural cooperatives deploy rollable formats for seasonal irrigation pumping.
- Others:Floating and vehicle-integrated applications serve specialized maritime and transport segments.
Installation standardization is strongest in Roof-mounted commercial deployment. Wall-mounted formats are gaining share fastest under Japan's distributed generation policy pivot.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangtze River Delta manufacturing corridor anchors solar blanket production capacity and certification standard-setting across the Asia-Pacific region. Regional deployment patterns diverge sharply between China's efficiency-driven procurement mandates and India's decentralized rural electrification push.
China
MEE oversight of dual carbon goals is disqualifying low-efficiency imports through tightening GB standards. Domestic suppliers with captive polysilicon supply chains are capturing procurement share from exporters lacking certification compliance. Jiangsu and Zhejiang industrial clusters are reconfiguring lamination lines to meet elevated efficiency benchmarks for both domestic and export markets.
India
Irrigation cooperatives in Maharashtra and Gujarat are deploying rollable formats for seasonal water pumping schedules. BIS certification timelines for fire resistance and cell efficiency are extending product entry cycles by six to nine months for foreign manufacturers. The PLI scheme for solar manufacturing is pressuring importers to establish local assembly partnerships or forfeit utility-scale procurement access.
Japan
METI feed-in tariff revisions for distributed generation are redirecting residential demand toward sub-15kg per square meter wall-mountable formats. Tokyo and Osaka prefecture installers are prioritizing lightweight substrates that rigid panels cannot achieve. JIS structural load standards are forcing manufacturers to engineer membrane systems for vertical mounting configurations.
Australia
Queensland and New South Wales irrigation cooperatives are signing ten-year energy-as-a-service contracts with third-party owner-operators rather than purchasing equipment directly. Clean Energy Council accreditation requirements are elevating supplier qualification barriers for permanent membrane installations. Manufacturing clusters in Victoria are specifying hybrid thermal-photovoltaic membranes for space-constrained food processing rooftops.
Indonesia
Maritime logistics constraints across 17,000 islands favor rollable, lightweight formats over rigid panels for distributed microgrid deployment. Portable ETFE-laminated units rated 50-150W per square meter are serving off-grid power needs in remote mining camps and island communities. The archipelago geography is creating natural market segmentation that rewards logistics-flexible product architectures.
Asia-Pacific Solar Blanket Market Competitive Landscape
The competitive structure tilts toward integrated polysilicon-to-module producers with captive supply chain control. Three strategic archetypes dominate: efficiency-certified domestic suppliers serving MEE-mandated procurement, scale-driven exporters competing on manufacturing volume, and hybrid technology specialists capturing industrial process heat specifications. Capacity expansion and certification diversification represent the dominant competitive moves as regional regulatory fragmentation intensifies.
Within the integrated manufacturing tier, LONGi Solar and Trina Solar exemplify archetypes built on upstream supply chain control and R&D intensity respectively. JinkoSolar anchors the scale-driven competitive position. These three entities represent the spectrum from polysilicon integration through hybrid thermal-photovoltaic convergence, illustrating how regional certification requirements are stratifying competitive positioning across the Asia-Pacific procurement landscape.
| Leading Market Players |
|---|
| Trina Solar |
| JinkoSolar |
| JA Solar |
| Canadian Solar |
| LONGi Solar |
| Hanwha Q CELLS |
| Yingli Green Energy |
| Risen Energy |
| Shenzhen Sungold Solar Co., Ltd |
| Others |
Pricing and Supply Chain Analysis
Polysilicon spot price volatility cascades through Asia-Pacific solar blanket manufacturing, compressing margins for flexible PV producers lacking captive silicon supply while amplifying price divergence between efficiency-certified and uncertified product tiers.
Pricing Analysis
Performance-guaranteed output anchors value-based pricing for agricultural cooperatives in Queensland and New South Wales, where ten-year energy-as-a-service contracts replace equipment purchases. Pricing stratifies across GB-certified premium tiers, BIS-compliant standard grades, and uncertified economy imports. Cost compression in economy tiers is intensifying because Indian and Australian certification timelines extend entry cycles for foreign manufacturers. Agricultural cooperatives exhibit highest price sensitivity, while Japanese residential installers prioritize sub-15kg wall-mountable formats regardless of premium positioning.
Supply Chain Analysis
Maritime freight costs across Indonesia's 17,000-island archipelago favor rollable formats over rigid panels, creating natural logistics-driven market segmentation. Manufacturing concentrates in China's Jiangsu and Zhejiang clusters, with polysilicon feedstock drawing from Xinjiang and Inner Mongolia. Supply chain risk centers on single-source vulnerability for cell-grade silicon purification. Distribution runs through integrated developers with balance-sheet capacity to underwrite performance-guaranteed deployment contracts across Australian and Indian agricultural corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific solar blanket supply is tightening around certified domestic capacity, with MEE efficiency mandates and BIS certification timelines constraining qualified supplier pools and propping pricing power for compliant producers.
For Market Incumbents: Anticipate margin compression from hybrid thermal-photovoltaic convergence by securing captive polysilicon supply through backward integration into Xinjiang and Inner Mongolia feedstock corridors. Invest in dual certification tracks for India's BIS fire resistance standards and Australia's Clean Energy Council accreditation to preempt competitor entry. For New Entrants and Emerging Players: Capture white-space opportunity in Indonesia's maritime microgrid deployment, where logistics constraints exclude rigid panel competition and rollable ETFE-laminated formats command natural advantage. Target agricultural cooperatives in Maharashtra and Gujarat with seasonal leasing models bypassing capital purchase barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated polysilicon-to-module producers with MEE certification compliance in China's Yangtze River Delta manufacturing corridor. Long-term viability hinges on regulatory fragmentation persisting across GB, BIS, and JIS standard regimes. Watch for PLI scheme localization mandates in India as inflection signal for supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous BIS and Clean Energy Council compliance unlocks Indian and Australian procurement access. |
| Backward Integration into Polysilicon | Captive silicon supply insulates margin pressure from Xinjiang feedstock price swings. |
| Hybrid Thermal-Photovoltaic R&D | Dual-output membranes capture Japanese industrial process heat specifications under METI policy. |
| Indonesia Microgrid Partnership | Maritime logistics constraints create defensible niche for rollable format deployment. |
| Energy-as-a-Service Platform | Performance-guaranteed contracts concentrate procurement influence among integrated developers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with solar blanket procurement officers at Indian agricultural cooperatives, Australian irrigation association executives, Japanese residential installer networks, and Chinese lamination equipment manufacturers. Secondary sources included MEE GB standard documentation, BIS certification registries, METI feed-in tariff revision notices, and Clean Energy Council accreditation databases. Bottom-up shipment volume estimates triangulated against top-down capacity utilization data from Jiangsu and Zhejiang manufacturing clusters.
Data-stream reconciliation across product type, end user, technology, installation method, and regional regulatory framework dimensions shaped the analytical framework. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion across the projection horizon. Forecast inputs incorporated polysilicon price elasticity coefficients and certification timeline lag effects for cross-border supplier entry.
The model holds under continued MEE efficiency mandate enforcement and BIS certification persistence; deviation in PLI scheme localization requirements or METI tariff structure would shift supply chain configuration assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
India Solar Tracker Market
Solar Power Systems
Solar-Powered EV Charging Stations Market
Solar Power Systems
South America Solar PV Inverters Market
Solar Power Systems
Solar Cells Market
Solar Power Systems
South Korea Solar Energy Market
Solar Power Systems
Solar Mirror Market
Solar Power Systems
Rooftop Solar PV Market
Solar Power Systems
Thin-Film Photovoltaic Market
Solar Power Systems
China Distributed Solar Power Generation Market
Solar Power Systems
Marine Solar Panel Market
Solar Power Systems
Bulgaria Solar Energy Market
Solar Power Systems
Residential Solar Inverter Market
Solar Power Systems
Solar Backsheet Market
Solar Power Systems
Plastic Solar Cell Market
Solar Power Systems
Solar Crimp Set Market
Solar Power Systems
Solar Power Meters Market