
 Electronic Expansion Valves Market | 2026-2036
Electronic Expansion Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Expansion Valves Market Analysis
Modular chiller-heat pump packages is repositioning buyer choice away from standalone valve procurement toward pre-integrated refrigerant management modules. Danfoss leverages its captive controller technology to anchor premium positions in European HVAC OEM channels. Sanhua Holding Group dominates cost-optimized supply for Asian residential heat pump manufacturers through in-house production of both valves and stepper motors.
An electronic expansion valve is a precision refrigerant flow control device utilizing a stepper motor-driven needle and electronic controller to modulate superheat in vapor-compression cycles, typically operating with resolution down to fractions of a millimeter and response times under two seconds. Its primary purpose is to optimize evaporator utilization and system efficiency across variable load conditions in air conditioning, refrigeration, and thermal management equipment. Electronic valves sustain the fastest growth trajectory as thermal expansion valves face displacement across commercial refrigeration and heat pump platforms. Smart sensors technology captures expanding margin pools as OEMs specify predictive maintenance and IoT-enabled diagnostics. Residential end user demand lags commercial and industrial uptake where payback periods on efficiency gains compress most rapidly.
The EU F-Gas Regulation and REACH compliance frameworks restrict high-GWP refrigerants, forcing valve redesigns for compatibility with R32, R290, and CO2 transcritical cycles. Japan's METI Top Runner program and China's GB energy efficiency standards mandate minimum performance coefficients that electronic valves enable through precise superheat control. Stakeholders must monitor refrigerant transition timelines and certify valve portfolios against emerging flammability and pressure standards before thermal valve obsolescence accelerates.
Market Dynamics
Heat pump OEMs in Germany and China are consolidating valve procurement into pre-integrated refrigerant management modules, compressing standalone component margins while elevating controller-embedded valve architectures. This structural shift favors suppliers with captive stepper motor production and firmware development capabilities.
Growth Catalysts
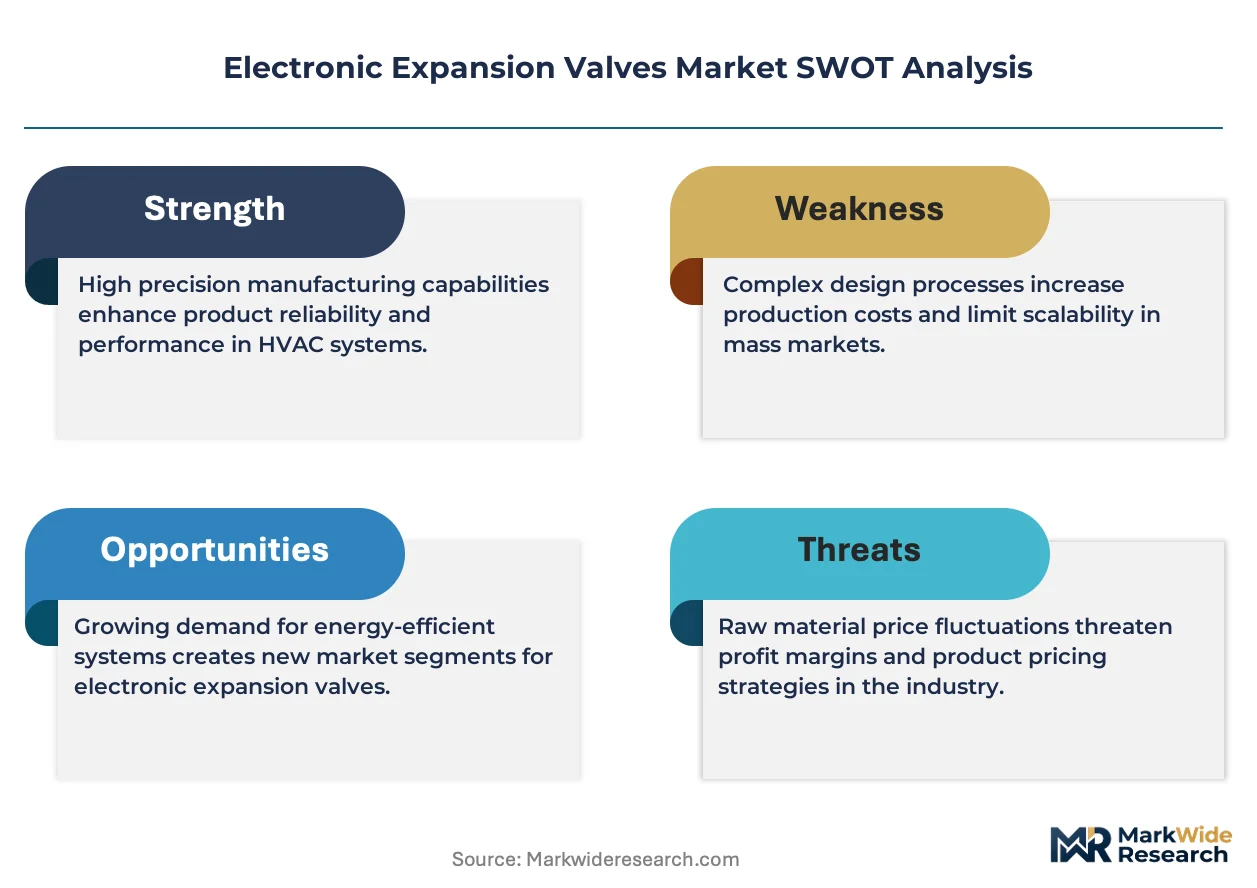
- EU F-Gas Regulation:The phasedown of high-GWP refrigerants mandates electronic superheat control to maintain efficiency coefficients with R32 and R290, accelerating displacement of thermal expansion valves across commercial refrigeration platforms.
- China's GB energy efficiency standards:Minimum performance coefficients for residential heat pumps now require precision modulation that only electronic valves deliver, driving procurement volume in the eastern manufacturing corridor.
- Stepper motor miniaturization:Advances in micro-actuator resolution enable sub-millimeter needle positioning, expanding electronic valve applicability into compact residential split systems previously served by capillary tubes.
Market Restraints
- Controller cost concentration:Electronic valve systems require dedicated PCBs and firmware, adding 40-60% material cost premium over thermal alternatives that constrains adoption in price-sensitive residential segments.
- Copper and rare earth volatility:Stepper motor windings and valve bodies depend on copper and neodymium pricing, exposing manufacturers to input cost swings that compress margin predictability.
- Technician skill gaps:Electronic valve commissioning requires superheat measurement and controller parameter adjustment, creating installation friction in markets lacking HVAC technician certification infrastructure.
Strategic Opportunities
- India's residential heat pump underpenetration:Cooling-dominated markets present conversion opportunity as BIS efficiency labeling tightens and urban electrification expands, favoring electronic valve suppliers with localized controller production.
- Predictive maintenance convergence:Integration of pressure-temperature sensors with IoT-enabled controllers creates recurring revenue streams through remote diagnostics and preemptive valve health monitoring.
- CO2 transcritical cycle expansion:The EU Green Deal's refrigeration decarbonization timeline drives demand for high-pressure-rated electronic valves compatible with transcritical CO2 systems in supermarket and cold chain applications.
Industry Challenges
- Flammability certification timelines:R290 compatibility requires ATEX and IEC 60079-15 testing protocols that extend product qualification cycles by 8-14 months, delaying portfolio refresh.
- Legacy controller incompatibility:Retrofit installations face integration friction with existing HVAC control architectures, requiring custom firmware adaptation that fragments engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Expansion Valves Market |
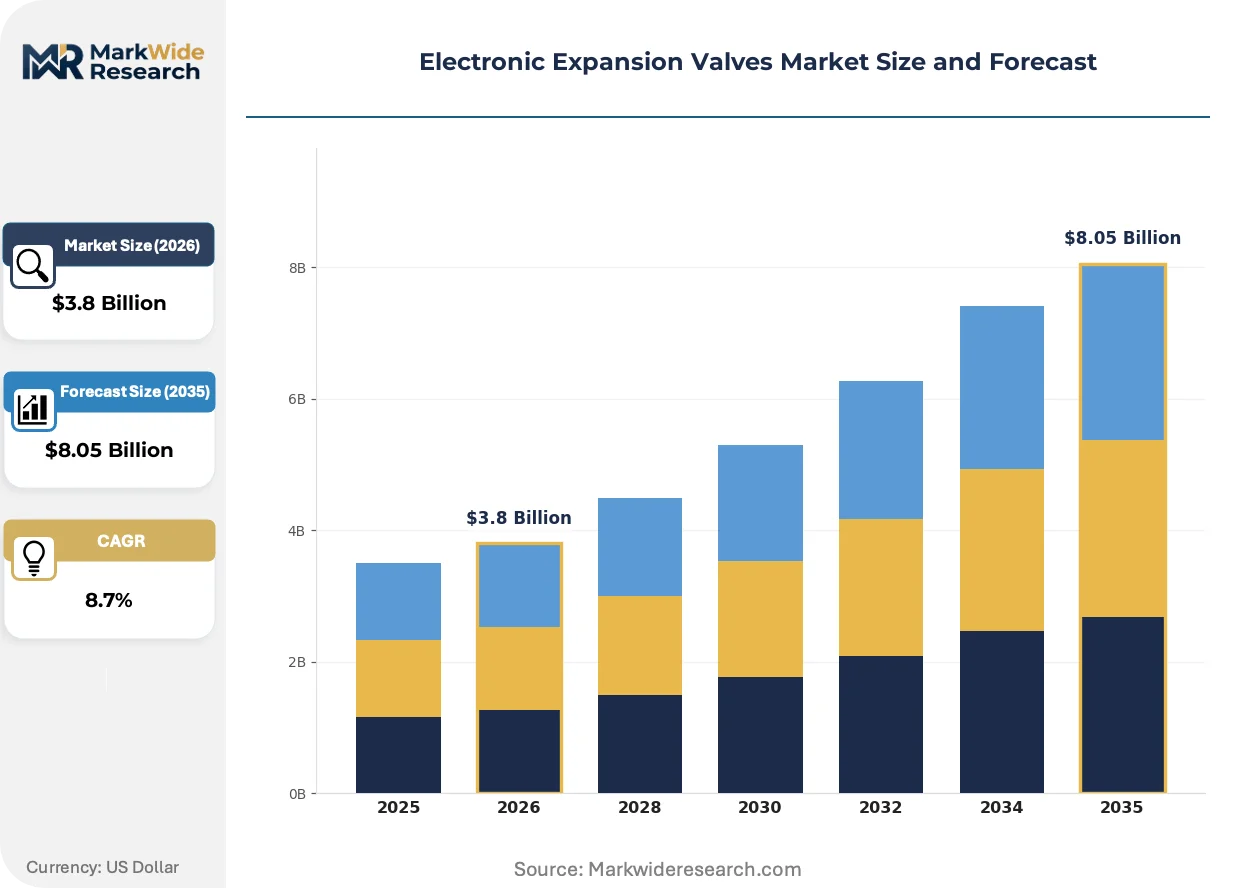
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Expansion Valves, Electronic Valves, Variable Orifice Valves, Solenoid Valves End User: Residential, Commercial, Industrial, Automotive Application: HVAC Systems, Refrigeration, Chillers, Heat Pumps Technology: Thermal Sensing, Electronic Control, Multifunctional, Smart Sensors |
| Companies Covered | Sanhua Holding Group, CAREL Industries S.p.A., Danfoss, Saginomiya Seisakusho, Inc., Zhejiang DUNAN Artificial Environment Co., Ltd., Emerson Electric Co., Fujikoki Corporation, Denso Corporation, Parker Hannifin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Expansion Valves Market Emerging Trajectories
Valve-controller integration is compressing the traditional component supply chain, with OEMs specifying embedded intelligence rather than discrete mechanical devices. Three developments are reshaping competitive positioning.
Sensor-fused electronic expansion valves are unifying flow modulation with real-time superheat calculation, eliminating external controller boxes. Commercial chiller manufacturers in Japan and Germany are specifying these integrated units for variable refrigerant flow systems. The technology is unifying what were previously separate procurement categories—valves, sensors, and controllers—into single-source module contracts that favor vertically integrated suppliers.
Japan's METI Top Runner program now mandates annual efficiency improvement targets for commercial air conditioning that electronic valves enable through precise load matching. The regulation forces OEMs to abandon thermal expansion valve architectures in favor of electronically actuated alternatives across all new platform development. Heat pump manufacturers serving the Japanese market have compressed their electronic valve qualification timelines by half to meet 2026 product launch windows.
Buyer concentration among modular chiller-heat packagers is consolidating valve procurement decisions into subsystem integrators rather than end-equipment OEMs. Danfoss and Sanhua now negotiate directly with compressor module assemblers in China's eastern corridor, bypassing traditional HVAC equipment channels. This channel compression is most visible in Germany, where heat pump OEMs have reduced their valve supplier base from twelve to four qualified vendors over three years.
Electronic Expansion Valves Market Segmentation
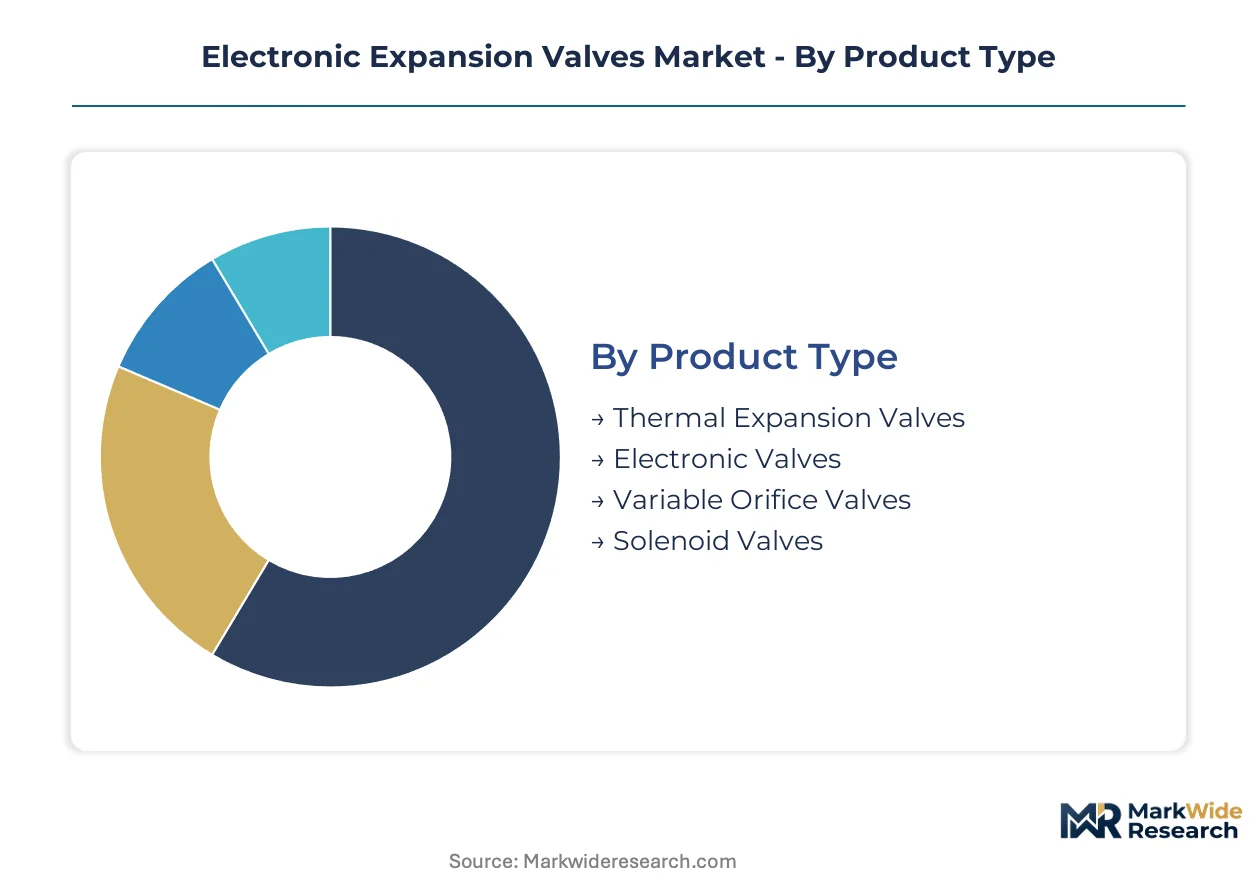
Electronic expansion valve procurement patterns diverge sharply across equipment categories, refrigerant architectures, and buyer sophistication levels. Understanding these segment boundaries reveals where controller-embedded premiums command pricing power versus where thermal alternatives retain residual share.
Product Type:
Volume concentrates in cost-optimized thermal architectures while premium capture shifts to electronically actuated alternatives with embedded intelligence.
- Thermal Expansion Valves:Bimetallic or bulb-sensing mechanical devices modulate refrigerant flow through pressure-temperature equilibrium without external power. These units dominate legacy installed bases and price-sensitive residential splits in India and Southeast Asia where technician familiarity reduces commissioning friction.
- Electronic Valves:Stepper motor-driven needle mechanisms with microcontroller-based superheat algorithms deliver sub-millimeter positioning resolution. Heat pump OEMs in Germany and China's eastern manufacturing corridor specify these for R32 and R290 systems where precise load matching satisfies tightening efficiency mandates.
- Variable Orifice Valves:Piston-actuated designs with continuous flow area adjustment bridge thermal and fully electronic architectures.
- Solenoid Valves:Binary on/off refrigerant switching for defrost cycles and compressor unloading sequences.
Today's leader: Electronic Valves. Tomorrow's challenger: Variable Orifice Valves.
End User:
Payback period sensitivity stratifies adoption velocity, with commercial operators recovering efficiency premiums fastest through continuous-duty cycles.
- Commercial:Supermarket chains and data center operators specify electronic valves for transcritical CO2 and low-GWP systems where energy costs dominate lifecycle economics. Japan's METI Top Runner program forces this segment's equipment refresh timelines.
- Industrial:Process cooling and cold storage facilities demand high-pressure-rated variants for ammonia and CO2 architectures with predictive maintenance integration.
- Residential:Split-system manufacturers in China face GB standard compliance costs that electronic valve premiums compress against total system price.
- Automotive:Electric vehicle thermal management modules require compact stepper motor designs for battery cooling circuits.
Commercial installations currently anchor procurement volume. Residential heat pump conversion in India and Brazil represents the steepest expansion trajectory.
Application:
Refrigerant transition timelines segment demand by pressure rating and flammability certification requirements.
- Heat Pumps:Air-source and geothermal systems require wide modulation range for seasonal coefficient optimization. German OEMs integrate these into pre-assembled refrigerant modules.
- Refrigeration:Commercial cold chain and supermarket racks drive CO2 transcritical valve demand under EU Green Deal decarbonization schedules.
- HVAC Systems:Variable refrigerant flow and chiller applications specify sensor-fused units with embedded superheat calculation.
- Chillers:Large-tonnage commercial and industrial cooling platforms favor modular valve arrays with centralized controller architectures.
Heat pump applications command the dominant revenue share. CO2 refrigeration systems are climbing fastest as ATEX certification bottlenecks clear.
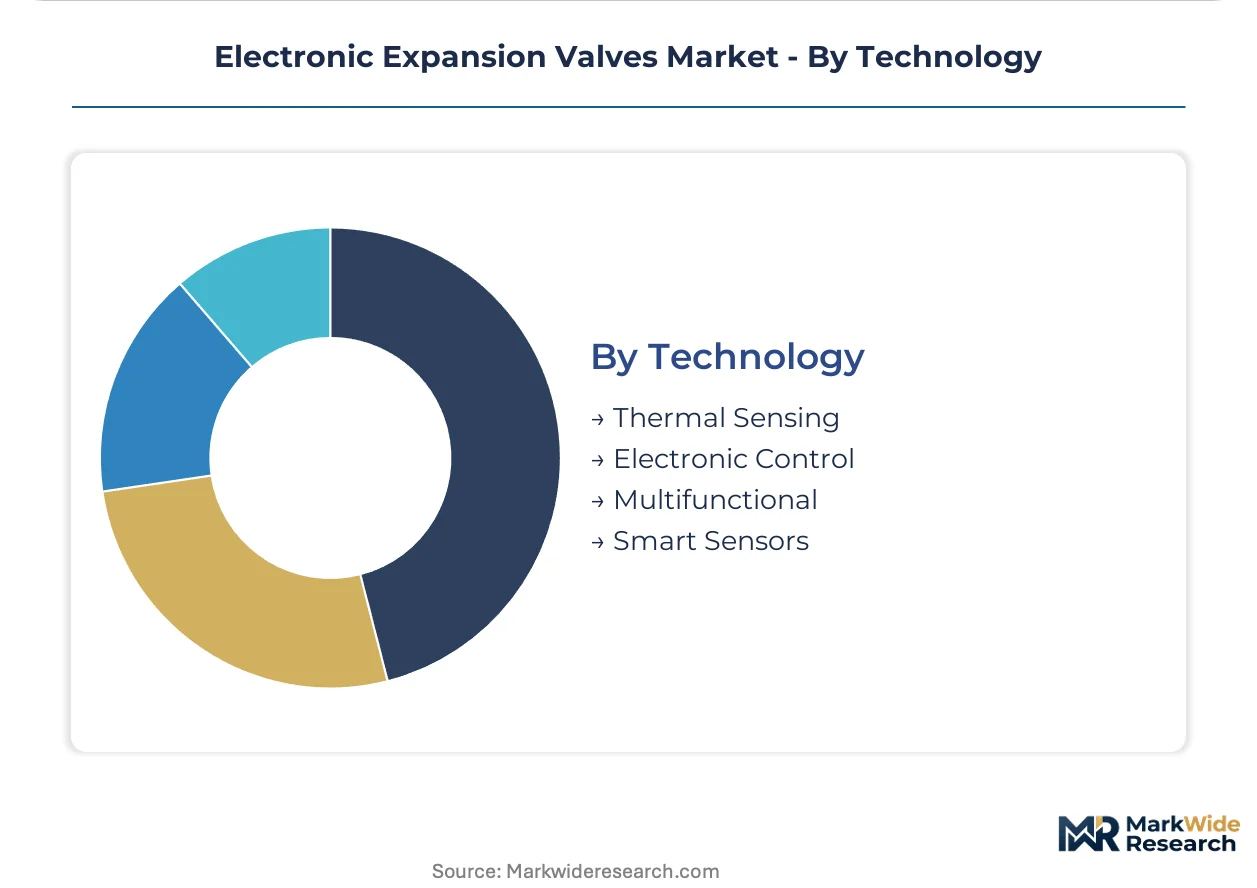
Technology:
Controller integration depth determines margin capture, with discrete mechanical components commoditizing fastest.
- Smart Sensors:Pressure-temperature transducers with IoT-enabled diagnostics and preemptive health monitoring create recurring service revenue streams. Japanese chiller manufacturers specify these for predictive maintenance contracts.
- Electronic Control:Microcontroller-driven stepper motor positioning with firmware-adjustable superheat setpoints.
- Multifunctional:Combined expansion, shutoff, and check valve operations in single housing for compact system designs.
- Thermal Sensing:Bulb-and-capillary temperature feedback without electronic actuation, residual in legacy maintenance markets.
Electronic Control architectures anchor current procurement. Smart Sensors are gaining share fastest as OEMs specify outcome-based service agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronic expansion valve production originated in Japanese precision manufacturing clusters during the 1980s, then migrated to German industrial automation corridors and China's eastern coastal manufacturing belt as HVAC electrification accelerated.
China
Heat pump OEMs in the Yangtze River Delta and Pearl River Delta are consolidating valve procurement into pre-integrated refrigerant modules. GB energy efficiency standards mandate precision superheat control for residential air-source heat pumps. Compressor module assemblers in Jiangsu and Zhejiang provinces now negotiate directly with valve suppliers, bypassing traditional HVAC equipment channels.
Germany
Heat pump manufacturers in Bavaria and Baden-Württemberg are scaling procurement of electronically actuated valves as building efficiency mandates tighten. The EU F-Gas Regulation phases down high-GWP refrigerants, forcing R32 and R290 compatibility redesigns. Industrial clusters around Stuttgart and Munich have reduced qualified valve suppliers from twelve to four vendors over three years.
Japan
Commercial chiller manufacturers in the Kanto and Kansai regions specify sensor-fused electronic expansion valves for variable refrigerant flow systems. METI Top Runner program mandates annual efficiency improvement targets that electronic superheat control enables. Equipment OEMs serving Tokyo and Osaka have compressed valve qualification timelines by half to meet 2026 product launch windows.
United States
Data center operators in Northern Virginia and Phoenix specify electronic valves for transcritical CO2 systems where energy costs dominate lifecycle economics. EPA SNAP program restrictions on high-GWP refrigerants accelerate thermal valve displacement. Supermarket chains in California and Texas are retrofitting cold storage racks with smart sensor-enabled valves for predictive maintenance integration.
India
Residential heat pump penetration remains minimal in cooling-dominated markets across Maharashtra and Gujarat. BIS efficiency labeling tightens as urban electrification expands, creating conversion opportunities for localized controller production. HVAC equipment distributors in Delhi-NCR and Bangalore face technician skill gaps that slow electronic valve commissioning.
Electronic Expansion Valves Market Vendor Landscape
Premium-margin players sit above commodity-margin players across controller-embedded versus discrete mechanical architectures. The supplier base stratifies into three tiers: vertically integrated specialists with captive stepper motor production, modular subsystem integrators bundling valves with compressors, and component assemblers sourcing motors and controllers externally. Dominant competitive moves include backward integration into stepper motor manufacturing and firmware development partnerships with HVAC OEMs.
Within the integrated manufacturing tier, Sanhua Holding Group and Danfoss exemplify contrasting geographic anchoring strategies. Zhejiang DUNAN Artificial Environment Co., Ltd. occupies a position bridging cost-optimized Asian supply and European certification standards. These three entities represent the archetype spectrum from scale-driven component supply to premium controller-embedded systems.
| Leading Market Players |
|---|
| Sanhua Holding Group |
| CAREL Industries S.p.A. |
| Danfoss |
| Saginomiya Seisakusho, Inc. |
| Zhejiang DUNAN Artificial Environment Co., Ltd. |
| Emerson Electric Co. |
| Fujikoki Corporation |
| Denso Corporation |
| Parker Hannifin Corporation |
| Others |
Supply Flow & Price Mechanics
Copper and neodymium pricing volatility in stepper motor windings propagates through three distinct valve tiers, with controller-embedded premiums widening against discrete mechanical alternatives as OEMs consolidate procurement into pre-integrated refrigerant modules.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates sensor-fused controller-embedded units from basic electronic actuation and residual thermal architectures. Certification grade for R290 flammability compliance and captive stepper motor production anchor premium capture, while cost compression in economy tiers intensifies because Asian residential heat pump OEMs negotiate module-level contracts. Commercial chiller manufacturers in Germany and Japan exhibit least price sensitivity; residential split-system distributors in India and Southeast Asia drive hardest bargain.
Supply Chain Analysis
Stepper motor supply rests on Chinese rare earth processing clusters, Japanese precision winding facilities, and German industrial automation corridors. Valve bodies draw from copper extrusion mills in Jiangsu province and Zhejiang stamping operations; controller PCBs source from Taiwanese semiconductor packaging. Single-source vulnerability concentrates in neodymium magnet supply from integrated rare earth processors. Distribution runs through compressor module assemblers in China's eastern manufacturing corridor, bypassing traditional HVAC equipment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electronic expansion valves market compounds steadily as building efficiency mandates across Japan, Germany, and China force displacement of thermal architectures with electronically actuated alternatives.
For Market Incumbents: Cement controller firmware and stepper motor production as defensive moats against modular subsystem integrators bundling valves with compressors. Capacity addition in Zhejiang province secures cost position for Asian residential heat pump supply; ATEX certification investment for R290 compatibility defends European commercial refrigeration share against emerging controller-embedded specialists. For New Entrants and Emerging Players: Enter via India's residential heat pump conversion as BIS efficiency labeling tightens and urban electrification expands, where localized controller production overcomes technician skill gaps slowing commissioning. Target supermarket chains in California and Texas retrofitting transcritical CO2 cold storage racks with predictive maintenance integration as the most penetrable application wedge. For Investors and Strategic Acquirers: Consolidation pressure builds where captive stepper motor production and firmware development capabilities concentrate margin capture away from component assemblers sourcing externally. Five-to-ten year viability favors vertically integrated specialists with backward integration into micro-actuator manufacturing; watch clearance of ATEX certification bottlenecks for R290-compatible portfolios as inflection signal for accelerated thermal valve obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stepper Motor Manufacturing | Captive micro-actuator supply secures positioning resolution and margin control against commodity motor vendors. |
| Sensor-Fused Valve Controller Development | Eliminates external controller boxes for Japanese and German variable refrigerant flow system specifications. |
| ATEX Certification for R290 Compatibility | Unlocks European commercial refrigeration and heat pump procurement under EU F-Gas Regulation phasedown timelines. |
| Localized Controller Production in India | Overcomes technician skill gaps and import cost barriers in residential heat pump conversion markets. |
| Predictive Maintenance Platform Integration | Creates recurring revenue through IoT-enabled diagnostics for supermarket chains and data center operators. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with heat pump OEM procurement directors, compressor module assembler supply chain managers, HVAC technician training coordinators, and refrigerant regulatory compliance officers with secondary validation through SEC filings of listed valve manufacturers, customs trade data on stepper motor imports, EPA SNAP program refrigerant phase-down schedules, and METI efficiency standard publications. Bottom-up equipment installation forecasts and top-down refrigerant transition modeling provided triangulation checks.
Segment-weighting across product type, end user, application, and technology dimensions shaped volume and value outputs throughout the forecast period. CAGRs derived from equipment replacement cycles, regulatory compliance deadlines, and OEM platform refresh timelines. Industry-specific inputs included GB standard implementation schedules for Chinese residential heat pumps and EU Green Deal decarbonization timelines for commercial refrigeration.
Inputs from OEM procurement directors and compressor module assemblers were available through the study window; gaps in technician certification infrastructure data introduce uncertainty bands around residential adoption velocity in India and Brazil. Forecasts reflect assumptions on refrigerant transition pace and flammability certification clearance timelines; regulatory acceleration or delay in Japan's METI program and EU F-Gas enforcement could materially revise trajectory. A small set of triggers—ATEX certification bottlenecks, copper-neodymium price spikes, and technician training program scale—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Choke and Kill Manifold Market
Valves
China Explosion-Proof Equipment Market
Valves
Float Traps Market
Valves
Global Compression Packing Market
Valves
Backflow Preventers Market
Valves
Sanitary Valves Market
Valves
Middle East and Africa Electro Hydraulic Servo Valve Market
Valves
Dense Phase Vessels Market
Valves
Expansion Valves Market
Valves
Global Marine Actuators and Valves Market
Valves
Stainless Steel Valve Tag Market
Valves
Global Stainless Steel Control Valves Market
Valves
Pipeline Strainers Market
Valves
Manual Control Valve Market
Valves
Pressure Control Equipment Market
Valves
Angle Opening Ball Locator Market