
 Malaysia Solar Energy Market | 2026-2036
Malaysia Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Solar Energy Market Foresight
Modular engineering, procurement, and construction bundling is consolidating buyer choice around turnkey solar solutions with embedded storage. Solarvest Holdings Berhad leverages its local EPC capabilities to anchor utility-scale project development across Peninsular Malaysia. LONGi Green Energy Technology Co Ltd. competes through monocrystalline wafer specialization and aggressive cost positioning in the distributed generation segment. TNB Engineering Corporation Sdn. Bhd. dominates grid interconnection infrastructure and transmission access for independent power producers.
Malaysia solar energy encompasses photovoltaic power generation systems that convert sunlight into electricity through semiconductor junctions, typically silicon cells with conversion efficiencies ranging from twenty to twenty-two percent for commercial modules. These installations serve industrial load offset, grid export revenue, and corporate renewable energy procurement objectives across tropical climates with high annual irradiance. Photovoltaic panels and solar inverters together constitute the core revenue pool, though battery storage systems represent the fastest-expanding segment as commercial users seek peak demand charge reduction. Utility-scale application growth outpaces residential deployment, driven by corporate power purchase agreements and the Energy Commission's large-scale solar auction program.
The Sustainable Energy Development Authority Malaysia administers feed-in tariff and net energy metering frameworks that determine project bankability and interconnection priority for distributed generators. The Energy Commission regulates licensing under the Electricity Supply Act, while BIS-equivalent standards govern module safety and inverter grid code compliance for equipment imported into the country. Stakeholders must monitor regulatory treatment of energy storage systems under existing tariff structures and anticipate how the national utility unbundling discussion affects third-party solar access to transmission networks.
Market Dynamics
Feed-in tariff revisions by SEDA Malaysia are compressing project returns and forcing developers toward merchant power structures and corporate power purchase agreements.
Growth Catalysts
- Net Energy Metering 3.0:Commercial and industrial facilities in Selangor leverage this framework to offset peak demand charges through behind-the-meter generation.
- Semiconductor manufacturing load growth:Fabrication plants in Kulim and Batu Kawan anchor gigawatt-scale renewable procurement to meet Scope 2 emissions targets.
- Monocrystalline PERC technology maturation:Module efficiency gains above twenty-one percent reduce land requirements for constrained rooftop deployments.
Market Restraints
- Polysilicon price volatility:Raw material cost swings from Xinjiang-based suppliers compress EPC margins on fixed-price contracts.
- Grid interconnection queuing:TNB Engineering Corporation processing delays extend project commissioning timelines for independent power producers.
- Land-use competition:Palm oil estates and solar developers compete for flat terrain in Johor, limiting utility-scale site availability.
Strategic Opportunities
- East Malaysia penetration:Sarawak and Sabah remain underserved for distributed generation despite high irradiance levels and rural electrification gaps.
- Battery-solar hybrid systems:Lithium-ion storage paired with photovoltaic arrays enables peak shaving for manufacturing facilities facing time-of-use tariffs.
- Green lane certification:SEDA Malaysia's expedited permitting for low-carbon building-integrated photovoltaics accelerates commercial adoption.
Industry Challenges
- Skilled installer shortage:Certified electrical contractors with medium-voltage experience remain concentrated in the Klang Valley, constraining nationwide deployment velocity.
- Legacy distribution network capacity:Rural substations in northern Perak and Kelantan require reinforcement to absorb reverse power flows from agricultural solar installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Solar Energy Market |
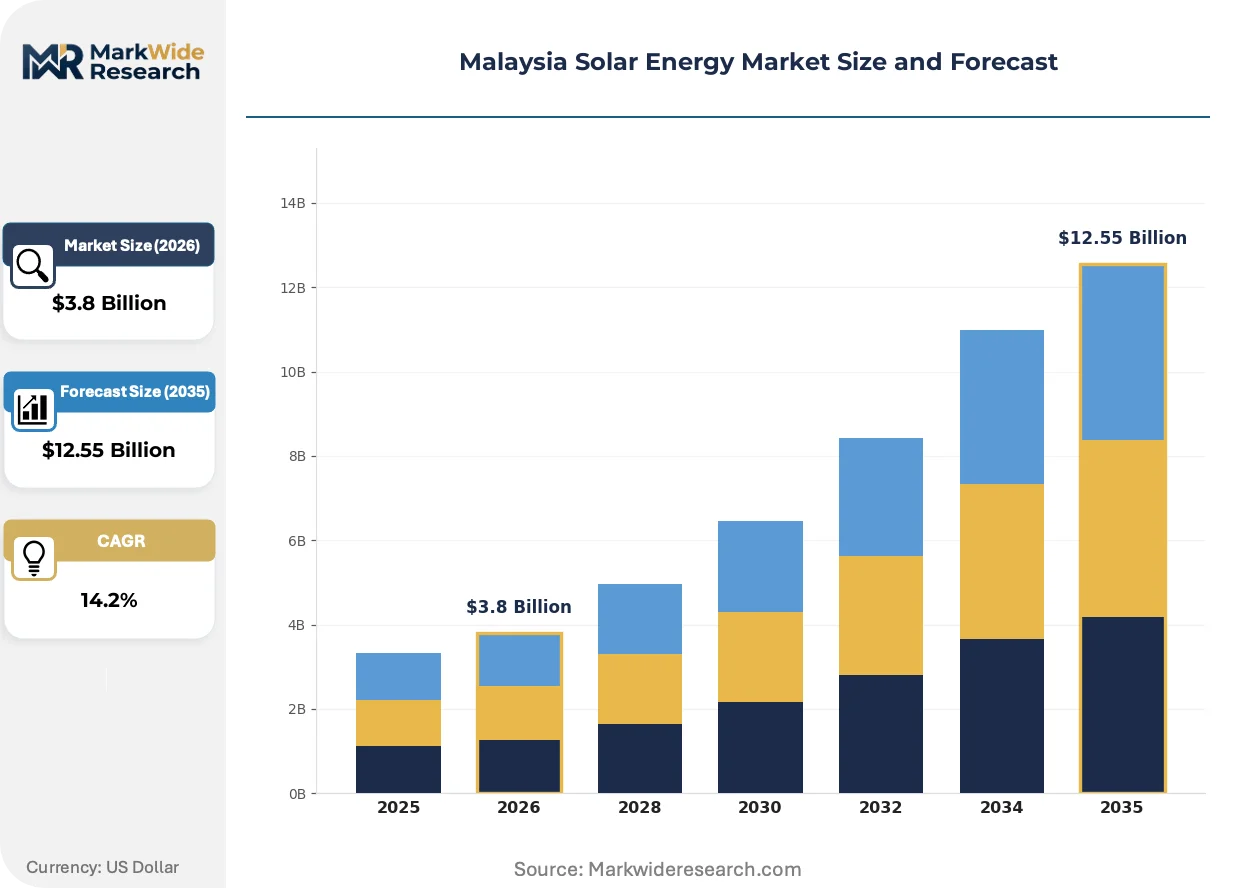
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Solar Inverters, Battery Storage Systems, Mounting Structures Application: Residential, Commercial, Industrial, Utility-Scale End User: Households, Businesses, Government, Energy Producers Installation Type: Rooftop, Ground-mounted, Hybrid Systems, Off-grid |
| Companies Covered | Canadian Solar Inc., First Solar Inc., Solarvest Holdings Berhad, LONGi Green Energy Technology Co Ltd., SunPower Corporation, JA Solar Technology Co., Ltd., Northern Solar Holdings Bhd, JinkoSolar Holding Co Ltd., TNB Engineering Corporation Sdn. Bhd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Solar Energy Market Shifts & Advancements
Module-level power electronics and artificial intelligence-driven performance optimization are restructuring how asset owners extract value from photovoltaic installations.
Bifacial solar modules with transparent back sheets are capturing reflected irradiance from rooftops and ground-mounted systems. Industrial offtakers in Penang and Johor Bahru are specifying these configurations for carport and warehouse applications. This technology is converging with floating solar platforms on water treatment reservoirs to unlock generation capacity without land competition.
SEDA Malaysia's revision of technical codes for energy storage interconnection is forcing inverter manufacturers to certify grid-forming capabilities. The new standards mandate frequency-watt and volt-watt response functions for systems above one megawatt. Commercial and industrial developers in Selangor are front-loading battery procurement to secure grandfathered interconnection agreements before code enforcement deadlines.
Aggregated virtual power plant models are displacing traditional net metering for commercial portfolios. Platform operators pool distributed assets and bid into ancillary service markets through TNB's grid operator. Manufacturing estates in Shah Alam and Pasir Gudang are piloting this structure to monetize flexible load alongside solar generation.
Malaysia Solar Energy Market Segmentation
Segmentation reveals where capital deployment concentrates and which technology configurations match Malaysia's regulatory incentives. Equipment choices and installation approaches determine project bankability under SEDA Malaysia's evolving tariff frameworks.
Product Type:
Capital intensity varies sharply across equipment categories, with integrated storage systems demanding the highest upfront outlays.
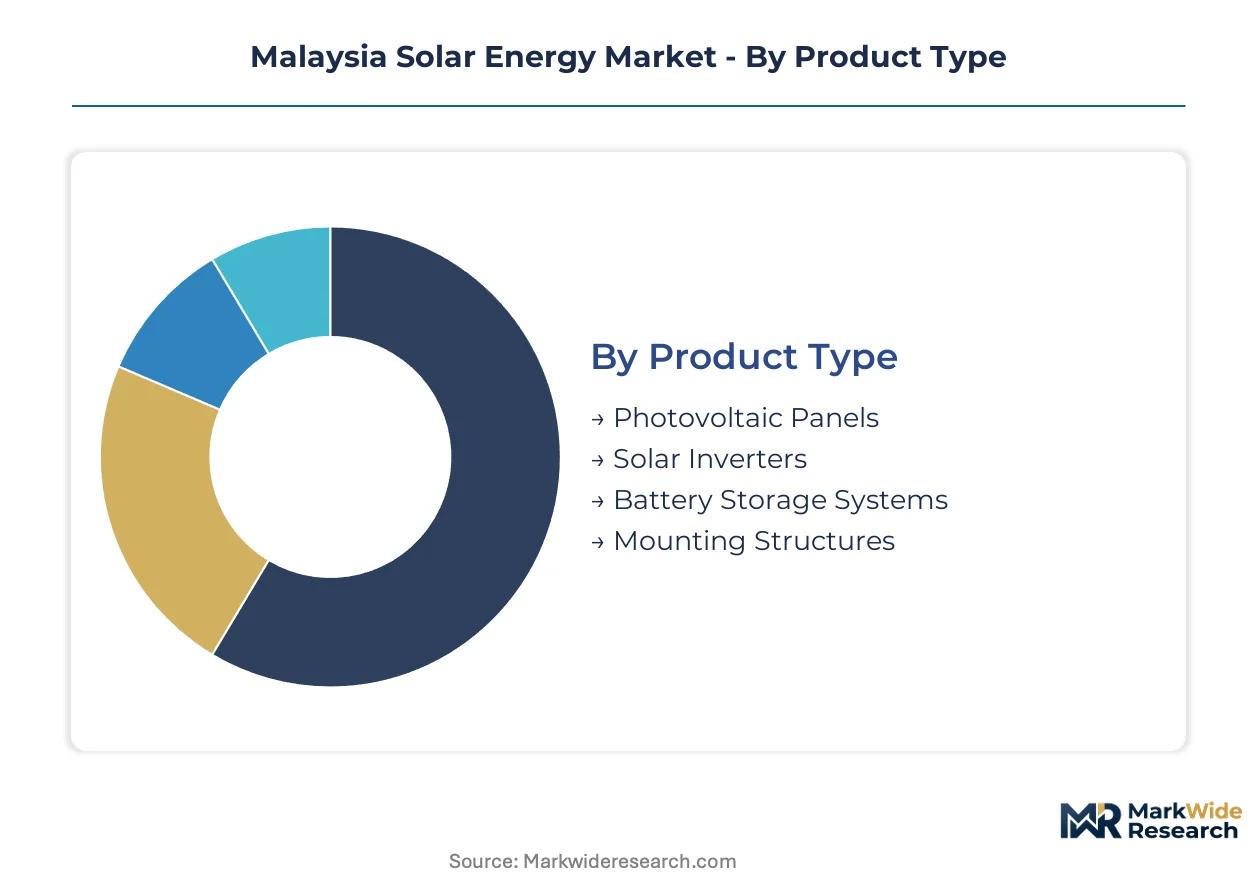
- Photovoltaic Panels:Monocrystalline PERC and TOPCon cells dominate commercial procurement, with conversion efficiencies above twenty-one percent reducing land requirements for constrained Selangor rooftops. Manufacturing facilities in Penang and Johor specify these modules for twenty-five-year power purchase agreements.
- Battery Storage Systems:Lithium-ion phosphate configurations paired with photovoltaic arrays enable peak demand charge reduction for industrial offtakers facing time-of-use tariffs. SEDA Malaysia's revised technical codes mandate grid-forming inverters for systems above one megawatt, accelerating certification timelines.
- Solar Inverters:String and central inverter architectures govern DC-to-AC conversion efficiency and grid code compliance under TNB interconnection standards.
- Mounting Structures:Aluminum and galvanized steel racking systems anchor modules to rooftops and ground-mounted installations across Peninsular Malaysia's tropical climate zones.
Most installed capacity flows through Photovoltaic Panels. Expansion is steepest in Battery Storage Systems.
Application:
Project scale determines financing structures, with utility-scale developments accessing institutional capital unavailable to smaller installations.
- Utility-Scale:Grid-connected installations above fifty megawatts compete in Energy Commission large-scale solar auctions, securing fixed tariffs over twenty-one-year contract periods. Independent power producers in Kedah and Pahang anchor gigawatt-scale pipelines through corporate renewable energy procurement.
- Industrial:Behind-the-meter generation at manufacturing estates in Shah Alam and Pasir Gudang offsets peak demand charges through Net Energy Metering 3.0 frameworks. Semiconductor fabrication plants in Kulim drive gigawatt-scale procurement to meet Scope 2 emissions targets.
- Commercial:Office buildings and retail centers leverage net metering for electricity cost stabilization under escalating TNB tariff schedules.
- Residential:Single-family installations remain constrained by rooftop space limitations and financing access in suburban Kuala Lumpur and Johor Bahru.
Utility-scale deployments absorb the majority of capital formation. Industrial applications are gaining share fastest as manufacturing load growth accelerates.
End User:
Customer type shapes procurement sophistication, with energy producers and large businesses driving standardized contract terms.
- Energy Producers:Independent power producers and TNB subsidiaries develop merchant and contracted assets, securing transmission access through TNB Engineering Corporation interconnection queues. These entities dominate utility-scale auction participation and corporate power purchase agreement origination.
- Businesses:Manufacturing conglomerates and logistics operators specify turnkey engineering-procurement-construction contracts with embedded performance guarantees. Selangor and Johor manufacturing estates anchor the majority of commercial and industrial deployment.
- Government:Federal and state agencies procure solar for public buildings and rural electrification programs in underserved East Malaysia regions.
- Households:Individual consumers face higher per-watt installed costs due to fragmented installation volumes and limited financing products.
Energy Producers command the largest aggregate capacity. Business procurement is expanding most quickly as corporate renewable energy targets harden.
Installation Type:
Site configuration determines land-use intensity and grid interconnection complexity, with hybrid systems requiring the most specialized engineering.
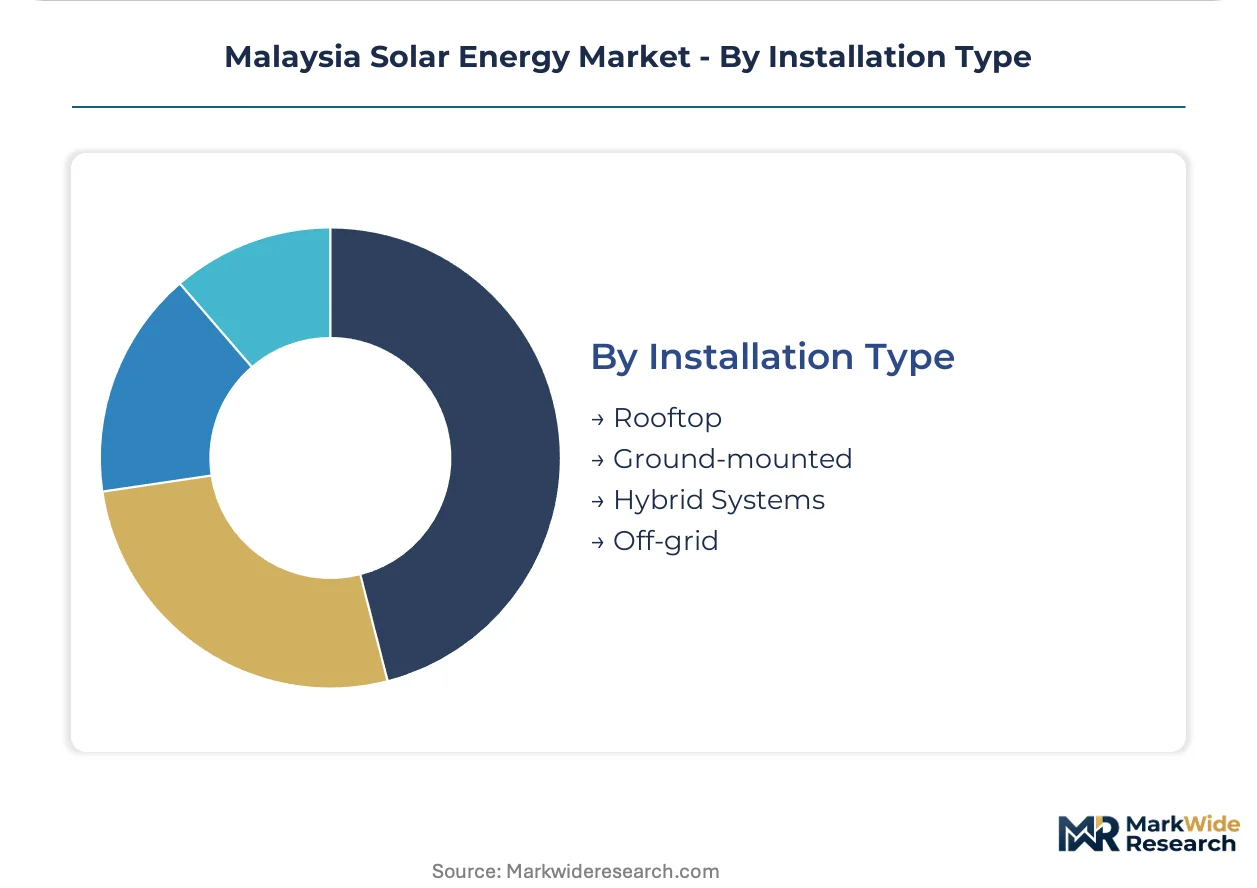
- Rooftop:Building-integrated and building-applied systems dominate commercial and industrial deployment across Peninsular Malaysia's manufacturing estates. SEDA Malaysia's Green Lane certification expedites permitting for low-carbon building-integrated photovoltaics in Selangor commercial zones.
- Ground-mounted:Fixed-tilt and tracking arrays occupy flat terrain in Johor and Kedah, competing with palm oil estates for land availability. These installations serve utility-scale auction winners and corporate offtakers with large electricity loads.
- Hybrid Systems:Battery-solar configurations with grid-forming capabilities enable virtual power plant participation and ancillary service market bidding.
- Off-grid:Standalone systems with diesel backup serve rural electrification gaps in Sarawak and Sabah, where TNB grid extension remains uneconomical.
Ground-mounted arrays carry the majority of megawatt-scale additions. Hybrid systems are climbing the fastest as storage economics improve under revised tariff structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's solar industry traces its commercial scale-up to the 2011 introduction of the feed-in tariff mechanism, which channeled early investment toward Peninsular Malaysia's manufacturing corridors. State-level policy variation and industrial load concentration now determine where capacity additions cluster.
Selangor
Semiconductor fabrication plants and logistics hubs in Shah Alam and Klang anchor the highest concentration of commercial rooftop installations. The Sustainable Energy Development Authority Malaysia's Green Lane certification expedites permitting for building-integrated photovoltaics in designated industrial zones. Manufacturing estates in Port Klang and Subang Jaya are aggregating distributed assets into virtual power plant configurations for ancillary service market participation.
Johor
Iskandar Malaysia's special economic status attracts corporate power purchase agreement offtakers seeking renewable energy certificates for export manufacturing compliance. Land-use competition between palm oil estates and ground-mounted solar developers constrains utility-scale site availability in the southern corridor. Pasir Gudang industrial zones are piloting battery-solar hybrid systems to reduce peak demand charges under time-of-use tariff structures.
Penang
Kulim's high-tech park hosts gigawatt-scale renewable procurement from semiconductor fabs pursuing Scope 2 emissions targets. The state's electronics manufacturing heritage creates sophisticated buyer sophistication for performance-guaranteed engineering-procurement-construction contracts. Bayan Lepas industrial clusters are specifying bifacial modules for carport and warehouse rooftop applications.
Kedah
Large-scale solar auction winners occupy flat agricultural terrain in the northern rice bowl region, securing twenty-one-year fixed tariffs from the Energy Commission. Grid interconnection queuing through TNB Engineering Corporation extends commissioning timelines for independent power producers. Alor Setar and Sungai Petani are emerging as logistics nodes for module distribution to northern Peninsular Malaysia.
Sarawak
Rural electrification gaps and high equatorial irradiance levels create distributed generation opportunities underserved by TNB grid extension. The state's autonomous electricity regulatory framework under Sarawak Energy Berhad permits alternative procurement structures unavailable in Peninsular Malaysia. Kuching and Miri industrial zones are exploring standalone solar-diesel hybrid systems for remote manufacturing facilities.
Malaysia Solar Energy Market Competitive Landscape
The competitive structure tilts toward integrated engineering-procurement-construction providers with captive development pipelines. Market concentration remains moderate, with distinct tiers separating utility-scale auction participants from distributed generation specialists. Two archetypes dominate: vertically integrated Chinese manufacturers leveraging module cost positions, and local EPC firms with regulatory navigation expertise. Competitive intensity manifests through strategic partnerships securing interconnection priority and portfolio diversification into storage-integrated offerings.
Among Malaysia-based developers, Solarvest Holdings Berhad exemplifies the local EPC archetype with turnkey project execution capabilities across Peninsular Malaysia. TNB Engineering Corporation Sdn. Bhd. occupies a structural position controlling grid access for independent power producers. LONGi Green Energy Technology Co Ltd. represents the Chinese manufacturing tier competing through monocrystalline specialization in the distributed generation segment.
| Leading Market Players |
|---|
| Canadian Solar Inc. |
| First Solar Inc. |
| Solarvest Holdings Berhad |
| LONGi Green Energy Technology Co Ltd. |
| SunPower Corporation |
| JA Solar Technology Co., Ltd. |
| Northern Solar Holdings Bhd |
| JinkoSolar Holding Co Ltd. |
| TNB Engineering Corporation Sdn. Bhd. |
| Others |
Supply & Pricing Matrix
State-linked utility subsidiaries and independent power producers anchor procurement discipline across Peninsular Malaysia, translating captive grid access into pricing power for engineering-procurement-construction bundles. This ownership pattern feeds directly into supply behavior, where developers prioritize module cost predictability over spot-market flexibility to preserve project bankability under SEDA Malaysia's tariff frameworks.
Pricing Analysis
Project-based long-term offtake contracts dominate utility-scale solar economics, with pricing stratifying across premium, standard, and economy tiers based on module efficiency certification and EPC performance guarantees. Cost compression in the standard tier intensifies because polysilicon volatility from Xinjiang-based suppliers compresses fixed-price contract margins. Industrial offtakers in Selangor manufacturing estates exhibit the lowest price sensitivity, prioritizing grid-forming inverter certification and twenty-five-year performance warranties over per-watt capital expenditure minimization.
Supply Chain Analysis
Direct-to-IPP channels handle hyperscale buyer demand for monocrystalline PERC and TOPCon modules, bypassing distributor markups for auction winners and corporate PPA offtakers. Manufacturing concentrates in China, Vietnam, and Malaysia's own Kulim high-tech park, with wafer and cell production drawing from polysilicon feedstock anchored in Xinjiang and Inner Mongolia. Single-source vulnerability in metallurgical-grade silicon refining creates exposure to trade remedy investigations and forced-labor due diligence requirements. Distribution runs through TNB Engineering Corporation interconnection queues, which gate project commissioning timelines regardless of module availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia solar energy functions as a stable compounder, with Net Energy Metering 3.0 policy continuity and semiconductor manufacturing load growth providing durable demand visibility across the analysis window.
For Market Incumbents: Lock in interconnection priority through TNB Engineering Corporation queue positioning before SEDA Malaysia's revised technical codes trigger recertification requirements for grid-forming inverters. Deepen backward integration into battery storage system assembly to capture margin pools shifting from module supply to integrated hybrid configurations, defending against Chinese manufacturers expanding downstream into turnkey EPC services. For New Entrants and Emerging Players: Local electrical contractors with medium-voltage certification represent the most accessible channel partner type for bypassing incumbent EPC relationships in underserved East Malaysia. Sarawak and Sabah distributed generation gaps, where TNB grid extension remains uneconomical and Sarawak Energy Berhad permits alternative procurement structures, offer the most penetrable geography. Target standalone solar-diesel hybrid systems for remote industrial facilities as the initial go-to-market wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap EPC specialists with captive development pipelines but limited balance sheet scale for utility-scale auction participation. Long-term viability hinges on storage integration capabilities and regulatory navigation expertise rather than pure module cost positioning. Watch SEDA Malaysia's treatment of energy storage systems under evolving tariff structures as the inflection signal for portfolio reallocation toward battery-solar hybrid developers.| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Forming Inverter Certification | SEDA Malaysia's revised technical codes mandate frequency-watt response for systems above one megawatt, accelerating compliance investment. |
| East Malaysia Geographic Expansion | Sarawak Energy Berhad's autonomous regulatory framework permits procurement structures unavailable under Peninsular Malaysia's TNB-dominated grid. |
| Virtual Power Plant Aggregation | Platform operators pool Shah Alam and Pasir Gudang distributed assets for ancillary service bidding through TNB's grid operator. |
| Battery-Solar Hybrid System Buildout | Lithium-ion phosphate configurations enable peak shaving for manufacturing facilities facing time-of-use tariffs under Net Energy Metering 3.0. |
| Green Lane Certification Program | SEDA Malaysia's expedited permitting for low-carbon building-integrated photovoltaics accelerates commercial adoption in Selangor industrial zones. |
Research Methodology
Bottom-up industrial load modeling reconciled against top-down module shipment tracking forms the analytical core of this study. Primary interviews with IPP project developers, EPC contractors, TNB grid planning officers, and SEDA Malaysia regulatory affairs specialists combine with secondary validation from Energy Commission auction results, SEDA Malaysia feed-in tariff registry data, and customs import records for photovoltaic equipment. This dual-structure approach captures both demand-side procurement intentions and supply-side equipment flows.
Historical trendline analysis of installed capacity additions and tariff regime transitions informs the projection framework across the modeling period. Segmentation dimensions include generation capacity tier, project scale, regulatory framework, and regional grid type, with CAGRs derived from regression analysis of auction award volumes and net metering application trajectories. Forecast inputs incorporate semiconductor fabrication plant expansion timelines and SEDA Malaysia policy revision schedules.
Revisions become necessary when feed-in tariff mechanism overhauls, polysilicon trade restrictions, or TNB unbundling discussions materialize beyond current policy baselines. Forecasts reflect documented assumptions regarding interconnection queue processing rates and module efficiency improvement curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Italy Distributed Solar Power Generation Market
Solar Power Systems
Europe Solar Blanket Market
Solar Power Systems
Ecuador Solar Energy Market
Solar Power Systems
Turkey Solar Energy Market
Solar Power Systems
Egypt Solar Energy Market
Solar Power Systems
India Solar Tracker Market
Solar Power Systems
Photovoltaic Solar Kits Market
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
PERC Solar Cell Market
Solar Power Systems
Czech Republic Solar Energy Market
Solar Power Systems
Flexible Solar Panel Market
Solar Power Systems
Organic PV Solar Cells Market
Solar Power Systems
Solar Metal Roof Market
Solar Power Systems
GCC Solar Microinverter Market
Solar Power Systems
Crystalline Silicon Solar PV Market