
 Trinidad and Tobago Solar Energy Market | 2026-2036
Trinidad and Tobago Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Trinidad and Tobago Solar Energy Market Analytics
Aftermarket service revenue for inverter maintenance and battery replacement is fragmenting across independent technicians and original equipment providers. NGC Green leverages its natural gas infrastructure relationships to anchor utility-scale project development. Lightsource bp competes through international photovoltaic deployment expertise transferred to Caribbean conditions. Resscott Ltd specializes in residential system integration and local workforce training.
Trinidad and Tobago solar energy encompasses photovoltaic electricity generation systems typically rated from kilowatt residential arrays to multi-megawatt utility installations, utilizing monocrystalline or polycrystalline silicon cells with DC-to-AC conversion efficiencies between 18% and 22%. These systems reduce fossil fuel import dependency for an economy historically dominated by hydrocarbon exports. Photovoltaic panels occupy the largest product category by installed capacity, though battery storage attachments are deepening margin pools as grid instability drives backup demand. The utility-scale application segment leads absolute deployment volumes, while commercial rooftop systems represent the fastest-growing subcategory as businesses hedge against volatile electricity tariffs.
The Trinidad and Tobago Electricity Commission regulates grid interconnection standards under the Renewable Energy Rider, while the Ministry of Energy and Energy Industries oversees national renewable energy target compliance and fiscal incentive structures. These frameworks shape project bankability by defining feed-in tariff eligibility and technical compliance pathways. Stakeholders must monitor regulatory momentum around energy storage mandates and distributed generation caps as policy evolves to accommodate higher renewable penetration rates.
Market Dynamics
The Renewable Energy Rider framework from the Trinidad and Tobago Electricity Commission is compressing interconnection timelines from years to months, fundamentally restructuring how distributed generators enter commercial operation and reshaping competitive positioning among developers.
Growth Catalysts
- Commercial tariff volatility:Manufacturing facilities and cold storage operators in Point Lisas are deploying rooftop photovoltaic systems to hedge against electricity price swings. The industrial load profile of these facilities matches solar generation curves effectively.
- Renewable Energy Rider:This regulatory mechanism from the Trinidad and Tobago Electricity Commission streamlines technical review processes and standardizes grid connection protocols for systems under one megawatt.
- Natural gas infrastructure leverage:Existing pipeline rights-of-way and substation access from the hydrocarbon sector are accelerating site preparation for utility-scale photovoltaic installations.
Market Restraints
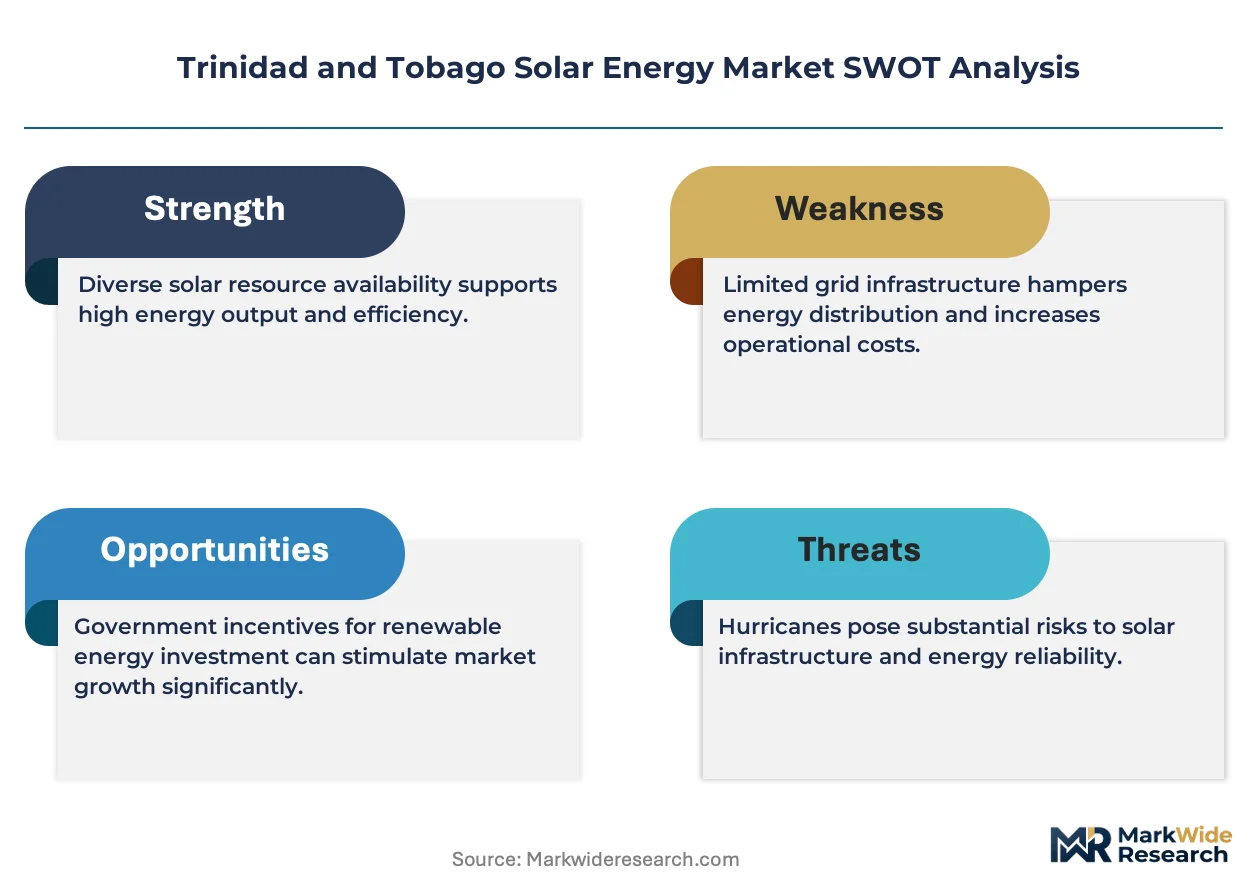
- Import dependency for photovoltaic modules:Trinidad and Tobago lacks domestic silicon cell manufacturing, exposing project economics to freight cost volatility and currency fluctuation against Asian supplier currencies.
- Grid absorption limits:The national electricity network's spinning reserve capacity constrains instantaneous renewable injection, forcing curtailment during peak generation periods.
- Financing cost premiums:Local commercial lenders apply risk spreads to renewable energy loans that exceed hydrocarbon project benchmarks, compressing developer equity returns.
Strategic Opportunities
- Energy storage convergence:Coupling lithium-ion battery systems with existing photovoltaic installations creates ancillary service revenue streams through frequency regulation and voltage support.
- Residential penetration gaps:Single-family households in eastern Trinidad remain underserved relative to commercial and utility segments, presenting untapped demand for rooftop leasing models.
- Workforce localization mandates:Government training subsidies for photovoltaic technician certification are lowering labor cost structures for installation contractors.
Industry Challenges
- Certification bottlenecks:Trinidad and Tobago Bureau of Standards compliance testing for imported inverters creates procurement delays averaging eight weeks beyond shipping timelines.
- Interconnection queue management:The Trinidad and Tobago Electricity Commission's technical review staff capacity limits simultaneous processing of multiple distributed generation applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trinidad and Tobago Solar Energy Market |
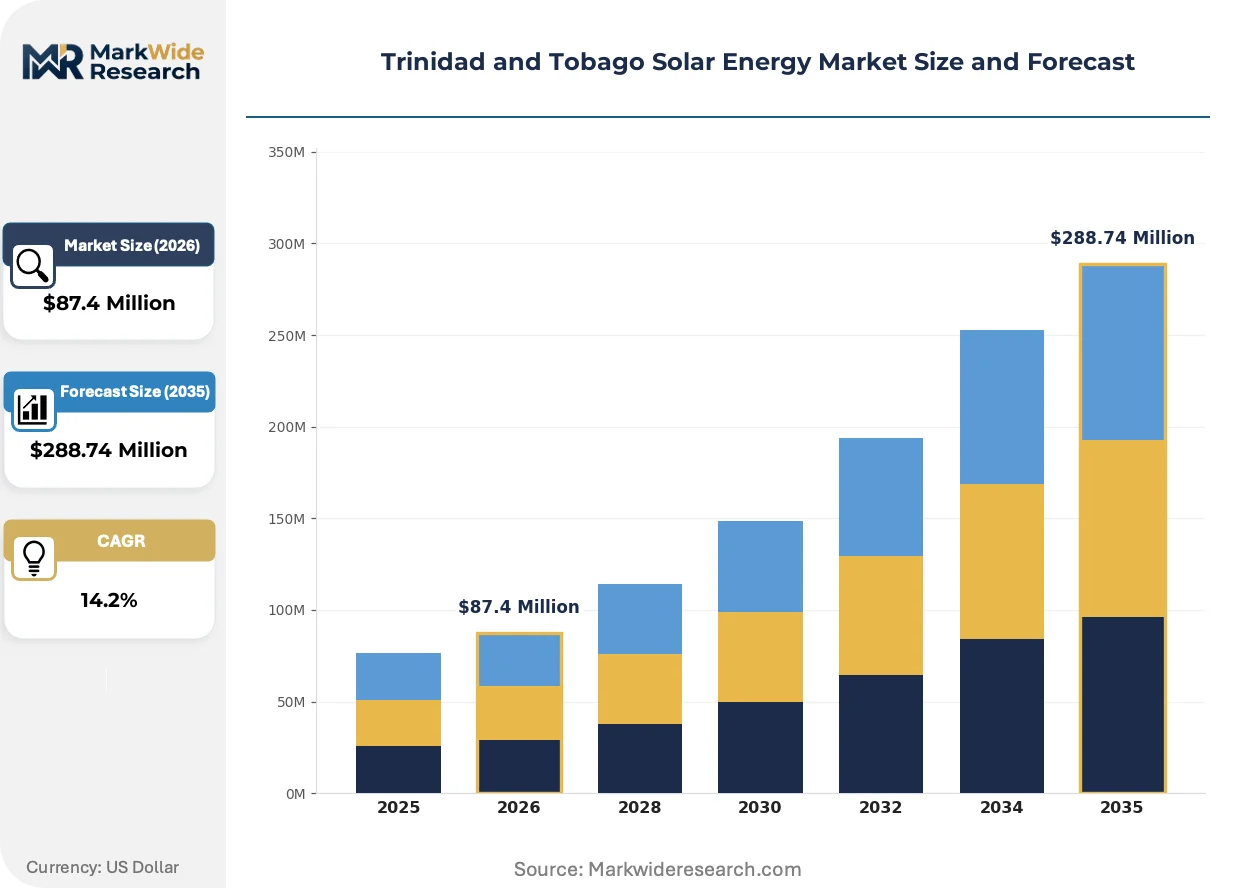
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $288.74 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Inverters, Batteries, Mounting Structures Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Application: Residential, Commercial, Industrial, Utility-Scale Deployment: On-Grid, Off-Grid, Hybrid, Community Solar |
| Companies Covered | NGC Green, Resscott Ltd, Lightsource bp, Trifactor Technical Sales and Services Ltd, AMBA Energy Limited, bp Alternative Energy Trinidad and Tobago, SolarWorld-tt, AIMS Power, Shell Renewables Caribbean, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trinidad and Tobago Solar Energy Market Evolving Landscape
Photovoltaic system economics in Trinidad and Tobago are being restructured by three concurrent forces: module efficiency improvements, regulatory process acceleration, and commercial buyer sophistication. These shifts are compressing project development cycles and altering competitive dynamics across the value chain.
Monocrystalline PERC cell technology is collapsing the installed cost per watt for commercial rooftop systems. Cold storage operators in the southwestern industrial corridor are adopting these higher-efficiency modules to maximize generation from limited roof areas. The technology is collapsing the economic threshold for behind-the-meter solar deployment, enabling smaller facilities to achieve viable payback periods.
The Renewable Energy Rider from the Trinidad and Tobago Electricity Commission has eliminated case-by-case interconnection negotiations for standard distributed generation configurations. This regulatory shift reduces legal and engineering soft costs that previously consumed twelve to eighteen months of project timelines. Commercial developers are responding by standardizing system designs to qualify for expedited approval pathways.
Power purchase agreement structures are displacing direct equipment ownership among manufacturing facilities. Industrial buyers in Port of Spain are contracting with third-party operators who retain asset ownership and assume performance risk. This financing innovation is most visible in the metropolitan corridor, where balance sheet constraints previously blocked captive solar investment.
Trinidad and Tobago Solar Energy Market Segmentation
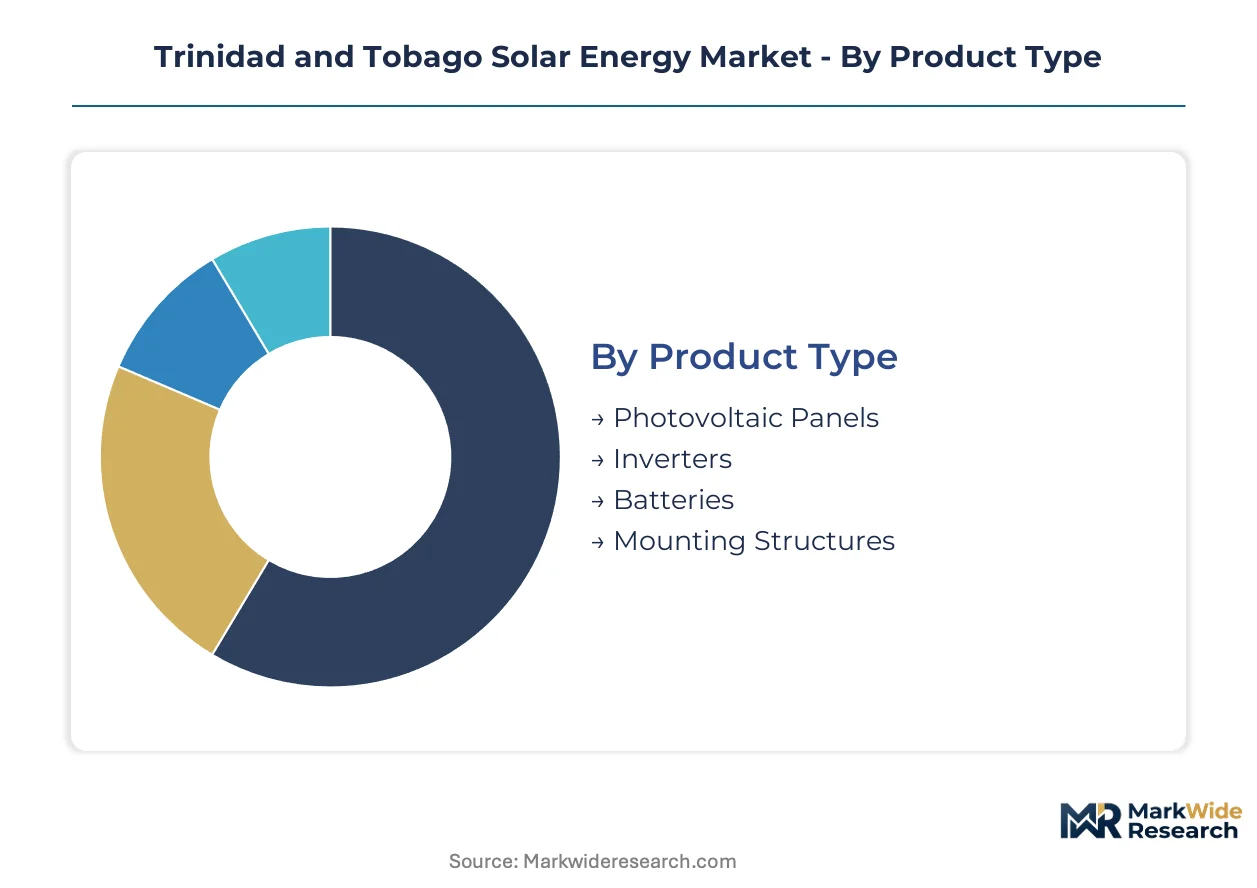
Segmentation in the Trinidad and Tobago solar energy market reveals distinct procurement cycles and margin structures across hardware categories and deployment models. Understanding these patterns enables suppliers to align inventory and service capabilities with actual demand velocity.
Product Type:
Photovoltaic panels turn over fastest due to standardized procurement and rapid project commissioning, while batteries cycle slowest given extended engineering and integration timelines.
- Photovoltaic Panels:Silicon-based modules rated 18-22% conversion efficiency dominate hardware procurement volumes. Manufacturing facilities in Point Lisas and cold storage operators across the southwestern industrial corridor specify monocrystalline variants to maximize generation density on constrained roof areas.
- Inverters:DC-to-AC conversion equipment with string or central architectures determines system performance reliability. The Trinidad and Tobago Bureau of Standards mandates eight-week compliance testing for imported units, creating procurement bottlenecks that slow project timelines.
- Batteries:Lithium-ion storage systems coupled with photovoltaic installations enable frequency regulation and voltage support services. Grid instability in the Port of Spain metropolitan corridor drives backup demand from commercial buyers seeking tariff arbitrage and resilience.
- Mounting Structures:Racking systems engineered for Caribbean wind loads and corrosion resistance complete hardware packages. Local fabrication capacity remains limited, forcing reliance on imported aluminum and steel assemblies.
Photovoltaic panels anchor the volume base while batteries gain share at the steepest rate.
Technology:
Cost tiers separate premium cell architectures from commodity alternatives, with efficiency premiums commanding differential pricing in space-constrained applications.
- Monocrystalline:PERC cell technology achieves highest conversion efficiencies and commands price premiums from commercial rooftop developers. Cold storage operators in Point Lisas prioritize these modules to offset volatile electricity tariffs within limited roof footprints.
- Polycrystalline:Lower-cost multicrystalline silicon cells serve price-sensitive utility-scale procurement where land availability reduces efficiency constraints. NGC Green incorporates these modules in pipeline-adjacent installations leveraging existing substation infrastructure.
- Thin-Film:Cadmium telluride and amorphous silicon alternatives suit high-temperature environments with reduced efficiency degradation. Limited local deployment experience constrains adoption.
- Bifacial:Dual-sided generation modules capture reflected irradiance from rooftops and ground surfaces. Early pilots in the Port of Spain corridor demonstrate yield improvements that justify procurement premiums.
Polycrystalline technology captures the largest deployment volumes while monocrystalline PERC expands most quickly in commercial segments.
Application:
Customer type determines financing structures and risk allocation, with industrial buyers leveraging balance sheet capacity distinct from residential payment constraints.
- Residential:Single-family rooftop systems typically rated 3-10 kilowatts serve eastern Trinidad households underserved relative to commercial segments. Resscott Ltd targets this penetration gap through leasing models that eliminate upfront capital requirements.
- Commercial:Behind-the-meter installations at manufacturing and cold storage facilities hedge against tariff volatility. The Renewable Energy Rider framework compresses interconnection timelines from years to months for sub-megawatt systems.
- Industrial:Multi-megawatt captive generation serves energy-intensive processing operations with load profiles matching solar generation curves. Point Lisas petrochemical complexes evaluate photovoltaic integration against natural gas price benchmarks.
- Utility-Scale:Grid-connected installations exceeding one megawatt feed centralized generation into the national network. The Trinidad and Tobago Electricity Commission manages technical review queues that constrain simultaneous project processing.
Utility-scale deployment anchors absolute capacity additions while commercial rooftop systems climb the fastest.
Deployment:
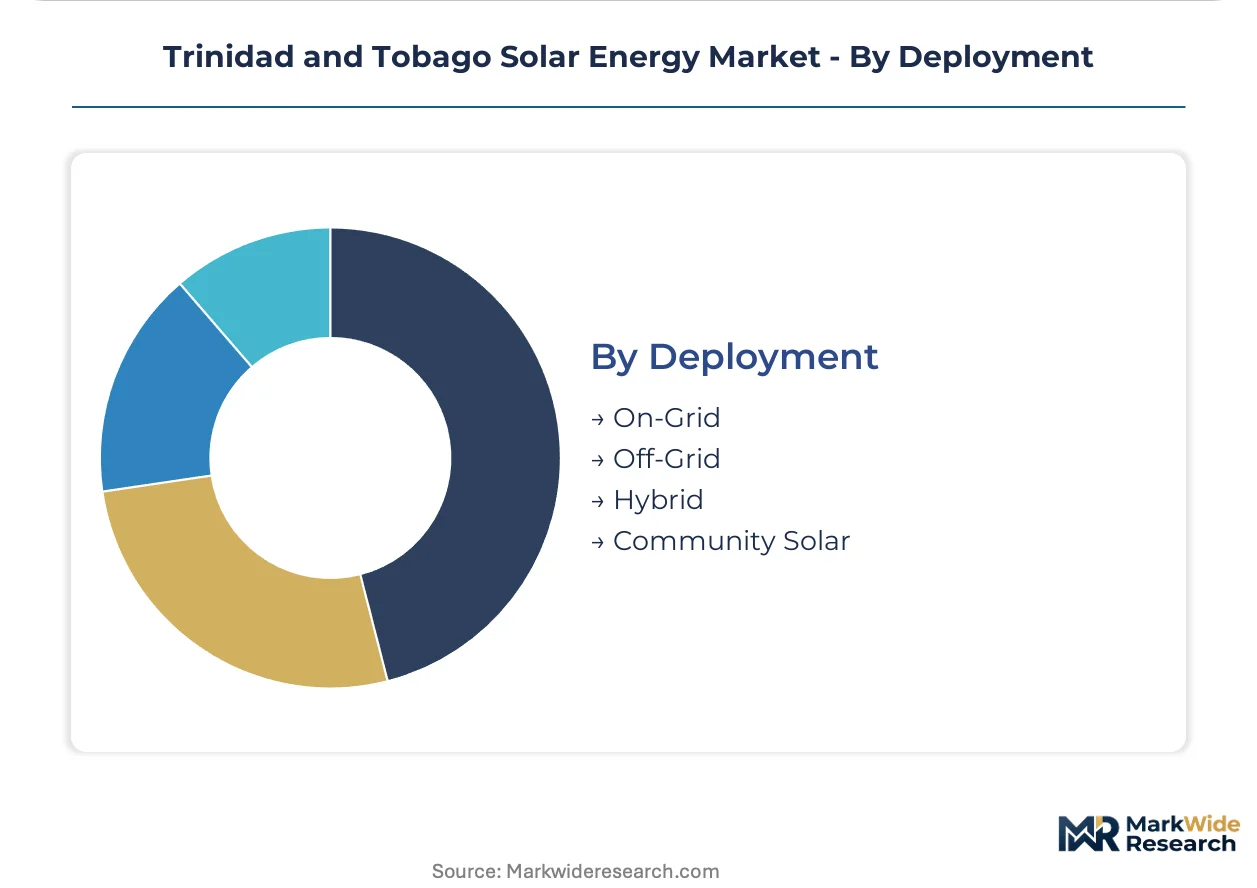
Grid connection status shapes regulatory pathway complexity and revenue model design, with on-grid systems accessing standardized tariffs unavailable to isolated configurations.
- On-Grid:Systems interconnected under the Renewable Energy Rider framework qualify for expedited approval and feed-in tariff eligibility. Standardized technical protocols reduce soft costs previously consuming twelve to eighteen months.
- Off-Grid:Standalone installations serve remote facilities beyond distribution network reach. Eastern Trinidad agricultural operations and isolated industrial sites rely on diesel hybrid backup given grid extension economics.
- Hybrid:Grid-connected systems with battery backup enable peak shaving and resilience during network outages. Frequency regulation services create ancillary revenue streams through grid operator contracts.
- Community Solar:Shared generation assets allow multiple subscribers to access renewable energy without individual rooftop installation. Regulatory frameworks for virtual net metering remain under development by the Ministry of Energy and Energy Industries.
On-grid deployment dominates current capacity while hybrid configurations gain share fastest as storage costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Trinidad and Tobago's solar market. Commercial buyers in Point Lisas absorb price premiums for resilience, while residential households in eastern districts remain highly price-sensitive to upfront capital requirements.
Port of Spain Metropolitan Corridor
Financial services firms and government buildings drive rooftop demand in the capital district. The Trinidad and Tobago Electricity Commission's Renewable Energy Rider framework expedites interconnection approvals for sub-megawatt systems here. Downtown commercial towers and westward suburban office parks concentrate the nation's highest density of behind-the-meter photovoltaic installations.
Southwestern Industrial Zone
Petrochemical complexes and cold storage operators anchor utility-scale procurement in the Point Lisas area. The Ministry of Energy and Energy Industries oversees fiscal incentive structures that shape project bankability for these energy-intensive users. Manufacturing facilities along the industrial corridor leverage existing natural gas infrastructure for accelerated site preparation.
Eastern Trinidad
Agricultural operations and single-family households represent underserved residential penetration. Grid extension economics force reliance on diesel hybrid backup for remote facilities beyond distribution network reach. Leasing models from specialized installers target this payment-constrained segment with zero-upfront financing structures.
Tobago
Tourism-dependent hospitality operators seek tariff stability through captive solar generation. The Trinidad and Tobago Electricity Commission manages technical review queues that constrain simultaneous project processing across both islands. Coastal resorts and inland eco-lodges constitute the primary commercial demand cluster.
Trinidad and Tobago Solar Energy Market Competitive Landscape
Capability concentration sits with infrastructure-anchored developers; scale advantage sits with international photovoltaic specialists. The market structures around three tiers: utility-scale project developers leveraging hydrocarbon sector relationships, commercial rooftop integrators with localized workforce capacity, and residential leasing operators penetrating payment-constrained segments. Dominant competitive moves include strategic partnerships with natural gas infrastructure holders and workforce localization mandates that lower labor cost structures for installation contractors.
Among domestic-anchored developers, NGC Green occupies a position exemplifying infrastructure leverage archetypes, while Resscott Ltd represents the residential specialization tier. Lightsource bp sits within the international expertise transfer category, bringing Caribbean-adapted deployment methodologies. These three anchors illustrate how competitive positioning fragments across capability domains rather than consolidating around scale alone.
| Leading Market Players |
|---|
| NGC Green |
| Resscott Ltd |
| Lightsource bp |
| Trifactor Technical Sales and Services Ltd |
| AMBA Energy Limited |
| bp Alternative Energy Trinidad and Tobago |
| SolarWorld-tt |
| AIMS Power |
| Shell Renewables Caribbean |
| Others |
Value Network & Pricing Analysis
Panama Canal freight corridors govern landed cost dynamics for photovoltaic modules entering Port of Spain, concentrating supply-side pricing power among Asian manufacturers while forcing downstream installers to differentiate through after-sales service bundling and workforce certification tiers.
Pricing Analysis
Aftermarket service revenue from inverter maintenance contracts and battery replacement cycles drives lifetime value capture for installation contractors. Project-based pricing dominates hardware procurement, with monocrystalline PERC modules commanding premiums over polycrystalline alternatives based on conversion efficiency certification and manufacturer warranty tiers. Cost compression in utility-scale procurement is intensifying because NGC Green leverages natural gas infrastructure relationships to accelerate site preparation and reduce balance-of-plant soft costs. Residential households in eastern Trinidad exhibit highest price sensitivity to upfront capital requirements, while Point Lisas petrochemical complexes absorb premiums for resilience against tariff volatility.
Supply Chain Analysis
Tariff exposure between China and Trinidad and Tobago dominates procurement risk calculations for project developers. Module supply concentrates in China, Vietnam, and Malaysia, with silicon cell manufacturing and aluminum frame fabrication drawing from these production hubs. Polysilicon feedstock, silver paste metallization, and tempered glass encapsulation constitute critical input dependencies. Single-source vulnerability persists for lithium-ion battery cells paired with photovoltaic systems. Distribution runs through Port of Spain warehousing clusters serving southwestern industrial zones and eastern residential corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diesel generator leasing incumbents pose the primary substitution threat as distributed solar penetrates backup power markets; defending installed base requires preemptive positioning before fuel price volatility shifts customer preference.
For Market Incumbents: Pre-empt diesel generator leasing firms by bundling battery-backed solar systems with maintenance contracts that match their fuel-inclusive service models. Anchor workforce certification investments to Trinidad and Tobago Bureau of Standards compliance pathways, creating switching costs that emerging technicians cannot replicate. Vertical integration into local mounting structure fabrication reduces aluminum import exposure and compresses project timelines. For New Entrants and Emerging Players: Mid-market commercial buildings in eastern Trinidad represent the most penetrable entry point given underserved rooftop capacity and limited incumbent leasing presence. Cold storage operators in Point Lisas offer adjacent expansion after initial residential traction. Lead with zero-upfront power purchase agreement structures that eliminate balance sheet constraints blocking captive solar investment. For Investors and Strategic Acquirers: Installation contractors with certified technician workforces and established Trinidad and Tobago Electricity Commission interconnection relationships offer the most defensible acquisition profile. Long-term viability hinges on storage attachment rates as grid instability deepens backup demand. Watch for Ministry of Energy and Energy Industries energy storage mandate announcements as the critical policy inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Expansion | Third-party ownership models transfer performance risk from Port of Spain manufacturing facilities to specialized operators. |
| Workforce Localization Program | Government training subsidies for photovoltaic technician certification lower labor cost structures for installation contractors. |
| Backward Integration into Storage | In-house battery system integration captures ancillary service revenue streams through frequency regulation contracts. |
| Renewable Energy Rider Optimization | Standardized system designs qualify for Trinidad and Tobago Electricity Commission expedited approval pathways. |
| Green Certification Program | Carbon accounting alignment with Ministry of Energy and Energy Industries targets enhances project bankability for fiscal incentives. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers at the Trinidad and Tobago Electricity Commission, independent power producer project developers, engineering-procurement-construction contractors, and residential installation specialists at Resscott Ltd. Secondary validation drew from Ministry of Energy and Energy Industries policy filings, Renewable Energy Rider technical standards, customs import records for photovoltaic modules, and Caribbean Development Bank energy sector reports. Bottom-up project pipeline aggregation was triangulated against top-down macroeconomic demand modeling.
Calibration against historical commissioning data and announced project development timelines anchored volume projections across the analysis window. Segmentation dimensions modeled include product type, cell technology architecture, application scale, and grid interconnection status. CAGRs were derived from fitted growth curves incorporating regulatory acceleration effects and capital cost decline trajectories. Specific forecast inputs included the Renewable Energy Rider interconnection queue processing capacity and lithium-ion battery cost decline curves.
Macroeconomic conditions sit as an overlay; deviation in natural gas export revenues and currency fluctuation against Asian supplier currencies would shift the trajectory of project finance availability and module procurement economics. Forecasts reflect documented assumptions regarding policy continuity and grid absorption capacity expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Photovoltaic Solar Kits Market
Solar Power Systems
GCC Solar Microinverter Market
Solar Power Systems
IBC Solar Cells Market
Solar Power Systems
Solar Mirror Market
Solar Power Systems
Alternative Solar Photovoltaic Technologies Market
Solar Power Systems
Single Axis Solar PV Tracker Market
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
Parabolic Solar Cookers Market
Solar Power Systems
Saudi Arabia Solar Energy Market
Solar Power Systems
GCC Solar Photovoltaic (PV) Market
Solar Power Systems
Asia-Pacific Distributed Solar Power Generation Market
Solar Power Systems
US Solar Films Market
Solar Power Systems
Global Solar Water Heaters Market
Solar Power Systems
Solar Fuel Market
Solar Power Systems
Thin-Film Photovoltaic Market
Solar Power Systems
Portable Solar Charger Market