
 Printable Self-Adhesive Vinyl Films Market | 2026-2036
Printable Self-Adhesive Vinyl Films Market Size, Share, and Industry Trends Forecast 2026-2036
Printable Self-Adhesive Vinyl Films Market Intelligence
A shift from single-source resin procurement to multi-source polymer sourcing is pivoting supply chain economics for printable self-adhesive vinyl film manufacturers. Avery Dennison leverages backward integration into acrylic adhesive production to secure formulation consistency across climate zones. ORAFOL Europe GmbH anchors its competitiveness through precision cast-film manufacturing in Leuchtenberg, sustaining premium positioning in reflective and specialty grades. HEXIS S.A.S. competes via deep color-matching capabilities and regional service density across French and Benelux markets.
Printable self-adhesive vinyl films comprise polyvinyl chloride or polyolefin substrates coated with pressure-sensitive adhesives, typically 3 mil to 8 mil in caliper, designed for solvent, eco-solvent, UV, and latex inkjet printing. These films serve commercial decoration, fleet identification, point-of-sale graphics, and durable labeling applications requiring conformability and clean removability. Glossy and matte finishes dominate volume throughput, though textured variants command margin premiums in architectural and luxury retail installations where tactile differentiation matters. Vehicle wraps represent the fastest-growing application dimension, driven by fleet operator demand for reversible branding and paint protection, while release liner selection—glassine versus polyester—shapes processing speed and die-cutting precision in automated label converting lines.
REACH regulates phthalate content and SVHC disclosure across EU vinyl film supply chains, while FDA indirect food-contact standards govern label applications in US packaged goods. The EPA oversees VOC emissions from solvent-based adhesives and inks used in film manufacturing and installation. Stakeholders must monitor evolving bio-based substrate certifications and regional extended-producer-responsibility mandates, as these frameworks will determine which material platforms qualify for public-sector and corporate-sustainability procurement.
Market Dynamics
Fleet operators are abandoning permanent paint applications in favor of removable vinyl wraps, restructuring demand toward cast-grade films with 5-7 year durability warranties and conformable adhesives for complex vehicle geometries.
Growth Catalysts
- REACH phthalate restrictions:ECHA enforcement is accelerating reformulation investments toward bio-based plasticizers and non-PVC substrates, opening premium positioning for compliant suppliers.
- Fleet branding migration:Logistics operators and ride-share platforms are standardizing vehicle wraps for reversible corporate identity deployment across multi-year lease cycles.
- Latex ink compatibility:Water-based latex printing systems are expanding addressable applications into indoor environments with stringent VOC thresholds.
Market Restraints
- Petrochemical input volatility:Crude-derived PVC resin and acrylic monomer costs swing with energy markets, compressing margin predictability for non-integrated converters.
- Cast film supply concentration:Precision casting equipment requires capital intensity that concentrates production among German and US-based specialists, creating bottleneck risk.
- Paint system substitution limits:High-temperature engine-bay applications and deep-draw compound curves exceed vinyl conformability, preserving automotive OEM paint for structural panels.
Strategic Opportunities
- Architectural surface films:Textured vinyl overlays for interior wall cladding and elevator cab refurbishment are penetrating commercial real estate retrofit cycles.
- EU Green Deal procurement:Public-sector sustainability mandates are creating qualified-supplier status for bio-based and recycled-content film platforms.
- Direct-to-installer digital channels:E-commerce platforms serving independent wrap shops are disintermediating traditional distributor tiers for standard grades.
Industry Challenges
- Certified installer scarcity:Complex cast-film application on compound curves demands trained technicians; training program throughput limits fleet rollout velocity.
- Multi-jurisdiction compliance layering:Simultaneous REACH SVHC disclosure, FDA indirect food-contact validation, and EPA VOC emission tracking strains quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printable Self-Adhesive Vinyl Films Market |
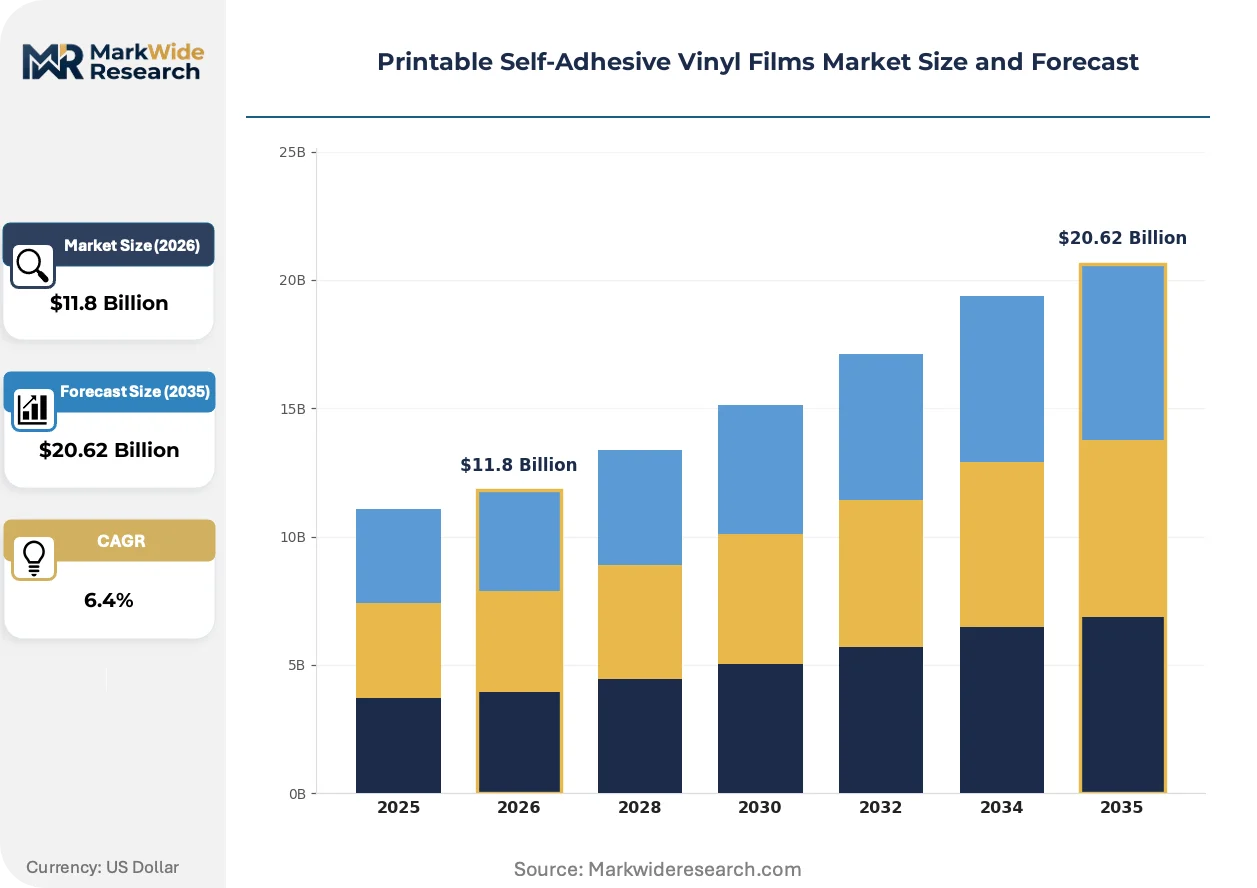
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glossy, Matte, Transparent, Textured Application: Signage, Wall Décor, Vehicle Wraps, Labels Release Liners: Glassine, Polyester, Paper, Film Thickness: 3 mil, 4 mil, 6 mil, 8 mil |
| Companies Covered | 3M, Avery Dennison, ORAFOL Europe GmbH, HEXIS S.A.S., Arlon Graphics, Lintec Corporation, LX Hausys, Mactac, Flexcon Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printable Self-Adhesive Vinyl Films Market Strategic Shifts & Innovations
Material science advances and regulatory pressure are converging to redefine substrate-adhesive-ink system architectures, with sustainability credentials becoming a gatekeeper for corporate procurement rather than a premium option.
Polyolefin-based printable films are overtaking conventional PVC substrates in premium architectural and fleet segments. These materials deliver comparable print receptivity and conformability without chlorine content or plasticizer migration risks. German automotive wrap specialists and Dutch retail display producers are specifying polyolefin grades for projects requiring cradle-to-cradle certification. The shift is compressing incumbent PVC compounders into commodity price tiers while rewarding early polymer platform diversifiers.
REACH SVHC candidate list expansion is forcing systematic supply chain requalification across EU vinyl film distribution. ECHA disclosure obligations now extend to adhesion promoters and UV stabilizers previously treated as proprietary formulations. Label converters serving pan-European packaged goods brands are demanding full material composition data from substrate suppliers. The regulatory friction is advantaging vertically integrated manufacturers with captive analytical laboratories over import-dependent distributors.
Outcome-based fleet graphics contracts are displacing traditional film-and-labor procurement in North American logistics. National carriers are contracting wrap providers for cost-per-mile or cost-per-impression pricing tied to vehicle utilization and graphic refresh cycles. This model transfers weathering risk and installation scheduling burden to service providers. The restructuring is most advanced among California and Texas-based regional fleets with standardized tractor-trailer configurations.
Printable Self-Adhesive Vinyl Films Market Segmentation
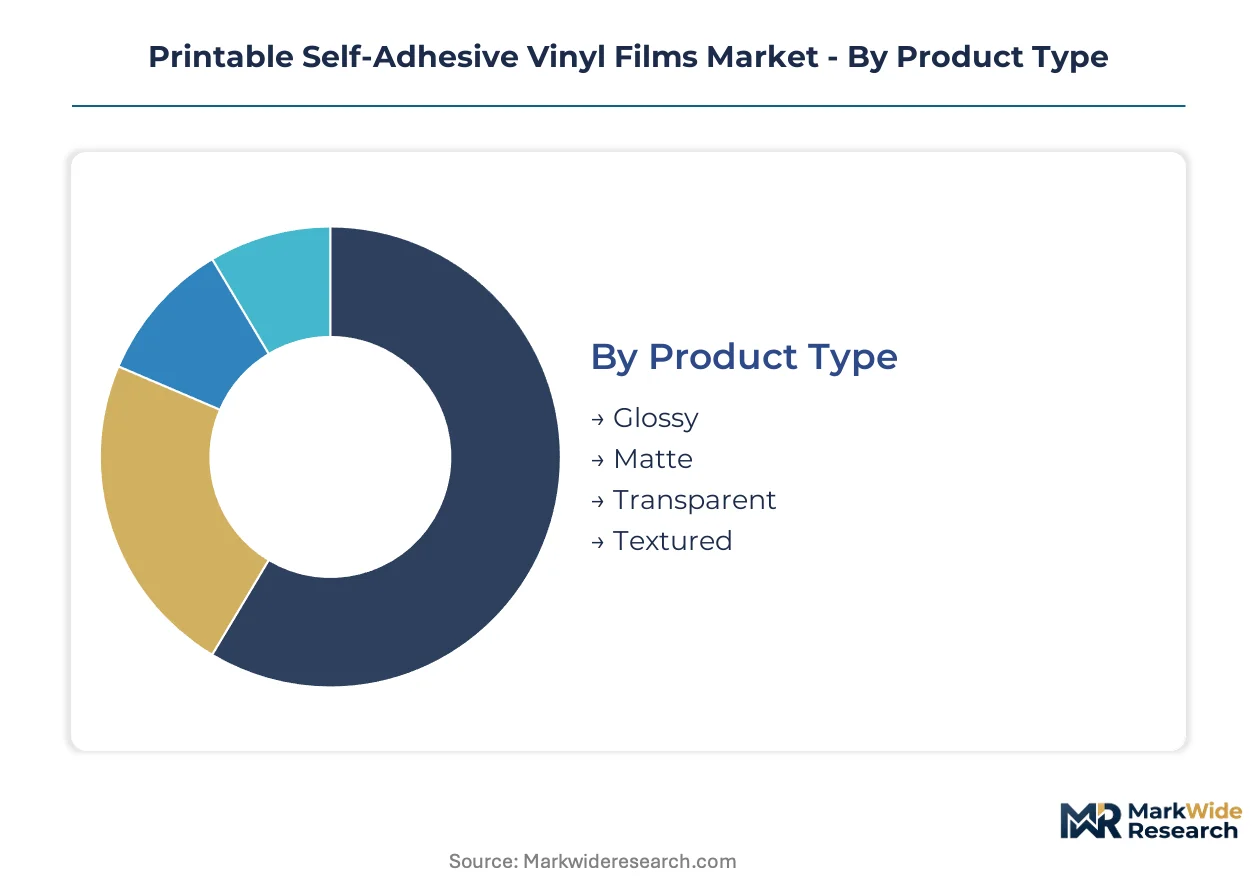
Printable self-adhesive vinyl films serve heterogeneous end-uses requiring precise matching of surface finish, caliper, and liner substrate to application demands. Segmentation reveals how technical specifications concentrate procurement decisions and manufacturing investment across converter networks.
Product Type:
Surface finish selection concentrates among German and US calendering specialists who maintain differentiated coating lines for gloss control and texture replication.
- Glossy:High-sheen PVC or polyolefin substrates with 80-110 gloss units at 60° deliver maximum color saturation for retail signage and fleet graphics. Fleet operators in Texas and California specify glossy wraps for maximum roadside visibility during daylight hours. This finish absorbs the bulk of installed capacity.
- Matte:Low-sheen surfaces at 5-15 gloss units reduce glare for interior architectural applications and luxury retail environments. Dutch museum display producers and French luxury brand flagship stores specify matte grades to eliminate reflective interference with lighting design.
- Transparent:Clear substrates with optical-grade clarity enable window graphic applications and overlay protection. German automotive aftermarket specialists use transparent films for headlight tinting and paint protection film printing.
- Textured:Embossed surface patterns replicate wood grain, carbon fiber, or brushed metal for architectural refurbishment and premium retail installations.
Glossy films absorb the bulk of installed capacity; textured variants are expanding most quickly as commercial real estate retrofit cycles accelerate.
Application:
End-use differentiation drives adhesive formulation chemistry and warranty positioning across converter product lines.
- Signage:Short-to-medium term outdoor graphics on rigid substrates and flexible banners, typically 1-3 year durability requirements. US municipal procurement and German retail chain rollouts concentrate volume in standard calendered grades with solvent-compatible adhesives.
- Wall Décor:Removable adhesives for interior mural applications requiring clean removal from painted drywall and commercial wallcoverings. French hospitality designers and UK office fit-out contractors specify low-tack repositionable formulations for temporary brand activations.
- Vehicle Wraps:Cast-grade films with conformable adhesives for compound curves, deep recesses, and riveted surfaces on commercial fleets. This application is climbing the fastest as logistics operators abandon permanent paint for reversible branding across multi-year lease cycles.
- Labels:Thin-gauge films with precision die-cutting compatibility for consumer goods, industrial asset tracking, and pharmaceutical serialization. FDA indirect food-contact validation governs US packaged goods label procurement.
Signage absorbs the bulk of installed capacity; vehicle wraps are gaining share fastest.
Release Liners:
Liner substrate selection determines processing speed, dimensional stability, and die-cutting precision in automated converting environments.
- Glassine:Calendered paper with silicone release coating offers cost-efficient liner for standard signage and short-run label applications. German mid-volume converters and US regional print shops specify glassine for equipment compatibility with legacy die-cutting infrastructure.
- Polyester: Dimensionally stable film liner enables high-speed automated dispensing and precision registration for narrow-web label converting. Pharmaceutical and electronics label producers in Switzerland and the Netherlands require polyester for tight-tolerance die-cutting and matrix stripping.
- Paper:Uncoated or clay-coated paper liners serve economy-grade signage and temporary promotional graphics where dimensional stability is secondary to material cost.
- Film:Specialty polymer liners including polyethylene and polypropylene for specific adhesive chemistries and extreme processing conditions.
Glassine absorbs the bulk of installed capacity; polyester is expanding most quickly as pharmaceutical serialization mandates tighten registration requirements.
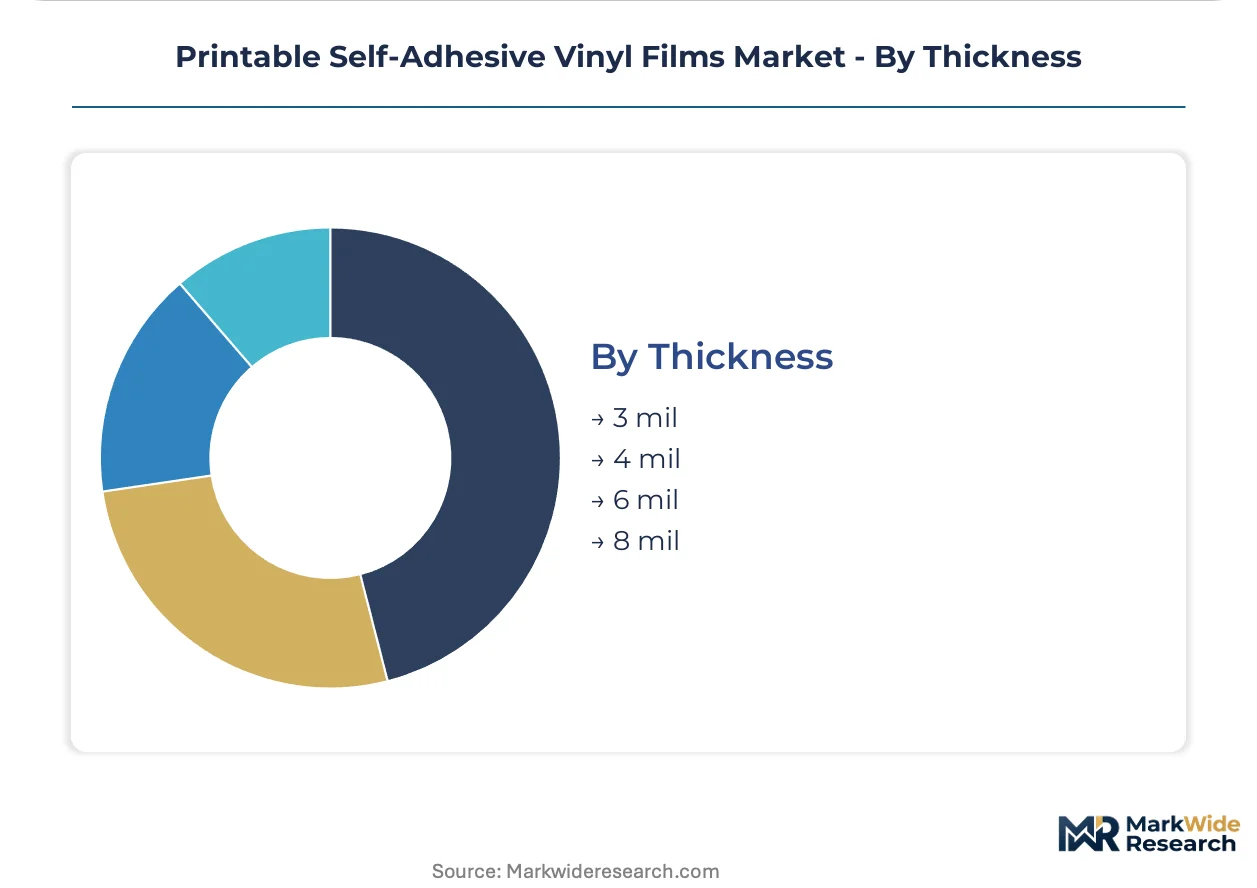
Thickness:
Caliper specification balances conformability, durability, and material cost across application requirements and installation complexity.
- 3 mil:Ultra-conformable films for complex compound curves, deep recesses, and riveted surfaces on vehicle wraps and irregular architectural elements. German automotive wrap specialists and UK motorsport livery producers specify 3 mil cast grades for Formula E and touring car fleet applications.
- 4 mil:Standard calendered and cast grades for general signage, fleet graphics, and wall décor with moderate conformability requirements. This specification dominates volume throughput across North American and European converter networks.
- 6 mil:Heavy-duty films for floor graphics, industrial safety markings, and abrasive environments requiring enhanced puncture resistance.
- 8 mil:Maximum durability substrates for extreme outdoor exposure, anti-graffiti protection, and heavy-traffic floor applications.
4 mil absorbs the bulk of installed capacity; 3 mil is expanding most quickly as fleet wrap complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German petrochemical corridors around Leuna and Ludwigshafen supply the specialty PVC and acrylic monomers that anchor printable vinyl film manufacturing across Europe. These feedstock localities shape regional production economics and compliance frameworks.
United States
California and Texas fleet operators drive cast-film consumption for commercial vehicle wraps and reversible corporate branding. EPA VOC emission standards govern solvent-based adhesive formulations used in manufacturing and installation. Dallas-Fort Worth and Los Angeles metropolitan areas concentrate independent wrap shops and fleet graphics service providers.
Germany
Automotive aftermarket specialists and commercial fleet operators demand premium cast grades with extended durability warranties. REACH SVHC disclosure mandates from ECHA force systematic supply chain requalification for adhesion promoters and UV stabilizers. The Leuchtenberg industrial cluster in Bavaria hosts precision cast-film manufacturing operations serving reflective and specialty grades.
France
Luxury retail flagship stores and hospitality designers specify matte and textured vinyl finishes for interior brand activations. EU Green Deal procurement criteria create qualified-supplier status for bio-based substrate platforms. Paris and Lyon metropolitan areas concentrate architectural surface film specification and installation expertise.
United Kingdom
Office fit-out contractors and motorsport livery producers source ultra-conformable 3 mil cast grades for complex geometries. The country's national environmental regulator enforces extended-producer-responsibility mandates affecting film waste recovery. The Midlands region hosts label converting operations serving pharmaceutical serialization requirements.
Netherlands
Dutch retail display producers and museum exhibition designers specify polyolefin grades for cradle-to-cradle certified projects. ECHA enforcement of phthalate restrictions accelerates reformulation toward non-PVC alternatives. The Eindhoven region concentrates narrow-web label converting infrastructure for pharmaceutical and electronics applications.
Printable Self-Adhesive Vinyl Films Market Key Industry Players
Backward integration into captive adhesive production dominates the current landscape as manufacturers secure formulation consistency across climate zones. The vendor base clusters around three tiers: multinational material science conglomerates with polymer platform diversification, mid-cap European specialists with precision casting capabilities, and regional converters with deep color-matching service density. Strategic archetypes include integrated resin-to-film manufacturers, precision cast-grade specialists, and distribution-intensive service providers. M&A activity and capacity expansion in polyolefin substrate lines represent the dominant competitive moves.
Among Germany-based specialists, ORAFOL Europe GmbH exemplifies the precision cast-film archetype through its Leuchtenberg manufacturing concentration. HEXIS S.A.S. occupies a position within the French specialist tier, serving regional service density requirements across Benelux markets. Avery Dennison represents the multinational integrated archetype with backward integration into acrylic adhesive production.
| Leading Market Players |
|---|
| 3M |
| Avery Dennison |
| ORAFOL Europe GmbH |
| HEXIS S.A.S. |
| Arlon Graphics |
| Lintec Corporation |
| LX Hausys |
| Mactac |
| Flexcon Company |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap German specialists anchor supply discipline through multi-generational capital allocation patience, insulating premium cast-film pricing from quarterly margin pressure while constraining capacity expansion that might destabilize warranty-backed value propositions.
Pricing Analysis
Warranty bundling separates premium cast grades with 5-7 year durability guarantees from unbundled calendered commodity tiers where weathering risk transfers to installers. Three-tier pricing structure across premium, standard, and economy levels reflects adhesive chemistry sophistication and liner substrate grade. Cost compression in calendered grades is intensifying because Asian import competition feeds distributor price wars. Fleet operators exhibit lowest price sensitivity for vehicle wraps where installation labor dominates total project cost, while municipal signage procurement shows highest sensitivity to per-square-meter film pricing.
Supply Chain Analysis
Skilled technician availability constraints in Bavaria and North Rhine-Westphalia limit precision casting line throughput despite capital availability for equipment expansion. Manufacturing gravity centers on Germany, the United States, and South Korea for cast-film production, with China dominating calendered commodity output. Feedstock dependency rests on crude-derived PVC resin, acrylic monomer, and specialty plasticizers subject to energy market volatility. Single-source vulnerability concentrates in precision casting equipment where German and US-based specialists control proprietary die technology. Distribution runs through three-tier structures: manufacturer-direct for national fleet accounts, specialized distributors for regional wrap shops, and e-commerce platforms disintermediating standard grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around REACH compliance investments that strand non-reformulated inventory and force smaller compounders into distressed exits.
For Market Incumbents: Deepen backward integration into captive adhesive production to secure formulation consistency across climate zones and defend against polyolefin substrate displacement. Expand precision casting capacity in Leuchtenberg or comparable industrial clusters to capture architectural surface film growth. Prioritize ECHA pre-registration of adhesion promoters and UV stabilizers ahead of SVHC list expansion. For New Entrants and Emerging Players: Direct-to-installer e-commerce platforms offer the lowest friction entry vector for standard calendered grades in underserved US Midwest markets. Target independent wrap shops in Dallas-Fort Worth and Chicago metropolitan areas with latex-compatible product lines and rapid color-matching service. Lead with EU Green Deal procurement qualification to access public-sector sustainability mandates creating qualified-supplier status. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision cast-film specialists with ECHA-compliant formulations and established fleet graphics service relationships in Germany. Five-to-ten year viability hinges on polymer platform diversification beyond PVC into polyolefin substrates. Watch for bio-based substrate certification acceleration as inflection signal for premium grade repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Production | Avery Dennison's captive acrylic supply secures batch consistency across humidity extremes. |
| Polyolefin Substrate Platform Expansion | ORAFOL Europe GmbH diversifies beyond PVC to capture cradle-to-cradle certified project demand. |
| Direct-to-Installer Digital Channel Buildout | E-commerce platforms disintermediate distributor tiers for standard grades in North American markets. |
| REACH Compliance Pre-Registration Investment | Early SVHC disclosure preparation advantages integrated manufacturers with captive analytical laboratories. |
| Outcome-Based Fleet Graphics Contracting | Cost-per-mile pricing transfers weathering risk from national carriers to wrap service providers. |
Research Approach
Independent corroboration across plant managers at German casting facilities, procurement leads at North American fleet operators, distribution channel partners in Benelux markets, and technical R&D directors at adhesive compounders underwrites the qualitative findings. Secondary validation draws from ECHA SVHC candidate list publications, EPA VOC emission standard filings, SEC 10-K disclosures by listed material science conglomerates, and customs trade data tracking PVC resin and acrylic monomer flows. Bottom-up demand modeling from end-use application sizing and top-down supply validation from manufacturer capacity disclosures achieve triangulation.
Rate-of-change decomposition across the projection horizon separates volume growth from value expansion through grade-mix shift analysis. Segmentation dimensions modeled include surface finish tier, application end-use, release liner substrate, and thickness specification alongside regional regulatory cluster differentiation. CAGRs derive from iterative convergence of demand-side adoption curves and supply-side capacity constraints. Forecast inputs incorporate REACH SVHC list expansion timelines and latex ink system penetration rates in indoor graphics environments.
The model holds under stable petrochemical input cost regimes and gradual regulatory phase-in; deviation in crude price volatility spikes or accelerated ECHA enforcement timelines would shift grade-mix assumptions and capacity utilization trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
Desiccant Market
Packaging Materials
Transit Packaging Market
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Packaging Primers Market
Packaging Materials
Stick Packaging Market
Packaging Materials
Refrigerator Door Seal Gaskets Market
Packaging Materials
Collagen Sausage Casings Market
Packaging Materials
Crimped End Mailing Tubes Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Reel in Box Market
Packaging Materials
Global Anti-Static Films Market
Packaging Materials
Corrugated Wrap Around Market
Packaging Materials
Foam Bottle Technology Market
Packaging Materials
North America Single-Use Packaging Market
Packaging Materials
Lid Laminates Market