
 Floor POP Display Market | 2026-2036
Floor POP Display Market Size, Share, and Industry Trends Forecast 2026-2036
Floor POP Display Market Analysis
A capital-intensity divergence between integrated paperboard producers and boutique display fabricators is reorganizing competitive tiers in floor POP displays. WestRock Company leverages its captive containerboard supply to control input costs across high-volume retail programs. Smurfit Kappa anchors European demand through corrugated structural design capabilities and regional mill networks. Creative Displays Now specializes in short-run customizable formats, competing on turnaround speed rather than scale.
Floor POP displays are freestanding retail fixtures engineered from corrugated fiberboard, rigid plastics, or metal tubing, typically designed to hold 50–200 product units and withstand 30–90 days of floor traffic. Manufacturers employ die-cutting, lithographic lamination, and structural CAD modeling to achieve load-bearing integrity with minimal material weight. Cardboard dominates unit volumes due to recyclability and printability, though plastic and metal segments command margin pools in reusable and premium-brand applications. Dump bins and floor stands lead product-type demand in grocery and club channels, while interactive design types are gaining traction in electronics and cosmetics retail where shopper engagement metrics drive procurement decisions.
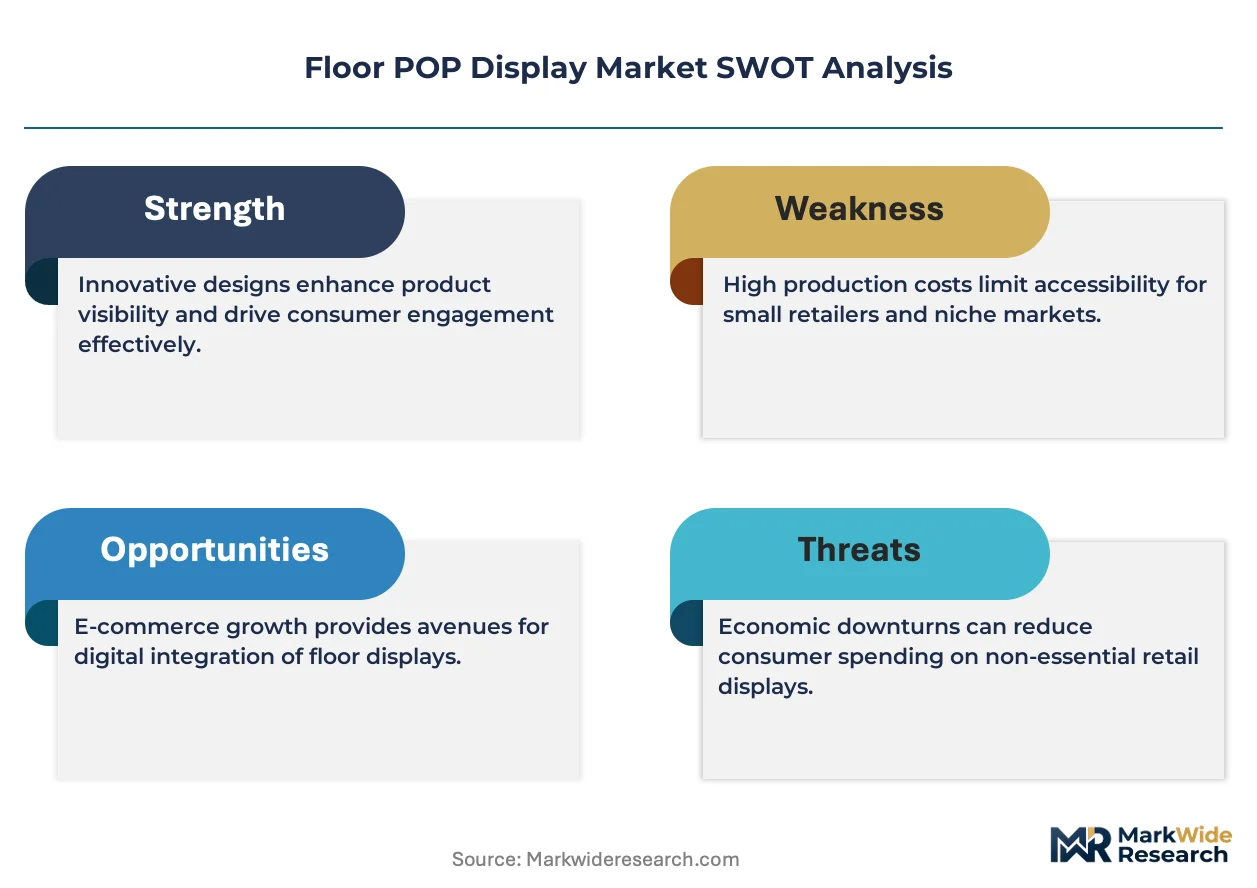
US EPA guidelines on recycled content and the EU Packaging and Packaging Waste Regulation are elevating compliance costs for cardboard-intensive producers while creating specification advantages for FSC-certified and post-consumer waste suppliers. FDA indirect food-contact standards govern displays positioned near consumables in US supermarkets, restricting adhesive and ink chemistries. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to internalize design-to-recycling capabilities or outsource compliance to specialized substrate partners.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles for cardboard-intensive floor POP displays while elevating compliance costs across European supply chains. CPG brands now demand structural CAD validation and material traceability before seasonal reset approvals.
Growth Catalysts
- Experiential Retail Investment:Grocery and mass retail channels are expanding floor fixture procurement as shopper engagement metrics displace traditional aisle productivity measures in buyer evaluations.
- Recyclability Mandates:The EU Green Deal's circular economy requirements are accelerating specification shifts toward FSC-certified corrugated substrates and post-consumer waste content.
- Seasonal Reset Velocity:United States big-box retailers command substantial quarterly display refresh volumes, pulling demand toward high-throughput structural design capabilities.
Market Restraints
- OCC Price Volatility:Old corrugated containerboard input costs swing with pulp futures, compressing margin predictability for non-integrated display fabricators.
- Mill Network Concentration:Containerboard supply concentrates among North American integrated producers, creating bottleneck risk for boutique display specialists lacking captive fiber sources.
- Reusable Plastic Substitution:Durable PP and PET floor fixtures threaten cardboard volumes in club channels where 90-day+ deployment cycles justify higher upfront unit costs.
Strategic Opportunities
- Electronics Retail Penetration:Interactive floor displays remain underdeployed in consumer electronics chains where unboxing experience and product demonstration drive conversion.
- Extended Producer Responsibility Tailwinds:Germany's Verpackungsgesetz and France's AGEC law incentivize design-to-recycling capabilities that internalize end-of-life compliance.
- Digital-Physical Convergence:NFC-enabled and QR-integrated displays merge mobile engagement with physical fixture presence, opening premium pricing tiers in cosmetics retail.
Industry Challenges
- Structural Engineering Talent Scarcity:Load-bearing corrugated design expertise pools narrowly among packaging engineers with retail fixture specialization.
- Extended Certification Timelines:FDA indirect food-contact validation for supermarket displays stretches procurement cycles, compressing seasonal launch windows.
- Legacy ERP Integration Friction:Real-time inventory synchronization between display fabricators and retailer planning systems demands costly middleware development.
Report Scope
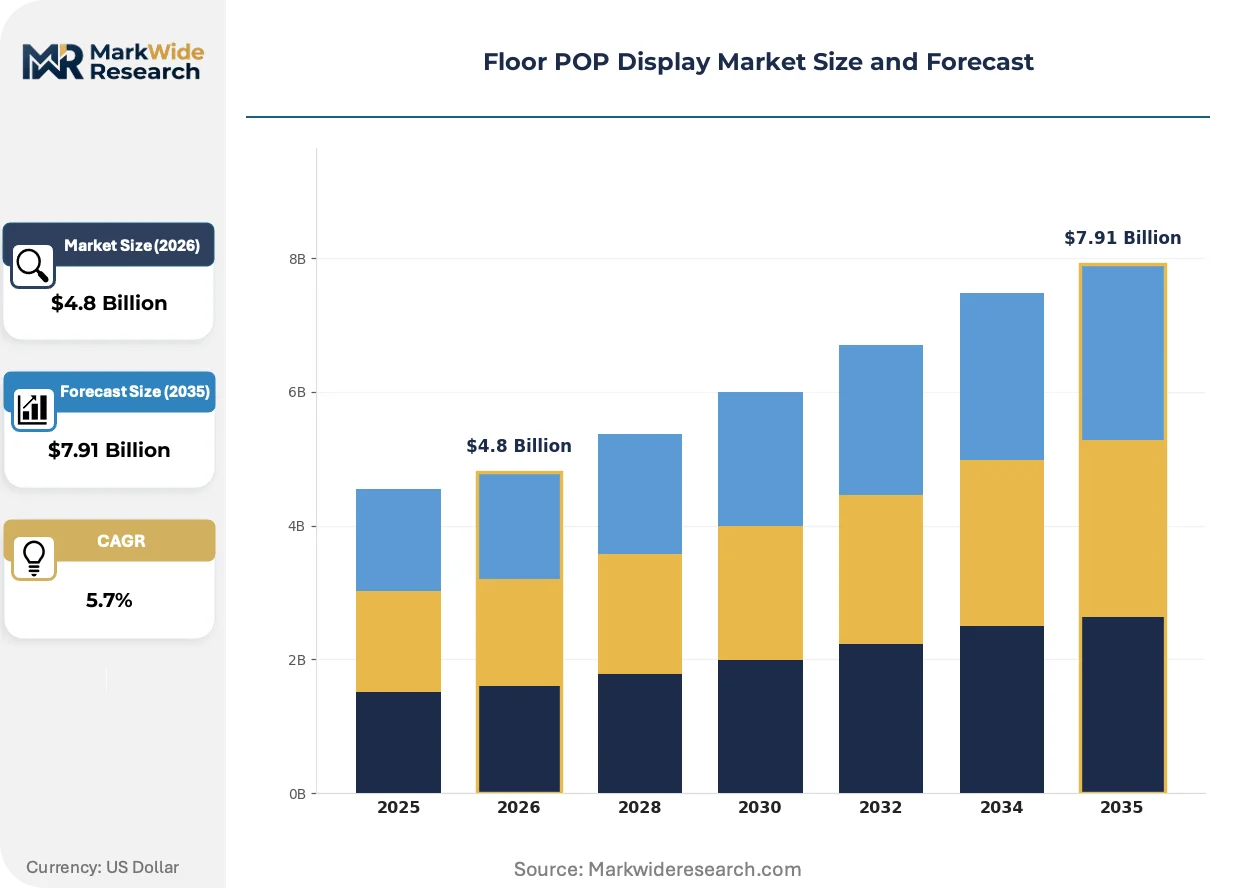
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor POP Display Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cardboard, Plastic, Metal, Wood Product Type: Standees, Shelf Displays, Dump Bins, Floor Stands Application: Retail, Events, Promotions, Exhibitions Design Type: Customizable, Pre-designed, Portable, Interactive |
| Companies Covered | WestRock Company, Smurfit Kappa, DS Smith, International Paper, Sonoco Products Company, Georgia-Pacific LLC, Menasha Packaging, Creative Displays Now, Marketing Alliance Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor POP Display Market Emerging Trajectories
Digital printing and structural simulation tools are compressing prototype-to-production timelines while enabling mass customization at previously impossible unit economics. These capabilities are redrawing competitive boundaries between scale producers and agile specialists.
Lithographic lamination paired with high-speed digital die-cutting is displacing conventional flexo-printed displays in premium cosmetics and electronics programs. Sephora and Best Buy procurement teams now specify photo-realistic graphics with 48-hour turnaround prototypes. This capability compression is eroding the volume advantage of traditional long-run offset producers.
REACH chemical restrictions and the EU Packaging and Packaging Waste Regulation are forcing adhesive and ink reformulation across European supply chains. Manufacturers face substitution costs for solvent-based systems while racing to validate bio-based alternatives. German and French retail chains now require full material disclosure, shifting specification power toward substrate partners with certified supply chain transparency.
CPG buyers are consolidating display procurement under centralized category management functions, displacing the fragmented store-level ordering that historically sustained regional fabricators. Walmart and Target have implemented unified seasonal reset programs with national display partners. This concentration is visible most acutely in United States grocery channels where private-label expansion demands consistent cross-banner fixture presence.
Floor POP Display Market Segmentation
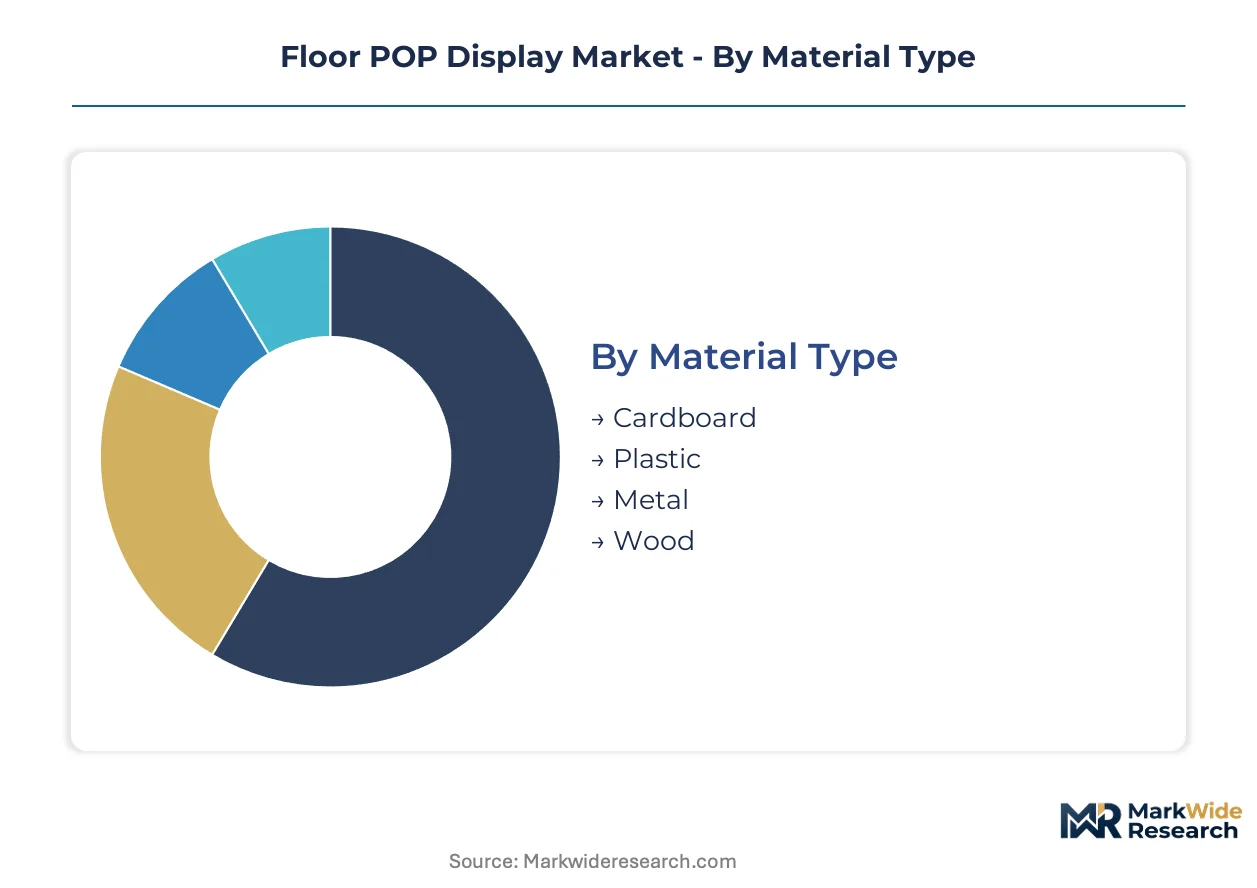
Floor POP display procurement decisions hinge on material compliance, structural load requirements, and deployment duration. Each segmentation dimension carries distinct regulatory exposure and margin architecture that shapes supplier selection and design investment.
Material Type:
EPA recycled content guidelines and EU Packaging and Packaging Waste Regulation create divergent compliance burdens across substrate categories.
- Cardboard:Corrugated fiberboard dominates unit volumes through FSC-certified and post-consumer waste streams that satisfy EU Green Deal circular economy mandates. Grocery and mass retail channels in the United States command substantial seasonal reset volumes for cardboard-intensive programs.
- Plastic:Durable PP and PET fixtures withstand 90-day-plus deployment cycles in club channels, justifying higher upfront unit costs where reuse economics offset material premiums. FDA indirect food-contact standards restrict adhesive and ink chemistries for displays positioned near consumables.
- Metal:Tubular steel and aluminum frames deliver premium-brand aesthetics and multi-year reusability in electronics and cosmetics retail where shopper engagement metrics drive procurement.
- Wood:Plywood and solid timber constructions serve boutique retail and exhibition applications requiring tactile warmth and custom fabrication at lower volume scale.
Cardboard handles the majority of throughput; Plastic is expanding most quickly on share as reusable deployment models gain traction.
Product Type:
Structural engineering requirements and retailer planogram integration determine fabrication complexity and turnaround velocity.
- Dump Bins:High-capacity corrugated containers engineered for 50-200 product units and 30-90 days of floor traffic. Die-cutting and lithographic lamination achieve load-bearing integrity with minimal material weight in grocery and club channels.
- Floor Stands:Freestanding fixtures with vertical product presentation optimize sightline capture in high-traffic retail zones. Structural CAD modeling validates stability against shopper contact and cart impact.
- Standees:Lightweight vertical displays prioritize graphic surface area over product capacity for promotional messaging in events and temporary retail.
- Shelf Displays:Countertop and inline fixtures integrate with existing gondola systems, reducing footprint requirements but demanding precise dimensional tolerances.
Dump Bins capture the highest absolute volume; Floor Stands are climbing the fastest as experiential retail investment prioritizes engagement over pure product density.
Application:
Deployment duration and traffic intensity separate procurement specifications across use cases.
- Retail:Permanent and seasonal fixture programs in grocery, mass, club, and specialty channels dominate procurement scale with quarterly reset calendars.
- Promotions:Short-cycle displays tied to product launches and price campaigns demand rapid prototyping and 48-hour turnaround capabilities.
- Events:Temporary installations at trade shows and brand activations prioritize portability and rapid assembly without tools.
- Exhibitions:Custom-fabricated environments for industry conferences emphasize structural distinction and premium material finishes.
Retail absorbs the dominant share of fabrication capacity; Promotions are gaining share fastest as CPG brands compress campaign-to-shelf timelines.
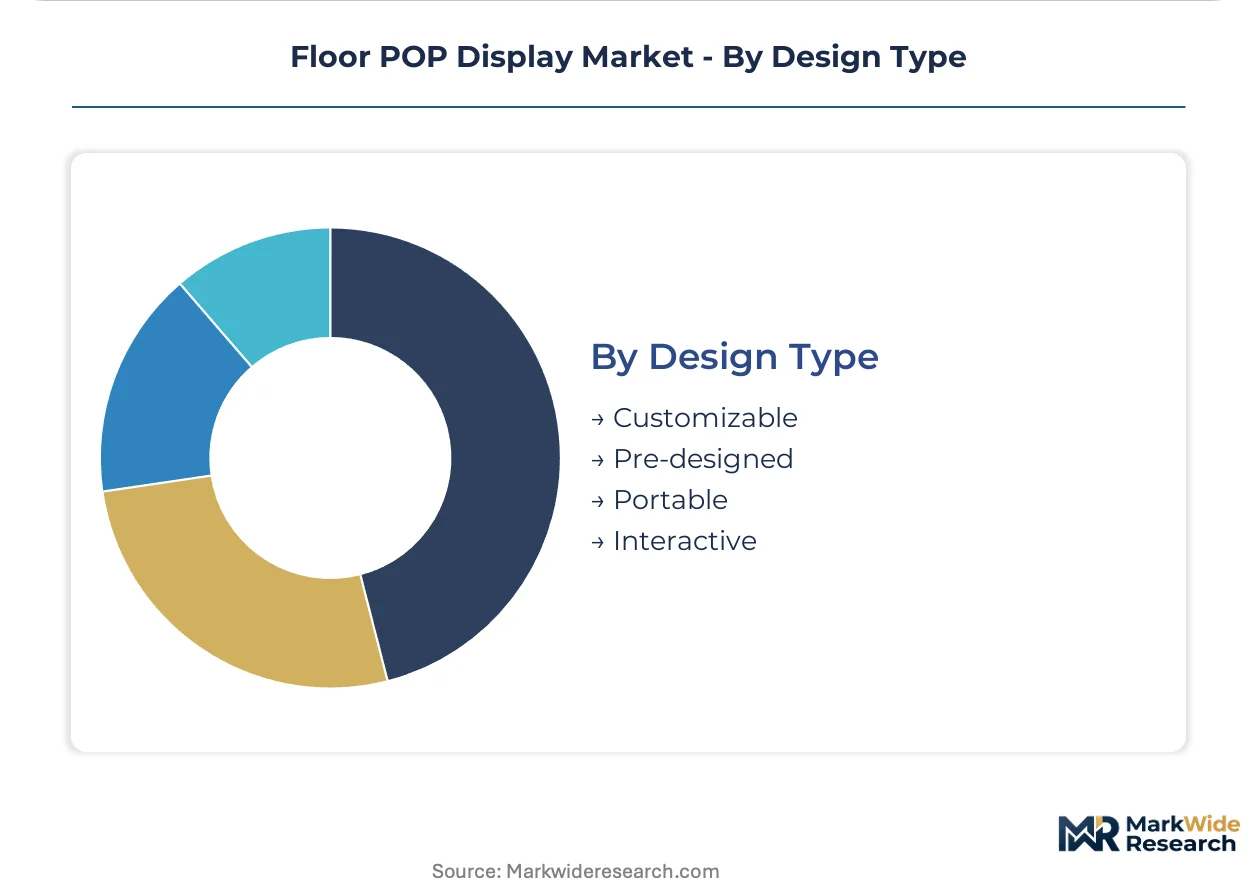
Design Type:
Digital-physical convergence capabilities and mass customization economics differentiate competitive positioning.
- Interactive:NFC-enabled and QR-integrated displays merge mobile engagement with physical fixture presence. Sephora and Best Buy procurement teams specify these formats where unboxing experience and product demonstration drive conversion.
- Customizable:Digital printing and structural simulation tools enable short-run formats with photo-realistic graphics and 48-hour prototype turnaround. Creative Displays Now competes on this agility rather than scale.
- Portable:Collapsible and modular systems reduce shipping cube and storage burden for event and exhibition redeployment.
- Pre-designed:Catalog formats with standardized dimensions accelerate procurement for routine promotional cycles with lower creative investment.
Customizable designs command the largest current volume; Interactive formats are on the steepest expansion trajectory as electronics and cosmetics retail prioritize engagement metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Floor POP display trade flows tilt toward net-import positions in European markets while the United States maintains substantial domestic fabrication capacity. Containerboard supply geography and retail reset velocity determine regional competitive positioning more than end-demand distribution alone.
United States
Big-box retailers command substantial seasonal reset volumes that pull demand toward high-throughput structural design capabilities. EPA recycled content guidelines elevate compliance costs for cardboard-intensive producers while creating specification advantages for certified suppliers. The Midwest industrial corridor hosts concentrated display fabrication clusters serving Walmart and Target unified procurement programs.
Germany
Verpackungsgesetz mandates incentivize design-to-recycling capabilities that internalize end-of-life compliance for display fabricators. REACH chemical restrictions force adhesive and ink reformulation across corrugated supply chains. The Rhine-Ruhr manufacturing belt anchors European demand through Smurfit Kappa's regional mill networks and structural engineering centers.
France
AGEC law requirements accelerate specification shifts toward FSC-certified substrates and post-consumer waste content in retail fixture procurement. National retail chains now demand full material disclosure, shifting specification power toward transparent substrate partners. The Île-de-France region concentrates cosmetics and luxury brand headquarters driving premium interactive display demand.
China
Dual carbon goals and MIIT industrial standards reshape substrate sourcing for export-oriented display fabricators serving multinational CPG brands. Domestic retail modernization expands floor fixture procurement beyond traditional promotional applications. The Yangtze River Delta hosts integrated paperboard producers controlling captive fiber sources for high-volume programs.
United Kingdom
Post-Brexit regulatory divergence from EU packaging rules creates parallel compliance tracks for displays serving continental versus domestic retail channels. Supermarket consolidation under Tesco and Sainsbury's procurement umbrellas concentrates demand toward national display partners. The Midlands manufacturing belt retains structural die-cutting and lithographic lamination capacity for seasonal promotional cycles.
Floor POP Display Market Vendor Landscape
Concentration sits with integrated paperboard producers who leverage captive containerboard supply to control input costs across high-volume retail programs. Boutique display fabricators compete on turnaround speed and customization rather than scale. Two strategic archetypes dominate: vertically integrated mill-to-display operators and agile short-run specialists. M&A activity targets regional fabrication assets, while strategic partnerships with substrate suppliers secure material traceability for EU compliance.
Among North American integrated producers, WestRock Company and Georgia-Pacific LLC exemplify the scale-driven archetype with upstream control over containerboard inputs. Smurfit Kappa anchors European positioning through corrugated structural design capabilities. Creative Displays Now occupies the specialist tier, competing on 48-hour prototype turnaround rather than volume scale.
| Leading Market Players |
|---|
| WestRock Company |
| Smurfit Kappa |
| DS Smith |
| International Paper |
| Sonoco Products Company |
| Georgia-Pacific LLC |
| Menasha Packaging |
| Creative Displays Now |
| Marketing Alliance Group |
| Others |
Supply Flow & Price Mechanics
High-volume containerboard capacity utilization at integrated North American mills shapes both supply concentration and price floors for floor POP display fabricators. Scale advantages at WestRock and Georgia-Pacific compress input costs for captive display operations while elevating procurement leverage over non-integrated competitors serving Walmart and Target seasonal programs.
Pricing Analysis
Mass retail buyers anchor contract-based long-term offtake pricing with quarterly reset volumes commanding volume-scale discounts. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified interactive displays from conventional corrugated formats from generic dump bins. Cost compression in standard-tier cardboard fixtures is intensifying because OCC price volatility feeds directly through non-integrated fabricator margins. Boutique specialists show highest price sensitivity due to spot-market fiber exposure, while integrated producers with captive supply demonstrate lowest sensitivity.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes elevate inbound logistics costs for substrate imports serving European display fabricators. Supply concentrates in the United States, Germany, and China, with integrated paperboard producers drawing from captive kraft pulp and recycled fiber networks. Raw material dependencies center on OCC bales, linerboard rolls, and lithographic inks. Single-source vulnerability concentrates around North American integrated mill networks. Distribution runs through direct mill-to-fabricator arrangements for high-volume programs and regional substrate distributors for short-run specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Durable PP and PET reusable fixtures threaten cardboard volumes in club channels with 90-day-plus deployment cycles, forcing incumbents to defend substitution economics through total-cost-of-ownership repositioning.
For Market Incumbents: Consolidate structural engineering talent pools through targeted acquisition of boutique CAD-specialist firms in the Midwest industrial corridor. Deepen backward integration into post-consumer waste fiber processing to secure FSC-certified substrate supply against REACH chemical restriction compliance costs. Channel control through exclusive national reset partnerships with Target and Walmart procurement umbrellas defends volume scale against reusable plastic substitution.
For New Entrants and Emerging Players: FSC certification fast-track programs open white-space penetration in French and German retail chains demanding full material disclosure under AGEC and Verpackungsgesetz mandates. Electronics retail interactive displays remain underdeployed relative to cosmetics penetration, presenting the most penetrable segment for NFC-enabled fixture specialization. Go-to-market angle centers on 48-hour prototype turnaround competing against Creative Displays Now agility rather than WestRock scale.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated mill-to-display operators with multi-year national retail program contracts. Long-term viability over a 5-10 year window favors substrate partners with certified supply chain transparency and design-to-recycling capabilities internalizing extended producer responsibility compliance. Acquisition target archetype: regional fabrication assets with structural die-cutting capacity and lithographic lamination equipment. Signal to watch: quarterly seasonal reset volume commitments from big-box retailers as inflection indicator for capacity utilization trends.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Recovery | Captive OCC supply insulates margin against pulp futures volatility for FSC-certified output. |
| Interactive Display Capability Buildout | NFC and QR integration commands premium pricing in Sephora and Best Buy procurement specifications. |
| Regional Mill Network Expansion | Rhine-Ruhr and Yangtze River Delta proximity reduces logistics burden for EU and Asian retail programs. |
| Design-to-Recycling Certification | Germany's Verpackungsgesetz and France's AGEC law incentivize end-of-life compliance internalization. |
| Digital-Physical Convergence Partnership | Mobile engagement integration opens premium tiers in electronics and cosmetics retail channels. |
Methodological Framework
Initial hypotheses were tested against primary input from category buyers at mass retailers, structural packaging engineers, substrate procurement managers, and seasonal reset program directors and refined through secondary validation. Bottom-up triangulation combined Nielsen retail audit data, EPA recycled content guideline filings, EU Packaging and Packaging Waste Regulation compliance disclosures, and customs records of containerboard trade flows. Top-down cross-checks anchored total addressable market sizing against integrated producer capacity disclosures and retail fixture procurement budget allocations.
Variance decomposition across material type, product type, application, and design type segmentation dimensions drove analytical framework construction throughout the projection horizon. CAGRs derived from regression analysis of historical seasonal reset volumes against retail square footage expansion and experiential marketing budget shifts. Industry-specific forecast inputs incorporated OCC price futures curves and EU Green Deal circular economy mandate implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained big-box retailer quarterly reset velocity or accelerated reusable plastic substitution thresholds would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and fiber supply network stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Packaging
Global Shoe Packaging Market
Retail Packaging
Retail Ready Trays Market
Retail Packaging
Free Standing Display Units Market
Retail Packaging
Club Store Packaging Market
Retail Packaging
Retail E Commerce Packaging Market
Retail Packaging
Black Friday Packaging Market
Retail Packaging
Table Tent Market
Retail Packaging
Retail Ready Packaging (RRP) Market
Retail Packaging
Retail Bags Market