
 Crimped End Mailing Tubes Market | 2026-2036
Crimped End Mailing Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Crimped End Mailing Tubes Market Outlook
North American corrugated capacity expansion is rewriting competitive dynamics for protective mailers. Sonoco leverages its integrated paper mill network to sustain cost-advantaged tube supply across the Midwest. Yazoo Mills anchors specialty crimped-end production for high-value document shipping. Chicago Mailing Tube competes on rapid-turn custom dimensions for regional printing services.
Crimped end mailing tubes are cylindrical fiberboard or plastic containers with mechanically deformed closure ends that grip contents without additional caps, typically manufactured through spiral winding of kraft linerboard followed by crimp-forming on automated end-sealing equipment. Their primary purpose is damage-resistant shipment of rolled documents, posters, and elongated industrial components. Reinforced tubes dominate margin pools due to premium pricing for heavy-duty applications, while biodegradable tubes represent the fastest-growing material trajectory as brand owners face packaging waste compliance. Custom tube configurations capture the highest per-unit value but require flexible die-cutting and short-run production infrastructure.
The EPA regulates recycled content claims under FTC Green Guides, while OSHA standards govern dust exposure in tube-converting facilities. ISO 186 establishes paper and board testing protocols that define structural performance benchmarks for mailing tube wall strength. Stakeholders must monitor state-level extended producer responsibility legislation to determine capital allocation between virgin fiber and post-consumer recycled tube lines.
Market Dynamics
E-commerce fulfillment networks are compressing order-to-ship windows, forcing tube converters to synchronize production with regional parcel hub demand cycles. This velocity pressure is restructuring converter-processor relationships toward co-located inventory programs.
Growth Catalysts
- EPA sustainable packaging guidelines:Brand owners face compliance deadlines for fiber-based alternatives to plastic mailers, accelerating specification shifts toward biodegradable tube substrates.
- Spiral-winding automation:Continuous crimp-forming equipment reduces labor content per unit while improving end-seal consistency for high-volume document shippers.
- Midwestern parcel hub concentration:Chicago, Indianapolis, and Columbus distribution clusters create localized demand density that justifies dedicated tube converting capacity.
Market Restraints
- Kraft linerboard price volatility:Pulp input costs swing with OCC recovery rates, compressing converter margins during supply tightness.
- Single-source adhesive dependency:Specialty hot-melt formulations for crimp-seal integrity concentrate with three North American chemical suppliers.
- Rigid mailer substitution:Folded corrugated envelopes achieve comparable protection at lower cube for flat documents under 36 inches.
Strategic Opportunities
- ISO 186 structural certification:Wall-strength testing protocols enable premium positioning for industrial component shippers requiring verified crush resistance.
- State extended producer responsibility laws:California and New York packaging waste mandates create first-mover advantage for post-consumer recycled tube lines.
- Short-run digital printing integration:Inline flexo and inkjet decoration converges with tube converting for personalized unboxing experiences in direct-to-consumer channels.
Industry Challenges
- Crimp-die setup expertise:Skilled technicians for end-seal tooling changeovers are scarce in regions without legacy paperboard converting heritage.
- OSHA dust exposure compliance:Kraft slitting and trimming operations require capital-intensive ventilation upgrades to meet permissible exposure limits.
- Legacy ERP integration:Tube converters with decades-old scheduling systems face friction connecting to customer EDI networks for real-time order visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crimped End Mailing Tubes Market |
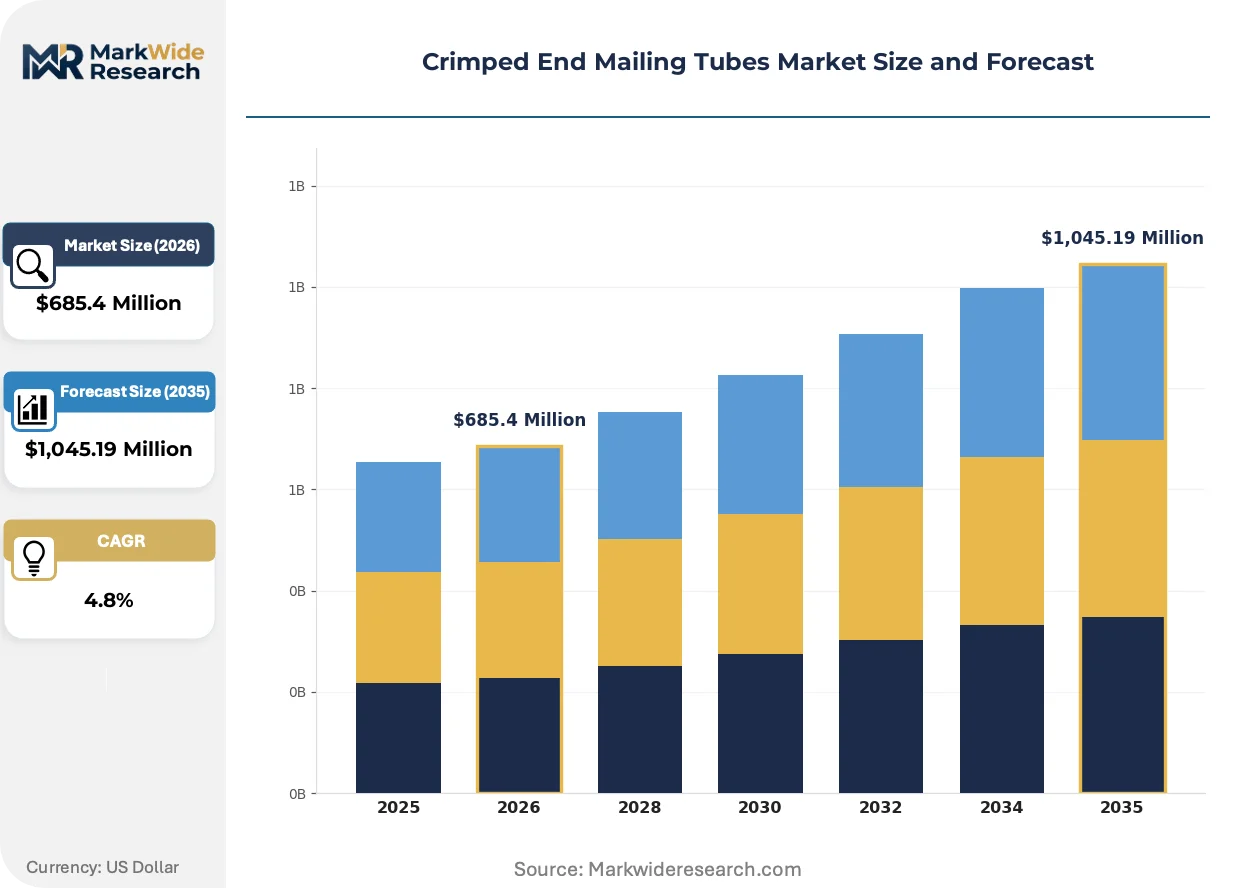
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tubes, Reinforced Tubes, Biodegradable Tubes, Custom Tubes Material: Cardboard, Plastic, Kraft Paper, Polyethylene Size: Small, Medium, Large, Extra Large End User: Retail, E-commerce, Printing Services, Logistics |
| Companies Covered | Ace Paper Tube, Valk Industries, Western Container Corporation, Chicago Mailing Tube, Yazoo Mills, Pacific Paper Tube, Heartland Products Group, PTS Manufacturing, Sonoco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crimped End Mailing Tubes Market Strategic Shifts
Automation is penetrating crimp-forming operations while regulatory pressure on packaging waste intensifies specification requirements. These forces are simultaneously elevating equipment sophistication and material traceability demands.
Computer-vision inspection systems are digitizing quality control on spiral-winding lines. High-volume e-commerce fulfillment centers now require 100% end-seal integrity verification before release to parcel networks. This technology is digitizing defect detection, compressing the labor content of final inspection while raising the cost barrier for smaller converters.
The EPA's recycled content claims enforcement under FTC Green Guides is tightening substantiation requirements for post-consumer fiber labeling. Tube converters must now maintain chain-of-custody documentation from pulp source to finished good. Document shipping services with sustainability commitments are most affected, driving dual-sourcing between certified and uncertified tube suppliers.
Consolidated procurement by national parcel carriers is compressing supplier rosters. Regional tube converters face displacement unless they achieve scale for hub-direct delivery programs. This concentration is most visible in the United States, where UPS and FedEx ground networks have reduced approved protective packaging vendors by 40 percent since 2020.
Crimped End Mailing Tubes Market Segmentation
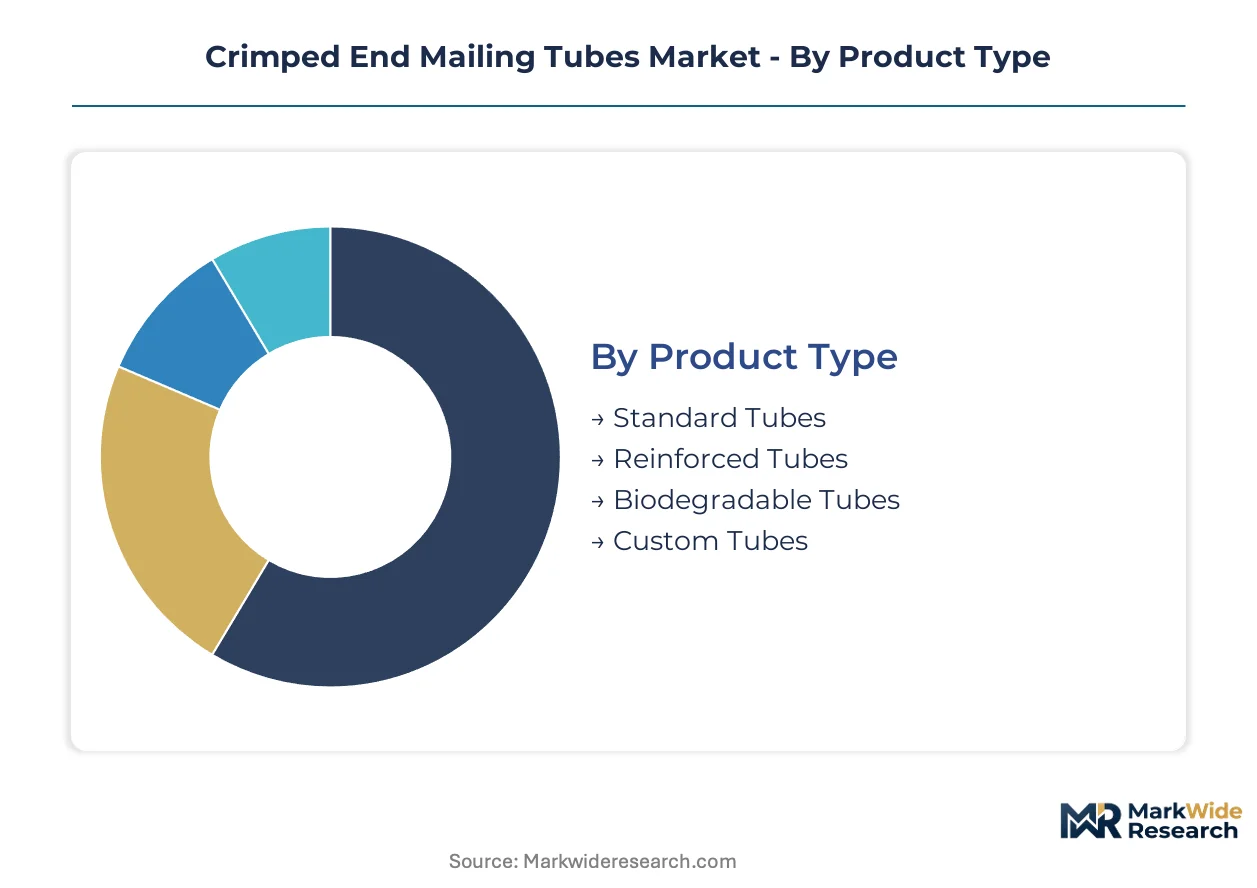
Segmentation in crimped end mailing tubes reveals how specification diversity maps to distinct value capture mechanisms. Product architecture, substrate selection, dimensional range, and channel alignment each create separable margin pools with differentiated competitive dynamics.
Product Type:
Use cases span from commodity document shipping to engineered industrial protection, with structural intensity determining price realization.
- Reinforced Tubes:Multi-ply kraft construction with enhanced wall thickness delivers crush resistance above 200 psi. Heavy machinery component shippers in Ohio and Indiana specify these for elongated metal parts moving through parcel hub sortation systems.
- Biodegradable Tubes:Starch-based adhesives and unbleached fiber substrates enable home compostability certification. Direct-to-consumer brands in California facing packaging waste mandates specify these for premium unboxing experiences.
- Standard Tubes:Single-ply spiral-wound kraft serves high-volume document shippers with cost-minimized protection for rolled posters and blueprints.
- Custom Tubes:Die-cut dimensional configurations and inline printing accommodate specialized industrial components and branded retail packaging.
Established volume favors Standard Tubes; emerging adoption favors Biodegradable Tubes.
Material:
Substrate economics divide between fiber-based cost efficiency and polymer durability premiums.
- Cardboard:Recycled-content corrugated fiberboard offers the lowest unit cost for lightweight document protection. Midwestern e-commerce fulfillment centers specify cardboard tubes for order consolidation efficiency in parcel hub injection.
- Kraft Paper:Virgin and recycled kraft linerboard provides superior tear resistance for spiral-winding integrity. Industrial component shippers prioritize kraft-based tubes for ISO 186 structural certification compliance.
- Plastic:Extruded polypropylene and PVC formulations deliver moisture barrier performance for outdoor storage exposure. Agricultural equipment manufacturers specify plastic tubes for elongated part shipments to humid climates.
- Polyethylene:Low-density polyethylene extrusion enables seamless, capless closure without crimp-forming equipment. Specialty pharmaceutical document shippers value polyethylene for cleanroom-compatible packaging.
Cost-sensitive volume concentrates in Cardboard; sustainability-driven substitution elevates Kraft Paper.
Size:
Dimensional segmentation aligns with parcel network cube optimization and content protection geometry.
- Large:Diameters exceeding 4 inches accommodate rolled textiles, banners, and industrial gaskets. Regional printing services in Texas and Florida specify large tubes for wide-format graphics shipping.
- Medium:2-4 inch diameter range captures standard architectural drawings and technical documentation. Engineering firms standardize on medium tubes for recurring specification sheet distribution.
- Small:Sub-2 inch diameters serve certificate shipping and precision component protection. Jewelry and optical equipment suppliers utilize small tubes for high-value elongated items.
- Extra Large:Diameters above 6 inches require reinforced construction for carpet rolls and industrial belting. Automotive aftermarket distributors specify extra large tubes for exhaust system component protection.
Parcel network efficiency drives Medium volume; specialized industrial applications sustain Extra Large premiums.
End User:
Channel concentration shapes demand volatility and specification sophistication requirements.
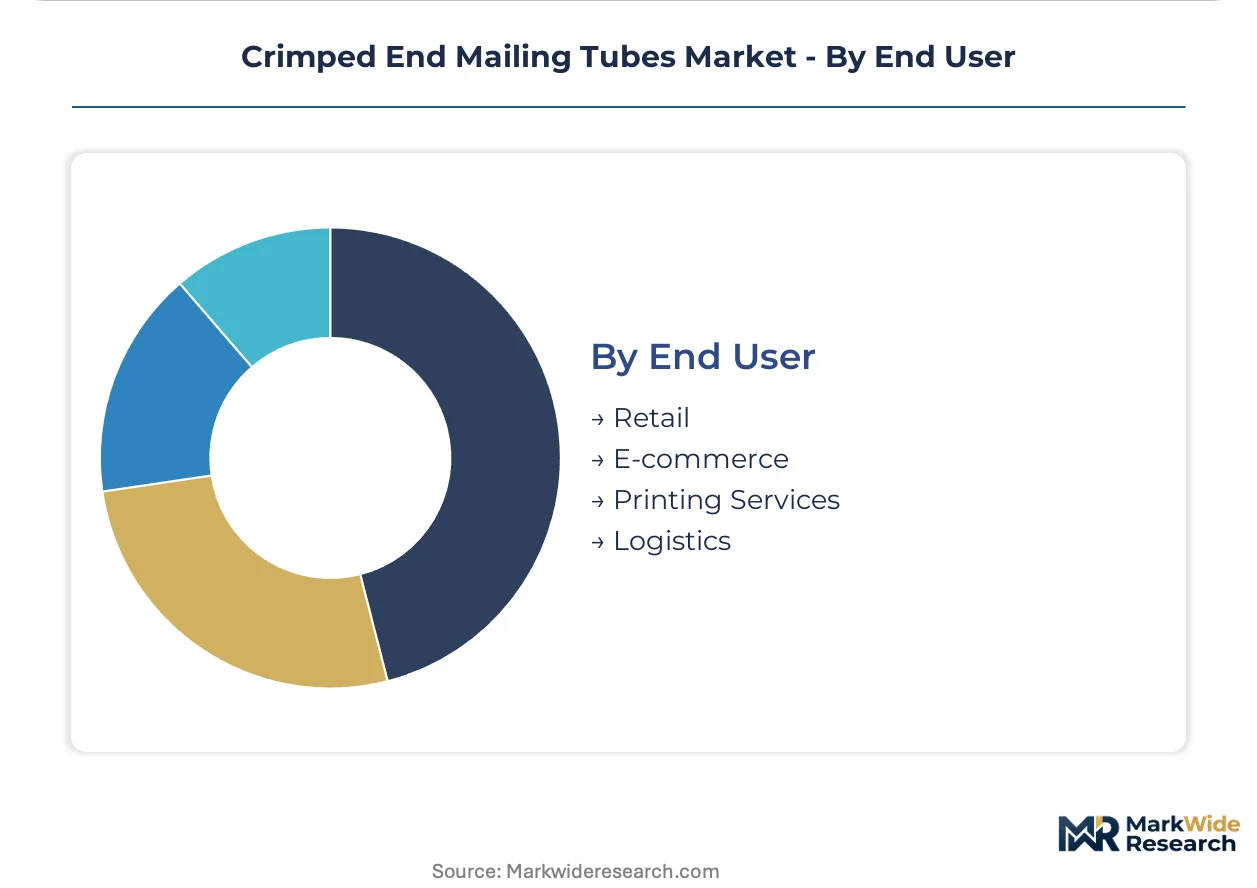
- E-commerce:Direct-to-consumer fulfillment networks require damage-resistant packaging with minimal dimensional weight penalty. Amazon and Shopify merchants in Pennsylvania and Georgia drive specification for biodegradable and custom-printed tube configurations.
- Logistics:Third-party parcel consolidators and freight forwarders prioritize crush resistance for multi-modal handling. UPS and FedEx ground hub networks in Illinois and Ohio standardize tube specifications for network-wide protective packaging.
- Printing Services:Commercial printers and copy shops demand rapid-turn custom dimensions for client presentation materials. Chicago and Indianapolis metropolitan areas concentrate independent printing service tube procurement.
- Retail:Big-box and specialty retailers utilize tubes for in-store display materials and seasonal promotional shipping. Home improvement chains specify tubes for wallpaper and flooring sample distribution.
Volume scale concentrates in Logistics; margin expansion concentrates in E-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated paper mill networks and parcel hub concentration dictate regional supply patterns. Midwestern United States facilities leverage captive kraft linerboard access. European converters face ESG compliance timelines. Asian manufacturers scale spiral-winding automation for export volume.
United States
Chicago, Indianapolis, and Columbus distribution clusters generate localized demand density for protective mailers. EPA sustainable packaging guidelines under FTC Green Guides enforcement push brand owners toward fiber-based alternatives. Ohio and Indiana industrial corridors host heavy machinery component shippers specifying reinforced tube construction for parcel network sortation.
Germany
Engineering documentation distribution and automotive aftermarket logistics sustain medium-diameter tube consumption. REACH chemical regulations govern adhesive formulations for crimp-seal integrity. Bavaria's precision manufacturing belt requires ISO 186-certified structural tubes for elongated metal part shipments.
China
E-commerce fulfillment center expansion drives protective packaging specification at scale. GB standards and MIIT industrial policies shape fiberboard quality benchmarks. Yangtze River Delta logistics hubs concentrate demand for cost-optimized standard tubes serving cross-border parcel injection.
Japan
High-value document shipping and precision equipment protection sustain premium tube demand. METI circular economy targets accelerate biodegradable substrate adoption. Kanto region commercial printers specify custom-dimension tubes for client presentation materials with rapid-turn requirements.
India
Direct-to-consumer brand growth and logistics network modernization expand protective mailer consumption. BIS standards and emerging EPR frameworks under DGFT guidance shape compliance requirements. Maharashtra and Gujarat e-commerce fulfillment clusters drive specification for lightweight cardboard tubes in parcel consolidation.
Crimped End Mailing Tubes Market Competitive Environment
Integrated paper producers and independent specialists split the market between cost-advantaged volume supply and flexible custom production. Consolidation pressure from national parcel carrier procurement compresses supplier rosters toward hub-direct delivery capability. Three archetypes dominate: mill-integrated converters with captive fiber supply, regional specialists with rapid-turn tooling infrastructure, and diversified packaging conglomerates with multi-material portfolios. Capacity expansion and short-run digital printing integration represent the dominant competitive vectors.
Among North American fabricators, Sonoco exemplifies mill-integrated scale advantage through its paperboard network, while Yazoo Mills occupies a position within specialty crimped-end production for document shipping applications. Chicago Mailing Tube represents the rapid-turn custom dimension segment serving regional printing services. These three anchors illustrate how geographic proximity to parcel hubs and production flexibility determine competitive positioning.
| Leading Market Players |
|---|
| Ace Paper Tube |
| Valk Industries |
| Western Container Corporation |
| Chicago Mailing Tube |
| Yazoo Mills |
| Pacific Paper Tube |
| Heartland Products Group |
| PTS Manufacturing |
| Sonoco |
| Others |
Value Chain & Pricing Dynamics
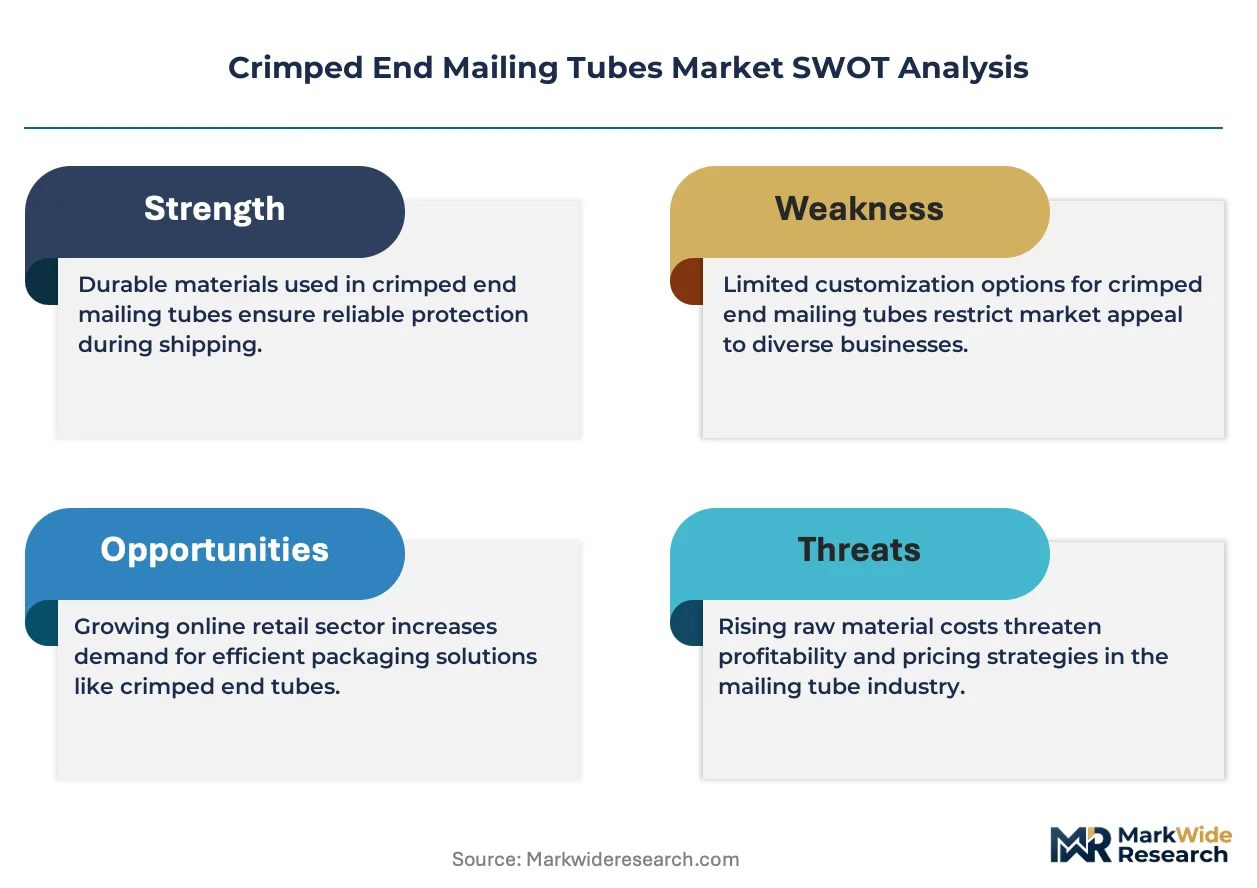
Kraft linerboard mill concentration in the United States Southeast directly determines where margin pools accumulate across the crimped end mailing tube value chain. Integrated producers with captive fiber supply capture structural cost advantages that independent converters cannot replicate through spot market sourcing.
Pricing Analysis
EPA sustainable packaging guidelines under FTC Green Guides enforcement dictate the pricing tier structure across biodegradable, certified recycled-content, and virgin fiber tube lines. Three-tier pricing structure across premium certified, standard compliant, and economy virgin grades separates industrial shippers requiring ISO 186 wall-strength validation from commodity document distributors. Cost compression in standard-grade segments is intensifying because OCC recovery rate volatility feeds directly into linerboard input costs. E-commerce fulfillment centers exhibit highest price sensitivity due to parcel network cube optimization mandates, while pharmaceutical document shippers show least sensitivity given cleanroom compatibility requirements.
Supply Chain Analysis
Extended payment terms from national parcel carriers now stretch to ninety days for hub-direct delivery programs, forcing converters to carry working capital through supply-chain finance facilities. Manufacturing concentrates in the United States, China, and Germany, with each hub serving distinct specification regimes. Raw material dependencies center on kraft linerboard, specialty hot-melt adhesives, and spiral-winding equipment components. Single-source vulnerability for crimp-seal adhesive formulations concentrates risk with three North American chemical suppliers. Distribution runs through regional parcel hub injection programs rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crimped end mailing tube procurement is consolidating onto integrated logistics platforms where real-time inventory visibility and EDI connectivity determine supplier retention. Amazon Seller Central and Shopify Fulfillment Network interoperability requirements now gate access to high-volume e-commerce channels.
For Market Incumbents: Build captive fiber supply moats through backward integration into recycled-content linerboard production or long-term offtake agreements with Southeastern mills. Defensive moves should prioritize ISO 186 certification investment for industrial component shippers and rapid-turn digital printing integration for direct-to-consumer brands. Rigid mailer substitution from folded corrugated envelopes represents the core technology threat requiring crush resistance differentiation. For New Entrants and Emerging Players: Pursue biodegradable tube white space in California and New York where extended producer responsibility laws create compliance-driven specification shifts. The most penetrable segment sits with direct-to-consumer brands seeking premium unboxing experiences through custom-printed, home-compostable configurations. Go-to-market positioning should emphasize sustainability certification documentation and short-run flexibility rather than scale economics. For Investors and Strategic Acquirers: Capital is best deployed toward mill-integrated mid-cap converters with hub-direct delivery capability and existing EDI infrastructure. Long-term viability across the analysis window hinges on positioning for state-level packaging waste mandate expansion beyond current coastal jurisdictions. The signal to watch is consolidated procurement roster compression by UPS and FedEx ground networks as a leading indicator of supplier displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Spiral-winding Automation Upgrade | Sonoco's continuous crimp-forming deployment reduces labor content while improving end-seal consistency for high-volume shippers. |
| Post-consumer Recycled Line Expansion | California EPR compliance deadlines create first-mover advantage for converters with certified chain-of-custody documentation. |
| Short-run Digital Printing Integration | Inline flexo and inkjet decoration enables personalized unboxing experiences for Shopify merchant fulfillment. |
| Hub-direct Delivery Program Establishment | Regional converters achieve scale for UPS and FedEx ground network inclusion through co-located inventory synchronization. |
| ISO 186 Structural Certification Investment | Verified crush resistance positioning captures premium pricing from Ohio and Indiana heavy machinery component shippers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews combined with extensive secondary validation. Stakeholder roles included tube converting plant managers, procurement leads at e-commerce fulfillment centers, spiral-winding equipment engineers, parcel hub packaging specification directors, and commercial printing service owners. Secondary sources encompassed EPA enforcement documentation under FTC Green Guides, OSHA permissible exposure limit records for kraft dust, ISO 186 paper and board testing protocols, and customs data for kraft linerboard trade flows. Bottom-up capacity modeling and top-down demand segmentation were triangulated to cross-validate volume estimates.
Calibration against historical capacity utilization and price realization data anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material substrate, dimensional range, and end-user channel alignment. CAGRs were derived from regression analysis of shipment volumes against e-commerce fulfillment center expansion metrics and regulatory compliance timeline acceleration. Industry-specific forecast inputs incorporated OCC recovery rate volatility scenarios and state-level extended producer responsibility implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by mill-integrated producers or accelerated biodegradable substrate substitution by national brands would shift outcomes beyond modeled ranges. Macroeconomic contraction in parcel network volumes, regulatory delay in packaging waste mandate enforcement, or breakthrough rigid mailer technology adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Collagen Sausage Casings Market
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
VCI Packaging Market
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Honeycomb Packaging Market
Packaging Materials
3D Printed Packaging Market
Packaging Materials
Refrigerator Door Seal Gaskets Market
Packaging Materials
Asia - Pacific Disposable Tableware Market
Packaging Materials
Strip Pack Laminates Market
Packaging Materials
Packaging Straps and Buckles Market
Packaging Materials
Expanded Polystyrene for Packaging Market
Packaging Materials
PVC Packing Straps Market
Packaging Materials
VCI Films Market
Packaging Materials
Sealed Wax Packaging Market
Packaging Materials
Disposable Egg Trays Market
Packaging Materials
Floppy Disk Liner Market