
 Global Multi Pack Carriers Market | 2026-2036
Global Multi Pack Carriers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Multi Pack Carriers Market Outlook
The EU Single-Use Plastics Directive is restructuring the competitive landscape for multi pack carriers across European markets. WestRock Company leverages its integrated fiber packaging infrastructure to anchor supply relationships with major beverage brands. DS Smith Plc competes through specialized paper carrier designs that reduce material weight while maintaining load integrity. Mondi Group differentiates via kraft-based solutions engineered for high-speed bottling lines.
Multi pack carriers are secondary packaging systems designed to group individual beverage containers—typically bottles or cans—into consumer-ready units, with specifications spanning tensile strength, moisture resistance, and compatibility with automated applicator equipment at filling speeds exceeding 1,000 units per minute. Paper carriers command expanding share as pulp-molded and folded-fiber formats displace plastic ring systems in regulated jurisdictions. Plastic carriers still dominate volume in markets without material restrictions, though biodegradable variants represent the fastest-growing product category as enzymatic and starch-based formulations achieve commercial scale. Food packaging applications generate the largest revenue pool, while cosmetic packaging offers narrower but higher-margin opportunities.
The EU Green Deal and REACH frameworks enforce material traceability and recyclability thresholds that shape product development cycles for carriers sold into European markets. The US EPA and state-level extended producer responsibility programs in California and Oregon are creating parallel compliance obligations for North American suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned capacity investments.
Market Dynamics
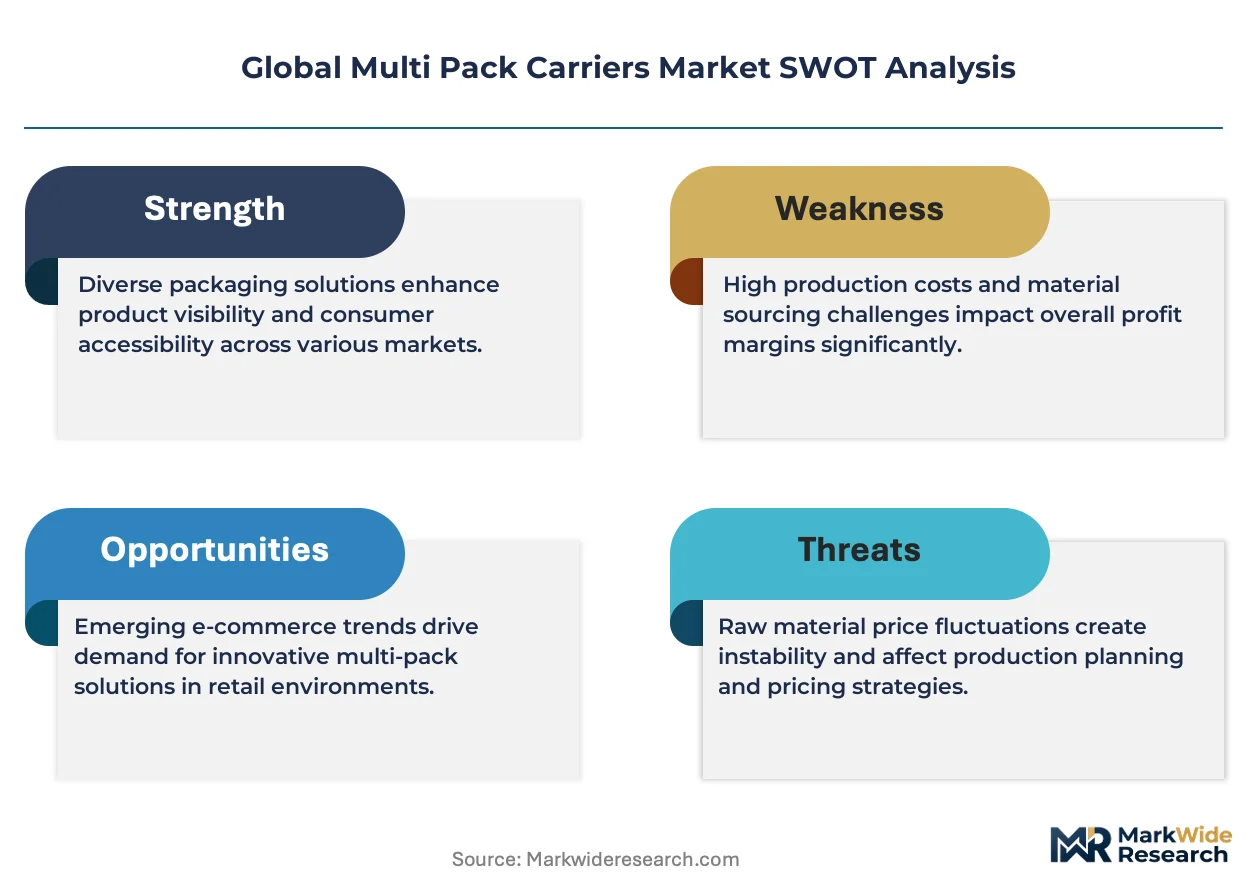
The EU Single-Use Plastics Directive and parallel state-level mandates in California and Oregon are forcing beverage manufacturers to abandon conventional plastic ring carriers faster than supply chains can pivot, creating acute sourcing pressure for fiber-based alternatives.
Growth Catalysts
- EU Green Deal packaging requirements:Binding recyclability thresholds for beverage packaging sold into Germany, France, and the Netherlands are mandating fiber carrier adoption by major bottlers.
- Pulp-molded carrier technology:Advances in wet-pressing and dry-molded fiber processes are enabling load-bearing performance matching plastic rings at comparable unit economics.
- Brazilian beverage export growth:Anheuser-Busch InBev and Ambev bottling operations are expanding paper carrier procurement to meet EU import compliance for exported product lines.
Market Restraints
- Softwood pulp price volatility:Input cost swings of 30-40% over 18-month cycles compress carrier margins and deter long-term supply contracts.
- Scandinavian pulp mill concentration:Four integrated producers control 60% of bleached kraft pulp suitable for food-contact carriers, creating supply vulnerability.
- Moisture resistance limitations:Uncoated fiber carriers degrade in refrigerated distribution environments exceeding 72 hours, restricting cold-chain applications.
Strategic Opportunities
- India beverage market expansion:Coca-Cola and PepsiCo bottling partners are piloting paper carriers in Maharashtra and Karnataka ahead of anticipated national plastic restrictions.
- Cosmetic multi-packs:Premium skincare brands are adopting rigid fiber carriers for gift sets, commanding 3-4x unit margins versus beverage applications.
- California EPR program:Extended producer responsibility fee structures effective 2027 will penalize plastic carriers and subsidize fiber alternatives through producer fund mechanisms.
Industry Challenges
- High-speed line integration:Retrofitting applicator equipment running above 1,200 bottles per minute for fiber carrier compatibility requires $2-4 million per production line.
- Food-contact certification timelines:FDA and EFSA migration testing protocols for novel barrier coatings extend product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Multi Pack Carriers Market |
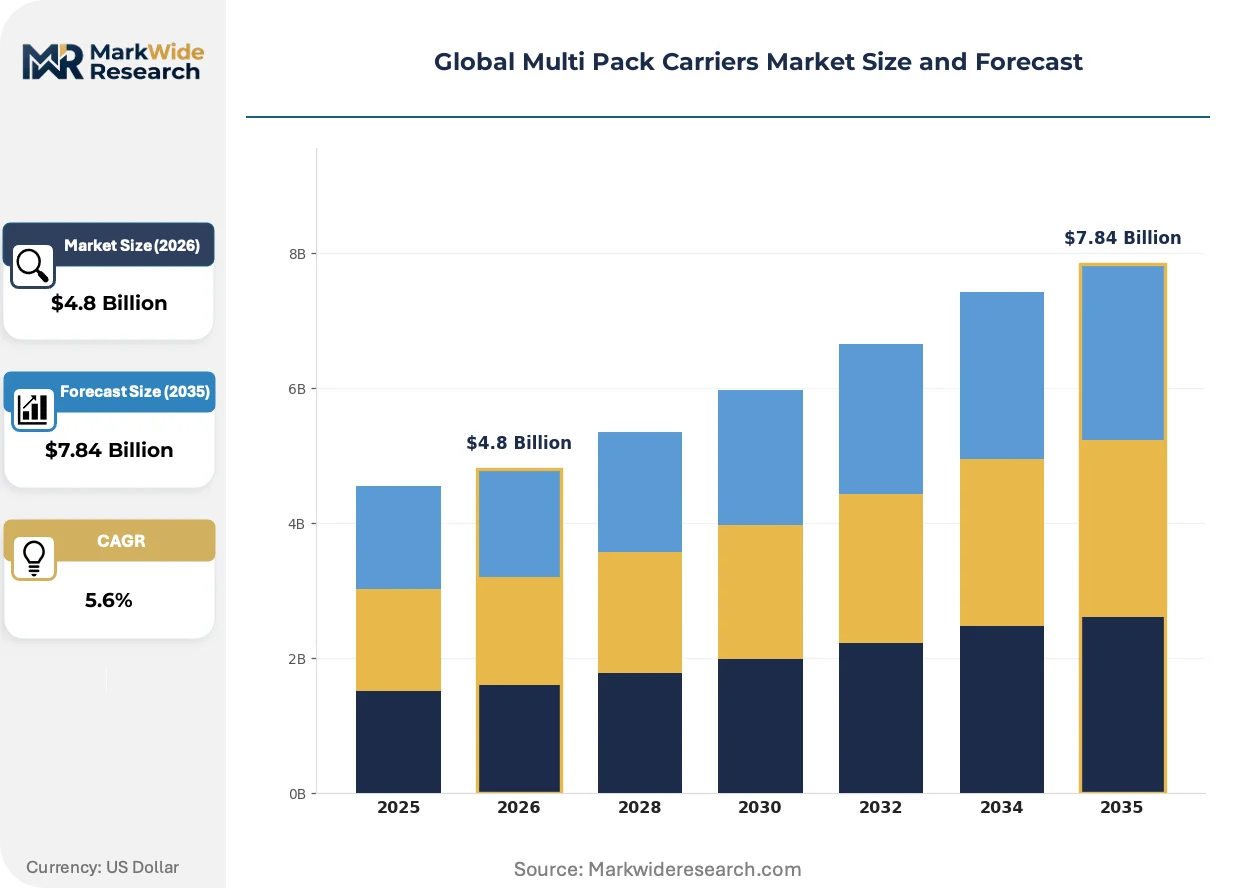
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Carriers, Paper Carriers, Fabric Carriers, Biodegradable Carriers End User: Retail Chains, E-commerce, Food Services, Grocery Stores Distribution Channel: Online Retail, Brick-and-Mortar, Wholesale, Direct Sales Application: Food Packaging, Consumer Goods, Electronics Packaging, Cosmetic Packaging |
| Companies Covered | WestRock Company, PakTech, Hi-Cone, Smurfit Kappa Group, Graphic Packaging International, Sonoco Products Company, DS Smith Plc, Mondi Group, International Paper Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Multi Pack Carriers Market Strategic Shifts
Material science breakthroughs and regulatory compliance automation are compressing development cycles for next-generation carriers. Three convergent developments are restructuring competitive advantage.
Pulp-molded carrier technology is consolidating market share as wet-pressed fiber formulations achieve tensile strength parity with plastic rings at 40% lower carbon intensity. Major beverage bottlers in Germany and the United States are qualifying these systems for high-speed production lines previously restricted to synthetic materials. The technology is consolidating supplier relationships around integrated pulp-and-paper producers capable of captive fiber sourcing.
REACH chemical safety protocols are expanding substance restriction lists to include per- and polyfluoroalkyl substances used in grease-resistant carrier coatings. European converters must reformulate barrier treatments or exit food-contact applications by 2026 compliance deadlines. Small and mid-size carrier producers lacking in-house R&D capacity are outsourcing coating development to specialty chemical firms, fragmenting the value chain.
Direct procurement relationships between beverage brand owners and fiber packaging producers are displacing traditional distributor intermediaries. Heineken, AB InBev, and Coca-Cola European Partners are establishing multi-year offtake agreements with WestRock, Mondi, and DS Smith to secure capacity and lock in sustainability metrics. This pattern is most visible in Western Europe, where retailer sustainability scorecards require verified supply chain transparency that distributors cannot provide.
Global Multi Pack Carriers Market Segmentation
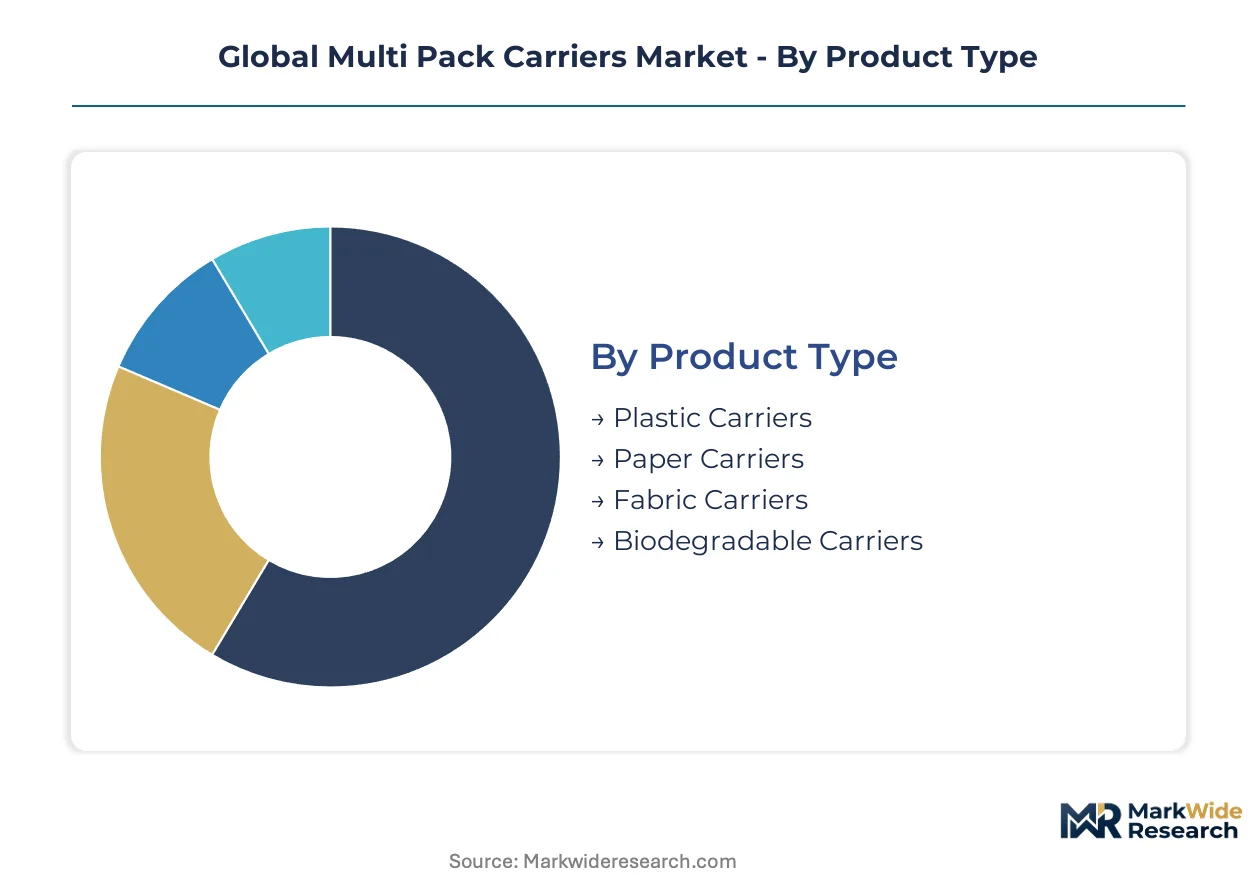
Multi pack carrier procurement patterns diverge sharply across material types, end-use channels, and distribution pathways. Understanding these divisions reveals where compliance costs, margin pressure, and capacity constraints concentrate most acutely.
Product Type:
Supplier capacity clusters around integrated pulp producers and specialized converters, with technology ownership determining pricing power and contract tenure.
- Paper Carriers:Wet-pressed and dry-molded fiber formulations now achieve tensile strength matching plastic alternatives. German bottlers and California beverage producers are mandating these systems to satisfy EU Green Deal recyclability thresholds and state-level extended producer responsibility frameworks.
- Biodegradable Carriers:Enzymatic and starch-based formulations decompose within marine environments without microplastic residue. Brazilian export operations and European premium brands are driving qualification programs for these carriers despite 15-20% unit cost premiums over conventional fiber.
- Plastic Carriers:Polyethylene ring systems retain dominance in unregulated markets across India and Southeast Asia, though demand is contracting in jurisdictions with active single-use plastics directives.
- Fabric Carriers:Woven polypropylene and cotton-based reusable systems serve boutique beverage brands and corporate gifting channels with higher per-unit margins but limited production scale.
Paper carriers absorb the bulk of installed capacity; biodegradable carriers are expanding most quickly.
End User:
Procurement scale and sustainability mandate intensity vary dramatically across buyer categories, reshaping sales force deployment and contract structures.
- Retail Chains:German supermarket cooperatives and French hypermarket operators enforce supplier scorecards requiring verified fiber content and carbon footprint disclosure. These buyers command volume commitments exceeding 50 million units annually with 3-5 year contract horizons.
- Grocery Stores:Independent and regional operators across Italy and Spain prioritize unit economics over sustainability certification, maintaining plastic carrier share where local regulations permit.
- E-commerce:Direct-to-consumer beverage subscriptions and meal-kit services are piloting fiber carriers for last-mile presentation value, though breakage rates in parcel networks remain unresolved.
- Food Services:Stadium concessionaires and quick-service restaurant chains specify carriers optimized for high-humidity cold storage, favoring coated fiber or hybrid constructions.
Retail chains anchor procurement volume; e-commerce channels show the steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin capture, with direct relationships displacing intermediaries where supply chain transparency requirements intensify.
- Direct Sales:Heineken, AB InBev, and Coca-Cola European Partners negotiate multi-year offtake agreements with WestRock, Mondi, and DS Smith to lock capacity and verify sustainability metrics. These arrangements eliminate distributor margins and accelerate technical collaboration on line integration.
- Wholesale:Regional beverage distributors in Brazil and Mexico aggregate demand from smaller bottlers, maintaining plastic carrier inventories where regulatory pressure remains muted.
- Brick-and-Mortar:Packaging distributors with physical stocking locations serve mid-tier producers requiring rapid fulfillment and technical support for applicator retrofitting.
- Online Retail:Digital procurement platforms are emerging for standardized carrier specifications, though high-speed line integration complexity limits adoption among major bottlers.
Direct sales capture the majority of contract value; online retail is gaining share fastest among small and mid-size producers.
Application:
Performance specifications and margin structures diverge across end-use categories, with food-contact certification requirements creating entry barriers.
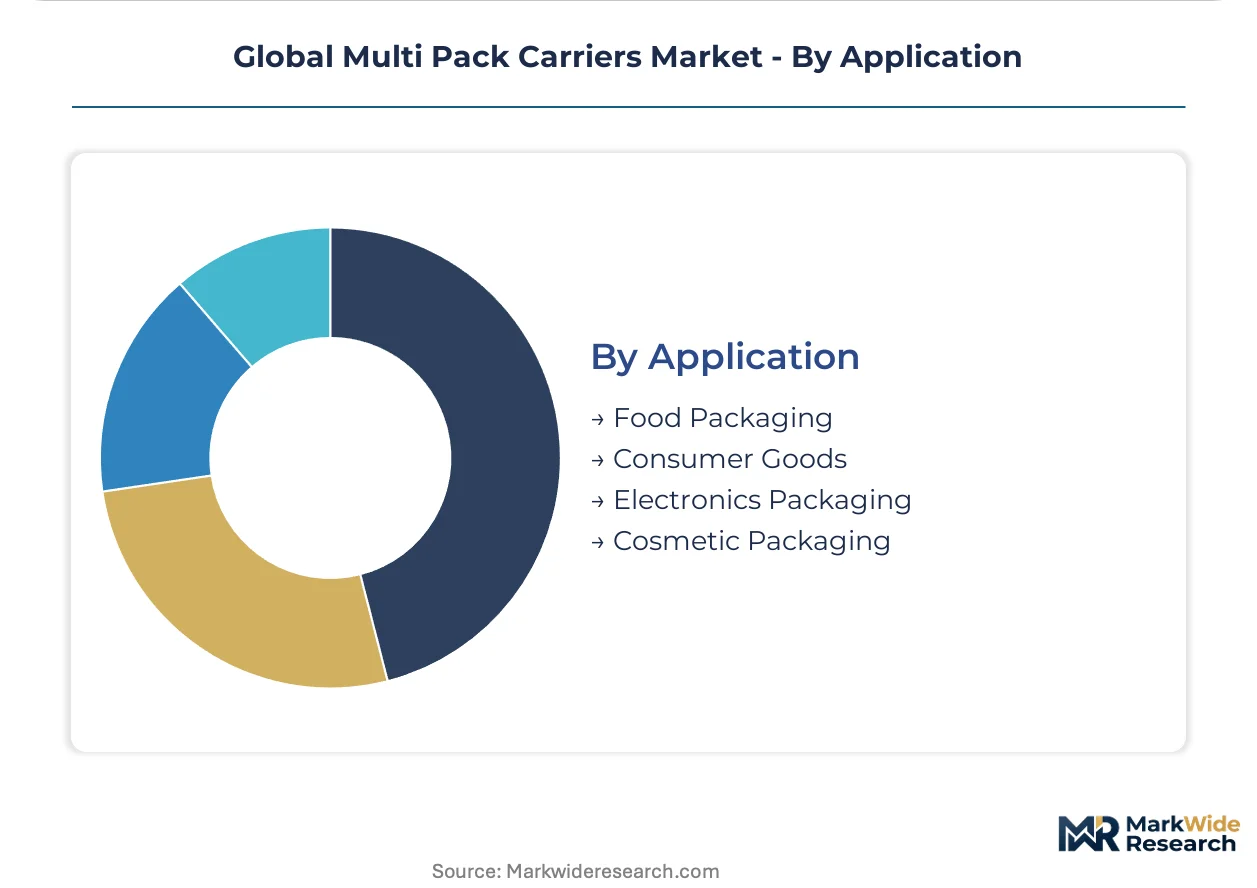
- Food Packaging:Beverage multi-packs dominate volume, with EFSA and FDA migration testing protocols for novel barrier coatings extending launch cycles. Pulp-molded carriers are displacing plastic rings in German, Dutch, and California markets under binding recyclability mandates.
- Cosmetic Packaging:Premium skincare and fragrance gift sets command 3-4x unit margins versus beverage applications. Rigid fiber carriers with embossed branding serve this segment, with demand concentrating in France, Italy, and South Korea.
- Consumer Goods:Household product multi-packs specify lower tensile requirements than beverage applications, permitting lighter fiber constructions and reduced material costs.
- Electronics Packaging:Anti-static and cushioning specifications for device accessories represent a narrow specialty segment with limited carrier overlap from beverage applications.
Food packaging deploys the greatest production capacity; cosmetic packaging delivers the highest margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Investment tax credits in South Carolina's packaging corridor are accelerating fiber carrier production scale-up for North American beverage export markets.
United States
California's extended producer responsibility program and Oregon's plastic restriction frameworks are mandating fiber carrier conversion by 2027. The EPA's state-level coordination on packaging waste reduction is tightening compliance timelines for major bottlers. Production clusters in South Carolina and Wisconsin are expanding wet-pressed fiber capacity to serve Coca-Cola and PepsiCo bottling networks.
Germany
Binding recyclability thresholds under the EU Green Deal are eliminating plastic ring carriers from supermarket supply chains. ECHA's REACH protocols are restricting per- and polyfluoroalkyl substances in barrier coatings, forcing reformulation investments. The Rhine-Ruhr industrial corridor hosts concentrated pulping and converting operations serving Heineken and AB InBev European bottling facilities.
Brazil
Anheuser-Busch InBev and Ambev export operations require EU-compliant packaging for European-bound product lines. ANVISA's evolving food-contact material standards are aligning with EFSA migration testing protocols. São Paulo state beverage production zones are piloting enzymatic biodegradable carriers for premium export segments.
India
Coca-Cola and PepsiCo bottling partners in Maharashtra and Karnataka are testing paper carrier systems ahead of anticipated national plastic restrictions. BIS certification requirements for food-contact packaging are extending qualification timelines for imported barrier coating technologies. The Pune-Nashik industrial belt is emerging as a converting hub for Western India beverage distribution networks.
Netherlands
Retailer sustainability scorecards at Ahold Delhaize and Jumbo Supermarkten are mandating verified fiber content and carbon footprint disclosure for all beverage packaging. The EU Single-Use Plastics Directive's implementation through Dutch environmental enforcement is accelerating carrier material transitions. Rotterdam port logistics clusters are consolidating import distribution for Nordic and German beverage markets.
Global Multi Pack Carriers Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across carrier material categories. The vendor base stratifies into three tiers: integrated pulp-and-paper producers with captive fiber sourcing, specialized packaging converters with applicator equipment integration capabilities, and regional distributors serving mid-tier bottlers. Dominant competitive moves include direct offtake agreements between brand owners and fiber producers, and capacity expansion in wet-pressed pulp-molded systems.
Within the integrated producer tier, WestRock Company and International Paper Company exemplify scale-driven positioning through upstream pulp control. DS Smith Plc and Mondi Group occupy specialist positions emphasizing high-speed line compatibility and kraft-based engineering. PakTech and Hi-Cone represent legacy plastic carrier specialists navigating material transition pressures through biodegradable formulation development.
| Leading Market Players |
|---|
| WestRock Company |
| PakTech |
| Hi-Cone |
| Smurfit Kappa Group |
| Graphic Packaging International |
| Sonoco Products Company |
| DS Smith Plc |
| Mondi Group |
| International Paper Company |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal recyclability mandates in Germany and the Netherlands are compelling beverage bottlers to specify wet-pressed fiber carriers, forcing converters to absorb pulp cost volatility while securing long-term offtake agreements that lock pricing structures.
Pricing Analysis
Short lead-time premiums of 15-25% apply to rush orders from beverage producers retrofitting applicator equipment ahead of regulatory deadlines. Contract-based long-term offtake agreements dominate procurement between major bottlers and integrated pulp producers, with price differentiation driven by certification grade and volume scale. Cost compression in standard-grade fiber carriers is intensifying because Scandinavian pulp mill concentration limits supplier alternatives. Independent regional bottlers exhibit the highest price sensitivity, while Heineken and AB InBev prioritize supply security over unit cost.
Supply Chain Analysis
Domestic-content requirements in Brazil and India are reshaping sourcing patterns for beverage export operations, mandating local converting capacity to satisfy ANVISA and BIS food-contact certification. Supply concentrates in Sweden, Finland, and Germany for bleached kraft pulp, with wet-pressed fiber equipment and barrier coating chemicals as critical component dependencies. Single-source vulnerability in Nordic pulp supply creates structural exposure to mill maintenance shutdowns. Distribution runs through direct procurement relationships between brand owners and integrated producers, displacing traditional packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race. Players are pursuing captive pulp supply to secure margin control against input cost volatility.
For Market Incumbents: Cement supply relationships with Brazilian and Indian bottlers ahead of anticipated plastic restrictions by securing multi-year offtake agreements. Add wet-pressed fiber capacity in South Carolina and Wisconsin to serve Coca-Cola and PepsiCo networks before California EPR penalties activate. Biodegradable carrier specialists represent the primary substitution threat requiring monitoring. For New Entrants and Emerging Players: California's extended producer responsibility program opens a window for fiber carrier specialists to capture mid-tier bottler demand without incumbent conversion line commitments. Target cosmetic multi-pack applications in France and South Korea where 3-4x margin premiums offset smaller volumes. Pursue direct technical collaboration with applicator equipment manufacturers to reduce line integration barriers. For Investors and Strategic Acquirers: The window for entry favors integrated pulp-and-paper producers with captive fiber sourcing and existing food-contact certification infrastructure. Long-term viability hinges on securing positions before EU REACH coating reformulation deadlines consolidate supplier relationships. Watch for EFSA migration testing protocol changes as the inflection signal for barrier coating technology winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive softwood pulp access insulates WestRock and International Paper from Scandinavian mill concentration risk. |
| Wet-Pressed Fiber Capacity Expansion | South Carolina production clusters position suppliers to serve Coca-Cola bottling networks under California EPR frameworks. |
| Barrier Coating Reformulation Investment | REACH per- and polyfluoroalkyl substance restrictions force R&D spending to maintain EFSA food-contact certification. |
| Direct Procurement Relationship Development | Heineken and AB InBev multi-year agreements eliminate distributor margins while accelerating technical collaboration. |
| Biodegradable Carrier Qualification Programs | Enzymatic formulation pilots in São Paulo state position Ambev for EU import compliance on premium export lines. |
Study Parameters
Independent corroboration across beverage procurement executives, pulp mill operations managers, and packaging converter technical directors underwrites the qualitative findings in this study. Primary interviews with applicator equipment specialists and sustainability compliance officers at major bottlers combined with secondary validation from SEC filings, EU regulatory databases, and trade customs records. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across material categories.
Comparable historical reference periods anchored the forecast window to pre-regulatory and post-implementation demand phases across jurisdictions. The analytical framework segments by material type, end-user channel, and distribution pathway, with CAGRs derived from regression analysis against pulp price indices and bottling line conversion rates. Wet-pressed fiber performance benchmarks and barrier coating certification timelines served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for enzymatic biodegradable carriers would alter the outlook if marine decomposition standards accelerate. Forecasts reflect assumptions about EU Green Deal implementation consistency and California EPR fee structures. Pulp price volatility, REACH substance restriction expansion, and applicator retrofitting cost overruns represent specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Snap Secure Containers Market
Containers
Half Height Containers Market
Containers
Trays Market
Containers
Thin Wall Plastic Containers Market
Containers
PS Containers Market
Containers
Bulk Container Packaging Market
Containers
Container Coating Market
Containers
Modular Container Market
Containers
EPS Shippers Market
Containers
Stackable Plastic Trays Market
Containers
Chest-Style Insulated Containers Market
Containers
Roll Containers Market
Containers
Child-Resistant Containers Market
Containers
In-Mold Labelled Containers Market
Containers
Injection Molding Containers Market
Containers
Tin Containers Market