
 Reel in Box Market | 2026-2036
Reel in Box Market Size, Share, and Industry Trends Forecast 2026-2036
Reel in Box Market Analytics
The Reel in Box Market is recalibrating around a widening gap between premium precision-engineered systems and commodity-grade alternatives. Carris Reels leverages its vertical integration in composite manufacturing to command premium positioning. Axjo anchors its European footprint through specialized spool engineering for industrial-grade applications. Reelcraft Industries dominates commercial distribution channels with standardized product lines serving volume buyers.
A reel in box denotes an integrated packaging and deployment system combining a wound spool mechanism with protective housing, typically constructed from marine-grade aluminum or glass-reinforced polymer composites rated for saltwater corrosion resistance, designed to store, transport, and dispense line, cable, or hose in fishing, industrial, and utility applications. Stainless Steel construction leads material segmentation due to its durability in marine environments, while Composite materials represent the fastest-growing category driven by weight reduction demands among Professional Fishers. Online Retail channels capture expanding margin pools as direct-to-consumer logistics reshape traditional specialty store networks.
EPA guidelines in the United States restrict certain polymer additives in marine equipment, while REACH in Europe mandates disclosure of substances of very high concern in aluminum and composite formulations, collectively elevating compliance costs for manufacturers seeking dual-market access. Japan's METI enforces JIS standards on reel mechanical performance that exporters must satisfy for commercial fishing fleet procurement. Stakeholders must monitor evolving material certification requirements across multiple jurisdictions to maintain market access without sacrificing cost competitiveness.
Market Dynamics
Precision-engineered reel systems are forcing a bifurcation between marine-grade stainless steel and lightweight composite formulations, with Professional Fishers driving specification upgrades that ripple through material certification requirements across Hamburg, Bremen, and Japanese port manufacturing clusters.
Growth Catalysts
- REACH compliance tightening:ECHA disclosure mandates for substances of very high concern in aluminum formulations are accelerating R&D investment in alternative corrosion-resistant alloys by German manufacturers clustered around North Sea ports.
- Professional Fisher equipment upgrade cycles:Fleet operators in Japan are replacing legacy mechanical reels with precision-engineered systems to satisfy METI procurement standards for commercial vessels.
- Composite material innovation:Glass-reinforced polymer formulations rated for saltwater resistance are displacing traditional metal housings in weight-sensitive deep-water applications.
Market Restraints
- Aluminum alloy supply concentration:Primary smelting capacity for marine-grade aluminum concentrates in a limited number of European and Asian suppliers, exposing manufacturers to input cost volatility.
- Dual-certification burden:EPA restrictions on polymer additives in US markets and REACH disclosure requirements in Europe force parallel compliance tracks, elevating fixed costs for cross-border suppliers.
- Mechanical performance standard divergence:JIS standards enforced by METI in Japan diverge from ISO mechanical testing protocols, creating technical barriers for unified product platforms.
Strategic Opportunities
- Direct-to-consumer channel expansion:Online retail logistics are capturing margin pools previously held by specialty marine equipment stores, enabling manufacturers to build owned customer relationships.
- Utility sector hose deployment applications:Industrial-grade reel systems originally engineered for fishing line management are finding adoption in municipal water and gas utility maintenance fleets.
- EU Green Deal material incentives:ESG-linked procurement preferences in European public sector fleets are creating demand pull for recyclable composite formulations over traditional metal constructions.
Industry Challenges
- Corrosion engineering talent scarcity:Specialized expertise in saltwater-resistant material science concentrates in Hamburg and Bremen industrial zones, constraining expansion by manufacturers elsewhere.
- Legacy fleet integration complexity:Precision-engineered reel systems require adapter kits and retraining for vessels operating mechanical legacy equipment, slowing replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reel in Box Market |
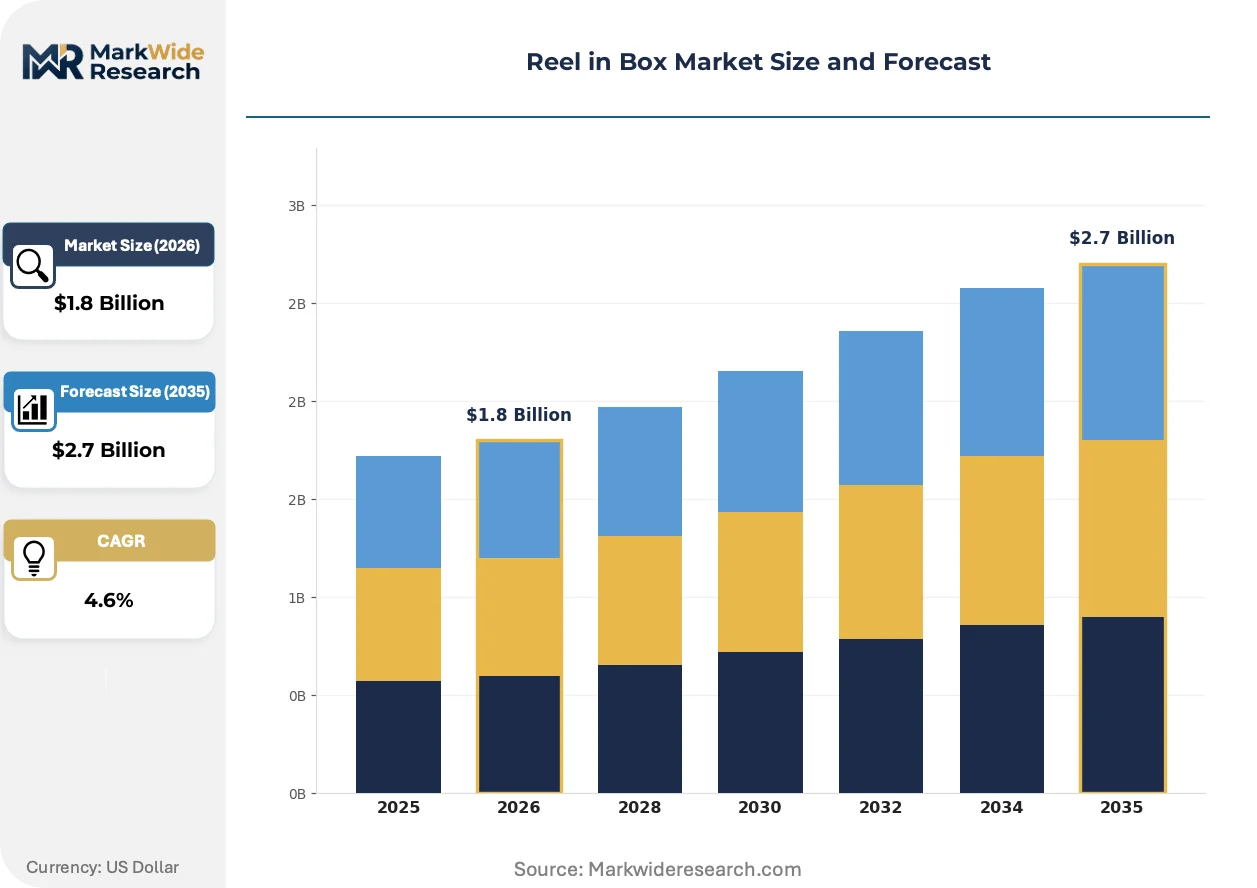
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fishing Reel, Tackle Box, Rod Holder, Bait Container Material: Plastic, Aluminum, Stainless Steel, Composite End User: Amateur Anglers, Professional Fishers, Retailers, Outdoor Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Mass Merchandisers, Direct Sales |
| Companies Covered | Carris Reels, Axjo, Reelcraft Industries, Hannay Reels, Coxreels, Nederman Holding, Cavotec SA, United Equipment Accessories, Gardena, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reel in Box Market Evolving Landscape
Active automation of spool deployment mechanisms is compressing the performance gap between manual and powered systems, while regulatory disclosure requirements and channel restructuring simultaneously reshape competitive positioning.
Smart tension-sensing spool mechanisms are automating line deployment calibration in real-time sea conditions. Professional Fishers operating deep-water charter fleets in Japan and Germany are adopting these systems at accelerating replacement cycles. This automation is compressing the skill differential between experienced deckhands and novice crew, enabling fleet operators to reduce training overhead.
REACH Article 33 disclosure requirements for substances of very high concern in aluminum and composite formulations are mandating supply chain transparency down to raw material batch levels. European manufacturers serving both consumer and commercial segments must now maintain dual documentation systems. Marine-grade aluminum suppliers in Germany are responding by investing in blockchain-traceable material certification to satisfy ECHA audit protocols.
Specialty store networks that historically dominated marine equipment distribution are losing share to direct-to-consumer platforms with integrated sizing configurators. Professional Fishers in dispersed port communities now bypass traditional retail entirely, purchasing precision-engineered reels through manufacturer-owned digital channels. This channel rotation is most visible in Japanese and German markets where fleet procurement officers have established direct supplier relationships.
Reel in Box Market Segmentation
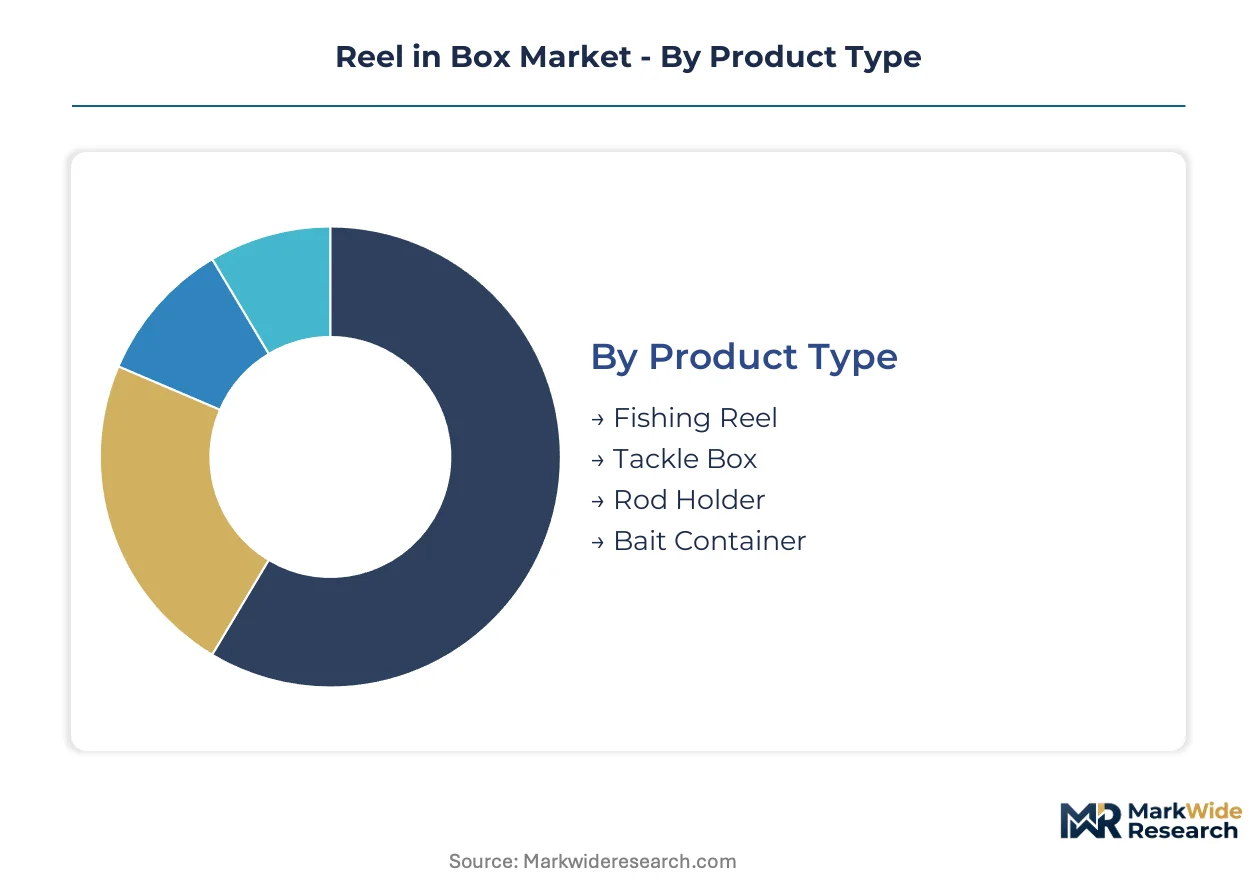
Segmentation in the Reel in Box Market reveals divergent specification requirements between recreational and commercial buyers. Material choices and distribution access points determine margin capture across precision-engineered and commodity-grade product tiers.
Product Type:
Application intensity separates casual users from commercial operators seeking integrated deployment systems.
- Fishing Reel:Precision-engineered spool mechanisms with marine-grade corrosion resistance dominate commercial fleet procurement. Professional Fishers in Japan and Germany specify these systems to satisfy METI and REACH compliance mandates for saltwater durability.
- Tackle Box:Integrated storage housings with modular compartment engineering serve organized line and lure management. Demand concentrates among Amateur Anglers in North American and European recreational markets where portability and waterproof sealing drive selection.
- Rod Holder:Mounting systems for secure rod storage during transit and deployment.
- Bait Container:Insulated and aerated storage units for live bait preservation.
Volume sits with Fishing Reel systems; growth tilts toward Tackle Box configurations as recreational participation expands.
Material:
Weight-performance tradeoffs separate saltwater commercial applications from freshwater recreational use.
- Stainless Steel:Marine-grade alloys rated for extreme corrosion resistance in continuous saltwater exposure. Professional Fishers operating deep-water charter fleets in Hamburg and Bremen port regions specify these housings despite weight penalties.
- Composite:Glass-reinforced polymer formulations achieving saltwater-rated performance at reduced mass. Japanese commercial fleets are adopting these most quickly to improve deckhand ergonomics and fuel efficiency.
- Plastic:Injection-molded polymers for cost-sensitive recreational applications.
- Aluminum:Lightweight metal housings balancing durability with moderate weight reduction.
Stainless Steel commands the installed base; composites are climbing the fastest on weight-reduction specifications.
End User:
Procurement sophistication ranges from individual retail purchase to fleet-scale vendor negotiation.
- Professional Fishers:Fleet operators and charter captains sourcing precision-engineered systems through direct manufacturer relationships. Japanese and German commercial operators drive specification upgrades with METI procurement standards and REACH material disclosure requirements.
- Amateur Anglers:Recreational participants purchasing through retail channels with price sensitivity and brand familiarity as primary selectors. This segment concentrates volume in North American and European consumer markets.
- Retailers:Specialty marine equipment stores and mass merchandisers stocking inventory for resale.
- Outdoor Enthusiasts:Multi-activity participants seeking crossover equipment for camping and boating.
Professional Fishers anchor premium pricing; Amateur Anglers expand addressable market breadth.
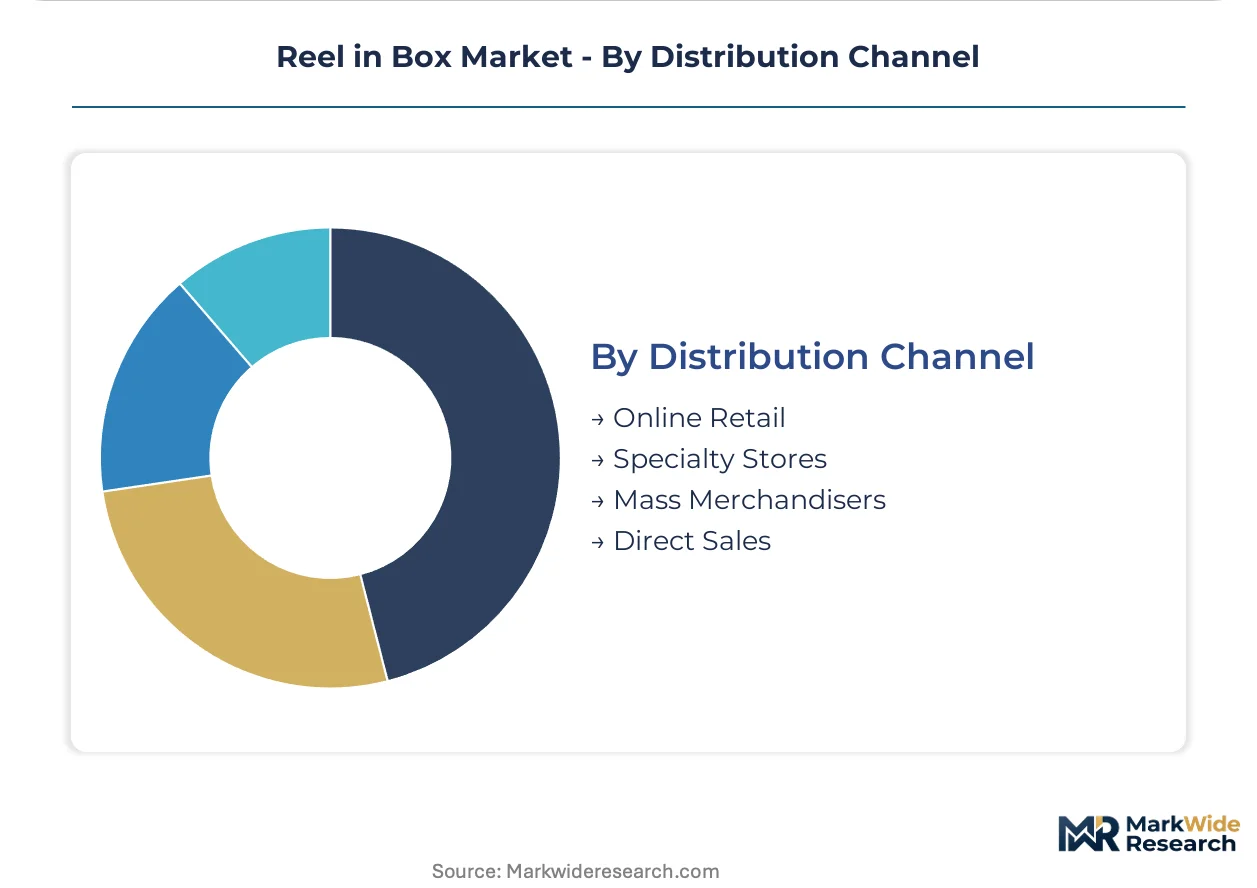
Distribution Channel:
Channel selection determines margin retention and customer relationship ownership.
- Online Retail:Direct-to-consumer platforms with integrated sizing configurators and logistics networks. Professional Fishers in dispersed Japanese and German port communities bypass traditional retail entirely through manufacturer-owned digital channels.
- Specialty Stores:Marine equipment retailers with technical staff and hands-on product evaluation. These outlets retain importance for Amateur Anglers seeking pre-purchase handling and local service support.
- Mass Merchandisers:Big-box retailers serving price-sensitive recreational buyers with standardized product lines.
- Direct Sales:Manufacturer-to-fleet procurement relationships for commercial volume contracts.
Specialty Stores hold legacy position; Online Retail is gaining share fastest on margin capture and geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg and Bremen anchor European manufacturing concentration for precision-engineered reel systems, with Japanese port cities driving parallel specification upgrades across commercial fishing fleets.
United States
Commercial charter operators in Florida and Pacific Northwest ports are replacing legacy mechanical reels with corrosion-resistant systems. EPA restrictions on polymer additives in marine equipment elevate compliance costs for cross-border suppliers. Manufacturing activity concentrates around Great Lakes industrial corridors where specialty metal fabrication serves both freshwater and saltwater applications.
Germany
Professional Fishers operating North Sea charter fleets specify REACH-compliant aluminum and composite formulations for saltwater durability. ECHA disclosure mandates for substances of very high concern accelerate R&D investment in alternative corrosion-resistant alloys. Specialized equipment manufacturers cluster around Hamburg and Bremen port regions, leveraging proximity to commercial fleet operators.
Japan
Fleet operators in Tokyo Bay and Kyushu fishing ports adopt precision-engineered systems to satisfy METI procurement standards for commercial vessels. JIS standards on reel mechanical performance create technical barriers for non-compliant imports. Manufacturing expertise concentrates in Nagoya industrial zones serving both domestic fleet replacement and export markets.
China
Domestic commercial fishing operators in Fujian and Zhejiang provinces drive volume demand for standardized reel systems. GB standards on marine equipment mechanical performance diverge from ISO protocols, complicating unified product platforms. Yangtze River Delta manufacturing zones supply both domestic fleet operators and export markets with cost-optimized formulations.
Australia
Deep-water charter operators in Queensland and Western Australia specify lightweight composite reels for extended-range operations. National environmental regulations on marine equipment materials align with broader Commonwealth sustainability frameworks. Industrial fabrication capacity concentrates in Melbourne and Sydney metropolitan areas serving regional fleet maintenance networks.
Reel in Box Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification and distribution channel dimensions. The vendor base stratifies into three tiers: integrated composite manufacturers commanding price premiums, specialized spool engineering houses serving industrial-grade applications, and standardized product distributors capturing volume buyers through commercial channels. Dominant competitive moves include direct-to-consumer channel expansion and utility sector diversification beyond core fishing applications.
Among North American fabricators, Carris Reels and Reelcraft Industries exemplify contrasting strategic positions. Carris Reels occupies the integrated manufacturing tier with captive composite production capabilities. Reelcraft Industries anchors the commercial distribution tier with standardized product lines serving volume procurement relationships. European specialists including Axjo represent the precision-engineering archetype, with GmbH-structured entities clustered around German port manufacturing zones.
| Leading Market Players |
|---|
| Carris Reels |
| Axjo |
| Reelcraft Industries |
| Hannay Reels |
| Coxreels |
| Nederman Holding |
| Cavotec SA |
| United Equipment Accessories |
| Gardena |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists clustered around Hamburg and Bremen port regions anchor supply discipline through captive aluminum casting operations, translating upstream control into pricing power that resists commodity erosion despite REACH compliance cost inflation.
Pricing Analysis
Value-based pricing anchored to saltwater durability outcomes separates precision-engineered reels from commodity alternatives. Three-tier pricing structure across premium corrosion-resistant systems, standard marine-grade units, and economy recreational lines reflects certification grade and volume scale differentiation. Cost compression in economy tiers is intensifying because amateur anglers migrate toward direct-to-consumer channels. Professional fishers exhibit lowest price sensitivity due to METI procurement standards and fleet uptime requirements.
Supply Chain Analysis
Single-source vulnerability sits with primary aluminum smelting capacity concentrated in Germany, Norway, and China. Marine-grade alloy feedstock draws from bauxite processing clusters in Guinea and Australia, glass-reinforced polymer resins from South Korean petrochemical complexes, and precision bearing assemblies from Japanese industrial zones. Tariff exposure on Chinese aluminum semifinished products elevates input cost volatility for European fabricators. Distribution runs through manufacturer-direct platforms for commercial fleets and specialty marine retailers for recreational buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
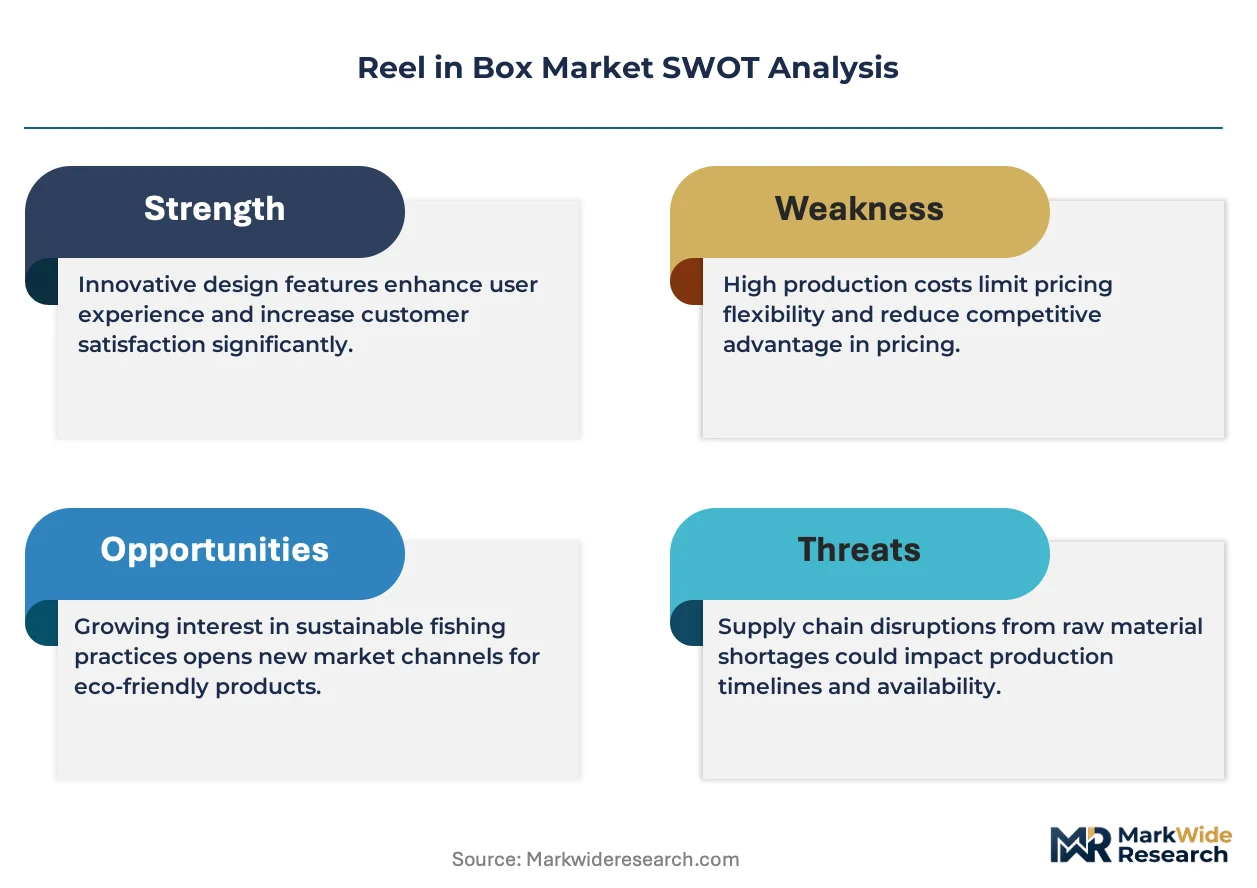
REACH disclosure mandates and dual-certification burdens are accelerating consolidation, forcing sub-scale composite formulators and regional distributors toward exit or acquisition as compliance fixed costs outrun revenue bases.
For Market Incumbents: Anchor Hamburg and Bremen manufacturing footprints through backward integration into marine-grade aluminum casting to secure supply against Norwegian smelter concentration. Invest in blockchain-traceable material certification systems to satisfy ECHA audit protocols and defend premium positioning against emerging Asian composite specialists.
For New Entrants and Emerging Players: Direct-to-consumer configurators with integrated sizing algorithms offer the lowest-friction entry path. Target utility sector hose deployment applications in German municipal fleets as the most penetrable white-space segment, leveraging transferable spool engineering from fishing line management systems.
For Investors and Strategic Acquirers: Distressed-cycle entries favor precision-engineering specialists with captive REACH-compliant material certifications in German port manufacturing zones. Long-term viability hinges on utility sector diversification beyond core fishing applications. Watch JIS-GB standard convergence as the inflection signal for unified product platform economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Casting | Captive supply of marine-grade alloys insulates Hamburg manufacturers from Norwegian smelter price volatility. |
| Blockchain Material Certification | Traceable batch documentation satisfies ECHA Article 33 disclosure mandates for composite formulations. |
| Utility Sector Diversification | Municipal water and gas fleet procurement opens volume channels beyond saturated fishing equipment markets. |
| Direct-to-Consumer Platform Launch | Manufacturer-owned digital channels capture margin pools previously held by specialty marine retailers. |
| Composite Formulation R&D Partnership | Collaboration with German polymer institutes accelerates glass-reinforced saltwater-rated housing development. |
Research Methodology
Independent corroboration across fleet procurement officers, marine equipment distributors, composite material suppliers, and ECHA regulatory consultants underwrites the qualitative findings. Primary interviews with Hamburg and Bremen manufacturers, Japanese METI compliance officers, and US EPA environmental engineers combined with secondary validation from customs trade databases, SEC equipment manufacturer filings, and JIS standard documentation. Bottom-up volume estimates triangulated against top-down addressable market calculations.
Comparable-period anchoring to historical fleet replacement cycles and regulatory implementation timelines structured the projection framework across the analysis window. Segmentation dimensions modeled include product type, material formulation, end-user procurement sophistication, and distribution channel ownership. CAGRs derived from fitted growth curves incorporating REACH compliance cost trajectories, composite material substitution elasticities, and channel shift velocity parameters.
The model holds under stable regulatory implementation schedules; deviation in ECHA enforcement intensity or METI standard revision timing would shift replacement cycle assumptions. Forecasts reflect documented assumptions about material certification cost pass-through rates and fleet procurement budget elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Thermoformed Trays Market
Packaging Materials
VCI Packaging Market
Packaging Materials
Packaging Straps and Buckles Market
Packaging Materials
Polystyrene Packaging Market
Packaging Materials
Cold Seal Films Market
Packaging Materials
Packaging Materials Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
Foil Laminates Market
Packaging Materials
Foam Trays Market
Packaging Materials
Packaging Primers Market
Packaging Materials
Global Adherence Packaging Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Skin Packaging Market
Packaging Materials
Germany Packaging Market
Packaging Materials
Cushion Case Liner Market