
 Global Anti-Static Films Market | 2026-2036
Global Anti-Static Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Static Films Market Analysis
The capital-intensity divergence between integrated resin producers and film converters is unwinding competitive boundaries in the anti-static films sector. Achilles Corporation leverages captive polymer supply to dominate Japanese electronics packaging channels. Toray Industries Inc. sustains technology leadership through precision coextrusion capabilities for sub-50μm specifications.
Anti-static films are polymer-based sheet materials engineered with conductive additives to maintain surface resistivity between 10^6 and 10^12 ohms per square, primarily serving to prevent electrostatic discharge damage to sensitive electronic components during handling and transit. Polyethylene formulations anchor volume demand due to cost efficiency in consumer electronics packaging, while PET variants occupy premium semiconductor equipment applications where optical clarity and dimensional stability command higher margins. Thickness segmentation below 50μm is accelerating fastest as miniaturization trends in medical devices and chip packaging drive thinner protective layers.
EPA guidelines in the United States, REACH in the European Union, and GB standards under China's SAMR collectively govern additive migration limits and surface resistivity testing protocols, forcing reformulation of legacy carbon-black loaded films. Japan's METI and South Korea's MFDS are tightening electrostatic control requirements for pharmaceutical and medical device packaging, expanding addressable demand beyond traditional electronics. Stakeholders must monitor regulatory divergence on perfluorinated additive bans versus carbon nanotube approvals to anticipate raw material cost trajectories and compliance timelines.
Market Dynamics
Carbon nanotube conductive additives are displacing legacy carbon-black formulations as semiconductor manufacturers demand tighter surface resistivity tolerances below 10^9 ohms per square, compressing reformulation cycles for compounders serving East Asian electronics clusters.
Growth Catalysts
- Semiconductor packaging densification:Wafer-level chip scale packaging in Taiwan and South Korea requires sub-50μm anti-static films with optical-grade clarity, pulling demand from polyethylene toward PET and coextruded multilayer structures.
- REACH surface resistivity mandates:ECHA's tightening additive migration limits for electrostatic discharge materials force converters toward halogen-free ionic conductive polymers, expanding addressable premium segments.
- Medical device miniaturization:Cardiac implant and diagnostic sensor manufacturers in Japan and Germany specify anti-static films for sterile barrier packaging of microelectronic components, opening non-electronics verticals.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin prices track naphtha and ethane spreads, squeezing converter margins when upstream petrochemical cycles turn.
- East Asian supply concentration:Over 60% of carbon nanotube masterbatch production sits with Chinese and South Korean compounders, creating single-source vulnerability for Western film extruders.
- Perfluorinated additive bans:Sweden's chemicals authority and several German Länder restrict fluorinated surfactants used in some premium anti-static coatings, forcing costly reformulation.
Strategic Opportunities
- India electronics manufacturing:PLI scheme subsidies for semiconductor and mobile phone assembly in Gujarat and Tamil Nadu create virgin demand for anti-static packaging materials without incumbent supplier lock-in.
- Biodegradable conductive polymers:Convergence of polylactic acid substrates with inherently dissipative polymer alloys addresses single-use medical packaging waste regulations in France and Italy.
- Direct compounder-to-OEM relationships:Bypassing traditional film converter distribution, resin producers like those in Saudi Arabia's petrochemical complexes offer toll-compounded anti-static masterbatches to large electronics assemblers.
Industry Challenges
- Thin-film extrusion technician scarcity:Precision coextrusion of sub-25μm multilayer structures requires specialized die design expertise concentrated among aging workforces in Japan and Germany.
- Dual certification timelines:Simultaneous FDA 510(k) medical device packaging clearance and EPA electrostatic discharge compliance extend product launch cycles by 14-22 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Static Films Market |
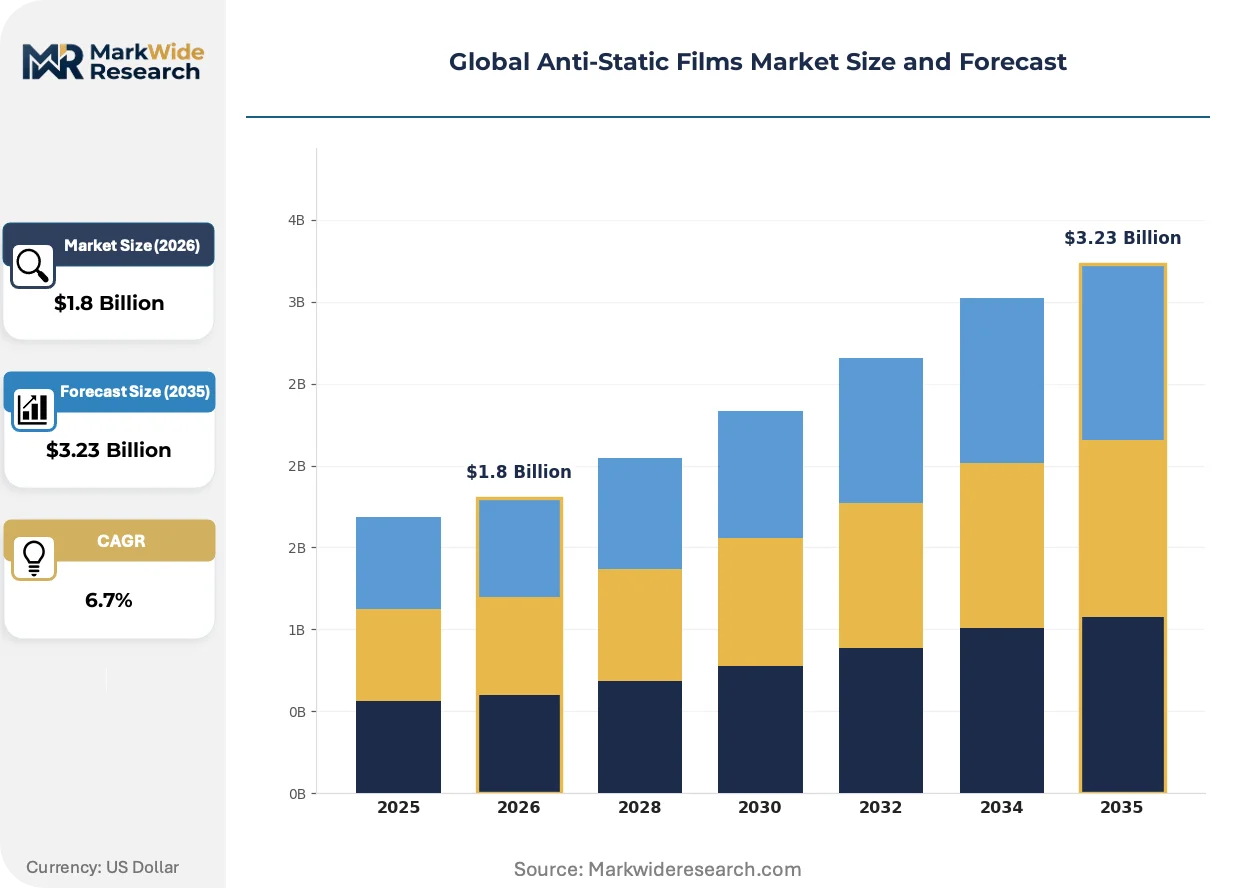
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
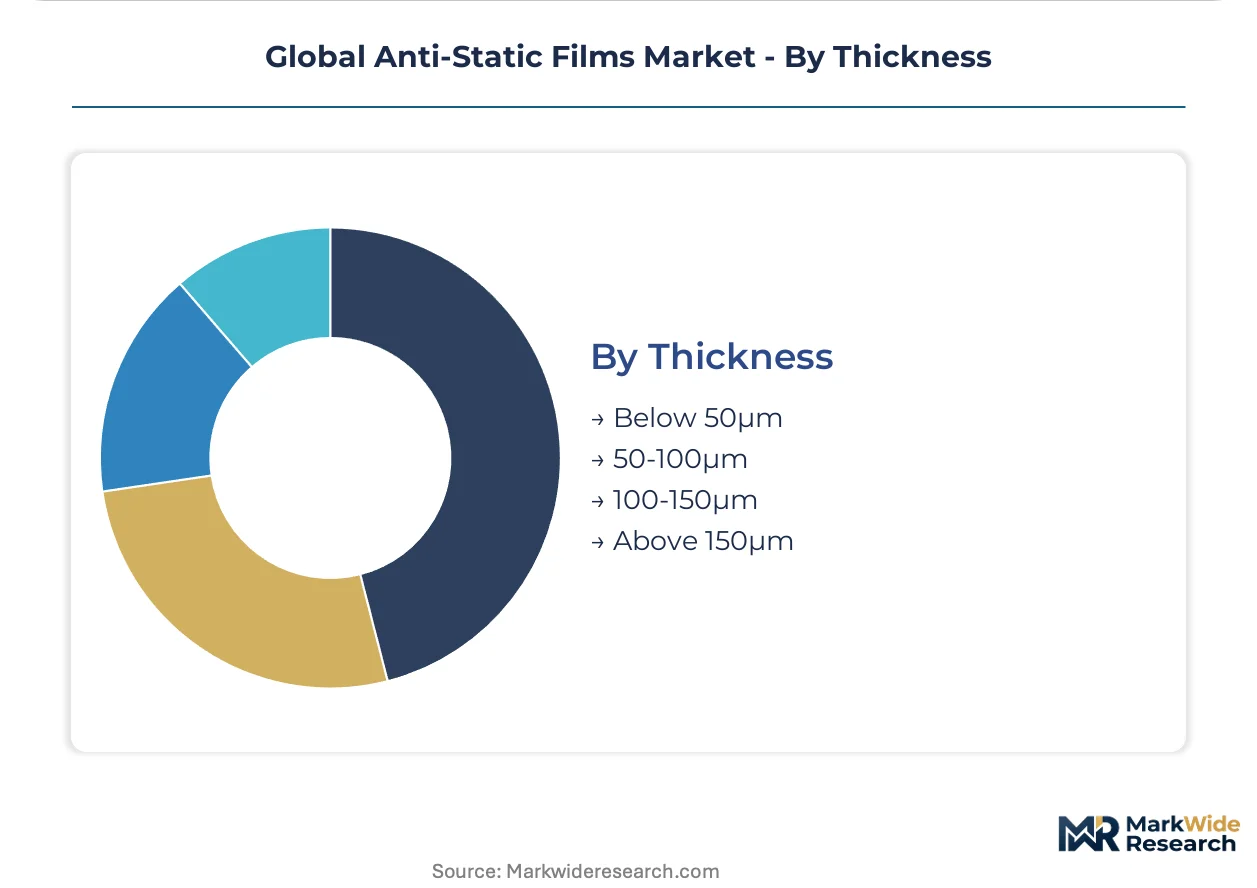
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, PET Application: Electronics Packaging, Automotive Components, Medical Devices, Semiconductor Equipment End User: Manufacturers, Retailers, Distributors, Service Providers Thickness: Below 50μm, 50-100μm, 100-150μm, Above 150μm |
| Companies Covered | Achilles Corporation, Toyobo Co. Ltd., 3M, Toray Industries Inc., Mitsubishi Chemical Group Corporation, Klöckner Pentaplast, Nan Ya Plastics Corp, Saint-Gobain Corp, Blueridge Films, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Static Films Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are fragmenting the anti-static films competitive landscape into specialty compounders with captive additive synthesis versus commodity converters dependent on merchant masterbatches.
Multi-walled carbon nanotube conductive networks is bifurcating the anti-static films technology hierarchy. These nanoscale conductive pathways achieve percolation at 0.5-2% loading versus 15-25% for carbon black, preserving base polymer mechanical properties. Semiconductor equipment OEMs in Hsinchu and Pyeongtaek specify nanotube-loaded PET for wafer shipping pods, paying 40-60% premiums over standard polyethylene. The technology is bifurcating margin structures between precision film specialists with nanomaterial handling capabilities and commodity extruders locked in carbon-black formulations.
ECHA's restriction proposal on per- and polyfluoroalkyl substances extends to fluorinated anti-static surfactants used in optical-grade films. The industrial consequence forces immediate substitution toward quaternary ammonium salt ionomers and inherently conductive polymer blends. Premium display packaging segments serving Dutch and German OLED manufacturers face 8-14 month qualification delays as they validate non-fluorinated surface resistivity performance across temperature and humidity ranges.
Consolidated procurement through electronics manufacturing services providers concentrates anti-static film specification authority with Foxconn, Jabil, and Flex. These intermediaries displace direct OEM-supplier relationships, unbundling technical service from volume pricing and compressing converter margins. The shift is most visible in Shenzhen and Ho Chi Minh City assembly corridors, where EMS procurement teams mandate pan-Asian supplier audits and unified masterbatch approval databases.
Global Anti-Static Films Market Segmentation
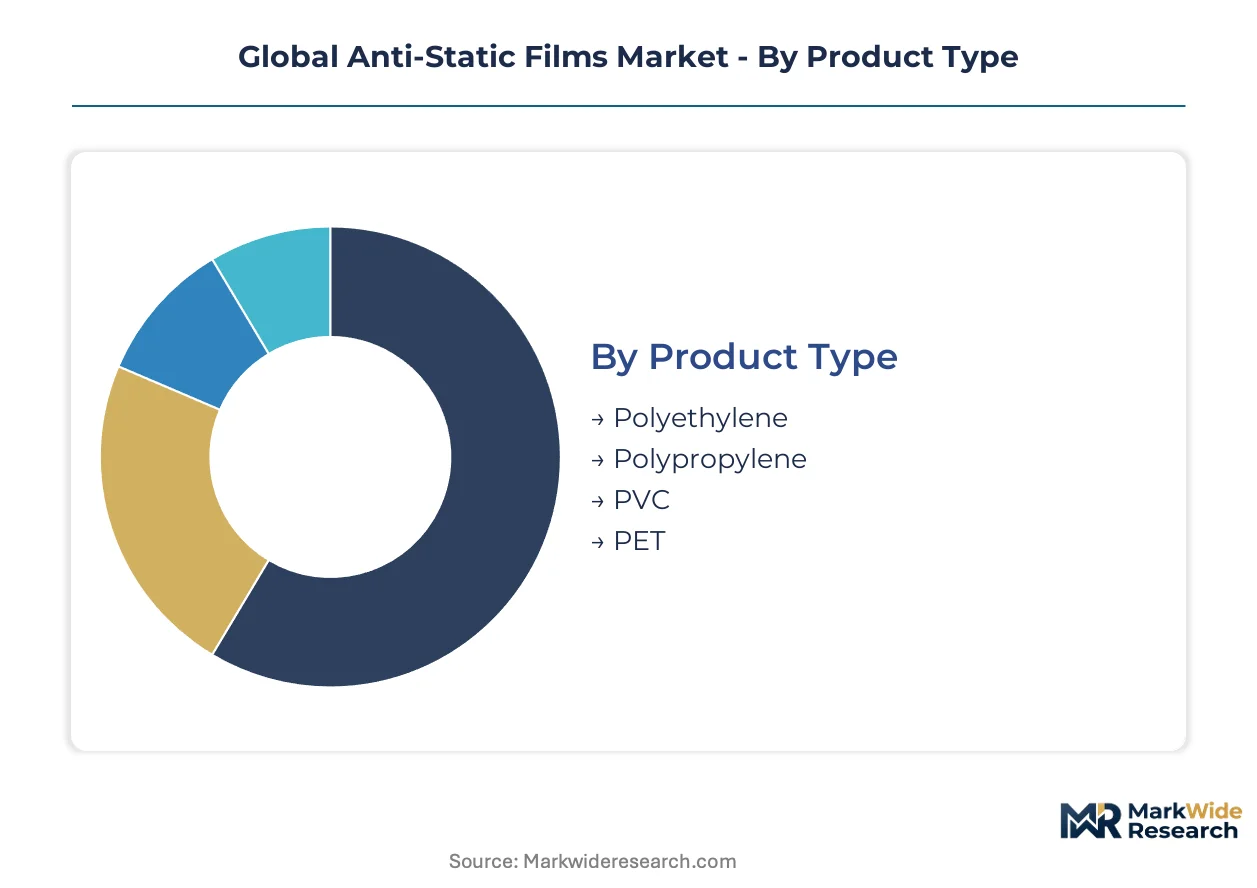
Anti-static films segment across material chemistry, functional thickness, and end-use precision requirements. Each dimension carries distinct margin structures and technical barriers that determine supplier positioning and customer switching costs.
Product Type:
Polyethylene and PET command divergent margin pools based on optical clarity requirements and semiconductor qualification timelines.
- Polyethylene:Linear low-density formulations dominate consumer electronics packaging through cost-efficient carbon-black loading. Wafer shipping operations in Taiwan and South Korea specify polyethylene for non-optical applications where surface resistivity tolerances exceed 10^9 ohms per square.
- PET:Biaxially oriented structures with multi-walled carbon nanotube networks achieve sub-50μm precision for semiconductor equipment pods. German and Dutch OLED manufacturers pay substantial premiums for optical-grade clarity combined with electrostatic dissipation.
- Polypropylene:Cast film variants serve automotive component trays requiring thermal stability during engine bay exposure.
- PVC:Calendered formulations persist in legacy industrial packaging despite REACH additive migration scrutiny.
Polyethylene holds installed capacity. PET is rotating up the share rankings.
Application:
Application segmentation tracks value destruction risk from electrostatic discharge, with semiconductor and medical verticals commanding specification authority.
- Electronics Packaging:Smartphone and tablet assembly lines in Shenzhen and Ho Chi Minh City consume volume polyethylene films. EMS procurement teams at Foxconn and Jabil consolidate masterbatch approvals across pan-Asian supplier networks.
- Semiconductor Equipment:Wafer-level chip scale packaging demands sub-50μm PET with carbon nanotube conductivity below 10^9 ohms per square. Hsinchu and Pyeongtaek equipment OEMs enforce 14-22 month dual certification timelines combining EPA electrostatic compliance with FDA 510(k) clearance.
- Medical Devices:Cardiac implant and diagnostic sensor packaging in Japan and Germany requires sterile barrier properties with anti-static performance. METI and MFDS tightening of electrostatic control standards expands addressable demand beyond traditional electronics.
- Automotive Components:EV battery module shipping trays specify thicker films with thermal resistance for assembly line transit.
Electronics packaging holds installed capacity. Semiconductor equipment is rotating up the share rankings.
Thickness:
Thickness segmentation correlates directly with miniaturization trends in medical devices and chip packaging, where thinner layers command technical premiums.
- Below 50μm:Precision coextrusion of multilayer structures requires specialized die design expertise concentrated among aging workforces in Japan and Germany. Wafer-level packaging in Taiwan and South Korea drives steepest expansion trajectory for this specification band.
- 50-100μm:Standard consumer electronics packaging thickness where polyethylene formulations anchor volume economics.
- 100-150μm:Automotive and industrial applications requiring puncture resistance during heavy component handling.
- Above 150μm:Structural trays and reusable shipping containers for capital equipment logistics.
50-100μm holds installed capacity. Below 50μm is rotating up the share rankings.
End User:
End user segmentation reveals procurement pattern divergence between direct OEM relationships and consolidated EMS channel control.
- Manufacturers:Semiconductor fabs and medical device OEMs in Japan and Germany specify directly, maintaining technical service relationships with precision film specialists.
- Distributors:Merchant masterbatch and film converter networks serve mid-tier electronics assemblers without captive compounder access.
- Retailers:Consumer electronics brands with private-label packaging requirements.
- Service Providers:Third-party logistics operators managing sterile barrier packaging for pharmaceutical distribution.
Manufacturers hold installed capacity. Distributors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German precision film converters while Taiwanese compounders compete on throughput volume. Japanese resin producers capture margin through captive additive synthesis. Chinese masterbatch suppliers face margin compression from carbon nanotube import dependence.
United States
Semiconductor equipment OEMs in Austin and Phoenix specify sub-50μm PET films for wafer shipping pods. EPA tightening of electrostatic discharge testing protocols extends qualification timelines for new film formulations. Boston-area medical device manufacturers drive sterile barrier packaging demand for cardiac implants.
Germany
Dutch and German OLED display manufacturers pay substantial premiums for optical-grade anti-static films with non-fluorinated surface treatments. ECHA restrictions on perfluorinated surfactants force immediate reformulation toward quaternary ammonium salt ionomers. Düsseldorf and Stuttgart packaging converters face 8-14 month validation delays for REACH-compliant alternatives.
China
Shenzhen electronics manufacturing services providers consolidate procurement authority across pan-Asian supplier networks. SAMR GB standards on additive migration limits diverge from REACH timelines, creating dual compliance burdens for exporters. Suzhou and Dongguan film extruders scale carbon-black loaded polyethylene for consumer electronics trays.
Japan
Medical device packaging for diagnostic sensors and cardiac implants expands addressable demand beyond traditional electronics verticals. METI tightening of electrostatic control standards for pharmaceutical packaging forces reformulation of legacy films. Osaka and Nagoya precision coextrusion specialists maintain die design expertise for sub-25μm multilayer structures.
South Korea
Hsinchu and Pyeongtaek equipment manufacturers enforce 14-22 month dual certification timelines combining EPA compliance with FDA 510(k) clearance. MFDS pharmaceutical packaging regulations expand anti-static film specifications to sterile barrier applications. Seoul-based compounders dominate multi-walled carbon nanotube masterbatch production for sub-10^9 ohm per square tolerances.
Global Anti-Static Films Market Vendor Landscape
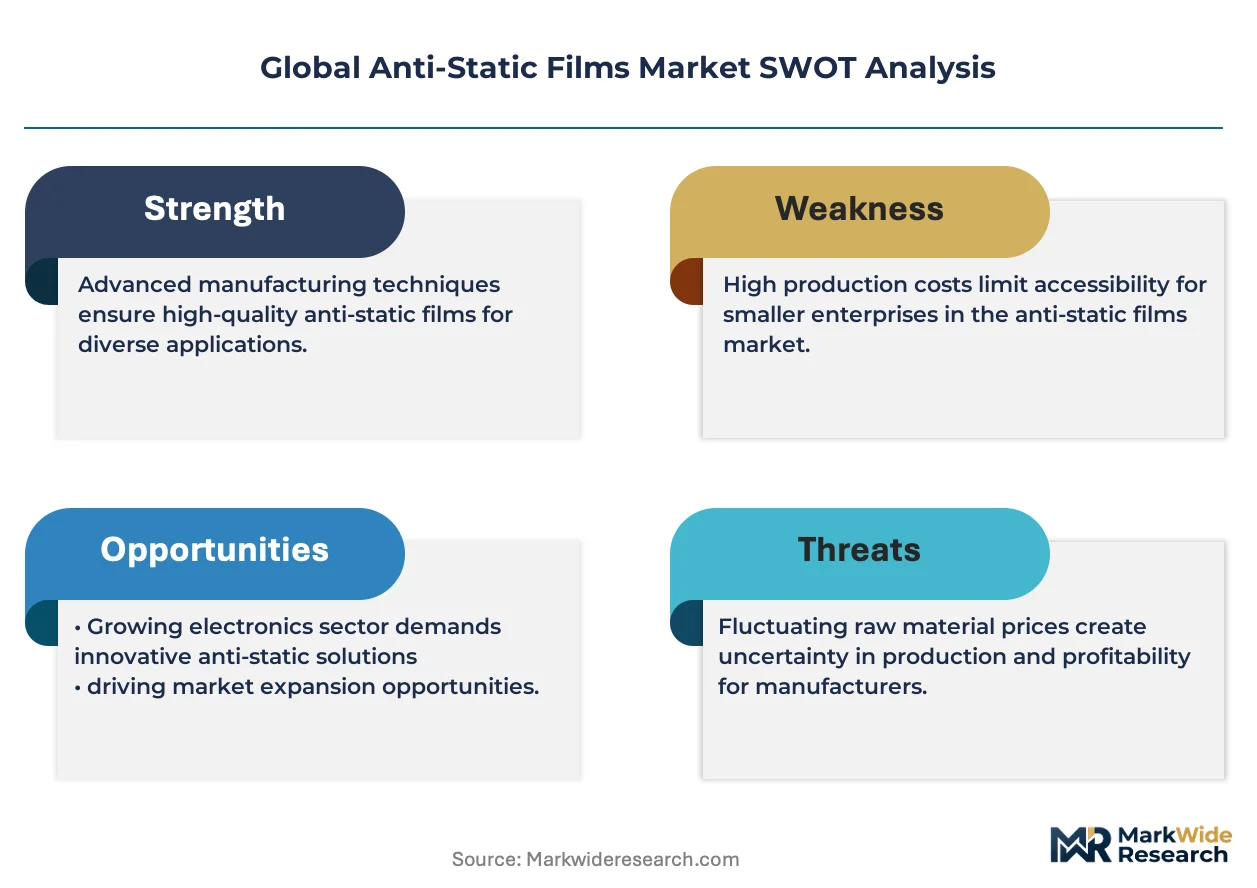
Concentration sits with integrated resin producers who control captive polymer supply and compounder networks dependent on merchant masterbatches. Three archetypes define competitive positioning: Japanese chemical conglomerates with backward integration into conductive additive synthesis, German precision film specialists with coextrusion capabilities for sub-50μm specifications, and Taiwanese volume converters serving EMS procurement channels. Dominant competitive moves include direct compounder-to-OEM relationship formation bypassing traditional distribution, and geographic expansion toward Indian electronics manufacturing corridors.
Within the integrated chemical conglomerate tier, Achilles Corporation and Toray Industries Inc. exemplify positioning anchored to captive resin supply and precision coextrusion capabilities respectively. Among diversified materials specialists, 3M occupies a position spanning adhesive technologies and film substrates. These three entities represent the technology-to-scale spectrum: additive synthesis control, precision manufacturing expertise, and broad materials portfolio diversification.
| Leading Market Players |
|---|
| Achilles Corporation |
| Toyobo Co. Ltd. |
| 3M |
| Toray Industries Inc. |
| Mitsubishi Chemical Group Corporation |
| Klöckner Pentaplast |
| Nan Ya Plastics Corp |
| Saint-Gobain Corp |
| Blueridge Films |
| Others |
Supply Flow & Price Mechanics
REACH surface resistivity mandates and EPA electrostatic discharge protocols gate both supplier qualification and price differentiation, forcing converters to absorb certification costs while semiconductor OEMs in Hsinchu and Pyeongtaek pay configured-to-order premiums for sub-50μm PET with carbon nanotube conductivity.
Pricing Analysis
The customization-premium spread separates standard polyethylene formulations from precision-configured PET structures. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and optical clarity requirements. Price differentiation hinges on carbon nanotube loading precision and dual EPA-FDA clearance status. EMS procurement teams at Foxconn and Jabil squeeze standard-tier margins through pan-Asian volume consolidation, while medical device OEMs in Germany and Japan absorb premium-tier pricing for sterile barrier qualifications.
Supply Chain Analysis
Just-in-time inventory strategies dominate semiconductor equipment channels in Taiwan and South Korea, while strategic stockpiling of carbon nanotube masterbatches persists among Japanese compounders hedging Chinese supply volatility. Raw material sourcing draws from Saudi ethylene feedstock, Chinese carbon black, and South Korean multi-walled carbon nanotube production. Single-source vulnerability concentrates in East Asian masterbatch supply. Distribution runs through consolidated EMS procurement networks displacing traditional film converter channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anti-static films are shifting toward platform-economics dynamics as consolidated EMS procurement unifies masterbatch approval databases across pan-Asian supplier networks, creating interoperability lock-in for compounders integrated into Foxconn and Jabil sourcing systems.
For Market Incumbents: Shield specification authority by deepening captive carbon nanotube synthesis capabilities and securing dual EPA-FDA certification pipelines ahead of perfluorinated additive bans. Carbon-black dependent converters face margin compression from ECHA reformulation deadlines. Priority investment targets precision coextrusion capacity in Germany and Japan where aging technician scarcity creates defendable capability moats.
For New Entrants and Emerging Players: Lead with biodegradable conductive polymer formulations targeting France and Italy medical packaging waste regulations, where incumbent PET suppliers lack polylactic acid substrate expertise. India's PLI-subsidized electronics manufacturing in Gujarat and Tamil Nadu offers virgin demand without entrenched supplier relationships. Direct compounder-to-OEM tolling relationships bypass EMS procurement consolidation.
For Investors and Strategic Acquirers: ECHA's perfluorinated surfactant restriction proposal reshapes the acquisition landscape toward quaternary ammonium salt ionomer specialists with validated REACH-compliant formulations. Five-to-ten year viability favors precision film converters with sub-50μm coextrusion capabilities and medical device packaging dual certifications. Watch carbon nanotube import dependence ratios as inflection signal for Chinese supply disruption premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Nanotube Synthesis | Captive additive production insulates margin from Chinese and South Korean compounder pricing power. |
| Dual Certification Investment | Simultaneous EPA electrostatic compliance and FDA 510(k) clearance unlocks semiconductor-medical cross-selling. |
| Biodegradable Substrate Development | Polylactic acid conductive polymer alloys address France and Italy single-use packaging waste regulations. |
| Direct OEM Tolling Relationships | Bypassing EMS procurement consolidation restores technical service margins and specification influence. |
| India Manufacturing Corridor Expansion | PLI scheme subsidies in Gujarat and Tamil Nadu create first-mover positioning without incumbent lock-in. |
Methodological Framework
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings for this analysis. Film extruder plant managers, EMS procurement leads at Foxconn and Jabil, semiconductor OEM packaging engineers, carbon nanotube compounder technical directors, and medical device sterile barrier specialists provided operational data. Secondary sources include EPA electrostatic discharge guidelines, ECHA restriction proposals, SAMR GB standards, METI pharmaceutical packaging directives, and customs trade data for polyethylene and PET resin flows. Bottom-up capacity assessments triangulate against top-down demand modeling from electronics manufacturing cluster outputs.
Sensitivity analysis around carbon nanotube loading cost trajectories and perfluorinated additive ban timelines frames the forecast uncertainty. The analytical framework segments by material chemistry, functional thickness, end-use precision requirements, and regional regulatory cluster across the projection horizon. CAGRs derive from installed capacity expansion schedules, qualification timeline assumptions, and substitution elasticity between carbon black and nanotube formulations. Semiconductor packaging densification rates and medical device miniaturization trends feed directly into thickness-segment growth allocations.
The analysis sits within stated boundaries; outcomes outside sustained East Asian electronics manufacturing concentration or accelerated biodegradable polymer adoption would require recalibration. Forecasts reflect assumptions on regulatory timeline adherence and raw material supply continuity. Revision becomes warranted when carbon nanotube import dependence or REACH enforcement intensity crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Cardboard Trays Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
Europe Paint Packaging Market
Packaging Materials
Floppy Disk Liner Market
Packaging Materials
Reel in Box Market
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Card Films Market
Packaging Materials
Die Cut Support Pads Market
Packaging Materials
Box and Carton Overwrap Films Market
Packaging Materials
Global Packaging Foams Market
Packaging Materials
Cold Chain Packaging Materials Market
Packaging Materials
Thailand Packaging Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Textile Packaging Market
Packaging Materials
Primary Packaging Market
Packaging Materials
Thermoformed Tubs Market