
 Dispensing Trays Market | 2026-2036
Dispensing Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Dispensing Trays Market Outlook
The capital-intensity divergence between automated thermoforming lines and manual assembly setups is bifurcating competitive tiers in dispensing trays. Oliver Healthcare Packaging leverages captive cleanroom film extrusion to sustain margin control across healthcare-grade product lines. Thermo Fisher Scientific anchors its position through ISO 14644-compliant manufacturing infrastructure that dominates laboratory and biopharma segments. Nelipak Healthcare Packaging competes via specialized barrier-coated PETG formulations calibrated to pharmaceutical stability protocols.
Dispensing trays are thermoformed or injection-molded containers engineered with precise cavity dimensions, typically manufactured from PETG, PVC, or PP resins, designed to organize, protect, and present unit-dose pharmaceuticals, medical devices, or food items through automated or manual handling systems. Plastic material formulations lead volume due to sterilization compatibility and cost-efficient high-speed forming, though bamboo substrates represent the fastest-growing niche as retail and food service buyers pursue fiber-based alternatives to conventional polymers. Custom trays command premium positioning by addressing patient-specific medication regimens and complex device geometries, while standard trays occupy commoditized healthcare procurement channels where price and supply security dominate vendor selection.
FDA enforces 21 CFR Part 820 quality system regulations that mandate validation of tray sealing and sterility maintenance for pharmaceutical applications, while EU MDR requires Unique Device Identification traceability that elevates demand for serialized, tamper-evident tray designs. The EPA's emerging per- and polyfluoroalkyl substances restrictions are pressuring converters to certify fluorine-free barrier coatings without compromising moisture and oxygen protection. Stakeholders must monitor evolving material compliance deadlines across multiple jurisdictions to preempt supply chain disruption and secure preferred supplier status with institutional purchasers.
Market Dynamics
Unit-dose pharmaceutical packaging is concentrating demand for precision-formed dispensing trays as healthcare systems automate medication distribution and tighten cold-chain integrity requirements. This structural pull is reshaping material specifications, manufacturing scale thresholds, and vendor qualification protocols across the supply base.
Growth Catalysts
- EU MDR traceability mandates:Serialized tray designs with tamper-evident features are capturing procurement preference as European healthcare systems upgrade compliance infrastructure.
- Pharmaceutical contract manufacturing expansion:CDMO capacity buildouts in Germany and Switzerland are pulling dedicated tray supply agreements with validated sterilization protocols.
- Automated dispensing system integration:Robotic pharmacy fulfillment centers require dimensional tolerances below 0.1mm, favoring suppliers with in-house thermoforming tool design.
Market Restraints
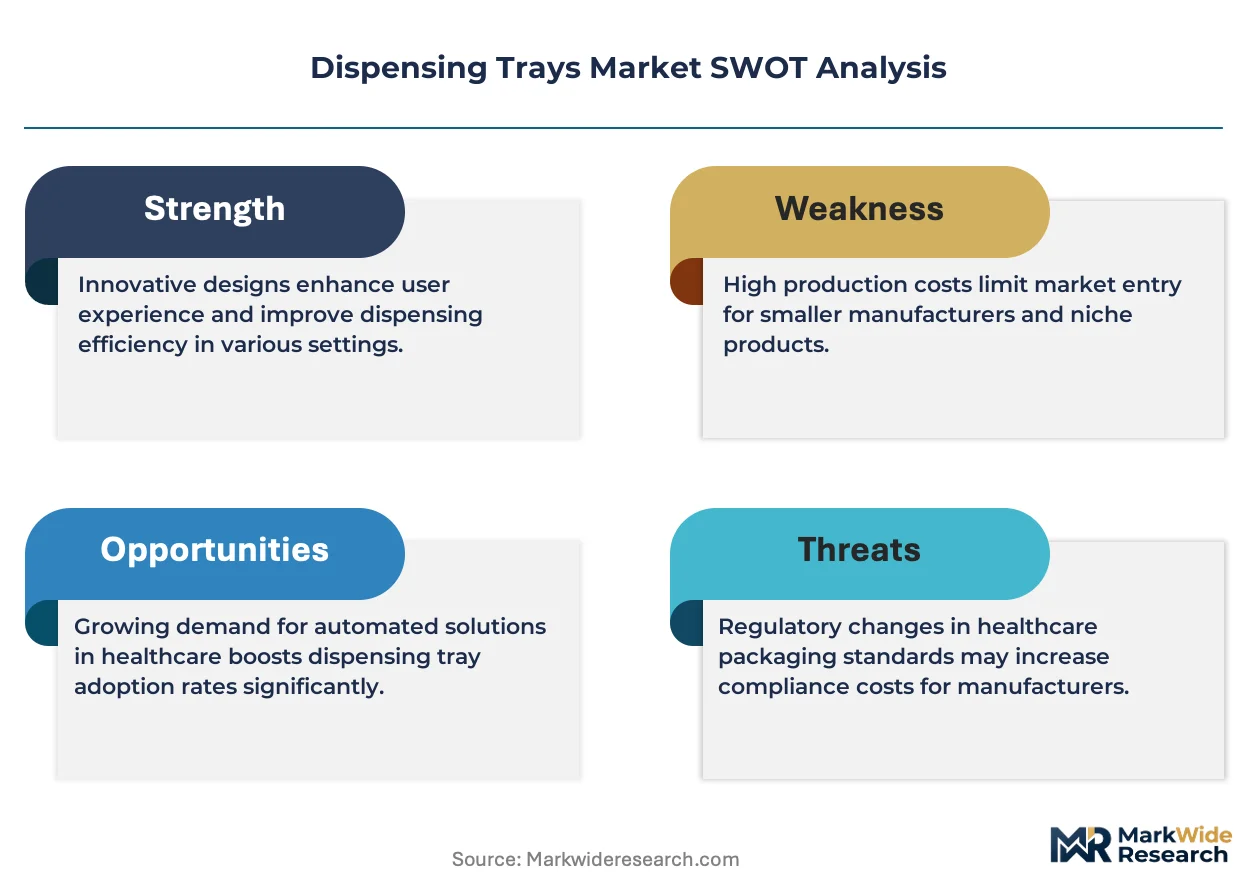
- Medical-grade resin cost volatility:PETG and PP feedstock prices fluctuate with crude oil derivatives, compressing converter margins on fixed-price hospital contracts.
- Cleanroom infrastructure concentration:ISO 14644 Class 7+ manufacturing clusters concentrate in southern Germany and northern Italy, creating geographic supply risk.
- Fluorine-free barrier coating performance gap:EPA restrictions on PFAS chemistry limit moisture protection compared to legacy formulations, forcing material requalification cycles.
Strategic Opportunities
- India pharmaceutical export corridor:CDSCO-aligned tray suppliers can capture contract manufacturing demand from Ahmedabad and Hyderabad API clusters.
- Biologics cold-chain expansion:Temperature-stable tray designs with integrated phase-change materials address mRNA vaccine distribution requirements.
- Retail pharmacy automation:Central fill pharmacy networks in the US are adopting unit-dose compliance packaging with patient-specific tray configurations.
Industry Challenges
- Tooling lead time compression:Custom cavity designs require 12-16 week aluminum mold production, delaying new product introductions.
- Multi-jurisdiction certification overlap:Concurrent FDA 510(k) and EU MDR technical documentation demands strain regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dispensing Trays Market |
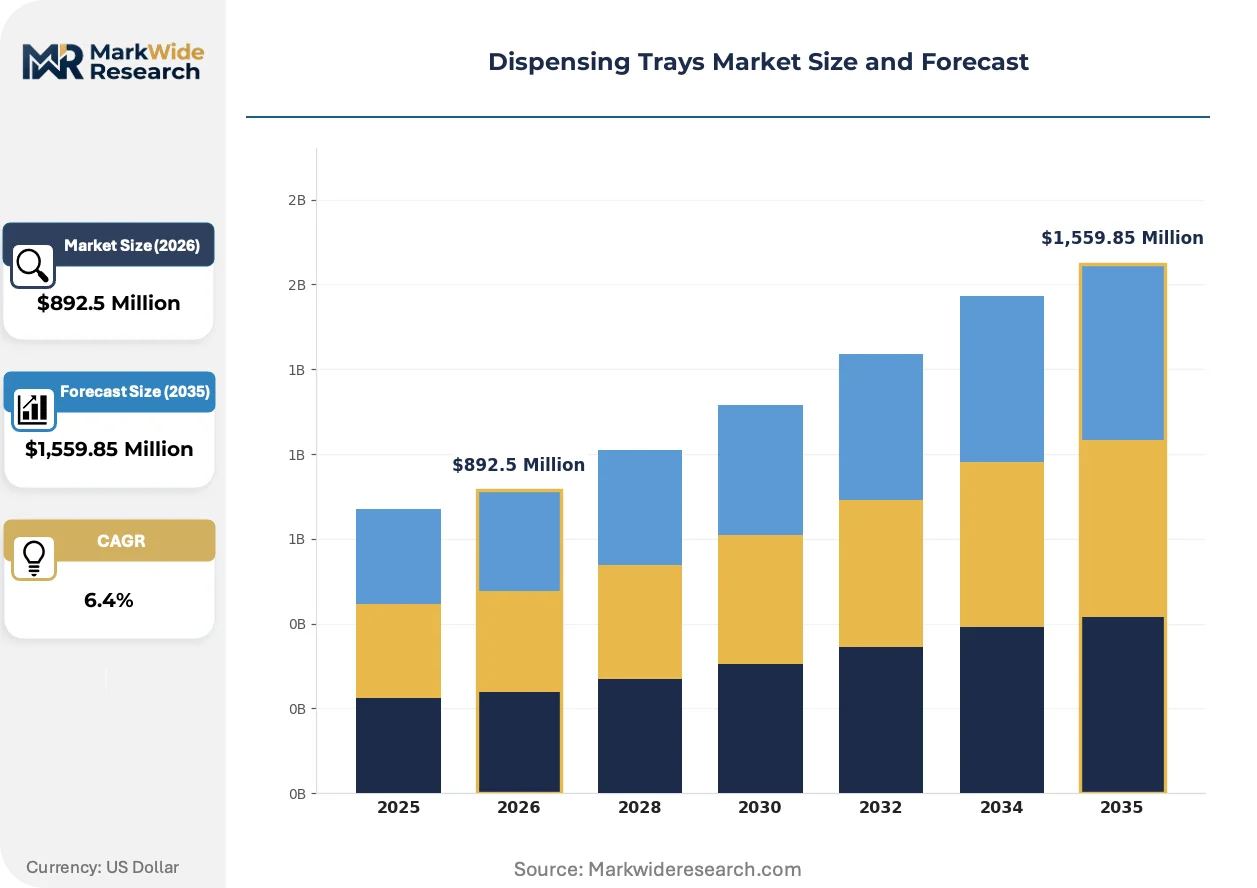
| Market Size in 2026 | $892.5 Million |
| Market Size in 2035 | $1,559.85 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Metal, Bamboo, Wood Product Type: Standard Trays, Compartment Trays, Stackable Trays, Custom Trays End User: Healthcare Facilities, Retail Outlets, Food Service, Laboratories Size: Small, Medium, Large, Extra Large |
| Companies Covered | Oliver Healthcare Packaging, Thermo Fisher Scientific, Sonoco Products Company, Tray-Pak Corporation, Placon Corporation, Rohrer Corporation, West Pharmaceutical Services, Medline Industries, Nelipak Healthcare Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dispensing Trays Market Strategic Shifts
Material science breakthroughs and regulatory tightening are converging to redefine dispensing tray performance standards. Suppliers must now engineer for simultaneous sterilization compatibility, sustainability credentials, and automated handling precision.
Barrier-coated PETG formulations with plasma-enhanced surface treatment are displacing conventional multi-layer laminates in pharmaceutical stability applications. Biopharma packaging teams at major CDMOs are specifying these substrates for moisture-sensitive oral solids. The shift is compressing demand for separate foil lidding configurations and simplifying line integration.
EPA per- and polyfluoroalkyl substances restrictions are forcing rapid reformulation of moisture barrier coatings ahead of 2025 enforcement windows. Converters are qualifying silicon oxide and aluminum oxide vapor-deposited alternatives through accelerated aging protocols. Pharmaceutical sponsors in the US market are requiring fluorine-free certifications in new supplier agreements.
Hospital procurement teams are consolidating vendor panels around dual-source validated suppliers with captive resin extrusion capabilities. Group purchasing organizations are favoring tray converters with ISO 15378 certification and documented business continuity plans. This concentration is most visible in the US acute care segment, where IDN consolidation has reduced qualified supplier lists by 40 percent over three years.
Dispensing Trays Market Segmentation
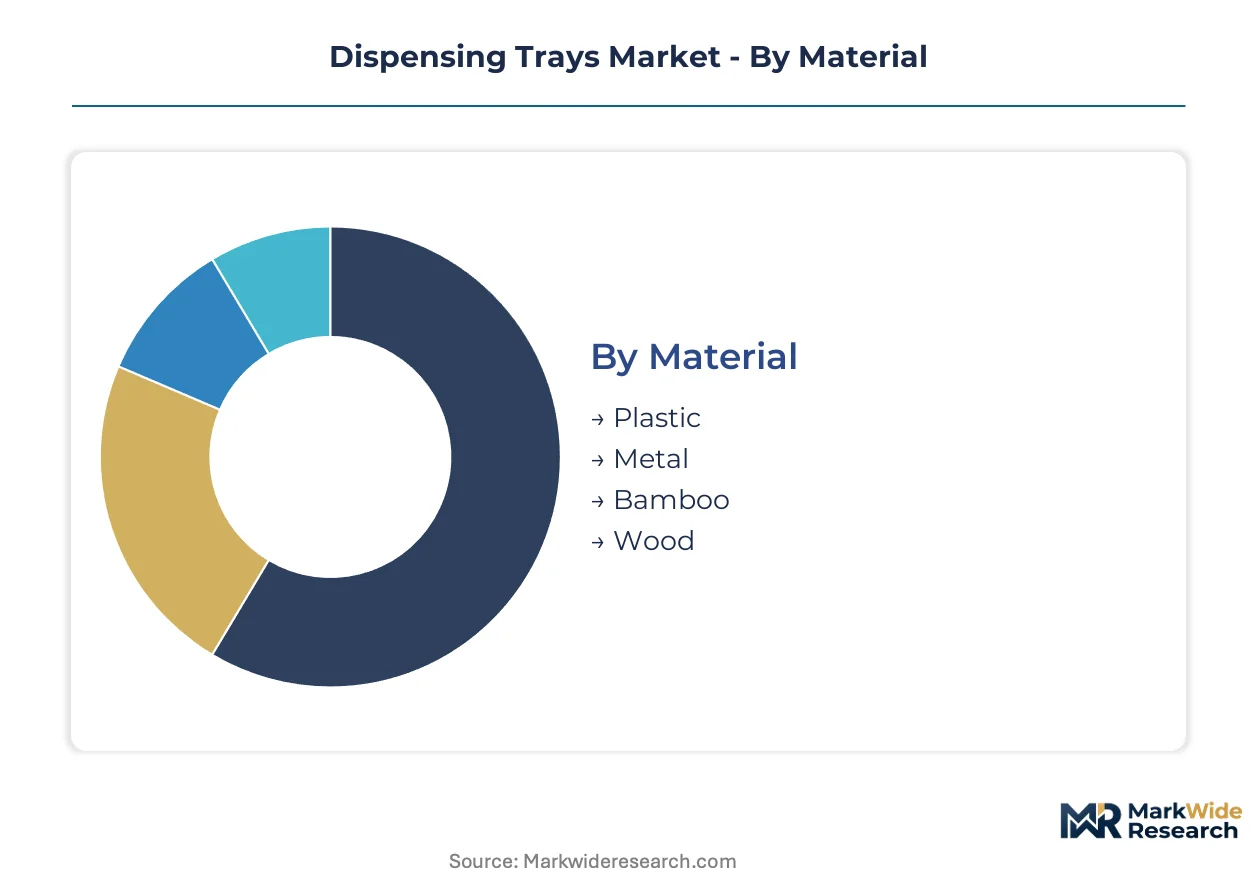
Segmentation in dispensing trays reveals how material specifications, dimensional precision, and end-use sterilization requirements create distinct competitive battlegrounds. Each category carries different margin profiles and regulatory burdens that reshape supplier positioning across pharmaceutical, food service, and laboratory channels.
Material:
Premium margin pools concentrate in medical-grade formulations where sterilization validation and barrier performance command price premiums over commodity substrates.
- Plastic:Thermoformed PETG, PVC, and PP resins dominate pharmaceutical applications through gamma and EtO sterilization compatibility. Hospital procurement in Germany's Stuttgart-Freiburg corridor and Swiss CDMO clusters pull validated supply agreements with ISO 15378-certified converters.
- Metal:Stainless steel trays serve surgical instrument sterilization and reusable healthcare workflows. FDA 21 CFR Part 820 quality system requirements and EU MDR traceability mandates elevate demand for laser-etched serialization in US and European acute care settings.
- Bamboo:Fiber-based substrates target retail and food service buyers pursuing polymer alternatives ahead of EPA per- and polyfluoroalkyl substances restrictions.
- Wood:Sealed hardwood constructions occupy artisan food presentation and specialty pharmaceutical packaging niches with limited sterilization throughput.
The dominant share belongs to Plastic, while Bamboo is closing the gap fastest.
Product Type:
Application complexity and tooling investment separate commoditized formats from engineered solutions with multi-year contract security.
- Standard Trays:Fixed-cavity designs for high-volume oral solid dose packaging occupy price-sensitive procurement channels. Group purchasing organizations in the US acute care segment favor these formats where supply security and dual-source validation outweigh customization needs.
- Custom Trays:Patient-specific medication regimens and complex device geometries require aluminum mold investments with 12-16 week lead times. Robotic pharmacy fulfillment centers demand dimensional tolerances below 0.1mm, concentrating supply among converters with in-house thermoforming tool design.
- Compartment Trays:Multi-cavity configurations organize combination therapies and dose-escalation protocols in oncology and infectious disease treatment.
- Stackable Trays:Nesting geometries optimize cold-chain cube utilization for biologics distribution and central fill pharmacy networks.
Standard Trays capture volume leadership, yet Custom Trays deliver the steepest expansion trajectory as automation penetrates pharmaceutical fulfillment.
End User:
Regulatory intensity and handling precision requirements stratify margin capture across customer categories.
- Healthcare Facilities:Hospital and clinic networks drive unit-dose medication distribution with FDA and EU MDR compliance infrastructure. IDN consolidation in the US has reduced qualified supplier lists by 40 percent, favoring tray converters with captive resin extrusion and documented business continuity plans.
- Laboratories:ISO 14644-compliant manufacturing infrastructure dominates biopharma and diagnostic segments where contamination control protocols exceed healthcare-grade thresholds.
- Retail Outlets:Pharmacy chains and consumer health channels prioritize shelf-ready presentation and patient adherence packaging over sterilization validation.
- Food Service:Commercial kitchens and catering operations emphasize durability and temperature resistance with minimal regulatory documentation.
Healthcare Facilities command the largest revenue share, though Laboratories are expanding most quickly on biologics cold-chain investment.
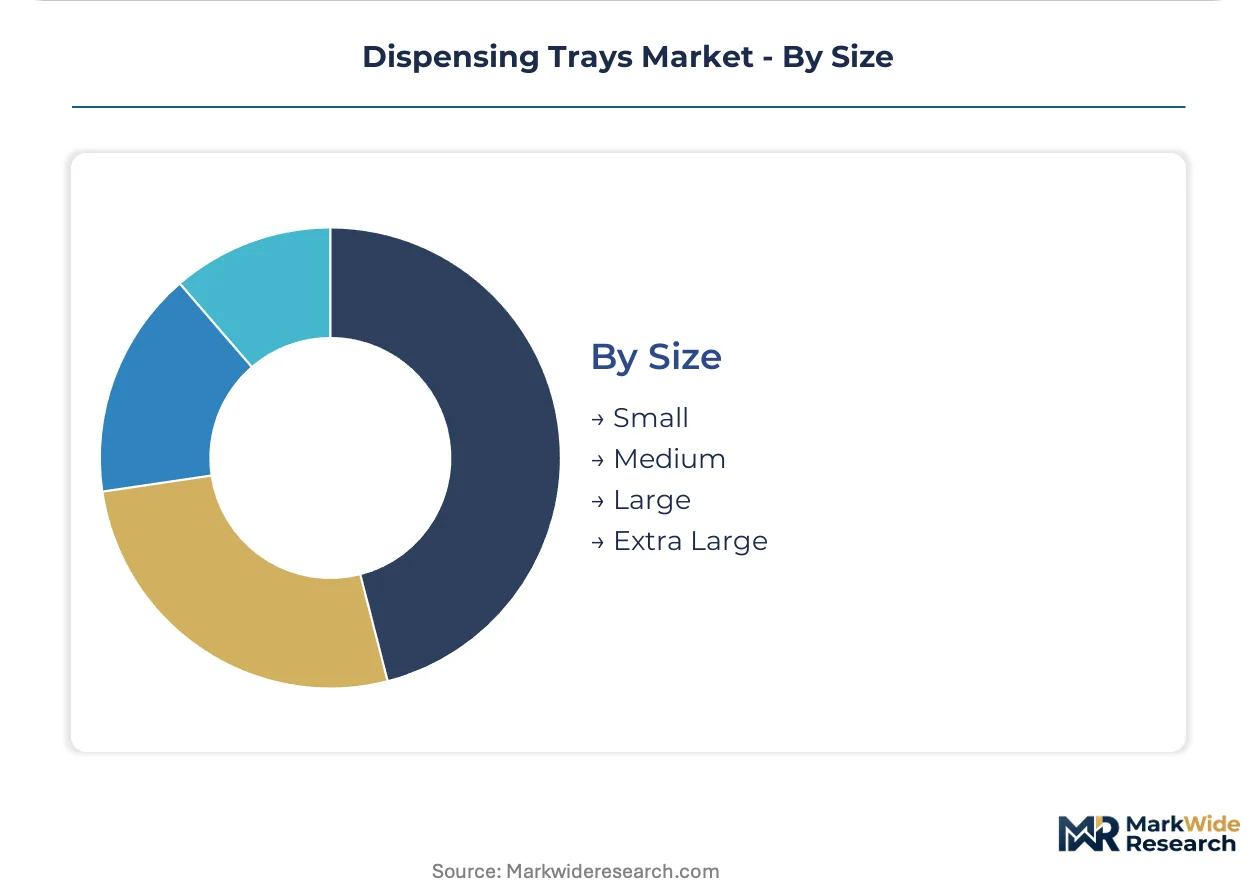
Size:
Dimensional scale determines thermoforming equipment utilization and per-unit economics across production runs.
- Small:Single-dose cavities for high-potency oral solids and pre-filled syringe presentation maximize cavity count per tool.
- Medium:Multi-day compliance packaging for chronic disease management balances patient convenience with cold-chain efficiency.
- Large:Surgical kit and medical device organizers require deeper draw ratios and reinforced sidewall structures.
- Extra Large:Bulk pharmaceutical distribution and automated dispensing system cassettes occupy specialized tooling with lower cavity density.
Medium sizes lead procurement volume, while Small formats gain share fastest on unit-dose automation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement teams in Germany absorb price premiums for validated sterilization protocols, while retail pharmacy buyers in India prioritize unit-cost minimization over barrier performance specifications.
United States
Central fill pharmacy networks and robotic dispensing system deployments drive precision-tray demand. FDA 21 CFR Part 820 quality system regulations enforce validation documentation for sterile barrier maintenance. The Greater Boston corridor concentrates biopharma packaging engineering talent serving mRNA vaccine distribution workflows.
Germany
CDMO capacity expansion around Stuttgart and Freiburg pulls dedicated supply agreements with ISO 15378-certified converters. EU MDR traceability mandates elevate demand for serialized, tamper-evident tray designs. The Baden-Württemberg medical device manufacturing cluster hosts captive cleanroom film extrusion operations.
Switzerland
Swissmedic pharmaceutical stability protocols calibrate barrier-coated PETG specifications for moisture-sensitive oral solids. Contract manufacturing buildouts in Basel and Zug require documented business continuity plans from tray suppliers. The Lake Geneva region concentrates precision thermoforming tool design capabilities.
India
Pharmaceutical export corridors from Ahmedabad and Hyderabad API clusters expand CDSCO-aligned tray procurement. The country's national pharmaceutical regulator tightens material certification requirements for sterile dosage form packaging. Maharashtra's Thane-Belapur belt hosts emerging thermoforming capacity serving domestic and export markets.
China
Domestic biologics cold-chain infrastructure investment accelerates temperature-stable tray adoption. NMPA pharmaceutical packaging material registration rules extend approval timelines for imported substrates. The Yangtze River Delta concentrates automated thermoforming line deployments serving multinational CDMO operations.
Dispensing Trays Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the dispensing trays supply base. The market structure concentrates around ISO 14644-certified converters with captive resin extrusion and validated sterilization protocols. Three strategic archetypes dominate: integrated healthcare packaging specialists, diversified laboratory supply conglomerates, and regional thermoforming contract manufacturers. Competitive moves center on backward integration into medical-grade film production and geographic expansion into pharmaceutical manufacturing corridors.
Among integrated healthcare packaging specialists, Oliver Healthcare Packaging and Nelipak Healthcare Packaging exemplify the premium-tier archetype through barrier formulation expertise and cleanroom manufacturing infrastructure. Thermo Fisher Scientific occupies a position representing diversified laboratory supply conglomerates with ISO 14644-compliant production networks. These three anchors illustrate how sterilization validation capabilities and regulatory documentation depth separate qualified suppliers from commodity converters in institutional procurement channels.
| Leading Market Players |
|---|
| Oliver Healthcare Packaging |
| Thermo Fisher Scientific |
| Sonoco Products Company |
| Tray-Pak Corporation |
| Placon Corporation |
| Rohrer Corporation |
| West Pharmaceutical Services |
| Medline Industries |
| Nelipak Healthcare Packaging |
| Others |
Value Chain & Pricing Dynamics
Twelve-to-sixteen-week aluminum mold production cycles concentrate pricing power among converters with in-house thermoforming tool design capabilities, while hospital procurement teams leverage dual-source validation requirements to compress margins on standard tray formats. The supply chain's geographic clustering around southern Germany and northern Italy creates asymmetric bargaining positions that favor ISO 14644-certified manufacturers with captive resin extrusion.
Pricing Analysis
After-sales revenue from sterilization validation documentation and multi-year supply agreements drives lifetime value for premium-tier suppliers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15378-certified medical-grade formulations from commodity food-service substrates. Cost compression in standard trays is intensifying because group purchasing organizations consolidate vendor panels around dual-source validated suppliers. Retail pharmacy buyers in India exhibit highest price sensitivity, while Swiss CDMOs absorb premiums for barrier-coated PETG with documented stability protocols.
Supply Chain Analysis
Strategic stockpile preferences dominate among pharmaceutical sponsors facing FDA 21 CFR Part 820 validation requirements, while just-in-time inventory management characterizes food-service procurement. Manufacturing gravity centers on Germany, Switzerland, and the United States for healthcare-grade production, with emerging capacity in India and China serving export corridors. Supply chains draw from medical-grade PETG, PP resins, and fluorine-free barrier coating chemistries. Single-source vulnerability concentrates in ISO 14644 Class 7+ cleanroom infrastructure clusters. Distribution runs through validated converter networks to institutional procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dispensing trays market is accelerating on EU MDR traceability mandates and robotic pharmacy automation, creating structural openings for suppliers with serialized, tamper-evident design capabilities.
For Market Incumbents: Fortify market position through backward integration into medical-grade film extrusion and expansion of ISO 14644-compliant manufacturing footprints in Germany's Stuttgart-Freiburg corridor. Threats from fluorine-free barrier coating performance gaps and EPA PFAS restrictions demand accelerated R&D investment in silicon oxide vapor-deposited alternatives. Certification investment in concurrent FDA 510(k) and EU MDR technical documentation capabilities represents the critical defensive lever.
For New Entrants and Emerging Players: Differentiate on fluorine-free barrier formulation expertise and temperature-stable tray designs with integrated phase-change materials for biologics cold-chain applications. White-space targets concentrate in India's Ahmedabad-Hyderabad pharmaceutical export corridor and US central fill pharmacy automation networks. A go-to-market angle anchored to CDSCO-aligned regulatory documentation offers the most penetrable entry path.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified laboratory supply conglomerates seeking to divest non-core healthcare packaging units. Long-term viability over a multi-year horizon rests on biologics distribution infrastructure expansion and mRNA vaccine cold-chain requirements. The signal to watch is hospital procurement consolidation reducing qualified supplier lists and elevating preference for vendors with documented business continuity plans.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15378 Certification Investment | Validates pharmaceutical-grade manufacturing protocols for EU MDR compliance. |
| Fluorine-Free Barrier Coating Qualification | Addresses EPA restrictions while maintaining moisture protection for oral solids. |
| In-House Thermoforming Tool Design | Reduces 12-16 week mold production cycles for robotic pharmacy precision requirements. |
| India Manufacturing Footprint Expansion | Captures CDSCO-aligned demand from Ahmedabad and Hyderabad API clusters. |
| Serialized Tamper-Evident Tray Development | Meets EU MDR traceability mandates for European healthcare system upgrades. |
Study Parameters
Initial hypotheses were tested against primary input from hospital procurement managers, pharmaceutical packaging engineers, CDMO supply chain directors, and regulatory affairs specialists, and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, ISO certification registries, and pharmaceutical trade customs data. Bottom-up demand modeling from end-user segments triangulated with top-down supply-side capacity assessments across validated converter networks.
Variance decomposition across material formulations, product types, end-user categories, and regional regulatory clusters shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectories weighted by sterilization validation intensity and automation adoption curves. Forecast inputs incorporated pharmaceutical contract manufacturing expansion timelines and biologics cold-chain infrastructure investment patterns.
The analysis sits within stated boundaries; outcomes outside sustained EU MDR enforcement and EPA PFAS restriction timelines would require recalibration. Forecasts reflect assumptions regarding resin price stability and cleanroom manufacturing capacity expansion. Revision becomes warranted when fluorine-free barrier coating performance gaps or multi-jurisdiction certification overlap strain regulatory affairs capacity beyond current thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Tamper Evident Pots and Tubs Market
Packaging Containers
Self - Locking Trays Market
Packaging Containers
Logistics Packaging Market
Packaging Containers
Middle East and Africa Aerosol Cans Market
Packaging Containers
Telescope Box Market
Packaging Containers
Insulated Storage Vessel Market
Packaging Containers
Insulated Food Containers Market
Packaging Containers
Gable Boxes Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
Hinged Food Containers Market
Packaging Containers
Cooler Box Market
Packaging Containers
Latin America Aerosol Cans Market
Packaging Containers
Thermoform Cups Market
Packaging Containers
Foldable Mailer Box Market
Packaging Containers
North America Food Cans Market
Packaging Containers
Global Acrylic Airless Bottle Market