
 Refrigerator Door Seal Gaskets Market | 2026-2036
Refrigerator Door Seal Gaskets Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerator Door Seal Gaskets Market Insights
China's expanding polymer compounding base is reconfiguring regional supply dynamics for refrigerator door seal gaskets. Industrie Ilpea leverages European formulation expertise to sustain premium positioning in EPDM-intensive segments. REHAU anchors its competitiveness through backward integration into extrusion tooling and captive PVC resin processing.
Refrigerator door seal gaskets are elastomeric closure profiles, typically extruded from EPDM, PVC, or silicone compounds with embedded magnetic strips, designed to maintain hermetic sealing across temperature cycles from -40°C to +65°C while resisting plasticizer migration and compression set. Their primary purpose is to minimize refrigerant loss and thermal bridging in compression-cooled enclosures. EPDM formulations dominate replacement demand owing to superior ozone and low-temperature resilience, while silicone grades command margin pools in medical and laboratory cold-chain applications where FDA compliance and steam-cleanability are mandatory. The commercial end-user segment generates disproportionate aftermarket volume, as restaurant chains and supermarket operators face strict HACCP audit cycles that mandate scheduled gasket replacement.
The US EPA SNAP program and OSHA refrigeration safety standards shape product specifications by penalizing systems with elevated leakage rates, while the EU F-Gas Regulation and ECHA REACH restrictions on phthalate plasticizers are forcing reformulation of legacy PVC compounds toward non-migratory alternatives. China's GB standards for household appliance energy efficiency and the NMPA's cold-chain pharmaceutical storage rules collectively tighten performance benchmarks across manufacturing and end-use jurisdictions. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether to standardize on EPDM or maintain multi-material portfolios.
Market Dynamics
EPA SNAP refrigerant phase-down rules and EU F-Gas leakage limits are forcing gasket specification upgrades across commercial cold-chain infrastructure, compressing replacement cycles and elevating performance thresholds for elastomeric seal compounds.
Growth Catalysts
- Commercial HACCP mandates:Restaurant chains and supermarket operators face mandatory gasket replacement schedules under food safety audit protocols, sustaining aftermarket volume independent of new equipment sales.
- REACH phthalate restrictions:ECHA's tightening limits on migratory plasticizers in legacy PVC compounds are accelerating reformulation toward non-migratory alternatives and EPDM substitution.
- Southeast Asian manufacturing localization:Appliance OEMs in Vietnam and Thailand are consolidating component sourcing within regional polymer compounding clusters, shortening supply lead times for seal gasket procurement.
Market Restraints
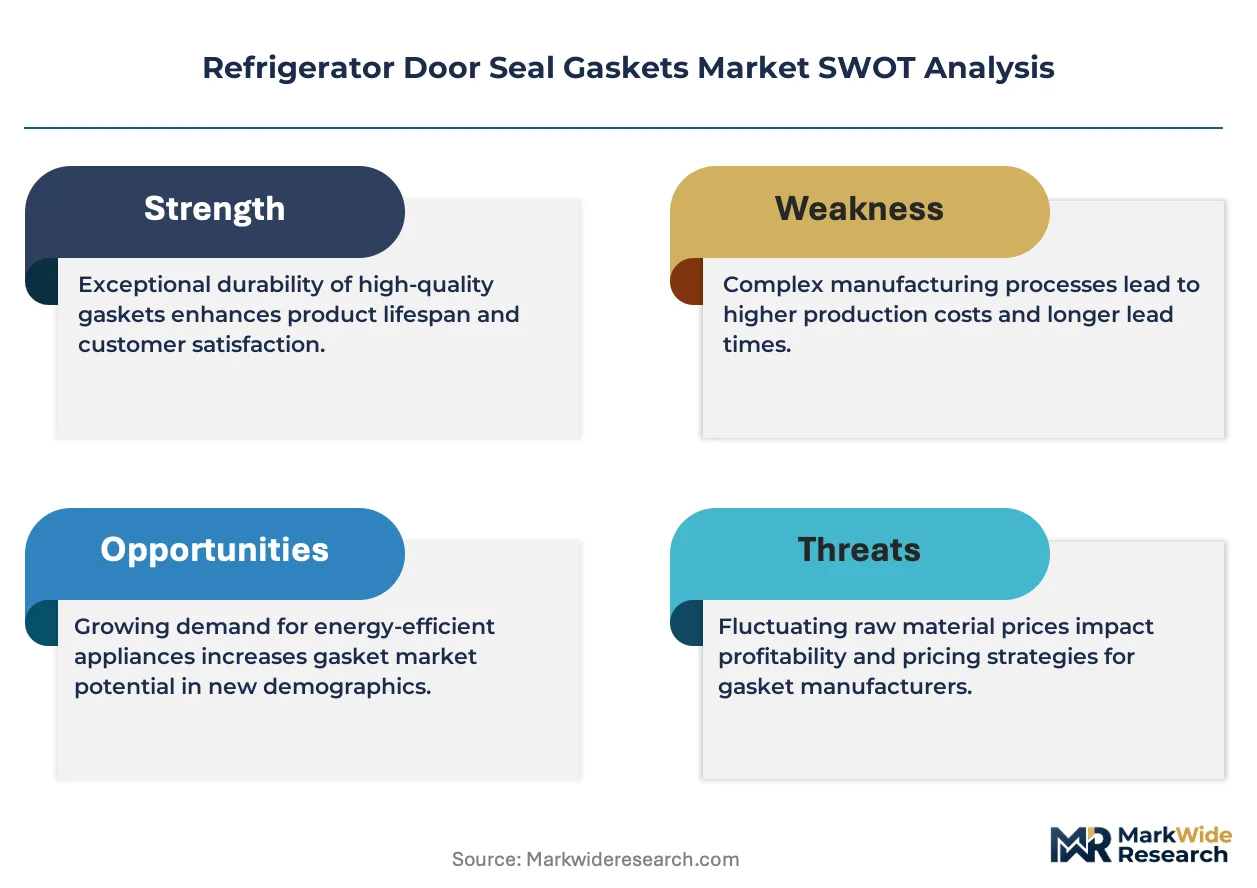
- EPDM feedstock volatility:Ethylene-propylene rubber pricing tracks naphtha and ethylene cracker margins, exposing compounders to petrochemical input cost swings that compress formulation margins.
- Magnetic strip supply concentration:Ferrite magnetic powder and extruded magnetic strip production clusters heavily in Chinese coastal provinces, creating single-source vulnerability for gasket assemblers elsewhere.
- Silicone grade cost premium:Medical and laboratory cold-chain specifications requiring FDA-compliant silicone formulations face 3-4x material cost multiples versus standard EPDM, limiting addressable market expansion.
Strategic Opportunities
- Indian cold-chain buildout:FSSAI enforcement of pharmaceutical storage temperature integrity and PLI scheme incentives for domestic appliance manufacturing are opening gasket demand in an underpenetrated replacement market.
- Predictive maintenance integration:IoT-enabled refrigeration monitoring systems that track seal degradation via thermal imaging or pressure differential sensors create embedded gasket replacement alert services.
- EU Green Deal refurbishment incentives:Member state programs subsidizing commercial refrigeration equipment retrofits are compressing payback periods for high-performance gasket upgrades that reduce energy consumption.
Industry Challenges
- Multi-jurisdiction certification complexity:Gasket compounders must maintain parallel testing protocols for FDA food contact, EU 1935/2004 migration limits, and China GB standards, extending product qualification timelines.
- Tooling amortization pressure:Custom extrusion dies for OEM-specific refrigerator profiles require capital deployment against uncertain model lifecycle volumes, stranding tooling investments when platforms discontinue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerator Door Seal Gaskets Market |
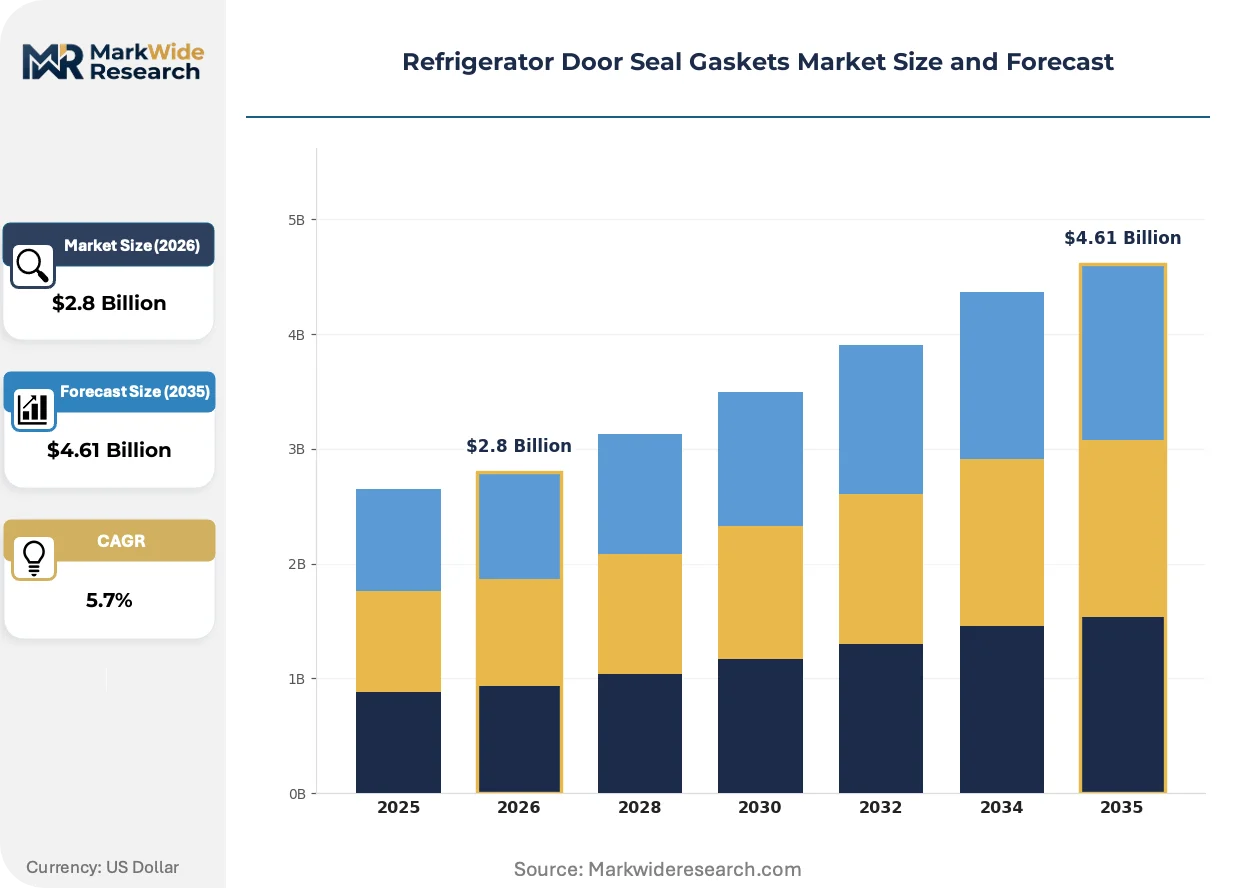
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPDM, PVC, Silicone, Polyurethane End User: Household, Commercial, Industrial, Retail Thickness: Thin, Medium, Thick, Extra Thick Installation Type: Permanent, Removable, Adhesive, Snap-in |
| Companies Covered | Industrie Ilpea, REHAU, Qingdao Qinke Engineering Plastics, Anhui Higasket Plastics, DSU, Anhe Enterprise, Qingdao Zhenxiong Mechanical Equipment, The Seal Company, Sure Seal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerator Door Seal Gaskets Market Trends and Innovations
Digital sensing technologies and predictive analytics are penetrating refrigeration maintenance workflows, while regulatory chemistry restrictions and procurement centralization are restructuring how seal performance is specified and purchased.
Magnetic field mapping during gasket extrusion is digitizing quality assurance protocols for embedded magnetic strip alignment. Commercial cold-chain operators in North American supermarket chains are adopting this inline inspection technology fastest. The capability is compressing defect rates and enabling lot-level traceability that satisfies escalating retailer audit requirements.
The EU F-Gas Regulation's 2024 tightening of allowable leakage rates for commercial refrigeration systems is mandating gasket replacement at shortened intervals. Equipment operators face penalty structures tied to refrigerant loss measurements, elevating seal specification priority in total cost of ownership calculations. Medical cold-chain applications in Germany and France are migrating fastest to silicone grades that maintain integrity across steam-sterilization cycles.
Centralized procurement by multi-site foodservice operators is consolidating gasket supplier relationships and compressing vendor counts per buying organization. National restaurant chains are unbundling gasket replacement from OEM service contracts, directing volume toward specialized seal distributors with same-day fulfillment capabilities. This pattern concentrates most visibly in US and UK markets where operator scale permits dedicated MRO procurement functions.
Refrigerator Door Seal Gaskets Market Segmentation
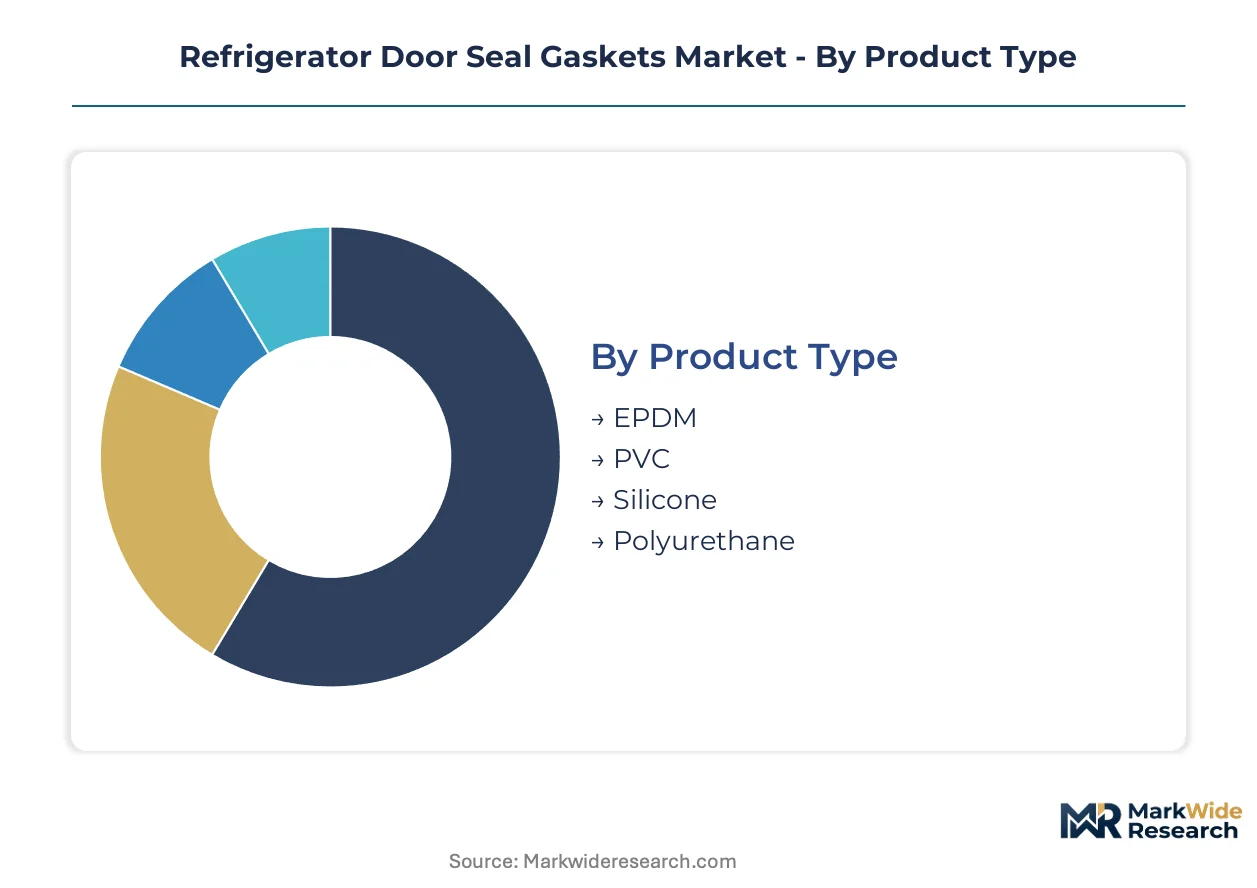
Segmentation in refrigerator door seal gaskets reveals divergent replacement economics across material grades and end-use environments. Cycle times compress dramatically in commercial settings versus residential applications, reshaping how suppliers configure inventory and service capabilities.
Product Type:
EPDM formulations turn over fastest in commercial replacement programs, while silicone grades exhibit extended service intervals that stretch procurement cycles.
- EPDM:Ethylene-propylene-diene monomer compounds dominate commercial cold-chain specifications for their ozone resistance and flexibility across -40°C to +65°C operating windows. Restaurant chains and supermarket operators in the US and EU specify EPDM for scheduled HACCP-mandated replacement cycles. EPDM anchors the volume base while silicone gains share at the steepest rate.
- PVC:Legacy polyvinyl chloride formulations persist in household appliance OEM production, though ECHA REACH phthalate restrictions are accelerating reformulation toward non-migratory plasticizers or material substitution. Southeast Asian manufacturing clusters still favor PVC for cost-sensitive domestic refrigerator programs.
- Silicone:FDA-compliant grades command premium positioning in medical and laboratory cold-chain applications where steam-sterilization cycles and biocompatibility are mandatory.
- Polyurethane:Niche deployments in specialized industrial enclosures requiring abrasion resistance and custom compression profiles.
EPDM compounds generate the highest replacement frequency while silicone posts the steepest expansion trajectory among premium specifications.
End User:
Commercial operators bear the most intensive gasket maintenance burdens, whereas household replacement follows equipment failure rather than preventive schedules.
- Household:Residential replacement demand concentrates in aftermarket channels, triggered by visible seal degradation or refrigerant performance decline rather than calendar-based protocols. US and European consumers typically defer gasket replacement until appliance malfunction.
- Commercial:Foodservice chains and pharmaceutical logistics operators face mandatory audit-driven replacement schedules. HACCP protocols in the US and EU F-Gas leakage penalties compress replacement intervals to 12-18 months in high-duty applications.
- Industrial:Cold storage warehouses and processing facilities specify heavy-duty compounds for extreme cycle counts, with procurement centralized through facility management contractors.
- Retail:Supermarket refrigeration systems combine OEM specification with aftermarket service contracts, unbundling gasket replacement from original equipment vendor relationships.
Commercial end users drive the highest aftermarket velocity while retail channels are consolidating supplier relationships fastest.
Thickness:
Profile dimension selection correlates directly with enclosure size and thermal load, creating distinct procurement patterns across equipment categories.
- Thin:Undercounter and medical refrigerator applications where space constraints limit profile geometry. German and French laboratory equipment OEMs specify thin profiles for compact cold-chain units.
- Medium:Standard household refrigerator platforms across Asian manufacturing hubs. Vietnamese and Thai appliance OEMs source medium-thickness EPDM profiles for regional production.
- Thick:Walk-in commercial coolers and industrial cold storage doors requiring enhanced thermal bridging resistance. US foodservice distribution centers specify thick profiles for high-traffic entries.
- Extra Thick:Specialized pharmaceutical storage and ultra-low temperature freezers where seal compression must maintain integrity across extreme differential pressures.
Medium thickness profiles dominate unit volume while extra thick specifications command the highest per-meter pricing premiums.
Installation Type:
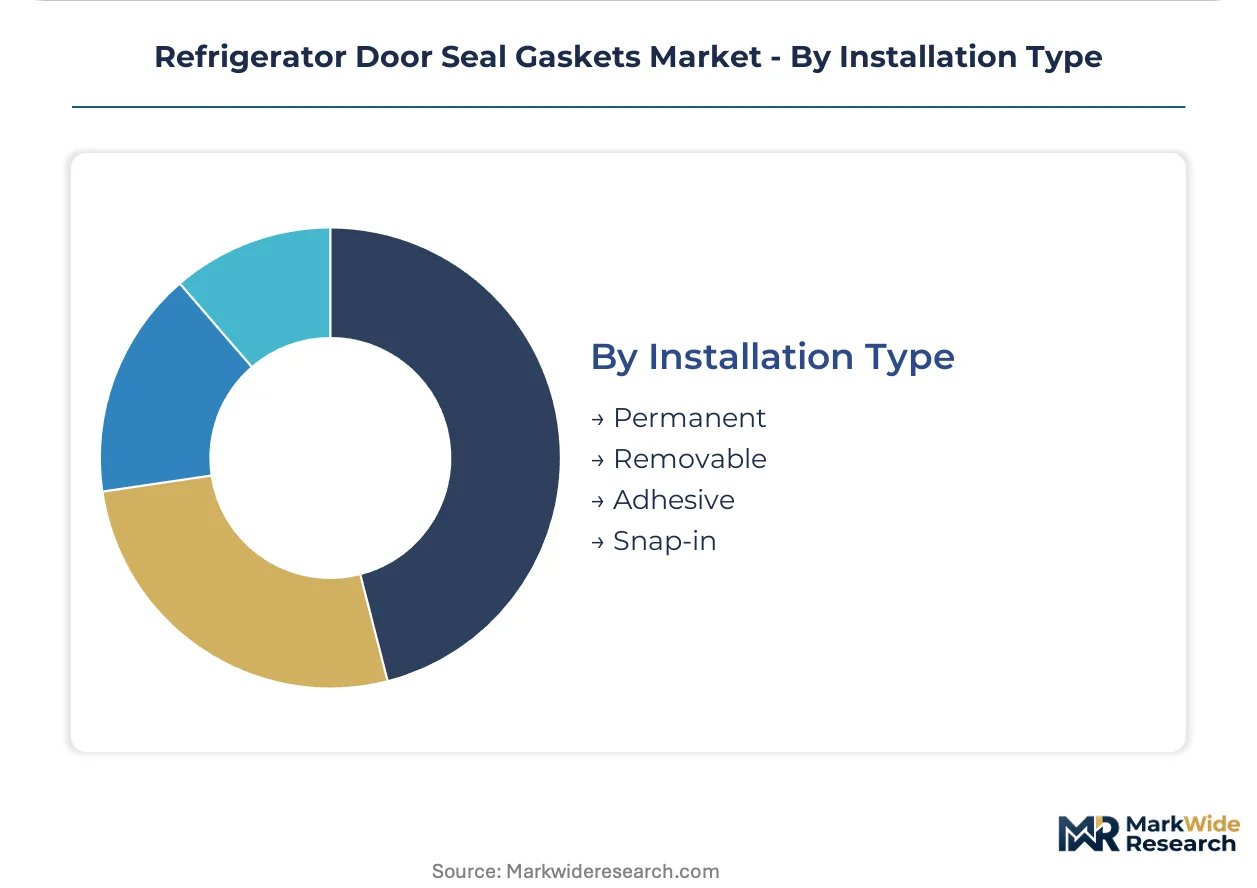
Mounting mechanism selection shapes field service economics, with snap-in designs enabling rapid replacement versus permanent installations requiring equipment downtime.
- Permanent:OEM-applied profiles bonded during refrigerator assembly, common in economy household appliances where field replacement is uneconomical.
- Removable:Compression-fit designs allowing tool-free gasket exchange, preferred by US commercial foodservice operators for minimized equipment downtime.
- Adhesive:Pressure-sensitive backing for retrofit applications where original channel geometry is degraded. UK refrigeration service contractors favor adhesive systems for aging equipment fleets.
- Snap-in:Mechanical retention profiles that lock into extruded metal or plastic retainers, enabling sub-15-minute replacement cycles in supermarket display cases.
Snap-in mechanisms are gaining fastest in commercial retrofit programs while permanent installations retain dominance in OEM original equipment supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics corridors anchor European pharmaceutical distribution, while Vietnam's Cái Mép-Thị Vải deepwater port complex underwrites Southeast Asian appliance manufacturing export capacity.
United States
Commercial foodservice chains and supermarket operators drive replacement demand through HACCP-mandated schedules. The EPA SNAP refrigerant phase-down rules compress gasket service intervals for operators facing leakage penalty structures. Dallas-Fort Worth distribution centers concentrate national cold-chain logistics, supporting rapid-turn gasket procurement for multi-site restaurant operators.
Germany
Medical laboratory cold-chain specifications and commercial refrigeration retrofit programs sustain premium silicone demand. The EU F-Gas Regulation's tightened leakage thresholds elevate seal performance requirements in commercial installations. Bavarian industrial clusters around Munich and Nuremberg host specialized gasket compounders serving pharmaceutical OEMs.
China
Appliance OEM localization and polymer compounding expansion reshape component sourcing patterns. NMPA cold-chain pharmaceutical storage rules tighten performance benchmarks for domestic manufacturers. Yangtze River Delta manufacturing bases around Shanghai and Suzhou consolidate magnetic strip extrusion and EPDM compounding capabilities.
Vietnam
Regional appliance production localization accelerates seal gasket procurement within ASEAN supply networks. Domestic energy efficiency standards for household refrigeration equipment elevate material specifications. Ho Chi Minh City industrial zones attract compounding investments serving Thai and Indonesian OEM assembly operations.
India
FSSAI pharmaceutical storage enforcement and PLI scheme appliance manufacturing incentives open underpenetrated replacement markets. Maharashtra's Pune-Aurangabad industrial corridor hosts emerging gasket fabrication capacity serving domestic cold-chain buildout. Mumbai pharmaceutical logistics operators face escalating audit pressure on refrigeration seal integrity.
Refrigerator Door Seal Gaskets Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying seal profiles to equipment OEMs and aftermarket channels. The supplier base organizes around formulation expertise, extrusion tooling ownership, and magnetic strip integration capabilities. Three archetypes predominate: European compounders with polymer science heritage, Asian fabricators leveraging feedstock proximity, and specialized seal distributors with same-day fulfillment networks. Competitive positioning hinges on backward integration into captive resin processing and multi-jurisdiction certification maintenance.
Among European formulation specialists, Industrie Ilpea and REHAU occupy positions defined by compounding expertise and tooling control. Industrie Ilpea represents the polymer science-driven archetype, while REHAU anchors the vertically integrated model with captive extrusion capabilities. Qingdao Qinke Engineering Plastics exemplifies Chinese fabricators serving regional OEM localization trends.
| Leading Market Players |
|---|
| Industrie Ilpea |
| REHAU |
| Qingdao Qinke Engineering Plastics |
| Anhui Higasket Plastics |
| DSU |
| Anhe Enterprise |
| Qingdao Zhenxiong Mechanical Equipment |
| The Seal Company |
| Sure Seal |
| Others |
Pricing and Supply Chain Analysis
Chinese coastal provinces concentrate ferrite magnetic powder and extruded magnetic strip production, anchoring margin capture at the compounding tier while gasket assemblers elsewhere face input cost pass-through limitations. EPDM feedstock pricing tracks naphtha and ethylene cracker margins, exposing formulators to petrochemical volatility that compresses formulation economics when cracker runs tighten.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across commercial cold-chain specifications, with leakage penalty structures elevating seal performance priority in total cost of ownership calculations. Three-tier pricing structure across premium silicone, standard EPDM, and economy PVC levels separates FDA-compliant medical grades from HACCP-mandated commercial replacements and cost-sensitive household OEM supply. Cost compression in standard EPDM tiers is intensifying because Southeast Asian manufacturing localization shortens supply lead times and compresses distributor markups. Commercial foodservice operators exhibit lowest price sensitivity due to audit-mandated replacement schedules, while residential aftermarket channels remain most price-responsive.
Supply Chain Analysis
Contract manufacturing for magnetic strip extrusion concentrates in Yangtze River Delta facilities around Shanghai and Suzhou, with secondary compounding capacity clustering in Ho Chi Minh City industrial zones and Bavarian corridors near Munich. Raw material dependencies center on ferrite magnetic powder from Chinese coastal provinces, EPDM rubber from South Korean and Japanese petrochemical complexes, and non-migratory plasticizer alternatives for REACH-compliant PVC reformulation. Single-source vulnerability for magnetic strip supply creates structural risk for gasket assemblers outside China. Distribution runs through specialized seal distributors with same-day fulfillment networks serving US and UK multi-site foodservice operators, alongside OEM direct supply for appliance manufacturers in Vietnam and Thailand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigerator door seal gaskets sit at a platform-economics inflection where IoT-enabled refrigeration monitoring systems create embedded replacement alert services, shifting procurement from calendar-based schedules to predictive demand signals.
For Market Incumbents: Build formulation certification moats by securing parallel FDA food contact, EU 1935/2004 migration limits, and China GB standard qualifications before regulatory divergence widens qualification timelines. Incumbent compounders should deepen backward integration into captive PVC resin processing to offset REACH phthalate restriction impacts, while defending channel position against specialized seal distributors unbundling gasket replacement from OEM service contracts. Magnetic strip supply concentration in Chinese coastal provinces represents the critical vulnerability requiring dual-source arrangements or captive extrusion investments. For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical cold-chain buildout where FSSAI enforcement and PLI scheme incentives create gasket demand in an underpenetrated replacement market. New entrants should target predictive maintenance integration partnerships with IoT refrigeration monitoring providers, offering embedded gasket replacement alert services that compress procurement cycles. Same-day fulfillment capability for multi-site restaurant operators represents the most penetrable service gap in US and UK markets. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap compounders with multi-jurisdiction certification maintenance and backward integration into extrusion tooling ownership. Long-term viability in this market hinges on regulatory chemistry adaptation capacity and magnetic strip supply security across the analysis window. The signal to watch is EPA SNAP refrigerant phase-down enforcement intensity, which compresses gasket service intervals and elevates performance specification priority in commercial installations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnetic Strip Extrusion | Captive ferrite powder processing insulates margin pools from Chinese coastal province supply concentration. |
| Multi-Jurisdiction Certification Investment | Parallel FDA, EU 1935/2004, and China GB qualifications compress product launch timelines for OEM customers. |
| Predictive Maintenance Partnership | IoT sensor integration with thermal imaging creates embedded replacement alert services for commercial operators. |
| Regional Compounding Localization | Ho Chi Minh City and Pune-Aurangabad facilities shorten lead times for Thai and Indonesian OEM assembly. |
| REACH-Compliant PVC Reformulation | Non-migratory plasticizer substitution preserves access to EU commercial cold-chain replacement programs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs/trade data, appliance OEM procurement disclosures, and regulatory filing databases. Primary interviews engaged polymer compounding technical directors, commercial refrigeration maintenance contractors, pharmaceutical cold-chain logistics operators, and foodservice MRO procurement managers. Secondary validation drew from EPA SNAP program documentation, ECHA REACH restriction updates, China GB standard revisions, and SEC filings from listed appliance manufacturers. Bottom-up demand modeling across replacement cycles and OEM attach rates was triangulated against top-down market sizing from polymer consumption data.
Forecast inputs span material grade substitution trajectories, regulatory tightening schedules, and commercial end-user consolidation patterns across the projection horizon. Segmentation dimensions modeled include elastomer compound type, end-use environment, profile thickness, and installation mechanism, with geographic production cluster dynamics as an industry-specific overlay. CAGRs were derived from replacement cycle compression rates and OEM localization trends. Industry-specific forecast inputs incorporate HACCP audit mandate enforcement intensity and F-Gas leakage penalty structures.
Stress conditions across EPDM feedstock volatility, magnetic strip supply disruption, and REACH phthalate restriction acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation timelines and commercial operator procurement centralization rates. Quarterly review of EPA enforcement actions, ECHA restriction proposal progress, and Indian PLI scheme disbursement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Wrapping Tissues Market
Packaging Materials
Nonwoven Packaging Market
Packaging Materials
Thailand Packaging Market
Packaging Materials
Trifold Packaging Market
Packaging Materials
Sterilization Roll Market
Packaging Materials
Cold Chain Packaging Materials Market
Packaging Materials
Collagen Sausage Casings Market
Packaging Materials
Packaging Laminates Market
Packaging Materials
Stick Packaging Market
Packaging Materials
Floppy Disk Liner Market
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market
Packaging Materials
VCI Shrink Films Market
Packaging Materials
Transit Packaging Market
Packaging Materials
Mylar Market
Packaging Materials
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market
Packaging Materials
Cutting Tool Packaging Market