
 Transit Packaging Market | 2026-2036
Transit Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Transit Packaging Market Outlook
Corrugated board mills across the North American Southeast are consolidating as containerboard capacity tightens. Smurfit Kappa leverages integrated pulp-to-box operations across Europe and the Americas. International Paper sustains massive linerboard output from its US Gulf Coast mills. DS Smith specializes in recycled-content corrugated solutions for grocery and consumer goods channels.
Transit packaging encompasses reusable and single-use containers engineered to protect goods during intermodal transport, with corrugated fiberboard typically constructed from 23-42 lb/msf linerboard and 26-36 lb/msf medium fluting to achieve Edge Crush Test ratings of 23-71 lb/in. Its primary purpose is to prevent product damage through compression resistance, stacking stability, and vibration damping across truck, rail, and ocean freight legs. Boxes constructed from cardboard dominate volume shipments in e-commerce and retail distribution, while plastic pallets are gaining share in closed-loop pharmaceutical and food supply chains where hygiene standards exceed wood alternatives. The automotive end user segment relies heavily on returnable plastic crates and metal stillages for just-in-sequence assembly line delivery.
The US EPA promotes sustainable materials management guidelines that push shippers toward recyclable and lightweight formats. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility and recycled content thresholds that reshape material selection across member states. China's GB standards for packaging require reduction of excessive packaging layers in e-commerce parcels. Stakeholders must monitor how diverging national recycling infrastructure investments alter total cost of ownership calculations for multi-material packaging systems.
Market Dynamics
E-commerce fulfillment velocity is compressing packaging specification cycles from annual to quarterly reviews, forcing converters to maintain digital print and die-cut flexibility that legacy equipment cannot support.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates accelerate investment in closed-loop collection infrastructure across Germany, France, and Italy.
- Returnable plastic crates:Automotive suppliers in Stuttgart and Wolfsburg adopt standardized foldable containers for just-in-sequence assembly line delivery, cutting per-trip packaging costs.
- China's export manufacturing zones:Shenzhen and Dongguan electronics clusters generate concentrated demand for anti-static corrugated and vacuum-formed trays.
Market Restraints
- Containerboard input volatility:Old corrugated container feedstock prices swing with Chinese import quota fluctuations, squeezing independent converter margins.
- Gulf Coast linerboard concentration:Three integrated mills control over half of North American kraft linerboard supply, creating bottleneck risk during hurricane season.
- Reusable pallet pooling limitations:Hygiene certification gaps block plastic pallet expansion into fresh produce beyond controlled-temperature channels.
Strategic Opportunities
- India's pharmaceutical cold chain:Temperature-assured transit packaging penetration remains below 15% for generic drug exports, creating white space for insulated corrugated solutions.
- RFID-embedded corrugated convergence:Item-level tracking integration with existing box manufacturing lines enables premium pricing for high-value electronics shippers.
- US EPA sustainable materials management:Federal procurement preference for recyclable formats opens institutional buyer segments previously locked into reusable plastic.
Industry Challenges
- Structural engineer talent scarcity:Finite element analysis capability for custom box design concentrates among aging specialists near Wisconsin and Michigan paper research institutes.
- Legacy ERP integration friction:Converter scheduling systems struggle to synchronize with real-time e-commerce order streams from Amazon and Shopify fulfillment networks.
- ISPM-15 heat treatment certification backlog:Wood pallet exporters face 6-8 week approval delays at understaffed USDA inspection facilities near Los Angeles and Savannah ports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transit Packaging Market |
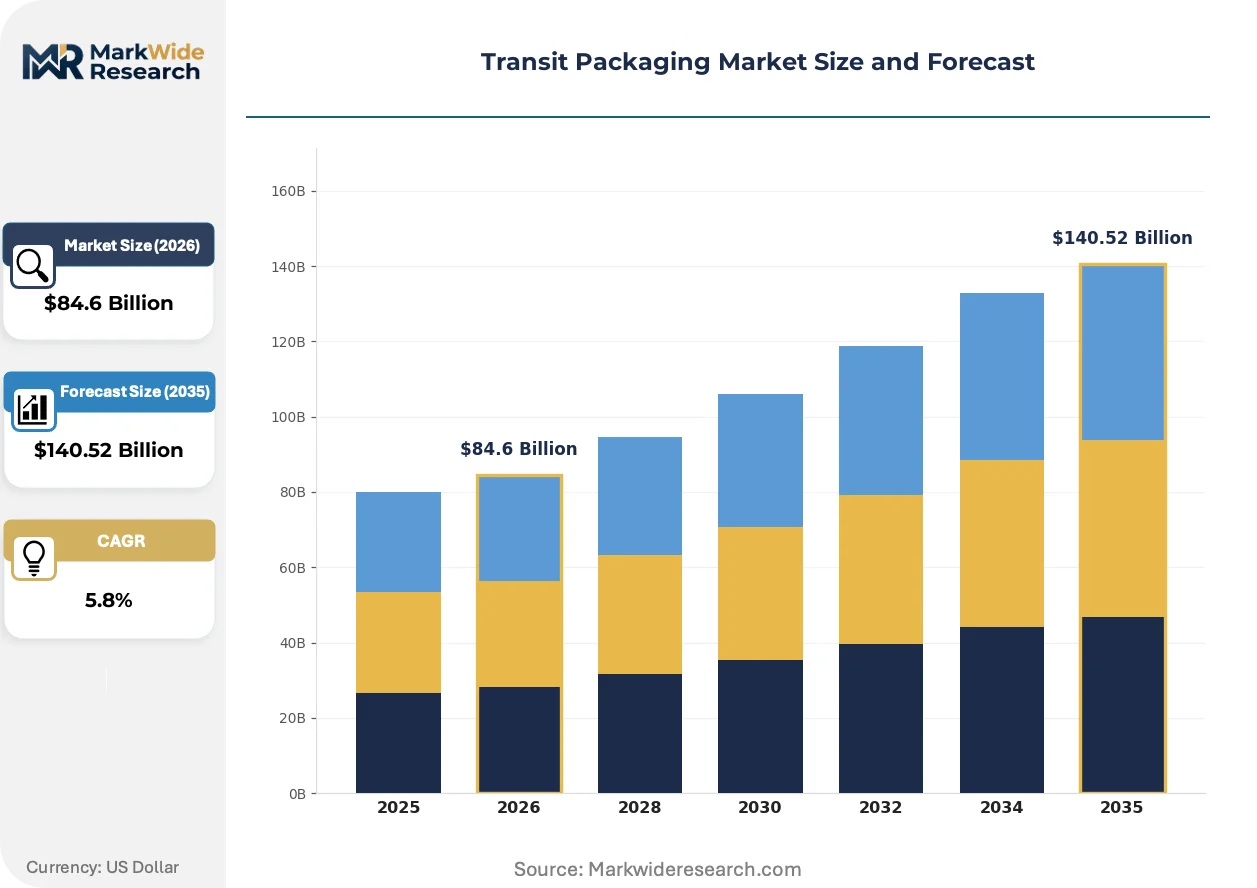
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $140.52 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Pallets, Crates, Bags Material: Wood, Plastic, Metal, Cardboard End User: Electronics, Food & Beverage, Pharmaceuticals, Automotive Size: Small, Medium, Large, Oversized |
| Companies Covered | Smurfit Kappa, International Paper, WestRock Company, Mondi, Nefab AB, ProAmpac, DS Smith, Sonoco Products Company, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transit Packaging Market Strategic Shifts
Digital specification workflows and automated quality verification are compressing the traditional sample-to-production timeline from weeks to days across converter operations.
Water-based barrier coatings are unifying grease and moisture resistance with standard repulpability. Quick-service restaurant chains in the US Midwest adopt these treatments for fried food delivery boxes at scale. The technology is unifying food safety compliance with circular economy targets previously treated as trade-offs.
REACH restrictions on per- and polyfluoroalkyl substances eliminate oil-resistant fluorochemical treatments from European food contact packaging by 2025. Converter R&D teams in Belgium and the Netherlands pivot to clay-based and bio-wax alternatives. Fresh seafood exporters to Nordic retail chains face the steepest reformulation timelines.
Shippers now specify packaging performance outcomes rather than material prescriptions in tender documents. Third-party logistics providers in the Netherlands and Belgium contract corrugated converters on damage-rate guarantees rather than unit prices. This specification shift concentrates volume with converters maintaining in-house testing laboratories and claims data analytics.
Transit Packaging Market Segmentation
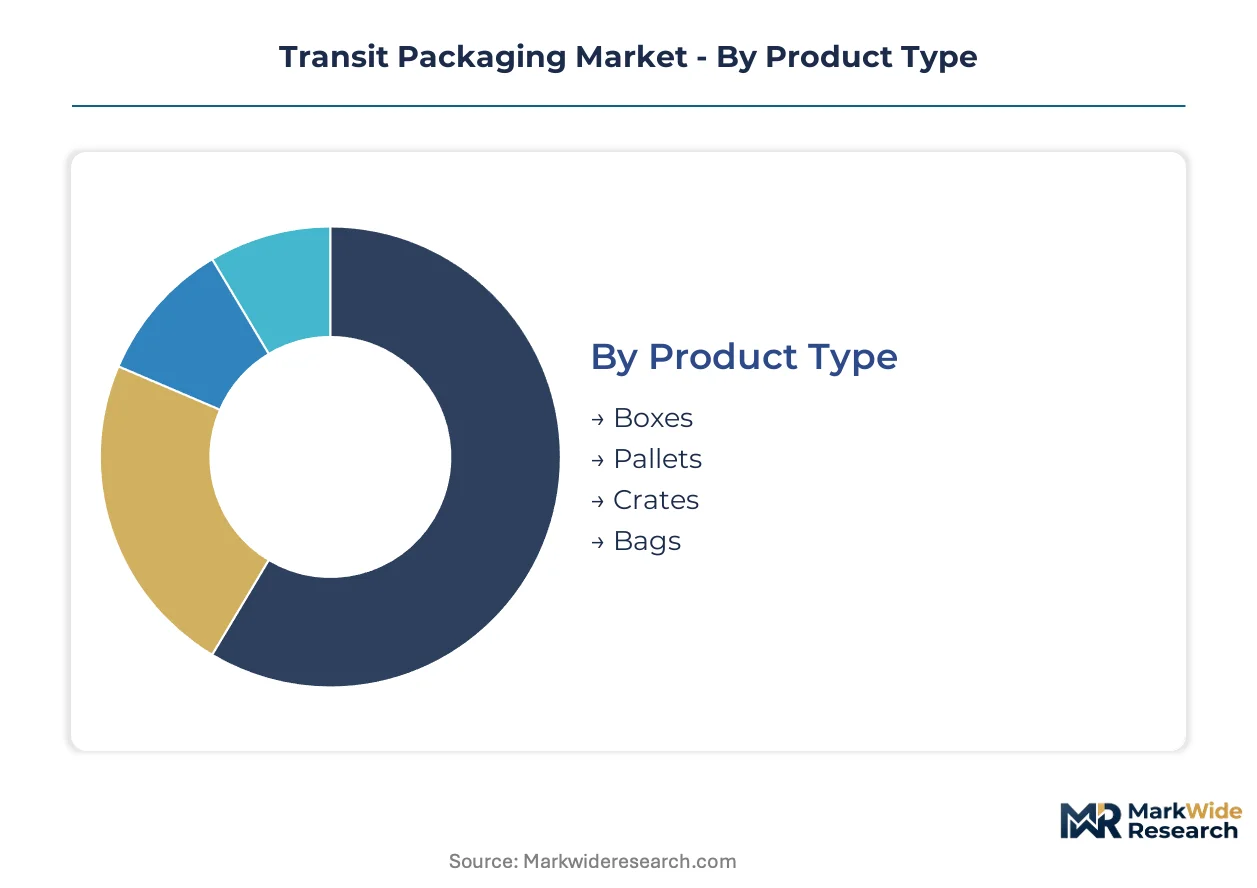
Transit packaging segmentation reflects divergent performance requirements across supply chain legs. Material selection and dimensional specifications determine total cost of ownership calculations for shippers operating multi-modal networks.
Product Type:
Structural format dictates handling compatibility with automated warehouse systems and vehicle cube utilization.
- Boxes:Corrugated fiberboard containers dominate e-commerce fulfillment with standardized FEFCO styles enabling automated case erecting. Demand concentrates in Germany's automotive supplier corridor where just-in-sequence delivery requires precise dimensional tolerances.
- Pallets:Wood block pallets remain the workhorse for FMCG distribution, while plastic pallets capture pharmaceutical cold chains requiring washdown protocols. Hygiene certification gaps block plastic expansion into fresh produce beyond controlled-temperature channels.
- Crates:Returnable plastic crates serve closed-loop produce distribution between farms and retail distribution centers.
- Bags:Flexible intermediate bulk containers handle granular chemicals and agricultural commodities in rail and ocean bulk shipments.
Mature deployment sits with Pallets. Newer deployment is concentrated in Crates with RFID tracking integration.
Material:
Cost tier and circularity credentials drive procurement decisions across institutional buyer segments.
- Cardboard:Recycled-content corrugated from 23-42 lb/msf linerboard achieves ECT ratings of 23-71 lb/in for stacking stability. E-commerce fulfillment velocity in China's export manufacturing zones compresses specification cycles from annual to quarterly reviews.
- Plastic:High-density polyethylene and polypropylene formats deliver moisture resistance and multi-trip durability for closed-loop pooling systems. Automotive suppliers in Stuttgart and Wolfsburg adopt standardized foldable containers for assembly line delivery.
- Wood:ISPM-15 heat-treated softwood pallets face certification backlogs at understaffed USDA inspection facilities near Los Angeles and Savannah ports.
- Metal:Steel stillages and wire mesh containers handle heavy automotive components in just-in-sequence supply chains.
Volume leadership belongs to Cardboard. Margin expansion is concentrating in Plastic with pooling service revenue attachment.
End User:
Application-specific damage sensitivity and regulatory compliance reshape material specifications.
- Automotive:Just-in-sequence assembly line delivery mandates returnable plastic crates and metal stillages with precise dimensional repeatability.
- Electronics:Anti-static corrugated and vacuum-formed trays protect semiconductor components in Shenzhen and Dongguan export clusters.
- Food & Beverage:Water-based barrier coatings unify grease resistance with repulpability for quick-service restaurant delivery boxes.
- Pharmaceuticals:Temperature-assured transit packaging penetration remains below 15% for Indian generic drug exports, creating white space for insulated corrugated solutions.
Specification complexity peaks with Pharmaceuticals. Standardization pressure is strongest in Automotive.
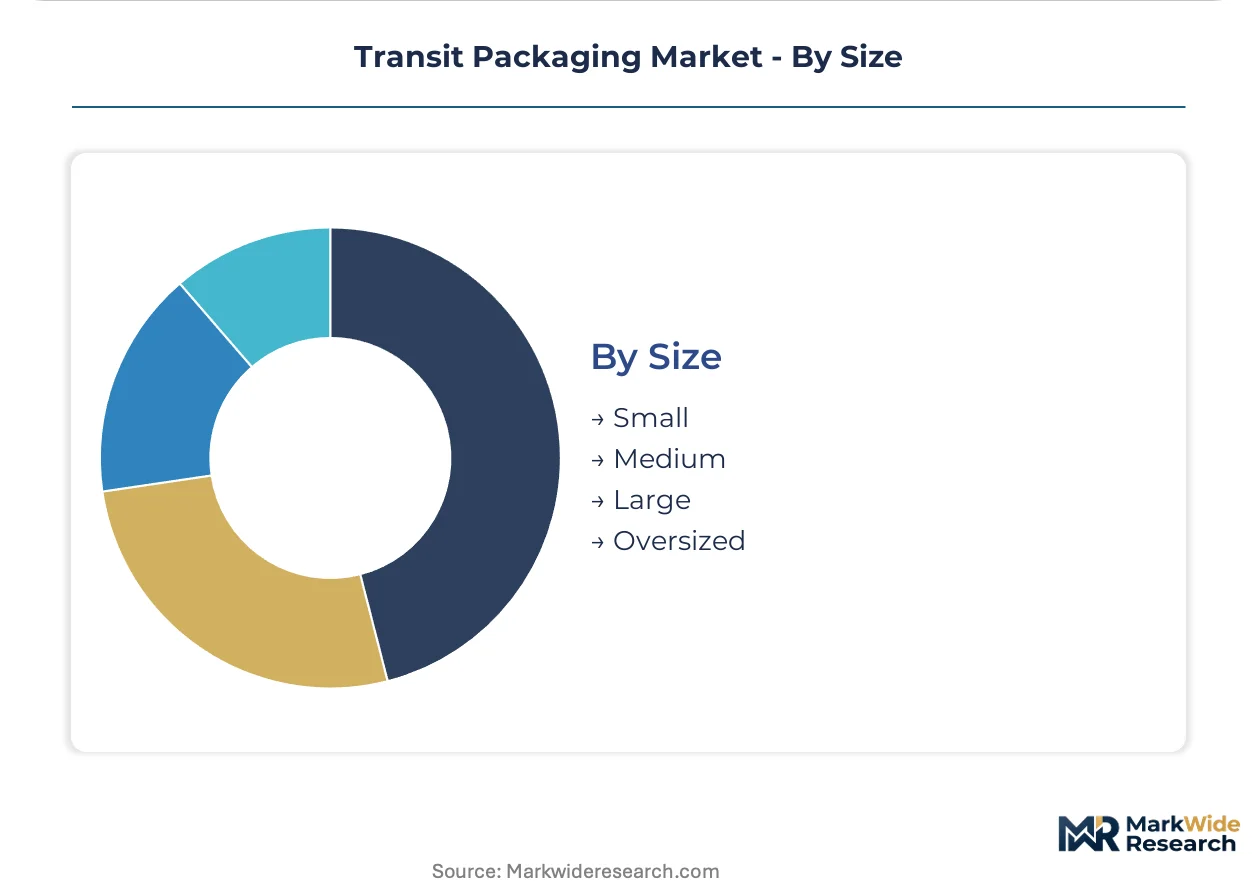
Size:
Dimensional categories align with material handling equipment constraints and vehicle loading optimization.
- Medium:48x40 inch footprint compatibility with standard pallet racking and forklift tine spacing dominates FMCG distribution.
- Large:Custom dimensions for appliance and furniture shipments maximize trailer cube utilization.
- Small:Parcel-scale formats align with last-mile delivery vehicle constraints and automated sortation system clearances.
- Oversized:Project cargo and machinery shipments require engineered blocking and bracing with load-rated timber or steel structures.
Procurement volume concentrates in Medium formats. Engineering intensity escalates with Oversized specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Old corrugated container feedstock availability anchors competitive positioning across major producing geographies, with integrated mills leveraging captive pulp supplies against independent converters facing volatile OCC pricing.
United States
E-commerce fulfillment velocity from Amazon and Shopify networks compresses specification cycles for corrugated converters. The EPA promotes sustainable materials management guidelines that push federal procurement toward recyclable formats. Gulf Coast linerboard mills near Houston and Mobile sustain massive kraft output, though hurricane season creates periodic bottleneck risk.
Germany
Automotive suppliers in Stuttgart and Wolfsburg drive demand for returnable plastic crates with just-in-sequence assembly line delivery. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility and recycled content thresholds that reshape converter investments. The automotive supplier corridor stretching from Bavaria to Lower Saxony concentrates specification expertise for precision-tolerance packaging.
China
Shenzhen and Dongguan electronics clusters generate concentrated demand for anti-static corrugated and vacuum-formed trays protecting semiconductor components. GB standards for packaging require reduction of excessive packaging layers in e-commerce parcels. Export manufacturing zones in Guangdong Province face specification pressure from cross-border fulfillment platforms.
India
Generic drug exports drive underpenetrated demand for temperature-assured transit packaging, with current adoption below 15% creating white space for insulated corrugated solutions. CDSCO regulations govern pharmaceutical distribution integrity requirements. Mumbai-Pune pharmaceutical clusters and Ahmedabad formulation hubs are expanding cold chain infrastructure.
Netherlands
Third-party logistics providers in Rotterdam and Antwerp contract corrugated converters on damage-rate guarantees rather than unit prices, concentrating volume with testing-capable suppliers. REACH restrictions on per- and polyfluoroalkyl substances eliminate oil-resistant fluorochemical treatments from food contact packaging by 2025. The Benelux distribution hub position demands multi-modal packaging performance verification.
Transit Packaging Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital print flexibility and RFID-embedded tracking integration. The vendor base spans integrated containerboard-to-box operators, independent converters with regional die-cut specialization, and pooling service providers attaching logistics revenue to plastic crate deployment. Three archetypes dominate: pulp-integrated giants with captive linerboard supply, mid-scale converters leveraging digital equipment for short-run agility, and pooling operators monetizing returnable asset cycles. Competitive moves concentrate on M&A-driven geographic consolidation and backward integration into recycled fiber collection infrastructure.
Within the integrated tier, Smurfit Kappa and International Paper exemplify scale-driven positioning across multiple continents, while DS Smith represents recycled-content specialization for grocery and consumer goods channels. These entities anchor industry structure through captive pulp-to-box operations that independent converters cannot replicate without massive capital deployment.
| Leading Market Players |
|---|
| Smurfit Kappa |
| International Paper |
| WestRock Company |
| Mondi |
| Nefab AB |
| ProAmpac |
| DS Smith |
| Sonoco Products Company |
| Sealed Air Corporation |
| Others |
Value Chain & Pricing Dynamics
Digital print flexibility and automated die-cut workflows are compressing converter margins while simultaneously concentrating volume with equipment-rich suppliers capable of quarterly specification cycles. This production-method transition simultaneously reshapes cost economics across legacy fixed-asset operators and supply concentration toward digitally enabled converters in Germany and the Netherlands.
Pricing Analysis
Damage-rate guarantee bundling separates testing-capable converters from commodity box suppliers in Benelux procurement contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Price erosion runs through independent converters lacking captive linerboard supply as OCC feedstock volatility squeezes margins. E-commerce fulfillment platforms exhibit highest price sensitivity; pharmaceutical cold chain buyers prioritize performance guarantees over unit cost.
Supply Chain Analysis
EU Packaging and Packaging Waste Regulation domestic-content mandates are reshaping sourcing patterns toward integrated European pulp-to-box operators. Supply concentrates in the United States, Germany, and China, with captive linerboard mills in the US Gulf Coast and integrated European operations anchoring volume. Raw material dependencies center on old corrugated containers, kraft pulp, and water-based barrier coatings. Single-source vulnerability concentrates around hurricane-season disruption at Gulf Coast mills. Distribution runs through third-party logistics providers contracting on outcome-based performance metrics rather than transactional unit pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RFID-embedded corrugated convergence represents a technology-transition phase displacing legacy tracking attachments with integrated manufacturing-line solutions. This shift from bolt-on to built-in capability redefines competitive positioning across converter tiers.
For Market Incumbents: To counter digital-native entrants with short-run agility, Smurfit Kappa and International Paper should deepen backward integration into recycled fiber collection infrastructure across Germany and the American Southeast. Captive OCC supply buffers margin pressure from Chinese import quota volatility. Certification investment in ISPM-15 heat treatment capacity at understaffed USDA facilities defends wood pallet market share against plastic alternatives.
For New Entrants and Emerging Players: The premium-economy price-point gap in Indian pharmaceutical cold chain packaging opens white space for insulated corrugated solutions below 15% current penetration. Target Mumbai-Pune generic drug export clusters with temperature-assurance performance guarantees. Go-to-market through CDSCO-compliant validation partnerships accelerates regulatory acceptance faster than direct converter competition.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale digital converters with RFID integration capability and regional die-cut specialization. The five-to-ten year viability window favors pooling service operators monetizing returnable plastic crate cycles in automotive closed-loop systems. Watch for inflection when e-commerce fulfillment platforms mandate item-level tracking as standard tender requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Collection | Captive OCC supply insulates margins from Chinese import quota fluctuations at Gulf Coast mills. |
| RFID-Embedded Corrugated Manufacturing Line Investment | Item-level tracking integration enables premium pricing from high-value electronics shippers in Shenzhen. |
| Damage-Rate Guarantee Contracting Model | Outcome-based pricing concentrates volume with testing-capable converters in Rotterdam and Antwerp. |
| Water-Based Barrier Coating Scale-Up | Grease resistance with repulpability captures quick-service restaurant delivery box demand in the US Midwest. |
| Returnable Plastic Crate Pooling Service Expansion | Multi-trip durability with hygiene certification penetrates pharmaceutical cold chains beyond fresh produce limitations. |
Study Parameters
Document review covered customs and trade data, SEC filings from integrated packaging producers, and EU regulatory submissions, complemented by interviews with corrugated converter operations directors, automotive Tier 1 supplier procurement managers, third-party logistics contract specialists, and pharmaceutical cold chain quality assurance leads. Secondary validation drew from EPA sustainable materials management guidelines, CDSCO distribution integrity requirements, and Chinese GB packaging standards. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation outputs reflect material, product type, end user, and geographic production cluster dimensions throughout the forecast period. CAGRs were derived from regression analysis against e-commerce fulfillment velocity indices, automotive production schedules, and pharmaceutical export growth trajectories. Industry-specific inputs included containerboard capacity utilization rates, returnable asset cycle counts, and digital print equipment deployment tracking.
Inputs from regulatory filings and trade databases were available through the study window; gaps in real-time converter pricing transparency and proprietary pooling service utilization data introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding EU Packaging and Packaging Waste Regulation implementation timelines and hurricane-season supply disruption frequencies. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
VCI Packaging Market
Packaging Materials
Nonwoven Packaging Market
Packaging Materials
Europe Single-Use Packaging Market
Packaging Materials
Flow Wraps Market
Packaging Materials
US Packaging Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Child Resistant Re-Closable Edible Bags Market
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Mailer Packaging Market
Packaging Materials
Cement Packaging Market
Packaging Materials
Anti-Scratch Film Market
Packaging Materials
Collagen Sausage Casings Market
Packaging Materials
Packaging Materials Market
Packaging Materials
Greaseproof Sheets Market
Packaging Materials
Insulated Thermal Box Liners Market