
 Pressure Cooker Market | 2026-2036
Pressure Cooker Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Cooker Market Intelligence
REACH compliance is hardening material sourcing requirements across European supply chains, forcing manufacturers to reformulate non-stick coatings and validate stainless steel grades. Hawkins Cookers Limited leverages its foundry-to-retail integration to absorb alloy cost volatility in India. Groupe SEB sustains premium positioning through multi-brand architecture spanning Fissler and Tefal. Midea Group anchors volume production through automated stamping lines in Guangdong, competing on scale across Asia-Pacific distribution channels.
A pressure cooker is a sealed vessel designed to cook food under elevated steam pressure, typically operating at 15 psi above atmospheric pressure to achieve cooking temperatures exceeding 121 degrees Celsius through trapped steam. Its primary purpose is to reduce cooking duration by up to 70 percent while preserving nutrient density in legumes, grains, and tough meat cuts. Electric and multifunctional variants now lead revenue growth as programmable pressure sensors and microprocessor-controlled thermal cycles displace manual stovetop units in urban households. Stainless steel construction commands the dominant material share due to durability and compatibility with induction cooktops, though aluminum retains cost advantages in entry-level stovetop segments across price-sensitive markets.
FDA food-contact substance regulations govern coating chemistries in US-bound products, while EU F-Gas Regulation constrains refrigerant choices in multifunctional units with integrated cooling. India's BIS mandatory certification for pressure cookers mandates burst-pressure testing and handle integrity standards that exclude unbranded imports. Stakeholders must monitor divergence between regional pressure-safety standards and emerging energy-efficiency labeling schemes as compliance costs fragment export strategies.
Market Dynamics
Electric pressure cookers with programmable microprocessors are compressing manual stovetop replacement cycles in Southeast Asian urban households, while India's BIS certification tightening is forcing material-grade upgrades across export-bound manufacturing clusters.
Growth Catalysts
- REACH compliance in Europe:ECHA chemical restrictions on non-stick coatings are accelerating stainless steel adoption as manufacturers reformulate surface treatments to maintain EU market access.
- Induction cooktop proliferation:Urban kitchen renovations across India and China are creating pull for magnetic-grade stainless steel vessels compatible with electromagnetic heating surfaces.
- Compact electric models:Space-constrained apartments in Jakarta, Bangkok, and Ho Chi Minh City are driving replacement of traditional stovetop units with countertop multifunctional appliances.
Market Restraints
- Nickel alloy cost volatility:304-grade stainless steel input prices fluctuate with London Metal Exchange nickel futures, squeezing margin structures for mid-tier manufacturers without captive foundry capacity.
- Guangdong supply concentration:Automated stamping and assembly lines cluster in China's Pearl River Delta, creating geographic single-point vulnerability for brands dependent on contract manufacturing.
- EU F-Gas Regulation constraints:Multifunctional units with integrated cooling face refrigerant chemistry restrictions that limit thermal management design flexibility and extend R&D validation timelines.
Strategic Opportunities
- Tier-II Indian cities:Underpenetrated markets in Lucknow, Indore, and Coimbatore present whitespace for electric pressure cooker distribution as electrification rates and disposable incomes rise.
- Smart home integration:Wi-Fi-enabled pressure sensors and app-controlled thermal cycles are converging with voice-assistant ecosystems to create premium positioning in connected kitchens.
- India PLI scheme:Production-linked incentives for domestic manufacturing of consumer appliances are reducing landed cost disadvantages for local assembly versus Chinese imports.
Industry Challenges
- BIS certification timelines:Burst-pressure testing and handle integrity validation for India's mandatory ISI mark creates 4-6 month product launch delays for new market entrants.
- Coating chemistry expertise:FDA food-contact substance compliance for US-bound products requires specialized formulation knowledge that concentrates among a limited supplier base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Cooker Market |
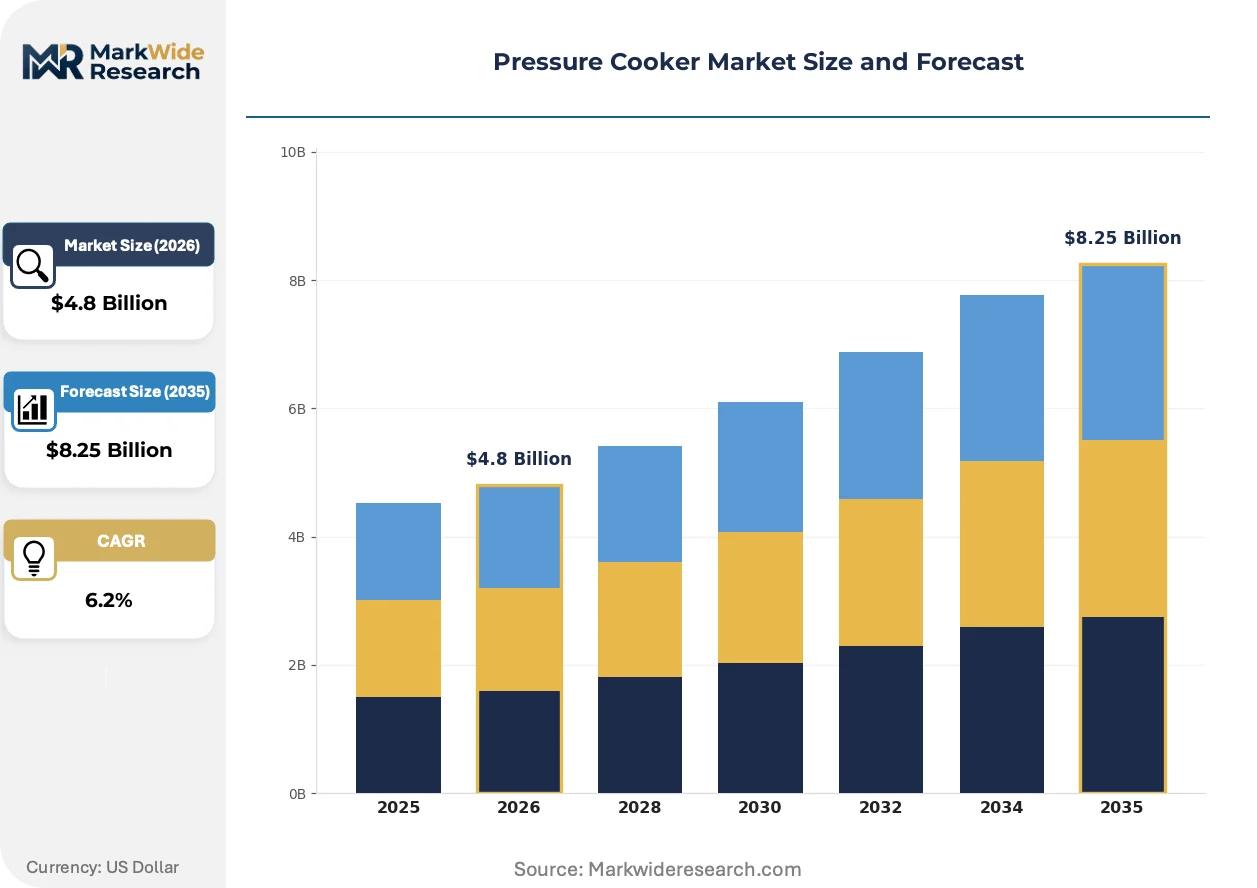
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Stovetop, Multifunctional, Pressure Canner Material: Stainless Steel, Aluminum, Non-Stick Coating, Cast Iron Size: 6 Quart, 8 Quart, 10 Quart, 12 Quart End User: Households, Restaurants, Catering Services, Food Trucks |
| Companies Covered | Instant Brands Inc., Hawkins Cookers Limited, National Presto Industries, Inc., Matfer Bourgeat USA, Inc., Midea Group, Fissler, TTK Prestige Limited, IRIS USA, Inc., Groupe SEB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Cooker Market Strategic Shifts & Innovations
Microprocessor-controlled thermal management is rewriting competitive differentiation as programmable sensors replace mechanical pressure valves, while regulatory chemistry constraints are fragmenting coating supply chains across major export destinations.
Precision pressure sensors with digital feedback loops are absorbing the safety-assurance function previously served by weighted mechanical valves. Urban Indian households with induction cooktops are adopting these units fastest, compressing the replacement window for legacy aluminum stovetop models from decade-long cycles to 3-5 year refresh rates.
REACH substance restrictions on perfluorinated compounds are forcing reformulation of non-stick interior coatings across European supply chains. Manufacturers are validating ceramic-based and sol-gel alternatives that trade some release performance for regulatory compliance, with small-appliance brands in Germany and France most affected by the 2025 enforcement timeline.
Direct-to-consumer channel expansion is fragmenting traditional kitchenware retail in Southeast Asia. Subscription-box and live-commerce platforms in Indonesia and Vietnam are displacing hypermarket appliance aisles for first-time electric pressure cooker purchases, compressing brand-building budgets toward influencer partnerships rather than shelf-space negotiations.
Pressure Cooker Market Segmentation
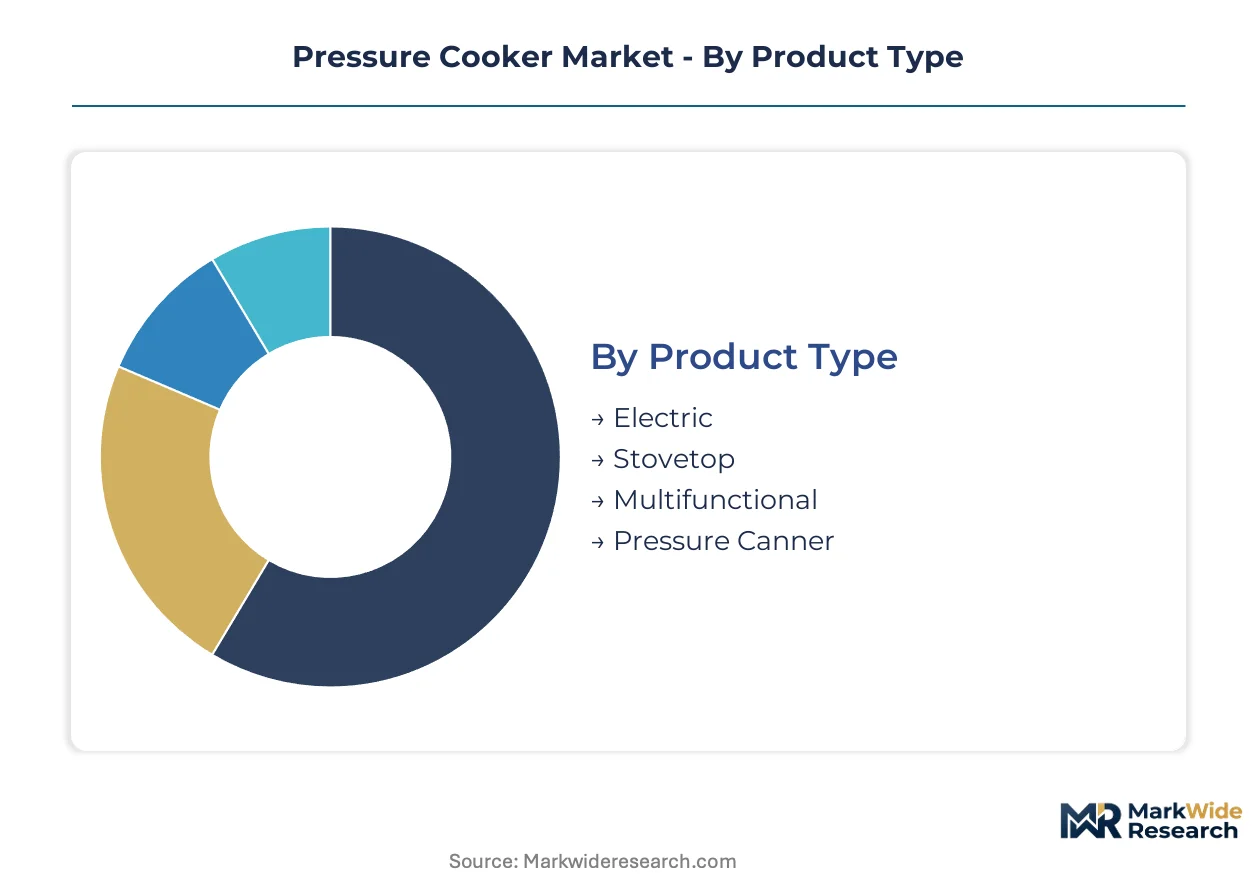
Pressure cooker segmentation reveals how capital allocation, material chemistry, and end-use durability requirements fragment manufacturing strategies. Distinct tooling investments and certification pathways separate electric programmable units from legacy stovetop vessels.
Product Type:
Electric pressure cookers demand the heaviest upfront capital, requiring microprocessor assembly lines, pressure sensor calibration labs, and electromagnetic compatibility testing infrastructure that stovetop manufacturers bypass entirely.
- Electric:Microprocessor-controlled thermal cycles with programmable pressure sensors enable precise cooking algorithms for grains and legumes. Demand concentrates in Jakarta, Bangkok, and Ho Chi Minh City apartments where countertop units displace gas stovetops amid space constraints and induction cooktop proliferation.
- Multifunctional:Integrated pressure cooking, slow cooking, and sautéing capabilities expand utility in single-appliance kitchens. Urban Indian households with BIS-certified induction surfaces drive replacement cycles as these units compress multiple appliances into one footprint.
- Stovetop:Manual pressure valves and weighted regulators serve price-sensitive rural markets and commercial kitchens requiring rapid heat response.
- Pressure Canner:Larger-capacity vessels with sustained high-pressure capability target food preservation enthusiasts and small-scale commercial processors.
Most installed capacity flows through Stovetop. Expansion is steepest in Electric.
Material:
Material selection directly determines compatibility with induction heating surfaces, BIS burst-pressure certification outcomes, and REACH coating compliance costs across export destinations.
- Stainless Steel:304-grade austenitic construction withstands cyclic pressure loading while maintaining magnetic permeability for induction cooktops. Maharashtra and Karnataka foundries supply domestic Indian manufacturers facing BIS certification tightening that excludes lower-grade alloys.
- Aluminum:Die-cast and stamped variants retain cost advantages in entry-level stovetop segments across price-sensitive Southeast Asian markets, though induction incompatibility limits urban replacement demand.
- Non-Stick Coating:Ceramic and sol-gel formulations replace perfluorinated compounds under ECHA REACH restrictions, trading release performance for European market access.
- Cast Iron:Enamel-coated vessels serve slow-cooking traditions and outdoor pressure-frying applications with exceptional thermal retention.
Volume leadership sits with Stainless Steel. Aluminum faces steepest share erosion.
Size:
Capacity segmentation tracks household composition patterns and commercial batch-size economics, with quart ratings determining wall thickness engineering and lid-seal design specifications.
- 6 Quart:Compact footprint serves nuclear families and countertop electric units in space-constrained urban apartments. Indonesian and Vietnamese live-commerce channels push this capacity for first-time electric pressure cooker buyers.
- 8 Quart:Mid-capacity workhorse balances batch flexibility with storage practicality for multi-generational households.
- 10 Quart:Larger vessels target meal-preparation enthusiasts and small catering operations requiring bulk protein preparation.
- 12 Quart:Maximum residential capacity serves pressure canning applications and commercial food trucks with high-throughput demands.
Household penetration peaks at 6 Quart. Commercial migration favors 10 Quart and above.
End User:
End-use segmentation separates consumer durability expectations from commercial duty-cycle demands, with warranty terms and replacement part availability diverging sharply across buyer categories.
- Households:Primary demand engine spanning urban induction-compatible upgrades and rural stovetop replacement. Indian tier-II cities including Lucknow, Indore, and Coimbatore present whitespace as electrification and disposable incomes rise.
- Restaurants:High-frequency cycling demands reinforced gaskets, quick-release valves, and rapid pressure recovery for lunch-rush throughput.
- Catering Services:Batch-scale operations prioritize 10-quart and 12-quart vessels with NSF or equivalent food-safety certifications for event-volume cooking.
- Food Trucks:Space-optimized electric and stovetop units with compact footprints and dual-fuel flexibility for mobile kitchen constraints.
Households anchor absolute unit volumes. Food Trucks represent the most nascent addressable segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pressure cooker manufacturing traces its industrial roots to post-war aluminum foundries in the United States and Germany, where stamped-metal vessel production first achieved scale. Contemporary demand geography reflects this heritage while shifting toward Asian electrification and certification-driven consolidation.
United States
Programmable electric units with Wi-Fi connectivity dominate kitchen appliance retail as consumers replace decade-old stovetop models. FDA food-contact substance regulations govern coating chemistries for domestic production and imports alike. Eau Claire, Wisconsin hosts legacy stamping operations that supply National Presto Industries with aluminum vessel components for North American distribution.
India
Urban households in Mumbai, Bangalore, and Delhi-NCR are upgrading to induction-compatible stainless steel vessels at compressed replacement cycles. BIS mandatory certification for pressure cookers mandates burst-pressure testing and handle integrity standards that exclude unbranded imports. Maharashtra and Karnataka foundry clusters supply Hawkins Cookers and TTK Prestige with 304-grade austenitic steel certified for domestic ISI mark requirements.
China
Guangdong Province anchors automated stamping and assembly capacity serving export markets across Southeast Asia and Europe. MIIT energy-efficiency labeling schemes for small appliances are tightening standby power requirements for electric multifunctional units. Midea Group's volume production lines in Foshan compete on scale through Pearl River Delta logistics integration.
Germany
ECHA REACH substance restrictions on perfluorinated compounds are forcing reformulation of non-stick interior coatings ahead of 2025 enforcement timelines. Premium stainless steel fabricators in Solingen and Stuttgart exemplify archetype positioning through multi-brand architecture. Fissler maintains foundry-to-retail integration that absorbs nickel alloy cost volatility through captive 18/10 steel supply.
Indonesia
Jakarta apartment dwellers are displacing traditional gas stovetops with compact countertop electric units amid space constraints and induction cooktop proliferation. The country's national standards body enforces pressure vessel safety markings that parallel BIS testing protocols. Live-commerce platforms and subscription-box channels in Surabaya and Bandung are fragmenting traditional hypermarket appliance retail for first-time electric pressure cooker purchases.
Pressure Cooker Market Key Industry Players
The competitive structure tilts toward vertically integrated domestic specialists with captive foundry capacity. Three tiers separate premium multi-brand holding companies from volume-scale Chinese exporters and regional certification specialists. Strategic moves concentrate on backward integration into alloy supply and geographic expansion through direct-to-consumer channel capture.
Among India-based fabricators, Hawkins Cookers Limited and TTK Prestige Limited exemplify the certification-anchored specialist archetype through Maharashtra and Karnataka production clusters. Groupe SEB occupies a position representing European multi-brand architecture spanning premium and mass-market price points. Instant Brands Inc. anchors the connected-appliance vector through programmable microprocessor integration that compresses replacement cycles in North American households.
| Leading Market Players |
|---|
| Instant Brands Inc. |
| Hawkins Cookers Limited |
| National Presto Industries, Inc. |
| Matfer Bourgeat USA, Inc. |
| Midea Group |
| Fissler |
| TTK Prestige Limited |
| IRIS USA, Inc. |
| Groupe SEB |
| Others |
Cost & Logistics Intelligence
EU REACH substance restrictions on perfluorinated compounds gate qualified supply for European market access while simultaneously anchoring premium-tier pricing for compliant stainless steel and ceramic-coated alternatives. Manufacturers lacking reformulation capabilities face exclusion from higher-margin segments as certification-validated inputs concentrate among foundry-integrated specialists.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates induction-compatible stainless steel vessels with BIS certification from basic aluminum stovetop units and unbranded imports. Price differentiation hinges on material grade validation and after-sales service bundling, with 304-grade austenitic construction commanding substantial premiums over die-cast aluminum. Cost compression in entry-level segments is intensifying because nickel alloy volatility squeezes mid-tier manufacturers without captive foundry capacity. Rural Indian households and Southeast Asian price-sensitive buyers exhibit highest price sensitivity, while urban induction-upgrade purchasers in Mumbai and Jakarta demonstrate lowest sensitivity to premium positioning.
Supply Chain Analysis
India's PLI scheme for domestic appliance manufacturing is reshaping sourcing patterns by incentivizing local assembly over Chinese imports. Geographic supply concentration centers on China, India, and Germany, with Guangdong Province anchoring automated stamping capacity, Maharashtra and Karnataka hosting Hawkins and TTK Prestige foundry clusters, and Solingen maintaining premium stainless steel fabrication. Raw material dependencies draw from Indonesian nickel ore, South African chromium, and domestic Indian manganese alloys. Single-source vulnerability concentrates in Guangdong contract manufacturing for brands lacking alternative stamping capacity. Distribution runs through direct-to-consumer live-commerce platforms in Indonesia and Vietnam alongside traditional hypermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where India's BIS certification tightening and EU REACH enforcement timelines are accelerating replacement demand for compliant vessels while excluding marginal competitors.
For Market Incumbents: Deepen backward integration into 304-grade stainless steel supply through captive Maharashtra or Karnataka foundry investments to absorb nickel cost volatility. Prioritize BIS certification pipeline expansion to exploit 4-6 month launch delays that disadvantage new entrants lacking testing infrastructure. Defend against direct-to-consumer channel fragmentation by securing influencer partnerships on Indonesian and Vietnamese live-commerce platforms.
For New Entrants and Emerging Players: Begin with tier-II Indian cities—Lucknow, Indore, Coimbatore—where electrification rates and disposable incomes are rising yet electric pressure cooker penetration remains underdeveloped. Target 6-quart countertop electric units for first-time buyers via subscription-box and live-commerce channels rather than competing for hypermarket shelf space. Anchor go-to-market strategy on app-controlled thermal cycles and Wi-Fi-enabled pressure sensors for connected-kitchen positioning.
For Investors and Strategic Acquirers: Roll-up economics work for foundry-integrated regional specialists because BIS certification timelines and alloy sourcing expertise create durable moats against contract-manufactured imports. Long-term viability favors captive 304-grade supply and multi-brand architecture spanning premium and mass-market price points. Watch for inflection when tier-II Indian city electrification crosses thresholds that trigger compressed replacement cycles comparable to Jakarta and Bangkok patterns.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Supply | Captive 304-grade foundry capacity insulates Hawkins and TTK Prestige from London Metal Exchange nickel volatility. |
| BIS Certification Pipeline Expansion | ISI mark validation creates 4-6 month competitive moats against unbranded imports and new market entrants. |
| Direct-to-Consumer Channel Capture | Live-commerce platforms in Surabaya and Bandung fragment traditional hypermarket retail for first-time electric unit purchases. |
| Smart Home Integration Investment | Wi-Fi-enabled pressure sensors and voice-assistant compatibility command premium positioning in connected North American kitchens. |
| Ceramic Coating Formulation Development | Sol-gel alternatives to perfluorinated compounds secure EU market access ahead of ECHA REACH enforcement timelines. |
Research Approach
Multiple input streams—foundry operator interviews, retail channel audits, and regulatory filing analysis—were reconciled against customs records and appliance shipment data to construct market size estimates. Primary engagement spanned plant managers at Maharashtra and Karnataka foundries, category buyers at Indonesian hypermarket chains, BIS certification laboratory directors, and procurement leads at Guangdong contract manufacturers. Secondary validation drew from BIS mandatory certification registries, ECHA REACH substance restriction databases, MIIT energy-efficiency labeling disclosures, and Pearl River Delta export customs manifests. Bottom-up unit shipment aggregation and top-down consumer expenditure modeling were cross-referenced for triangulation.
Data-stream reconciliation across product type, material grade, capacity tier, and end-use segmentation anchored volume and value projections over the analysis window. Electric, multifunctional, stovetop, and pressure canner categories were modeled separately with distinct replacement cycle assumptions. Material segmentation tracked stainless steel, aluminum, non-stick coating, and cast iron with induction compatibility and BIS burst-pressure certification as cross-cutting variables. CAGR derivation incorporated urban electrification rates, induction cooktop penetration curves, and regulatory enforcement timelines as industry-specific forecast inputs.
Caveats apply where nickel alloy price spikes, BIS certification backlog extensions, or ECHA substance restriction scope expansions could materially shift the outlook. Forecasts reflect assumptions regarding induction cooktop adoption trajectories and tier-II Indian city income growth patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Ceramic Coated Cookware Market
Kitchen Appliances
Kitchen Appliances Market
Kitchen Appliances
Europe Built-In Coffee Machine Market
Kitchen Appliances
Global Stainless Woks Market
Kitchen Appliances
US Household Coffee Machine Market
Kitchen Appliances
US Smart Oven Market
Kitchen Appliances
Global Smart Ovens Market
Kitchen Appliances
Digital BBQ Tongs and Thermometer Market
Kitchen Appliances
Commercial Tabletop Kitchen Products Market
Kitchen Appliances
Global Baking Tools Market
Kitchen Appliances
North America Electric Kettle Market
Kitchen Appliances
Europe Major Home Appliances Market
Kitchen Appliances
Self-Stirring Mug Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
Portable Outdoor Pizza Oven Market
Kitchen Appliances
Commercial Induction Cooktops Market