

Modular Zero-Waste Kitchen Appliance Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Zero-Waste Kitchen Appliance Market Insights
Recycled stainless steel is broadening the material palette for modular appliance chassis, cutting virgin metal dependence without sacrificing corrosion resistance. BSH Home Appliances Group leverages its European manufacturing footprint to anchor premium composting unit production. Samsung Electronics differentiates through IoT-integrated refrigerator modules that sustain recurring software revenue streams. Whirlpool Corporation competes on manufacturing scale across North American assembly plants.
Modular zero-waste kitchen appliances comprise interchangeable cooking, preservation, and waste-processing units built around standardized connection interfaces and shared power management systems, typically operating at 110-240V with IPX4 minimum ingress protection for wet-zone deployment. The primary commercial purpose is to eliminate food scrap landfill diversion while reducing per-appliance embodied carbon through upgradeable sub-assemblies rather than full-unit replacement. Smart Refrigerators command the largest installed base among product types, though Composting Units represent the fastest margin pool expansion as municipal organic waste bans proliferate. Home Kitchens dominate unit volume, yet Commercial Kitchens concentrate higher average selling prices due to duty-cycle durability requirements and NSF certification premiums.
The EPA guides appliance energy efficiency benchmarks under ENERGY STAR specifications, while the EU Green Deal's circular economy action plan mandates repairability scoring and spare parts availability windows that directly shape product architecture decisions. China's MIIT enforces GB standards for smart home device interoperability, creating compliance costs for modular connectivity protocols. Stakeholders must monitor whether emerging right-to-repair legislation in additional US states fragments certification requirements beyond federal ENERGY STAR baselines.
Market Dynamics
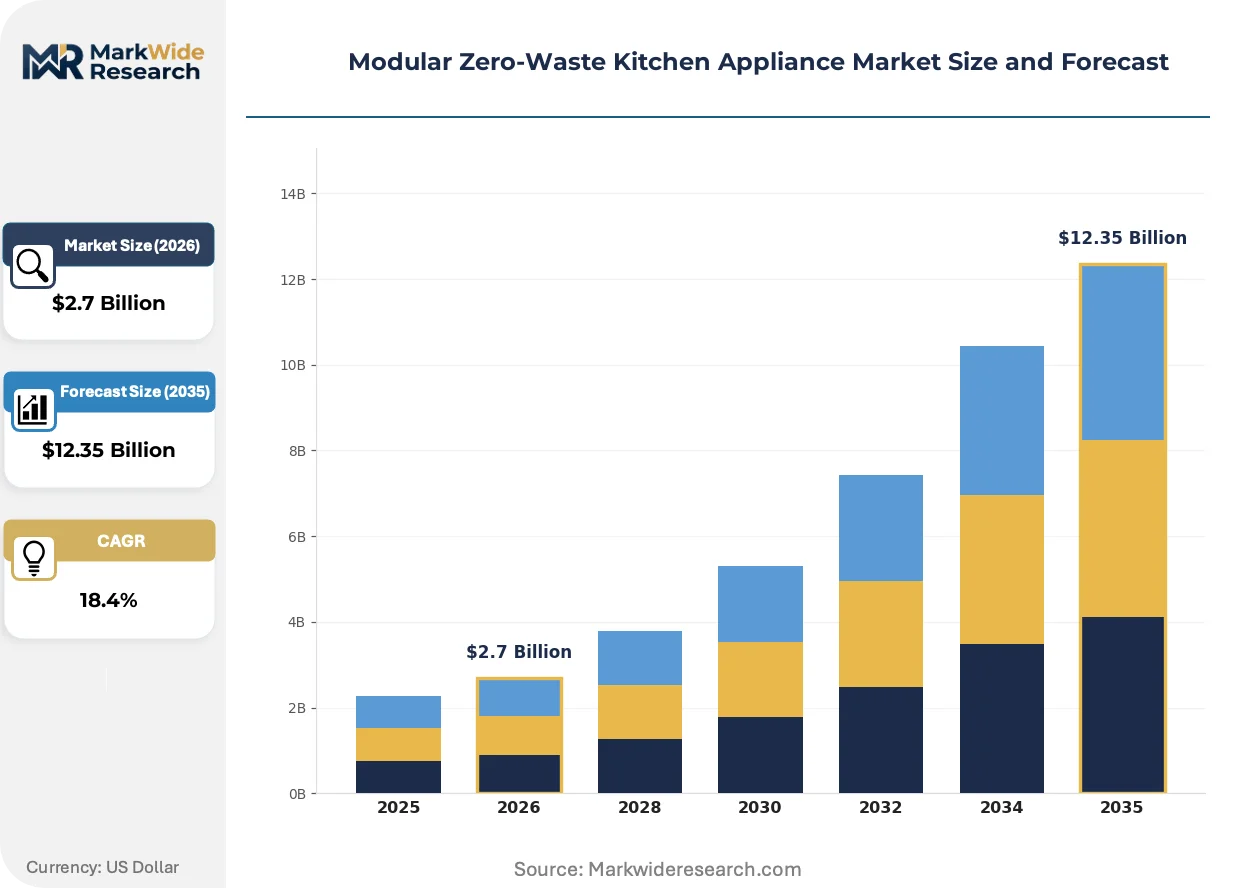
The Modular Zero-Waste Kitchen Appliance Market is experiencing structural pressure from municipal organic waste bans that mandate residential and commercial food scrap diversion, compelling appliance architecture to prioritize interchangeable composting modules over fixed-function units.
Growth Catalysts
- EU Green Deal Circular Economy Mandates:Germany's eco-friendly restaurants are expanding procurement of composting units to comply with binding food waste diversion targets, creating a concentrated demand cluster that validates premium module economics.
- China's Tier-One Municipal Policies:Beijing and Shanghai municipal zero-waste regulations are driving synchronized residential retrofit cycles, compressing replacement timelines for conventional kitchen systems.
- Recycled Stainless Steel Processing:Advanced metallurgical recovery techniques are broadening chassis material palettes, reducing virgin metal dependence while maintaining IPX4 wet-zone corrosion resistance standards.
Market Restraints
- GB Standards Compliance Burden:China's MIIT interoperability mandates for smart home device connectivity impose certification costs on modular protocol development, delaying product launches for non-domestic manufacturers.
- Neodymium Magnet Supply Concentration:Rare-earth element processing for high-efficiency motor modules concentrates in limited geographic clusters, exposing bill-of-materials volatility to geopolitical supply disruptions.
- Legacy Kitchen Footprint Rigidity:Existing residential cabinetry dimensions in mature housing stocks constrain standardized module interface adoption, forcing costly spatial reconfiguration for retrofit installations.
Strategic Opportunities
- Commercial Kitchen NSF Certification Premiums:Duty-cycle durability requirements in restaurant and hospitality segments command higher average selling prices, offering margin expansion beyond residential volume plays.
- IoT-Enabled Recurring Revenue Streams:Software-integrated preservation modules enable subscription-based energy optimization and predictive maintenance services, decoupling manufacturer economics from hardware-only transactions.
- Right-to-Repair Legislative Tailwinds:Emerging state-level repairability mandates in the US are creating regulatory arbitrage opportunities for brands with pre-positioned spare parts availability and modular sub-assembly architectures.
Industry Challenges
- Cross-Protocol Integration Complexity:MIIT GB standards, ENERGY STAR specifications, and emerging repairability scoring systems create fragmented certification timelines that extend product development cycles.
- Specialized Field Service Talent Scarcity:Modular appliance deployment requires technicians trained in both electrical systems and biological waste processing, a skill intersection with limited vocational pipeline capacity.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Zero-Waste Kitchen Appliance Market Trends and Innovations
Interconnected preservation and waste-processing modules are redefining kitchen system architecture, with software-defined functionality displacing fixed-purpose hardware across residential and commercial installations.
Biological processing sensors are integrating anaerobic digestion monitoring with automated aeration control, enabling real-time compost quality optimization. High-end residential developers in Shanghai and Shenzhen are specifying these modules in new construction at accelerating rates. The technology is integrating predictive maintenance algorithms that compress service intervention cycles from reactive breakdowns to preemptive component swaps.
REACH substance restrictions and RoHS hazardous material limits are tightening allowable chemical compositions in electronic control modules and heating elements. Manufacturers serving European markets must reformulate solder alloys and insulation materials to maintain CE marking compliance. Composting unit producers with integrated heating functions face the most acute reformulation timelines as legacy component stocks deplete.
Direct-to-developer specification channels are displacing traditional retail distribution for premium modular systems in China's tier-one cities. Kitchen designers and property developers now source integrated appliance packages through specialized B2B platforms that bundle installation and commissioning services. This pattern is most visible in Beijing's high-density residential towers, where municipal zero-waste compliance deadlines accelerate procurement centralization.
Modular Zero-Waste Kitchen Appliance Market Segmentation
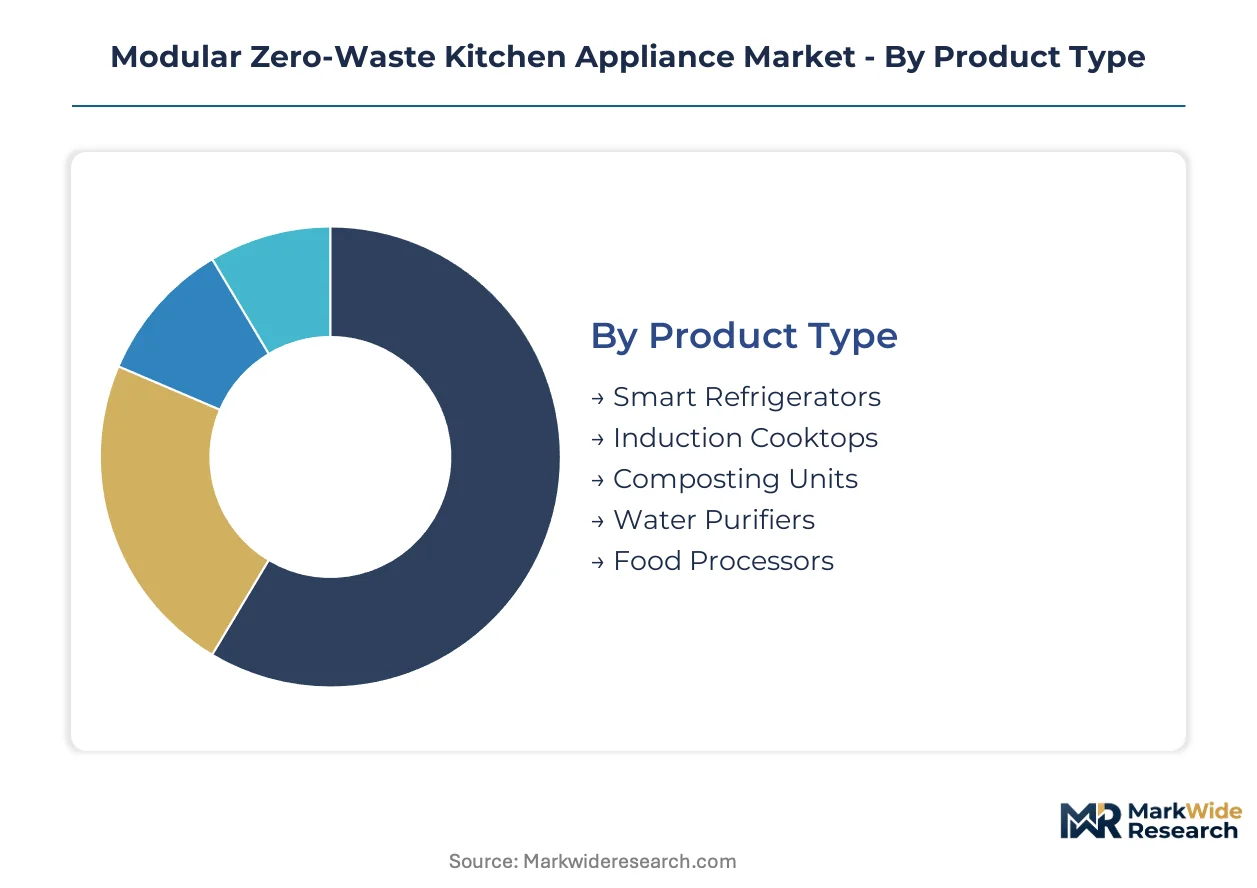
Modular zero-waste kitchen appliances segment across four critical dimensions that determine upgrade pathways and replacement economics. Interchangeable sub-assemblies create distinct lifecycle patterns across product types, technologies, applications, and end-user profiles. Understanding these segment boundaries enables precise positioning for both retrofit installations and new construction specifications.
Product Type:
Upgrade cycles vary dramatically by product type, with some modules requiring annual refresh while others sustain decade-long service intervals.
- Smart Refrigerators:Preservation modules with standardized 110-240V power interfaces and IPX4 wet-zone ratings anchor most residential installations. Demand clusters in China's tier-one cities where municipal zero-waste policies compress replacement timelines for conventional cooling systems.
- Composting Units:Biological processing modules integrate anaerobic digestion sensors with automated aeration control for real-time quality optimization. Germany's eco-friendly restaurants are expanding procurement under EU Green Deal circular economy mandates that mandate food scrap diversion.
- Induction Cooktops:Heating elements face acute reformulation pressure from REACH substance restrictions and RoHS hazardous material limits.
- Water Purifiers:Filtration modules with replaceable cartridge architectures reduce full-unit disposal frequency.
- Food Processors:Preparation units with interchangeable blade and vessel configurations support upgradeable motor sub-assemblies.
Smart Refrigerators sit at the top of the volume ranking, with Composting Units climbing the fastest.
Technology:
Cost tier stratification separates premium connected modules from baseline mechanical alternatives, with software-defined functionality commanding sustained margin premiums.
- IoT Integration:Networked modules enable subscription-based energy optimization and predictive maintenance services. Samsung Electronics leverages this technology to sustain recurring software revenue streams decoupled from hardware transactions.
- Sensor-Based Controls:Biological processing sensors monitor compost quality parameters and automate aeration adjustments. High-end residential developers in Shanghai and Shenzhen specify these modules in new construction at accelerating rates.
- Energy-Efficient Motors:High-efficiency designs depend on neodymium magnet supply chains concentrated in limited geographic clusters.
- Modular Design:Standardized connection interfaces enable sub-assembly replacement without full-unit disposal.
- Voice Activation:Hands-free control interfaces integrate with smart home ecosystems under China's MIIT interoperability mandates.
Sensor-Based Controls command the steepest expansion trajectory as real-time optimization becomes standard specification.
Application:
Customer type concentration shapes procurement channel selection, with direct-to-developer platforms displacing traditional retail for premium integrated systems.
- Home Kitchens:Residential installations dominate absolute unit volume but face margin pressure from legacy cabinetry footprint constraints. Beijing's high-density residential towers drive procurement centralization through specialized B2B platforms bundling installation and commissioning.
- Commercial Kitchens:Restaurant and hospitality segments command higher average selling prices due to duty-cycle durability requirements and NSF certification premiums. BSH Home Appliances Group anchors production from its European manufacturing footprint to serve this price tier.
- Eco-Friendly Restaurants:Sustainability-focused operators prioritize composting module integration under binding organic waste diversion mandates.
- Cafeterias:Institutional food service requires high-throughput configurations with extended service intervals.
- Food Trucks:Mobile applications demand compact form factors with dual-voltage compatibility for grid-independent operation.
Home Kitchens generate the largest installed base, while Commercial Kitchens capture the most favorable margin structure.
End User:
Maturity differentiation separates established food service chains with centralized procurement from fragmented household decision-making.
- Households:Residential purchasers respond to municipal zero-waste policy deadlines with synchronized retrofit cycles. Tier-one Chinese cities compress replacement timelines through regulatory enforcement rather than gradual preference shifts.
- Food Service Chains:Multi-unit operators leverage volume scale for standardized module specifications across property portfolios. These buyers prioritize spare parts availability windows mandated by emerging right-to-repair legislation.
- Culinary Professionals:Chef-driven specifications emphasize performance durability over connected feature sets.
- Sustainable Living Enthusiasts:Early adopter segment accepts premium pricing for advanced composting and preservation technologies.
- Small Cafes:Independent operators balance upgrade investment against constrained capital budgets.
Households represent the deepest volume pool, with Food Service Chains gaining share fastest through centralized procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one cities anchor demand concentration for modular zero-waste kitchen appliances, with municipal policy enforcement compressing replacement timelines across residential and commercial installations.
China
Beijing and Shanghai municipal zero-waste regulations drive synchronized residential retrofit cycles, compelling developers to specify integrated appliance packages. MIIT enforces GB standards for smart home device interoperability, creating compliance costs for modular connectivity protocols. High-end residential towers in Shenzhen specify composting modules with biological processing sensors at accelerating rates.
Germany
Eco-friendly restaurants expand procurement of composting units under binding EU Green Deal circular economy mandates. REACH substance restrictions and RoHS hazardous material limits tighten allowable chemical compositions in electronic control modules. Industrial clusters in Bavaria anchor premium composting unit production for European commercial kitchens.
United States
Emerging right-to-repair legislation in multiple states fragments certification requirements beyond federal ENERGY STAR baselines established by the EPA. Food service chains leverage volume scale for standardized module specifications across property portfolios. California's municipal organic waste bans compel residential and commercial food scrap diversion at scale.
Japan
METI efficiency standards and JIS interoperability frameworks shape product architecture decisions for connected preservation modules. Culinary professionals drive chef-driven specifications emphasizing performance durability over connected feature sets. The Kanto region around Tokyo concentrates demand for compact modular systems in high-density residential construction.
South Korea
MFDS certification requirements and METI-aligned efficiency benchmarks influence modular appliance development for export markets. The Seoul Capital Area generates concentrated demand from sustainable living enthusiasts accepting premium pricing for advanced composting technologies. Domestic manufacturers prioritize spare parts availability windows mandated by emerging repairability regulations.
Modular Zero-Waste Kitchen Appliance Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and software integration capabilities, producing a tiered structure where premium IoT-enabled modules command sustained margin premiums over baseline mechanical alternatives. Three strategic archetypes dominate: European manufacturing specialists leveraging circular economy regulatory alignment, Asian electronics conglomerates monetizing connected device ecosystems, and North American scale players optimizing assembly plant throughput. Competitive moves concentrate on strategic partnerships for protocol standardization and portfolio diversification into subscription-based energy optimization services.
Among the European manufacturing specialists, BSH Home Appliances Group exemplifies the premium-tier archetype through its continental production footprint. Samsung Electronics and LG Electronics represent the connected-ecosystem vector, anchoring the software-defined functionality segment where recurring revenue streams decouple manufacturer economics from hardware-only transactions. Whirlpool Corporation occupies the scale-driven position, competing on manufacturing throughput across North American assembly plants.
| Leading Market Players |
|---|
| BSH Home Appliances Group |
| Samsung Electronics |
| Whirlpool Corporation |
| Electrolux Group |
| Miele |
| Fisher & Paykel Appliances |
| InSinkErator |
| LG Electronics |
| Haier Smart Home |
| Others |
Pricing and Supply Chain Analysis
NSF certification premiums and EU repairability scoring create a bifurcated value architecture that manifests in both module pricing and supplier qualification requirements. Premium composting units with biological processing sensors command sustained margin multiples over baseline mechanical alternatives, while REACH-compliant component sourcing concentrates procurement relationships among qualified European and East Asian metallurgical suppliers.
Pricing Analysis
Neodymium magnet cost pass-through from concentrated rare-earth processing clusters in China exerts direct pressure on high-efficiency motor module pricing. Three-tier pricing structure across premium IoT-enabled, standard connected, and economy mechanical levels differentiates primarily by software integration depth and ENERGY STAR certification tier. Pricing pressure stems from GB standards compliance costs for MIIT interoperability mandates, compressing margins for non-domestic manufacturers entering Beijing and Shanghai procurement channels. Food service chains exhibit lowest price sensitivity due to duty-cycle durability requirements and centralized volume procurement, while independent small cafes face acute capital constraint sensitivity.
Supply Chain Analysis
CE marking and NSF certification gating concentrates qualified chassis manufacturing in Germany, China, and South Korea, with recycled stainless steel processing anchored in Bavarian and Guangdong industrial clusters. Critical component dependencies include neodymium magnets for motor efficiency, biological processing sensors for compost quality optimization, and RoHS-compliant solder alloys for control module assembly. Single-source vulnerability in rare-earth element processing exposes bill-of-materials volatility to geopolitical supply disruptions. Distribution runs through direct-to-developer B2B platforms in China's tier-one cities and traditional appliance retail channels in North American and European residential markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The modular zero-waste kitchen appliance market reads as a late-cycle quality story, with municipal organic waste bans and right-to-repair mandates shifting procurement specifications toward premium durability and upgradeable sub-assembly architectures.
For Market Incumbents: Deploy spare parts availability windows as a defensive moat against emerging right-to-repair legislative fragmentation across US states. Anchor capacity addition in European manufacturing footprints to capture EU Green Deal circular economy procurement premiums, while investing in backward integration into recycled stainless steel processing to offset virgin metal cost volatility from geopolitical supply disruptions. For New Entrants and Emerging Players: Independent eco-friendly restaurants in Germany represent an underserved buyer archetype with binding organic waste diversion mandates and limited incumbent relationship lock-in. Target commercial kitchen NSF certification premiums through specialized composting unit configurations, leveraging direct specification relationships with kitchen designers and property developers bypassing traditional retail channel barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale manufacturers possessing pre-qualified CE marking pathways and established MIIT GB standards compliance, positioned for accelerated consolidation as certification complexity rises. Long-term viability over a five-to-ten year window favors targets with captive biological processing sensor development capabilities and modular protocol interoperability. The signal to watch is municipal zero-waste policy enforcement velocity in China's tier-two cities as an inflection indicator for demand expansion beyond current tier-one concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | MIIT GB standards compliance enables interoperability certification for modular connectivity protocols across Beijing and Shanghai installations. |
| Backward Integration into Recycled Stainless Steel | Bavarian and Guangdong metallurgical clusters anchor chassis production with reduced virgin metal dependence and maintained IPX4 corrosion resistance. |
| Software-Defined Module Investment | Samsung Electronics leverages IoT integration to sustain recurring energy optimization subscription revenue decoupled from hardware transactions. |
| Geographic Manufacturing Footprint | BSH Home Appliances Group anchors European production to capture EU Green Deal circular economy mandates and REACH compliance premiums. |
| Repairability Infrastructure Partnership | Spare parts availability windows align with emerging US state-level right-to-repair legislation and EU repairability scoring requirements. |
Research Methodology
Multiple input streams — primary interviews with appliance engineering directors, municipal sustainability officers, and commercial kitchen procurement managers; secondary validation through EPA ENERGY STAR specifications, EU Green Deal circular economy action plan documentation, and China MIIT GB standards filings; plus customs trade data and SEC appliance manufacturer disclosures — were reconciled through bottom-up unit shipment modeling and top-down market sizing triangulation.
Historical shipment trajectories were cross-referenced against panel input from industry stakeholders to construct analytical frameworks across product type, technology tier, application segment, and end-user profile dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers and regulatory enforcement timelines. Industry-specific forecast inputs included municipal zero-waste policy implementation schedules and neodymium magnet supply chain concentration indices.
Underlying measurement precision varies by segment; Smart Refrigerator and Composting Unit categories carry tighter precision than emerging Food Processor module configurations due to established shipment reporting conventions. Forecasts reflect assumptions regarding regulatory enforcement continuity and rare-earth supply chain stability. A model refresh is warranted upon material change in EU Green Deal circular economy mandate binding strength or China municipal zero-waste policy expansion geography.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.