
 Stainless Steel Vacuum Flask Market | 2026-2036
Stainless Steel Vacuum Flask Market Size, Share, and Industry Trends Forecast 2026-2036
Stainless Steel Vacuum Flask Market Insights
ISO 9001 quality management certification is rotating as a baseline gating standard for OEM partnerships and private-label contracts in the stainless steel vacuum flask supply chain. Zojirushi leverages precision vacuum insulation engineering and domestic Japanese production to sustain premium positioning. Haers anchors high-volume manufacturing capacity through captive metal-forming operations in Zhejiang province. Tiger competes on thermal retention benchmarking and direct-to-retail channel control across Asian markets.
A stainless steel vacuum flask is a double-walled container fabricated from austenitic grades such as 304 or 316 stainless steel, with the interstitial air evacuated to create a vacuum barrier that suppresses conductive and convective heat transfer; the assembly typically incorporates copper or aluminum getter layers to maintain vacuum integrity over thousands of thermal cycles, serving the primary commercial purpose of temperature preservation for beverages in mobile and remote-use scenarios. Double-walled construction dominates value capture due to superior thermal performance and higher unit economics, while wide-mouth designs represent the fastest-growing product configuration as consumers prioritize cleaning accessibility and ice compatibility. Online retail channels are displacing traditional specialty store distribution for premium brands, though supermarkets retain volume leadership in private-label and mid-tier segments.
The US FDA regulates food-contact surface compliance under 21 CFR, while China's SAMR enforces GB 4806 series standards for stainless steel articles in contact with food; REACH restrictions in Europe limit certain alloying element compositions, collectively elevating material traceability and testing costs for cross-border suppliers. Stakeholders must monitor evolving chemical disclosure requirements and vacuum seal durability testing protocols as regulatory divergence between major economies intensifies compliance complexity.
Market Dynamics
Vacuum seal durability testing protocols are intensifying compliance complexity as regulatory divergence between the US, EU, and China forces manufacturers to maintain parallel certification tracks for food-contact stainless steel sourcing.
Growth Catalysts
- Outdoor recreation procurement:Corporate wellness programs and adventure tourism operators are expanding bulk purchasing of vacuum-insulated drinkware for field deployment.
- REACH chemical restrictions:The EU's tightening alloying element disclosure requirements are accelerating material traceability investments among premium suppliers seeking export eligibility.
- Wide-mouth configuration demand:Consumer preference for cleaning accessibility and ice compatibility is pulling product development toward accessible-opening designs.
Market Restraints
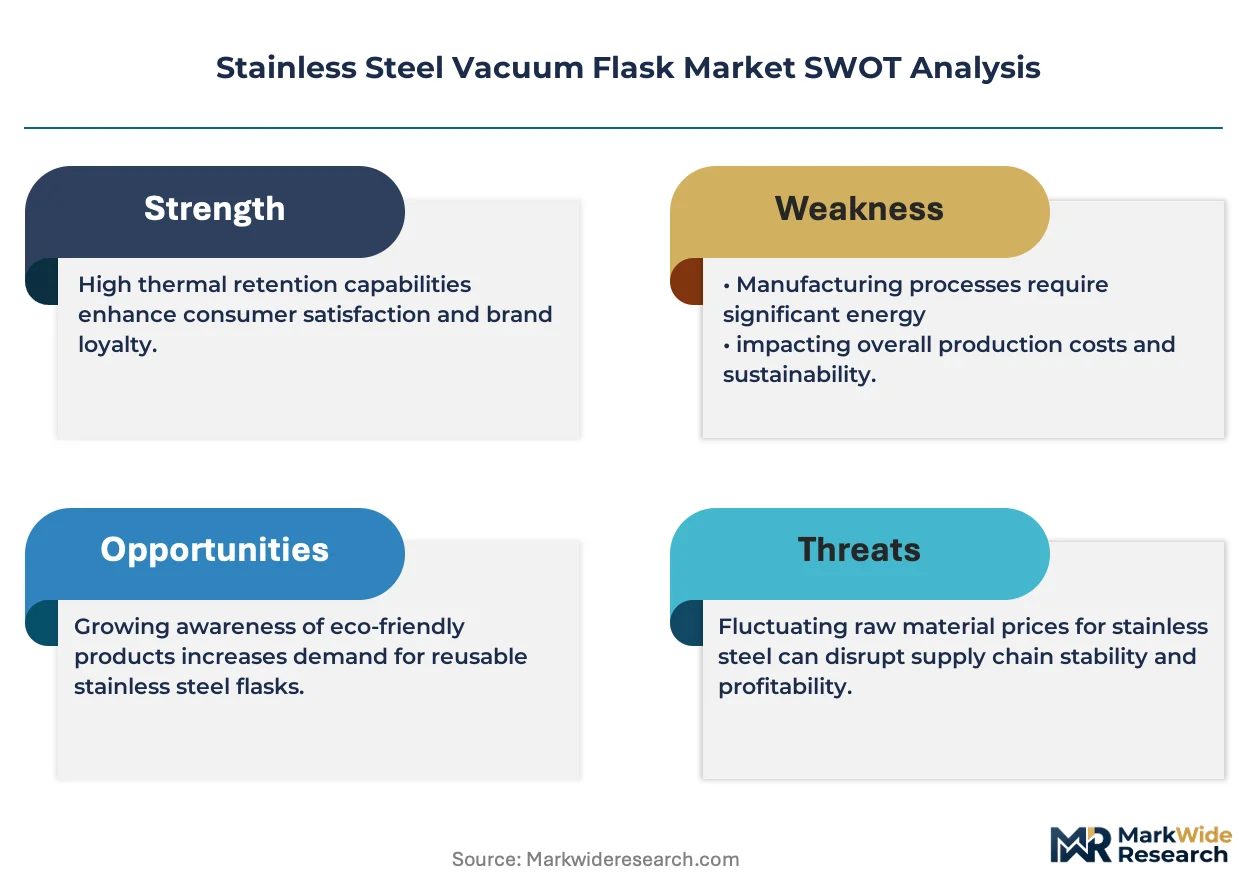
- Nickel price volatility:Austenitic 304 and 316 stainless steel grades face input cost pressure from London Metal Exchange nickel contract fluctuations.
- Zhejiang manufacturing concentration:Captive metal-forming operations cluster in East Asian production hubs, creating geographic supply vulnerability.
- Copper getter layer scarcity:Vacuum integrity maintenance depends on specialized copper or aluminum getter materials with constrained supplier bases.
Strategic Opportunities
- Direct-to-retail channel expansion:Premium brands are bypassing traditional specialty store distribution through owned e-commerce platforms.
- SAMR GB 4806 alignment:China's food-contact material standards create compliance moats for early-adopting exporters to domestic Chinese retail.
- Corporate gifting vertical:Branded vacuum flask procurement for employee wellness and client retention programs remains underpenetrated in mid-market enterprises.
Industry Challenges
- Vacuum seal technician scarcity:Precision evacuation and getter-layer installation require specialized labor pools concentrated in Japanese and German manufacturing regions.
- Dual certification timeline compression:Simultaneous FDA 21 CFR and GB 4806 testing protocols extend product launch cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stainless Steel Vacuum Flask Market |
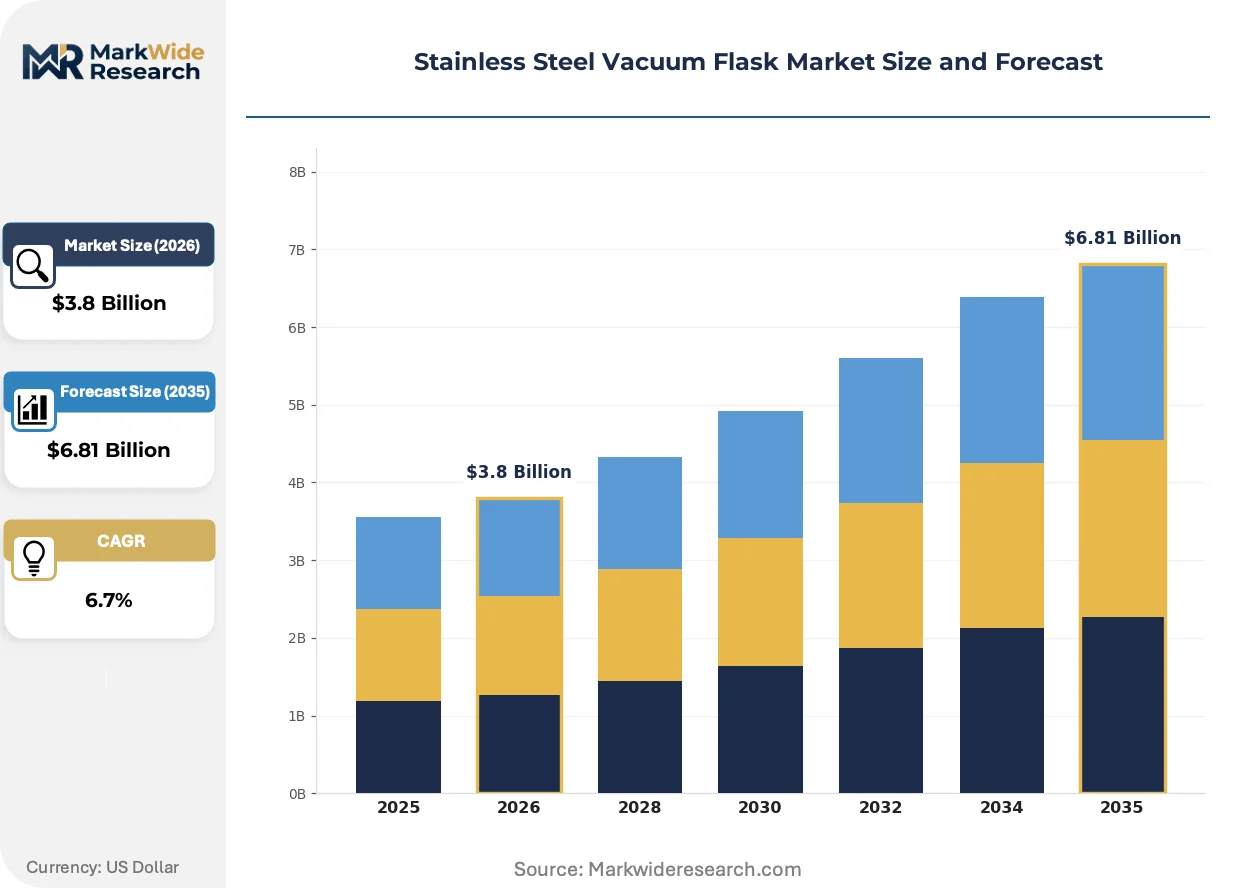
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated, Double-Walled, Single-Walled, Wide Mouth Application: Travel, Outdoor Activities, Home Use, Work Volume Capacity: 350 ml, 500 ml, 750 ml, 1 L Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Thermos, Zojirushi, Tiger, Haers, Nanlong, Hydro Flask, Klean Kanteen, Shine Time, Fuguang, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stainless Steel Vacuum Flask Market Trends and Innovations
Product engineering and regulatory disclosure requirements are compressing development cycles while reshaping competitive differentiation around thermal performance benchmarking and material provenance transparency.
Copper-coated vacuum barrier technology is miniaturizing. Thin-film getter deposition systems now enable sub-millimeter vacuum gaps in compact flask geometries. Urban commuters and ultralight backpackers are adopting these reduced-form-factor designs at accelerating rates. This miniaturization is compressing the addressable market gap between traditional vacuum flasks and insulated tumblers.
China's SAMR enforcement of GB 4806 series standards for stainless steel food-contact articles is tightening. Manufacturers must now submit batch-level material composition certificates for import clearance. Export-oriented suppliers in Zhejiang and Guangdong provinces are most affected, with many establishing in-house testing laboratories to reduce third-party certification delays.
Online retail channels are displacing specialty store distribution for premium vacuum flask brands. Direct-to-consumer platforms now capture thermal retention benchmarking data that previously required retail floor demonstrations. North American and Japanese markets exhibit the most pronounced channel migration, with subscription-based replacement programs emerging as a retention mechanism.
Stainless Steel Vacuum Flask Market Segmentation
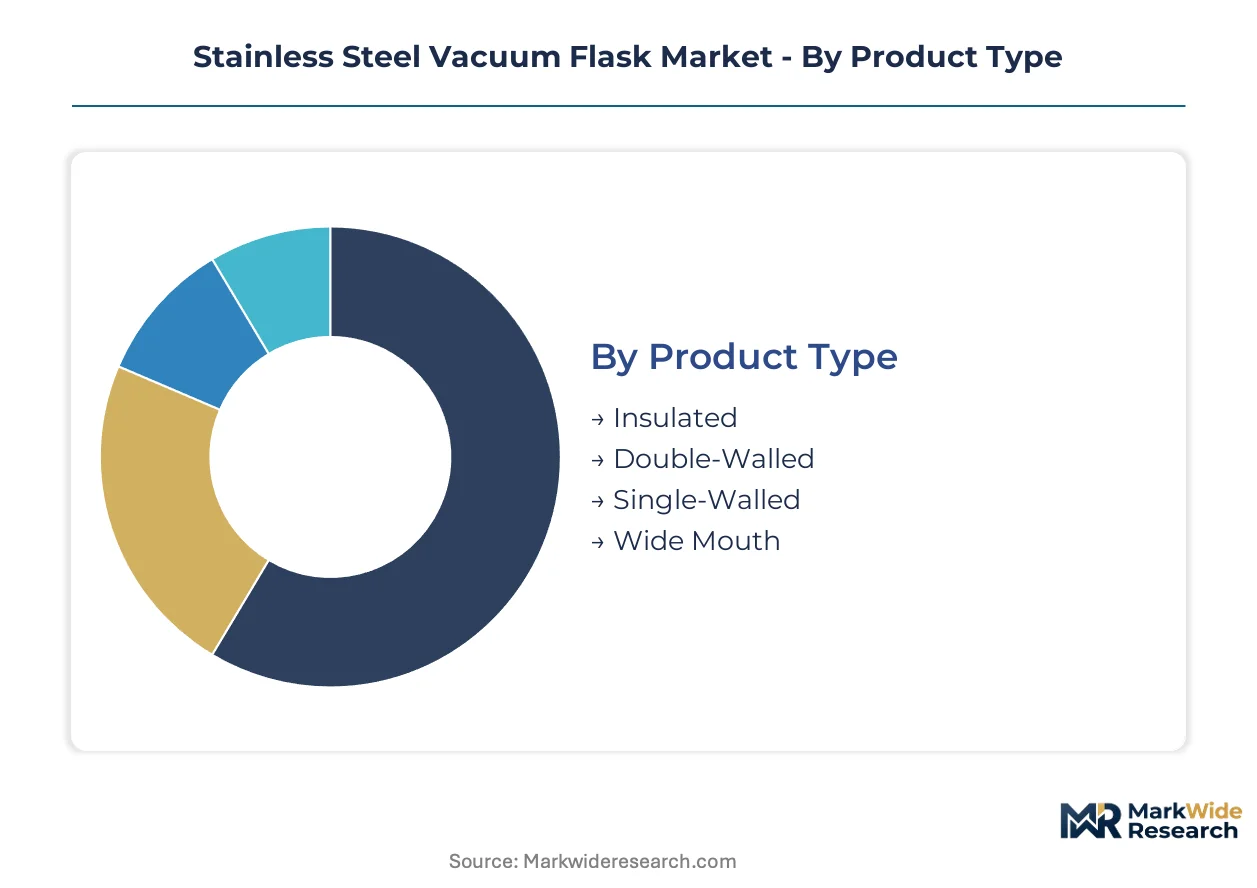
Vacuum flask segmentation reveals how thermal performance specifications, use-case mobility requirements, and channel economics fragment purchasing behavior. Manufacturers configure product lines across insulation architecture, capacity tiers, and retail formats to capture divergent willingness-to-pay.
Product Type:
Margin pools concentrate in vacuum-insulated architectures where copper getter layers and precision evacuation protocols justify premium positioning.
- Double-Walled:Austenitic 304 or 316 stainless steel shells enclose sub-millimeter vacuum gaps with copper or aluminum getter deposition. Corporate wellness programs and adventure tourism operators in the United States and Japan drive bulk procurement of these high-retention units.
- Wide Mouth:Expanded aperture diameters accommodate ice loading and mechanical brush access for sanitation compliance. Urban commuters across Chinese metropolitan clusters are adopting these configurations fastest as cleaning accessibility displaces pure thermal metrics in purchase decisions.
- Insulated:Foam-filled or air-gap barriers without vacuum evacuation serve price-sensitive segments.
- Single-Walled:Uninsulated shells function as lightweight water vessels for immediate consumption.
Double-walled holds installed capacity. Wide mouth is rotating up the share rankings.
Application:
Volume concentration tracks mobility intensity, with field-deployment scenarios commanding higher per-unit investment than stationary use.
- Outdoor Activities:Backpacking, camping, and expedition use cases demand sub-zero thermal retention and impact resistance. Procurement from North American outdoor retailers and Japanese specialty channels sustains premium pricing for vacuum-insulated architectures.
- Travel:Airport and commuter transit environments favor compact 350-500 ml geometries with leak-proof sealing. Chinese high-speed rail passengers and European intercity commuters represent concentrated demand pockets for these portable formats.
- Home Use:Kitchen countertop and bedside hydration prioritizes capacity over portability.
- Work:Office desk and construction site deployment spans thermal retention requirements.
Outdoor activities holds installed capacity. Travel is climbing the fastest among application segments.
Volume Capacity:
Customer type stratification across individual, household, and institutional buyers maps directly to milliliter tier selection.
- 500 ml:Mid-range capacity balances portability with sufficient hydration for half-day excursions. Individual consumers in Japanese and South Korean urban markets treat this tier as the default single-user specification.
- 750 ml:Extended-duration capacity serves day-hikers and corporate field staff with limited refill access. German and Austrian outdoor retailers report strongest relative demand for this intermediate format.
- 350 ml:Pocket-sized geometry targets minimalist commuters and children's lunchbox integration.
- 1 L:Family and group-sharing capacity dominates car camping and base camp scenarios.
500 ml holds installed capacity. 750 ml is gaining share fastest as day-trip duration extends.
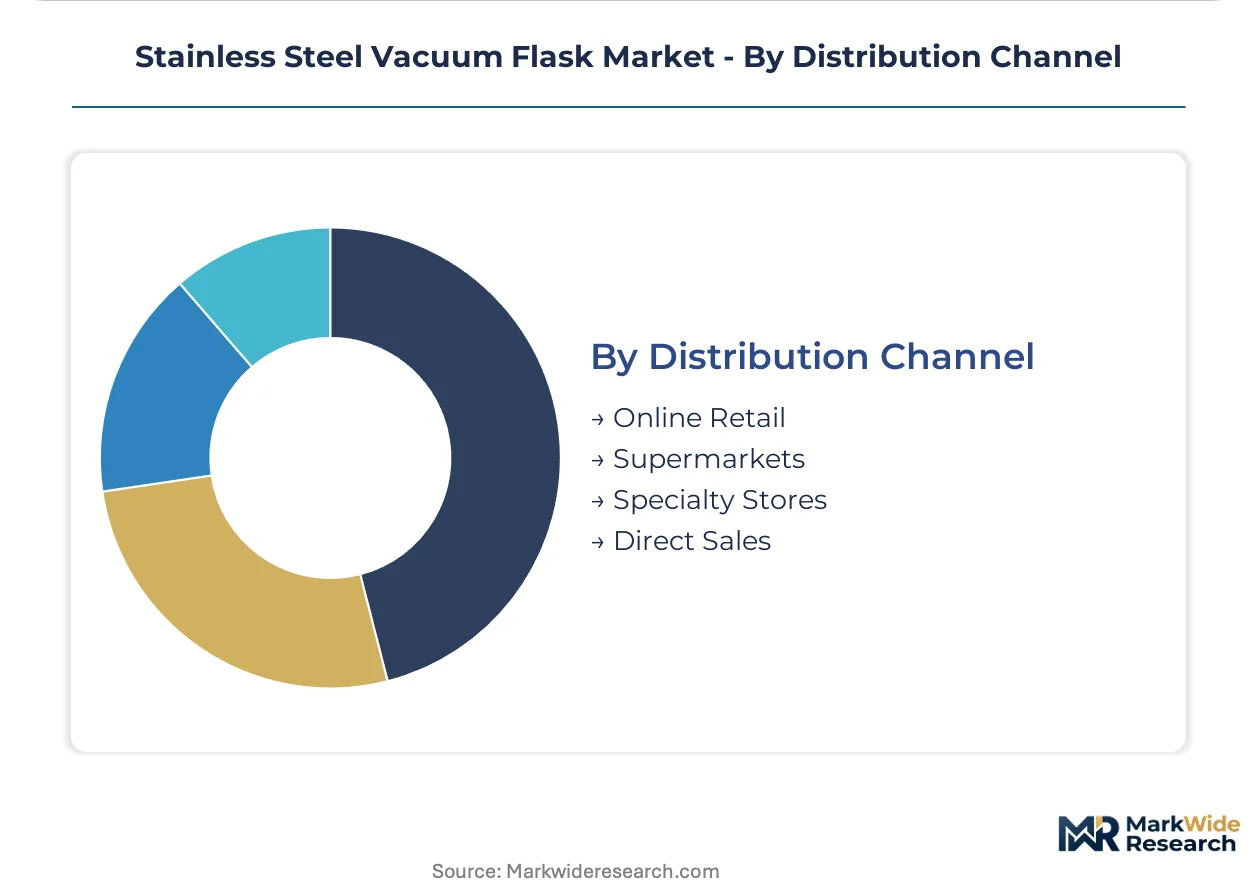
Distribution Channel:
Channel economics diverge sharply between inventory-heavy retail and direct-to-consumer platforms with thermal performance data transparency.
- Online Retail:E-commerce platforms capture thermal retention benchmarking data previously requiring physical demonstration. North American premium brands and Japanese manufacturers deploy subscription replacement programs through owned digital channels.
- Supermarkets:High-velocity private-label and mid-tier volume moves through mass retail with limited specification disclosure. Chinese domestic chains and European hypermarket operators dominate this channel's transaction density.
- Specialty Stores:Curated outdoor and housewares retail retains importance for hands-on vacuum seal quality assessment.
- Direct Sales:Corporate gifting and institutional procurement bypass retail markup through manufacturer relationships.
Supermarkets holds installed capacity. Online retail is expanding most quickly as demonstration data migrates digital.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate wellness buyers concentrate procurement in the United States and Japan, while Chinese manufacturing clusters supply global volume through Zhejiang and Guangdong province operations.
United States
Adventure tourism operators and outdoor retailers drive premium vacuum flask procurement for field deployment. The FDA enforces 21 CFR compliance for food-contact stainless steel surfaces, elevating testing costs for import suppliers. Manufacturing concentrates in Pacific Northwest design studios and Southeast distribution hubs serving corporate gifting verticals.
China
Domestic high-speed rail commuters and urban professionals fuel demand for compact 350-500 ml travel formats. SAMR's GB 4806 series standards now require batch-level material composition certificates for food-contact articles. Zhejiang province hosts captive metal-forming operations and precision evacuation facilities serving export markets.
Japan
Precision-oriented consumers prioritize thermal retention benchmarking and domestic production provenance. METI oversees JIS standards alignment for vacuum insulation performance claims. Kansai and Chubu manufacturing regions maintain specialized technician pools for getter-layer installation and vacuum seal protocols.
Germany
Outdoor retailers and day-hiking enthusiasts favor 750 ml intermediate capacity specifications. REACH chemical restrictions limit certain alloying element compositions in stainless steel sourcing. Bavarian and Baden-Württemberg industrial clusters specialize in thin-film getter deposition systems for compact flask geometries.
South Korea
Urban commuters treat 500 ml capacity as the default single-user specification for workplace hydration. MFDS regulates food-contact material safety for domestic retail distribution. Seoul Capital Area design houses collaborate with Zhejiang manufacturers on wide-mouth configuration development.
Stainless Steel Vacuum Flask Market Competitive Landscape
Player mix skews toward precision-engineering specialists and high-volume fabricators competing across divergent capability requirements. Market structure exhibits tiered consolidation with premium Japanese manufacturers, Chinese scale producers, and North American brand marketers occupying distinct competitive spaces. Three archetypes dominate: domestic precision specialists leveraging vacuum insulation engineering, East Asian volume manufacturers with captive metal-forming operations, and brand marketers controlling direct-to-retail channel access. Competitive moves center on ISO 9001 certification acquisition for OEM partnerships and e-commerce platform expansion bypassing traditional specialty retail.
Among precision-engineering specialists, Zojirushi and Tiger represent the premium-tier archetype through domestic Japanese production positioning. Haers anchors the high-volume manufacturing archetype through Zhejiang-based metal-forming integration. Thermos occupies a position spanning both precision and brand marketing vectors through multi-regional channel presence. These three exemplify how geographic production location and channel control strategy separate competitive positions in vacuum flask supply.
| Leading Market Players |
|---|
| Thermos |
| Zojirushi |
| Tiger |
| Haers |
| Nanlong |
| Hydro Flask |
| Klean Kanteen |
| Shine Time |
| Fuguang |
| Others |
Pricing and Supply Chain Analysis
Ninety-day nickel inventory cycles on the London Metal Exchange connect Zhejiang manufacturing concentration to premium-tier pricing power, while wide-mouth configuration demand pulls cost structures toward specialized tooling investments. Contract manufacturers serving North American corporate gifting verticals absorb margin compression from parallel FDA 21 CFR and SAMR GB 4806 certification tracks.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange nickel futures dominate raw material procurement for austenitic 304 and 316 grades. Pricing stratifies across premium, standard, and economy tiers based on vacuum retention certification tier and domestic Japanese production provenance. Cost compression in mid-tier private-label segments is intensifying because supermarket buyers consolidate volume through annual bidding programs. Corporate wellness procurement teams exhibit lowest price sensitivity; Chinese domestic e-commerce consumers drive hardest bargain hunting.
Supply Chain Analysis
China and Japan anchor global vacuum flask fabrication, with Zhejiang province hosting captive metal-forming operations and Kansai region maintaining specialized getter-layer installation technician pools. Supply chains draw from nickel ore processing in Indonesia, copper getter deposition materials from German thin-film specialists, and precision evacuation equipment from Japanese industrial gas suppliers. Single-source vulnerability concentrates in vacuum seal technician labor pools concentrated in Chubu manufacturing regions. Distribution runs through East Asian export hubs to North American direct-to-consumer platforms and European specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized vacuum seal technician pools and precision evacuation equipment access constrain capacity expansion more than capital availability, creating durable moats for incumbents with established Japanese or German manufacturing footprints.
For Market Incumbents: Fortify domestic production positioning through METI JIS standards alignment and precision thermal retention benchmarking protocols. Deepen backward integration into copper getter layer supply through Bavarian thin-film deposition partnerships. ISO 9001 certification maintenance defends OEM partnership eligibility against emerging Zhejiang volume competitors. For New Entrants and Emerging Players: Differentiate on wide-mouth configuration engineering for Chinese urban commuter segments where cleaning accessibility displaces pure thermal metrics. Target South Korean 500 ml default specification markets through Seoul Capital Area design house collaborations. Pursue direct-to-retail channel buildout with thermal performance data transparency as primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified housewares conglomerates with underutilized precision evacuation capabilities and dormant ISO 9001 certifications. Long-term viability hinges on regulatory compliance infrastructure amortization across multi-jurisdiction certification tracks. Watch SAMR GB 4806 enforcement intensity as inflection indicator for export-oriented supplier margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Bypasses specialty retail markup while capturing thermal retention data previously requiring floor demonstration. |
| Backward Integration into Getter Materials | Secures copper and aluminum deposition supply from constrained German and Japanese supplier bases. |
| Dual Certification Investment | Accelerates FDA 21 CFR and SAMR GB 4806 parallel approval timelines for export market eligibility. |
| Wide-Mouth Product Line Extension | Captures Chinese metropolitan commuter preference shift toward cleaning accessibility and ice compatibility. |
| Corporate Gifting Vertical Development | Penetrates underexploited mid-market enterprise employee wellness and client retention procurement budgets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with vacuum flask manufacturing executives, precision evacuation equipment suppliers, and corporate procurement managers at outdoor recreation operators; and secondary validation through customs trade records, SAMR GB 4806 compliance filings, and retail channel thermal performance benchmarking disclosures. Bottom-up capacity estimates from Zhejiang and Guangdong province manufacturing clusters triangulated against top-down demand segmentation across North American, Japanese, and Chinese consumer archetypes.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product architecture, capacity tier, application intensity, and distribution channel format. CAGRs derived from historical shipment correlations with nickel price cycles, outdoor recreation participation rates, and corporate wellness program adoption curves. Industry-specific inputs included vacuum seal durability testing protocol evolution and REACH chemical restriction amendment tracking.
Decision-makers should treat outputs as directional under stable nickel price band assumptions and sustained SAMR enforcement intensity; material deviation in either would warrant model refresh. Recalibration cycles align with shifts in regulatory divergence patterns between FDA, ECHA, and SAMR jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Sanitary Napkin Receptacles Market
Household Items
Party Balloon Market
Household Items
Portable Showers Market
Household Items
Leaf Blower Market
Household Items
Plastic Bathtub Market
Household Items
Home Use Air Purifiers Market
Household Items
Sleeping Pods Market
Household Items
Air Mattress Market
Household Items
Kuwait Gas Hobs Market
Household Items
North America Ceramic Barbeque Grill Market
Household Items
North America Robotic Pool Cleaner Market
Household Items
Sanitary Napkin Vending Machine Market
Household Items
Europe & UK Nonstick Cookware Market
Household Items
Innerspring Mattresses Market
Household Items
Toilet Rim Blocks Market
Household Items
HEPA Vacuum Cleaners Market