
 Asia-Pacific Electric Rice Cooker Market | 2026-2036
Asia-Pacific Electric Rice Cooker Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electric Rice Cooker Market Outlook
A capital-intensity divergence between high-end induction heating specialists and mass-market conventional producers is redrawing competitive boundaries in the Asia-Pacific electric rice cooker landscape. Panasonic Corporation leverages deep vertical integration in Japanese manufacturing to sustain premium positioning across induction heating lines. Midea Group anchors volume throughput in China through massive domestic production scale and channel control. Cuckoo Electronics specializes in pressure-cooking technology for Korean consumer preferences, while TTK Prestige Limited dominates South India's brand-conscious residential segment.
An electric rice cooker is an automated countertop appliance that uses thermostatic control, resistive heating elements or magnetic induction coils, and microcomputer logic to heat water to boiling, absorb it into starch granules, and transition to a holding temperature without manual intervention. Micom rice cookers with fuzzy logic processors currently occupy the largest installed base across Asia-Pacific households due to accessible price points and programmable versatility. Induction heating rice cookers command concentrated margin pools in Japan and South Korea where consumers prioritize thermal precision and uniform grain texture. Pressure rice cookers represent the fastest-growing product category as time-constrained urban buyers seek accelerated cooking cycles without quality sacrifice.
China's SAMR enforces GB standards for energy efficiency and electrical safety that manufacturers must satisfy for domestic market access, while India's BIS certification mandates product testing before commercialization. Japan's METI promotes standby power regulations that push incumbents toward lower-wattage designs. Stakeholders must monitor how divergent national efficiency regimes reshape component sourcing and whether harmonization pressures emerge across ASEAN trade frameworks.
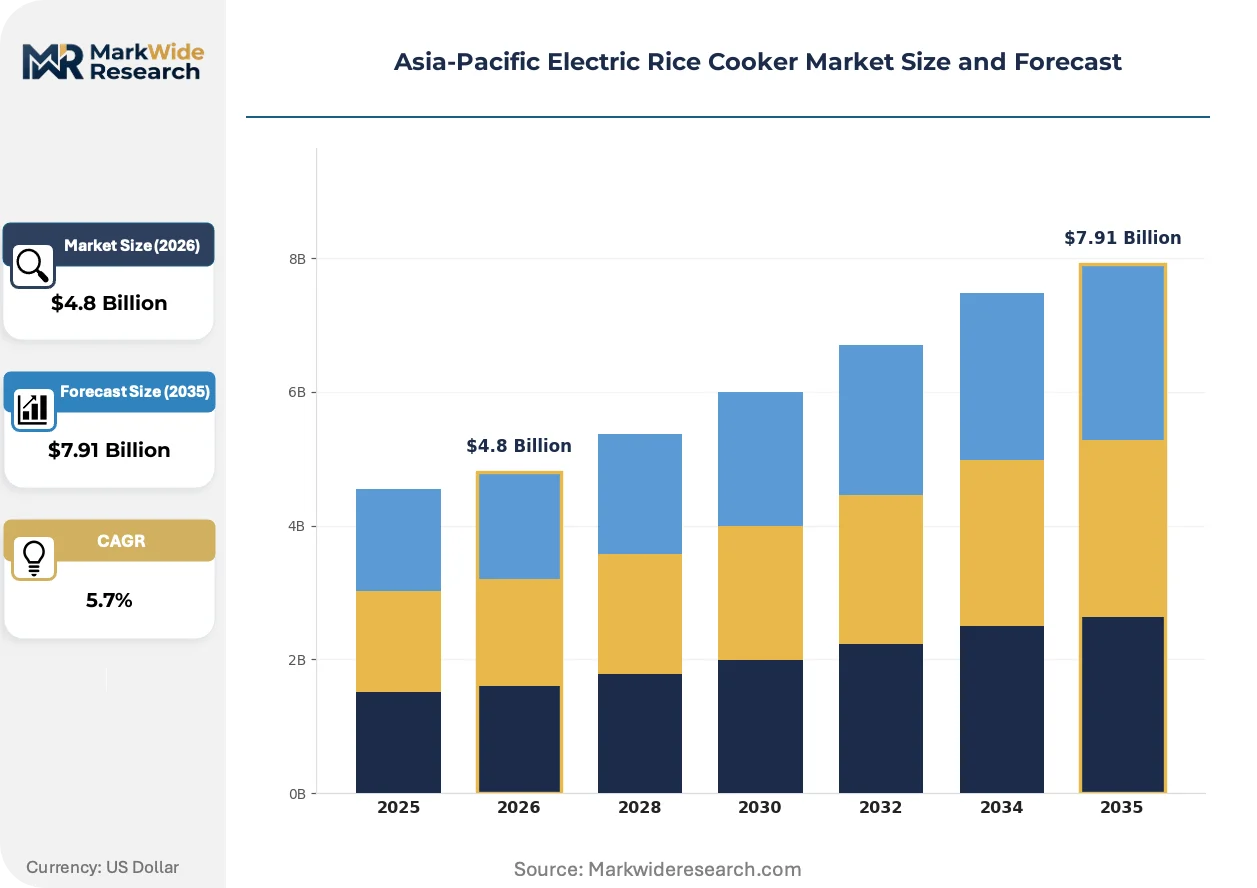
Market Dynamics
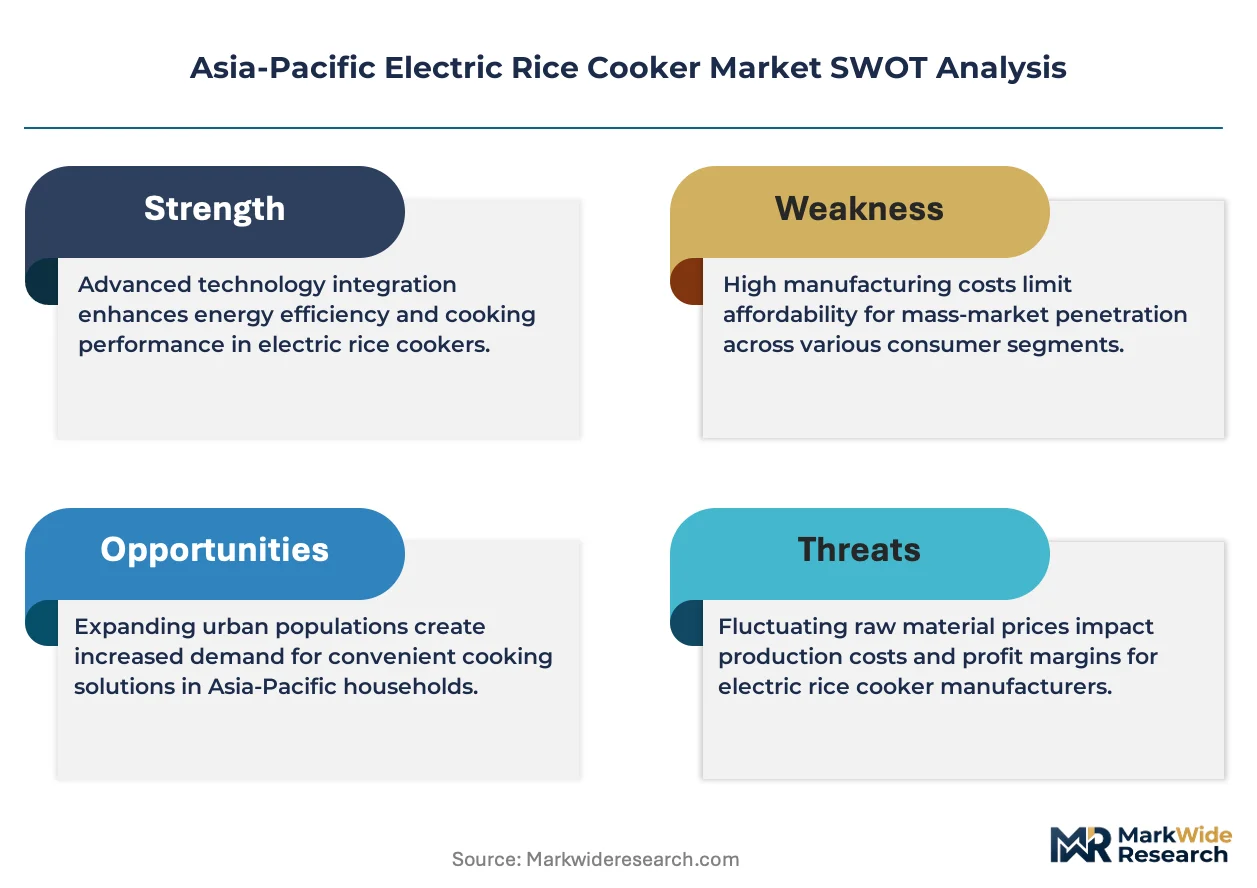
Induction heating technology is redrawing competitive boundaries across Asia-Pacific electric rice cooker manufacturing, forcing mass-market producers to upgrade thermal engineering capabilities or retreat to commoditized conventional segments. China's GB standards for energy efficiency and electrical safety are simultaneously raising compliance costs and accelerating consolidation among smaller domestic assemblers.
Growth Catalysts
- India's rural electrification:Government grid expansion programs are connecting millions of previously off-grid households to stable power supplies, creating first-time appliance demand in Bihar, Uttar Pradesh, and Odisha.
- Pressure-cooking technology:Accelerated cooking cycles address time scarcity among dual-income urban households in Seoul, Tokyo, and Singapore without sacrificing rice texture quality.
- METI standby power regulations:Japan's efficiency mandates are pushing manufacturers toward sub-one-watt idle consumption designs that command premium positioning in energy-conscious segments.
Market Restraints
- IGBT module supply concentration:Induction heating rice cookers depend on insulated-gate bipolar transistor components sourced primarily from Japanese and German semiconductor foundries, creating input cost volatility and allocation risk.
- BIS certification timelines:India's mandatory product testing and factory inspection protocols extend commercialization lead times by 4-6 months for new market entrants.
- Conventional gas stovetops:LPG infrastructure in rural Vietnam, Indonesia, and the Philippines sustains a low-cost cooking alternative that limits electric appliance penetration in price-sensitive segments.
Strategic Opportunities
- Vietnam's urban middle-class expansion:Ho Chi Minh City and Hanoi residential construction is outpacing regional peers, creating concentrated demand for compact, multi-function rice cookers in high-rise kitchens.
- Voice-activated smart connectivity:Integration with Tmall Genie, Baidu DuerOS, and Kakao i platforms enables remote cooking initiation and recipe customization for tech-forward Chinese and Korean consumers.
- India's PLI scheme for white goods:Production-linked incentives are attracting component localization investments that reduce landed costs for domestic manufacturers serving price-elastic South Indian markets.
Industry Challenges
- Thermal engineering talent scarcity:Fuzzy logic algorithm development and induction coil design require specialized firmware and magnetics expertise that concentrates in Osaka, Shenzhen, and Seoul industrial clusters.
- Multi-regional certification burden:Simultaneous compliance with China's GB standards, India's BIS requirements, Japan's JIS specifications, and South Korea's KC marking fragments product development resources and extends validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electric Rice Cooker Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micom Rice Cooker, Induction Heating Rice Cooker, Conventional Rice Cooker, Pressure Rice Cooker End User: Residential, Commercial, Hospitality, Institutions Capacity: 1-2 Cups, 2-4 Cups, 4-6 Cups, 6-10 Cups Features: Multi-Cooking Function, Delay Timer, Keep Warm Function, Non-Stick Interior |
| Companies Covered | Panasonic Corporation, Toshiba Corporation, Midea Group Co., Ltd., Zojirushi Corporation, Tiger Corporation, Cuckoo Electronics Co., Ltd., TTK Prestige Limited, Groupe SEB, Koninklijke Philips N.V., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electric Rice Cooker Market Strategic Shifts
Digital control architectures are displacing analog thermostatic systems across Asia-Pacific rice cooker production, enabling programmable cooking curves and connectivity features that redefine user interaction. This shift is compressing development cycles and forcing component supplier relationships to evolve.
Multi-layer ceramic coating technology is decomposing the traditional non-stick fluoropolymer supply chain in premium rice cooker manufacturing. Japanese and Korean brands are adopting diamond-particle-infused ceramic interiors for scratch resistance and thermal conductivity. Urban households in Tokyo and Seoul are paying 40-60% price premiums for these finishes. The technology is decomposing incumbent coating chemical suppliers' market position and forcing reformulation partnerships with advanced materials specialists.
China's SAMR enforcement of revised GB 4706 household appliance safety standards is mandating enhanced ingress protection and thermal runaway prevention in all domestic-market rice cookers. Manufacturers must redesign control boards and heating element housings to satisfy updated dielectric strength and flame-retardancy tests. Mass-market producers in Guangdong and Zhejiang are consolidating testing laboratory relationships to accelerate compliance documentation.
Direct-to-consumer channel expansion is disrupting traditional appliance retail dependence across Southeast Asia. Tmall, JD.com, and Shopee platform storefronts now capture significant transaction volume for mid-tier and premium rice cooker models. Younger buyers in Bangkok, Jakarta, and Manila prioritize user review aggregation and video demonstration content over physical retail inspection. Brand marketing budgets are reallocating toward influencer partnerships and live-streaming commerce events.
Asia-Pacific Electric Rice Cooker Market Segmentation
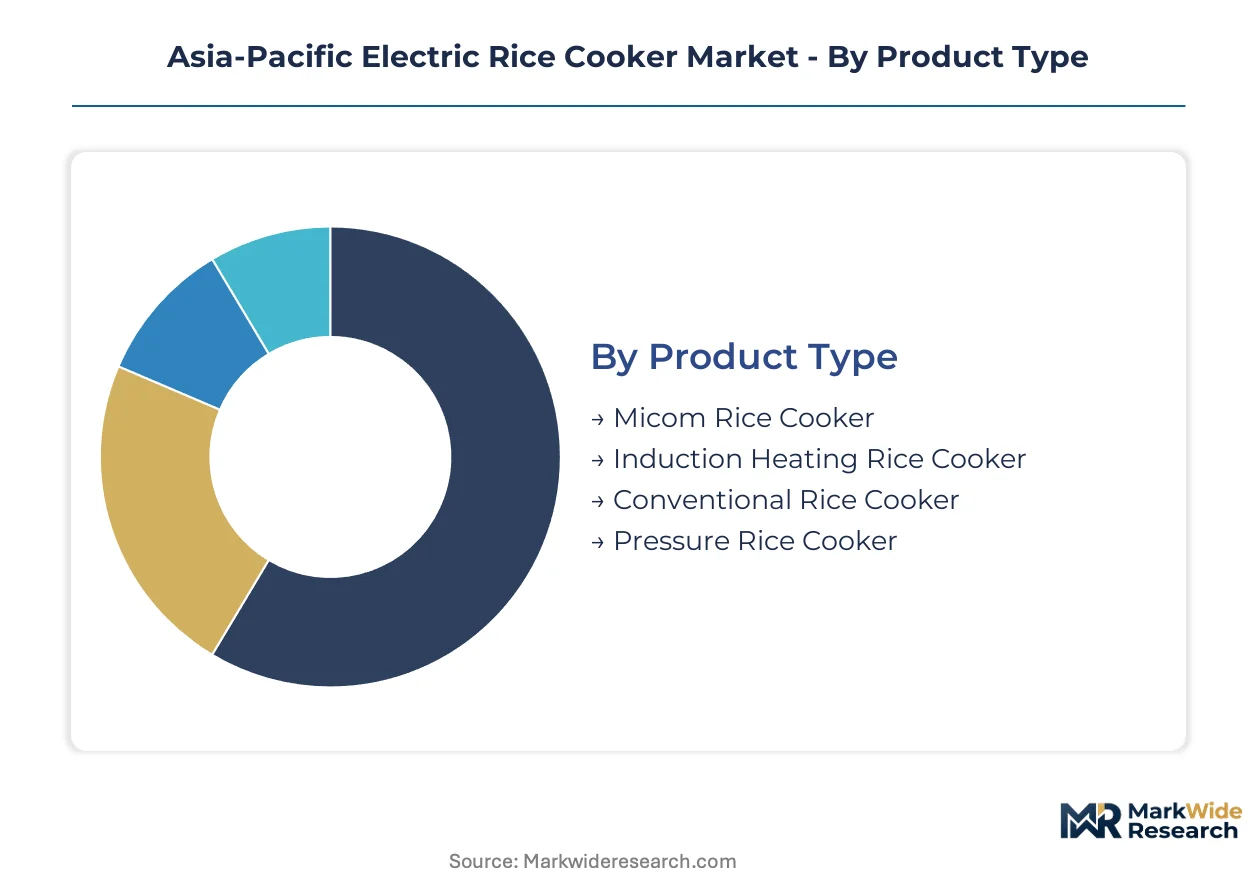
Segmentation reveals how technology tiers, user contexts, and capacity bands fragment demand across the Asia-Pacific electric rice cooker market. Manufacturers must align thermal engineering capabilities and channel strategies to specific buyer profiles rather than pursuing undifferentiated volume.
Product Type:
Domestic manufacturing clusters in Osaka, Shenzhen, and Seoul anchor production for each technology tier, with export intensity varying by thermal complexity.
- Micom Rice Cooker:Fuzzy logic microprocessors automate temperature modulation through resistive heating elements. Demand concentrates across mass-market households in Jakarta, Bangkok, and Manila where programmable versatility at accessible price points drives replacement cycles.
- Induction Heating Rice Cooker:Magnetic induction coils generate eddy currents for precise thermal distribution without direct element contact. Premium positioning dominates in Tokyo and Seoul where consumers prioritize uniform grain texture and energy efficiency metrics.
- Conventional Rice Cooker:Simple thermostatic switching between heating and warming states serves price-elastic rural markets in Vietnam and the Philippines.
- Pressure Rice Cooker:Sealed vessels accelerate starch gelatinization through elevated boiling points. Dual-income households in Singapore and Hong Kong prioritize cooking speed without quality degradation.
Micom units command the established base across Asia-Pacific households. The steepest expansion runs through pressure-cooking configurations as urban time scarcity intensifies.
End User:
Application context determines durability specifications, batch capacity requirements, and after-service infrastructure investment.
- Residential:Individual household units dominate transaction volume across all technology tiers, with brand loyalty strongest in South India and South Korea.
- Commercial:High-cycle durability demands from restaurant chains in Ho Chi Minh City and Kuala Lumpur favor stainless-steel construction and extended warranty terms.
- Hospitality:Hotel breakfast buffet operations in Bangkok and Sydney require 6-10 cup capacities with rapid recovery between service waves.
- Institutions:School and hospital canteens in Delhi and Mumbai prioritize BIS-certified safety ratings and simplified operator interfaces for non-technical staff.
Residential applications anchor manufacturer revenue stability. Hospitality procurement is climbing fastest as tourism infrastructure expands across Southeast Asia.
Capacity:
Household size distribution and kitchen footprint constraints shape regional preference patterns for vessel volume.
- 1-2 Cups:Compact footprints serve single-person households and studio apartments in Tokyo and Seoul where counter space commands premium valuations.
- 2-4 Cups:Standard nuclear family sizing dominates new household formation in Hanoi and Manila residential construction.
- 4-6 Cups:Extended family configurations and meal-preparation habits in Chennai and Hyderabad sustain demand for mid-scale batch cooking.
- 6-10 Cups:Large-format units address multi-generational households in rural Indonesia and commercial food service requirements.
The 2-4 cup segment holds the largest installed base. Single-person urbanization is pushing 1-2 cup configurations up the growth curve.
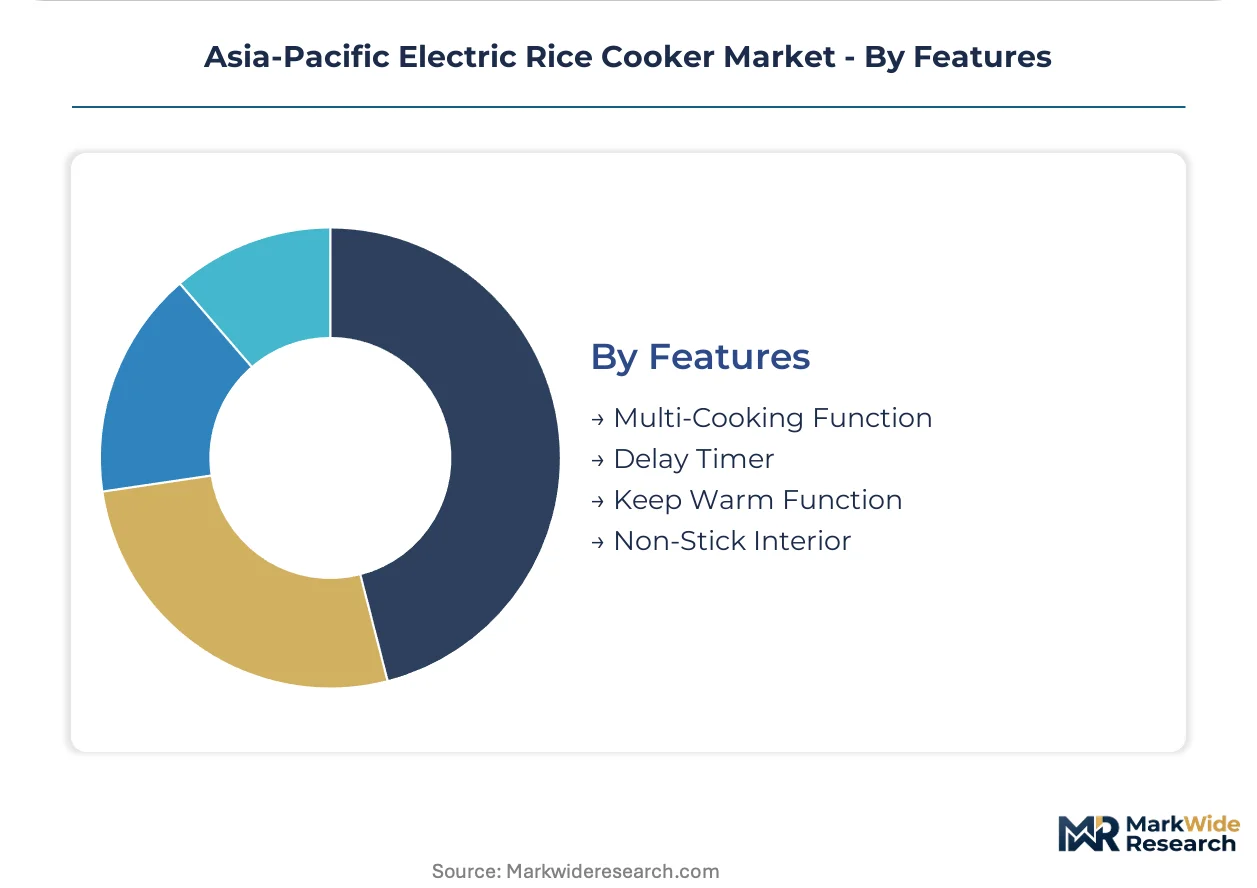
Features:
Feature bundling strategies differentiate price tiers and determine margin capture across distribution channels.
- Multi-Cooking Function:Programmable presets for porridge, soup, and cake modes expand utility beyond rice preparation. Younger buyers in Shanghai and Beijing prioritize versatility-per-dollar metrics.
- Delay Timer:Scheduled start capabilities align with commuting patterns in Seoul and Taipei where return-time predictability enables meal synchronization.
- Keep Warm Function:Extended holding temperatures at 60-70°C preserve texture for staggered family dining schedules across South India.
- Non-Stick Interior:Diamond-particle ceramic coatings command 40-60% price premiums in Tokyo and Osaka for scratch resistance and reduced oil requirements.
Keep warm functionality remains standard across all price tiers. Multi-cooking presets are gaining share fastest as manufacturers bundle capability to justify premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium induction heating units command 40-60% price premiums in Tokyo and Seoul while conventional models dominate price-elastic rural India and Vietnam. This asymmetry drives divergent manufacturer strategies across the region. National regulatory regimes further fragment competitive positioning.
China
Domestic electrification completion and urban middle-class expansion sustain replacement demand in Shanghai and Beijing. SAMR enforcement of GB 4706 household appliance safety standards mandates enhanced ingress protection and thermal runaway prevention. Manufacturing clusters in Guangdong and Zhejiang provinces consolidate testing laboratory relationships to accelerate compliance documentation.
India
Rural electrification campaigns in Bihar, Uttar Pradesh, and Odisha connect millions of previously off-grid households to stable power supplies. BIS certification mandates product testing and factory inspection protocols that extend commercialization lead times. TTK Prestige Limited anchors brand-conscious demand across South India's residential segment.
Japan
Single-person household proliferation in Tokyo drives compact 1-2 cup capacity preference. METI standby power regulations push manufacturers toward sub-one-watt idle consumption designs. Osaka industrial clusters concentrate fuzzy logic algorithm development and induction coil design expertise.
South Korea
Dual-income urban households in Seoul prioritize accelerated cooking cycles without quality degradation. Pressure-cooking technology adoption concentrates among time-constrained professionals. Cuckoo Electronics specializes in pressure-cooking configurations for domestic consumer preferences.
Vietnam
Ho Chi Minh City and Hanoi residential construction outpaces regional peers, creating concentrated demand for compact multi-function units. LPG infrastructure in rural provinces sustains conventional gas stovetop competition that limits electric appliance penetration. Urban high-rise kitchen footprint constraints favor space-efficient designs.
Asia-Pacific Electric Rice Cooker Market Competitive Environment
Concentration sits with diversified appliance conglomerates and specialized thermal engineering houses. The vendor base spans Japanese precision manufacturers, Chinese scale operators, and Korean technology specialists. Three archetypes dominate: vertically integrated premium brands, mass-market volume producers, and pressure-cooking technology specialists. Competitive moves center on component localization investments and multi-regional certification capacity expansion.
Among Japanese manufacturers, Panasonic Corporation and Zojirushi Corporation exemplify premium-tier positioning through in-house magnetics and control system capabilities. Chinese scale-driven producers include Midea Group Co., Ltd., which anchors volume throughput through massive domestic production scale. Cuckoo Electronics Co., Ltd. occupies a specialist position in pressure-cooking configurations.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Toshiba Corporation |
| Midea Group Co., Ltd. |
| Zojirushi Corporation |
| Tiger Corporation |
| Cuckoo Electronics Co., Ltd. |
| TTK Prestige Limited |
| Groupe SEB |
| Koninklijke Philips N.V. |
| Others |
Value Chain & Pricing Dynamics
China's GB standards for household appliance safety and energy efficiency simultaneously gate supply qualification and stratify price tiers across the Asia-Pacific electric rice cooker landscape. Manufacturers must satisfy SAMR-mandated testing protocols to access domestic distribution, while compliance costs concentrate pricing power among scaled producers capable of absorbing certification overhead.
Pricing Analysis
Configured-to-order pricing for induction heating units commands substantial premiums over standard Micom configurations across Tokyo and Seoul retail channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with BIS-certified models capturing margin advantages in South India. Cost compression in conventional segments is intensifying because Guangdong assemblers compete on volume throughput. Rural Vietnamese buyers exhibit highest price sensitivity, while Japanese single-person households demonstrate lowest elasticity for thermal precision features.
Supply Chain Analysis
IGBT module sourcing from Japanese and German semiconductor foundries constitutes a critical chokepoint constraining induction heating production scaling. Manufacturing concentrates in China, Japan, and South Korea, with magnetic induction coils and fuzzy logic control boards drawing from Osaka and Shenzhen industrial clusters. Single-source vulnerability in specialized ceramic coating feedstocks threatens premium tier output stability. Distribution runs through appliance retail chains in established markets and direct-to-consumer platforms across Southeast Asian urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific electric rice cooker market functions as a service-attach opportunity where extended warranty programs and consumable accessory subscriptions expand faster than hardware replacement cycles. After-sales revenue layers including ceramic inner pot replacements and firmware upgrade services warrant strategic prioritization.
For Market Incumbents: Consolidate testing laboratory relationships across Guangdong and Zhejiang to accelerate multi-regional certification documentation. Deepen backward integration into magnetic induction coil production to defend margin position against IGBT supply volatility. Prioritize channel control in South India where TTK Prestige Limited has established brand loyalty moats.
For New Entrants and Emerging Players: Anchor in Vietnam's high-rise residential construction corridor where compact multi-function unit demand outpaces regional supply. Target Ho Chi Minh City and Hanoi household formation with space-efficient designs priced below Korean import parity. Pursue direct-to-consumer platform storefronts on Shopee and Lazada to bypass established retail gatekeepers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified Japanese electronics conglomerates seeking to divest non-core appliance divisions with intact Osaka engineering talent. Mid-cap specialists with captive fuzzy logic algorithm development capabilities present acquisition appeal over pure assembly operations. Monitor BIS certification timeline compression as inflection indicator for India market entry feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Technology Partnership | Diamond-particle ceramic formulation agreements with Japanese materials specialists secure premium tier supply continuity. |
| Voice Platform Integration | Tmall Genie and Kakao i connectivity certifications unlock smart home ecosystem positioning in China and Korea. |
| Production-Linked Incentive Localization | India PLI scheme qualification reduces landed cost exposure for South Indian market penetration. |
| Multi-Regional Certification Buildout | Simultaneous GB, BIS, JIS, and KC marking capacity fragments competitor development resources. |
| Direct-to-Consumer Channel Expansion | Shopee and JD.com storefronts capture transaction volume from younger buyers prioritizing video demonstration content. |
Study Parameters
Operator-level perspectives from appliance manufacturing executives, thermal engineering specialists, channel procurement managers, and regulatory compliance officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SAMR certification databases, BIS product registration records, METI efficiency standard filings, and customs trade flow documentation. Bottom-up shipment modeling and top-down consumer expenditure triangulation converged on segment-level estimates.
Sensitivity analysis tested demand elasticity assumptions across the projection horizon under varying electrification rollout scenarios. Segmentation dimensions modeled include product technology tier, end-use application context, household capacity band, and feature bundling configuration. CAGRs derived from fitted growth curves incorporating replacement cycle dynamics, urbanization rates, and regulatory compliance cost trajectories. Induction heating adoption curves and pressure-cooking penetration rates served as category-specific forecast inputs.
Decision-makers should treat outputs as directional under stable electrification investment and trade policy assumptions; material deviation would warrant model refresh. Forecasts embed assumptions regarding IGBT supply availability and ceramic coating technology maturation timelines. Practitioners should keep alternative scenarios live as India's BIS certification processing capacity and China's GB standard enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Asia-Pacific Tumble Dryers Market
Appliances
Smart Connected Washing Machine Market
Appliances
Household Side by Side Refrigerator Market
Appliances
Egypt Microwave Ovens Market
Appliances
Turkey Washing Machine Market
Appliances
US Portable Washing Machines Market
Appliances
US Electric Rice Cooker Market
Appliances
India Washing Machine Market
Appliances
Portable Mini Fridge Market
Appliances
Minibar Refrigerators Market
Appliances
Portable Fridges Market
Appliances
Triple Barrel Waver Market
Appliances
Bahrain Dishwashers Market
Appliances
Asia Pacific Water Heater Market
Appliances
Commercial Microwave Ovens Market
Appliances
Electrical Appliances Plastics Market