
 Outdoor Cooking Table Market | 2026-2036
Outdoor Cooking Table Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Cooking Table Market Analytics
Stainless steel is broadening its share in outdoor cooking table construction as powder-coated carbon steel faces corrosion challenges in coastal climates. Weber-Stephen Products LLC leverages its captive foundry network to control alloy sourcing costs across North American distribution. Camp Chef anchors its position in the portable segment through dedicated SKU lines for overlanding and backcountry use. Blackstone differentiates via flat-top griddle integration that expands cooking surface utility beyond traditional open-flame formats.
An outdoor cooking table is a purpose-built food preparation and heating platform, typically fabricated from 304-grade stainless steel or weather-treated hardwood, designed for open-air residential or commercial culinary operations with integrated fuel containment and thermal management. Portable grills command the largest revenue pool within product type segmentation due to recurring replacement demand from frequent transport wear. Folding design features are capturing accelerated interest among tailgating and camping applications where vehicle cargo constraints dictate form factor. Stainless steel material grades concentrate margin pools at the premium tier, while aluminum dominates volume production for entry-level picnic table configurations.
EPA wood heater regulations constrain fire pit emissions specifications in the United States, forcing redesigns of combustion chambers and catalytic after-treatment systems. OSHA workplace safety standards influence commercial-grade outdoor cooking table specifications for culinary competition and foodservice staging environments. Stakeholders must monitor evolving state-level burn bans and municipal open-flame ordinances that fragment addressable market geography and complicate national inventory planning.
Market Dynamics
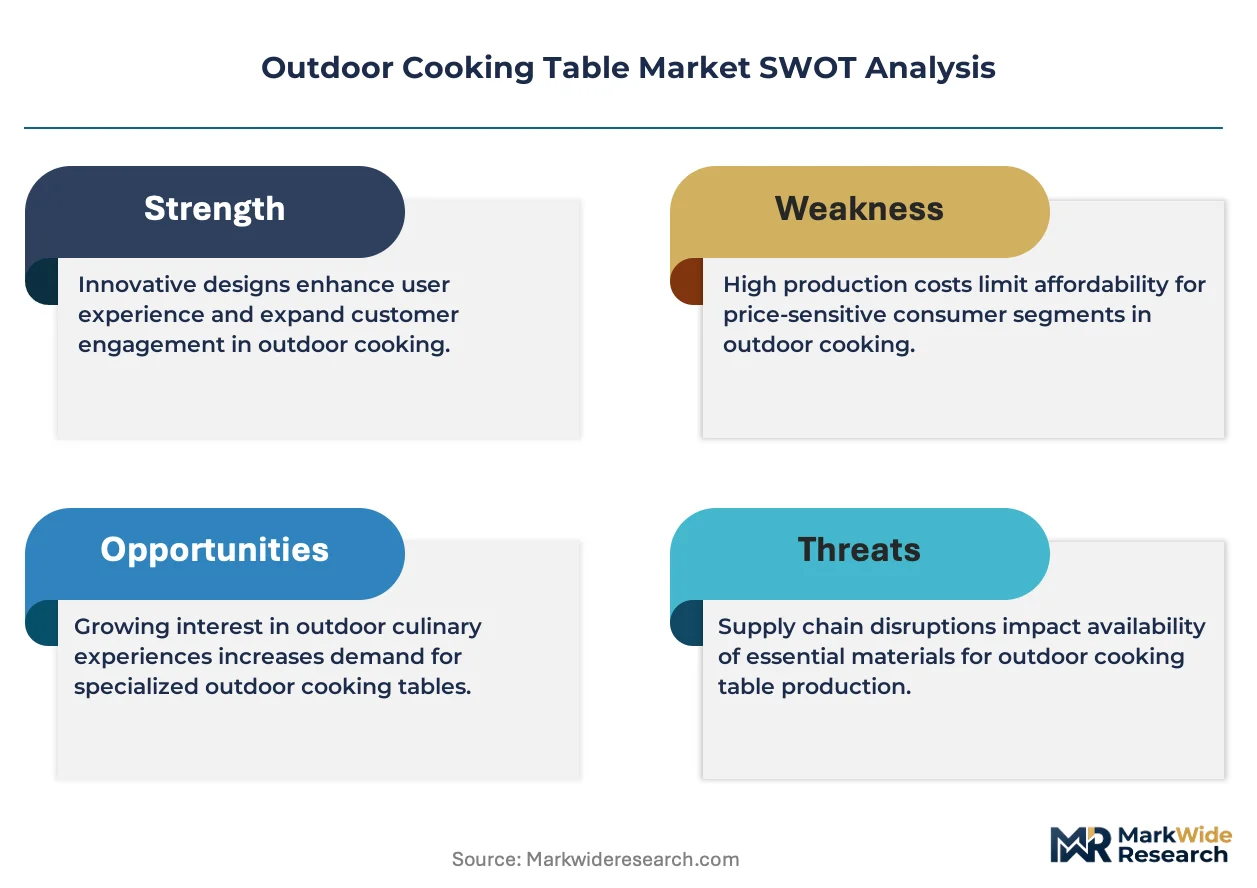
EPA emissions standards for wood-burning appliances are forcing manufacturers to redesign combustion chambers and adopt catalytic after-treatment systems, compressing margins for legacy fire pit configurations while creating premium tiers for compliant products.
Growth Catalysts
- Backyard entertaining surge:Suburban homeowners across Texas, Florida, and California are replacing entry-level grills with integrated outdoor cooking stations that combine prep surfaces with fuel containment.
- 304-grade stainless steel adoption:Coastal climate corrosion failures in powder-coated carbon steel are accelerating specification upgrades to marine-grade alloys in waterfront residential construction.
- OSHA commercial safety standards:Culinary competition and foodservice staging environments now mandate workplace-compliant outdoor cooking table specifications, expanding addressable demand beyond residential buyers.
Market Restraints
- Alloy input cost volatility:Nickel and chromium price swings in stainless steel supply chains compress margin predictability for fabricators locked into annual retail pricing contracts.
- State-level burn ban fragmentation:Municipal open-flame ordinances in drought-prone counties complicate national inventory planning and force region-specific SKU proliferation.
- Propane tank integration limits:DOT cylinder certification requirements constrain portable design flexibility and add compliance testing overhead for folding configurations.
Strategic Opportunities
- Overlanding accessory expansion:Vehicle-integrated outdoor cooking tables for backcountry use represent underpenetrated white space beyond traditional campground and tailgate segments.
- Flat-top griddle convergence:Blackstone's cooking surface utility expansion beyond open-flame formats demonstrates viable path to capture breakfast and lunch preparation occasions.
- Integrated smart fuel monitoring:Bluetooth-enabled propane level sensors paired with mobile apps create subscription-service potential and differentiate premium tiers.
Industry Challenges
- Welding certification bottlenecks:AWS D1.6 structural welding qualifications for 304-grade fabrication limit qualified labor pools and extend production ramp timelines.
- EPA 2020 wood heater compliance:Catalytic converter integration requires thermal engineering expertise that concentrates among a limited supplier base, creating single-source risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Cooking Table Market |
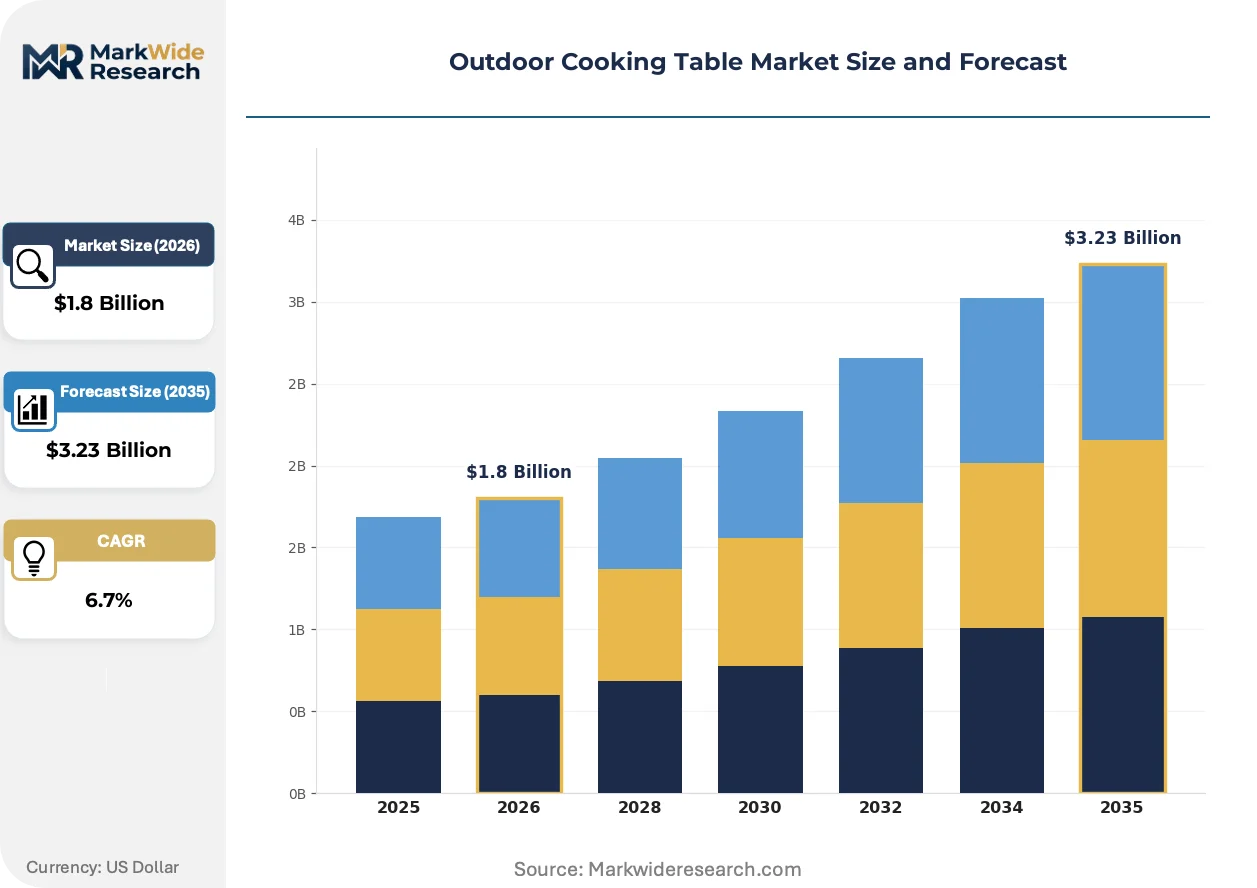
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Grills, Fire Pits, Picnic Tables, Outdoor Stoves Material: Stainless Steel, Aluminum, Wood, Plastic Feature: Multi-Burner, Folding Design, Built-In Storage, Non-Stick Surface Application: Camping, Tailgating, Backyard Parties, Culinary Competitions |
| Companies Covered | Weber-Stephen Products LLC, Camp Chef, Coleman, Blackstone, Napoleon, Bull Outdoor, Masterbuilt, Traeger, The Middleby Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Cooking Table Market Evolving Landscape
Material science advances and regulatory pressure are compressing traditional product lifecycles while opening premium positioning opportunities for manufacturers that master compliant combustion engineering.
Infrared searing burners are converging with traditional convection cooking zones to create hybrid thermal profiles that compress meal preparation times. High-end residential buyers in California and Texas are specifying these configurations for steakhouse-quality crust formation at home. This convergence is enabling premium pricing tiers that separate performance-oriented brands from commodity grill suppliers.
EPA Phase II wood heater regulations are mandating particulate emission limits below 2.0 grams per hour for outdoor fire pit configurations. Manufacturers are responding with reburn chambers and secondary combustion air injection that add material cost but unlock sales in jurisdictions with strict burn bans. The Pacific Northwest and Mountain West states represent the most affected geographies, where seasonal restrictions previously eliminated entire selling seasons.
Direct-to-consumer assembly models are displacing traditional big-box retail stocking for premium outdoor cooking tables. Buyers in suburban Texas and Florida markets increasingly expect white-glove delivery with on-site construction, unbundling the purchase from seasonal retail inventory cycles. This channel shift compresses working capital requirements for manufacturers while raising last-mile logistics complexity.
Outdoor Cooking Table Market Segmentation
Segmentation in outdoor cooking tables exposes how regulatory requirements, material specifications, and use-case intensity fragment manufacturing priorities. Certification burdens vary sharply across fuel types and thermal outputs, dictating which SKUs justify dedicated production lines versus contract assembly.
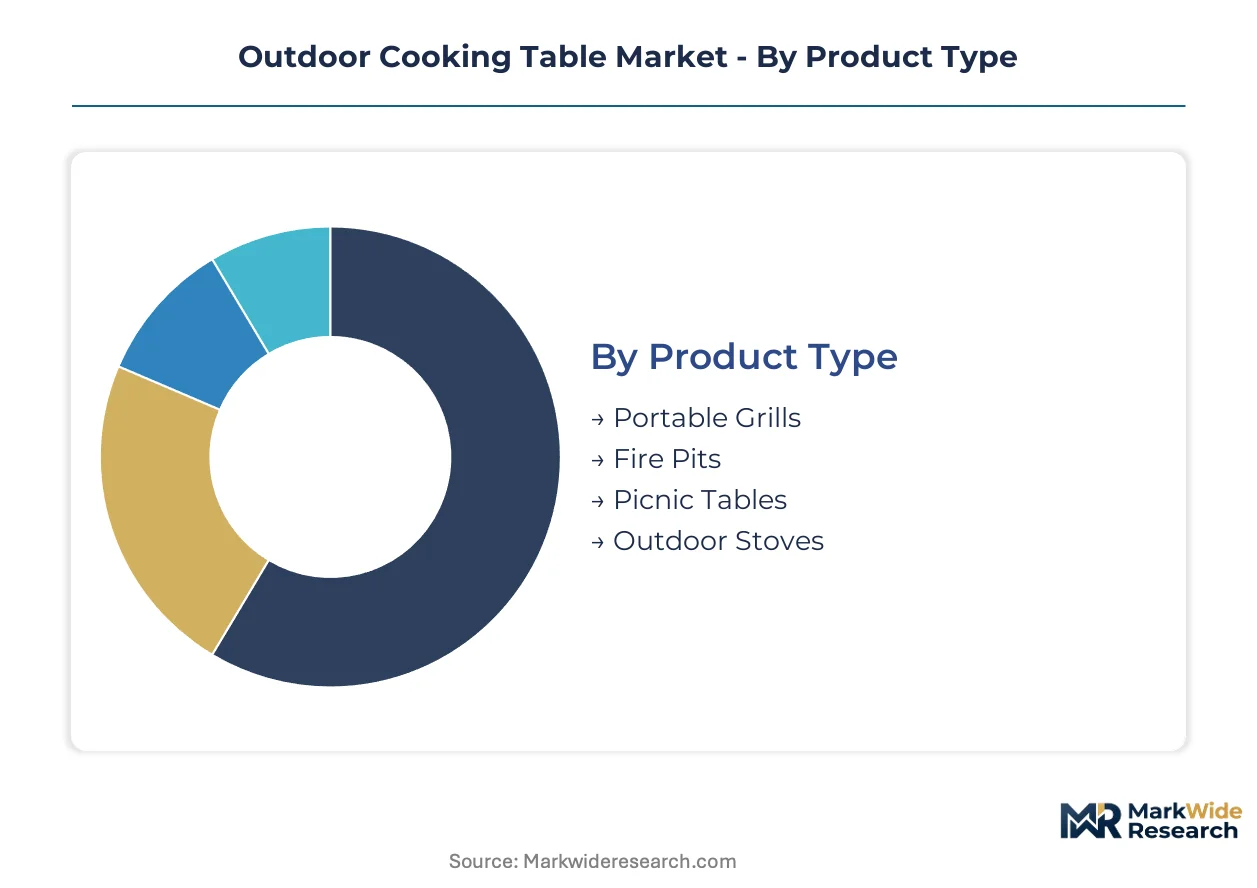
Product Type:
Portable Grills and Fire Pits carry distinct EPA compliance obligations under wood heater regulations, while Outdoor Stoves face DOT cylinder certification for propane integration. Picnic Tables largely bypass thermal emissions oversight but must satisfy CPSC surface coating standards for food contact.
- Portable Grills:These units combine fuel containment with prep surfaces in configurations ranging from two-burner cart models to six-burner island stations. Demand concentrates in Texas and Florida suburban markets where replacement cycles accelerate from salt-air corrosion and UV degradation. The folding configurations for vehicle transport require DOT compliance for propane cylinder housing, adding testing overhead that elevates price floors.
- Fire Pits:Wood-burning and gas-fueled variants fall under EPA Phase II particulate limits below 2.0 grams per hour, forcing catalytic after-treatment or secondary combustion engineering. Sales in Pacific Northwest and Mountain West states depend on seasonal burn ban exemptions that compliant designs unlock. Manufacturers without emissions engineering capability face exclusion from these high-margin jurisdictions.
- Picnic Tables:Static configurations emphasize food-safe surface treatments and weather resistance over thermal management. Demand tracks municipal park procurement and campground operator refresh cycles.
- Outdoor Stoves:High-BTU propane and butane units for backcountry and overlanding use require pressure vessel certification and wind-screen stability testing. Volume concentrates in Colorado and Utah recreation corridors.
Portable Grills sits at the top of the volume ranking, with Fire Pits climbing the fastest.
Material:
Raw material selection determines corrosion performance, thermal mass, and margin structure across coastal versus inland deployment zones. Marine-grade alloys command premium positioning while commodity metals serve price-sensitive segments.
- Stainless Steel:304-grade and 316-marine alloys dominate premium residential construction in California and Florida waterfront properties where salt spray destroys powder-coated carbon steel within three seasons. Nickel and chromium price volatility compress fabricator margins on annual retail contracts. AWS D1.6 welding certification requirements limit qualified production capacity.
- Aluminum:Cast and extruded grades enable lightweight portable configurations for camping and tailgating where vehicle payload constraints dictate form factor. Volume production concentrates in entry-level picnic table configurations for park and campground procurement.
- Wood:Cedar, teak, and thermally modified hardwoods serve aesthetic-driven residential installations in Pacific Northwest and Northeast markets. EPA wood heater regulations constrain fire pit emissions for wood-burning variants.
- Plastic:HDPE and recycled polymer composites offer maintenance-free surfaces for municipal and institutional buyers with extended replacement horizons. UV stabilizers and food-contact additives drive formulation costs.
Aluminum captures the highest shipment volumes, with Stainless Steel expanding most quickly.
Feature:
Feature bundling separates commodity grills from premium outdoor kitchen systems, with smart connectivity and modular storage commanding price premiums. OSHA compliance requirements for commercial staging environments favor specific configurations.
- Multi-Burner:Configurations ranging from dual-zone to six-burner arrays enable simultaneous high-heat searing and indirect convection. Infrared burner integration commands premium positioning in Texas and California residential markets.
- Folding Design:Hinge and latch mechanisms for vehicle transport face DOT cylinder certification constraints that limit design freedom. Demand accelerates in tailgating and overlanding segments where cargo space dictates purchase decisions.
- Built-In Storage:Propane tank enclosures, utensil drawers, and condiment compartments add material cost but reduce setup friction for frequent users. Commercial foodservice staging environments mandate OSHA-compliant workspace organization.
- Non-Stick Surface:Ceramic and porcelain coatings reduce cleaning burden for residential users while commercial operators prefer bare steel for thermal performance. California Proposition 65 compliance requirements constrain coating chemistry options.
Multi-Burner leads feature attachment rates, with Folding Design gaining share fastest.
Application:
Use-case intensity determines durability specifications, portability requirements, and replacement frequency. Commercial culinary competition demands workplace safety compliance absent from residential segments.
- Camping:Backcountry and campground use prioritizes packable weight, wind resistance, and multi-fuel flexibility. Overlanding vehicle integration represents underpenetrated white space beyond traditional tent-camping segments.
- Tailgating:Pre-game food preparation in stadium parking lots drives demand for rapid setup, integrated storage, and team-color customization. Folding configurations dominate where pickup bed and SUV cargo constraints apply.
- Backyard Parties:Suburban entertaining across Texas, Florida, and California accelerates replacement of entry-level grills with integrated outdoor kitchen stations. Prep surface integration and fuel containment combinations command premium positioning.
- Culinary Competitions:BBQ contests and foodservice staging environments mandate OSHA workplace safety standards for commercial-grade specifications. Thermal output consistency and durability under continuous operation separate competition-grade equipment from residential alternatives.
Backyard Parties anchors application demand, with Culinary Competitions showing steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas-California-Florida corridor anchors North American outdoor cooking table demand through suburban backyard construction and replacement cycles driven by coastal corrosion.
United States
Suburban homeowners across Texas, Florida, and California accelerate replacement of entry-level grills with integrated outdoor cooking stations combining prep surfaces with fuel containment. EPA Phase II wood heater regulations mandate particulate emissions below 2.0 grams per hour, forcing catalytic after-treatment adoption for fire pit configurations. Dallas-Fort Worth and Houston metropolitan clusters concentrate demand for premium stainless steel configurations resistant to Gulf Coast humidity.
Canada
Municipal park procurement and campground operator refresh cycles drive demand for aluminum picnic table configurations across Ontario and British Columbia. Health Canada surface coating standards govern food-contact treatments for institutional buyers with extended replacement horizons. Toronto-area fabricators supply lightweight folding designs targeting provincial park systems and recreational vehicle integration.
Germany
REACH chemical compliance constrains coating chemistry options for ceramic and porcelain non-stick surfaces exported from Bavarian manufacturing clusters. Ecodesign regulations under the EU Green Deal pressure combustion efficiency standards for gas-fueled outdoor cooking appliances. Stuttgart industrial fabricators supply precision-welded stainless steel frames to premium residential construction across Baden-Württemberg.
Australia
Queensland and New South Wales coastal markets prioritize marine-grade 316 stainless steel specifications to combat salt-air degradation in waterfront residential construction. State-level burn ban ordinances in drought-prone regions fragment addressable market geography and complicate national inventory planning for wood-burning configurations. Melbourne-area distributors coordinate white-glove delivery models for premium outdoor kitchen installations.
Japan
METI energy efficiency guidelines influence thermal output specifications for high-BTU propane units targeting compact urban balcony installations in Tokyo and Osaka metropolitan areas. JIS welding standards govern structural fabrication qualifications for 304-grade stainless steel outdoor cooking platforms. Nagoya industrial suppliers concentrate on precision folding mechanisms for vehicle-integrated overlanding configurations.
Outdoor Cooking Table Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers expand beyond traditional open-flame formats into flat-top griddle and hybrid thermal configurations. The vendor base stratifies across three tiers: mass-market commodity suppliers, premium residential specialists, and commercial-grade fabricators meeting OSHA workplace safety standards. Two strategic archetypes define competitive positioning: foundry-integrated players controlling alloy sourcing costs, and design-forward brands differentiating through cooking surface utility expansion. M&A activity concentrates among outdoor lifestyle conglomerates acquiring regional fabrication assets, while capacity expansion targets coastal corrosion-resistant alloy production.
Among North American fabricators, Weber-Stephen Products LLC represents the foundry-integrated archetype through captive alloy sourcing networks, while Blackstone exemplifies cooking surface utility expansion beyond traditional formats. Camp Chef occupies a position within the portable specialization tier targeting vehicle-integrated backcountry configurations. These three entities anchor distinct competitive vectors: upstream supply control, format innovation, and use-case segmentation respectively.
| Leading Market Players |
|---|
| Weber-Stephen Products LLC |
| Camp Chef |
| Coleman |
| Blackstone |
| Napoleon |
| Bull Outdoor |
| Masterbuilt |
| Traeger |
| The Middleby Corporation |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap fabricators concentrated in Guangdong and Zhejiang provinces anchor stainless steel component supply, translating captive workshop networks into pricing discipline that resists the volatility seen in contract-manufactured alternatives. Their ownership structure insulates long-term alloy procurement strategies from quarterly earnings pressure, compressing cost pass-through timelines to North American distributors while sustaining margin pools at premium tiers.
Pricing Analysis
Nickel and chromium price swings in stainless steel feedstock force fabricators into annual contract renegotiations with big-box retailers, compressing margin predictability for 304-grade configurations. Three-tier pricing structure across premium, standard, and economy levels separates marine-grade 316 alloys from commodity 304 and powder-coated carbon steel alternatives. Pricing pressure stems from EPA compliance engineering costs for catalytic after-treatment systems in fire pit configurations. Entry-level picnic table buyers exhibit highest price sensitivity, while waterfront residential construction in California and Florida shows lowest elasticity for corrosion-resistant specifications.
Supply Chain Analysis
Dual-sourcing mandates from major North American retailers require qualified fabrication capacity in both China and Vietnam, hedging tariff exposure and port congestion risks. Raw material dependencies center on Indonesian nickel ore, South African chromium, and Australian bauxite for aluminum extrusions. Supply chain risk concentrates in single-source vulnerability for AWS D1.6-certified welding labor pools that constrain 304-grade production ramp rates. Distribution runs through seasonal big-box retail stocking overlaid with expanding direct-to-consumer white-glove delivery channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on 304-grade stainless steel specification upgrades displacing powder-coated carbon steel in coastal construction, capturing value from corrosion-driven replacement cycles.
For Market Incumbents: Deploy captive foundry networks to lock in alloy sourcing costs ahead of nickel price volatility, insulating premium-tier pricing from commodity swings. Secure EPA 2020 wood heater compliance engineering capability through acquisition or exclusive partnership, eliminating single-source risk for catalytic converter integration. Defend against flat-top griddle format entrants by accelerating infrared burner convergence in Texas and California residential markets. For New Entrants and Emerging Players: Capture vehicle-integrated overlanding configurations as underpenetrated white space beyond traditional campground segments, where Camp Chef's established portable lines leave gaps for premium backcountry specifications. Target culinary competition staging environments with OSHA-compliant commercial-grade fabrication, leveraging welding certification bottlenecks that limit incumbent capacity expansion. Pursue direct-to-consumer assembly models with white-glove delivery to bypass seasonal retail inventory cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabrication assets lacking emissions engineering capability but holding AWS D1.6-qualified production capacity. Long-term viability favors platforms combining compliant combustion technology with coastal corrosion-resistant alloy expertise. Watch EPA enforcement intensity in Pacific Northwest and Mountain West states as inflection indicator for compliant fire pit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Catalytic After-Treatment Integration | EPA Phase II compliance unlocks sales in burn-ban jurisdictions across Pacific Northwest states. |
| Marine-Grade Alloy Specification | 316 stainless steel penetration in Florida waterfront construction commands 40-60% price premiums over carbon steel. |
| Direct-to-Consumer Assembly Model | White-glove delivery compresses working capital requirements while raising last-mile logistics complexity. |
| Overlanding Vehicle Integration | Backcountry cooking table configurations tap underpenetrated demand beyond traditional campground segments. |
| Smart Fuel Monitoring Systems | Bluetooth-enabled propane sensors paired with mobile apps create subscription-service differentiation at premium tiers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with outdoor cooking equipment product managers, stainless steel procurement leads at fabrication shops, EPA compliance engineering consultants, and big-box retail category buyers with secondary validation. Secondary sources included EPA wood heater certification databases, customs import records for 304-grade stainless steel components, SEC 10-K filings from outdoor lifestyle conglomerates, and regional burn ban ordinance compilations from municipal jurisdictions. Bottom-up SKU-level volume estimates triangulated against top-down market sizing derived from construction permit data and replacement cycle analysis.
Segment-weighting across product type, material grade, feature bundle, and application intensity drove analytical framework construction over the projection horizon. Portable grills, fire pits, picnic tables, and outdoor stoves each carried distinct thermal output and certification burden assumptions. Aluminum, stainless steel, wood, and plastic material segments incorporated nickel price elasticity and coastal corrosion failure rates. CAGRs derived from regression analysis against suburban household formation trends and EPA regulatory phase-in schedules, with backcountry overlanding and culinary competition applications receiving distinct growth coefficients.
Underlying measurement precision varies by segment; stainless steel specification upgrades and EPA-compliant fire pit configurations carry tighter precision than commodity picnic table volumes given clearer regulatory and corrosion-driven demand drivers. Forecasts reflect documented assumptions regarding suburban backyard construction rates, alloy price trajectories, and state-level burn ban enforcement intensity. Deviation in EPA Phase II enforcement consistency or nickel supply disruption from Indonesian export policies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
North America Floral Gifting Market
Home & Garden
Hedge Trimmer Market
Home & Garden
Europe Robotic Lawn Mower Market
Home & Garden
Residential Snow Blower Market
Home & Garden
Electric Lawn Mower Market
Home & Garden
Flowerpots and Planters Market
Home & Garden
Aquarium Decor Market
Home & Garden
Automated Blinds and Shades Market
Home & Garden
North America Flower Pots and Planters Market
Home & Garden
North America Flowerpots Market
Home & Garden
Global Wind Chime Market
Home & Garden
Japan Flower Pots Market
Home & Garden
United States Lawn Care Market
Home & Garden
Landscaping Services Market
Home & Garden
Flexible Garden Hoses Market
Home & Garden
Landscaping Products Market