
 Italy Home Appliances Market | 2026-2036
Italy Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Home Appliances Market Foresight
Buyer concentration across Italian retail channels is rebalancing as independent specialty stores lose ground to consolidated online platforms and hypermarket chains. Electrolux AB leverages its Nordic design heritage to anchor premium positioning in Italian kitchens. Samsung Electronics competes through smart appliance ecosystems that integrate with mobile devices. De'Longhi specializes in compact appliances for space-constrained urban apartments, particularly in Milan and Turin.
Italy home appliances encompass electrically powered devices for domestic tasks including food preservation, cleaning, cooking, and climate control, typically rated between 220-240V at 50Hz for the Italian grid and subject to EU energy labeling classes from A to G. Their primary purpose is to reduce household labor time and energy consumption in residential and light commercial settings. Refrigerators command the largest product type share due to universal household necessity and shorter replacement cycles driven by efficiency mandates. Smart appliances and IoT-enabled units represent the fastest-expanding technology segment as Italian consumers adopt voice-controlled and app-integrated kitchen management. Energy-efficient models capture disproportionate margin pools because Ecodesign compliance allows manufacturers to command price premiums while qualifying for national renovation incentives.
Italy's Ministry of Ecological Transition enforces EU Ecodesign and Energy Labeling regulations through national decrees that mandate minimum efficiency standards and visible consumption disclosures at point of sale. BIS-equivalent conformity assessment procedures through accredited Italian laboratories ensure CE marking validity for domestic and imported products. Stakeholders must monitor upcoming EU F-Gas Regulation revisions affecting refrigeration appliances and assess whether localized production or strategic importing better serves compliance costs and carbon footprint requirements.
Market Dynamics
Italy's transposition of EU Ecodesign directives into binding national law through the Ministry of Ecological Transition is compressing replacement cycles for legacy refrigeration and washing equipment, forcing manufacturers to redesign product portfolios around A-class efficiency thresholds.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for hydrofluorocarbons in cooling appliances are accelerating R&D investment in natural refrigerant systems across Italian manufacturing.
- Smart kitchen ecosystems:Voice-controlled and app-integrated appliance networks are penetrating Milan and Rome urban households at accelerating velocity.
- Northern industrial corridor:Concentrated disposable income in Turin-Milan-Veneto housing stock supports premium appliance penetration above national averages.
Market Restraints
- Copper and steel input volatility:Raw material price swings compress margin stability for mid-tier Italian manufacturers dependent on commodity-exposed supply chains.
- CE marking complexity:Multi-layered conformity assessment through accredited Italian laboratories extends time-to-market for imported components.
- Induction cooking substitution:Gas infrastructure legacy in southern Italian housing stock slows electrification transitions mandated by efficiency frameworks.
Strategic Opportunities
- Super-ecobonus incentives:Italy's national renovation subsidies for energy-efficient home upgrades create price-premium capture potential for A-rated appliance portfolios.
- Compact appliance formats:Space-constrained Turin and Genoa apartments drive demand for multi-functional countertop equipment currently underrepresented in manufacturer lineups.
- IoT-utility convergence:Integration between smart appliances and time-of-use electricity pricing platforms opens subscription revenue models for energy management services.
Industry Challenges
- Field service technician scarcity:Specialized repair skills for connected appliance diagnostics lag installation volumes in Rome and Naples metropolitan zones.
- Legacy housing electrical capacity:Pre-1990s Italian residential wiring infrastructure requires expensive retrofitting to support high-draw induction and heat-pump appliances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Home Appliances Market |
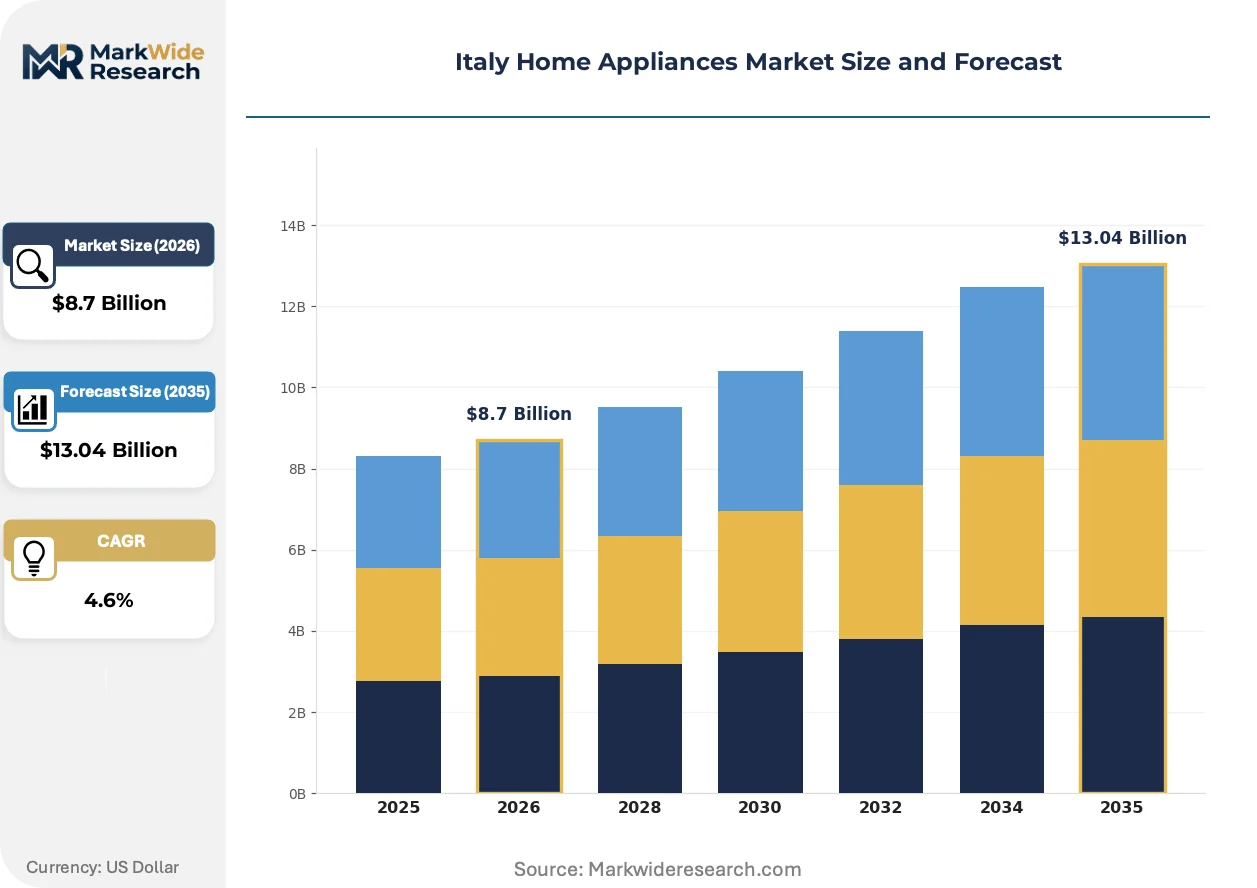
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Microwave Ovens, Dishwashers End User: Households, Commercial Establishments, Retailers, Hospitality Sector Technology: Smart Appliances, Energy-Efficient, Traditional Technologies, IoT-Enabled Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Wholesale |
| Companies Covered | Electrolux AB, Samsung Electronics, Whirlpool Corp, Miele, LG Electronics, Haier Europe, Arçelik AŞ, De'Longhi, BSH Hausgeräte GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Home Appliances Market Shifts & Advancements
Italian appliance manufacturers are reconfiguring R&D roadmaps around three converging pressures: hardware modularity, regulatory efficiency mandates, and channel consolidation toward direct-to-builder sales.
Refrigeration compressor technology is modularizing around variable-speed inverter platforms that separate cooling capacity from cabinet architecture. Premium kitchen renovators in Milan and Bologna are specifying these systems at accelerating rates. This modularity is compressing manufacturer SKU complexity while enabling customized interior configurations without engineering retooling.
Italy's Ministry of Ecological Transition is enforcing tightened EU Ecodesign minimum efficiency thresholds through national decrees effective at point-of-sale display. Manufacturers must redesign thermal insulation and motor systems to maintain market access. Built-in refrigerator categories face the steepest compliance costs given dimensional constraints that limit insulation thickness.
Builder-direct procurement is consolidating appliance specification authority away from independent retail channels toward large Lombardy and Veneto construction groups. These developers are bundling connected kitchen ecosystems into new-build contracts. Turin's high-rise residential pipeline exhibits the most pronounced shift toward pre-installed smart appliance infrastructure.
Italy Home Appliances Market Segmentation
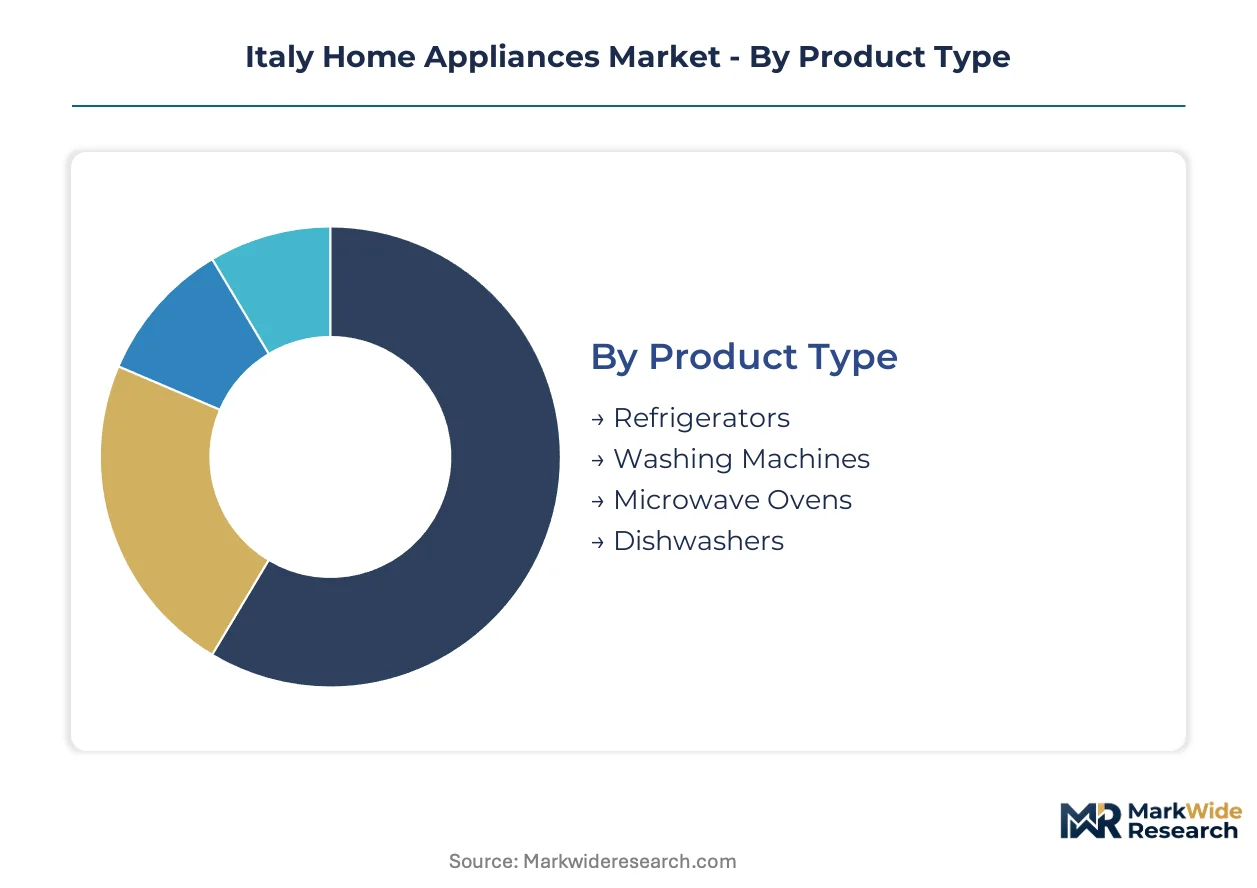
Product architecture and connectivity specifications are fragmenting the Italian market into distinct margin tiers. Manufacturers must align R&D investments with regulatory efficiency mandates while addressing divergent installation constraints across northern industrial corridors and aging southern housing stock.
Product Type:
Refrigeration and cleaning equipment dominate replacement cycles driven by Ecodesign compliance deadlines and energy labeling visibility requirements.
- Refrigerators:Variable-speed inverter compressors with modular cooling capacity now separate from cabinet architecture. Demand clusters in Milan and Bologna premium kitchen renovations where built-in configurations face steepest insulation thickness constraints under tightened EU efficiency thresholds.
- Washing Machines:Heat-pump and water-recirculation systems are displacing conventional heating elements in northern Italy's industrial corridor. Turin and Veneto households with newer housing stock support A-rated penetration above national replacement averages.
- Microwave Ovens:Compact countertop formats serve space-constrained Genoa apartments with multi-functional cooking modes.
- Dishwashers:Slimline 45cm widths address kitchen footprint limitations in Rome and Naples metropolitan zones.
Mature deployment sits with Refrigerators. Newer deployment is concentrated in Washing Machines.
End User:
Procurement authority is shifting from individual consumers toward institutional buyers with bundled specification power.
- Households:Urban households in Milan and Rome are upgrading to connected kitchen ecosystems with voice-controlled and app-integrated management. Super-ecobonus renovation subsidies create price-premium capture opportunities for A-rated appliance portfolios in owner-occupied housing.
- Commercial Establishments:Lombardy and Veneto construction groups are consolidating appliance specification authority through builder-direct procurement. These developers bundle connected kitchen ecosystems into new-build contracts with pre-installed smart infrastructure.
- Retailers:Independent specialty stores are losing ground to consolidated online platforms and hypermarket chains.
- Hospitality Sector:Boutique hotels in Florence and Venice prioritize design-forward compact appliances for space-optimized guest room configurations.
Volume concentration rests with Households. Margin expansion is accelerating fastest in Commercial Establishments.
Technology:
Connectivity integration and efficiency compliance are creating a three-tier technology architecture with diverging R&D allocation requirements.
- Smart Appliances:Voice-controlled and app-integrated networks are penetrating Milan and Rome urban households at accelerating velocity. IoT-utility convergence with time-of-use electricity pricing platforms opens subscription revenue models for energy management services.
- Energy-Efficient:A-class efficiency thresholds are compressing manufacturer SKU complexity while enabling customized interior configurations without engineering retooling. Ecodesign compliance allows manufacturers to command price premiums while qualifying for national renovation incentives.
- Traditional Technologies:Gas infrastructure legacy in southern Italian housing stock slows electrification transitions mandated by efficiency frameworks.
- IoT-Enabled:Specialized repair skills for connected appliance diagnostics lag installation volumes in Rome and Naples metropolitan zones.
Installed base dominance belongs to Traditional Technologies. Steepest expansion trajectory is climbing in Smart Appliances.
Distribution Channel:
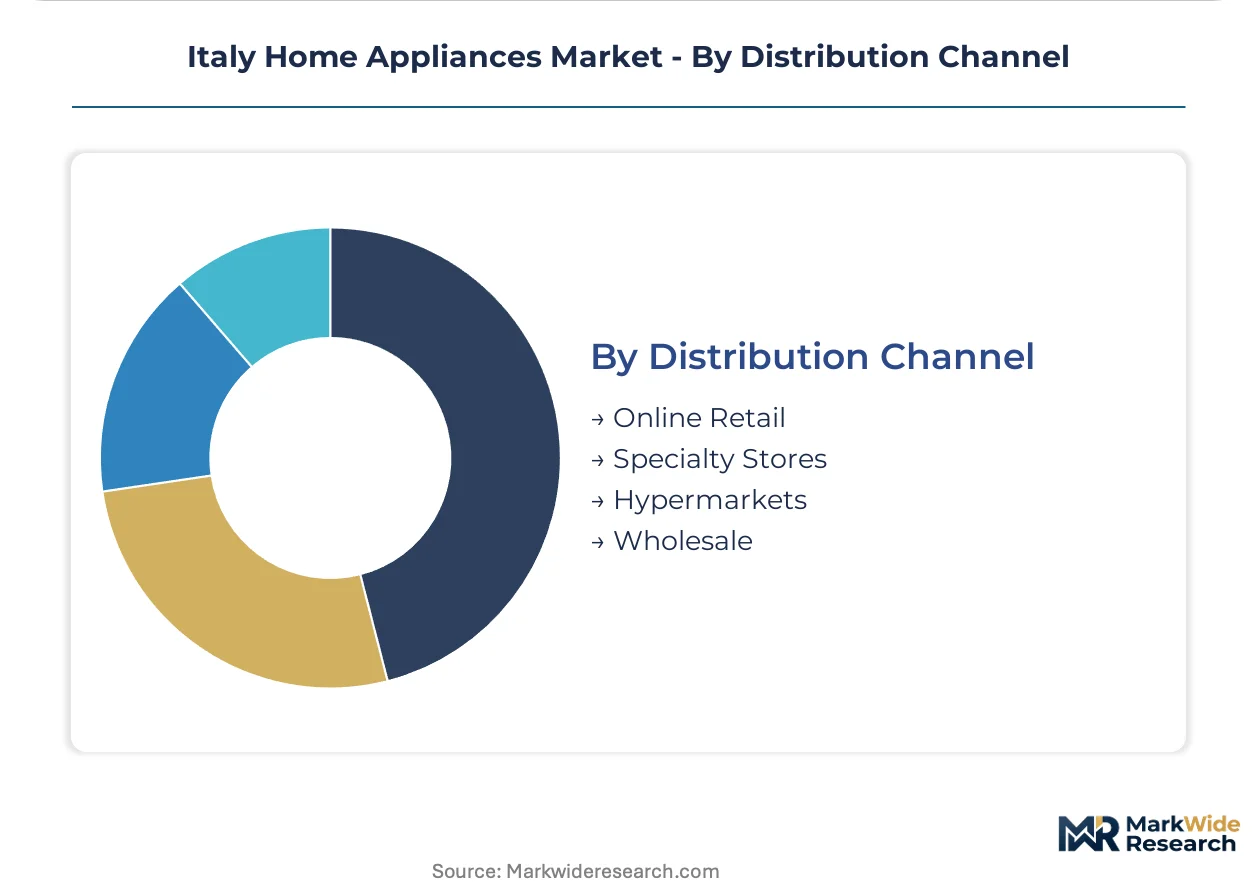
Channel consolidation is rebalancing buyer concentration toward platforms with logistics scale and installation service integration.
- Online Retail:Consolidated platforms are capturing share from independent specialty stores through bundled delivery-installation services and extended warranty programs.
- Specialty Stores:Design-focused independents in Milan's Brera district maintain positioning for premium built-in kitchen configurations.
- Hypermarkets:Large-format chains leverage volume procurement for mid-tier standard-size appliance replacement cycles.
- Wholesale:Builder-direct procurement channels serve Lombardy and Veneto construction groups with project-scale pricing and specification support.
Legacy strength remains with Specialty Stores. Channel share is gaining fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper and steel supply chains from northern Italian industrial districts anchor appliance manufacturing capacity across the peninsula. Regional demand patterns diverge sharply between the efficiency-mandated replacement cycles of the north and the infrastructure-constrained housing stock of the south.
Lombardy
Milan's premium kitchen renovation pipeline drives specification of built-in refrigeration with modular inverter compressors. The Ministry of Ecological Transition enforces EU Ecodesign thresholds through point-of-sale efficiency labeling mandates. Turin's high-rise residential developments bundle pre-installed smart appliance infrastructure into new-build contracts.
Veneto
Veneto households exhibit A-rated washing machine penetration above national averages due to newer housing stock and higher disposable incomes. Super-ecobonus renovation subsidies create price-premium capture opportunities for energy-efficient appliance portfolios. The Verona-Padua corridor concentrates builder-direct procurement channels serving construction groups with project-scale pricing.
Piedmont
Space-constrained Turin apartments generate demand for compact multi-functional countertop equipment currently underrepresented in manufacturer lineups. CE marking conformity assessment through accredited Italian laboratories extends time-to-market for imported components. The metropolitan zone exhibits pronounced shifts toward pre-installed smart appliance infrastructure in high-rise developments.
Emilia-Romagna
Bologna's premium kitchen renovators specify variable-speed inverter refrigeration systems at accelerating rates. EU F-Gas Regulation phase-down schedules for hydrofluorocarbons accelerate R&D investment in natural refrigerant systems across regional manufacturing. The city anchors northern Italy's industrial corridor demand for connected kitchen ecosystems.
Lazio
Rome's urban households upgrade to voice-controlled and app-integrated appliance networks with accelerating velocity. Specialized repair skills for connected appliance diagnostics lag installation volumes in the metropolitan zone. Field service technician scarcity constrains after-market support capacity for smart appliance deployments.
Italy Home Appliances Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in compact urban formats and IoT-enabled services. The vendor base clusters around three archetypes: Nordic design heritage anchors, Korean-Japanese smart ecosystem integrators, and German-Italian precision engineering specialists. Consolidation pressures favor platforms with logistics scale and installation service integration. Competitive moves concentrate on portfolio diversification around energy efficiency certifications and backward integration into compressor motor systems.
Among Swedish-anchored producers, Electrolux AB occupies a position exemplifying Nordic design heritage positioning in premium kitchen specifications. Samsung Electronics and LG Electronics represent the smart ecosystem archetype, anchoring connectivity integration strategies that interface with mobile device platforms. De'Longhi sits within the compact appliance specialization tier, serving space-constrained urban apartments in Milan and Turin metropolitan zones.
| Leading Market Players |
|---|
| Electrolux AB |
| Samsung Electronics |
| Whirlpool Corp |
| Miele |
| LG Electronics |
| Haier Europe |
| Arçelik AŞ |
| De'Longhi |
| BSH Hausgeräte GmbH |
| Others |
Supply & Pricing Matrix
Variable-speed inverter compressor modularization is compressing SKU complexity while simultaneously concentrating manufacturing economics among platforms with captive motor production. This production-method transition feeds directly into pricing power stratification across northern Italy's industrial corridor.
Pricing Analysis
Extended warranty bundling with installation services anchors premium positioning in Milan and Bologna kitchen renovations, while unbundled transactional pricing dominates replacement cycles in southern markets. Three-tier pricing structure across premium, standard, and economy levels separates A-rated connected ecosystems from legacy efficiency classes. Cost compression in mid-tier segments is intensifying because copper and steel input volatility erodes margin stability. Households in Veneto and Lombardy exhibit lowest price sensitivity due to Super-ecobonus subsidy absorption, while southern owner-occupiers face highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Builder-direct procurement channels handle hyperscale demand from Lombardy and Veneto construction groups with project-scale specification authority. Manufacturing capacity concentrates in Italy, Poland, and Turkey for final assembly, with compressor motors sourcing from China and Germany. Copper winding, steel sheet, and electronic control modules constitute critical input dependencies. Single-source vulnerability in semiconductor-based inverter controllers creates exposure to automotive sector demand surges. Distribution runs through consolidated online platforms capturing share from independent specialty stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
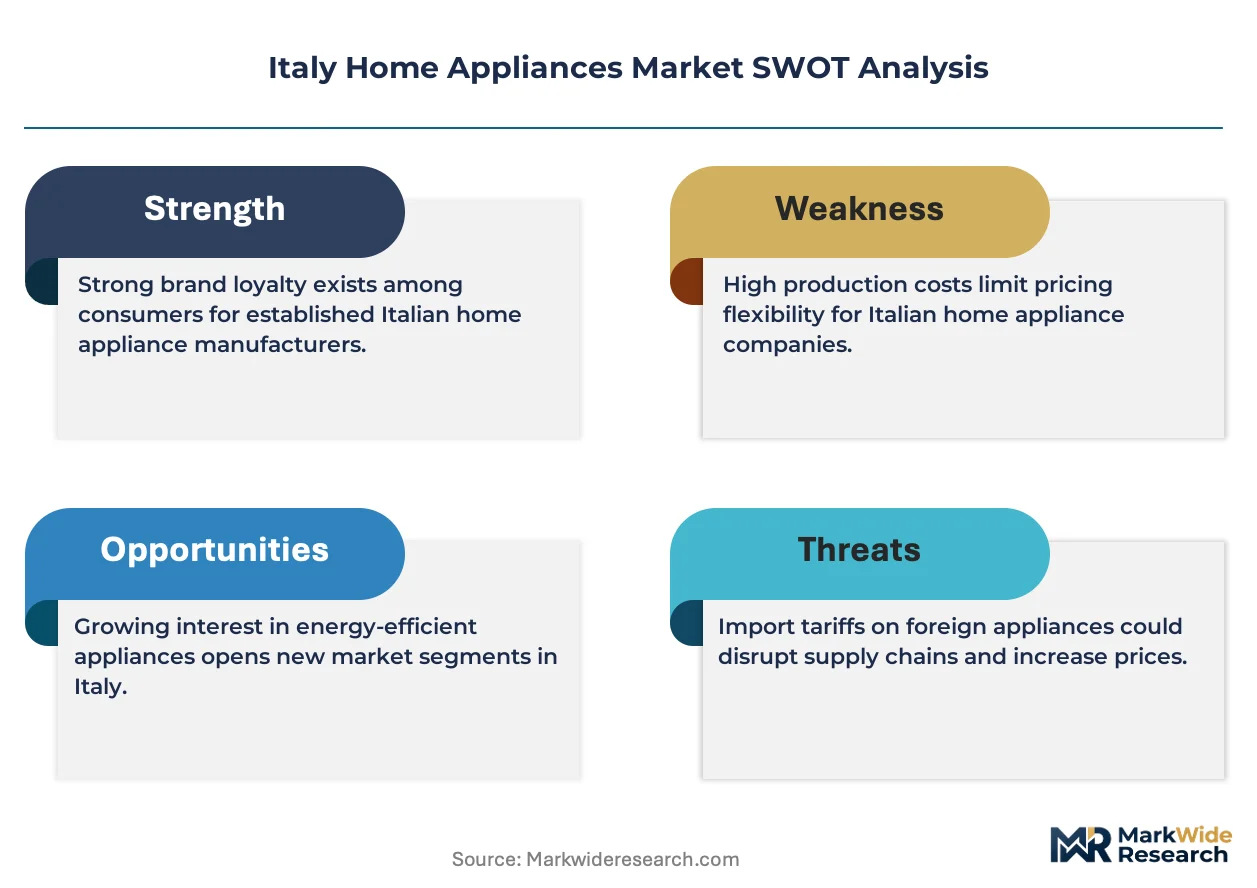
Italy's home appliances market operates as a cost-of-compliance story where EU Ecodesign transposition through the Ministry of Ecological Transition erects barrier-to-entry moats favoring players with accredited laboratory relationships and A-rated portfolio breadth.
For Market Incumbents: Deploy backward integration into compressor motor systems to defend margin position against commodity-exposed mid-tier competitors. Consolidate specification authority through exclusive builder-direct partnerships with Lombardy and Veneto construction groups facing compressed project timelines. Counter emerging Korean-Japanese smart ecosystem integrators by anchoring Nordic design heritage in premium kitchen renovations. For New Entrants and Emerging Players: Wholesale distributor relationships in southern Italy offer lowest competitive density for compact appliance formats addressing space-constrained Naples and Rome apartments. Target hospitality sector procurement in Florence and Venice where design-forward specifications prioritize aesthetic differentiation over scale economies. Pursue white-label manufacturing partnerships with accredited Italian laboratories to circumvent CE marking complexity delays. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to pan-European appliance platforms seeking A-rated portfolio augmentation and Italian market access. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone. Monitor F-Gas Regulation revision timelines as inflection indicator for natural refrigerant R&D investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Motors | Captive motor production insulates margin stability from copper and steel commodity volatility. |
| Builder-Direct Procurement Partnerships | Lombardy construction groups consolidate specification authority away from independent retail channels. |
| Natural Refrigerant R&D Investment | EU F-Gas Regulation phase-down mandates accelerate technical compliance requirements. |
| Compact Appliance Format Development | Space-constrained Turin and Genoa apartments drive underrepresented multi-functional countertop demand. |
| IoT-Utility Convergence Platform Launch | Time-of-use electricity pricing integration opens subscription revenue models for energy management services. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with appliance manufacturing executives, retail category managers, builder procurement directors, and field service technicians. Ministry of Ecological Transition decrees, EU Ecodesign implementing measures, and accredited laboratory conformity assessment protocols provided regulatory validation. Customs records tracked import volumes for compressor motors and electronic control modules. Bottom-up SKU-level demand modeling triangulated against top-down macroeconomic consumption indicators.
Production volume data reconciled against channel shipment disclosures and builder project pipeline tracking across the analysis window. Segmentation dimensions modeled include product type, end-user procurement authority, technology tier, and distribution channel structure. CAGRs derived from regression analysis of replacement cycle compression rates and efficiency mandate compliance deadlines. Natural refrigerant adoption curves and smart appliance connectivity penetration served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt F-Gas Regulation revision timelines, copper price shock scenarios exceeding historical volatility bands, and grid infrastructure retrofit acceleration in southern housing stock. Forecasts reflect documented assumptions regarding Super-ecobonus subsidy continuity and EU Ecodesign threshold implementation schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
India Small Home Appliances Market
Home Appliances
India Laundry Appliances Market
Home Appliances
France Household Appliances Market
Home Appliances
Household Refrigerators and Freezers Market
Home Appliances
Residential Dishwashers Market
Home Appliances
Range Hood Market
Home Appliances
China Small Home Appliances Market
Home Appliances
South Korea Home Appliances Market
Home Appliances
United States Major Home Appliances Market
Home Appliances
Europe Small Home Appliances Market
Home Appliances
Italy Small Home Appliances Market
Home Appliances
North America Electric Fireplace Market
Home Appliances
Europe White Goods Market
Home Appliances
Global Electric Motors Household Appliances Market
Home Appliances
Green Smart Household Appliances Market
Home Appliances
Kuwait Small Home Appliances Market