
 North America Electric Kettle Market | 2026-2036
North America Electric Kettle Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Kettle Market Analytics
Smart temperature control integration is reconfiguring how electric kettles communicate with home automation ecosystems and mobile applications. Breville USA, Inc. leverages precision heating algorithms to anchor its position in the premium variable temperature segment. Hamilton Beach Brands, Inc. sustains volume leadership through mass-market channel control and broad retail distribution across the United States and Canada.
An electric kettle is a self-contained vessel that heats water to boiling point through embedded resistive heating elements or induction coils, typically operating between 1,000 and 1,500 watts with boil-dry protection and auto shut-off safety circuits; its primary commercial purpose spans beverage preparation, cooking water pre-heating, and sterilization tasks across residential and institutional settings. Cordless kettles lead the product type dimension by volume due to consumer preference for countertop mobility and pour control, while variable temperature kettles command the strongest margin pools as tea culture sophistication rises among North American buyers. Glass kettles represent the fastest-growing material sub-segment as visual water monitoring and aesthetic kitchen integration displace opaque plastic housings.
The U.S. Department of Energy sets minimum energy conservation standards under 10 CFR Part 430 that manufacturers must satisfy for interstate commerce, while Health Canada administers the Canadian Electrical Code and product safety certifications through CSA Group accreditation that governs market access. State-level efficiency mandates in California and New York extend federal baselines and create compliance complexity for multi-jurisdictional product lines. Stakeholders must monitor how pending revisions to appliance efficiency test procedures and emerging right-to-repair legislation reshape design cycles and aftermarket service obligations across the region.
Market Dynamics
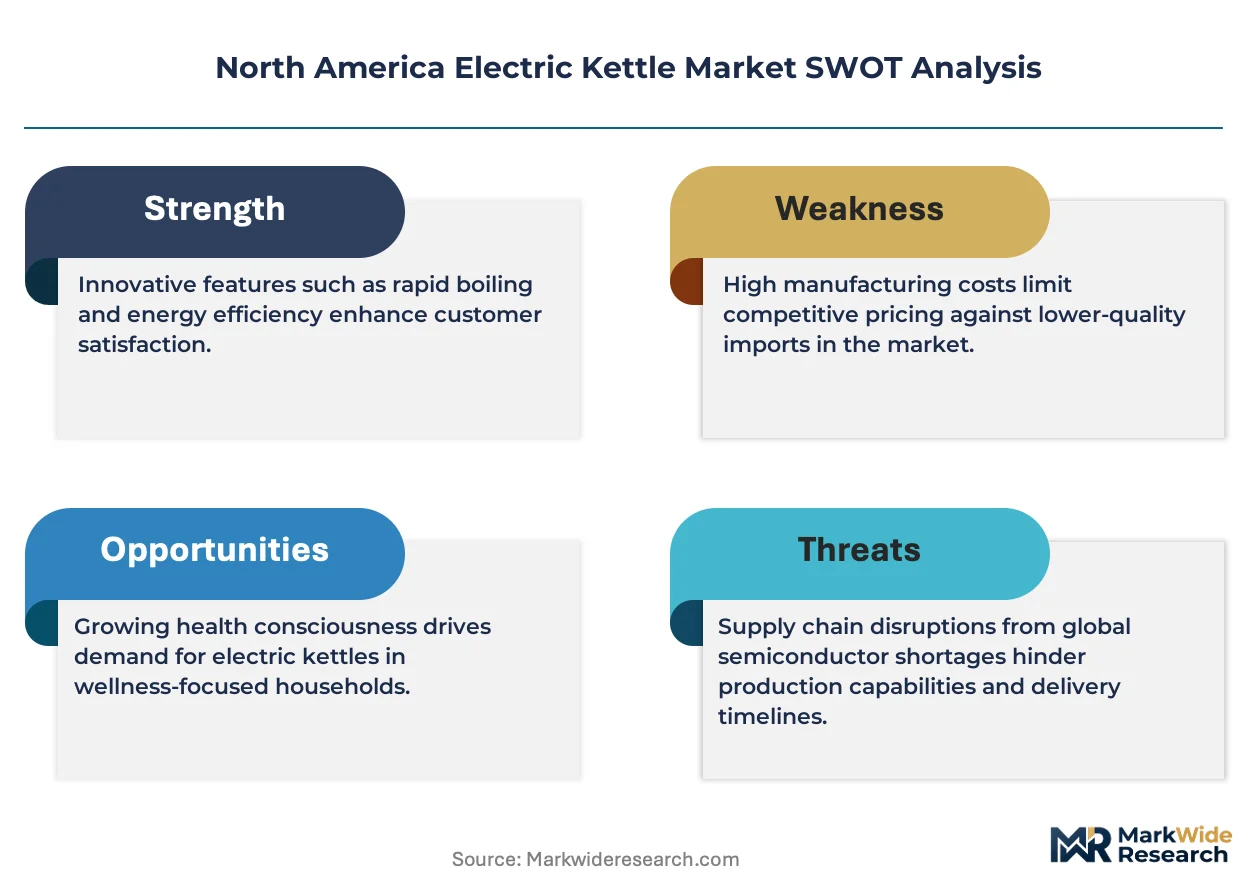
State-level electrification mandates and federal appliance efficiency standards are compressing design cycles and elevating compliance costs for manufacturers serving the United States and Canadian markets.
Growth Catalysts
- Variable Temperature Technology:Tea culture sophistication among North American consumers is pulling demand for precision heating controls into mainstream retail channels.
- California Title 20:Appliance efficiency mandates in California and New York are accelerating product refresh cycles and creating upgrade demand.
- Hospitality Procurement:Premium hotel chains across the United States and Canada are standardizing glass and smart-enabled kettles for guest room amenities.
Market Restraints
- Copper and Stainless Steel Input Volatility:Heating element materials face commodity price swings that compress margin pools for mid-tier manufacturers.
- Multi-Jurisdictional Compliance:Divergent efficiency test procedures between U.S. federal and Canadian provincial standards fragment product lines.
- Induction Cooktop Substitution:Built-in induction surfaces with rapid boil functions displace standalone kettle purchases in new kitchen construction.
Strategic Opportunities
- Canadian Prairie Provinces:Underpenetrated rural markets in Alberta and Saskatchewan present whitespace for cordless kettle distribution expansion.
- Voice Assistant Integration:Convergence of Wi-Fi connectivity with Alexa and Google Home ecosystems opens premium positioning for smart kitchen portfolios.
- IRA Efficiency Rebates:Inflation Reduction Act appliance incentives create demand pull for ENERGY STAR-certified models in the U.S. Northeast.
Industry Challenges
- Embedded Firmware Talent Scarcity:Smart kettle development requires IoT engineering capabilities that appliance manufacturers struggle to source domestically.
- CSA Group Certification Timelines:Canadian Electrical Code approval cycles extend product launch windows by four to six months versus U.S. equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Kettle Market |
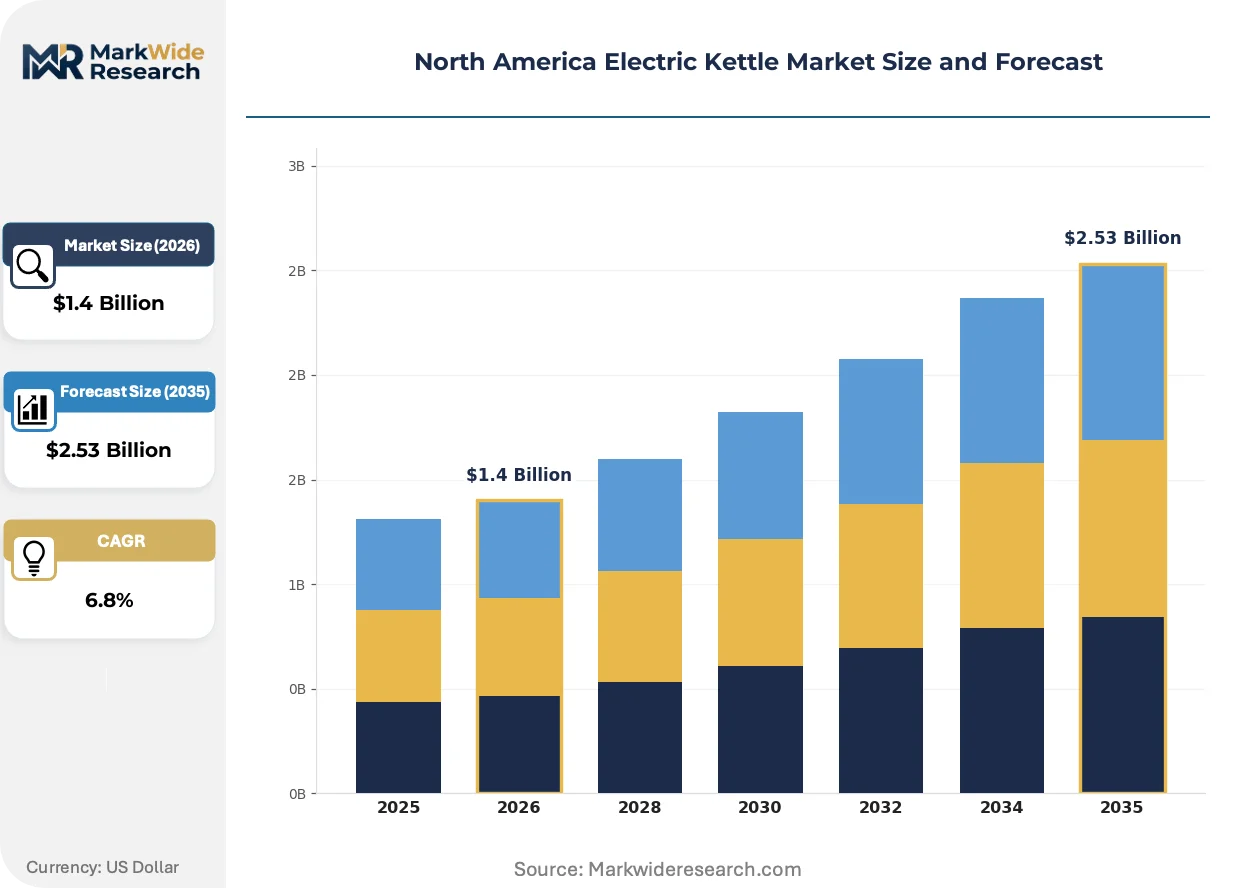
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corded Kettles, Cordless Kettles, Travel Kettles, Variable Temperature Kettles, Glass Kettles Technology: Rapid Boil, Induction Heating, Keep Warm, Auto Shut-Off, Water Level Indicator Application: Home Use, Office Use, Hospitality, Educational Institutions, Healthcare Facilities Customer Type: Individual Consumers, Hospitality Chains, Corporate Offices, Educational Organizations, Medical Centers |
| Companies Covered | Hamilton Beach Brands, Inc., Breville USA, Inc., Conair LLC, Groupe SEB, Spectrum Brands Holdings, Aroma Housewares Company, bonavitaworld, Koninklijke Philips N.V., Cuisinart, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Kettle Market Evolving Landscape
Product architecture and consumer interface design are converging around transparency, connectivity, and energy accountability in ways that reward first-movers with premium positioning.
Glass kettle construction is migrating from niche wellness positioning into mass-market dominance. Visual water level monitoring and aesthetic kitchen integration now drive purchase decisions among millennial and Gen Z buyers. Hospitality procurement teams specify borosilicate glass housings for durability and guest perception of cleanliness.
The U.S. Department of Energy's pending revisions to 10 CFR Part 430 test procedures are forcing manufacturers to redesign heating element configurations and control board logic. Compliance engineering now consumes twelve to eighteen months of pre-launch development. Variable temperature kettles face the steepest redesign burden due to multi-point calibration requirements.
Direct-to-consumer subscription models for replacement filters and descaling supplies are capturing recurring revenue streams previously lost to mass retail. Premium brands bypass wholesale markup by owning customer relationships through mobile applications. California metro clusters show the highest attach rates for consumable subscription services.
North America Electric Kettle Market Segmentation
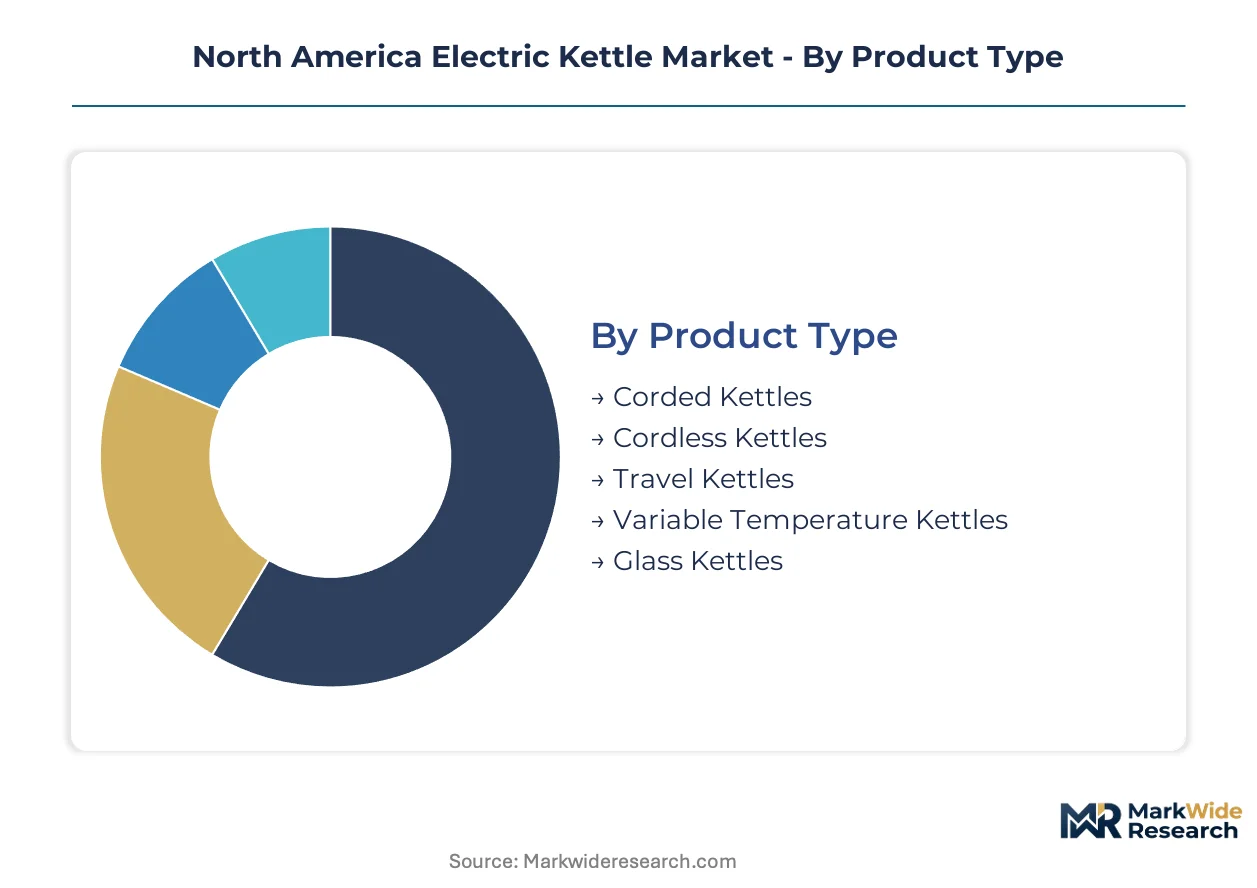
Electric kettle segmentation in North America reflects divergent replacement cycles across product architectures and procurement patterns. Technology-driven segments refresh every eighteen to thirty-six months while institutional application segments operate on five-to-seven-year capital equipment cycles.
Product Type:
Cordless kettles turn inventory fastest through retail channels, while variable temperature and glass variants command longer consideration cycles and premium shelf positioning.
- Corded Kettles:Fixed-base designs with tethered power connections dominate entry-level price tiers and institutional bulk procurement. Demand concentrates in educational facilities across the U.S. Midwest where capital budgets prioritize durability over countertop mobility.
- Cordless Kettles:Detachable base units with 360-degree rotation dominate residential countertop placement in dense urban corridors. U.S. Northeast apartment dwellers and Canadian metro buyers favor pour control and stowability.
- Travel Kettles:Compact 0.5-liter collapsible units serve transient professionals and hospitality amenities. Canadian business travel corridors and U.S. remote work patterns sustain niche volume.
- Variable Temperature Kettles:Precision heating presets for green, black, and herbal tea extraction pull demand from specialty beverage enthusiasts. California and Pacific Northwest markets show concentration where third-wave coffee culture extends into tea preparation rituals.
- Glass Kettles:Borosilicate housings with LED illumination satisfy wellness positioning and visual cleanliness verification. Hospitality chains across the United States and Canada standardize these for guest room perception management.
Cordless kettles anchor the volume base while glass kettles gain share at the steepest rate.
Technology:
Cost tier stratification separates rapid boil commodity engineering from induction heating premium architectures with steeper bill-of-materials profiles.
- Rapid Boil:High-wattage resistive elements achieving sub-four-minute boil times define mass-market performance expectations. U.S. big-box retail channels and Canadian mass merchants specify this as baseline table stakes.
- Induction Heating:Coil-based electromagnetic heating delivers energy efficiency and precise temperature modulation. California Title 20 compliance pressures and ENERGY STAR positioning drive specification in premium segments.
- Keep Warm:Thermostatic hold functions maintain water temperature for thirty to sixty minutes. Office break rooms and hospitality back-of-house operations value this for service continuity.
- Auto Shut-Off:Thermal cutoff circuits triggered by boil-dry sensors or lid-lift detection satisfy U.S. Department of Energy safety mandates and liability reduction for institutional buyers.
- Water Level Indicator:External sight glasses or LED-illumified windows reduce overfill waste and heating element damage. Glass kettle integration makes this standard rather than optional in aesthetic-driven segments.
Rapid boil configurations dominate unit economics while induction heating climbs fastest on regulatory efficiency pressure.
Application:
Customer type concentration varies sharply between high-frequency residential use and capital-intensive institutional deployment with divergent procurement authority structures.
- Home Use:Daily beverage preparation across single-family and multifamily dwellings drives replacement demand. U.S. coastal metro clusters and Canadian urban centers concentrate premium feature adoption.
- Office Use:Corporate break room and coworking facility provisioning operates on facilities management procurement cycles. Enterprise standardization favors cordless durability and scale pricing.
- Hospitality:Guest room amenities and lobby service stations demand aesthetic alignment with brand positioning. Premium hotel chains specify glass and smart-enabled models for experiential differentiation.
- Educational Institutions:University dining halls and campus housing units prioritize theft resistance and vandal-proofing in high-traffic installations. Bulk procurement through cooperative purchasing agreements dominates.
- Healthcare Facilities:Hospital patient floors and clinic waiting areas require infection-control surface materials and rapid sanitization compatibility. Canadian provincial health authorities and U.S. hospital systems maintain strict equipment approval lists.
Home use anchors the volume base while hospitality gains share at the steepest rate.
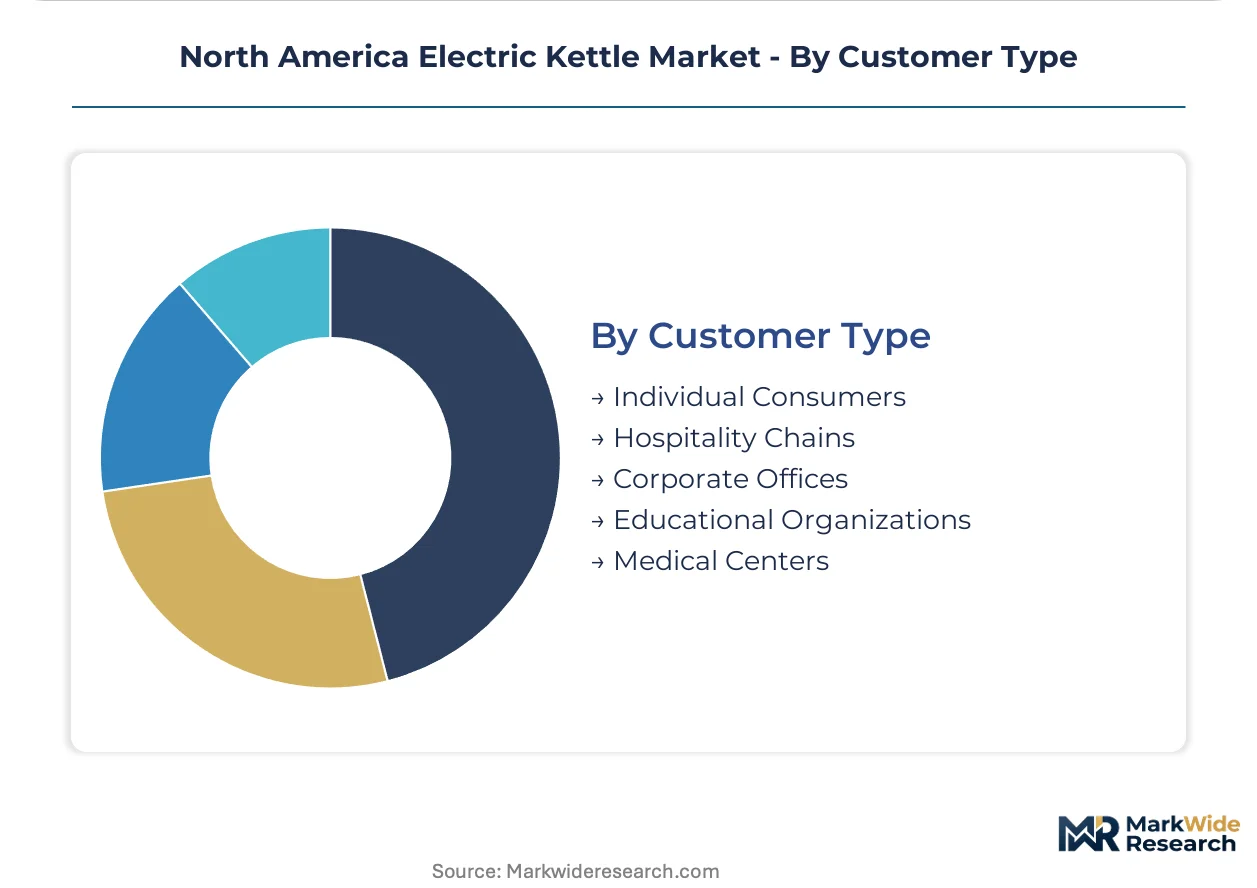
Customer Type:
Margin structure inverts between price-sensitive individual consumers and contract-negotiated institutional buyers with divergent lifetime value calculations.
- Individual Consumers:Discretionary purchasers responding to retail merchandising and online review ecosystems. Amazon and Canadian Tire dominate discovery and conversion in this segment.
- Hospitality Chains:Brand-standard procurement teams specifying uniform amenities across property portfolios. Marriott, Hilton, and Canadian hotel operators negotiate multi-year supply agreements with compliance auditing.
- Corporate Offices:Facilities and administrative services departments managing break room provisioning. Fortune 500 procurement consolidation favors approved vendor lists and sustainability scorecards.
- Educational Organizations:K-12 districts and higher education institutions purchasing through cooperative contracts and state procurement vehicles. California and New York state contracts set pricing benchmarks.
- Medical Centers:Infection control committees and biomedical engineering departments vetting equipment for clinical environments. Joint Commission accreditation requirements constrain vendor qualification.
Individual consumers anchor the volume base while hospitality chains gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian manufacturing facilities supply variable temperature and glass kettle models to hospitality chains across the United States, with cross-border logistics corridors handling the majority of premium product flows into California and Northeast corridor distribution centers.
United States
Apartment density in the Northeast corridor and California metro clusters concentrates cordless kettle demand among urban consumers prioritizing countertop mobility. The U.S. Department of Energy administers appliance efficiency standards under 10 CFR Part 430 that manufacturers must satisfy for interstate commerce. Dallas-Fort Worth distribution hubs serve as consolidation points for mass-market inventory flowing to big-box retail channels.
Canada
Hospitality procurement teams at Toronto and Vancouver headquarters standardize glass kettle amenities across continental property portfolios. Health Canada oversees Canadian Electrical Code compliance through CSA Group accreditation that governs market access. Montreal-area warehousing supports Quebec retail distribution while Prairie Provinces present underpenetrated whitespace for cordless kettle expansion.
Mexico
Manufacturing operations in Nuevo León and the Bajío Region assemble heating element components and control board assemblies for North American supply chains. The country's national consumer protection agency monitors electrical product safety certifications for domestic market entry. Mexico City Metro retail channels concentrate volume sales of entry-level corded kettles serving price-sensitive household segments.
North America Electric Kettle Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered price bands defined by feature complexity and material grade. Mass-market retailers and e-commerce platforms concentrate volume through approved vendor list structures, while premium positioning depends on precision heating technology and hospitality contract penetration. Two strategic archetypes dominate: scale-driven manufacturers optimizing bill-of-materials costs for retail channel dominance, and engineering-focused specialists capturing margin through variable temperature calibration and smart connectivity integration. Competitive moves center on multi-year hospitality supply agreements and direct-to-consumer subscription models for consumable attachments.
Among U.S.-based market participants, Hamilton Beach Brands, Inc. and Breville USA, Inc. exemplify divergent archetype positioning within the regional competitive structure. Hamilton Beach Brands, Inc. occupies a position aligned with mass-market channel control and broad retail distribution networks. Breville USA, Inc. anchors the premium variable temperature segment through precision heating algorithm development. Koninklijke Philips N.V. represents the multinational electronics conglomerate archetype with kitchen appliance portfolio diversification.
| Leading Market Players |
|---|
| Hamilton Beach Brands, Inc. |
| Breville USA, Inc. |
| Conair LLC |
| Groupe SEB |
| Spectrum Brands Holdings |
| Aroma Housewares Company |
| bonavitaworld |
| Koninklijke Philips N.V. |
| Cuisinart |
| Others |
Value Network & Pricing Analysis
Cross-border freight corridors between Ontario manufacturing clusters and California distribution centers transmit copper price volatility into variable temperature kettle premiums while compressing margin pools for mid-tier corded models lacking hospitality contract anchor pricing.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate heating element procurement, creating bill-of-materials pressure that manufacturers absorb or pass through via premium-mid-economy pricing differentiation. Price differentiation hinges on ENERGY STAR certification tier and hospitality brand-standard approval status, with California Title 20 compliance adding certification cost premiums. Pricing pressure intensifies as induction cooktop substitution erodes standalone kettle replacement demand in new residential construction. Individual consumers through Amazon and mass retail channels exhibit highest price sensitivity, while hospitality procurement teams prioritize total cost of ownership and brand alignment over unit economics.
Supply Chain Analysis
Export-control restrictions on advanced induction coil winding equipment limit technology transfer to Mexican assembly operations, concentrating precision heating component production in China and South Korea. Heating element manufacturing draws from copper cathode supplies in Chile and recycled stainless steel feedstock from U.S. scrap processors. Single-source vulnerability in borosilicate glass furnace capacity creates supply risk for aesthetic-driven glass kettle segments. Distribution runs through Dallas-Fort Worth consolidation hubs serving U.S. big-box retail and Toronto-area warehousing for Canadian hospitality procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America electric kettle market is cycling through a post-pandemic replacement wave as hospitality capital expenditure resumes and residential kitchen appliance refresh accelerates.
For Market Incumbents: Harden supply chain resilience through backward integration into heating element component production or captive borosilicate glass sourcing partnerships. Secure multi-year hospitality supply agreements with Marriott and Hilton procurement teams to defend volume base against emerging smart-kettle entrants. Invest in CSA Group pre-certification engineering to compress Canadian launch windows.
For New Entrants and Emerging Players: Establish a beachhead in Canadian Prairie Provinces where cordless kettle penetration lags U.S. urban benchmarks. Target voice assistant integration as a premium positioning wedge against Hamilton Beach mass-market dominance. Deploy direct-to-consumer subscription models for descaling supplies to capture recurring revenue streams bypassing wholesale markup.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors engineering-focused specialists with precision heating algorithm IP over scale-driven manufacturers dependent on retail channel control. Long-term viability hinges on hospitality contract renewal rates and smart home ecosystem integration depth. Monitor Inflation Reduction Act rebate utilization rates in the U.S. Northeast as inflection indicator for ENERGY STAR-certified model demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospitality Supply Agreement | Marriott and Hilton standardization creates multi-year revenue visibility and brand legitimacy. |
| Voice Assistant Integration | Alexa and Google Home ecosystem convergence opens premium positioning beyond mass retail channels. |
| Direct-to-Consumer Subscription | Consumable attach rates for descaling supplies capture recurring revenue lost to wholesale. |
| CSA Group Pre-Certification | Early Health Canada compliance engineering compresses launch windows versus U.S.-first competitors. |
| Glass Kettle Capacity Expansion | Borosilicate furnace investment secures supply for hospitality amenity standardization trends. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospitality procurement directors, retail category managers, appliance manufacturing engineers, and CSA Group certification specialists. Secondary validation drew from U.S. Department of Energy 10 CFR Part 430 filings, Health Canada product safety databases, ENERGY STAR qualified product lists, and customs trade records for heating element component flows. Bottom-up demand modeling across cordless, variable temperature, and glass product architectures triangulated against top-down market sizing from retail audit data.
Calibration against historical replacement cycle patterns and regulatory implementation timelines anchored value projections across the analysis window. Segmentation dimensions spanned product type, heating technology, application setting, and customer procurement authority structure. CAGRs were derived from regression analysis of price-volume elasticities and technology adoption S-curves. Forecast inputs incorporated copper price trajectory assumptions and state-level electrification mandate implementation schedules.
Sensitivities concentrate around copper commodity volatility, CSA Group certification timeline extensions, and hospitality capital expenditure cycle turns. Forecasts reflect documented assumptions regarding replacement frequency and premium feature adoption rates. Material shifts in U.S. Department of Energy test procedure revisions or Canadian provincial efficiency standard harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Germany Kitchen Appliances Market
Kitchen Appliances
Commercial Tabletop Kitchen Products Market
Kitchen Appliances
Cookware Accessories Market
Kitchen Appliances
France Cookware Market
Kitchen Appliances
Europe Major Home Appliances Market
Kitchen Appliances
Self-Stirring Mug Market
Kitchen Appliances
Garlic Press Market
Kitchen Appliances
Global Baking Tools Market
Kitchen Appliances
Global Stainless Woks Market
Kitchen Appliances
Outdoor Commercial Grills Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Europe Electric Vegetable Chopper Market
Kitchen Appliances
Self-Heating Butter Knife Market
Kitchen Appliances
Europe Air Fryers Market
Kitchen Appliances
Kitchen Appliances Market
Kitchen Appliances
Australia Kitchen Appliances Market