
 US Smart Oven Market | 2026-2036
US Smart Oven Market Size, Share, and Industry Trends Forecast 2026-2036
US Smart Oven Market Insights
China's appliance manufacturing belt is tilting toward North American export capacity. Samsung Electronics Co., Ltd. leverages its semiconductor supply chain to integrate proprietary IoT chipsets directly into oven control systems. Whirlpool Corporation anchors its position through captive production of smart appliance motors and sensors in Ohio facilities. LG Electronics competes on display panel integration, bundling OLED interface technology with convection heating platforms.
A US smart oven constitutes a connected cooking appliance embedding sensors, wireless transceivers, and microprocessor-controlled heating elements to automate temperature regulation, recipe execution, and remote monitoring via smartphone applications. Units typically operate across 240V residential circuits with internal cavity temperatures ranging from 150°F to 550°F depending on cooking mode. Countertop configurations lead current shipment volumes due to lower price points and installation flexibility, while built-in variants command the strongest margin pools through kitchen renovation tie-ins. Wi-Fi-enabled units outpace Bluetooth-only alternatives as consumers prioritize over-the-air firmware updates and cloud-based recipe libraries.
The FCC certifies radio frequency emissions for all wireless-enabled cooking devices, while the CPSC governs thermal safety and fire prevention standards for residential appliance sales. California's Title 20 appliance efficiency regulations and DOE federal test procedures for conventional ovens shape product development roadmaps and market access requirements. Stakeholders must monitor evolving cybersecurity mandates for connected kitchen ecosystems as the FTC intensifies scrutiny of IoT data privacy practices.
Market Dynamics
Kitchen automation momentum in US residential households is compressing replacement cycles for conventional appliances as connectivity infrastructure matures and consumer comfort with IoT-controlled cooking rises.
Growth Catalysts
- Title 20 Efficiency Mandates:California's appliance efficiency regulations force manufacturers to redesign heating elements and insulation systems, accelerating smart oven refresh cycles in the nation's largest state market.
- Wi-Fi Firmware Architecture:Over-the-air update capability eliminates service technician dispatches for software patches, reducing total cost of ownership for multi-unit property managers and renovation contractors.
- Texas Metro Corridor Density:Dallas-Fort Worth and Houston smart home penetration rates exceed national averages by substantial margins, creating concentrated demand pockets for premium built-in configurations.
Market Restraints
- Semiconductor Supply Concentration:Proprietary IoT chipset fabrication relies on concentrated Asian foundry capacity, exposing control system production to geopolitical friction and shipping lane disruption.
- Copper and Steel Input Volatility:Heating element windings and chassis fabrication depend on commodity metals whose price swings compress margin predictability for Ohio-based motor and sensor production.
- Bluetooth-Only Obsolescence:Consumers perceive Bluetooth-only units as technologically stranded, creating inventory markdown pressure on legacy channel stock and depressing average selling prices for entry-tier configurations.
Strategic Opportunities
- FCC Cybersecurity Rulemaking:Pending Federal Communications Commission IoT security labeling requirements will favor manufacturers with established secure boot architectures, creating regulatory moats against late entrants.
- Apartment Renovation Cycles:Multi-family housing operators in Austin and Phoenix are standardizing smart appliance packages to command rent premiums, opening bulk procurement channels distinct from retail.
- Voice Assistant Convergence:Integration of natural language processing with convection control algorithms enables hands-free recipe execution, appealing to accessibility-focused demographics and aging-in-place renovations.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for real-time thermal control requires specialized skill sets concentrated in coastal technology corridors, forcing Midwest appliance manufacturers into compensation wars with automotive and aerospace sectors.
- CPSC Certification Timelines:Thermal safety testing for novel heating element geometries extends product launch windows by six to nine months, delaying revenue recognition against competitor refresh cycles.
- Legacy Kitchen Electrical Infrastructure:Pre-1990s residential wiring lacks dedicated 240V circuits for built-in smart ovens, forcing costly electrical upgrades that stall renovation project conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Smart Oven Market |
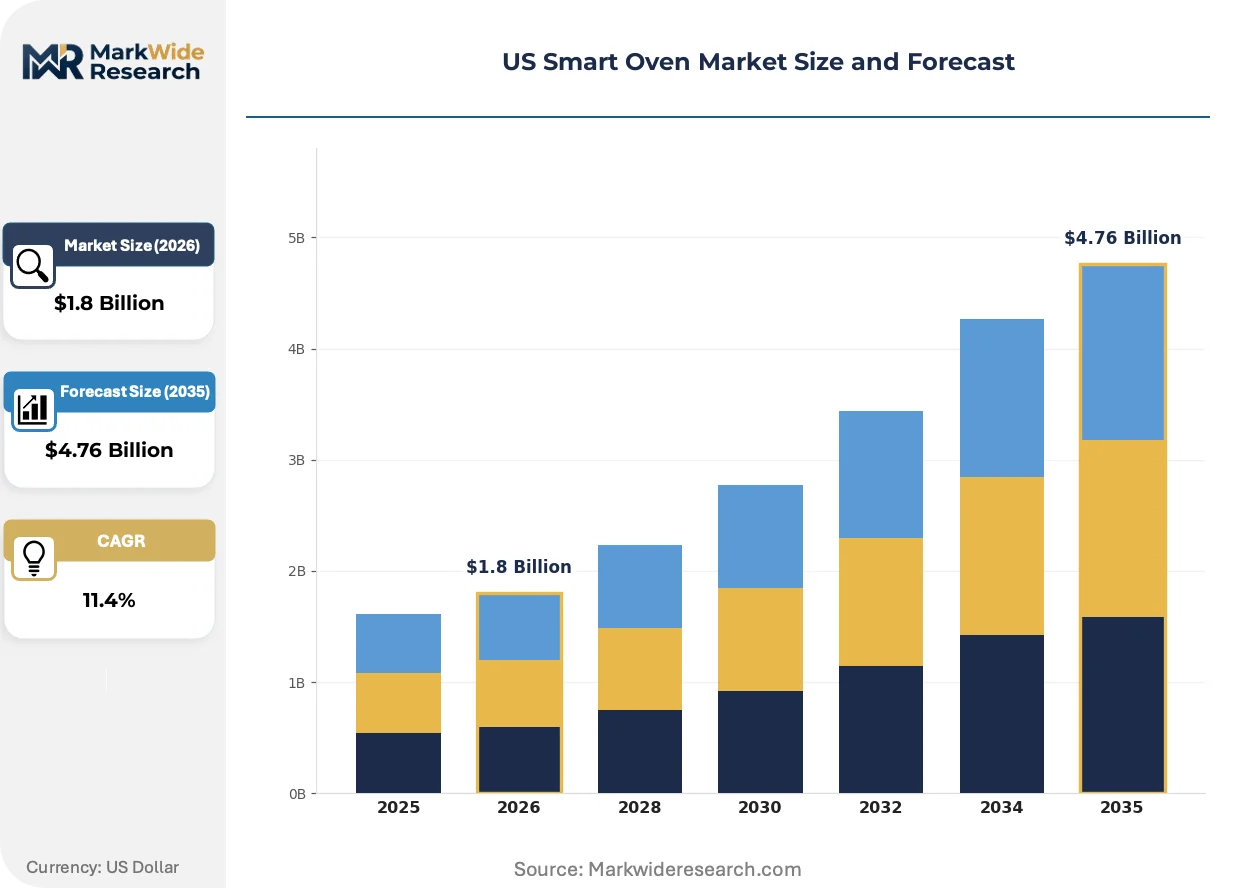
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Built-In, Microwave, Toaster Oven Technology: Wi-Fi, Bluetooth, Voice Activation, Touch Control End User: Residential, Commercial, Culinary Schools, Hospitality Distribution Channel: Online Retail, Appliance Stores, Home Improvement Stores, Wholesale |
| Companies Covered | Whirlpool Corporation, LG Electronics, Samsung Electronics Co., Ltd., Panasonic Corporation, Sharp Corporation, AB Electrolux, Alto-Shaam, Inc., Tovala, June Life, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Smart Oven Market Trends and Innovations
Sensor fusion and cloud-connected recipe databases are redefining cooking automation from temperature control toward predictive meal preparation, shifting competitive differentiation from hardware specifications to software ecosystem depth.
Computer vision systems embedded in oven cavities are collapsing the distinction between manual and automated cooking by identifying food type, browning progression, and doneness through camera arrays and machine learning models. High-end residential buyers in California are specifying these units in new construction at accelerating rates. The technology is collapsing traditional recipe adherence into autonomous cooking cycles that require minimal user intervention.
The Federal Trade Commission is intensifying scrutiny of IoT data privacy practices across connected kitchen ecosystems, compelling manufacturers to rearchitect data collection pipelines and consent mechanisms. Industrial consequence includes delayed product launches as legal teams validate compliance against evolving enforcement standards. Smart oven lines with integrated cameras and usage analytics face the steepest compliance burden and are responding with on-device processing to minimize cloud data transmission.
Property developers are bundling smart appliances into specification-grade kitchen packages for rental and for-sale multi-family units, displacing traditional retail-driven consumer selection. The channel shift concentrates purchasing power with national multi-family operators and their procurement consortia. This concentration is most visible in Sun Belt metropolitan areas where new construction volumes outpace national averages and developer incentives align with technology-forward branding.
US Smart Oven Market Segmentation
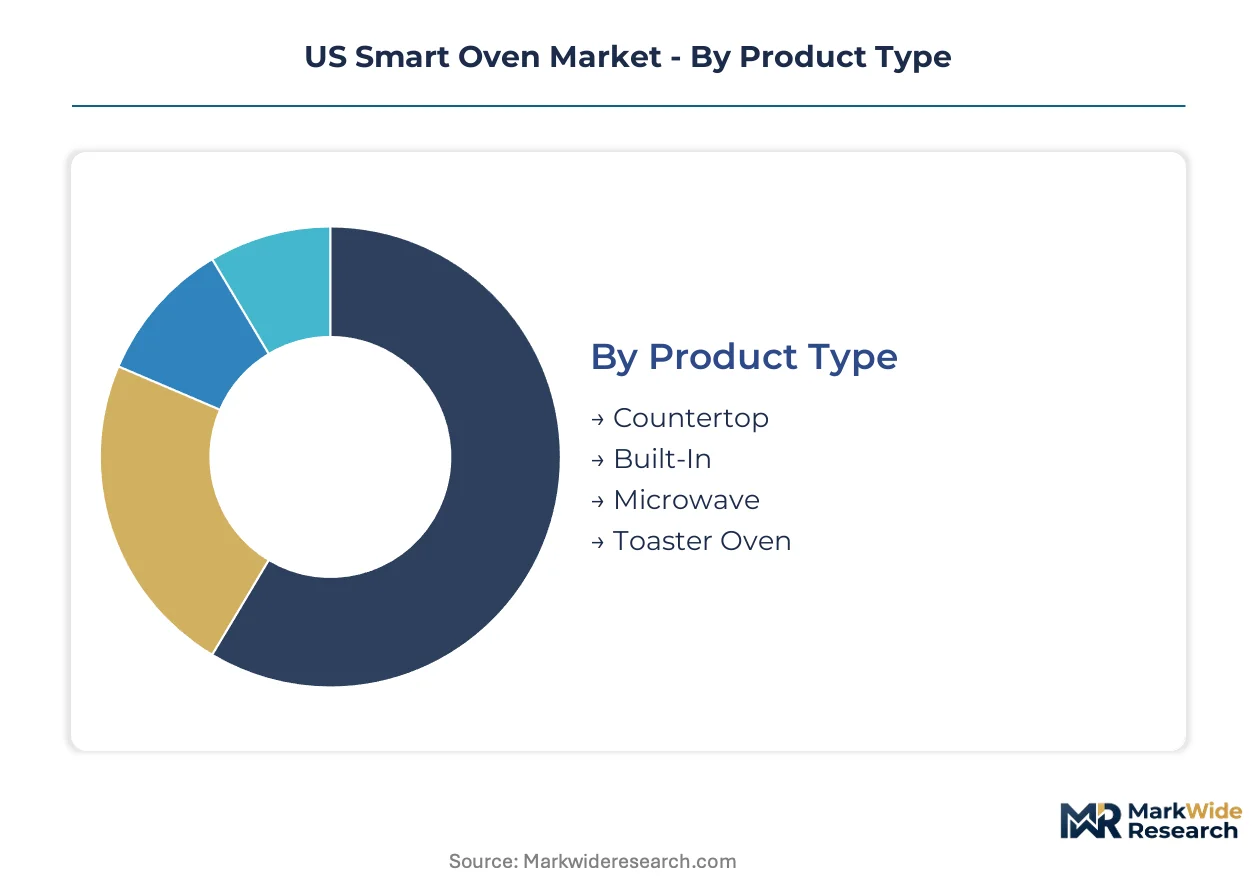
Smart oven segmentation reveals distinct service architectures. Countertop units require minimal installation support while built-in configurations demand electrical contractor coordination. Technology tiers separate cloud-dependent ecosystems from isolated Bluetooth implementations. End-user categories expose diverging durability requirements between residential replacement cycles and commercial continuous-duty operations.
Product Type:
After-sales-service intensity varies dramatically across installation requirements. Countertop models need only warranty fulfillment while built-in units trigger contractor networks for electrical upgrades and cabinetry modifications.
- Countertop:Freestanding units operating on 120V circuits with plug-and-play deployment. Demand concentrates in Texas metropolitan corridors where apartment dwellers prioritize portability and avoid electrical infrastructure investments. FCC certification for Wi-Fi modules remains the primary regulatory gateway.
- Built-In:Hardwired 240V installations integrated with kitchen cabinetry and ventilation systems. California residential renovations drive adoption through Title 20 efficiency mandates that accelerate replacement of legacy conventional ovens. Service intensity peaks with electrical contractor dispatch requirements.
- Microwave:Combination units merging rapid heating with convection capabilities. Commercial foodservice operators in hospitality segments specify these for space-constrained back-of-house environments.
- Toaster Oven:Compact countertop variants with reduced cavity capacity and lower price positioning. College markets and secondary residential kitchens represent concentrated demand pockets.
By volume, Countertop leads. By growth pace, Built-In is expanding most quickly through kitchen renovation tie-ins.
Technology:
Cost tier stratification separates premium cloud-connected ecosystems from entry-level isolated controls. Wi-Fi architectures command development investment for firmware maintenance while Bluetooth-only implementations face obsolescence pressure.
- Wi-Fi:Cloud-connected transceivers enabling over-the-air updates, remote monitoring, and recipe library access. FCC Part 15 certification governs radio frequency emissions for all residential deployments. Texas and California smart home infrastructure penetration drives concentrated demand.
- Bluetooth:Short-range wireless for local smartphone pairing without internet dependency. Inventory markdown pressure intensifies as consumers perceive technological isolation from ecosystem integration.
- Voice Activation:Natural language processing integration with Amazon Alexa and Google Assistant protocols. Aging-in-place renovations in Sun Belt metropolitan areas prioritize hands-free operation for accessibility compliance.
- Touch Control:Capacitive interface panels with OLED or LCD display integration. LG Electronics leverages captive display manufacturing for premium tier differentiation.
By installed base, Wi-Fi dominates. By margin contribution, Voice Activation is gaining share fastest through premium positioning.
End User:
Application requirements dictate durability specifications and warranty structures. Residential segments prioritize aesthetic integration while commercial operators emphasize mean-time-between-failure metrics.
- Residential:Household consumers replacing conventional appliances during kitchen renovations. California Title 20 regulations and Texas smart home adoption create geographic concentration of upgrade activity.
- Commercial:Foodservice operations requiring continuous-duty thermal cycling and rapid recovery performance. CPSC thermal safety standards apply with heightened inspection protocols.
- Culinary Schools:Educational institutions standardizing connected appliances for curriculum consistency and remote instructor monitoring.
- Hospitality:Hotel and extended-stay operators deploying in-suite kitchenettes for competitive differentiation. Austin and Phoenix multi-family developers specify these in bulk procurement arrangements.
By unit volume, Residential leads. By revenue per unit, Commercial commands premium positioning through durability specifications.
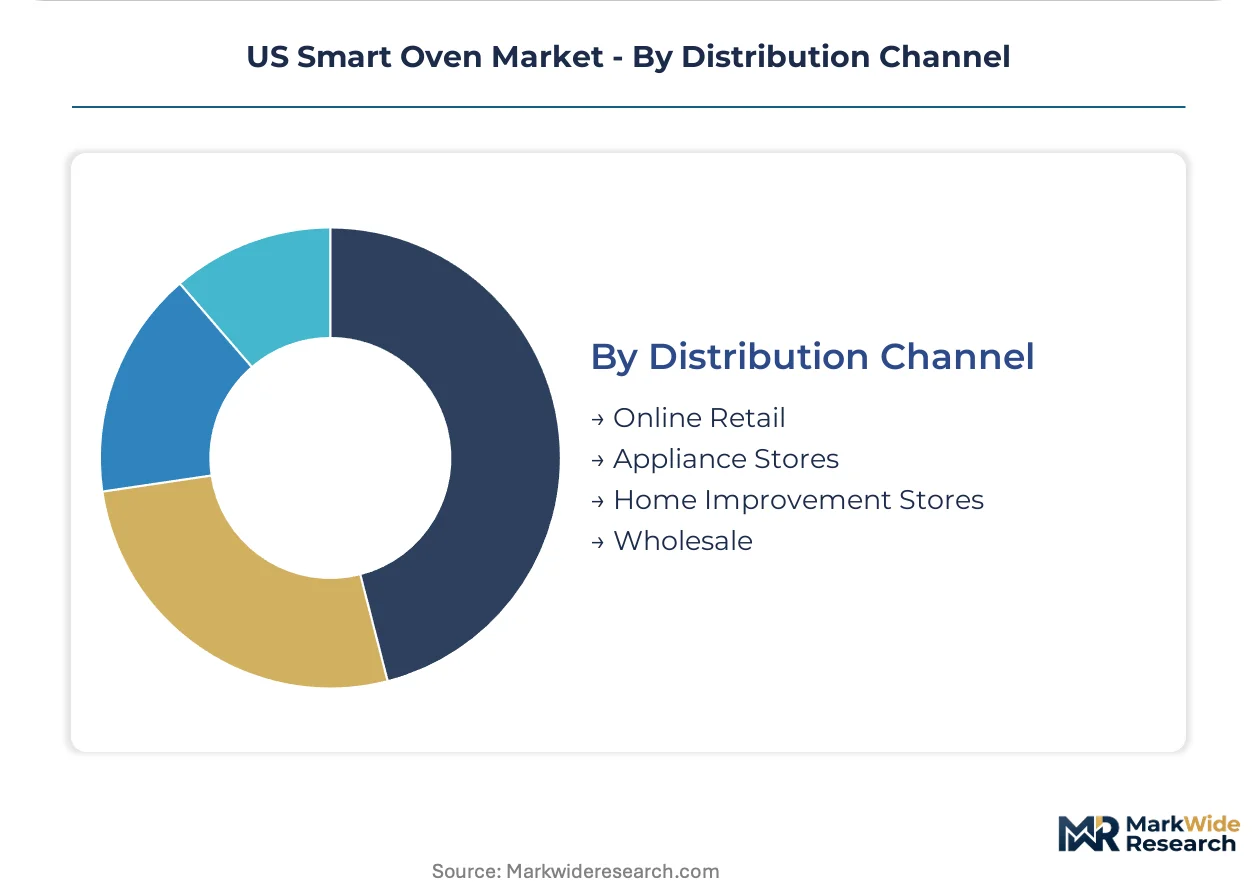
Distribution Channel:
Customer type separation distinguishes individual purchase behavior from institutional procurement. Online retail captures convenience-driven replacement while wholesale channels aggregate multi-unit property operator demand.
- Online Retail:Direct-to-consumer platforms with review-dependent conversion and subscription accessory revenue. Amazon and manufacturer direct sites capture metropolitan corridor demand with rapid fulfillment expectations.
- Appliance Stores:Specialty retailers with in-store demonstration capabilities and installation service bundling. California and Texas independent dealers maintain regional loyalty through contractor referral networks.
- Home Improvement Stores:Big-box channels integrating smart ovens with broader renovation project baskets. Lowe's and Home Depot locations in Dallas-Fort Worth and Houston metropolitan areas coordinate electrical contractor panels.
- Wholesale:Bulk procurement consortia serving national multi-family operators and property developers. Sun Belt construction volume concentration creates demand clustering distinct from retail patterns.
By transaction count, Online Retail leads. By average order value, Wholesale shows steepest expansion trajectory through developer bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California and Texas metropolitan corridors consume smart ovens differently than the national baseline, with built-in configurations dominating Pacific Coast renovations while countertop units concentrate in Sun Belt apartment markets.
California
Residential kitchen automation drives demand through Title 20 appliance efficiency mandates that accelerate replacement cycles. The California Energy Commission enforces standby power limits and thermal efficiency minimums that reshape product roadmaps. Silicon Valley and Los Angeles Basin smart home infrastructure penetration creates concentrated adoption pockets for Wi-Fi-enabled premium units.
Texas
Dallas-Fort Worth and Houston apartment dwellers prioritize portable countertop configurations over electrical infrastructure investments. The Public Utility Commission of Texas oversees grid reliability standards that influence IoT device connectivity requirements. Austin multi-family developers specify smart appliance packages in bulk procurement arrangements distinct from retail channels.
New York Metro
Pre-war building stock limits built-in smart oven penetration due to legacy electrical infrastructure constraints. The New York State Department of Public Service regulates residential voltage standards that affect installation feasibility. Manhattan and Brooklyn renovation contractors coordinate electrical upgrades for high-end residential conversions targeting connectivity-forward buyers.
Florida
Sun Belt migration patterns concentrate demand in Tampa and Orlando metropolitan areas where new construction outpaces national averages. The Florida Public Service Commission governs residential energy efficiency disclosure requirements for appliance sales. Miami-Dade and Broward County developers bundle smart kitchen packages into specification-grade rental units.
Illinois
Chicago metropolitan corridor exhibits slower adoption due to older housing stock and deferred renovation cycles. The Illinois Commerce Commission administers appliance efficiency standards that align with federal DOE test procedures. Cook County independent appliance dealers maintain regional loyalty through contractor referral networks for built-in installations.
US Smart Oven Market Competitive Landscape
Capability concentration sits with semiconductor-integrated appliance specialists; scale advantage sits with diversified electronics conglomerates. The market structure reflects a tiered competitive field where captive component manufacturing separates premium positioning from assembly-dependent challengers. Three archetypes dominate: integrated electronics manufacturers with proprietary chipset control, traditional appliance makers with motor and sensor captive production, and software-native entrants with cloud-first recipe ecosystems. Competitive moves center on FCC cybersecurity certification pre-positioning and multi-family developer procurement consolidation.
Within the integrated electronics tier, Samsung Electronics Co., Ltd. and LG Electronics occupy positions defined by captive semiconductor and display supply chain control. Whirlpool Corporation anchors the traditional appliance manufacturer archetype through Ohio-based motor and sensor production. These three entities exemplify divergent strategic postures: semiconductor integration versus component manufacturing depth versus platform ecosystem development.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| LG Electronics |
| Samsung Electronics Co., Ltd. |
| Panasonic Corporation |
| Sharp Corporation |
| AB Electrolux |
| Alto-Shaam, Inc. |
| Tovala |
| June Life, Inc. |
| Others |
Pricing and Supply Chain Analysis
China's appliance manufacturing belt concentrates IoT chipset fabrication and display panel production, anchoring margin pools in semiconductor-integrated control systems and OLED interface tiers rather than commodity heating element assembly.
Pricing Analysis
Long-term offtake agreements dominate procurement between multi-family developers and manufacturers, while spot-market transactions govern replacement countertop sales through online retail. Pricing stratifies across premium Wi-Fi-enabled built-in configurations, standard countertop cloud-connected units, and economy Bluetooth-only alternatives facing obsolescence-driven markdowns. Cost compression in entry tiers intensifies as inventory liquidation pressure mounts on stranded Bluetooth channel stock. Property developers exhibit lowest price sensitivity through bundled specification-grade packages, whereas individual apartment dwellers in Texas metropolitan corridors demonstrate acute sensitivity to upfront acquisition costs.
Supply Chain Analysis
Export-control restrictions on advanced semiconductor manufacturing equipment limit foundry capacity expansion for proprietary IoT chipsets, constraining control system supply to Taiwan, South Korea, and concentrated Chinese fabrication facilities. Smart oven production draws from copper heating element windings, steel chassis fabrication, and captive Ohio-based motor manufacturing. Single-source vulnerability concentrates in Asian semiconductor foundries exposed to geopolitical friction and shipping lane disruption. Distribution runs through big-box home improvement channels with electrical contractor coordination, wholesale consortia serving national multi-family operators, and direct-to-consumer online platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US smart oven market sits in early-cycle expansion as kitchen automation adoption accelerates replacement cycles and Wi-Fi infrastructure penetration deepens in California and Texas metropolitan corridors.
For Market Incumbents: Entrench FCC cybersecurity certification pre-positioning to construct regulatory moats against late entrants lacking secure boot architectures. Deepen captive production of smart appliance motors and sensors in Ohio facilities to insulate margin pools from commodity metals volatility. Counter the threat of software-native entrants by accelerating cloud-first recipe ecosystem development through platform integration investments. For New Entrants and Emerging Players: Establish a beachhead in voice-activated premium tiers targeting aging-in-place renovations in Sun Belt metropolitan areas where accessibility compliance drives specification. Exploit underdeveloped culinary school and hospitality segments requiring remote instructor monitoring capabilities. Pursue direct-to-consumer online retail with subscription accessory revenue models to bypass entrenched wholesale consortia relationships. For Investors and Strategic Acquirers: Capital is best deployed toward semiconductor-integrated appliance specialists with proprietary chipset control and established FCC certification pipelines rather than assembly-dependent challengers. Target acquisition archetypes include software-native entrants with cloud-first recipe ecosystems and voice processing integration capabilities. Monitor FCC cybersecurity rulemaking implementation as the critical inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Boot Architecture Certification | FCC cybersecurity labeling requirements favor early movers with established IoT security protocols. |
| Multi-Family Developer Procurement Consolidation | Bulk specification agreements in Austin and Phoenix concentrate purchasing power away from retail channels. |
| Voice Assistant Platform Integration | Amazon Alexa and Google Assistant convergence enables hands-free recipe execution for accessibility markets. |
| On-Device Processing Migration | FTC data privacy scrutiny compels manufacturers to minimize cloud transmission through edge computing. |
| Ohio Motor and Sensor Capacity Expansion | Captive production insulates Whirlpool from commodity metals volatility and supply chain disruption. |
Research Methodology
The analysis maps countertop configurations, built-in installations, Wi-Fi-enabled ecosystems, and voice-activated premium tiers, each validated through product managers at Samsung Electronics and LG Electronics, smart home integration specialists, multi-family property developers in Austin and Phoenix, and electrical contractors in California renovation markets. Primary interview data triangulates against FCC certification databases, CPSC thermal safety filings, California Energy Commission Title 20 compliance records, and DOE federal test procedure documentation. Bottom-up shipment volume estimates from manufacturer channels reconcile with top-down market sizing derived from smart home penetration rates and replacement cycle analysis.
Assumptions held fixed include California Title 20 efficiency mandate enforcement timelines and Texas metropolitan smart home infrastructure deployment trajectories, while semiconductor supply availability and copper pricing were modeled as variable inputs across the projection horizon. Segmentation dimensions span installation requirements, connectivity architecture, end-user application, and distribution channel structure. CAGRs derive from regression analysis against historical replacement cycle compression and connectivity adoption curves, with specific inputs including multi-family housing permit volumes in Sun Belt markets and FCC Part 15 certification issuance rates.
Sensitivities concentrate around semiconductor foundry capacity constraints, copper and steel commodity price volatility, and FTC cybersecurity enforcement intensity. Forecasts reflect documented assumptions regarding smart home infrastructure maturation and consumer IoT comfort thresholds. Material shifts in export-control regime stringency or CPSC thermal safety testing timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Residential Hobs Market
Kitchen Appliances
Japan Kitchen Appliances Market
Kitchen Appliances
South Korea Kitchen Appliances Market
Kitchen Appliances
Cookware Accessories Market
Kitchen Appliances
Temperature Controlled Mug Market
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
Toaster Market
Kitchen Appliances
Outdoor Cooking Equipment Market
Kitchen Appliances
Air Fryer Accessories Market
Kitchen Appliances
China Kitchen Appliances Market
Kitchen Appliances
France Kitchen Appliances Market
Kitchen Appliances
Europe Smart Cooker Market
Kitchen Appliances
Smart Kitchen Faucet Market
Kitchen Appliances
Cooktop Market
Kitchen Appliances
Commercial Induction Cooktops Market