
 Europe Major Home Appliances Market | 2026-2036
Europe Major Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Major Home Appliances Market Foresight
Built-in appliance bundling with kitchen cabinetry is hardening as the dominant configuration pattern across new residential construction. BSH Hausgeräte GmbH leverages its engineered integration systems to anchor premium project channels. Samsung Electronics competes through connected kitchen ecosystems that extend software control across refrigeration and cooking platforms. Miele & Cie. KG differentiates via material specifications and in-house component production that sustains price positioning at the luxury tier.
Europe major home appliances comprise freestanding and built-in electromechanical equipment for domestic food preservation, fabric care, cooking, and surface cleaning, typically operating at 220-240V with energy efficiency ratings scaled from A to G under EU labeling rules. Refrigerators and dishwashers dominate replacement volume where energy label upgrades drive trade-in decisions, while smart appliances capture margin pools through software subscription and predictive maintenance revenue. Connected devices and energy efficient technology segments are expanding fastest as utility time-of-use tariffs and building energy codes tighten operational cost thresholds for households and commercial establishments.
The EU Ecodesign Directive and F-Gas Regulation constrain refrigerant chemistry and minimum performance standards, forcing manufacturers to redesign compressor architectures and thermal insulation systems. CE marking and national efficiency rebate schemes administered by Germany's KBA-aligned federal agencies and France's DGCCRF shape market access and consumer price sensitivity. Stakeholders must monitor how the EU Green Deal's embodied carbon tracking requirements will alter supplier qualification and material sourcing rules for steel and plastic components.
Market Dynamics
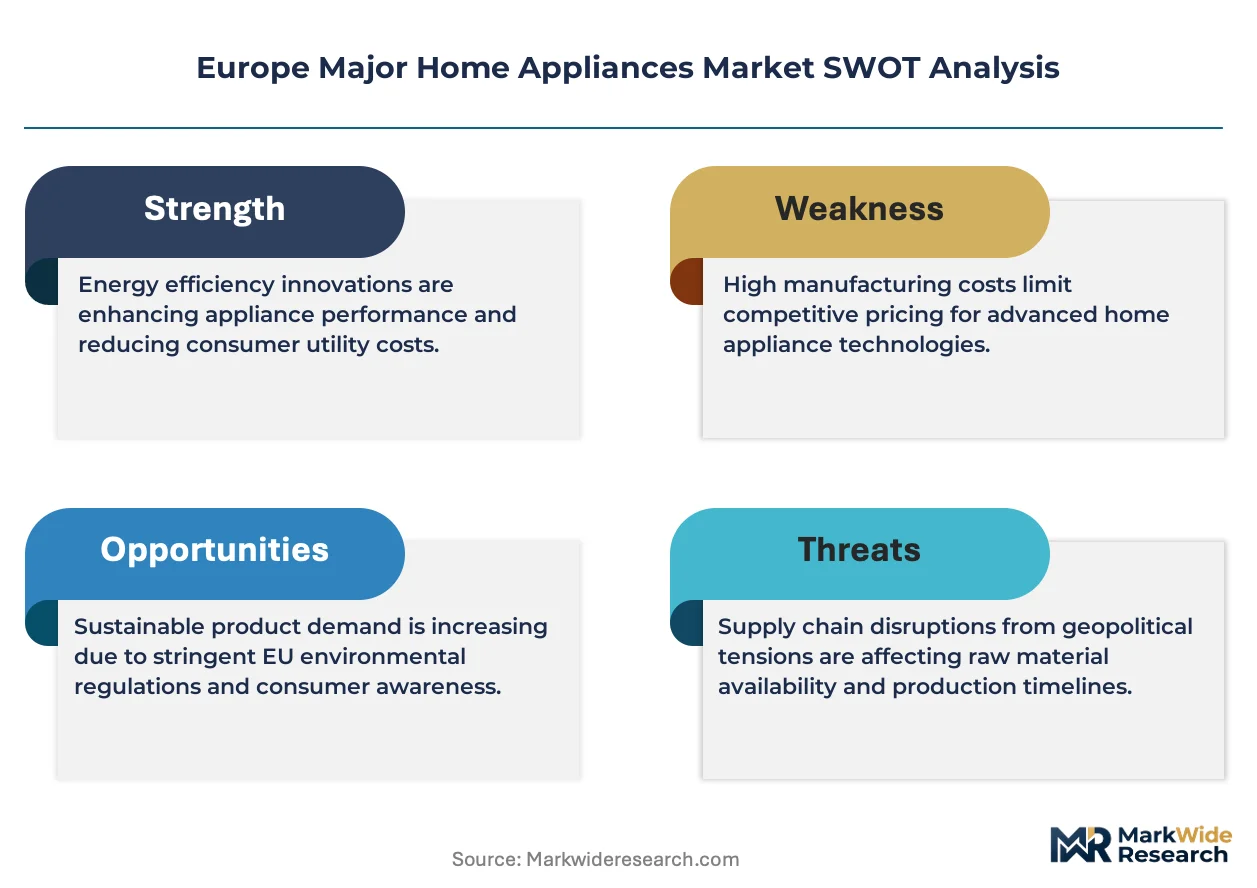
Energy efficiency mandates under the EU Ecodesign Directive are compressing replacement cycles and forcing compressor architecture redesigns across European manufacturing bases. This regulatory pressure is rewriting procurement priorities for both trade channels and direct consumers.
Growth Catalysts
- EU Ecodesign Directive:Mandatory efficiency upgrades for refrigerators and dishwashers accelerate trade-in velocity among urban households seeking lower utility bills.
- Connected-home ecosystems:Software-controlled kitchen platforms extend manufacturer margins through predictive maintenance subscriptions and usage-based service tiers.
- Germany housing renovation:Elevated appliance turnover in renovation-heavy metros sustains replacement volume for built-in configurations.
Market Restraints
- Steel and plastic embodied carbon tracking:EU Green Deal supplier qualification rules increase compliance overhead for component sourcing.
- F-Gas Regulation constraints:Refrigerant chemistry restrictions force thermal insulation system redesigns that extend R&D timelines.
- CE marking fragmentation:Divergent national efficiency rebate schemes between Germany's KBA-aligned agencies and France's DGCCRF create market access friction.
Strategic Opportunities
- Italy's elevated appliance turnover:Housing renovation rates in northern Italian metros support premium built-in bundling with kitchen cabinetry.
- Time-of-use tariff alignment:Utility pricing structures in France and Germany create demand for load-shifting smart appliances.
- Software-hardware convergence:Predictive maintenance algorithms paired with refrigeration compressors enable recurring revenue streams.
Industry Challenges
- Compressor thermal engineering talent:Scarce expertise in low-GWP refrigerant system design constrains product development velocity.
- Building energy code synchronization:Misaligned national implementation timelines for EU directives complicate pan-European product planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Major Home Appliances Market |
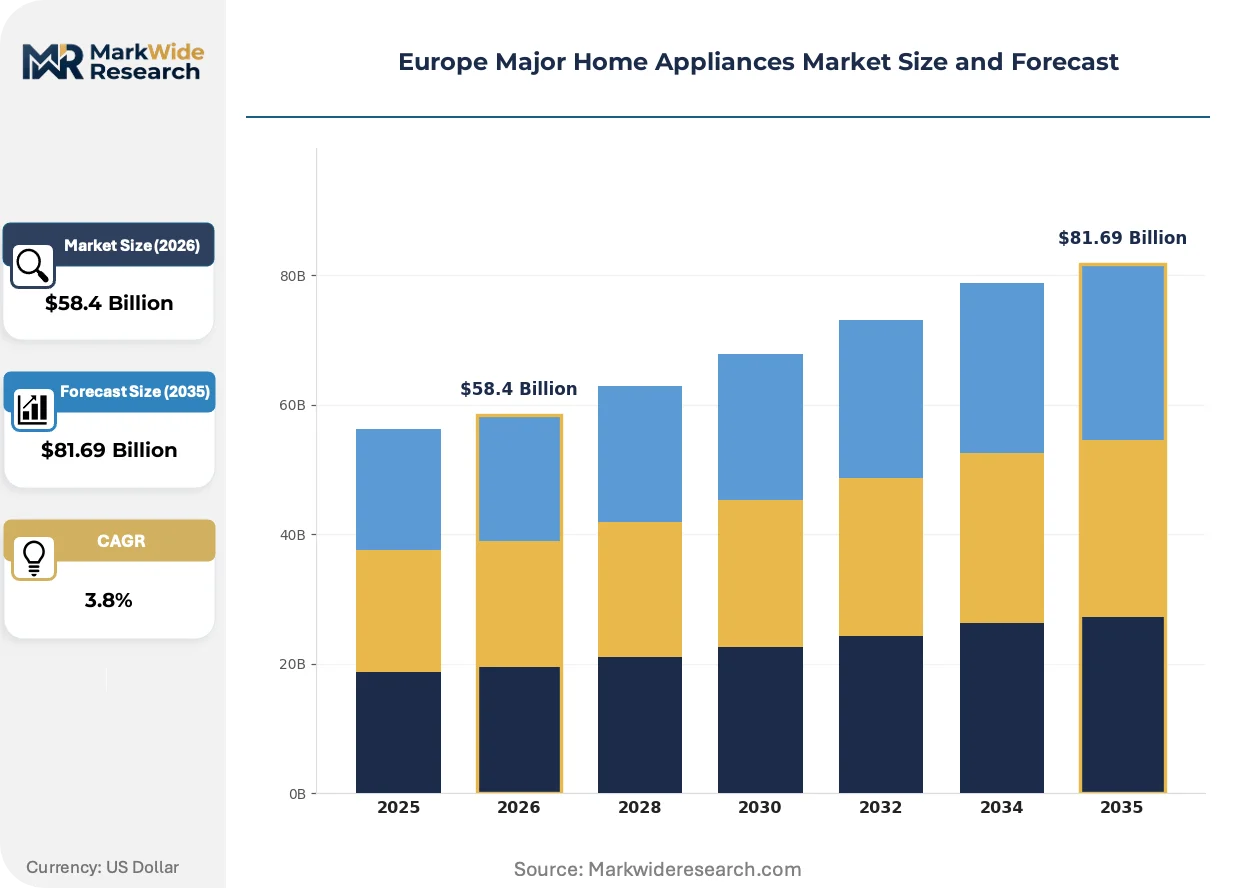
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $81.69 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washers, Ovens, Dishwashers Technology: Smart Appliances, Traditional Appliances, Energy Efficient, Connected Devices End User: Households, Commercial Establishments, Rental Properties, Hotels Price Tier: Premium, Mid-range, Budget, Luxury |
| Companies Covered | Whirlpool Corporation, Samsung Electronics, BSH Hausgeräte GmbH, Miele & Cie. KG, LG Electronics, Beko Europe (Arçelik A.Ş.), Haier Europe (Candy/Hoover), Midea Group, Electrolux AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Major Home Appliances Market Shifts & Advancements
Connected-device integration and predictive service models are displacing transactional hardware sales across European kitchen renovation channels. Manufacturers now compete through software ecosystems rather than standalone appliance specifications.
Variable-speed inverter compressors with natural refrigerant compatibility are rewriting thermal management economics for domestic refrigeration. German and French housing renovators specify these systems at accelerating rates. The technology is compressing energy consumption benchmarks and enabling A-grade efficiency ratings under tightened EU labeling rules.
The EU F-Gas Regulation phase-down schedule is forcing refrigerant chemistry transitions across cold-chain and domestic appliance production lines. Manufacturers must redesign compressor architectures and validate alternative thermal insulation systems. France and Germany's housing renovation markets face the steepest compliance curves due to earlier national implementation timelines.
Service unbundling from hardware sales is fragmenting traditional dealer relationships across European kitchen channels. Direct manufacturer subscriptions for predictive maintenance and remote diagnostics replace bundled after-sales warranties. Italy and Spain exhibit the fastest channel restructuring as independent installers lose exclusive servicing rights.
Europe Major Home Appliances Market Segmentation
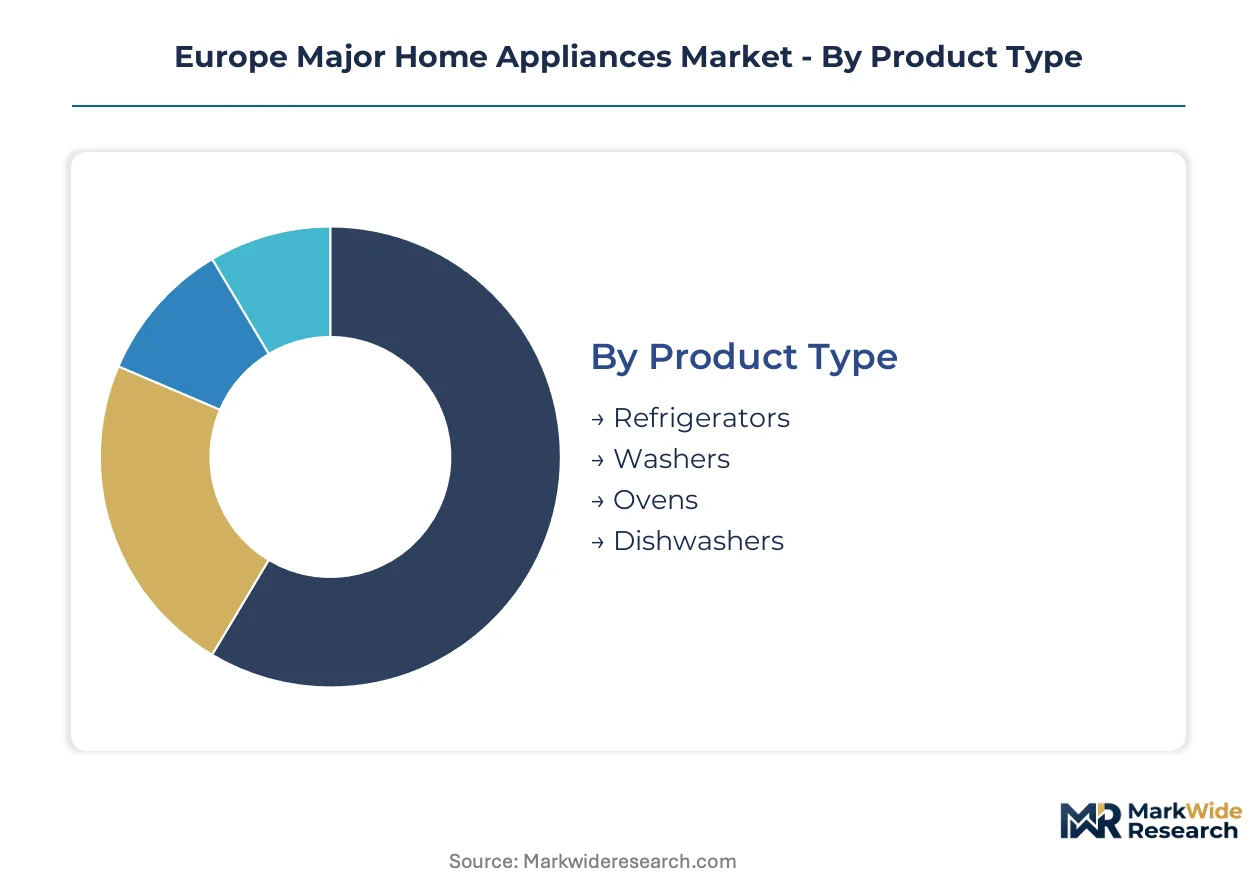
Segmentation in Europe's major home appliances market reveals how regulatory pressure and renovation cycles concentrate demand across distinct product configurations. Understanding these splits enables suppliers to align R&D pipelines with where replacement velocity and margin expansion actually occur.
Product Type:
Upgrade cycles vary sharply by product category, with energy label thresholds and kitchen integration requirements driving divergent replacement timelines across European households.
- Refrigerators:Variable-speed inverter compressors with natural refrigerant compatibility now dominate thermal management architectures. German and French housing renovators specify these systems at accelerating rates to secure A-grade efficiency ratings under tightened EU labeling rules.
- Washers:Front-loading drum designs with heat-pump drying integration capture premium project channels. Italian and Spanish metro markets show concentrated demand where water efficiency rebates from national agencies shorten replacement intervals.
- Ovens:Built-in configurations with pyrolytic cleaning and steam injection anchor kitchen cabinetry bundles.
- Dishwashers:Slimline and fully integrated formats dominate urban apartment renovations.
Volume placements concentrate in Refrigerators; the faster expansion belongs to Washers.
Technology:
Cost tier stratification in European appliance procurement separates hardware-only transactions from software-enabled service relationships, with distinct margin structures at each level.
- Smart Appliances:Predictive maintenance algorithms paired with refrigeration compressors enable recurring revenue streams. Utility time-of-use tariffs in France and Germany create demand for load-shifting capabilities that justify subscription pricing.
- Connected Devices:Wi-Fi-enabled platforms extend manufacturer control over usage data and remote diagnostics. Northern Italian and Spanish kitchen channels exhibit the fastest restructuring as direct manufacturer subscriptions replace dealer warranties.
- Energy Efficient:A-grade rated systems dominate trade-in decisions where EU Ecodesign Directive mandates compress replacement cycles.
- Traditional Appliances:Basic electromechanical controls persist in budget rental property segments.
Hardware transactions still dominate unit volume; software-hardware convergence claims the steepest expansion trajectory.
End User:
Customer type determines specification intensity, with commercial operators prioritizing total cost of ownership while residential buyers respond to kitchen aesthetics and energy rebates.
- Households:Urban renovation projects in Germany, France, and Italy drive built-in configuration demand. National efficiency rebate schemes administered by Germany's KBA-aligned federal agencies and France's DGCCRF shape price sensitivity and brand selection.
- Commercial Establishments:Restaurants and catering operations specify heavy-duty cycles with rapid wash and cook times. F-Gas Regulation compliance costs weigh more heavily here due to larger refrigeration footprints.
- Rental Properties:Landlords prioritize acquisition cost over operating efficiency, sustaining demand for basic C-D rated units.
- Hotels:In-room mini-bar and laundry specifications follow corporate sustainability mandates.
Households account for the dominant placement volume; Commercial Establishments register the fastest climb in specification intensity.
Price Tier:
Margin capture stratifies across material specifications, in-house component production, and software ecosystem control, with luxury positioning sustained by engineered integration systems.
- Premium:Engineered integration systems anchor project channels for kitchen cabinetry bundling. BSH Hausgeräte GmbH leverages proprietary mounting and ventilation architectures to defend specification slots in German new residential construction.
- Luxury:In-house component production and material specifications sustain positioning at the highest tier. Miele & Cie. KG controls captive supply of cast iron and enamel finishes that differentiate against mass-manufactured alternatives.
- Mid-range:Connected kitchen ecosystems from Samsung Electronics compete through software control across refrigeration and cooking platforms.
- Budget:Basic functionality without smart connectivity or premium finishes serves price-sensitive replacement demand.
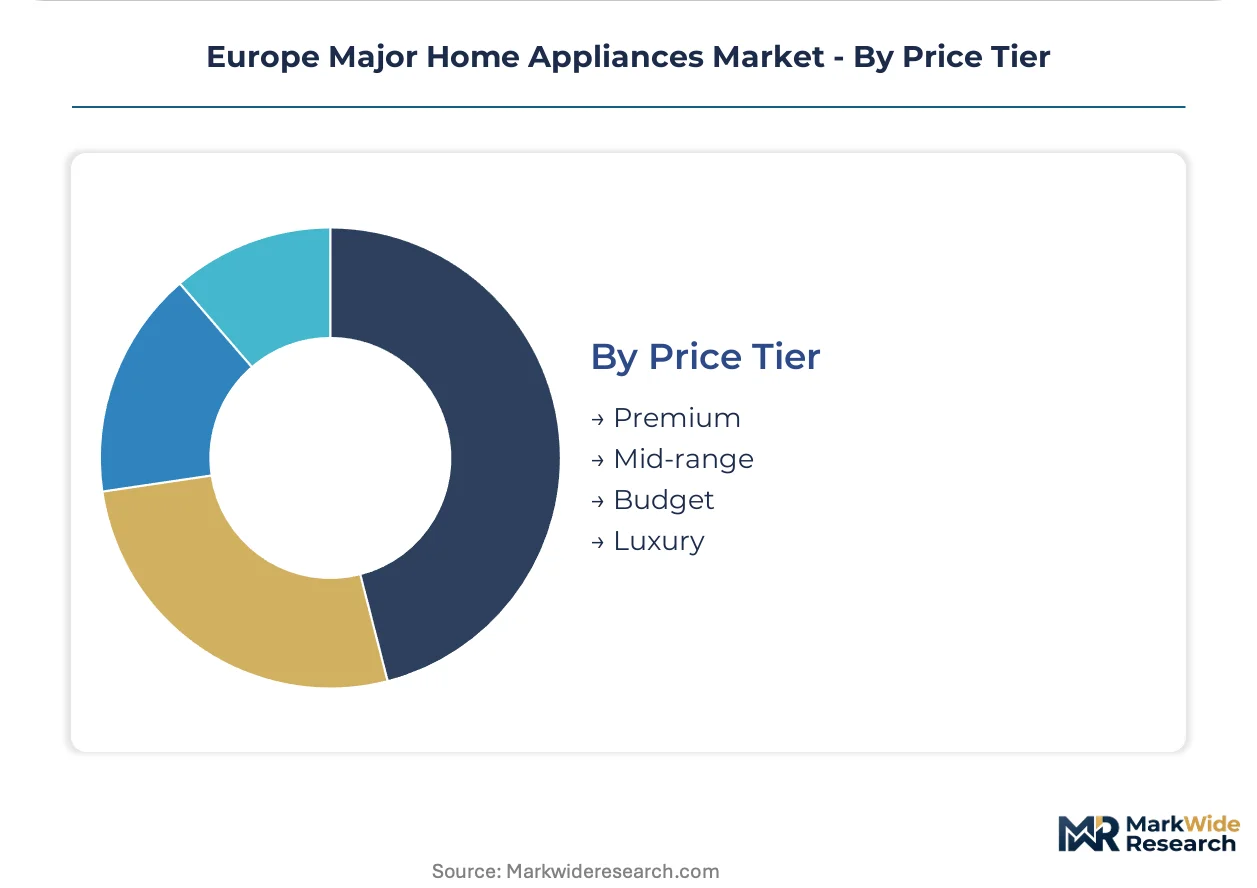
Mid-range configurations absorb the highest unit volume; Luxury tier gains share fastest on renovation-driven specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special-economic-zone incentives in Poland's Łódź region and Slovakia's western industrial corridor concentrate appliance assembly capacity serving central European distribution networks. Tax-advantaged manufacturing parks in these zones attract component suppliers co-locating with final assembly operations.
Germany
Urban renovation cycles in Berlin, Munich, and Hamburg accelerate built-in appliance turnover as housing stock upgrades to meet federal efficiency standards. KBA-aligned federal agencies administer rebate schemes that compress replacement intervals for A-rated refrigerators and dishwashers. The Baden-Württemberg industrial cluster around Stuttgart hosts compressor engineering facilities redesigning thermal architectures for natural refrigerant compatibility.
France
Housing renovation rates in Paris, Lyon, and Marseille sustain premium kitchen cabinetry bundling with integrated cooking and refrigeration platforms. DGCCRF oversight shapes national efficiency labeling enforcement and consumer rebate program eligibility. The Auvergne-Rhône-Alpes region concentrates dishwasher and cooking appliance manufacturing serving both domestic and export channels.
Italy
Northern Italian metros including Milan, Turin, and Bologna exhibit elevated appliance turnover tied to residential renovation intensity and kitchen modernization cycles. National building energy codes transposing EU Ecodesign Directive mandates drive specification upgrades in Lombardy and Piedmont. The Veneto region anchors supply chain nodes for built-in configuration components serving cabinetry integration channels.
Spain
Barcelona and Madrid renovation markets show concentrated demand for slimline and fully integrated dishwasher formats suited to urban apartment footprints. Utility time-of-use tariff structures in these metros create pull for load-shifting smart appliance capabilities. The Basque Country maintains component fabrication capacity supporting thermal insulation system redesigns for F-Gas Regulation compliance.
Poland
Łódź and Wrocław special-economic zones host assembly operations serving German and Nordic export markets with cost-optimized production configurations. EU structural funds support manufacturing modernization aligning with CE marking and efficiency labeling harmonization. The western industrial corridor near the German border concentrates logistics infrastructure for pan-European distribution of mid-range appliance portfolios.
Europe Major Home Appliances Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price positioning in European major home appliances. Market structure shows consolidation at the premium and luxury tiers alongside fragmentation in mid-range and budget segments. Three archetypes dominate: integrated kitchen system providers, component-captive luxury manufacturers, and scale-driven connected-platform operators. Competitive moves center on strategic partnerships for software ecosystem integration and backward integration into compressor and control system production.
Within the integrated kitchen system tier, BSH Hausgeräte GmbH and Miele & Cie. KG exemplify divergent approaches to premium positioning. Samsung Electronics occupies a position at the scale-driven, software-enabled end of the competitive spectrum. These three entities represent the primary competitive anchors shaping procurement relationships across European trade channels.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Samsung Electronics |
| BSH Hausgeräte GmbH |
| Miele & Cie. KG |
| LG Electronics |
| Beko Europe (Arçelik A.Ş.) |
| Haier Europe (Candy/Hoover) |
| Midea Group |
| Electrolux AB |
| Others |
Supply & Pricing Matrix
The EU Ecodesign Directive's tightening efficiency thresholds gate qualified supply access and premium-tier pricing power across European appliance channels. Manufacturers must redesign compressor architectures and thermal insulation systems to meet A-grade labeling requirements, forcing cost absorption or price escalation at each tier.
Pricing Analysis
Margin tightening in mid-range configurations reflects steel and plastic embodied carbon tracking compliance costs passed through from component suppliers. Three-tier pricing structure across premium, standard, and economy levels separates engineered integration systems from connected-platform offerings and basic electromechanical units. Price differentiation hinges on certification grade under EU labeling rules and in-house component production depth. Budget rental property segments exhibit highest price sensitivity; luxury buyers anchored by Miele and BSH specifications show least elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German and French housing renovators specifying built-in configurations. Component fabrication concentrates in Poland's Łódź special-economic zone, Slovakia's western industrial corridor, and Germany's Baden-Württemberg cluster. Steel sheet, copper winding, and refrigerant chemistry draw from EU-qualified suppliers under F-Gas Regulation constraints. Single-source vulnerability in natural refrigerant-compatible compressor engineering constrains product development velocity. Distribution runs through kitchen cabinetry integrators and independent installer networks restructuring toward manufacturer-direct subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European appliance manufacturing is becoming a backward integration race. Control over compressor thermal engineering and refrigerant system design now determines margin capture and specification access.
For Market Incumbents: Extend proprietary mounting and ventilation architectures into software-controlled kitchen ecosystems before Samsung Electronics consolidates connected-platform dominance. Deepen captive supply of cast iron and enamel finishes to defend luxury positioning against mass-manufactured alternatives. Compressor thermal engineering talent scarcity threatens product development velocity; secure exclusive relationships with German and Italian technical institutes. For New Entrants and Emerging Players: Launch via direct manufacturer subscription models in Spain and Italy where independent installer networks are restructuring fastest. Target slimline dishwasher formats for urban apartment renovations in Barcelona and Madrid where specification intensity lags northern European metros. White space exists in predictive maintenance algorithms paired with refrigeration compressors for utility time-of-use tariff alignment. For Investors and Strategic Acquirers: F-Gas Regulation implementation timeline acceleration in France and Germany is the leading indicator that refrigerant chemistry transition costs will concentrate market share among component-captive manufacturers. Five-to-ten year viability favors vertically integrated specialists with in-house compressor production and EU-qualified steel sourcing. Monitor DGCCRF and KBA-aligned agency rebate scheme harmonization for early signals of pan-European pricing power consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Production | Captive thermal engineering capacity secures A-grade efficiency ratings under tightened EU Ecodesign Directive thresholds. |
| Software Subscription Launch for Predictive Maintenance | Recurring revenue streams from refrigeration compressor diagnostics offset transactional hardware margin compression. |
| Natural Refrigerant Compatibility Certification | F-Gas Regulation compliance validates product access to German and French renovation-heavy metro markets. |
| Kitchen Cabinetry Bundling Partnership Expansion | Engineered integration systems from BSH and Miele anchor specification slots in new residential construction channels. |
| Poland and Slovakia Manufacturing Footprint Scale-Up | Special-economic-zone incentives concentrate cost-optimized assembly capacity serving central European distribution networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this European appliance market analysis. Primary interviews with compressor engineering directors, kitchen cabinetry procurement managers, national efficiency rebate program administrators, and thermal insulation system suppliers combined with CE marking documentation and EU Ecodesign Directive implementation schedules. Bottom-up shipment data from German KBA-aligned agencies and French DGCCRF enforcement records triangulated against top-down housing renovation expenditure estimates.
Product-level granularity modeled refrigerator, washer, oven, and dishwasher configurations separately across smart, connected, energy-efficient, and traditional technology tiers. End-user splits captured household, commercial establishment, rental property, and hotel demand patterns. Price tier segmentation tracked premium, luxury, mid-range, and budget positioning. CAGRs derived from replacement cycle compression analysis under regulatory mandate timelines and connected-home ecosystem adoption curves across the analysis window. Housing renovation rates, utility tariff structures, and refrigerant chemistry transition costs fed sector-specific forecast inputs.
Regulatory implementation delays, steel and plastic embodied carbon tracking rule changes, and compressor thermal engineering talent availability are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about EU Green Deal supplier qualification timelines and national building energy code synchronization. Practitioners should monitor F-Gas Regulation phase-down schedule acceleration and DGCCRF-KBA rebate scheme convergence for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Electric Countertop Griddles Market
Kitchen Appliances
United States Large Kitchen Appliances Market
Kitchen Appliances
Portable Outdoor Pizza Oven Market
Kitchen Appliances
Electric Corkscrew Market
Kitchen Appliances
Switzerland Kitchen Appliances Product Market
Kitchen Appliances
Electric Pizza Oven Market
Kitchen Appliances
Poland Household Electric Grills Market
Kitchen Appliances
India Kitchen Appliances Market
Kitchen Appliances
Capsule Coffee Machines Market
Kitchen Appliances
Outdoor Commercial Grills Market
Kitchen Appliances
France Kitchen Appliances Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Smart Induction Cooktop Market
Kitchen Appliances
United States Electric Vegetable Choppers Market
Kitchen Appliances
Global Baking Tools Market
Kitchen Appliances
Hand-Held Mixer Market